
 Smart Water Management Market | 2026-2036
Smart Water Management Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Water Management Market Intelligence
The shift toward Advanced Metering Infrastructure (AMI) with integrated analytics is unwinding the traditional utility model of periodic, manual meter reading. This transition creates opportunities for technology providers that can deliver end-to-end solutions. Xylem Inc. leverages its comprehensive portfolio of pumps and sensors to offer integrated systems. Siemens AG competes on the strength of its industrial automation and SCADA software, while Itron Inc. specializes in metering hardware and network solutions for utility clients.
Smart water management applies information and communication technologies to monitor and control water and wastewater networks. These systems typically integrate IoT sensors communicating over low-power wide-area networks (LPWAN) to a central platform for real-time data processing. Hardware devices, including smart meters and sensors, constitute the foundational investment layer for municipal utilities. Software platforms offering cloud analytics and AI-powered demand forecasting represent the highest-margin segment, especially for applications like leak detection.
Regulatory mandates from bodies like the US Environmental Protection Agency (EPA) and compliance with the EU's Water Framework Directive directly drive technology investment. In China, the Ministry of Ecology and Environment (MEE) sets stringent targets for water quality, creating demand for advanced monitoring solutions. Future investment decisions for utilities will hinge on selecting platforms that ensure data security and interoperability between disparate hardware and software components.
Market Dynamics
The imperative to modernize aging water infrastructure against a backdrop of increasing climate-induced water stress and stringent regulatory pressure defines the market's core tension. This dynamic forces utilities to move beyond traditional capital works toward data-driven network optimization for efficiency and resilience.
Growth Catalysts
- Non-Revenue Water (NRW) Mandates:Regulatory frameworks, including targets within the EU Green Deal and guidelines from the US EPA, compel utilities to reduce water losses from leaks and theft, directly stimulating investment in smart metering and leak detection systems.
- IoT and LPWAN Proliferation:The declining cost and expanding coverage of Low-Power Wide-Area Networks enable cost-effective deployment of vast sensor networks, providing the real-time data flow essential for smart water management applications from pressure monitoring to quality control.
- Agricultural Water Scarcity:In arid and semi-arid regions, particularly for large-scale irrigation in Australia and Spain, the demand for precision agriculture drives adoption of soil moisture sensors, smart valves, and automated irrigation systems to maximize crop yield per unit of water.
Market Restraints
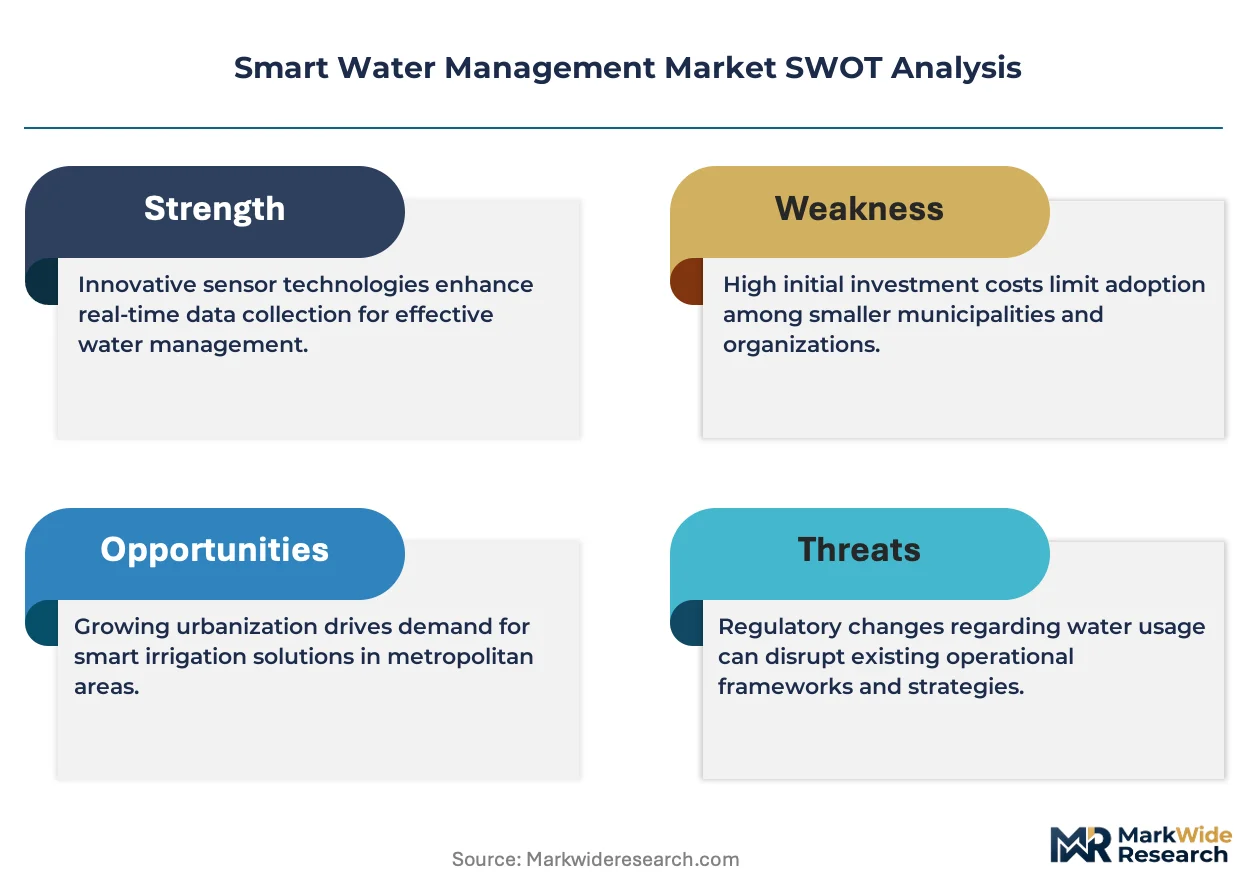
- High Initial Capital Outlay:The substantial upfront investment required for deploying Advanced Metering Infrastructure (AMI) and associated communication networks presents a significant barrier for capital-constrained municipal utilities, particularly in smaller towns and developing economies.
- System Interoperability:A lack of standardized communication protocols across devices from different vendors creates integration challenges, risking vendor lock-in and complicating the development of a unified, city-wide water management platform.
- Data Security and Privacy Concerns:The collection of granular water usage data via smart meters raises significant privacy concerns, requiring robust cybersecurity measures and compliance with data protection regulations like GDPR, which adds complexity and cost to system deployment.
Strategic Opportunities
- Digital Twin for Network Optimization:The convergence of real-time sensor data with hydraulic modeling software allows for the creation of digital twins of water distribution networks, enabling predictive simulations for maintenance scheduling, capital planning, and emergency response.
- Expansion in Southeast Asia:Rapid urbanization and government-led smart city initiatives in countries like Vietnam and Indonesia present significant greenfield opportunities for smart water technology providers as new infrastructure is built and old systems are upgraded.
- AI-Powered Predictive Analytics:Moving beyond basic leak detection, AI algorithms can analyze historical and real-time data to forecast demand, predict pipe failures, and optimize pumping schedules, offering higher-value services for utilities.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is integrating modern IoT-based systems with utilities' existing, often decades-old, SCADA and billing software, which can lead to costly and time-consuming custom development projects.
- Workforce Skill Gaps:The transition to smart water management requires a new set of skills, including data science, network engineering, and cybersecurity, which are often in short supply within traditional water utility workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Water Management Market |
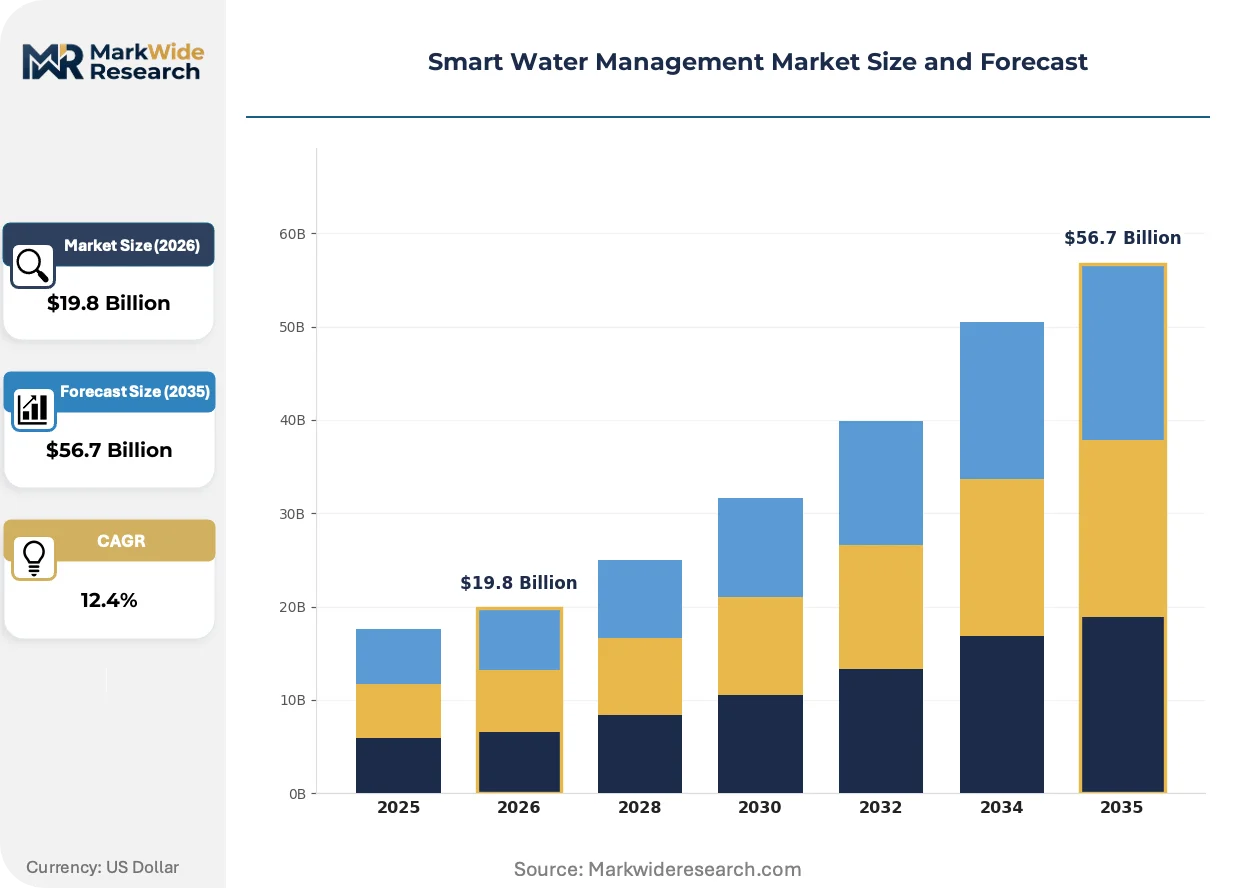
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $56.7 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Sensors, Cloud Analytics, AI Platforms, SCADA Systems, Data Visualization, Remote Monitoring Application: Leak Detection, Water Quality Monitoring, Pressure Management, Asset Optimization, Demand Forecasting, Energy Efficiency End User: Municipal Utilities, Agricultural Irrigation, Industrial Facilities, Commercial Complexes, Residential Complexes, Water Treatment Plants Solution Type: Hardware Devices, Software Platforms, Integrated Systems, Cloud Services, Consulting Services, Maintenance Contracts |
| Companies Covered | Xylem Inc., Itron Inc., ABB Ltd., Siemens AG, Schneider Electric SE, IBM Corporation, Honeywell International Inc., Badger Meter Inc., SUEZ SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Water Management Market Strategic Shifts & Innovations
Value creation is shifting from the provision of physical hardware to the delivery of data-driven insights and operational intelligence. This transition prioritizes software platforms, analytics, and service models that translate real-time data into actionable outcomes like reduced water loss and optimized energy consumption.
Edge computing integrated within smart meters and network sensors provides localized data processing capabilities. Municipal utilities are adopting this technology to reduce network latency and minimize the volume of data transmitted to a central cloud. The use of edge intelligence is decomposing the monolithic, cloud-only analytics model, enabling faster, autonomous control actions like pressure adjustments within a distribution zone.
China's "dual carbon" goals and stringent water quality targets set by the Ministry of Ecology and Environment (MEE) are creating significant domestic demand. These national policies compel municipal authorities to upgrade wastewater treatment plants and invest in real-time monitoring solutions for urban water bodies. The industrial and municipal wastewater segments are responding by deploying advanced sensor arrays to ensure compliance.
A shift from one-time capital purchases to performance-based service contracts is altering technology procurement. This model disrupts the traditional upfront sale of hardware, with utilities paying technology providers based on achieving verified outcomes such as a percentage reduction in non-revenue water. This trend is most advanced in North American and Australian markets where operational budget predictability is a key priority.
Smart Water Management Market Segmentation
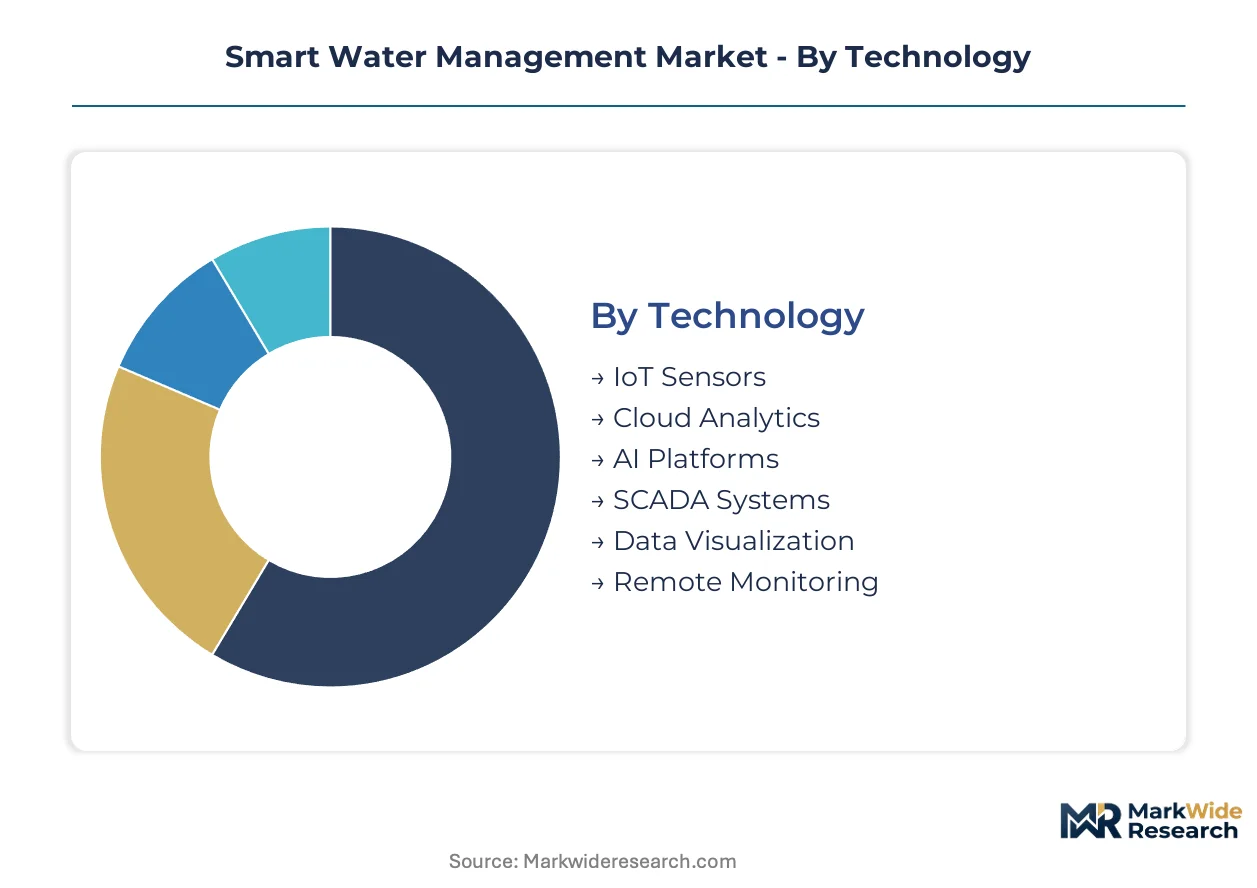
The Smart Water Management Market's segmentation reflects diverse technological approaches and application-specific demands across various end-user groups. Understanding these segments is crucial for technology providers to tailor solutions and for utilities to optimize their investment strategies.
Technology:
The technological landscape for smart water management is shaped by both foundational infrastructure and advanced analytical capabilities, with adoption patterns varying significantly across different national regulatory environments.
- IoT Sensors:These devices form the physical layer for data collection, measuring parameters like flow, pressure, and water quality. Their widespread deployment is critical in regions like the US and Europe, driven by mandates for real-time network visibility and non-revenue water reduction.
- Cloud Analytics:These platforms process vast datasets from connected sensors, enabling pattern recognition, predictive modeling, and operational insights. Demand for cloud analytics is high in developed markets such as Australia and Germany, where data-driven decision-making is a priority for asset optimization.
- AI Platforms:Artificial intelligence algorithms analyze historical and real-time data to forecast demand, predict infrastructure failures, and optimize system operations.
- SCADA Systems:Supervisory Control and Data Acquisition systems provide centralized control and monitoring of water infrastructure.
- Data Visualization:Tools that present complex water network data in an intuitive, graphical format for easier interpretation by utility operators.
- Remote Monitoring:Technologies enabling oversight and control of geographically dispersed water assets from a central location.
SCADA Systems command the established base. The steepest expansion runs through AI Platforms.
Application:
Smart water management applications target specific operational challenges, with utilities prioritizing solutions that directly address their most pressing pain points, from water loss to energy consumption.
- Leak Detection:This application identifies and locates water leaks within distribution networks, significantly reducing non-revenue water. Municipal utilities in water-stressed regions like Spain and California heavily invest in these systems to conserve resources and meet regulatory targets.
- Demand Forecasting:Predictive models analyze consumption patterns, weather data, and other variables to anticipate future water needs. This capability helps utilities in countries like the Netherlands optimize pumping schedules and manage reservoir levels more efficiently, leading to energy savings.
- Water Quality Monitoring:Sensors and analytical platforms continuously assess water parameters to ensure compliance with health standards.
- Pressure Management:Systems that optimize water pressure across the network to reduce leaks and extend pipe lifespan.
- Asset Optimization:Solutions that maximize the performance and longevity of water infrastructure through predictive maintenance.
- Energy Efficiency:Applications focused on reducing the energy consumption associated with water treatment and distribution.
Leak Detection is critical for operational efficiency. Demand Forecasting is driving future investment decisions.
End User:
The adoption of smart water management solutions varies by end-user type, reflecting distinct operational scales, regulatory pressures, and investment priorities.
- Municipal Utilities:These entities manage public water supply and wastewater treatment for cities and towns, representing the largest segment for smart water technology. Modernization efforts in countries like China and India are driving substantial investment to address rapid urbanization and aging infrastructure.
- Agricultural Irrigation:This segment uses smart systems to optimize water use in farming, particularly in arid regions facing water scarcity. Countries such as Australia and Israel are pioneers in deploying precision irrigation technologies to maximize crop yields with minimal water input.
- Industrial Facilities:Manufacturing plants and processing facilities implement smart water solutions for process optimization and effluent treatment.
- Commercial Complexes:Large buildings and campuses use smart systems for efficient water usage and leak detection within their premises.
- Residential Complexes:Multi-dwelling units and smart homes integrate water monitoring for conservation and early leak alerts.
- Water Treatment Plants:Facilities that purify water for consumption or treat wastewater before discharge, utilizing smart sensors for process control.
Municipal Utilities represent core demand. Agricultural Irrigation offers emerging opportunities for specialized solutions.
Solution Type:
Smart water management offerings are categorized by their delivery model and the core components they provide, ranging from physical devices to comprehensive service packages.
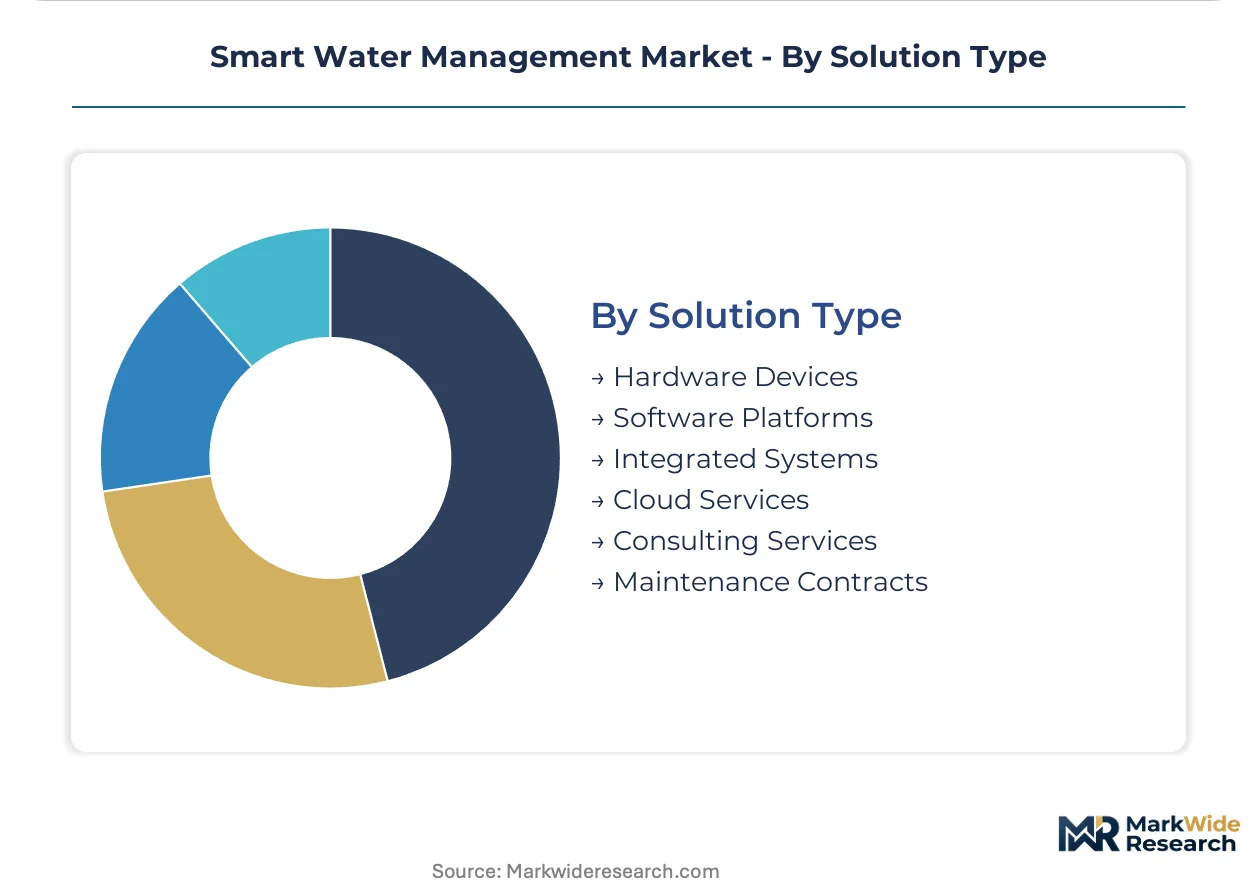
- Software Platforms:These cloud-based or on-premise systems aggregate data, provide analytics, and enable remote control of water infrastructure. They represent a high-margin segment, particularly for advanced leak detection and predictive maintenance applications.
- Integrated Systems:These solutions combine hardware, software, and communication networks into a unified package, offering end-to-end functionality. Utilities often prefer integrated systems to simplify procurement and reduce interoperability challenges.
- Hardware Devices:This category includes smart meters, sensors, and control valves that form the physical backbone of smart water networks.
- Cloud Services:Subscription-based access to software platforms and data storage, reducing the need for on-premise IT infrastructure.
- Consulting Services:Expert advice on system design, implementation, and optimization for smart water projects.
- Maintenance Contracts:Ongoing support and servicing for smart water management hardware and software.
Hardware Devices form the foundational investment. Software Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The flow of smart water management solutions often reflects the interplay between regional water scarcity and the capacity for technological adoption. Countries facing severe water stress frequently drive demand for advanced solutions, while developed economies with aging infrastructure prioritize data-driven optimization. Regulatory frameworks also significantly influence the direction and scale of technology investment across different geographies.
United States
Demand for smart water technologies in the United States stems from the imperative to reduce non-revenue water and modernize aging infrastructure. The US Environmental Protection Agency (EPA) mandates for water quality and efficiency compel utilities to invest in advanced monitoring. Cities in California, particularly within the Central Valley, are deploying smart irrigation systems to enhance agricultural water efficiency.
Germany
German utilities prioritize asset optimization and data-driven decision-making to maintain high service standards. Compliance with the EU's Water Framework Directive and the broader EU Green Deal targets accelerates technology adoption. Municipal utilities in Bavaria are at the forefront of deploying advanced analytics platforms for predictive maintenance.
China
China's rapid urbanization and stringent water quality targets drive substantial investment in smart water solutions. The Ministry of Ecology and Environment (MEE) sets specific mandates for real-time monitoring and wastewater treatment upgrades. Cities within the Yangtze River Delta are implementing comprehensive smart water systems to manage urban water bodies.
Australia
Australian agricultural regions face significant water scarcity, pushing demand for precision irrigation and water conservation technologies. The National Water Initiative guides sustainable water management practices across the continent. Farmers in the Murray-Darling Basin are early adopters of soil moisture sensors and automated irrigation systems.
Spain
Spanish municipalities and agricultural sectors heavily invest in smart water management due to arid climates and water stress. The EU Water Framework Directive and national drought management plans encourage efficient water use. The Andalusia region is a key area for the deployment of smart irrigation systems and leak detection technologies.
Smart Water Management Market Key Industry Players
Listed leaders compete with private specialists across the smart water management technology and service spectrum. The market structure features large industrial conglomerates alongside specialized software and hardware providers. Strategic archetypes include comprehensive solution integrators, metering infrastructure specialists, and industrial automation experts. Companies are increasingly engaging in strategic partnerships to enhance interoperability and diversify their technology portfolios.
Specialists in integrated water management solutions include Xylem Inc., which offers a comprehensive portfolio of pumps and sensors. Siemens AG occupies a position as a leading provider of industrial automation and SCADA software for water infrastructure. Itron Inc. exemplifies a focused approach, specializing in advanced metering hardware and network solutions for utility clients across various regions. These entities anchor distinct segments within the evolving smart water ecosystem.
| Leading Market Players |
|---|
| Xylem Inc. |
| Itron Inc. |
| ABB Ltd. |
| Siemens AG |
| Schneider Electric SE |
| IBM Corporation |
| Honeywell International Inc. |
| Badger Meter Inc. |
| SUEZ SA |
| Others |
Cost & Logistics Intelligence
Economies of scale in sensor manufacturing and software development shape both supply concentration and price floors across the smart water management market. This dynamic influences how technology providers structure their offerings and how utilities procure advanced solutions.
Pricing Analysis
Municipal utility buyers anchor subscription-based pricing models for software platforms, often tiered by data volume or number of connected devices. Price differentiation stems from the level of customization required for integration and the depth of AI-powered analytics offered. Cost compression in hardware components is intensifying due to increasing competition from Asian manufacturers. Agricultural irrigation entities demonstrate the highest price sensitivity, often seeking value-based pricing tied to water savings outcomes.
Supply Chain Analysis
Access to specialized IoT sensor components underwrites the smart water management supply chain, primarily sourced from East Asia and Europe. Key raw material dependencies include rare earth elements for advanced sensors and specialized polymers for durable metering hardware. Single-source vulnerability for embedded processors represents a structural risk for integrated system providers. Downstream distribution runs through a mix of direct sales to large municipal utilities and channel partnerships with local system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart water management market faces a significant capability gap in data science and network engineering skills within utility workforces. Bridging this gap is crucial for realizing the full potential of advanced monitoring and control systems.
For Market Incumbents:Secure long-term service contracts by bundling hardware, software, and ongoing data analytics support. This strategy mitigates the threat of new entrants offering point solutions and reinforces customer loyalty. Invest in developing interoperable platforms that can integrate with diverse legacy SCADA systems. Focus R&D on edge computing capabilities to reduce data transmission costs and improve real-time response for utilities.
For New Entrants and Emerging Players:Lead with niche, high-value applications like AI-powered predictive maintenance for critical infrastructure in water-stressed regions. The agricultural irrigation segment in Southern Europe presents a penetrable market for specialized sensor and analytics providers. Offer flexible, cloud-native solutions with clear return-on-investment metrics to appeal to capital-constrained municipal utilities.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among software platform providers offering cloud analytics and AI-driven insights. Seek acquisition targets with strong intellectual property in data security and interoperability protocols. The long-term viability of this market hinges on continued regulatory pressure for water efficiency and quality. Watch for increasing utility investment in digital twin technologies as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Interoperable Software APIs | Enables seamless integration with existing utility infrastructure, reducing deployment friction for clients. |
| Invest in Edge AI Capabilities | Minimizes data latency and enhances autonomous control actions within distributed water networks. |
| Form Strategic Partnerships with Integrators | Expands market reach and provides localized implementation expertise for complex utility projects. |
| Acquire Data Science Consulting Firms | Addresses the critical skill gap within utilities, offering high-value managed services for analytics. |
| Pilot Performance-Based Contracts | Aligns technology provider incentives with utility outcomes, accelerating adoption of smart solutions. |
Research Approach
A standing panel of utility operations managers, IoT hardware engineers, and environmental regulators provided ongoing calibration for market sizing and trend validation. This primary research was complemented by extensive secondary validation from public environmental agency reports and technology patent databases. The approach combined bottom-up market estimation with top-down industry analysis.
Outputs were validated against external benchmarks from leading technology associations to ensure consistency across the analysis window. The analytical framework modeled segmentation across technology, application, end-user, and solution type, with an industry-specific focus on non-revenue water reduction impact. Compound annual growth rates were derived from historical adoption patterns and projected technology penetration rates, using water scarcity indices as a key forecast input.
The analysis sits within stated boundaries; outcomes outside significant shifts in global water policy or climate change mitigation efforts would require recalibration. Forecasts reflect assumptions regarding continued technology cost reduction and regulatory enforcement. Practitioners should keep alternative scenarios live as utility investment cycles and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
Municipal Water Market
Water Management
Global Water Market
Water Management
Atmospheric Water Generator (AWG) Market
Water Management
NRW Smart Leak Management Market
Water Management
Spain Water Consumption Market
Water Management
Smart Water Network Market
Water Management
Mexico Water Consumption Market
Water Management
Water Utility Services Market
Water Management
Water Free Urinals Market
Water Management
Chile Water Consumption Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
Middle East and Africa Water Sink Market
Water Management
Water Trading Market
Water Management
France Water Consumption Market
Water Management
Asia-Pacific Water Sink Market
Water Management
North America Water Sink Market