
 Atmospheric Water Generator (AWG) Market | 2026-2036
Atmospheric Water Generator (AWG) Market Size, Share, and Industry Trends Forecast 2026-2036
Atmospheric Water Generator (AWG) Market Analysis
ISO 14001 environmental management certification is redrawing competitive boundaries in atmospheric water generation, favoring manufacturers with verified lifecycle assessments. Watergen leverages its Israeli R&D base to dominate military and emergency deployment contracts across arid zones. GENAQ Technologies S.L. anchors European commercial sales through modular designs that satisfy CE marking and local water quality ordinances. EcoloBlue, Inc. competes on consumer accessibility with countertop units distributed through retail channels in North America.
An atmospheric water generator extracts potable water from ambient air humidity through thermodynamic cooling, desiccant absorption, or membrane separation, typically achieving extraction rates of 15–10,000 liters per day depending on relative humidity and temperature conditions. The technology serves commercial and industrial users facing groundwater depletion, contamination events, or infrastructure gaps. Cooling-based systems occupy the largest installed base due to mature compressor supply chains and service networks. Desiccant technology represents the fastest-expanding segment because it operates efficiently below 30% relative humidity where mechanical refrigeration fails. Agricultural end users constitute a concentrated margin pool as irrigation districts pay premium pricing for guaranteed daily yields independent of rainfall variability.
The U.S. EPA enforces Safe Drinking Water Act standards that AWG output must meet when sold commercially, while California's State Water Resources Control Board imposes additional testing for emerging contaminants. The EU Drinking Water Directive, revised under the European Green Deal, now explicitly recognizes atmospheric water as a potable source subject to parametric compliance. Stakeholders must monitor how FDA food-contact regulations and state-level plumbing codes treat AWG integration into restaurant and hospitality supply chains as jurisdictional definitions fragment.
Market Dynamics
Desiccant technology is fragmenting the installed base of cooling-based atmospheric water generators as arid-zone operators demand extraction capability below 30% relative humidity where mechanical refrigeration fails.
Growth Catalysts
- EU Drinking Water Directive:The revised directive under the European Green Deal explicitly recognizes atmospheric water as a potable source, creating parametric compliance pathways for commercial AWG deployment across member states.
- Agricultural irrigation districts:Farmers facing groundwater depletion pay premium pricing for guaranteed daily yields independent of rainfall variability, concentrating margin pools in rural AWG procurement.
- Saudi Arabia's NEOM:Desert megaprojects are embedding atmospheric water generation into master-planned infrastructure, normalizing AWG as core utility infrastructure rather than backup supply.
Market Restraints
- Compressor supply chains:Cooling-based systems depend on mature refrigeration component networks concentrated in East Asian manufacturing clusters, exposing procurement to geopolitical friction and input cost volatility.
- Relative humidity floor:Mechanical refrigeration AWG units face technical incapacity below 30% humidity, excluding their deployment from hyper-arid zones without hybrid desiccant augmentation.
- California State Water Resources Control Board:Additional testing mandates for emerging contaminants create regulatory friction that extends commercial approval timelines and elevates compliance expenditure.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for clean technology manufacturing could localize AWG assembly and reduce landed cost for South Asian agricultural and industrial buyers.
- Membrane separation convergence:Hybrid systems combining desiccant absorption with selective membrane filtration promise energy efficiency gains that open municipal-scale contracts currently held by reverse osmosis.
- Restaurant and hospitality supply chains:FDA food-contact regulations and state-level plumbing codes are clarifying AWG integration protocols, creating first-mover advantage for certified equipment in commercial kitchen retrofits.
Industry Challenges
- ISO 14001 certification timelines:Lifecycle assessment verification for environmental management certification demands 12-18 month documentation cycles that delay competitive positioning in European public tenders.
- After-sales service networks:Desiccant technology requires specialized maintenance protocols distinct from refrigeration servicing, creating talent gaps in field technician availability across distributed installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atmospheric Water Generator (AWG) Market |
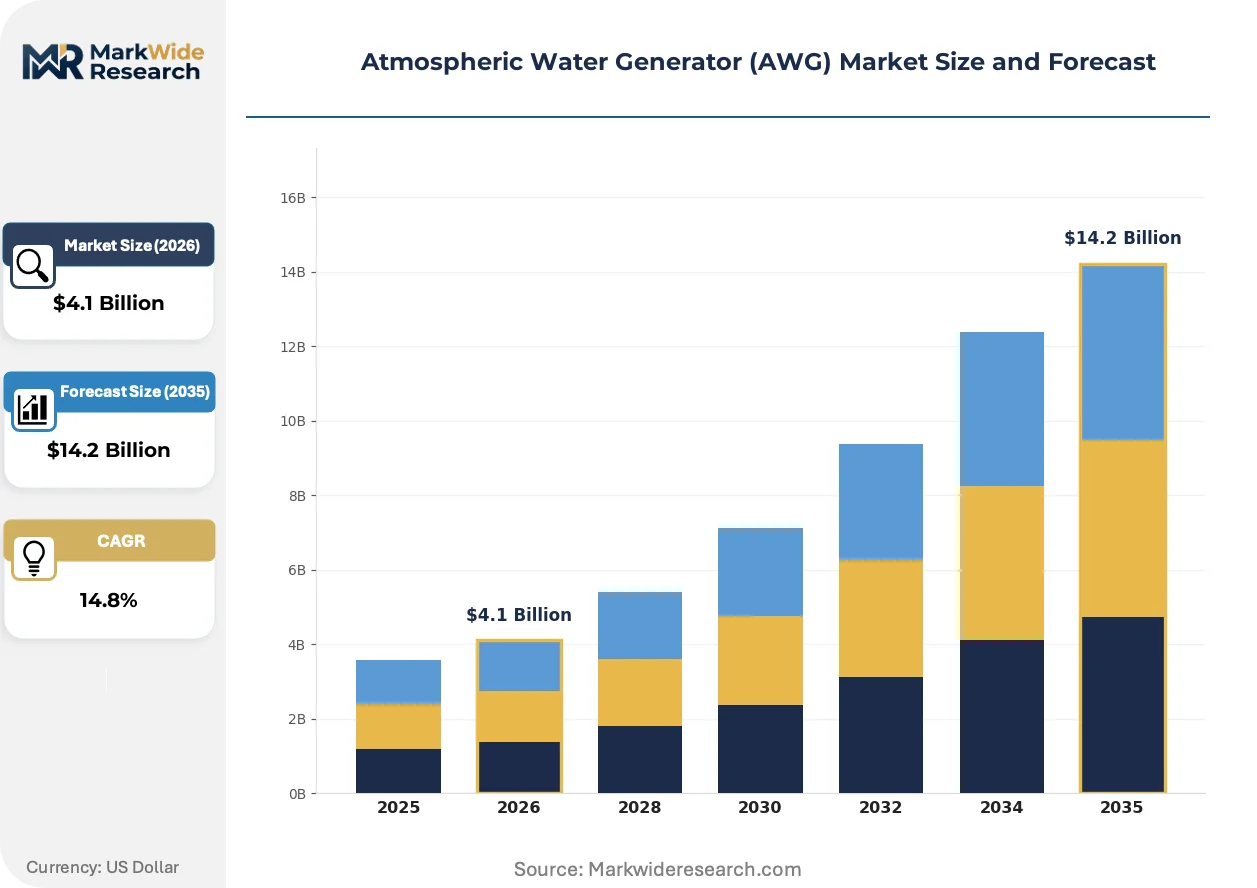
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $14.2 Billion |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Mobile, Atmospheric, Hybrid Technology: Cooling, Desiccant, Membrane, Chemical End User: Residential, Industrial, Commercial, Agriculture Deployment: On-Premise, Off-Grid, Centralized, Decentralized |
| Companies Covered | Dew Point Manufacturing, Atlantis Solar, Akvo Atmospheric Water Systems Pvt. Ltd., EcoloBlue, Inc., Drinkable Air, Watergen, Water Technologies International, Inc., Energy and Water Development Corp., GENAQ Technologies S.L., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atmospheric Water Generator (AWG) Market Emerging Trajectories
Active materials research and regulatory recognition of atmospheric water as a potable source are converging to expand addressable humidity ranges and accelerate commercial deployment timelines.
Desiccant wheel technology is fragmenting the product landscape as manufacturers engineer hygroscopic coatings that achieve extraction rates competitive with cooling systems at 20% relative humidity. Agricultural cooperatives in Australia's Murray-Darling Basin are piloting these units for drought-proof irrigation. The structural consequence is compressing the addressable market advantage of legacy compressor-based equipment in semi-arid zones.
REACH chemical registration requirements in Europe are forcing reformulation of desiccant materials away from lithium chloride toward silica gel and metal-organic frameworks. Industrial AWG manufacturers serving EU markets must resubmit material safety dossiers. Food and beverage processing facilities face the tightest compliance windows as they integrate atmospheric water into product-contact applications.
Buyers are unbundling after-sales service from equipment procurement, contracting third-party maintenance providers rather than manufacturer service networks. This pattern is most visible in North American commercial deployments where facility managers prioritize response-time guarantees over brand-aligned technician dispatch. Distributor margins compress as service revenue migrates to independent HVAC contractors with existing regional coverage.
Atmospheric Water Generator (AWG) Market Segmentation
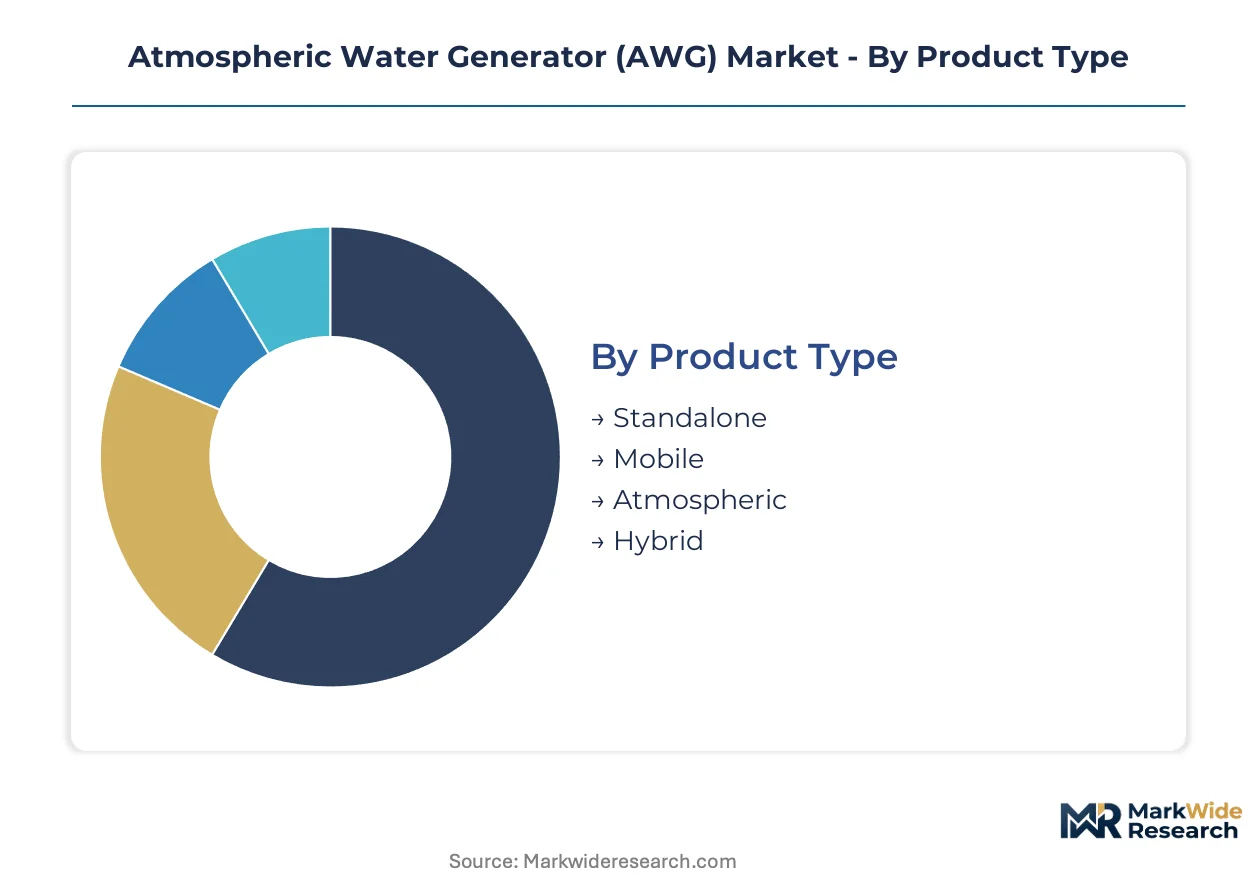
AWG procurement channels diverge sharply across segment boundaries. Industrial buyers contract directly with manufacturers for centralized installations, while residential and commercial segments flow through distributor networks with attached service agreements.
Product Type:
Channel economics vary substantially across form factors, with mobile and hybrid units commanding premium placement fees in emergency response catalogs.
- Standalone:Fixed-installation units with 500–10,000 liter daily capacity anchor municipal and industrial procurement in Saudi Arabia's NEOM and UAE desert megaprojects. Water-stressed regions favor these for permanent infrastructure integration where grid power is stable.
- Mobile:Trailer-mounted or vehicle-integrated systems serve military logistics and disaster relief deployments across arid zones. Israeli R&D bases supply these through defense procurement channels with rapid-fielding requirements.
- Atmospheric:Compact residential units extract 15–50 liters daily for single-family use in North American retail channels.
- Hybrid:Configurations combining AWG with solar or battery storage address off-grid agricultural demand in Australia's Murray-Darling Basin.
Standalone dominates installed base. Hybrid is where expansion concentrates.
Technology:
Cost tiers separate mature compressor supply chains from emerging desiccant material platforms with specialized maintenance protocols.
- Cooling:Vapor-compression refrigeration achieves extraction above 30% relative humidity through mature component networks concentrated in East Asian manufacturing clusters. These systems face procurement exposure to geopolitical friction and input cost volatility.
- Desiccant:Hygroscopic absorption operates efficiently below 30% humidity where mechanical refrigeration fails. REACH chemical registration in Europe is forcing reformulation away from lithium chloride toward silica gel and metal-organic frameworks.
- Membrane:Selective permeation systems promise energy efficiency gains for municipal-scale contracts.
- Chemical:Reaction-based extraction remains experimental for extreme aridity conditions.
Cooling retains volume leadership. Desiccant is climbing the fastest as arid-zone operators demand sub-30% humidity capability.
End User:
Margin pools concentrate in agricultural districts paying premium pricing for irrigation yield guarantees independent of rainfall variability.
- Industrial:Factories and processing plants facing groundwater depletion deploy AWG as primary supply across water-stressed manufacturing corridors. EPA Safe Drinking Water Act amendments tighten potable source standards, pushing commercial buyers toward decentralized atmospheric extraction.
- Agricultural:Irrigation districts in drought-prone regions purchase high-capacity units with guaranteed daily output contracts. Australia's agricultural cooperatives pilot desiccant wheels for drought-proofing in the Murray-Darling Basin.
- Commercial:Hotels, restaurants, and office buildings integrate AWG for branding and resilience.
- Residential:Countertop units target consumer accessibility through retail distribution.
Agricultural captures the steepest margin expansion. Industrial provides the largest contract value per installation.
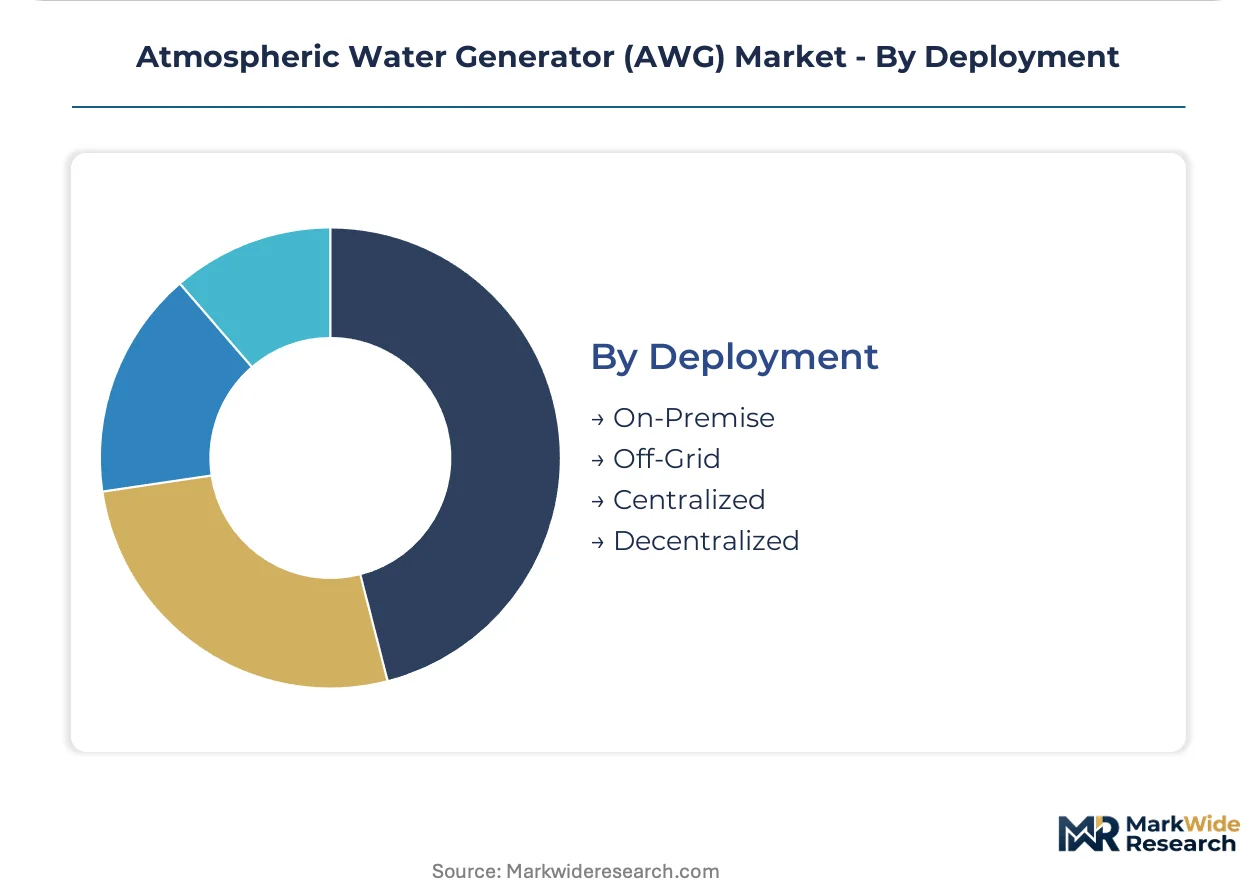
Deployment:
Supply concentration in centralized systems is fragmenting as decentralized architectures gain favor in distributed agricultural and commercial applications.
- On-Premise:Building-integrated systems serve hospitality and healthcare facilities requiring point-of-use potable water. FDA food-contact regulations and state-level plumbing codes are clarifying integration protocols for restaurant retrofits.
- Decentralized:Modular cluster deployments replace failing municipal infrastructure in rural and peri-urban zones. India's PLI scheme for clean technology manufacturing could localize assembly and reduce landed cost for South Asian buyers.
- Off-Grid:Remote installations pair AWG with renewable generation for mining camps and frontier settlements.
- Centralized:Utility-scale plants serve master-planned communities with dedicated distribution networks.
On-Premise leads current procurement volume. Decentralized is gaining share fastest as infrastructure gaps widen in water-stressed regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in water-stressed manufacturing corridors dominate procurement decisions, with municipal utilities and agricultural cooperatives forming secondary demand clusters across distinct regulatory environments.
United States
Commercial facilities facing groundwater depletion in Arizona and California drive centralized AWG procurement. EPA Safe Drinking Water Act amendments tighten potable source standards, pushing buyers toward decentralized atmospheric extraction. The Central Valley agricultural belt pilots desiccant-wheel systems for drought-proof irrigation.
Saudi Arabia
Desert megaprojects embed atmospheric water generation into master-planned infrastructure as core utility supply. The Saudi Food and Drug Authority and national water regulator establish parametric compliance pathways for commercial deployment. NEOM's northwest development zone normalizes AWG integration alongside renewable generation clusters.
India
Agricultural cooperatives in Maharashtra and Gujarat purchase high-capacity units with guaranteed daily output contracts independent of monsoon variability. The Production-Linked Incentive scheme for clean technology manufacturing could localize assembly and reduce landed costs. Tamil Nadu's industrial corridors deploy AWG as primary supply where municipal infrastructure gaps persist.
Australia
Irrigation districts in the Murray-Darling Basin pay premium pricing for yield guarantees during extended drought cycles. The Therapeutic Goods Administration and state-level water quality frameworks govern potable output standards. Queensland mining camps pair off-grid AWG installations with solar generation for remote workforce supply.
Germany
Industrial processors facing Rhine water level volatility integrate AWG for process water resilience. REACH chemical registration requirements force desiccant material reformulation toward silica gel and metal-organic frameworks. Bavaria's food and beverage facilities face compressed compliance windows for product-contact atmospheric water integration.
Atmospheric Water Generator (AWG) Market Vendor Landscape
Player mix skews toward technology-specialist fabricators with regional service networks, creating a tiered structure where ISO 14001 certification separates premium-positioned suppliers from commodity competitors. Two strategic archetypes dominate: Israeli and European manufacturers with military-to-commercial technology transfer capabilities, and North American distributors optimizing retail channel penetration. Competitive moves concentrate on geographic licensing partnerships and backward integration into desiccant material supply.
Within the technology-transfer archetype, Watergen and GENAQ Technologies S.L. exemplify manufacturers leveraging defense-sector R&D origins for commercial market positioning. EcoloBlue, Inc. anchors the consumer-accessibility tier through countertop unit distribution. These three occupy distinct competitive spaces rather than direct confrontation, with geographic origin and certification portfolios determining tender eligibility more than price-point overlap.
| Leading Market Players |
|---|
| Dew Point Manufacturing |
| Atlantis Solar |
| Akvo Atmospheric Water Systems Pvt. Ltd. |
| EcoloBlue, Inc. |
| Drinkable Air |
| Watergen |
| Water Technologies International, Inc. |
| Energy and Water Development Corp. |
| GENAQ Technologies S.L. |
| Others |
Supply Flow & Price Mechanics
ISO 14001 environmental management certification gates supply qualification and price differentiation simultaneously, filtering commodity competitors from premium-positioned suppliers in European public tenders while compressing margins for uncertified entrants across water-stressed manufacturing corridors.
Pricing Analysis
Cost-plus contracts with energy-indexed adjustments dominate industrial procurement in Saudi Arabia's NEOM and UAE desert megaprojects, insulating buyers from compressor input volatility while locking in supplier margins. Price differentiation rests on ISO 14001 certification tier and after-sales service bundling, with certified manufacturers commanding placement in municipal tenders. Cost compression in cooling-based systems is intensifying because East Asian component networks face geopolitical friction. Agricultural irrigation districts exhibit lowest price sensitivity due to yield guarantee premiums, while North American retail channels face acute pressure from countertop unit commoditization.
Supply Chain Analysis
Inventory cycles for desiccant materials stretch 16-20 weeks longer than compressor components, constraining rapid scaling for arid-zone deployments below 30% relative humidity. Manufacturing gravity centers on China, South Korea, and Germany for refrigeration compressors, desiccant coatings, and precision membrane fabrication respectively. Raw material dependencies span lithium chloride alternatives under REACH reformulation, silica gel feedstocks, and metal-organic framework precursors. Single-source vulnerability concentrates in hygroscopic coating formulations transitioning away from lithium chloride. Distribution runs through manufacturer-direct channels for industrial buyers and HVAC contractor networks for commercial retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of field technicians trained in desiccant maintenance protocols is constraining deployment velocity in distributed agricultural installations, creating acquisition premiums for manufacturers with captive service networks.
For Market Incumbents: Shield installed base advantage by backward integration into desiccant material supply and accelerating ISO 14001 certification timelines for European tender eligibility. Compressor supply chain fragmentation in East Asia threatens input cost stability; captive coating formulation capabilities reduce REACH compliance exposure. Capacity addition in India's PLI-eligible zones captures South Asian agricultural demand. For New Entrants and Emerging Players: Differentiate on membrane-desiccant hybrid architectures that promise municipal-scale energy efficiency gains currently held by reverse osmosis. Australia's Murray-Darling Basin irrigation cooperatives present the most penetrable agricultural segment due to drought-cycle urgency. Go-to-market through independent HVAC contractors rather than manufacturer service networks aligns with North American facility manager preferences for response-time guarantees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across desiccant technology platforms as material science matures and production scales. Long-term viability favors manufacturers with defense-sector R&D origins capable of military-to-commercial technology transfer. Target acquisition archetype: mid-cap specialists with verified lifecycle assessments and regional service density in water-stressed manufacturing corridors. Signal to watch: FDA food-contact regulation finalization for restaurant integration protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Desiccant Materials | REACH reformulation mandates captive supply of silica gel and metal-organic framework coatings. |
| ISO 14001 Certification Acceleration | Twelve-to-eighteen month documentation cycles gate European public tender eligibility and premium positioning. |
| Hybrid System Development | Membrane-desiccant convergence opens municipal contracts from incumbent reverse osmosis operators. |
| Service Network Captivity | Third-party maintenance migration in North America creates acquisition value for regional HVAC contractor partnerships. |
| PLI Scheme Localization | India's clean technology manufacturing incentives reduce landed cost for South Asian agricultural and industrial buyers. |
Methodological Framework
A spread of perspectives from AWG plant engineers, agricultural cooperative procurement managers, municipal utility planners, and desiccant material R&D directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA Safe Drinking Water Act filings, EU Drinking Water Directive implementation reports, customs and trade data for compressor component flows, and SEC disclosures from publicly traded water technology firms. Bottom-up unit economics triangulated against top-down market sizing across deployment archetypes.
Segmentation dimensions modeled span product type (standalone, mobile, hybrid), technology platform (cooling, desiccant, membrane), end-user vertical (industrial, agricultural, commercial, residential), and deployment architecture (on-premise, decentralized, off-grid, centralized). CAGRs were derived from installed base expansion rates, replacement cycles, and penetration assumptions across water-stressed geographies. Industry-specific forecast inputs include relative humidity threshold technical capabilities, REACH chemical registration timelines, and PLI scheme localization trajectories.
Decision-makers should treat outputs as directional under assumptions of stable compressor supply chain access and continued regulatory recognition of atmospheric water as potable source; material deviation in East Asian manufacturing concentration or EU desiccant material bans would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
Water Free Urinals Market
Water Management
Smart Water Management Market
Water Management
Mexico Water Consumption Market
Water Management
Chile Water Consumption Market
Water Management
Middle East and Africa Water Sink Market
Water Management
Asia-Pacific Water Sink Market
Water Management
NRW Smart Leak Management Market
Water Management
Water Trading Market
Water Management
North America Water Sink Market
Water Management
Water Utility Services Market
Water Management
France Water Consumption Market
Water Management
Smart Water Network Market
Water Management
Global Water Market
Water Management
Water Filters Market
Water Management
Municipal Water Market
Water Management
US Water Leak Detection and Repair Services Market