
 Smart Water Network Market | 2026-2036
Smart Water Network Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Water Network Market Outlook
European sensor manufacturers is consolidating around precision flow instrumentation for smart water networks. Xylem Inc. leverages its vertical integration across pump systems and analytics platforms to control project pipelines. Siemens AG anchors European utility automation through SCADA-to-cloud architectures. Badger Meter Inc. specializes in ultrasonic metering technology that sustains margins in North American municipal tenders.
A smart water network integrates sensor arrays, telemetry infrastructure, and analytics software to monitor hydraulic performance, detect anomalies, and automate distribution decisions across potable water systems. These networks typically operate at pressure thresholds of 20-80 psi with sampling frequencies from 15-minute intervals to real-time streaming for critical nodes. IoT Solutions and Smart Meters represent the dominant technology stack where utility procurement concentrates, while Data Analytics commands expanding margin pools as utilities shift from hardware purchase to subscription-based intelligence services. Cloud-based Solutions lead deployment preferences among mid-sized municipalities seeking lower capital burden, though Hybrid Solutions are gaining traction where cybersecurity policies mandate on-premise data sovereignty for critical infrastructure.
EPA drinking water standards, EU Drinking Water Directive revisions, and ISO 24500 series guidelines collectively shape product certification requirements and procurement eligibility across major markets. The EU Green Deal's water efficiency targets are forcing equipment vendors to document lifecycle carbon metrics before qualifying for public tenders. Stakeholders must weigh interoperability standards against vendor lock-in risks as utilities migrate from legacy AMR systems to fully networked AMI architectures.
Market Dynamics
The transition from automated meter reading to advanced metering infrastructure is compressing procurement cycles as utilities consolidate vendor relationships around full-stack platform providers capable of unified hardware-software deployment.
Growth Catalysts
- EPA Lead-and-Copper Rule Revisions:Municipal utilities across the United States face mandated lead service line inventory deadlines that accelerate sensor network deployment for real-time contamination monitoring.
- IoT Sensor Miniaturization:Reduced form factors enable retrofit installation in legacy pipe networks without excavation, expanding addressable infrastructure in aging distribution systems.
- California Central Valley Agricultural Districts:Severe drought stress drives precision irrigation networks that integrate soil moisture telemetry with municipal water allocation systems.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea fabs control 73% of industrial-grade microcontroller production, creating vulnerability in telemetry module lead times.
- Cybersecurity Compliance Burden:NERC CIP standards and state-level critical infrastructure mandates impose multi-year certification timelines that delay network activation.
- Legacy AMR System Stranding:Existing drive-by meter reading infrastructure represents sunk capital that finance committees resist writing off prematurely.
Strategic Opportunities
- EU Green Deal Water Efficiency Targets:Lifecycle carbon documentation requirements for public tenders favor vendors with vertically integrated manufacturing and verified supply chain emissions data.
- Subscription Analytics Migration:Utilities in Germany and France are unbundling hardware purchase from intelligence services, creating recurring revenue pools for platform providers.
- Edge Computing Convergence:Integration of on-premise analytics with cloud orchestration enables hybrid architectures that satisfy data sovereignty policies while preserving scalability.
Industry Challenges
- SCADA-to-Cloud Integration Complexity:Decades-old supervisory control systems utilize proprietary protocols that resist API standardization, forcing costly middleware development.
- Interoperability Certification Delays:Fragmented testing regimes across ISO 24500, AWWA M36, and national variants prolong product qualification timelines.
- Field Engineering Talent Scarcity:Deployment of pressure-correlating acoustic leak detection requires specialized technicians that vocational pipelines have failed to replenish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Water Network Market |
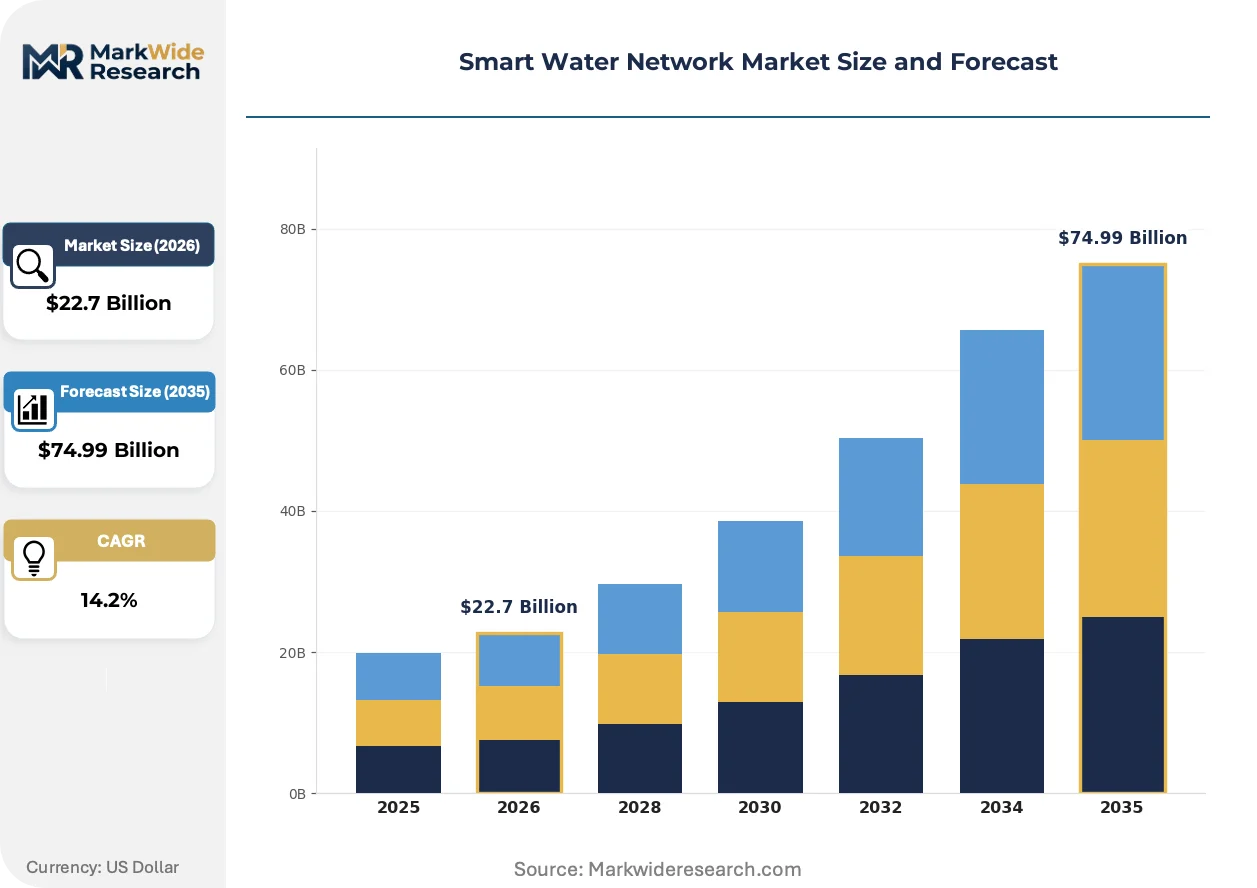
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $74.99 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, Smart Meters, SCADA Systems, Data Analytics End User: Municipalities, Industrial Facilities, Residential Customers, Agriculture Application: Leak Detection, Water Quality Monitoring, Flow Management, Asset Management Deployment: Cloud-based Solutions, On-premise Solutions, Hybrid Solutions, Edge Computing |
| Companies Covered | Itron Inc., Badger Meter Inc., Xylem Inc., Siemens AG, Honeywell International Inc., Schneider Electric SE, ABB Ltd., SUEZ SA, Kamstrup A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Water Network Market Strategic Shifts
Digital twin technology is migrating from design-phase simulation to operational decision support, enabling utilities to model hydraulic transients and optimize pressure management in real time. This shift demands recalibration of vendor capabilities toward physics-based modeling expertise.
Ultrasonic flow metering is consolidating around solid-state designs that eliminate mechanical wear components. California agricultural cooperatives and Texas municipal utilities are prioritizing these sensors for high-sediment water sources. The technology is consolidating supplier margins by extending calibration intervals from annual to multi-year cycles, compressing aftermarket service revenue.
The EU Drinking Water Directive revision mandates enhanced monitoring of emerging contaminants including per- and polyfluoroalkyl substances. Equipment vendors must now demonstrate detection thresholds below 0.1 micrograms per liter to qualify for public procurement. Dutch and Danish utilities are pioneering multi-parameter sensor arrays that consolidate chlorine, turbidity, and PFAS measurement into single nodes.
Municipal finance departments are unbundling capital expenditure from operational technology budgets, accelerating software-as-a-service contracting for network analytics. Mid-sized utilities in Ohio and Pennsylvania are displacing perpetual license models with consumption-based pricing indexed to connected meter counts. This restructuring concentrates purchasing authority within chief financial officer functions rather than engineering departments.
Smart Water Network Market Segmentation
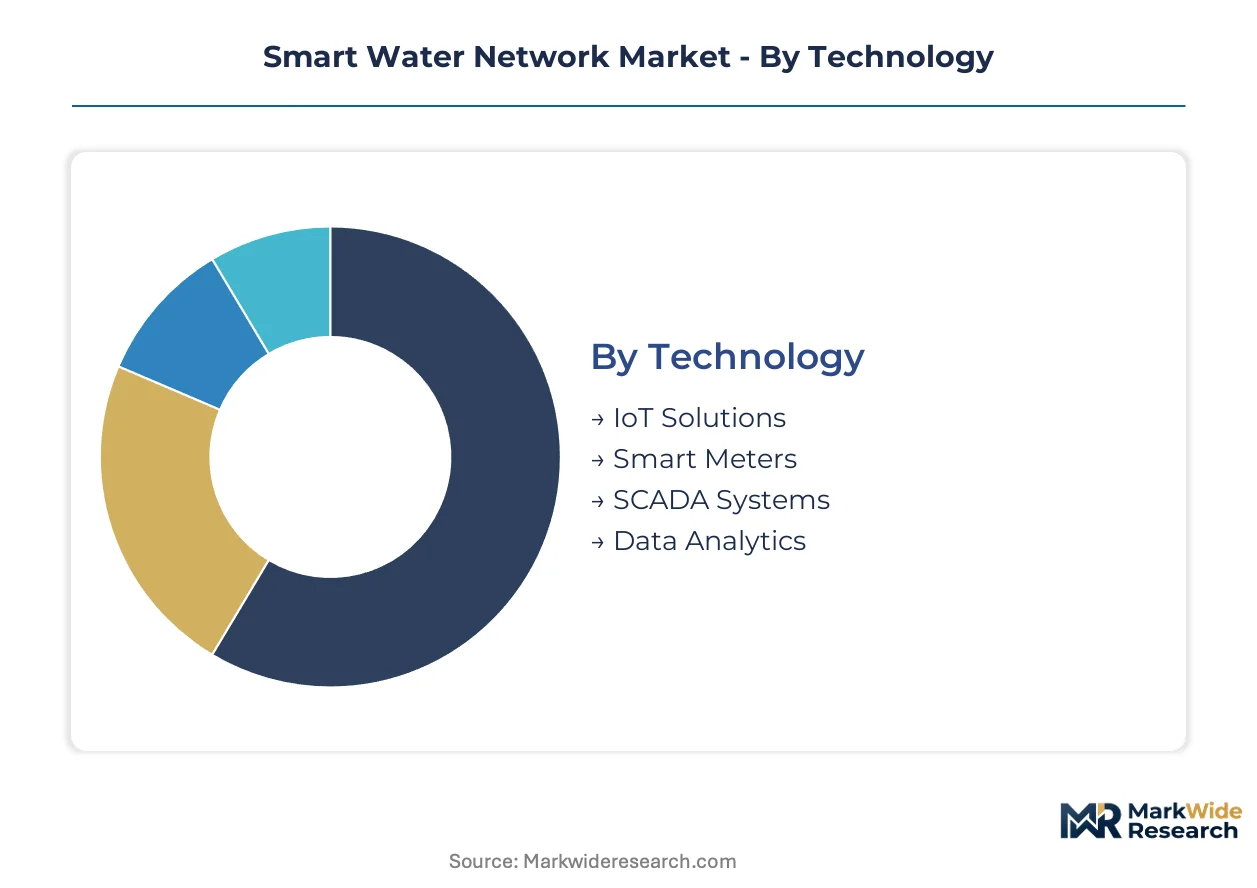
Smart water network procurement concentrates around technology stacks that unify hardware telemetry with software intelligence. Utility capital allocation patterns vary sharply across deployment architectures and end-user sophistication levels. Segment boundaries are blurring as platform providers bundle previously discrete capabilities into unified offerings.
Technology:
Supply concentration in microcontroller fabrication and sensor miniaturization favors vendors with captive component sourcing or long-term foundry partnerships.
- IoT Solutions:Sensor arrays and telemetry modules transmit pressure, flow, and quality data across distribution networks at frequencies ranging from 15-minute intervals to real-time streaming. Municipal utilities in California's Central Valley and Texas municipal systems are prioritizing retrofit-compatible form factors that install without excavation. Component lead times from Taiwan and South Korea fabs create procurement vulnerability for vendors without buffer inventory.
- Smart Meters:Solid-state ultrasonic designs eliminate mechanical wear components and extend calibration intervals from annual to multi-year cycles. North American municipal tenders favor these units for high-sediment water sources where traditional mechanical meters degrade rapidly. Margin compression in hardware sales is pushing vendors toward subscription-based intelligence services.
- SCADA Systems:Decades-old supervisory control infrastructure utilizing proprietary protocols resists cloud API standardization.
- Data Analytics:Physics-based hydraulic modeling and anomaly detection algorithms command expanding margin pools as utilities shift from perpetual licenses to consumption-based pricing.
Smart Meters absorb the bulk of installed capacity; Data Analytics is expanding most quickly.
End User:
Customer type determines procurement authority structures and budget cycle alignment, with CFO-led purchasing displacing traditional engineering department authority.
- Municipalities:City and county water utilities face EPA lead-and-copper rule deadlines that mandate real-time contamination monitoring infrastructure. Procurement cycles are compressing as finance committees consolidate vendor relationships around full-stack platform providers. Ohio and Pennsylvania mid-sized utilities are unbundling capital expenditure from operational technology budgets.
- Industrial Facilities:Manufacturing and processing plants require high-reliability flow instrumentation with cybersecurity certifications under NERC CIP standards. Multi-year certification timelines delay network activation for critical infrastructure operators. On-premise data sovereignty policies favor hybrid deployment architectures.
- Residential Customers:Individual household metering drives volume demand for cost-optimized ultrasonic units with cellular or mesh network connectivity.
- Agriculture:California Central Valley cooperatives integrate soil moisture telemetry with municipal allocation systems under severe drought stress.
Municipalities command the dominant share of contract value; Agriculture is gaining share fastest.
Application:
Functional use case determines sensor specification requirements and integration complexity with legacy infrastructure.
- Leak Detection:Pressure-correlating acoustic sensors identify distribution system breaches through transient waveform analysis. Deployment requires specialized field engineering talent that vocational pipelines have failed to replenish. Dutch utilities are pioneering multi-parameter nodes that consolidate leak detection with quality monitoring.
- Water Quality Monitoring:Multi-parameter arrays measure chlorine, turbidity, and emerging contaminants including PFAS at detection thresholds below 0.1 micrograms per liter. EU Drinking Water Directive revisions mandate enhanced monitoring that qualifies vendors for public procurement only with documented lifecycle carbon metrics.
- Flow Management:Real-time hydraulic optimization through digital twin modeling enables pressure management that reduces non-revenue water.
- Asset Management:Predictive maintenance algorithms extend infrastructure lifecycle through condition-based intervention scheduling.
Leak Detection carries the largest installed base; Water Quality Monitoring shows the steepest expansion trajectory.
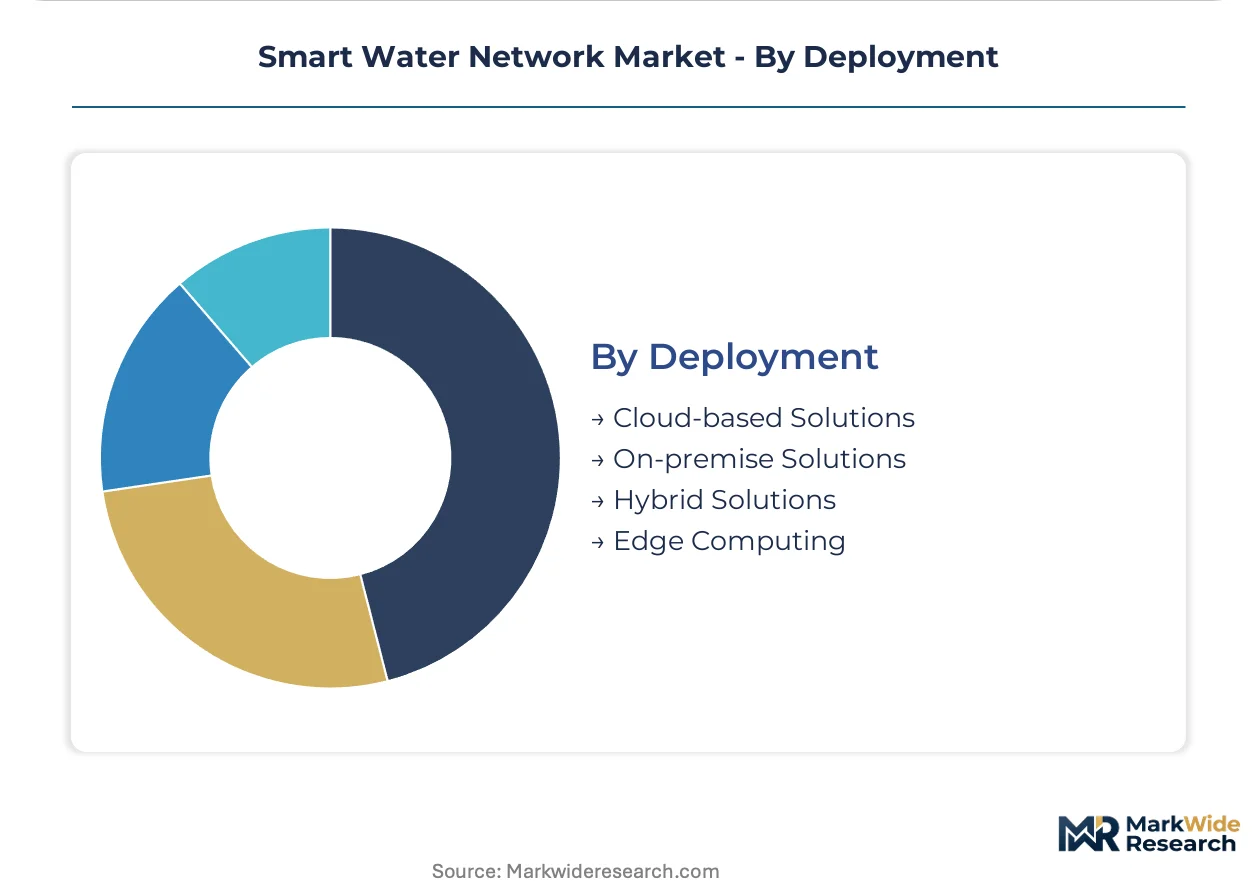
Deployment:
Architecture choice reflects cybersecurity policy constraints against scalability requirements in utility risk assessments.
- Cloud-based Solutions:Fully hosted analytics platforms reduce capital burden for mid-sized municipalities with limited IT infrastructure. German and French utilities are unbundling hardware purchase from intelligence services, creating recurring revenue concentration for platform providers. Data sovereignty concerns limit adoption where critical infrastructure policies mandate on-premise control.
- Hybrid Solutions:Edge computing convergence integrates on-premise analytics with cloud orchestration to satisfy security policies while preserving scalability. Texas municipal utilities and California agricultural districts prioritize this architecture for operational continuity during connectivity disruptions.
- On-premise Solutions:Air-gapped installations serve utilities with strict cybersecurity mandates and legacy SCADA integration requirements.
- Edge Computing:Distributed processing nodes enable real-time decision autonomy without cloud latency for critical control loops.
Cloud-based Solutions dominate new procurement volume; Hybrid Solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry concentration in Taiwan and South Korea anchors component supply for telemetry modules deployed across distribution networks worldwide. Municipal procurement cycles vary sharply by regulatory deadline proximity and infrastructure age profiles.
United States
EPA lead-and-copper rule revisions mandate real-time contamination monitoring infrastructure with 2024 inventory deadlines accelerating sensor deployment. Ohio and Pennsylvania mid-sized utilities are unbundling capital expenditure from operational technology budgets to finance SaaS analytics contracts. The Central Valley agricultural districts in California integrate soil moisture telemetry with municipal allocation systems under severe drought stress.
Germany
EU Green Deal water efficiency targets force equipment vendors to document lifecycle carbon metrics before qualifying for public tenders. The country's national drinking water regulator enforces enhanced monitoring standards that favor hybrid deployment architectures. Bavarian and North Rhine-Westphalian utilities are pioneering subscription-based intelligence services that separate hardware purchase from analytics licensing.
China
National dual carbon goals and smart city initiatives drive municipal investment in pressure management and non-revenue water reduction. The Ministry of Ecology and Environment mandates enhanced water quality monitoring in key river basins. Yangtze River Delta municipalities are deploying edge computing nodes for real-time hydraulic optimization without cloud latency.
Netherlands
EU Drinking Water Directive revisions require detection thresholds below 0.1 micrograms per liter for emerging contaminants including PFAS. Dutch utilities pioneer multi-parameter sensor arrays consolidating chlorine, turbidity, and contaminant measurement. Randstad water authorities are migrating from legacy AMR systems to fully networked AMI architectures with cybersecurity-compliant data sovereignty.
Australia
Severe drought cycles in New South Wales and Queensland drive precision irrigation network integration with municipal allocation systems. The country's national water quality regulator enforces standards aligned with ISO 24500 series guidelines for smart network certification. Sydney Water and Melbourne metropolitan utilities are deploying digital twin technology for operational decision support and pressure transient modeling.
Smart Water Network Market Competitive Environment
Global majors compete with regional champions across platform integration capabilities and local regulatory familiarity. The vendor base organizes around three tiers: full-stack platform providers with captive hardware-software deployment, specialized sensor manufacturers with precision flow instrumentation expertise, and analytics pure-plays migrating utilities to subscription intelligence models. Dominant competitive moves include vertical integration of component supply and strategic partnerships bridging SCADA-to-cloud protocol gaps.
Within the full-stack platform tier, Xylem Inc. and Siemens AG exemplify archetypes of unified deployment capability. Itron Inc. and Badger Meter Inc. represent North American specialists in metering technology and AMI infrastructure. SUEZ SA and Schneider Electric SE anchor European positions through utility automation and water services integration.
| Leading Market Players |
|---|
| Itron Inc. |
| Badger Meter Inc. |
| Xylem Inc. |
| Siemens AG |
| Honeywell International Inc. |
| Schneider Electric SE |
| ABB Ltd. |
| SUEZ SA |
| Kamstrup A/S |
| Others |
Value Chain & Pricing Dynamics
Captive semiconductor sourcing from Taiwan and South Korea fabs anchors vendor pricing power in telemetry module production, while unbundled analytics subscriptions compress hardware margins across North American municipal tenders. Component concentration forces tiered pricing stratification that separates full-stack platform providers from specialized sensor manufacturers.
Pricing Analysis
Warranty and calibration-service bundling separates premium ultrasonic meter vendors from economy-tier competitors in California agricultural districts and Texas municipal systems. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 24500 certification status and multi-year calibration interval guarantees. Cost compression in hardware-only tiers is intensifying because utilities unbundle capital expenditure from SaaS analytics contracts. Mid-sized municipalities in Ohio and Pennsylvania demonstrate highest price sensitivity, while industrial facilities under NERC CIP mandates absorb premium cybersecurity-certified equipment.
Supply Chain Analysis
Field engineering talent scarcity in Taiwan and South Korea constrains telemetry module assembly capacity despite abundant semiconductor fabrication. Microcontroller production draws from TSMC and Samsung foundry networks, while sensor miniaturization feeds from Japanese precision optics and German flow instrumentation expertise. Single-source vulnerability in industrial-grade microcontroller supply creates procurement risk for vendors without buffer inventory. Distribution runs through authorized system integrators who bridge SCADA-to-cloud protocol gaps for municipal utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Water Network Market sits in a technology-transition phase where AMI architectures displace legacy AMR drive-by infrastructure. Solid-state ultrasonic metering and physics-based digital twin modeling represent the replacement technologies reshaping competitive positioning.
For Market Incumbents: Anchor platform consolidation around full-stack hardware-software deployment to defend against specialized analytics pure-plays unbundling intelligence services. Deepen backward integration into semiconductor sourcing through long-term foundry partnerships in Taiwan and South Korea. Prioritize ISO 24500 certification investment to maintain eligibility for EU Green Deal-mandated public tenders.
For New Entrants and Emerging Players: Enter via California Central Valley agricultural cooperatives where drought-stressed precision irrigation networks lack integrated soil moisture telemetry. Target mid-sized German and French utilities separating hardware purchase from subscription analytics. Pursue edge computing convergence as the go-to-market angle for hybrid deployment architectures satisfying data sovereignty policies.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by full-stack platform providers seeking SCADA-to-cloud middleware capabilities and field engineering talent pools. Long-term viability favors vendors with documented lifecycle carbon metrics and verified supply chain emissions data for EU public tender qualification. Watch NERC CIP certification timeline acceleration as the inflection signal indicating industrial facility procurement cycle normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| SCADA-to-Cloud Platform Integration | Resolves proprietary protocol barriers that delay network activation for municipal utilities. |
| Ultrasonic Metering Product Launch | Extends calibration intervals from annual to multi-year cycles for high-sediment water sources. |
| Strategic Partnership with Foundry Networks | Secures microcontroller allocation from Taiwan and South Korea fabs amid supply concentration. |
| Acquisition of Analytics Pure-Play | Captures recurring revenue pools as utilities migrate from perpetual licenses to consumption-based pricing. |
| Geographic Expansion into California Central Valley | Addresses drought-driven demand for precision irrigation networks integrating soil moisture telemetry. |
Study Parameters
Multi-period observation of AMI procurement cycles, EPA compliance deadline proximity, and semiconductor lead time volatility anchored the trend analysis, supplemented by interviews with municipal utility engineering directors, water authority CFOs, SCADA systems integrators, and precision agriculture cooperative managers. Secondary validation drew from EPA enforcement databases, EU Drinking Water Directive revision texts, ISO 24500 certification registries, and foundry utilization disclosures. Bottom-up project pipeline tracking triangulated against top-down utility capital expenditure surveys.
Input-output matrix modeling connected technology adoption rates, regulatory deadline schedules, and component supply constraints to segment-level value projections across the analysis window. Segmentation dimensions included deployment architecture, end-user procurement authority structure, application functional use case, and regional regulatory cluster. CAGRs derived from utility budget cycle alignment patterns and vendor pricing migration trajectories. Industry-specific forecast inputs incorporated EPA lead service line inventory completion rates and EU Green Deal tender qualification timelines.
Revisions become necessary when semiconductor fab utilization shifts, cybersecurity certification timelines compress, or municipal finance committee procurement authority restructures materialize. Forecasts reflect documented assumptions about regulatory deadline adherence and component supply continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
Water Free Urinals Market
Water Management
Global Water Market
Water Management
Asia-Pacific Water Sink Market
Water Management
Chile Water Consumption Market
Water Management
Atmospheric Water Generator (AWG) Market
Water Management
Middle East and Africa Water Sink Market
Water Management
France Water Consumption Market
Water Management
Municipal Water Market
Water Management
Water Utility Services Market
Water Management
Smart Water Management Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
Mexico Water Consumption Market
Water Management
Water Filters Market
Water Management
North America Water Sink Market
Water Management
Water Trading Market
Water Management
NRW Smart Leak Management Market