
 Global Desalination System Market | 2026-2036
Global Desalination System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Desalination System Market Analysis
ISO 14001 environmental management certification is reorganizing supplier qualification protocols for large-scale desalination tenders, particularly in the Middle East where project finance requires verified sustainability credentials. Veolia leverages its integrated operations platform across multiple coastal utilities. Doosan Enerbility anchors heavy thermal desalination engineering for mega-scale plants in the Persian Gulf. Toray Industries specializes in advanced membrane chemistry for high-salinity feedwater conditions.
A desalination system removes dissolved salts and minerals from seawater, brackish water, or wastewater through thermal distillation or pressure-driven membrane separation, typically achieving product water below 500 ppm total dissolved solids for potable or industrial use. Reverse osmosis membrane technologies dominate new capacity additions due to lower energy intensity compared to thermal alternatives, though multi-effect distillation retains share where waste heat integration is feasible. Municipalities represent the largest end-user segment by installed base, while the industrial sector—particularly power generation and petrochemicals—generates the fastest-growing demand for high-purity process water.
The EPA regulates brine discharge limits under the Clean Water Act in the United States, while Saudi Arabia's Saline Water Conversion Corporation enforces efficiency benchmarks that shape technology selection for new projects. The EU Water Framework Directive and REACH chemical registration requirements constrain membrane material composition and anti-scalant chemistry across European installations. Stakeholders must monitor tightening energy-efficiency standards and carbon accounting rules that will determine which technology configurations remain financeable for large-scale deployment.
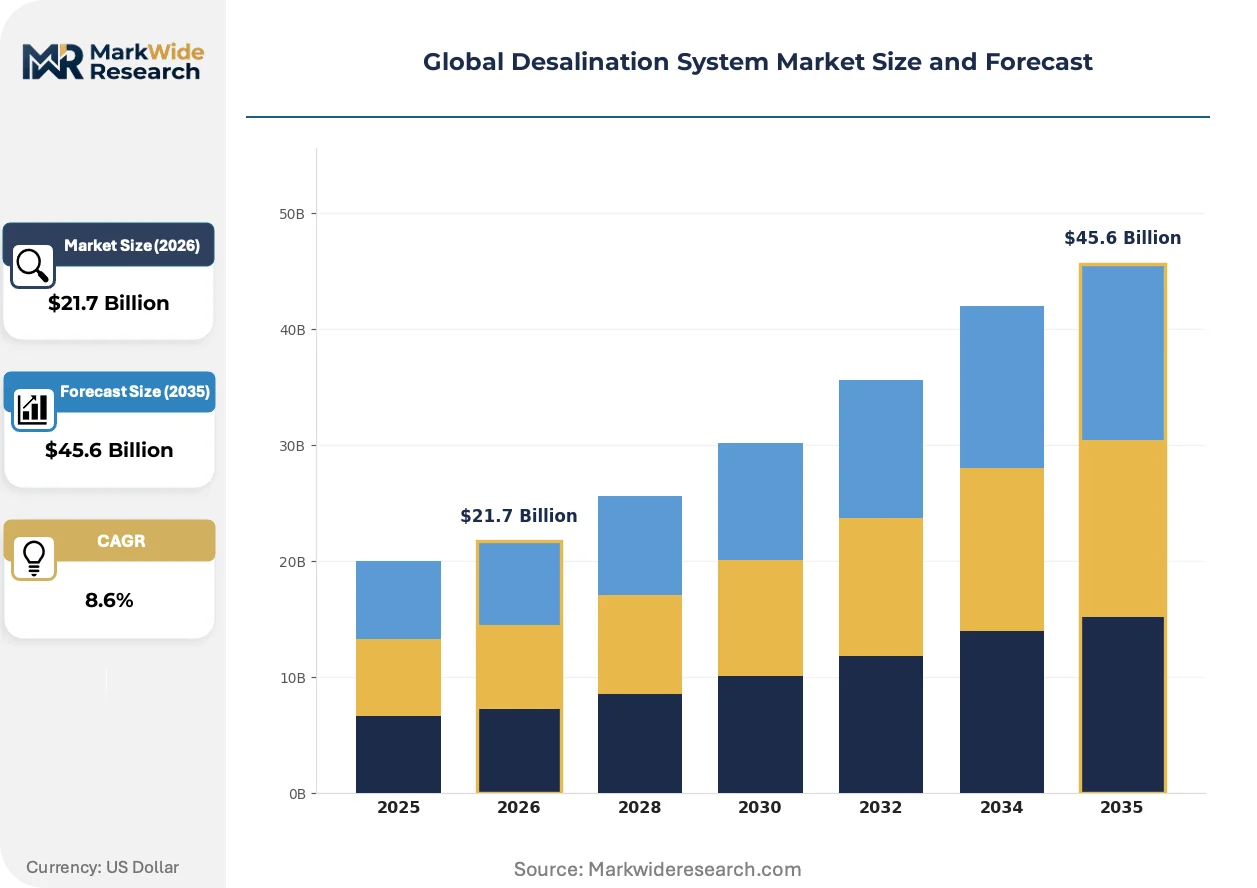
Market Dynamics
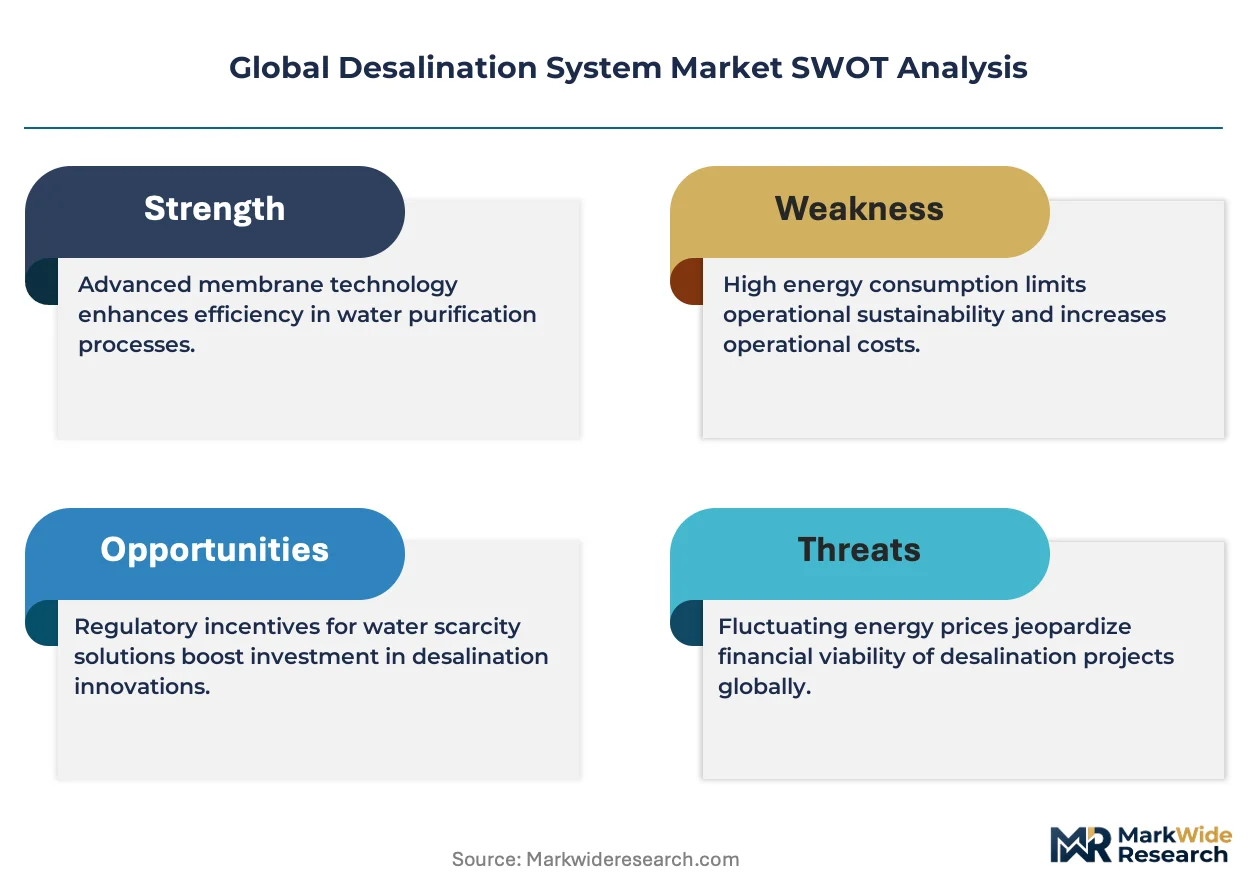
Membrane technology cost curves and energy efficiency mandates are compressing thermal desalination's project pipeline while expanding modular reverse osmosis deployments across coastal utilities.
Growth Catalysts
- EU Green Deal water reuse mandates:Tertiary treatment requirements for municipal discharge are accelerating membrane upgrades in Spanish and Italian coastal plants.
- Brackish groundwater depletion:Australia's Murray-Darling Basin authorities are commissioning emergency desalination capacity as aquifer salinity thresholds breach agricultural limits.
- Photovoltaic cost collapse:Solar-powered reverse osmosis configurations are eliminating diesel dependency for remote island installations in Indonesia and the Philippines.
Market Restraints
- Specialized alloy supply concentration:Super-duplex stainless steel for high-pressure pumps concentrates among Nordic and Japanese metallurgical suppliers, exposing project timelines to single-source risk.
- Brine discharge regulatory friction:EPA Clean Water Act Section 316(b) cooling water intake rules and California Ocean Plan amendments are extending permitting timelines for Pacific Coast facilities.
- Membrane fouling chemistry limitations:Existing anti-scalant formulations face performance ceilings in Red Sea and Arabian Gulf feedwaters with extreme calcium sulfate saturation indices.
Strategic Opportunities
- Industrial process water convergence:Data center cooling and green hydrogen electrolysis are creating dual-purpose demand for ultra-high-purity desalination in Saudi Arabia's NEOM zone.
- Sub-Saharan municipal underpenetration:Mozambique, Tanzania, and Kenya coastal cities lack any installed seawater capacity despite Indian Ocean access and chronic drought cycles.
- ISO 14001 certification differentiation:Verified environmental management credentials are becoming gatekeeping requirements for World Bank and Asian Development Bank project finance.
Industry Challenges
- Membrane integrity assessment skill gaps:Specialized technicians for early-stage biofouling detection and predictive replacement scheduling remain scarce across Middle Eastern operator workforces.
- Legacy thermal asset stranded value:Multi-stage flash plants in the Persian Gulf face accelerated depreciation as power-cogeneration economics deteriorate with renewable grid penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Desalination System Market |
| Market Size in 2026 | $21.7 Billion |
| Market Size in 2035 | $45.6 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Multi-Effect Distillation, Multi-Stage Flash, Electrodialysis End User: Municipalities, Industrial Sector, Agricultural Sector, Residential Units Deployment: Onshore, Offshore, Portable, Fixed Technology: Solar Desalination, Thermal Desalination, Hybrid Systems, Membrane Technologies |
| Companies Covered | Acciona, Veolia, Doosan Enerbility, IDE Technologies, Dow, DuPont, Xylem, Evoqua Water Technologies, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Desalination System Market Emerging Trajectories
Digital twin integration and advanced materials science are compressing operational learning curves while fragmenting traditional equipment procurement patterns across utility and industrial segments.
Graphene oxide nanocomposite membranes are fragmenting conventional polyamide thin-film composite dominance in high-salinity applications. Israeli and Singaporean research institutes are piloting sub-100 nanometer channel architectures that cut specific energy consumption by fifteen to twenty percent. The structural consequence is fragmenting supplier hierarchies as specialty material startups capture pilot-scale contracts previously reserved for established membrane houses.
REACH chemical registration constraints are forcing reformulation of anti-scalant and cleaning chemical portfolios across European installations. ECHA substance evaluation workflows are extending new chemistry approval timelines to thirty-six months, compressing product lifecycle economics. Membrane operators in Spain and Cyprus are responding by consolidating chemical procurement through multi-utility frameworks to amortize compliance costs.
Performance-based service contracting is displacing traditional equipment sale-plus-maintenance arrangements in Australian municipal tenders. Sydney Water and Melbourne Water are bundling twenty-year availability guarantees with capex financing, transferring operational risk to technology providers. This model concentrates vendor selection criteria on demonstrated mean-time-between-failure metrics rather than upfront capital cost.
Global Desalination System Market Segmentation
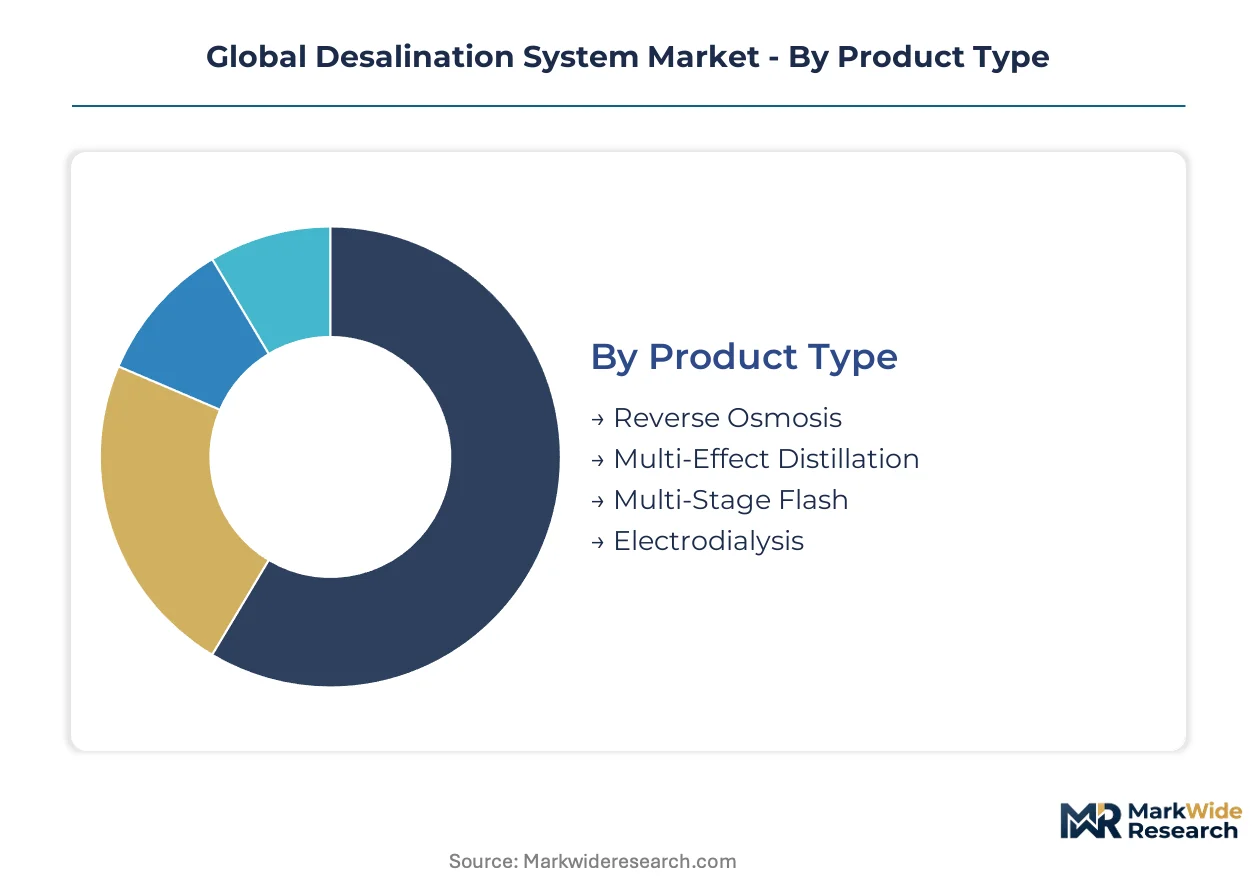
Desalination system procurement patterns diverge sharply across technology maturity curves and geographic water stress gradients. Segment boundaries increasingly blur as hybrid configurations and modular deployment models reshape traditional equipment categories.
Product Type:
Reverse osmosis systems dominate export-led shipments to Middle Eastern and Asia-Pacific utilities, while thermal technologies retain domestic concentration in legacy Persian Gulf installations.
- Reverse Osmosis:Pressure-driven membrane separation through spiral-wound polyamide thin-film composite elements achieves specific energy consumption below 3.5 kWh per cubic meter in optimized Mediterranean plants. Saudi Arabia's Saline Water Conversion Corporation and Israel's national water utility anchor procurement volume for large-diameter eight-inch element configurations.
- Multi-Effect Distillation:Vacuum-driven evaporation across successive stages with vapor compression achieves product water quality exceeding 5 ppm total dissolved solids for specialized industrial boiler feed. Waste heat integration from adjacent power plants preserves economics in Kuwait and Qatar thermal complexes despite membrane cost compression.
- Multi-Stage Flash:Brine recirculation through pressurized flash chambers dominates installed base in older Persian Gulf megaplants.
- Electrodialysis:Ion-selective membrane stacks with alternating electrical polarity suit brackish feedwaters below 10,000 ppm salinity.
Reverse osmosis holds the largest share; momentum sits with hybrid thermal-membrane configurations.
End User:
Customer procurement sophistication spans from standardized municipal tender frameworks to bespoke industrial process water specifications.
- Municipalities:Coastal utilities in Australia, Spain, and California deploy multi-train redundancy with 99.5 percent availability guarantees under twenty-year concession contracts. Sydney Water and Melbourne Water bundle operations risk transfer with capital financing through availability-based payment structures.
- Industrial Sector:Power generation and petrochemical complexes in Saudi Arabia's Jubail Industrial City and NEOM zone demand ultra-high-purity water below 0.1 ppm silica for combined-cycle turbine feed and green hydrogen electrolysis stacks.
- Agricultural Sector:Israel's national carrier and Spain's Almería greenhouse clusters commission brackish water desalination for drip irrigation compatibility.
- Residential Units:Distributed point-of-use systems concentrate in luxury coastal developments across Cyprus and the Balearic Islands.
Municipalities command installed base dominance; industrial process water claims the steepest expansion trajectory.
Deployment:
Physical configuration choices track infrastructure maturity and emergency response requirements across coastal and island geographies.
- Onshore:Permanent concrete civil works with intake structures and marine outfalls characterize Australian and Spanish Mediterranean megaplants.
- Offshore:Barge-mounted or gravity-based platforms serve Indonesian archipelago communities and Philippine remote islands with diesel-to-solar conversion pathways.
- Portable:Containerized skid systems with rapid deployment protocols address Australia's Murray-Darling Basin emergency drought contingencies.
- Fixed:Integrated civil and process engineering dominates Persian Gulf national water company portfolios.
Fixed installations retain capital commitment scale; portable configurations are gaining share fastest in climate adaptation procurement.
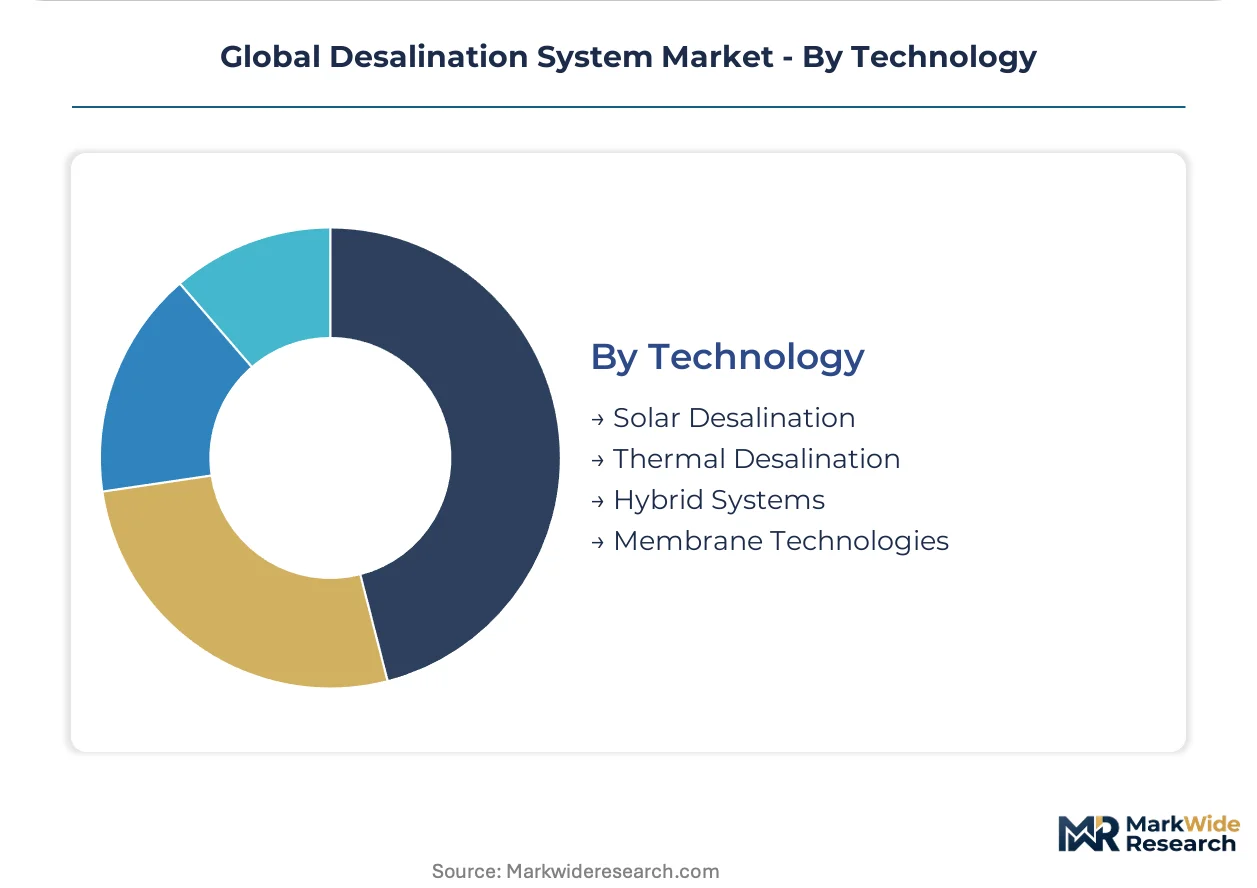
Technology:
Energy source integration and process intensification define competitive differentiation in technology selection.
- Solar Desalination:Photovoltaic-driven reverse osmosis with battery storage eliminates diesel logistics for Indonesian and Philippine island municipalities.
- Thermal Desalination:Steam-driven distillation retains niche positioning where industrial waste heat provides zero-cost energy input.
- Hybrid Systems:Membrane pre-treatment coupled with thermal polishing achieves lowest lifecycle cost in high-salinity Arabian Gulf feedwaters.
- Membrane Technologies:Graphene oxide nanocomposite pilots in Singapore and Israel target fifteen to twenty percent energy reduction through sub-100 nanometer channel architectures.
Membrane technologies anchor new capacity additions; solar-powered configurations climb the fastest in remote deployment segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal water reuse mandates and national water security programs are restructuring procurement priorities across coastal utilities worldwide. Saudi Arabia's Saline Water Conversion Corporation efficiency benchmarks and Australia's Murray-Darling Basin emergency protocols exemplify how regulation shapes technology deployment.
Saudi Arabia
Saline Water Conversion Corporation efficiency benchmarks are accelerating membrane upgrades at Jubail Industrial City complexes. The national water company enforces specific energy consumption thresholds that disqualify older thermal configurations from new tenders. NEOM zone development anchors demand for ultra-high-purity process water serving data center cooling and green hydrogen electrolysis stacks.
Australia
Murray-Darling Basin aquifer salinity breaches are forcing emergency desalination commissions across agricultural zones. Sydney Water and Melbourne Water bundle twenty-year availability guarantees with capital financing, transferring operational risk to technology providers. Containerized portable systems address drought contingency requirements in Victoria and South Australia.
Spain
EU Water Framework Directive discharge standards are tightening tertiary treatment requirements at Mediterranean coastal plants. ECHA REACH chemical registration workflows extend anti-scalant approval timelines, compressing product lifecycle economics. Almería greenhouse clusters commission brackish water capacity for drip irrigation compatibility.
Israel
National water utility procurement anchors volume for large-diameter reverse osmosis element configurations. The country's national water regulator mandates specific recovery rates and energy intensity ceilings for new municipal capacity. Research institutes pilot graphene oxide nanocomposite membranes targeting fifteen to twenty percent energy reduction.
United States
EPA Clean Water Act Section 316(b) cooling water intake rules extend permitting timelines for Pacific Coast facilities. California Ocean Plan amendments tighten brine discharge limits for proposed installations. Metropolitan Water District of Southern California evaluates modular configurations for Los Angeles basin supply diversification.
Global Desalination System Market Vendor Landscape
Listed leaders compete with private specialists across integrated operations platforms and membrane chemistry portfolios. The supplier base organizes into three tiers: diversified environmental conglomerates with multi-utility concessions, heavy engineering houses anchored to thermal megaprojects, and specialty material developers targeting high-salinity feedwater conditions. Consolidation pressure concentrates through performance-based service contracting and twenty-year availability guarantee bundling. Geographic expansion and technology licensing dominate competitive moves as vendors seek to amortize compliance costs across multi-utility frameworks.
Within the diversified environmental services tier, Veolia leverages integrated operations platforms across multiple coastal utilities. Doosan Enerbility anchors heavy thermal desalination engineering capabilities for Persian Gulf megaprojects. Toray Industries occupies a position among specialty material developers focused on advanced membrane chemistry for extreme feedwater conditions.
| Leading Market Players |
|---|
| Acciona |
| Veolia |
| Doosan Enerbility |
| IDE Technologies |
| Dow |
| DuPont |
| Xylem |
| Evoqua Water Technologies |
| Toray Industries |
| Others |
Supply Flow & Price Mechanics
ISO 14001 environmental management certification gates supplier qualification for large-scale desalination tenders while simultaneously stratifying price tiers across the value chain. Buyers with verified sustainability credentials command premium positioning in Middle Eastern project finance, whereas uncertified vendors face exclusion regardless of unit cost competitiveness.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers in desalination system procurement. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 14001 verification status, membrane element diameter specifications, and bundled availability guarantee durations. Cost compression in standard-tier reverse osmosis configurations is intensifying because Chinese membrane manufacturers are expanding eight-inch element production capacity. Municipal utilities in Australia and Spain exhibit the highest price sensitivity due to availability-based payment structures that transfer operational risk, while industrial buyers in Saudi Arabia's NEOM zone prioritize ultra-high-purity specifications over capital cost minimization.
Supply Chain Analysis
Extended lead times for super-duplex stainless steel high-pressure pumps now stretch eighteen to twenty-four months, compressing project delivery schedules across Persian Gulf installations. Manufacturing concentration for critical metallurgical components rests on Japan, Sweden, and Finland, while spiral-wound membrane elements draw from production facilities in Japan, the United States, and South Korea. Single-source vulnerability in specialized alloy supply exposes EPC contractors to timeline slippage when Nordic metallurgical suppliers face order backlogs. Distribution runs through multi-utility procurement frameworks in Australia and consolidated chemical supply consortia in Spain and Cyprus.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Atmospheric water generation and wastewater reuse infrastructure pose credible substitution threats to seawater desalination expansion in coastal zones with moderate water stress, forcing incumbents to defend position through performance differentiation rather than capacity scaling alone.
For Market Incumbents: Shield installed base relationships by embedding predictive maintenance platforms that reduce mean-time-between-failure metrics below competitor benchmarks. Deepen backward integration into membrane element manufacturing to capture margin compression from Chinese supply expansion. Counter atmospheric water generation substitutes by bundling twenty-year availability guarantees with carbon accounting transparency that emerging technologies cannot yet match.
For New Entrants and Emerging Players: Anchor in Sub-Saharan coastal municipalities where Mozambique, Tanzania, and Kenya lack any installed seawater capacity despite chronic drought exposure. Target Indonesian and Philippine island utilities with solar-powered reverse osmosis skids that eliminate diesel logistics dependencies. Pursue performance-based service contracting models pioneered by Australian utilities to bypass capital-intensive EPC competition.
For Investors and Strategic Acquirers: EU Green Deal water reuse mandates reshape the acquisition landscape by consolidating chemical procurement through multi-utility frameworks that favor scaled operators. Five-to-ten year viability hinges on exposure to membrane chemistry innovation rather than legacy thermal asset positions. Monitor ECHA substance evaluation timelines as inflection indicators for anti-scalant formulation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Chemistry R&D Partnership | Graphene oxide nanocomposite development in Israeli and Singaporean institutes targets fifteen to twenty percent energy reduction. |
| Performance-Based Service Contracting | Sydney Water and Melbourne Water bundle twenty-year availability guarantees with capex financing, transferring operational risk. |
| ISO 14001 Certification Investment | Verified credentials gate World Bank and Asian Development Bank project finance for Middle Eastern tenders. |
| Solar-Powered Configuration Deployment | Photovoltaic-driven reverse osmosis eliminates diesel dependency for Indonesian archipelago and Philippine remote island installations. |
| Multi-Utility Chemical Procurement Consolidation | Spanish and Cypriot operators amortize REACH compliance costs through framework agreements that reshape supplier economics. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and project development databases. Interviews with desalination plant operators, EPC contractors, membrane procurement managers, and saline water conversion corporation planning officers informed demand-side validation. Secondary sources included EPA Clean Water Act enforcement records, EU Water Framework Directive implementation reports, Saline Water Conversion Corporation efficiency benchmark disclosures, and Australian Bureau of Agricultural and Resource Economics water market data. Bottom-up capacity installation tracking triangulated against top-down macroeconomic water stress indices.
Segmentation dimensions modeled span technology type, end-user sector, deployment configuration, and energy integration approach across the analysis window. Reverse osmosis, thermal distillation, and hybrid system categories were cross-tabulated against municipal, industrial, agricultural, and residential demand segments. CAGRs derived from regression analysis of historical capacity additions against explanatory variables including aquifer depletion rates, photovoltaic cost trajectories, and regulatory stringency indices. Forecast inputs incorporated Saline Water Conversion Corporation efficiency benchmark trajectories and Murray-Darling Basin emergency protocol activation thresholds.
Material uncertainties — brine discharge regulatory amendments, membrane fouling chemistry breakthroughs, super-duplex alloy supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding technology cost curves and policy implementation timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
Water Ionizers Market
Water Treatment Systems
Home Water Filtration Unit Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Mobile Water Treatment Services Market
Water Treatment Systems
Water Purifier/Filter Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market
Water Treatment Systems
Water Desalination Equipment Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Water Treatment As a Service Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Residential Water Treatment Equipment Market