
 Packaged Water Treatment System Market | 2026-2036
Packaged Water Treatment System Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Water Treatment System Market Analysis
Modular bundling of membrane filtration with chemical disinfection into single-skid units is hardening as the default procurement specification for industrial buyers. Veolia Water Technologies leverages its global service network to anchor long-term operations contracts. Suez Water Technologies & Solutions differentiates through proprietary membrane chemistry that extends replacement cycles. GE Water & Process Technologies competes on digital monitoring integration bundled with hardware.
A packaged water treatment system integrates pre-engineered, factory-built components—typically including coagulation, filtration, and disinfection stages—into transportable skids or containers designed for rapid site deployment with minimal civil works. These systems process flows ranging from residential-scale units to industrial installations exceeding ten thousand cubic meters per day, delivering treated water compliant with discharge or reuse standards. Reverse osmosis dominates value capture in offshore and high-salinity applications where membrane replacement creates recurring revenue pools. Biological treatment is gaining share in municipal wastewater reuse schemes where nutrient removal requirements intensify. Ultrafiltration occupies the middle ground between cost and performance for commercial and light industrial end users seeking lower operator intervention.
The US EPA enforces Safe Drinking Water Act maximum contaminant levels that push municipal buyers toward certified packaged systems with validated performance data. India's Central Pollution Control Board mandates sewage treatment plant compliance for clusters above specified population thresholds, directly stimulating packaged unit procurement. China's Ministry of Ecology and Environment applies escalating discharge tariffs that make onsite packaged treatment economically preferable to centralized sewer access for many factories. Stakeholders must weigh membrane supply chain concentration against the operational flexibility that modular architectures provide when regulations shift.
Market Dynamics
Modular ultrafiltration architectures are compressing project timelines from eighteen months to under ninety days, forcing engineering-procurement-construction contractors to abandon stick-built designs in favor of factory-integrated skids.
Growth Catalysts
- India's CEA Effluent Mandates:Thermal power operators must install zero-liquid-discharge systems, triggering bulk orders for containerized reverse osmosis trains.
- Membrane Chemistry Advances:Polyethersulfone hollow-fiber modules now deliver five-year replacement cycles, cutting lifecycle costs for municipal buyers in China's Yangtze corridor.
- Offshore Platform Operators:North Sea oil producers specify compact electrochlorination packages to replace bulk chemical logistics, driving specification changes across marine engineering standards.
Market Restraints
- Polymer Feedstock Volatility:PVDF membrane production depends on fluoroethylene supply concentrated in Chinese chemical parks, exposing European fabricators to tariff and logistics disruptions.
- Technical Performance Ceilings:Packaged biological nutrient removal systems struggle to meet sub-3 mg/L total nitrogen limits in cold-climate applications without supplemental heating infrastructure.
- REACH Registration Burden:Novel disinfection byproduct control chemistries face multi-year authorization timelines in the European Union, delaying product launches.
Strategic Opportunities
- Indonesia's Industrial Zones:Batam and Karawang manufacturing clusters lack centralized sewer infrastructure, creating first-mover advantage for mobile treatment-as-a-service providers.
- Digital Twin Integration:Real-time membrane fouling prediction layered atop packaged hardware is converging with predictive maintenance contracts, capturing recurring revenue streams.
- Saudi Arabia's NEOM Project:The kingdom's renewable-powered desalination mandates specify modular construction to accelerate commissioning timelines for gigascale developments.
Industry Challenges
- Commissioning Engineer Shortage:Skilled technicians capable of calibrating multi-stage membrane trains remain scarce in Sub-Saharan African markets, extending startup periods.
- Legacy SCADA Integration:Brownfield industrial sites operate proprietary control protocols that resist seamless handshaking with modern packaged system PLCs, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Water Treatment System Market |
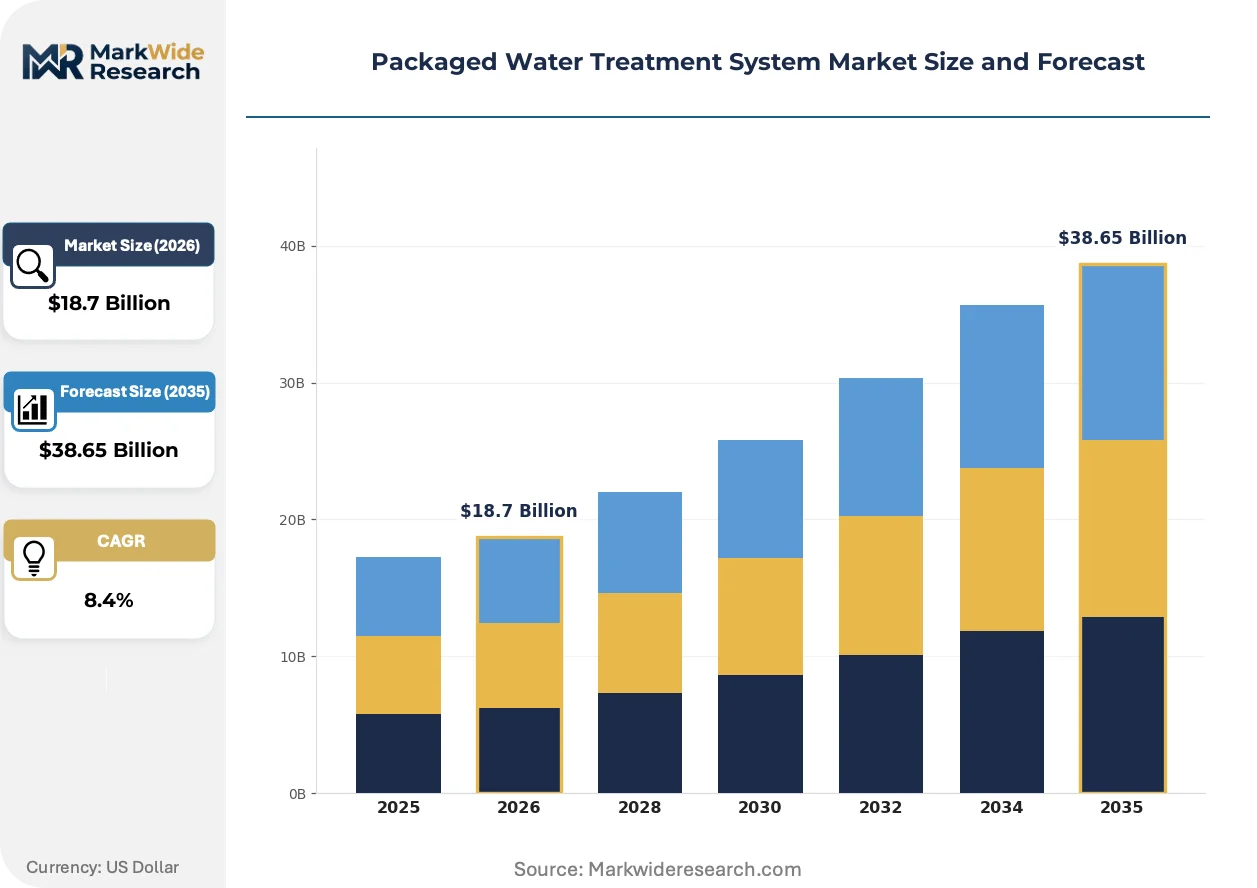
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrafiltration, Reverse Osmosis, Activated Carbon, Ion Exchange Application: Municipal Water Supply, Industrial Process Water, Wastewater Treatment, Drinking Water End User: Residential, Commercial, Industrial, Agricultural Technology: Membrane Filtration, Chemical Disinfection, Solar Desalination, Biological Treatment |
| Companies Covered | Veolia Water Technologies, GE Water & Process Technologies, Westech Engineering Inc., Smith & Loveless Inc., Napier-Reid Ltd., Corix Water Systems, RWL Water, Enviroquip, Suez Water Technologies & Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Water Treatment System Market Emerging Trajectories
Intelligent monitoring layers and prefabrication methods are compressing the traditional boundaries between equipment supply and operational service, redefining how buyers evaluate total cost of ownership.
Electrochemical advanced oxidation is converging with ceramic membrane filtration in single-skid configurations for pharmaceutical wastewater applications. Active pharmaceutical ingredient manufacturers in Ireland and Singapore specify these hybrid units to destroy recalcitrant compounds while meeting discharge consent limits. The convergence is compressing footprint requirements by forty percent versus sequential unit operations, enabling installation in congested industrial parks.
China's MEE is tightening discharge tariffs for chemical oxygen demand and ammonia nitrogen in the Yangtze and Pearl River deltas, forcing small and mid-sized factories to abandon municipal sewer connections. Industrial park operators in Jiangsu and Guangdong provinces now mandate packaged onsite treatment as a lease condition. Fabricators are responding with standardized 500-cubic-meter-per-day containerized biological systems certified to GB 8978-1996 Class I standards.
Buyers in Australia's mining sector are unbundling hardware procurement from long-term operations contracts, awarding separate tenders to equipment vendors and third-party O&M specialists. This fragmentation is compressing equipment margins while expanding the addressable market for remote monitoring and chemical logistics providers. The shift is most visible in Western Australia's Pilbara iron ore operations, where water scarcity intensifies performance guarantees.
Packaged Water Treatment System Market Segmentation
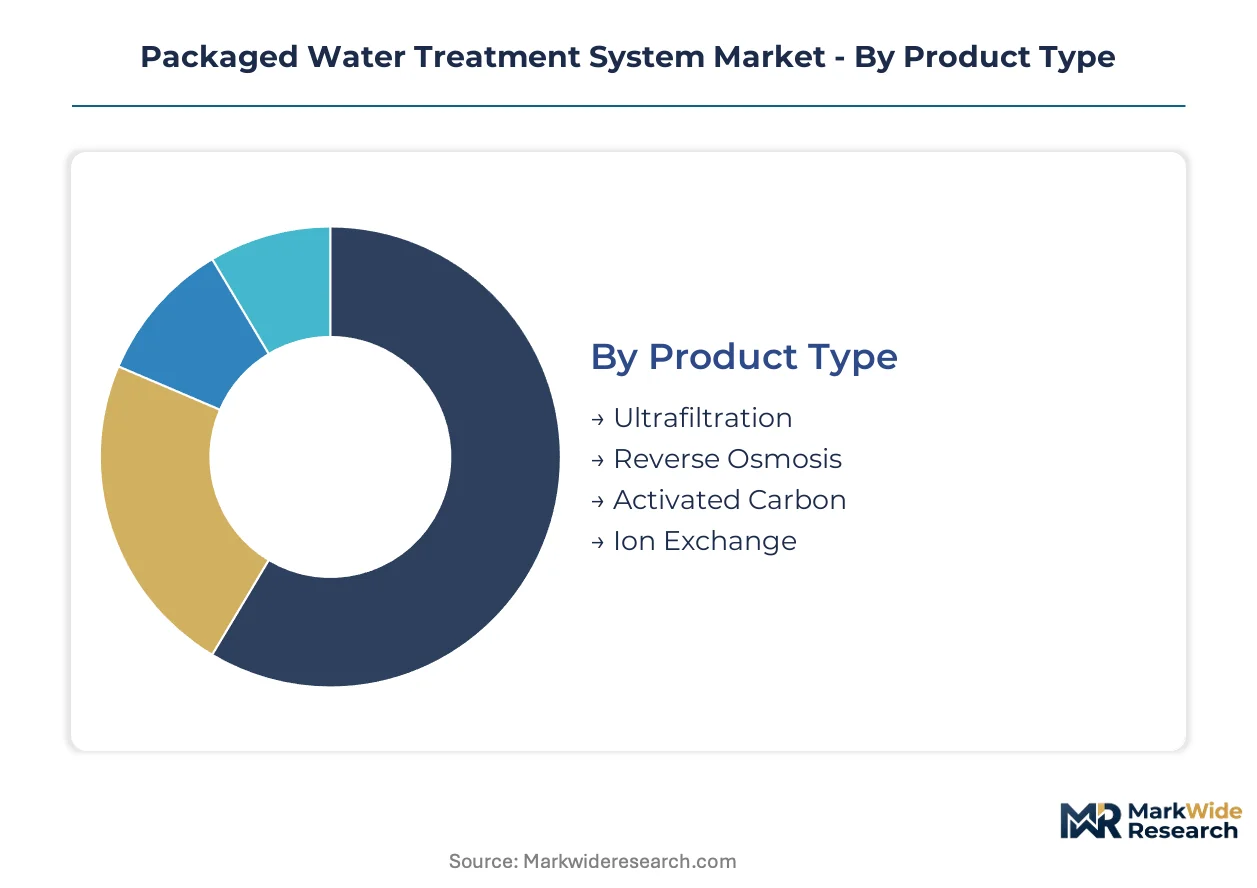
Packaged water treatment systems fragment across four distinct dimensions, each reflecting divergent buyer priorities around capital intensity, regulatory compliance, and operational complexity. Procurement patterns vary sharply between standardized containerized units for rapid deployment and engineered-to-order configurations for specialized effluent profiles.
Product Type:
Customization intensity spans from commodity cartridge systems to precision-engineered membrane trains requiring site-specific integration.
- Ultrafiltration:Hollow-fiber polyethersulfone modules operating at 0.01-micron retention separate colloids and pathogens without phase change. Municipal operators in India's tier-2 cities favor skid-mounted ultrafiltration for compact footprint and minimal chemical dependency under Central Pollution Control Board mandates. Leading the category by volume: Ultrafiltration. Growing fastest: Reverse Osmosis.
- Reverse Osmosis:Spiral-wound thin-film composite membranes achieve dissolved solids rejection exceeding 99 percent through hydraulic pressure-driven separation. Thermal power plants under India's Central Electricity Authority zero-liquid-discharge directives drive bulk procurement of containerized reverse osmosis trains for boiler feed and cooling tower blowdown recovery.
- Activated Carbon:Granular or extruded carbon adsorbs organics and chlorine residuals in point-of-entry commercial installations.
- Ion Exchange:Resin-based demineralization targets specific ionic contaminants in semiconductor and pharmaceutical process water loops.
Membrane-based systems command premium positioning through recurring consumables revenue; carbon and resin systems compete on lower upfront capital.
Application:
Regulatory stringency creates tiered demand clusters, with discharge permits dictating technology selection more than raw water quality.
- Municipal Water Supply:District-scale packaged plants integrate coagulation, filtration, and disinfection into transportable skids serving 10,000 to 100,000 population equivalents. China's Ministry of Ecology and Environment tightening of Class I discharge standards in Yangtze corridor cities accelerates retrofit procurement for aging centralized infrastructure. Municipal Water Supply dominates volume. Industrial Process Water expands most quickly.
- Industrial Process Water:Boiler feed, cooling makeup, and ingredient water specifications drive multi-stage membrane configurations with redundant trains. Jiangsu province industrial park operators now mandate onsite packaged treatment as lease compliance under escalating discharge tariffs.
- Wastewater Treatment:Containerized biological nutrient removal addresses ammonia and phosphorus limits where sewer connection is unavailable or cost-prohibitive.
- Drinking Water:Point-of-use and point-of-entry units serve residential and commercial buildings with certified pathogen barriers.
Industrial Process Water captures the steepest expansion trajectory as factory operators abandon municipal sewer networks for tariff-insulated self-treatment.
End User:
Scale economies separate mass-market residential units from engineered industrial systems requiring performance guarantees and long-term service contracts.
- Residential:Under-sink reverse osmosis and countertop ultrafiltration units address aesthetic and health concerns in groundwater-dependent regions. India's Bureau of Indian Standards certification requirements for domestic water purifiers consolidate demand toward validated membrane performance claims.
- Commercial:Hotels, hospitals, and office complexes specify mid-capacity skids balancing capital constraints against regulatory visibility.
- Industrial:Manufacturing facilities and power generators procure turn-key treatment trains with operations contracts spanning 10-15 years. Industrial segment leads absolute volume. Agricultural adoption climbs fastest.
- Agricultural:Drip irrigation and greenhouse operations deploy packaged filtration for dissolved solids management and pathogen exclusion in recirculating systems.
Industrial buyers concentrate procurement authority at headquarters level, while residential and agricultural segments fragment across distributor networks.
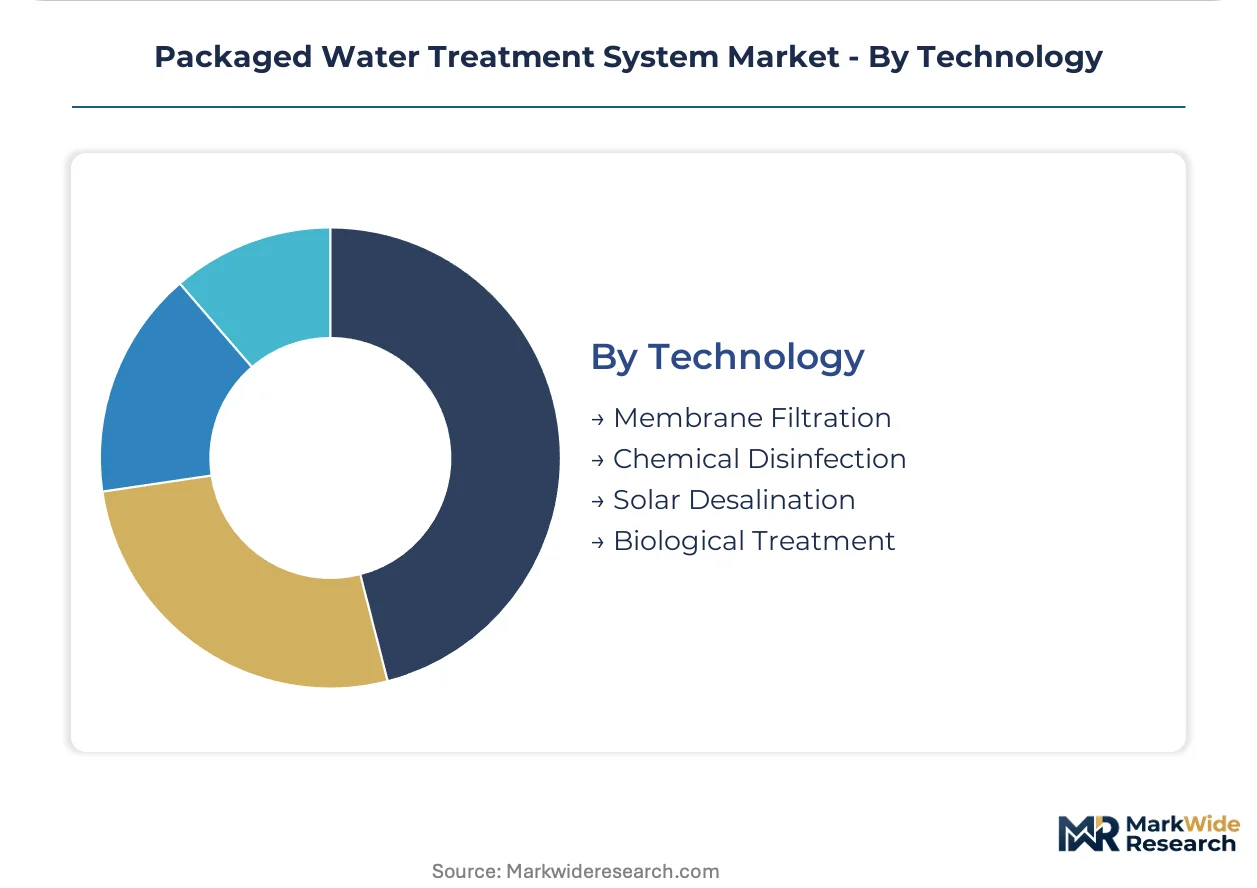
Technology:
Physical barrier methods dominate installed base, though chemical and biological approaches gain share in reuse-intensive applications.
- Membrane Filtration:Microfiltration, ultrafiltration, nanofiltration, and reverse osmosis variants provide size-exclusion barriers scalable from residential to industrial throughput. Offshore platform operators in the North Sea specify compact membrane packages to eliminate bulk chemical logistics and reduce helicopter supply dependency. Membrane Filtration leads by installed capacity. Biological Treatment gains share fastest.
- Chemical Disinfection:Electrochlorination, ozone generation, and UV irradiation provide residual protection against distribution system recontamination.
- Solar Desalination:Photovoltaic-driven reverse osmosis and membrane distillation address remote coastal communities and island installations without grid connectivity.
- Biological Treatment:Moving bed biofilm reactors and membrane bioreactors achieve nutrient removal in wastewater reuse schemes where total nitrogen limits tighten below 10 mg/L.
Technology selection increasingly bundles hardware with predictive monitoring layers, compressing the traditional boundary between equipment supply and operational service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's special economic zones for manufacturing exports concentrate packaged water treatment procurement authority near industrial park management offices. Chinese coastal development corridors channel foreign direct investment into modular treatment infrastructure. Gulf Cooperation Council free zones accelerate desalination plant deployment through streamlined permitting.
United States
Shale oil operators in the Permian Basin specify containerized electrochlorination packages to replace bulk chemical logistics. The EPA enforces Safe Drinking Water Act maximum contaminant levels that push municipal buyers toward certified packaged systems with validated performance data. Texas water utilities in the Dallas-Fort Worth metroplex retrofit aging centralized infrastructure with skid-mounted ultrafiltration.
China
Jiangsu province industrial park operators mandate onsite packaged treatment as lease compliance under escalating discharge tariffs. The Ministry of Ecology and Environment applies tightening discharge standards for chemical oxygen demand in Yangtze corridor cities. Factory clusters in Suzhou and Wuxi abandon municipal sewer connections for tariff-insulated self-treatment.
India
Thermal power operators under Central Electricity Authority zero-liquid-discharge directives drive bulk procurement of containerized reverse osmosis trains. The Central Pollution Control Board mandates sewage treatment plant compliance for clusters above specified population thresholds. Municipal operators in tier-2 cities favor skid-mounted ultrafiltration for compact footprint under Bureau of Indian Standards certification requirements.
Germany
Pharmaceutical manufacturers in the Rhine-Main region specify hybrid electrochemical oxidation with ceramic membrane filtration to destroy recalcitrant compounds. REACH registration requirements delay novel disinfection byproduct control chemistries, forcing multi-year authorization timelines. Industrial fabricators in Baden-Württemberg face polymer feedstock volatility from concentrated fluoroethylene supply in Chinese chemical parks.
Saudi Arabia
The NEOM gigaproject specifies modular construction to accelerate commissioning timelines for renewable-powered desalination developments. The kingdom's renewable energy mandates create first-mover advantage for mobile treatment-as-a-service providers. Red Sea coastal developments prioritize factory-integrated skids over stick-built designs to compress project timelines.
Packaged Water Treatment System Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology and service bundling vectors. The market structure separates membrane chemistry innovators from systems integrators and from operations contract providers. Strategic archetypes include global service network anchors, proprietary technology licensors, and digital monitoring bundlers. Dominant competitive moves center on long-term operations contract capture and predictive maintenance service layering atop hardware sales.
Among French-based diversified environmental service groups, Veolia Water Technologies and Suez Water Technologies & Solutions occupy positions as global service network anchors. GE Water & Process Technologies represents the digital integration archetype within industrial conglomerate structures. These three exemplify how competitive positioning separates hardware-centric procurement from bundled operational service contracts spanning 10-15 year horizons.
| Leading Market Players |
|---|
| Veolia Water Technologies |
| GE Water & Process Technologies |
| Westech Engineering Inc. |
| Smith & Loveless Inc. |
| Napier-Reid Ltd. |
| Corix Water Systems |
| RWL Water |
| Enviroquip |
| Suez Water Technologies & Solutions |
| Others |
Supply Flow & Price Mechanics
Fluoroethylene feedstock costs cascade from Chinese chemical parks through PVDF membrane fabrication, splitting final system pricing into premium-mid-economy tiers based on membrane chemistry grade and replacement cycle guarantees. Buyers in India's municipal sector face compressed procurement budgets under CPCB mandates, while industrial operators in China's Yangtze corridor absorb tariff-insulated premiums for zero-liquid-discharge configurations.
Pricing Analysis
Cost-down pressure on containerized ultrafiltration skids accelerates because municipal buyers in India's tier-2 cities prioritize capital expenditure minimization over lifecycle optimization under Bureau of Indian Standards certification requirements. Pricing stratifies across premium, standard, and economy tiers differentiated by membrane replacement cycle guarantees and digital monitoring bundling. European fabricators face margin tightening from polymer feedstock volatility concentrated in Chinese supply zones. Industrial end users in China's Jiangsu province demonstrate lowest price sensitivity due to lease-mandated compliance requirements, while residential point-of-use buyers in groundwater-dependent regions exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Germany, China, and India anchor hub-and-spoke patterns for membrane module logistics, with factory-integrated skids shipping direct to industrial park sites. PVDF membrane production draws from fluoroethylene supply concentrated in Chinese chemical parks, while polyethersulfone hollow-fiber manufacturing rests on European and Japanese resin sources. Single-source vulnerability in Chinese fluoroethylene exposes European fabricators to tariff and logistics disruptions. Distribution runs through authorized service networks for long-term operations contracts, bypassing traditional equipment distributor channels for industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commissioning engineer scarcity across Sub-Saharan African and Southeast Asian markets props pricing for factory-integrated skids with remote monitoring capabilities, constraining supply expansion for pure hardware vendors.
For Market Incumbents: To counter margin compression from unbundled hardware procurement in Australia's mining sector, anchor long-term operations contracts through predictive maintenance service layering and deepen captive supply of proprietary membrane chemistries to secure replacement revenue streams. For New Entrants and Emerging Players: The price-point gap between premium ceramic membrane systems and economy-grade ultrafiltration skids creates entry space for hybrid electrochemical oxidation configurations targeting pharmaceutical wastewater applications in Ireland and Singapore. Prioritize mobile treatment-as-a-service models in Indonesia's Batam and Karawang industrial zones lacking centralized sewer infrastructure, with lease-based revenue capture replacing capital equipment sales. For Investors and Strategic Acquirers: Bulk procurement orders from India's Central Electricity Authority zero-liquid-discharge directives is the leading indicator that thermal power retrofit cycles will concentrate vendor consolidation opportunities. Position for five-to-ten year viability through acquisition of membrane chemistry specialists with validated replacement cycle claims, monitoring CEA tender award velocity as inflection signal for capacity deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Chemistry | Captive polyethersulfone resin production insulates Veolia and Suez from Chinese fluoroethylene tariff exposure. |
| Digital Twin Platform Integration | Real-time fouling prediction layered atop GE Water hardware captures recurring predictive maintenance revenue streams. |
| Mobile Treatment-as-a-Service Launch | Lease-based models in Indonesia's industrial zones bypass capital constraint barriers for mid-sized factories. |
| Ceramic Membrane Hybrid Development | Electrochemical oxidation convergence addresses pharmaceutical discharge limits in Ireland's API manufacturing cluster. |
| Regional Distribution Center Expansion | Hub-and-spoke logistics in Saudi Arabia's NEOM zone compress commissioning timelines for gigascale desalination. |
Methodological Framework
Document review covered regulatory filings from EPA, India's CEA and CPCB, China's MEE, and ECHA REACH databases, complemented by interviews with membrane module procurement managers at thermal power operators, industrial park facility directors in Jiangsu and Guangdong provinces, municipal water utility engineers in India's tier-2 cities, and aftermarket service heads at global equipment vendors. Secondary validation drew from customs trade data for membrane imports, Bureau of Indian Standards certification records, and SEC filings from diversified environmental service groups. Bottom-up unit deployment estimates triangulated against top-down market sizing from project announcement tracking.
Historical deployment patterns across municipal, industrial, and residential end-use segments were cross-referenced against panel input from procurement officers and EPC contractors to establish baseline trajectories. The analytical framework modeled technology type, application segment, end-user scale tier, and regional regulatory cluster across the projection horizon. CAGRs were derived from regression analysis of announced project timelines against regulatory mandate effective dates, with membrane replacement cycle economics and digital service attachment rates as industry-specific forecast inputs.
Inputs from CEA tender announcements, MEE discharge tariff schedules, and industrial park lease mandate records were available through the study window; gaps in real-time commissioning data from Sub-Saharan African markets introduce uncertainty bands around startup period assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Commercial Water Filter Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
Home Water Softener System Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Point of Use Water Treatment Systems Market
Water Treatment Systems
Zero Liquid Discharge Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Water Purifier/Filter Market
Water Treatment Systems
Plant Based Water Filter Market
Water Treatment Systems
Home Water Filtration Unit Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
Mobile Water Treatment Services Market
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market