
 Ozone Generation Market | 2026-2036
Ozone Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Ozone Generation Market Intelligence
The integration of high-frequency, modular power supply units into generator designs is reshaping product efficiency and operational flexibility. This technological shift allows for more precise ozone output control and simplified maintenance routines. SUEZ Water Technologies & Solutions leverages its extensive portfolio to serve large-scale municipal water projects globally. Xylem competes on system integration and intelligent water management platforms, while Mitsubishi Electric Corporation specializes in high-capacity systems for industrial applications, particularly in Japan and China.
Ozone generation is the process of producing ozone gas (O3) by subjecting oxygen (O2) to a high-energy field. The most common method, corona discharge, uses a high-voltage current to split oxygen molecules, which then reform as ozone for use as a powerful oxidant. Water treatment applications represent the largest end-user segment, driven by wastewater compliance. Corona discharge technology dominates due to its scalability, while electrolytic methods serve niche, high-purity requirements in medical and semiconductor fields.
Regulatory frameworks like the US EPA's Disinfection Byproducts Rule and the European Union's Biocidal Products Regulation (BPR) govern the use of ozone in water treatment and as a disinfectant. In China, mandates from the Ministry of Ecology and Environment (MEE) on industrial effluent standards are accelerating adoption in manufacturing sectors. Stakeholder decisions will hinge on balancing the capital cost of advanced generator technologies against the long-term operational savings and compliance benefits they offer.
Market Dynamics
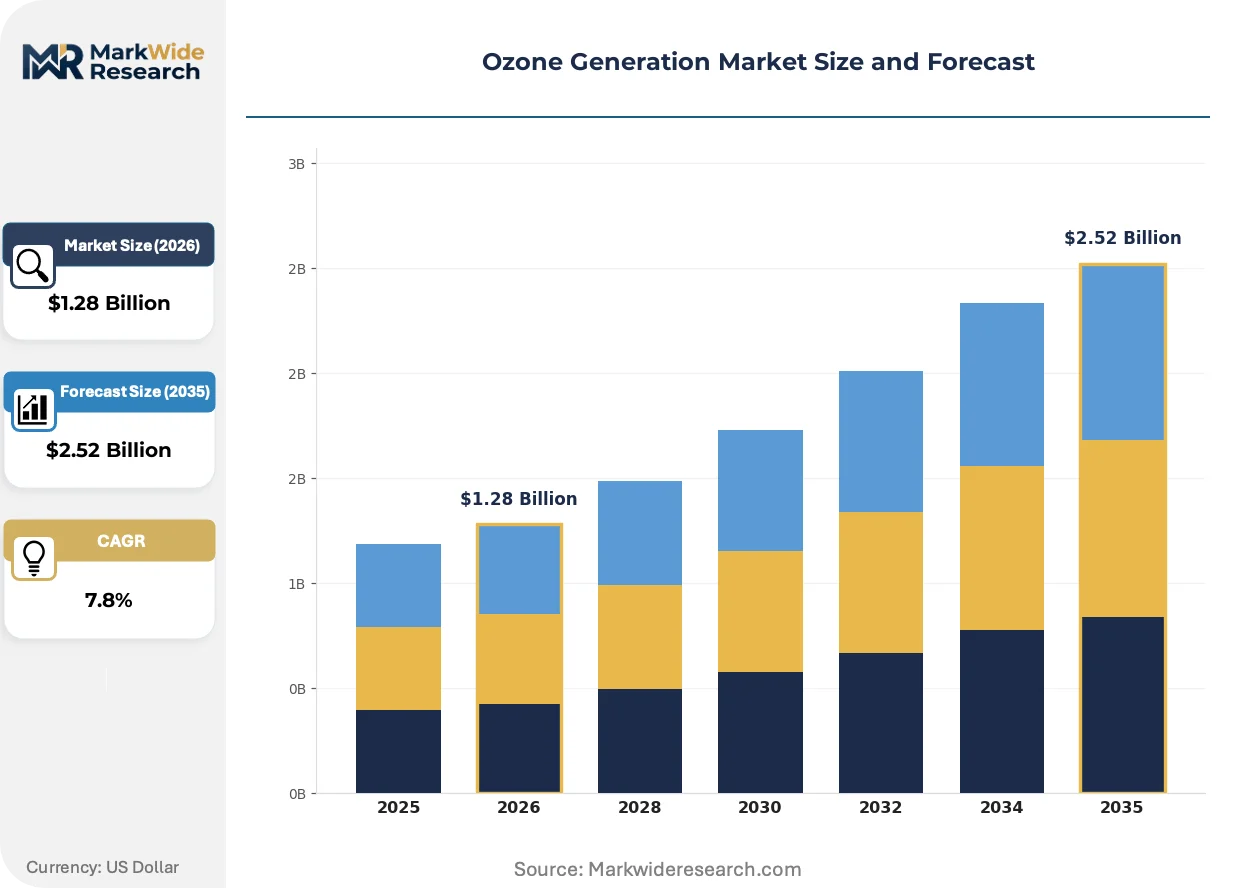
Stricter global regulations on disinfection byproducts and industrial effluents are the primary structural force shaping the market. This pressure compels utilities and manufacturers to adopt advanced oxidation processes, making ozone generation a compliance-driven necessity rather than an operational choice.
Growth Catalysts
- Stringent Water Standards:The US EPA's Disinfection Byproducts Rule and China's MEE industrial effluent mandates require advanced treatment, spurring demand for ozone systems to manage complex contaminants.
- Aquaculture Expansion:The intensification of fish farming operations requires superior water quality and disease control, creating a significant demand vector for ozone as a disinfectant over traditional chemicals.
- Modular Power Supplies:The adoption of high-frequency, modular power supply units enhances generator efficiency and simplifies maintenance, lowering the total cost of ownership and encouraging system upgrades.
Market Restraints
- High Initial Capital Outlay:The significant upfront investment for high-capacity corona discharge systems, particularly for large municipal projects, can deter adoption despite long-term operational benefits and savings.
- Corrosive Nature of Ozone:Ozone's high reactivity requires the use of expensive, corrosion-resistant materials like stainless steel or Teflon in system construction, which increases overall manufacturing costs.
- Oxygen Feed Gas Purity:The efficiency of corona discharge generators depends on high-purity oxygen feed gas, creating operational costs and complexities related to on-site oxygen generation or procurement.
Strategic Opportunities
- Food & Beverage Processing:Expanding applications in food processing for surface sanitation and extending the shelf life of produce represents a significant, underpenetrated commercial sector for ozone technology.
- Southeast Asian Water Infrastructure:Rapid urbanization and industrialization in countries like Vietnam and Indonesia are creating new greenfield opportunities for municipal and industrial water treatment systems.
- Pharmaceutical GMP Compliance:Stricter Good Manufacturing Practice (GMP) standards for ultrapure water systems in pharmaceutical manufacturing can be met using ozone for sanitization, opening a high-value niche.
Industry Challenges
- Legacy System Integration:Integrating modern, digitally controlled ozone generators with older, analog-based municipal water treatment control systems presents significant technical and software compatibility hurdles for utilities.
- Specialized Technician Scarcity:A shortage of technicians skilled in the maintenance and repair of high-voltage corona discharge systems and their associated power electronics limits aftermarket service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ozone Generation Market |
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.52 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Corona Discharge, UV Radiation, Electrolytic, Cold Plasma End User: Water Treatment, Air Purification, Food Processing, Medical Facilities Application: Wastewater Treatment, Surface Disinfection, Odor Removal, Industrial Applications Output Capacity: Low Capacity, Medium Capacity, High Capacity, Very High Capacity |
| Companies Covered | Xylem, Mitsubishi Electric Corporation, Ebara Corporation, SUEZ Water Technologies & Solutions, Toshiba Corporation, MKS Instruments, Industrie De Nora, Teledyne Technologies, Primozone Production AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ozone Generation Market Strategic Shifts & Innovations
Digital control technologies converging with stringent environmental mandates are pushing ozone generation beyond its traditional water treatment role. This evolution creates demand for more intelligent, versatile, and application-specific ozone systems capable of meeting complex purification challenges.
Advanced Oxidation Processes (AOPs) combine ozone with other oxidants like UV light or hydrogen peroxide to enhance contaminant destruction. Industrial wastewater treatment facilities, particularly in the textile and pharmaceutical sectors, are adopting AOPs to break down recalcitrant organic compounds. This technology is hybridizing the market, blending traditional ozone generation with other treatment stages into integrated, high-performance purification solutions.
The European Union's Biocidal Products Regulation (BPR) imposes strict authorization and data requirements for ozone generated in-situ for disinfection purposes. This regulation increases the compliance burden for manufacturers, requiring extensive dossier submissions and efficacy testing to gain market access. Medical device sterilization and food contact surface disinfection segments are most affected, favoring suppliers who have completed the BPR authorization process.
Customers are shifting from one-time capital equipment purchases toward long-term service agreements that include remote monitoring and performance guarantees. This model disrupts the traditional sales channel, moving value from upfront hardware sales to recurring revenue based on system uptime and water quality outcomes. This trend is most visible in large municipal utilities in North America and Europe where operational budget predictability is a high priority.
Ozone Generation Market Segmentation
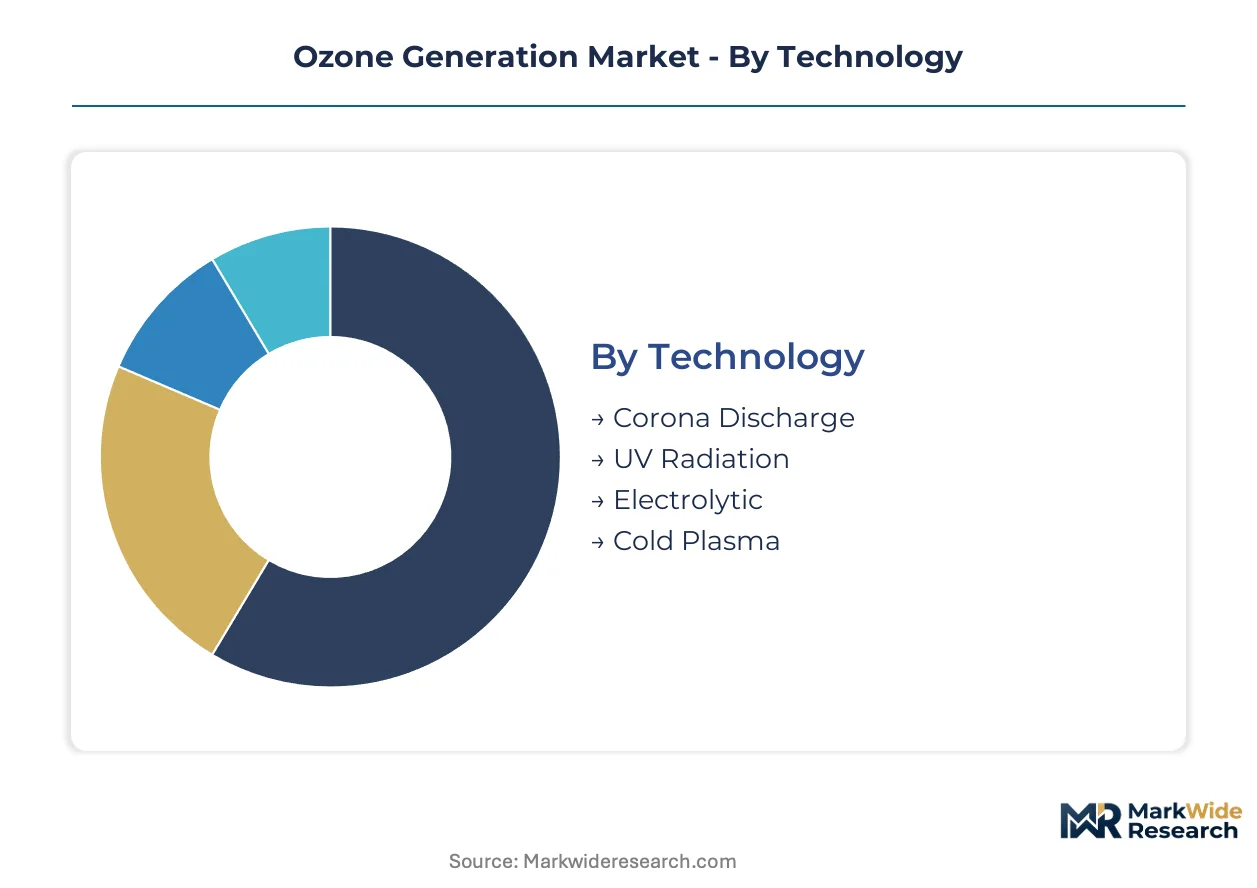
The ozone generation market segmentation reveals distinct operational profiles and adoption patterns across various dimensions. Analyzing these segments helps stakeholders understand where value accrues and how technological choices align with diverse end-user requirements. This granular view clarifies market dynamics and strategic investment areas for participants.
Technology:
The ozone generation market exhibits a varied technology landscape, ranging from mature, widely adopted methods to emerging, specialized solutions.
- Corona Discharge:This method uses a high-voltage electrical field to split oxygen molecules, which then recombine into ozone. Demand is concentrating in municipal water treatment facilities, driven by its scalability and effectiveness in managing disinfection byproducts.
- Electrolytic:Electrolytic ozone generators produce high-purity ozone by passing electricity through water, typically for specialized applications. This technology sees demand from the pharmaceutical and semiconductor industries due to its ability to meet stringent ultrapure water requirements.
- UV Radiation:UV ozone generation involves exposing oxygen to ultraviolet light, primarily used for smaller-scale air and water purification systems.
- Cold Plasma:Cold plasma technology generates ozone at lower temperatures, finding niche applications in air treatment and odor removal where energy efficiency is critical.
Corona Discharge technology handles the majority of throughput; Electrolytic methods are the fastest mover on share.
End User:
End-user segmentation highlights the diverse sectors benefiting from ozone technology, each with unique purity and volume requirements.
- Water Treatment:This segment includes municipal, industrial, and wastewater treatment plants utilizing ozone for disinfection, oxidation, and byproduct removal. Demand is concentrating in China's industrial sectors due to stringent effluent standards imposed by the MEE.
- Food Processing:Ozone is applied in food processing for surface sanitation, produce washing, and extending shelf life, offering a chemical-free alternative. This segment is experiencing demand expansion in North America, driven by consumer preference for natural preservation methods.
- Air Purification:Air purification applications use ozone for odor removal and sterilizing indoor air in commercial and residential settings.
- Medical Facilities:Medical facilities employ ozone for sterilizing equipment and sanitizing ultrapure water systems, particularly in pharmaceutical manufacturing.
Water Treatment remains the largest end-user segment, while Food Processing shows significant potential for accelerated adoption.
Application:
Application-based segmentation differentiates ozone use cases by their specific functional outcomes and target contaminants.
- Wastewater Treatment:Ozone oxidizes pollutants and disinfects treated water before discharge, helping facilities meet regulatory compliance. Demand is concentrating in Southeast Asian nations due to rapid urbanization and industrialization, necessitating new infrastructure.
- Industrial Applications:This broad segment covers diverse uses like pulp bleaching, chemical synthesis, and cooling tower treatment in various manufacturing sectors. Demand is experiencing growth in Japan's heavy industries, where high-capacity systems are crucial for process efficiency.
- Surface Disinfection:Ozone effectively disinfects surfaces in food processing, healthcare, and commercial environments, offering a residue-free sanitization method.
- Odor Removal:Ozone neutralizes malodorous compounds in air streams from industrial processes, wastewater facilities, and commercial kitchens.
Wastewater Treatment applications command substantial market volume, with Industrial Applications demonstrating strong expansion in specialized manufacturing.
Output Capacity:
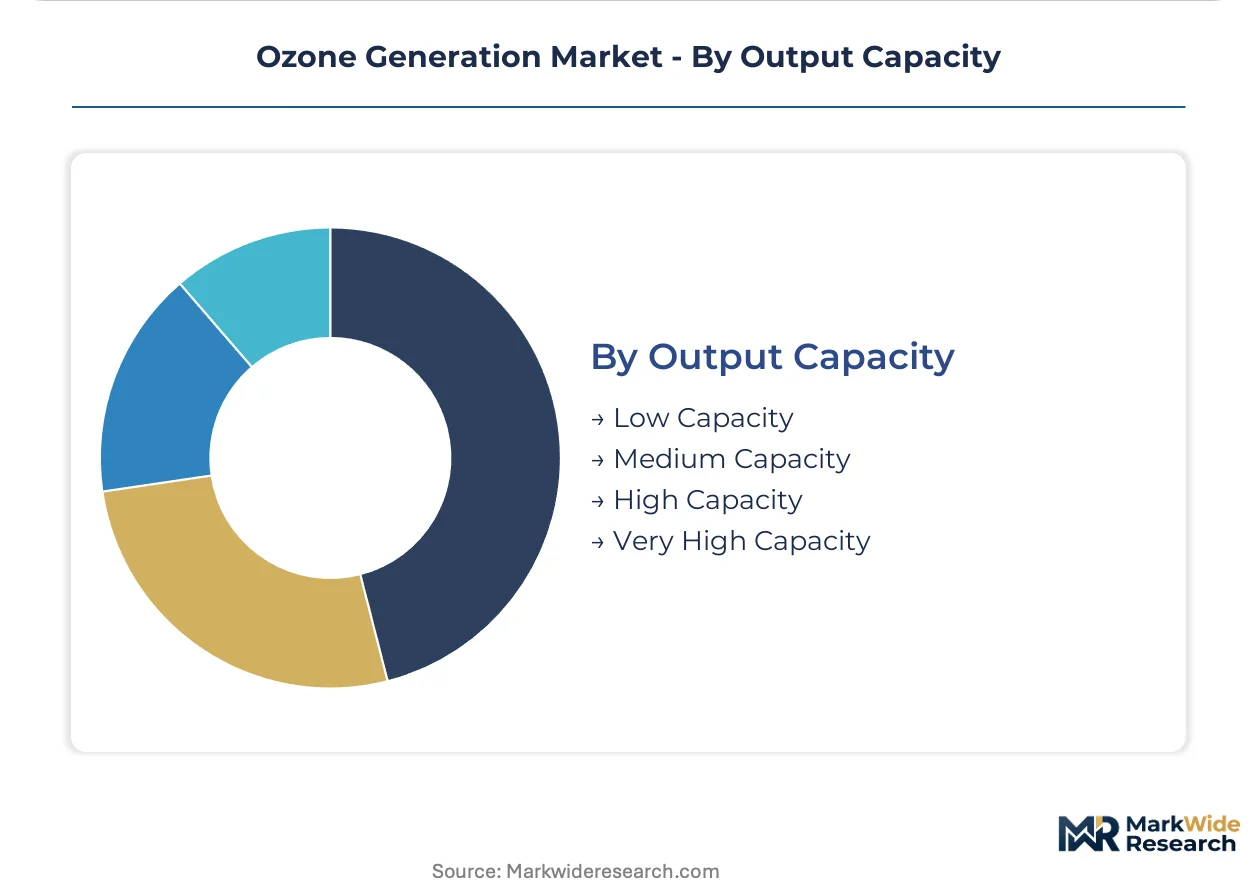
Output capacity segmentation distinguishes generator types based on their ozone production rates, catering to varied scale requirements.
- High Capacity:These systems produce large volumes of ozone, typically measured in kilograms per hour, for extensive municipal or industrial use. Demand is concentrating in large-scale municipal water projects globally, driven by the need for comprehensive disinfection.
- Very High Capacity:Representing the largest industrial-grade ozone generators, these units are designed for continuous, high-volume ozone supply in demanding environments. This capacity segment sees demand from major infrastructure investments in China, particularly for new water treatment installations.
- Low Capacity:Low-capacity generators produce small amounts of ozone, suitable for residential air purifiers or small-scale water treatment.
- Medium Capacity:Medium-capacity units serve commercial applications like swimming pools, laundries, and smaller industrial processes, balancing output with cost.
High Capacity units dominate installations for significant projects, while Very High Capacity systems are critical for new, large-scale infrastructure deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for ozone generation systems centers on municipal utilities and industrial operators. These entities require advanced oxidation processes to meet increasingly strict environmental compliance mandates. Long-term service agreements are gaining traction among large municipal utilities in North America and Europe, prioritizing operational budget predictability.
China
Demand for ozone systems in China is concentrating within industrial sectors due to stringent effluent standards. The Ministry of Ecology and Environment (MEE) mandates industrial effluent standards, accelerating adoption in manufacturing. Major infrastructure investments in cities like Shanghai and Beijing drive new high-capacity water treatment installations.
United States
The United States market sees significant demand from municipal water treatment for managing disinfection byproducts. The US EPA's Disinfection Byproducts Rule compels utilities to adopt advanced oxidation processes. Food processing facilities in states like California and Texas are expanding ozone use for surface sanitation and produce washing.
Japan
Japanese heavy industries are experiencing growth in demand for high-capacity ozone systems to ensure process efficiency. Japan's Ministry of Economy, Trade and Industry (METI) supports advanced industrial water treatment technologies. Industrial clusters in regions like Kansai and Kanto increasingly deploy ozone for diverse applications.
Germany
Germany's ozone generation market is driven by strict European Union environmental regulations. The EU's F-Gas Regulation and Biocidal Products Regulation (BPR) compel advanced water treatment and disinfection. Municipal utilities in regions like Bavaria and North Rhine-Westphalia integrate ozone for advanced oxidation processes.
Vietnam
Rapid urbanization and industrialization in Vietnam are creating new greenfield opportunities for water treatment systems. The country's Ministry of Natural Resources and Environment (MONRE) promotes advanced wastewater treatment solutions. Cities such as Ho Chi Minh City and Hanoi are investing in new municipal and industrial water infrastructure.
Ozone Generation Market Key Industry Players
Channel-controlling players compete with product-specialist players across the ozone generation market. The market structure exhibits a blend of large diversified conglomerates and niche technology providers, creating a multi-tiered competitive environment. Strategic archetypes include integrated water solution providers, industrial equipment specialists, and pure-play ozone system manufacturers focusing on specific applications. Companies pursue competitive positioning through portfolio diversification and strategic partnerships to expand their global reach and address diverse end-user needs.
Among the integrated water solution providers, SUEZ Water Technologies & Solutions exemplifies a global presence, serving large-scale municipal water projects with its extensive portfolio. Xylem occupies a position as a system integrator, focusing on intelligent water management platforms that enhance operational efficiency for utilities. Mitsubishi Electric Corporation anchors the high-capacity industrial systems segment, particularly for demanding applications in Japan and China. These entities leverage their extensive engineering capabilities and established client relationships to deliver comprehensive ozone solutions across varied end-user requirements.
| Leading Market Players |
|---|
| Xylem |
| Mitsubishi Electric Corporation |
| Ebara Corporation |
| SUEZ Water Technologies & Solutions |
| Toshiba Corporation |
| MKS Instruments |
| Industrie De Nora |
| Teledyne Technologies |
| Primozone Production AB |
Cost & Logistics Intelligence
Corona discharge technology components, especially high-voltage power supplies, largely originate from specialized electronics manufacturers in China and Japan. This concentration affects pricing power for ozone generator OEMs and influences their profit margins.
Pricing Analysis
Cost-plus contracts, often indexed to raw material costs for corrosion-resistant alloys, define many large-scale municipal project procurements. Price differentiation stems from system capacity, the inclusion of advanced digital controls, and comprehensive after-sales service agreements. Pricing pressure intensifies in the medium-capacity segment due to increasing competition among regional integrators. Water treatment utilities, driven by public budget constraints, exhibit the highest price sensitivity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common practices to manage working capital for manufacturers of ozone generation systems. Geographic supply concentration for critical components like high-purity oxygen generators and specialized dielectric materials centers on China and Germany. Raw material dependencies include stainless steel, Teflon, and proprietary ceramic components for corona discharge cells. Single-source vulnerability for advanced power electronics poses a structural risk. Distribution runs through a mix of direct sales to large municipal and industrial clients, alongside regional distributors for smaller commercial systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ozone generation market represents a defensive moat story, largely due to regulatory entrenchment from strict environmental compliance mandates. Utilities face high switching costs once advanced oxidation processes are integrated into existing infrastructure.
For Market Incumbents:
Pre-empt emerging competitive threats from modular system providers by investing in advanced power supply unit manufacturing capabilities. Reinforce control over after-sales service networks, particularly for high-voltage corona discharge systems, to mitigate technician scarcity. Consolidate market share through strategic acquisitions of specialized component manufacturers, ensuring supply chain resilience against raw material volatility. Develop next-generation AOP solutions that integrate seamlessly with existing water treatment infrastructure.
For New Entrants and Emerging Players:
Establish a beachhead in the food processing segment, leveraging demand for natural preservation methods and surface sanitation. Target Southeast Asian greenfield water infrastructure projects with cost-effective, modular ozone systems tailored for rapid deployment. Offer integrated solutions that bundle ozone generators with essential oxygen feed gas purification systems, simplifying procurement for smaller industrial clients. Focus on digital control integration and remote monitoring as a key go-to-market angle.
For Investors and Strategic Acquirers:
Secondary-cycle assets sit with mid-cap industrial equipment specialists with strong regional distribution networks. The ozone generation market offers long-term viability over the next decade, driven by persistent regulatory tailwinds and global water scarcity. Target integrated water solution providers that possess proprietary advanced oxidation process technologies and established long-term service agreements. Watch for increasing M&A activity among component suppliers as a signal of market consolidation and technology standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Oxidation Process R&D | Drives new applications for ozone technology in treating recalcitrant organic compounds in industrial wastewater. |
| Modular System Design Investment | Enhances operational flexibility and simplifies maintenance for municipal water treatment facilities. |
| Supply Chain Localization for Key Components | Mitigates single-source vulnerability for high-voltage power supplies and specialized dielectric materials. |
| Digital Control Platform Integration | Improves ozone output precision and enables remote monitoring for large-scale utility operations. |
| Long-term Service Contract Expansion | Secures recurring revenue streams and provides operational predictability for municipal utilities. |
Research Approach
Operator-level perspectives from municipal utility managers, industrial plant engineers, and water treatment solution integrators anchored the qualitative base for this analysis. Primary interviews were triangulated with secondary validation from regulatory filings, environmental agency reports, and industry association publications. This approach combined bottom-up market sizing with top-down validation across diverse data points.
Scenario-bracketing involved modeling optimistic and conservative growth trajectories to capture market volatility across the analysis window. The analytical framework segmented the market by technology, end-user, application, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical data trends and projected demand. Key forecast inputs included infrastructure spending in emerging economies and evolving effluent standards.
Stress conditions across capital expenditure cycles and regulatory enforcement levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented in the full report. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Quality Control Systems
Global Mist Eliminator Market
Air Quality Control Systems
US Air Quality Analyzers Market
Air Quality Control Systems
Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Air Quality Monitoring Software Market
Air Quality Control Systems
Europe Nitrogen Oxide Control Systems Market
Air Quality Control Systems
Air Quality Control Systems Market
Air Quality Control Systems
Middle-East and Africa Industrial Air Quality Control Systems Market
Air Quality Control Systems
Sustainable Air Filter Market
Air Quality Control Systems
Green Emissions Analyzers Market
Air Quality Control Systems
Asia-Pacific Indoor Air Purification Market
Air Quality Control Systems
Industrial Air Quality Control Systems Market
Air Quality Control Systems
United States Pollution Mask Market
Air Quality Control Systems
Asia Pacific Air Filtration Market
Air Quality Control Systems
Anti-Pollution Mask Market
Air Quality Control Systems
Asia-Pacific Air Quality Control System Market
Air Quality Control Systems
Southeast Asia Air Purifier Market