
 Philippines Gravity-Based Water Purifier Market | 2026-2036
Philippines Gravity-Based Water Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Gravity-Based Water Purifier Market Intelligence
Domestic assembly capacity in Laguna and Cavite manufacturing zones is shifting toward gravity-based systems with ceramic core technology. Unilever PLC leverages its nationwide FMCG distribution backbone to sustain shelf presence across provincial supermarkets. Woongjin Coway Co Ltd anchors its position through direct-to-home service contracts in Metro Manila. Kent RO Systems differentiates via stainless steel construction targeting premium household segments in Cebu and Davao.
Gravity-based water purifiers operate without electricity by forcing untreated water through activated carbon and ceramic micro-porous media, typically achieving bacterial retention at 0.2 to 0.5 micron porosity while preserving mineral content for potable output. Tabletop configurations dominate unit volume in dense urban barangays where counter space constraints limit wall-mounted installation. Ceramic material grades command margin premiums over plastic housings due to perceived durability and thermal stability in tropical climates. Online distribution channels are capturing Mindanao growth as logistics networks penetrate secondary municipalities previously served only by wholesale hardware channels.
The Department of Health enforces Philippine National Standards for Drinking Water that mandate coliform absence in household treatment devices, while the Department of Trade and Industry administers mandatory product certification through the Bureau of Philippine Standards. These frameworks elevate compliance costs for imported assemblies while creating procurement preference for locally certified units in government school and community center programs. Stakeholders must monitor pending amendments to labeling requirements that could force reformulation of activated carbon sourcing disclosures.
Market Dynamics
Ceramic core technology is unifying filtration performance expectations across Philippine household segments while the Department of Health tightens microbiological standards for potable water devices.
Growth Catalysts
- Metro Manila household density:Counter space constraints in dense urban barangays are pulling demand toward compact tabletop configurations that operate without electrical infrastructure.
- Department of Health water quality protocols:Mandatory coliform absence standards are elevating certified gravity-based systems above untreated alternatives in government procurement programs.
- Ceramic micro-porous media:Bacterial retention at 0.2 to 0.5 micron porosity is preserving mineral content while eliminating boiling requirements, reducing household energy expenditure.
Market Restraints
- Activated carbon sourcing volatility:Coconut shell carbon supply from Mindanao agricultural processors faces seasonal price fluctuation that compresses assembly margins in Laguna manufacturing zones.
- Import dependency for ceramic grades:High-porosity ceramic discs rely on concentrated overseas suppliers, exposing domestic assemblers to freight cost spikes and extended lead times.
- Technical throughput ceiling:Gravity-fed flow rates cap at approximately 3-4 liters per hour, limiting suitability for multi-family dwellings and small commercial kitchens.
Strategic Opportunities
- Visayas provincial penetration:Secondary municipalities in Cebu and Iloilo provinces remain underserved by direct-to-home service networks, creating whitespace for logistics-enabled distribution models.
- Online channel expansion:E-commerce platforms are penetrating Mindanao municipalities previously accessible only through wholesale hardware channels, collapsing traditional distributor tiers.
- Bureau of Philippine Standards certification preference:Local certification creates procurement advantage in Department of Education school drinking water programs and barangay health station deployments.
Industry Challenges
- Ceramic technician scarcity:Specialized kiln operation and porosity testing skills concentrate in Cavite industrial corridors, constraining quality-controlled expansion to new assembly locations.
- Labeling compliance timeline:Pending Department of Trade and Industry amendments to activated carbon sourcing disclosure requirements are forcing reformulation documentation across existing product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Gravity-Based Water Purifier Market |
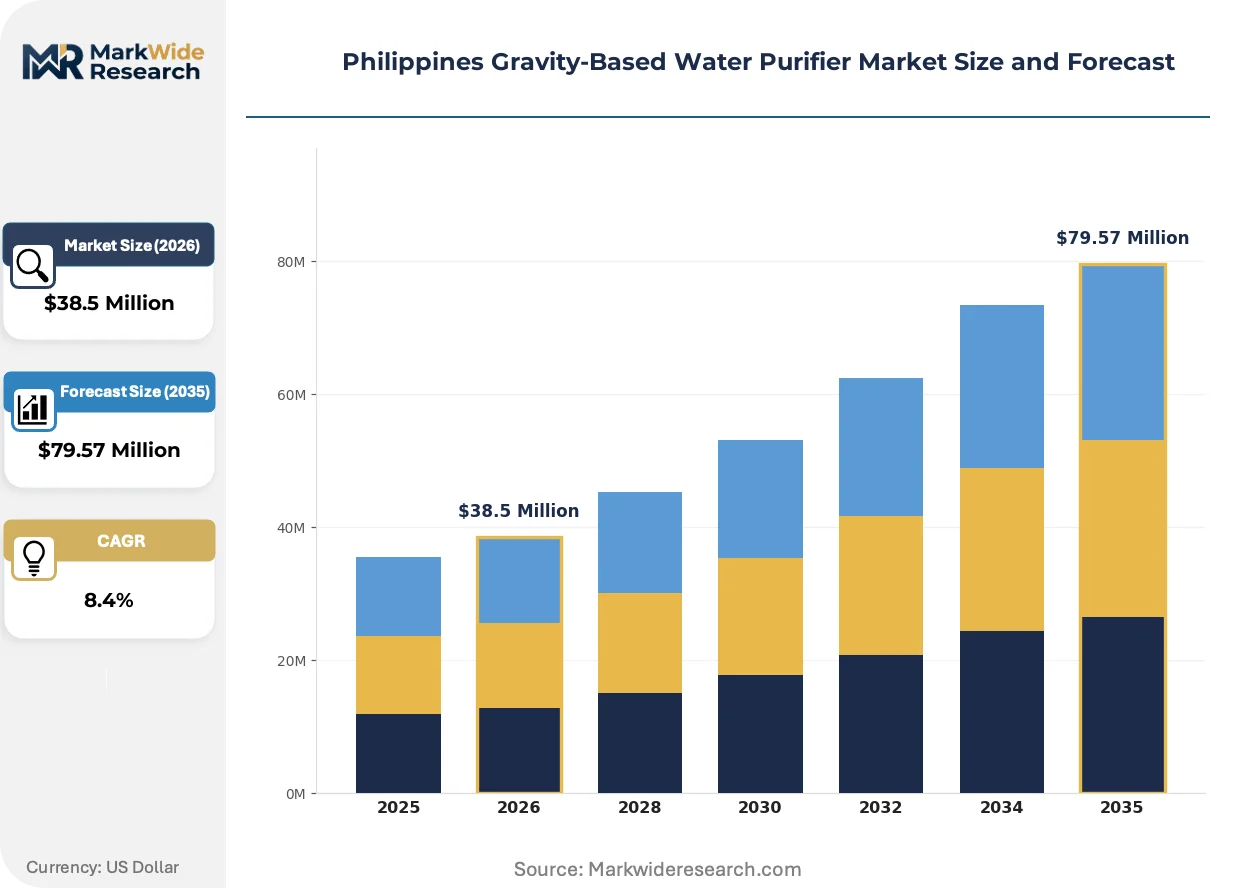
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $79.57 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop, Wall-Mounted, Portable, Dispenser Material: Plastic, Stainless Steel, Ceramic, Glass Distribution Channel: Online, Supermarket, Specialty Store, Wholesale End User: Household, Office, School, Community Center |
| Companies Covered | Culligan, Unilever PLC, A.O Smith, Woongjin Coway Co Ltd, Waters Philippines, Kent RO Systems, Toray, Pureit, Amway, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Gravity-Based Water Purifier Market Strategic Shifts & Innovations
Filtration technology convergence and regulatory disclosure mandates are compressing product development cycles while reshaping how Philippine households access certified water treatment.
Ceramic-activated carbon composite cartridges are unifying bacterial retention and chemical adsorption in single-replacement units. Metro Manila premium households are adopting these integrated systems at accelerating replacement frequencies. This unification is compressing the traditional two-stage maintenance cycle into simplified annual servicing, reducing household cognitive load and technician visit costs.
The Department of Health Philippine National Standards for Drinking Water is mandating explicit coliform test documentation for household treatment device marketing claims. Domestic assemblers in Laguna and Cavite zones are restructuring quality assurance protocols to capture batch-level microbiological validation. Stainless steel housing configurations targeting Cebu and Davao premium segments are absorbing disproportionate compliance investment due to export-intent positioning.
Direct-to-home service contracts are displacing transactional retail purchases in Metro Manila condominium clusters. Unbundled filter replacement subscriptions are capturing recurring revenue from households previously served by sari-sari store bottled water procurement. This behavioral pivot is most visible in gated community developments across Quezon City and Taguig where centralized water quality anxiety intersects with middle-income appliance ownership thresholds.
Philippines Gravity-Based Water Purifier Market Segmentation
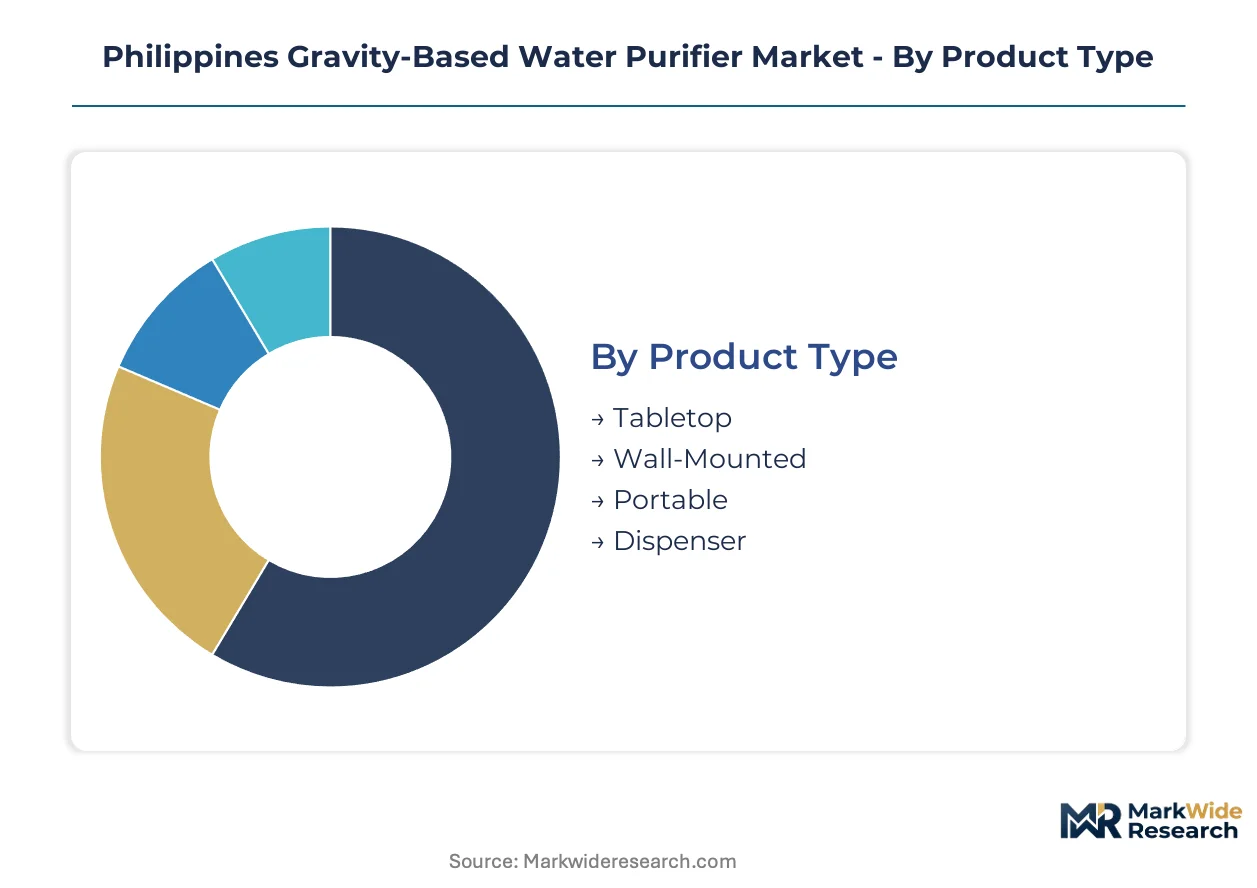
Gravity-based water purifier procurement in the Philippines fragments across certification tiers, installation constraints, and service delivery models. Bureau of Philippine Standards compliance requirements vary sharply by end-use setting, reshaping how assemblers configure product lines for distinct buyer workflows.
Product Type:
Tabletop configurations carry mandatory BPS safety certification for electrical-adjacent components, while wall-mounted variants trigger additional structural load testing protocols under Department of Public Works standards.
- Tabletop:Compact units with ceramic core filtration dominate Metro Manila condominium clusters where counter space constraints eliminate installation alternatives. Quezon City and Taguig gated communities absorb the highest replacement frequencies as direct-to-home service contracts displace sari-sari store bottled water procurement.
- Wall-Mounted:Bracket-fixed systems require reinforced housing assemblies to satisfy DPWH structural safety guidelines for elevated water load. Cebu and Davao premium household segments favor these configurations for kitchen aesthetic integration despite higher technician installation costs.
- Portable:Lightweight gravity-fed units target emergency deployment and rural barangay health stations with simplified BPS certification pathways.
- Dispenser:Integrated tap-and-reservoir designs serve multi-family dwellings and small commercial kitchens constrained by gravity-fed throughput ceilings.
Tabletop sits at the top of the volume ranking, with portable climbing the fastest as Department of Health school drinking water programs expand procurement.
Material:
Raw material selection determines thermal stability performance in tropical climates and shapes margin structures across Laguna and Cavite manufacturing zones.
- Plastic:Polypropylene housings dominate entry-tier production with lowest unit economics, though Visayas and Mindanao households increasingly perceive thermal degradation risks under sustained direct sunlight exposure.
- Stainless Steel:304-grade construction commands premium positioning in Cebu and Davao export-intent segments, absorbing disproportionate Department of Health microbiological validation investment for batch-level documentation.
- Ceramic:Micro-porous discs fired at controlled kiln temperatures achieve bacterial retention at 0.2 to 0.5 micron porosity while preserving mineral content.
- Glass:Borosilicate reservoir configurations serve aesthetic-conscious Metro Manila premium households with highest replacement part logistics costs.
Plastic retains dominant volume share, with ceramic gaining share fastest as ceramic-activated carbon composite cartridges compress maintenance cycles.
Distribution Channel:
Channel selection determines certification documentation requirements and service bundling feasibility for end-user segments.
- Online:E-commerce penetration into Mindanao secondary municipalities collapses traditional wholesale hardware tiers, though BPS labeling compliance documentation must accompany every shipment.
- Supermarket:Provincial shelf presence requires FMCG distribution backbone density that Unilever PLC leverages across Visayas supermarket networks.
- Specialty Store:Dedicated water treatment retailers concentrate in Metro Manila with technician-staffed showrooms enabling direct-to-home service contract origination.
- Wholesale:Hardware channel dominance persists in Mindanao municipalities with underdeveloped logistics infrastructure, constraining ceramic-grade product penetration.
Supermarket channels anchor volume leadership, with online expanding most quickly as logistics networks penetrate previously inaccessible barangays.
End User:
Buyer category dictates coliform testing documentation intensity and procurement preference for locally certified units.
- Household:Individual family units drive replacement subscription revenue in Metro Manila condominium clusters where centralized water quality anxiety intersects with appliance ownership thresholds.
- Office:Corporate procurement requires explicit Philippine National Standards for Drinking Water compliance documentation, favoring BPS-certified assemblers in Laguna and Cavite zones.
- School:Department of Education drinking water programs mandate coliform absence validation, creating procurement preference for locally certified tabletop configurations.
- Community Center:Barangay health station deployments absorb government program volume with simplified technical specifications and extended replacement cycles.
Household captures dominant volume share, with school representing the steepest expansion trajectory as Department of Health protocols tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic assembly in Laguna and Cavite manufacturing zones is capturing procurement preference as Bureau of Philippine Standards certification creates cost-of-compliance gaps against imported alternatives. Local certification pathways are accelerating production migration from overseas suppliers.
Metro Manila
Condominium density in Quezon City and Taguig gated communities is pulling demand toward compact tabletop configurations. Department of Health Philippine National Standards for Drinking Water enforcement is elevating certified systems above untreated alternatives. Direct-to-home service contracts are displacing sari-sari store bottled water procurement in middle-income clusters.
Visayas
Ceramic filtration technology is displacing conventional plastic units in Cebu and Iloilo provinces as households perceive thermal degradation risks. Unilever PLC leverages its FMCG distribution backbone to sustain shelf presence across provincial supermarket networks. Secondary municipalities remain underserved by direct-to-home service networks, creating whitespace for logistics-enabled distribution models.
Mindanao
E-commerce platforms are penetrating secondary municipalities previously accessible only through wholesale hardware channels. Coconut shell activated carbon supply from Mindanao agricultural processors faces seasonal price fluctuation that compresses assembly margins. Online distribution channels are collapsing traditional distributor tiers as logistics networks penetrate previously inaccessible barangays.
Central Luzon
Laguna and Cavite manufacturing zones are shifting toward gravity-based systems with ceramic core technology. Bureau of Philippine Standards certification creates procurement advantage in Department of Education school drinking water programs. Specialized kiln operation and porosity testing skills concentrate in Cavite industrial corridors, constraining quality-controlled expansion.
Davao Region
Premium household segments in Davao favor stainless steel housing configurations for kitchen aesthetic integration. Kent RO Systems differentiates via stainless steel construction targeting this export-intent positioning. Wall-mounted systems require reinforced housing assemblies to satisfy Department of Public Works structural safety guidelines for elevated water load.
Philippines Gravity-Based Water Purifier Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue ceramic-specialist positioning and online-native distribution. The market structure reflects moderate consolidation around FMCG-backed distribution networks and direct-to-home service specialists. Three archetypes dominate: multinational consumer goods conglomerates with existing retail density, Korean water appliance specialists with service-contract expertise, and Indian filtration manufacturers with stainless steel premium positioning. Competitive moves concentrate on certification leverage for government procurement and logistics penetration into secondary municipalities.
Within the multinational tier, Unilever PLC exemplifies FMCG distribution backbone deployment, while Woongjin Coway Co Ltd anchors Korean direct-to-home service contract origination. Kent RO Systems represents Indian-origin premium positioning through stainless steel construction differentiation. These three occupy distinct competitive vectors without direct feature-for-feature overlap.
| Leading Market Players |
|---|
| Culligan |
| Unilever PLC |
| A.O Smith |
| Woongjin Coway Co Ltd |
| Waters Philippines |
| Kent RO Systems |
| Toray |
| Pureit |
| Amway |
| Others |
Cost & Logistics Intelligence
Backward integration into coconut shell activated carbon sourcing anchors both cost position and margin stability for Laguna-based assemblers confronting Mindanao agricultural processor price volatility. This upstream control over feedstock procurement insulates domestic manufacturers from seasonal compression while supporting Bureau of Philippine Standards certification investment.
Pricing Analysis
Distributor margin layers in wholesale hardware channels absorb 18-25 point markups before reaching Mindanao barangay end-users, while direct-to-home service contracts collapse these tiers entirely. Three-tier pricing structure across premium stainless steel, standard ceramic-core, and economy plastic configurations stratifies by certification grade and after-sales bundling intensity. Cost compression in entry-tier plastic units is intensifying because Visayas households perceive thermal degradation risks under sustained tropical sunlight exposure. Sari-sari store procurement patterns in rural municipalities exhibit highest price sensitivity, whereas Metro Manila condominium clusters prioritize subscription convenience over unit economics.
Supply Chain Analysis
Bureau of Philippine Standards certification gates create 4-6 month qualification timelines that favor incumbent Laguna and Cavite assemblers with established quality protocols over import-dependent entrants. Ceramic micro-porous disc supply draws from concentrated overseas kiln operations in China and Vietnam, while activated carbon feeds from Mindanao agricultural processors. Single-source vulnerability in high-porosity ceramic grades exposes domestic assemblers to freight cost spikes and extended lead times. Distribution runs through FMCG backbone density for provincial supermarket penetration, direct-to-home technician networks for Metro Manila service contracts, and collapsing wholesale tiers for Mindanao e-commerce expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory momentum as Department of Health Philippine National Standards for Drinking Water enforcement tightens coliform absence mandates across household treatment devices.
For Market Incumbents: Anticipate ceramic-activated carbon composite cartridge unification compressing replacement frequencies and technician visit economics. Defend installed base through exclusive direct-to-home service contract origination in Quezon City and Taguig gated communities. Counter emerging online-native entrants by locking supermarket shelf presence via Unilever PLC-style FMCG distribution backbone density.
For New Entrants and Emerging Players: E-commerce logistics partnerships offer whitespace penetration into Mindanao secondary municipalities previously accessible only through wholesale hardware channels. Target Visayas provincial households in Cebu and Iloilo with ceramic-core positioning that displaces thermal-degradation-perceived plastic units. Anchor go-to-market through Bureau of Philippine Standards certification fast-tracking for Department of Education school drinking water program eligibility.
For Investors and Strategic Acquirers: Roll-up economics work for ceramic-specialist assemblers with captive kiln operations because Cavite industrial corridor technician scarcity constrains quality-controlled expansion to new locations. Five-to-ten year viability hinges on subscription revenue capture from Metro Manila middle-income condominium clusters. Monitor Department of Trade and Industry labeling amendment finalization as inflection indicator for compliance cost restructuring across existing product lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Bureau of Philippine Standards Certification Fast-Track | Accelerates procurement eligibility in Department of Education school drinking water programs. |
| Direct-to-Home Service Contract Expansion | Captures recurring subscription revenue from Metro Manila condominium clusters. |
| Ceramic-Activated Carbon Composite Cartridge Development | Unifies bacterial retention and chemical adsorption into simplified annual replacement cycles. |
| E-Commerce Logistics Partnership Penetration | Collapses traditional wholesale tiers in Mindanao secondary municipalities. |
| Backward Integration into Coconut Shell Carbon Sourcing | Insulates Laguna assemblers from Mindanao agricultural processor seasonal price fluctuation. |
Research Approach
Coverage spans Metro Manila, Visayas, Mindanao, Central Luzon, and Davao Region, with primary inputs from each. The approach combines structured interviews with ceramic kiln technicians, Bureau of Philippine Standards certification officers, Department of Health water quality inspectors, supermarket category buyers, and direct-to-home service contract managers with secondary validation. Secondary sources include Bureau of Philippine Standards product registry databases, Department of Education procurement documentation, customs import records for ceramic disc assemblies, and FMCG distribution network disclosures. Bottom-up unit shipment modeling triangulates against top-down market value reconstruction.
Granularity-level modeling captures product type configurations at the barangay cluster level, material grade tiers across manufacturing zones, distribution channel economics by logistics infrastructure maturity, and end-user segmentation by procurement documentation intensity. CAGRs derive from installed base replacement frequency analysis and new household penetration modeling across the projection horizon. Forecast inputs incorporate Department of Health protocol amendment timelines and e-commerce logistics network expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ceramic supply chain concentration and pending Department of Trade and Industry labeling disclosure requirements. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and logistics infrastructure buildout pacing. A model refresh is warranted upon material change in Bureau of Philippine Standards certification processing timelines or coconut shell activated carbon supply contract restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Home Water Softener System Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Home Water Filtration Unit Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Water Treatment Ozone Generator Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Water Treatment As a Service Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Point of Entry Water Treatment Systems Market
Water Treatment Systems
Water Desalination Equipment Market