
 US Wastewater Secondary Treatment Equipment Market | 2026-2036
US Wastewater Secondary Treatment Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
US Wastewater Secondary Treatment Equipment Market Intelligence
Texas is tilting toward membrane bioreactor deployments as Gulf Coast refineries and petrochemical complexes expand treatment capacity. Xylem, Inc. leverages its vertical integration across pumps, controls, and biological systems to anchor large municipal contracts. Evoqua Water Technologies LLC differentiates through advanced oxidation and biological process intensification, while Pentair plc sustains competitive positioning via modular skids that reduce field construction timelines.
US wastewater secondary treatment equipment encompasses biological reactors, aeration systems, clarifiers, and nutrient removal technologies designed to reduce biochemical oxygen demand and suspended solids following primary sedimentation. These systems typically operate at hydraulic retention times of four to twelve hours and mixed liquor suspended solids concentrations between 1500 and 3500 mg per liter, converting organic pollutants into settleable biomass before tertiary polishing or disinfection. Membrane bioreactor installations command premium pricing due to their smaller footprint and superior effluent quality, particularly in coastal municipalities where direct discharge standards are stringent. Sequencing batch reactor technology occupies a growing niche among smaller utilities seeking operational flexibility and reduced operator staffing requirements.
The EPA enforces secondary treatment standards under the Clean Water Act, while state environmental agencies such as the California State Water Resources Control Board and the Texas Commission on Environmental Quality impose basin-specific total maximum daily loads that drive equipment upgrades. OSHA and state-level confined space regulations further shape system design by mandating access provisions and ventilation for below-grade installations. Stakeholders must weigh capital intensity against operational resilience as climate volatility strains conventional activated sludge reliability across flood-prone watersheds.
Market Dynamics
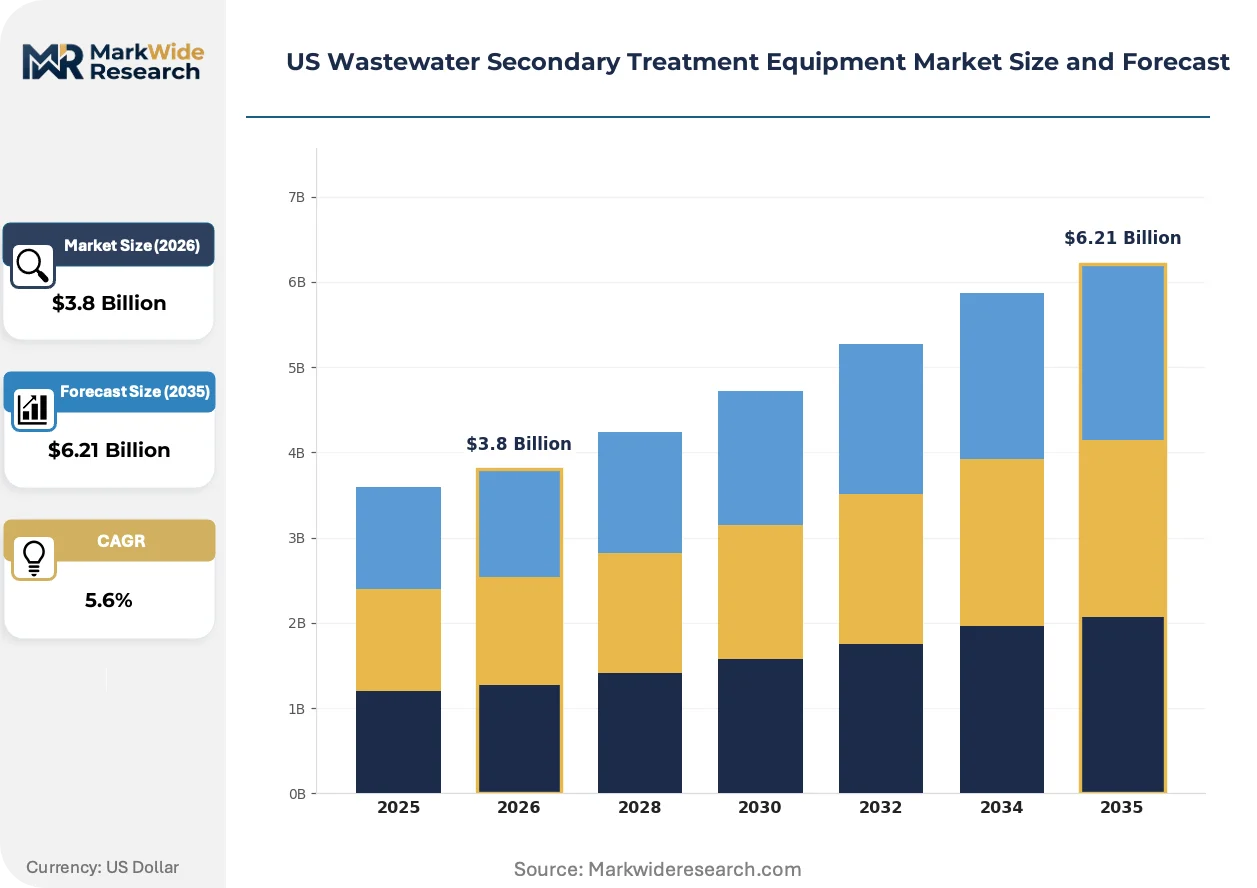
The US Wastewater Secondary Treatment Equipment Market is undergoing structural recalibration as EPA consent decrees force municipal utilities toward biological nutrient removal upgrades, while membrane bioreactor technology compresses project footprints and accelerates replacement cycles across flood-prone Gulf Coast watersheds.
Growth Catalysts
- EPA Consent Decrees:Federal enforcement actions mandate nutrient removal upgrades across aging activated sludge facilities, compelling capital deployment into clarifier and aeration system replacements.
- Membrane Bioreactor Technology:Coastal municipalities facing direct discharge standards adopt MBR systems for superior effluent quality and reduced land requirements.
- Texas Petrochemical Expansion:Gulf Coast refineries drive demand for high-capacity biological reactors as process water treatment volumes scale with downstream capacity additions.
Market Restraints
- Specialized Alloy Supply Concentration:Stainless steel and super-austenitic alloys for aeration diffusers and membrane cassettes concentrate among limited domestic mill suppliers, exposing project timelines to raw material volatility.
- Skilled Operator Scarcity:Complex sequencing batch reactor and MBR systems require certified wastewater operators that smaller utilities struggle to recruit and retain.
- Interconnection Queue Delays:Electrical infrastructure upgrades for high-energy aeration and pumping systems face utility interconnection backlogs that extend commissioning timelines.
Strategic Opportunities
- Florida Phosphorus Limits:State-level total maximum daily load reductions create replacement demand across the Kissimmee River and Lake Okeechobee watersheds for enhanced biological phosphorus removal systems.
- California Water Reuse Mandates:Title 22 regulations for indirect potable reuse drive tertiary-ready MBR installations that command premium equipment specifications.
- Digital Twin Integration:Convergence of computational fluid dynamics modeling with real-time dissolved oxygen sensors enables predictive aeration control that reduces energy intensity.
Industry Challenges
- Legacy SCADA Integration:Municipal utilities operate decades-old control architectures that resist seamless integration with modern biological process automation platforms.
- Confined Space Certification:OSHA-mandated entry protocols for below-grade reactor maintenance extend labor hours and complicate contractor mobilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Wastewater Secondary Treatment Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Sludge, Sequencing Batch Reactor, Membrane Bioreactor, Trickling Filter Technology: Aerobic Treatment, Anaerobic Treatment, Oxidation Ditch, Moving Bed Biofilm Reactor End User: Municipal Utilities, Industrial Plants, Agricultural Operations, Commercial Facilities Installation: On-site Systems, Centralized Facilities, Retrofit Installations, Modular Units |
| Companies Covered | Xylem, Inc., Pentair plc, Evoqua Water Technologies LLC, Aquatech International LLC, SUEZ, Ecolab Inc., Veolia, Calgon Carbon Corporation, Parkson Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Wastewater Secondary Treatment Equipment Market Strategic Shifts & Innovations
Digital instrumentation and real-time analytics are transforming how biological treatment systems optimize energy consumption and nutrient removal performance. Three convergent developments are redefining equipment specifications and vendor competitive positioning.
Smart dissolved oxygen and ammonia sensors paired with machine learning algorithms are digitizing aeration control across activated sludge basins. Large municipal utilities in California and Texas are deploying these systems at scale. The technology is digitizing operational decision-making, compressing the advantage of traditional manual sampling protocols.
The EPA's emerging per- and polyfluoroalkyl substances rule is tightening analytical detection limits for effluent monitoring. Industrial pretreatment programs must now specify advanced oxidation process compatibility in secondary system designs. Chemical manufacturers along the Ohio River Valley are retrofitting biological reactors with ozone and UV integration to meet anticipated enforcement thresholds.
Performance-based operations contracts are displacing traditional equipment procurement for municipal utilities. Florida water authorities now contract for guaranteed nutrient removal outcomes rather than specified reactor volumes. This shift concentrates risk with equipment vendors and favors integrated system providers capable of warranting biological process performance.
US Wastewater Secondary Treatment Equipment Market Segmentation
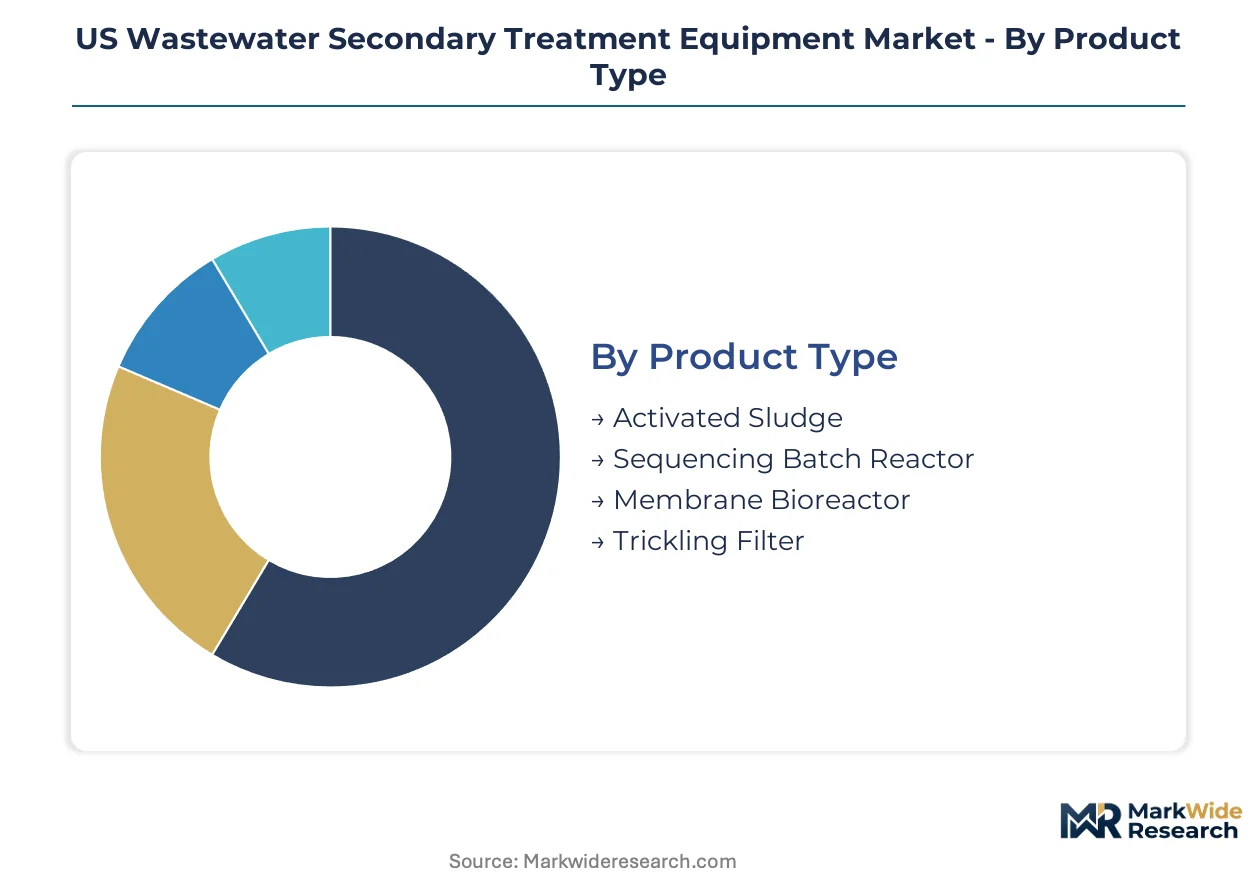
Equipment segmentation in US wastewater secondary treatment reflects divergent capital cycles and operational complexity. Municipal procurement patterns favor proven technologies with extended depreciation schedules, while industrial end-users prioritize footprint reduction and rapid deployment.
Product Type:
Replacement cycles vary dramatically across biological reactor categories, with some technologies turning over in 15-year regulatory-driven waves while others persist for 30-plus years.
- Activated Sludge:Conventional suspended-growth systems utilizing aeration basins and secondary clarifiers remain the workhorse technology across Midwest and Northeast municipal networks. Texas and California utilities are retiring aging infrastructure under EPA consent decrees, driving clarifier and aeration equipment replacement demand.
- Membrane Bioreactor:Integrated membrane filtration within biological reactors delivers effluent quality suitable for direct discharge or reuse applications without tertiary filtration. Coastal municipalities in Florida and California facing phosphorus limits and water scarcity are specifying MBR systems despite 40-60% capital cost premiums.
- Sequencing Batch Reactor:Time-sequenced fill-react-settle-decant cycles eliminate separate clarifiers, suiting smaller utilities with limited operator staffing. SBR installations are gaining share fastest among rural Texas water districts seeking operational flexibility.
- Trickling Filter:Fixed-film biological towers with rock or plastic media represent legacy infrastructure concentrated in older Appalachian and Rust Belt systems. These low-energy systems persist where electricity costs constrain operating budgets.
Activated Sludge dominates installed base. Membrane Bioreactor is where expansion concentrates.
Technology:
Cost tier stratification separates premium biological process intensification from standard aerobic configurations, with anaerobic systems commanding specialized engineering premiums.
- Aerobic Treatment:Oxygen-dependent microbial oxidation of organic pollutants operates across activated sludge, MBR, and SBR configurations. Municipal utilities in the Great Lakes region are expanding aerobic capacity to meet phosphorus discharge limits under state TMDL programs.
- Anaerobic Treatment:Oxygen-free biological processes generating methane biogas serve high-strength industrial wastewaters from food processing and brewing operations. California dairy operations and Texas meatpacking facilities are deploying covered anaerobic lagoons for energy recovery.
- Oxidation Ditch:Oval-shaped aeration basins with horizontal brush aerators provide extended detention times for small-to-medium communities. Florida water authorities favor oxidation ditches for their operational simplicity and nitrogen removal capability.
- Moving Bed Biofilm Reactor:Suspended plastic carriers with attached biofilm combine fixed-film stability with suspended-growth resilience. MBBR technology is climbing the fastest among industrial pretreatment applications requiring compact footprints.
Aerobic Treatment anchors municipal procurement. Moving Bed Biofilm Reactor is expanding most quickly in industrial segments.
End User:
Volume concentration and margin profile diverge sharply between rate-regulated municipal utilities and price-sensitive industrial operators.
- Municipal Utilities:Publicly owned treatment works serving residential and commercial sewer connections constitute the dominant demand channel. EPA consent decrees in Cleveland, Detroit, and Houston are driving billion-dollar biological nutrient removal upgrades.
- Industrial Plants:Manufacturing facilities with process water discharge requirements face increasingly stringent pretreatment standards. Gulf Coast petrochemical complexes are installing high-capacity biological reactors as refining capacity expands.
- Agricultural Operations:Concentrated animal feeding operations and food processing facilities generate high-strength organic wastewaters. California Central Valley dairy clusters are retrofitting anaerobic digesters under regional water quality control board orders.
- Commercial Facilities:Hotels, resorts, and remote workforce camps deploy packaged secondary treatment for decentralized wastewater management. Modular SBR and MBR systems serve Florida Keys resorts where centralized sewer access is unavailable.
Municipal Utilities dominate installed base. Industrial Plants represent the steepest expansion trajectory.
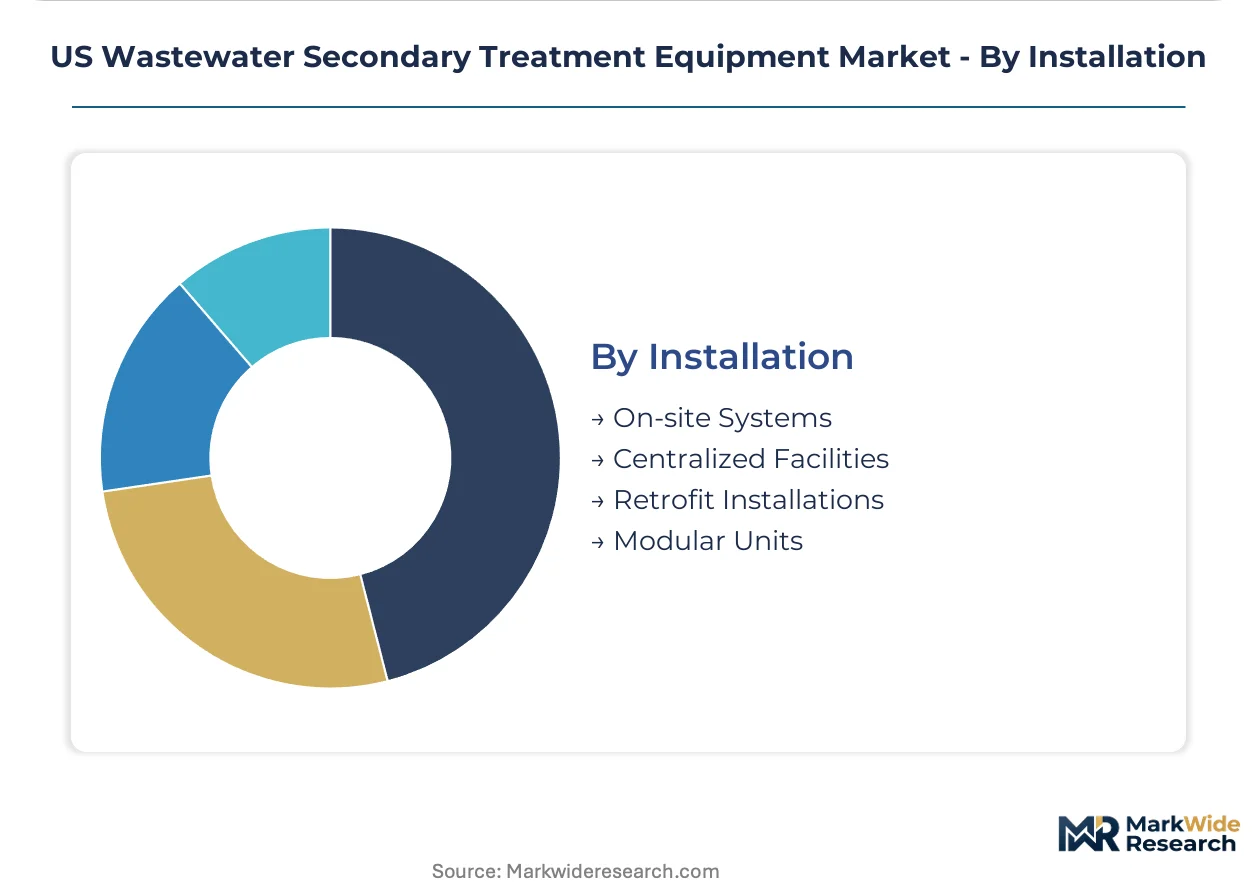
Installation:
Customer type and project urgency dictate installation modality, with retrofit constraints driving specialized equipment specifications.
- On-site Systems:Decentralized treatment at individual properties or small clusters serves unsewered areas and remote facilities. Texas Hill Country developments are specifying on-site MBR systems where municipal sewer extension is economically unfeasible.
- Centralized Facilities:Regional treatment plants aggregating flows from multiple municipalities or industrial zones achieve economies of scale. California's Orange County Sanitation District exemplifies centralized tertiary-ready MBR deployment.
- Retrofit Installations:Equipment replacement within existing hydraulic and structural constraints demands custom engineering. Aging activated sludge basins in the Northeast are receiving aeration system upgrades without full reconstruction.
- Modular Units:Pre-engineered skids and containerized systems compress field construction timelines for capacity expansion. Florida water authorities are specifying modular SBR units to accelerate phosphorus compliance timelines.
Centralized Facilities dominate installed base. Modular Units are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in industrial corridors with established water infrastructure supply chains. Texas, California, and Florida generate the dominant share of procurement volume as municipal consent decrees and industrial expansion converge. The analysis examines demand patterns across five sub-regional markets.
Texas
Gulf Coast petrochemical complexes are commissioning high-capacity biological reactors as refining throughput expands. The Texas Commission on Environmental Quality enforces basin-specific total maximum daily loads that force nutrient removal retrofits across the Houston-Galveston region. Dallas-Fort Worth water utilities are replacing aging activated sludge infrastructure under federal enforcement timelines.
California
Water reuse mandates under Title 22 regulations are accelerating membrane bioreactor deployments for indirect potable reuse. The State Water Resources Control Board imposes increasingly stringent effluent limits that drive clarifier and aeration system replacements. Orange County Sanitation District exemplifies centralized tertiary-ready MBR procurement at scale.
Florida
Phosphorus discharge limits across the Kissimmee River and Lake Okeechobee watersheds are forcing enhanced biological phosphorus removal upgrades. The Department of Environmental Protection administers total maximum daily load programs that mandate equipment replacement cycles. South Florida water authorities are specifying modular sequencing batch reactor units to compress compliance timelines.
Great Lakes Region
Municipal utilities across Michigan, Ohio, and Illinois are expanding biological nutrient removal capacity under Great Lakes Restoration Initiative priorities. EPA consent decrees in Cleveland and Detroit mandate billion-dollar clarifier and aeration system replacements. Chicago-area wastewater agencies are retrofitting oxidation ditches for simultaneous nitrogen and phosphorus removal.
Southeast
Atlanta-area utilities are upgrading secondary treatment capacity to accommodate metro population growth exceeding infrastructure design capacity. Georgia Environmental Protection Division enforcement actions are accelerating replacement of trickling filter systems with activated sludge alternatives. Carolina textile belt municipalities are retrofitting biological reactors for color and nutrient removal under renewed discharge permits.
US Wastewater Secondary Treatment Equipment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in aeration and membrane supply. The vendor base organizes around three strategic archetypes: full-system providers bundling biological reactors with controls and instrumentation; membrane cassette and diffuser component fabricators; and regional engineering firms assembling skid-mounted packages from purchased subsystems. Consolidation pressure is intensifying as municipal procurement shifts toward performance-based contracting, while backward integration into alloy fabrication and sensor manufacturing reshapes supplier economics.
Among the full-system integrators named in raw data, Xylem, Inc. and Evoqua Water Technologies LLC occupy positions representing the platform-provider archetype, while Pentair plc exemplifies the component-to-system expansion path. These Delaware-incorporated entities anchor the competitive set as municipal utilities consolidate vendor relationships around fewer integrated suppliers capable of warranting biological process outcomes.
| Leading Market Players |
|---|
| Xylem, Inc. |
| Pentair plc |
| Evoqua Water Technologies LLC |
| Aquatech International LLC |
| SUEZ |
| Ecolab Inc. |
| Veolia |
| Calgon Carbon Corporation |
| Parkson Corporation |
| Others |
Cost & Logistics Intelligence
The Houston Ship Channel freight corridor concentrates inbound stainless steel and membrane module movements, with demurrage costs at Port Houston feeding directly into equipment pricing spreads between Gulf Coast fabricators and inland municipal buyers.
Pricing Analysis
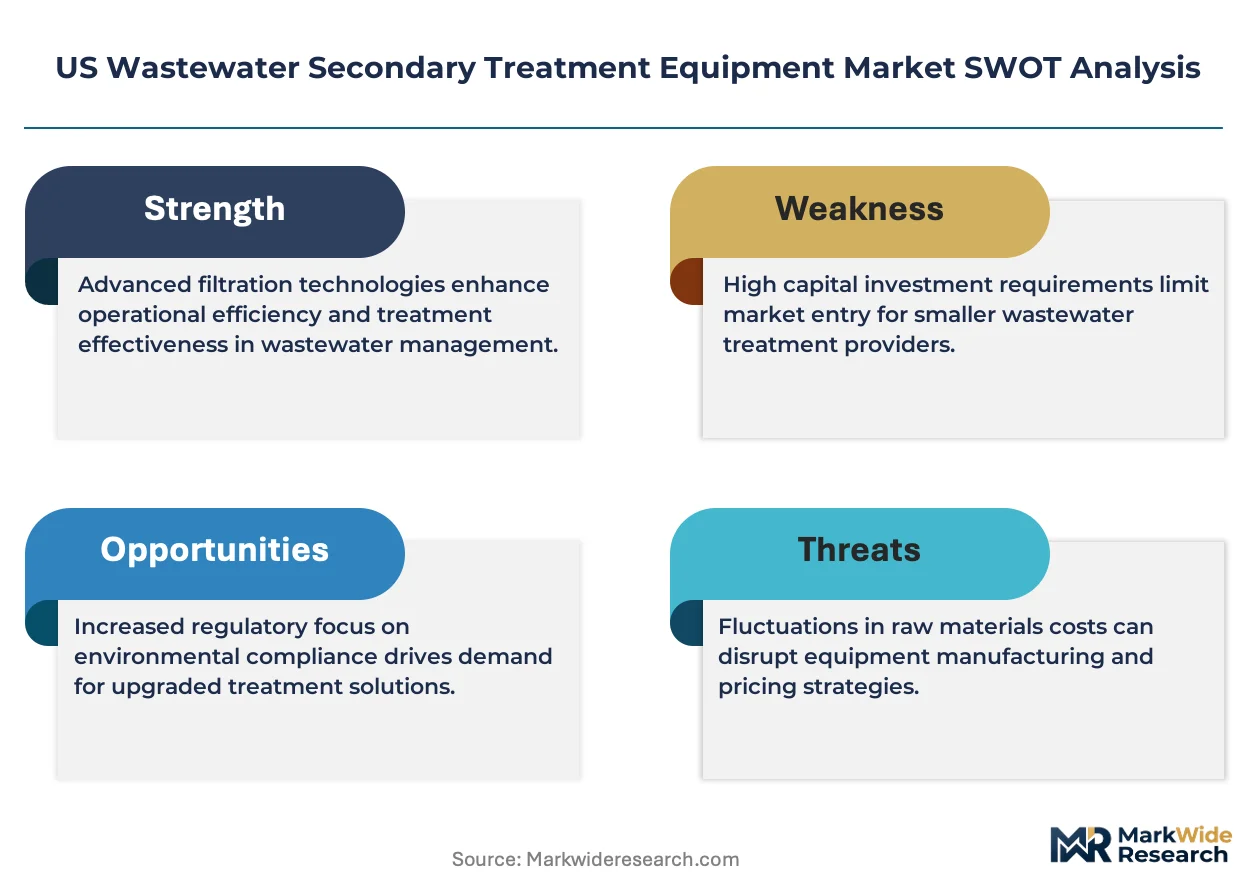
EPA consent decree timelines dictate the pricing tier structure across the US wastewater secondary treatment equipment landscape. Project-based contracting dominates, with price differentiation resting on membrane cassette quality grades and NSF/ANSI 61 certification levels for potable water contact components. Cost compression in conventional activated sludge equipment is intensifying because Texas petrochemical buyers are consolidating procurement around integrated system providers. Small rural utilities exhibit the highest price sensitivity, while California water authorities facing Title 22 reuse mandates absorb premium MBR specifications without volume negotiation.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for membrane cassettes and ceramic diffuser elements. Manufacturing concentrates in Germany, Japan, and domestic Ohio Valley fabrication facilities for specialized super-austenitic alloys. Raw material dependencies center on nickel, molybdenum, and polyvinylidene fluoride membrane polymers. Single-source vulnerability persists for high-flux hollow-fiber modules. Distribution runs through regional water infrastructure distributors holding municipal procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US wastewater secondary treatment equipment market sits in early-cycle expansion as EPA enforcement accelerates biological nutrient removal retrofits across aging municipal infrastructure.
For Market Incumbents: Build switching-cost moats through SCADA integration and long-term service contracts. Xylem and Evoqua should deepen backward integration into sensor manufacturing to lock out modular competitors. Consolidate regional engineering partners before performance-based contracting displaces equipment-only procurement. The threat is emerging skid-assemblers without biological process warranties. For New Entrants and Emerging Players: Build out digital twin and predictive aeration control capabilities as a beachhead into Texas municipal utilities. Target rural water districts in the Hill Country and Panhandle regions where operator scarcity creates appetite for automated SBR systems. Pursue equipment-as-a-service models that transfer performance risk from cash-constrained buyers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stagnant water divisions lacking MBR or advanced oxidation capabilities. The five-to-ten year viability window favors platforms with demonstrated nutrient removal outcomes rather than component catalogs. Watch Florida phosphorus limit enforcement velocity as the inflection signal for enhanced biological phosphorus removal system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Contracting Transition | Florida water authorities now contract for guaranteed nutrient removal outcomes rather than specified reactor volumes. |
| Membrane Bioreactor Capacity Expansion | Coastal municipalities facing direct discharge standards adopt MBR systems for superior effluent quality and reduced land requirements. |
| Digital Twin Integration | Convergence of computational fluid dynamics modeling with real-time dissolved oxygen sensors enables predictive aeration control. |
| Backward Integration into Sensor Manufacturing | Platform integrators are capturing margin from smart dissolved oxygen and ammonia sensor supply chains. |
| Modular Skid Deployment | Pre-engineered systems compress field construction timelines for phosphorus compliance deadlines across Florida watersheds. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with municipal procurement officers, wastewater operations managers, and biological process engineers; and secondary validation against EPA consent decree filings, state TMDL program documentation, and municipal bond prospectuses for capital improvement programs. The stakeholder set included equipment specification engineers at regional water authorities, aftermarket service directors at platform integrators, and project finance leads at infrastructure investment funds. Bottom-up equipment shipment tallies were triangulated against top-down municipal capital expenditure forecasts.
Forecast inputs encompassed regulatory enforcement velocity, replacement cycle timing for aging activated sludge infrastructure, and membrane technology adoption curves across coastal municipalities. Segmentation dimensions modeled include equipment type, technology tier, end-user category, and installation modality, with additional weighting for state-level phosphorus limit stringency. CAGRs were derived from regression analysis of historical capital deployment patterns projected across the analysis window, incorporating utility rate case filings and industrial expansion announcements as demand signals.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese membrane manufacturers or integrated European water platforms would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
Sewage Treatment Service Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Agricultural Wastewater Treatment Market
Water and Wastewater Treatment
Javelle Water Market
Water and Wastewater Treatment
Sludge Dewatering Equipment Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Global Wastewater Diffused Aerator Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Sewage Pump Market
Water and Wastewater Treatment
Aeration Pads Market