
 Environmental Testing Market | 2026-2036
Environmental Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Environmental Testing Market Analysis
Multi-source outsourcing among industrial facilities is consolidating as the dominant procurement pattern for environmental compliance programs. SGS SA leverages its global laboratory footprint to anchor large-scale contamination monitoring contracts across manufacturing corridors. Bureau Veritas competes through specialized air quality assessment capabilities tied to emission-intensive sectors. Eurofins Scientific differentiates by sustaining high-throughput chromatography workflows that reduce turnaround times for soil and water matrices.
Environmental testing encompasses the analytical measurement of pollutants, contaminants, and ecological stressors across air, water, soil, and waste media using standardized sampling protocols and instrumental methods such as gas chromatography-mass spectrometry with detection thresholds reaching parts-per-billion precision. Its primary purpose is to verify regulatory compliance, assess ecological risk, and support remediation decisions for industrial operators and government agencies. Chromatography and spectroscopy technologies command the deepest margin pools due to capital intensity and technical certification barriers, while biological testing represents the fastest-expanding category as genomic and microbiological methods penetrate site assessment protocols. Water quality testing remains the most mature application segment with stable municipal budgets, though soil analysis is gaining share around brownfield redevelopment clusters.
The EPA enforces method-specific protocols under the Clean Water Act and Safe Drinking Water Act that dictate allowable analytical techniques and reporting frequencies for permitted dischargers. ISO 17025 accreditation frameworks govern laboratory competence standards, creating market access barriers for uncertified competitors in contract bidding processes. REACH compliance obligations in Europe and state-level ambient air standards in California similarly expand testing volumes across jurisdictions. Stakeholders must monitor evolving per- and polyfluoroalkyl substances regulatory limits, as proposed threshold reductions will trigger retooling of extraction and detection methodologies across service portfolios.
Market Dynamics
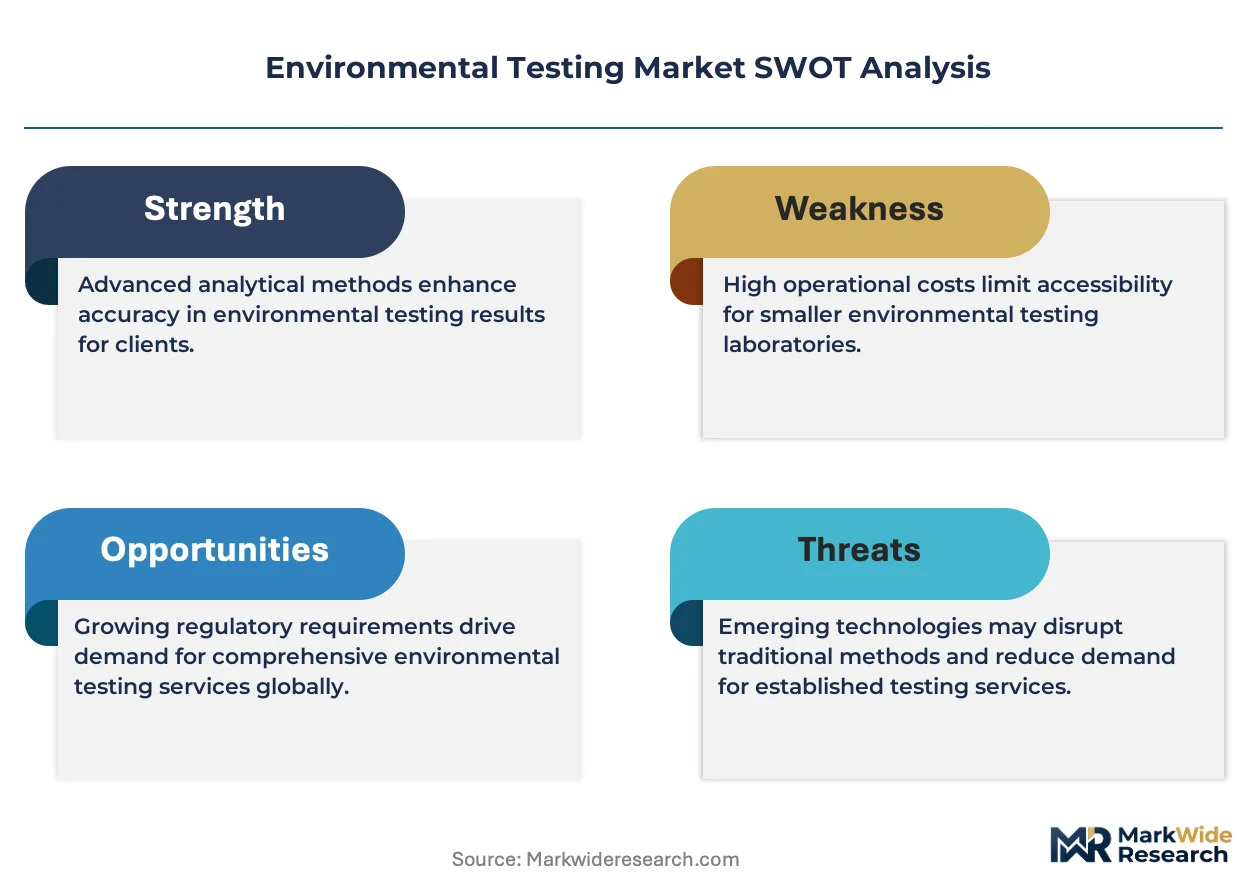
Per- and polyfluoroalkyl substances regulatory threshold reductions are forcing laboratories to retool extraction and detection methodologies, compressing margins while expanding service portfolios across contamination monitoring contracts.
Growth Catalysts
- EPA Safe Drinking Water Act amendments:Municipal utilities in the United States face tightened compliance thresholds for drinking water contaminants, accelerating capital deployment into advanced chromatography infrastructure.
- Industrial clusters around the Rhine corridor:Dense laboratory networks in Germany sustain concentrated demand for soil and water matrices testing, anchoring regional service expansion.
- ISO 17025 accreditation frameworks:Laboratory competence standards create bidding barriers for uncertified competitors, consolidating contract awards among accredited providers.
Market Restraints
- Capital intensity of chromatography equipment:Gas chromatography-mass spectrometry systems require substantial upfront investment, limiting market entry for mid-scale laboratories.
- Specialized technician scarcity:Parts-per-billion precision detection demands certified analytical chemists, constraining throughput expansion at existing facilities.
- REACH compliance complexity in Europe:Chemical substance registration obligations fragment testing protocols across member states, elevating operational coordination costs.
Strategic Opportunities
- Brownfield redevelopment clusters:Soil analysis services gain share around contaminated industrial site rehabilitation projects, particularly in post-manufacturing urban corridors.
- Genomic and microbiological methods:Biological testing penetrates site assessment protocols, opening margin expansion in ecological risk evaluation.
- California state-level ambient air standards:Emission-intensive sectors face expanding monitoring mandates, creating dedicated air quality assessment demand.
Industry Challenges
- Methodology retooling timelines:Proposed PFAS threshold reductions compress the window for laboratories to validate new extraction protocols before enforcement dates.
- Multi-jurisdiction reporting standardization:Divergent state-level ambient standards in the United States fragment quality management systems, complicating national service delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Environmental Testing Market |
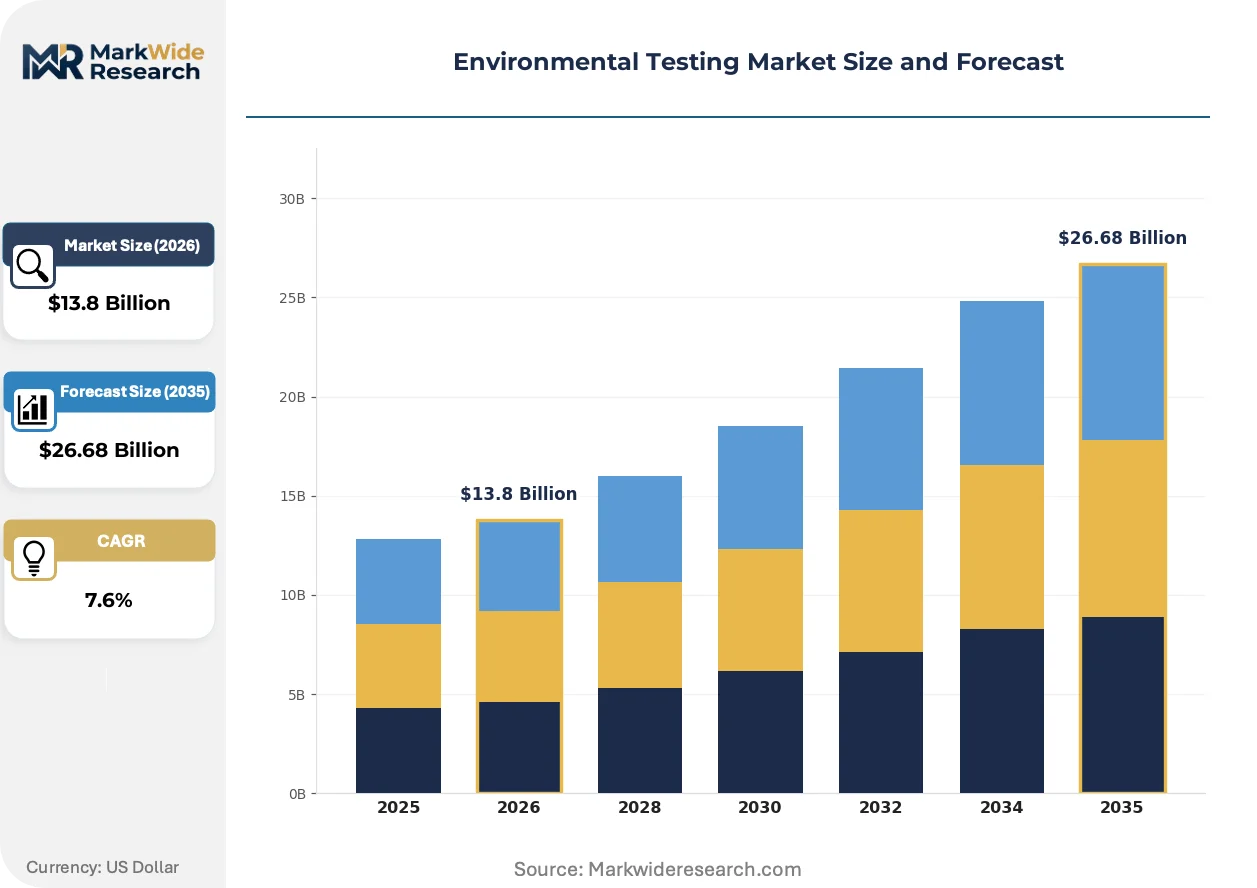
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
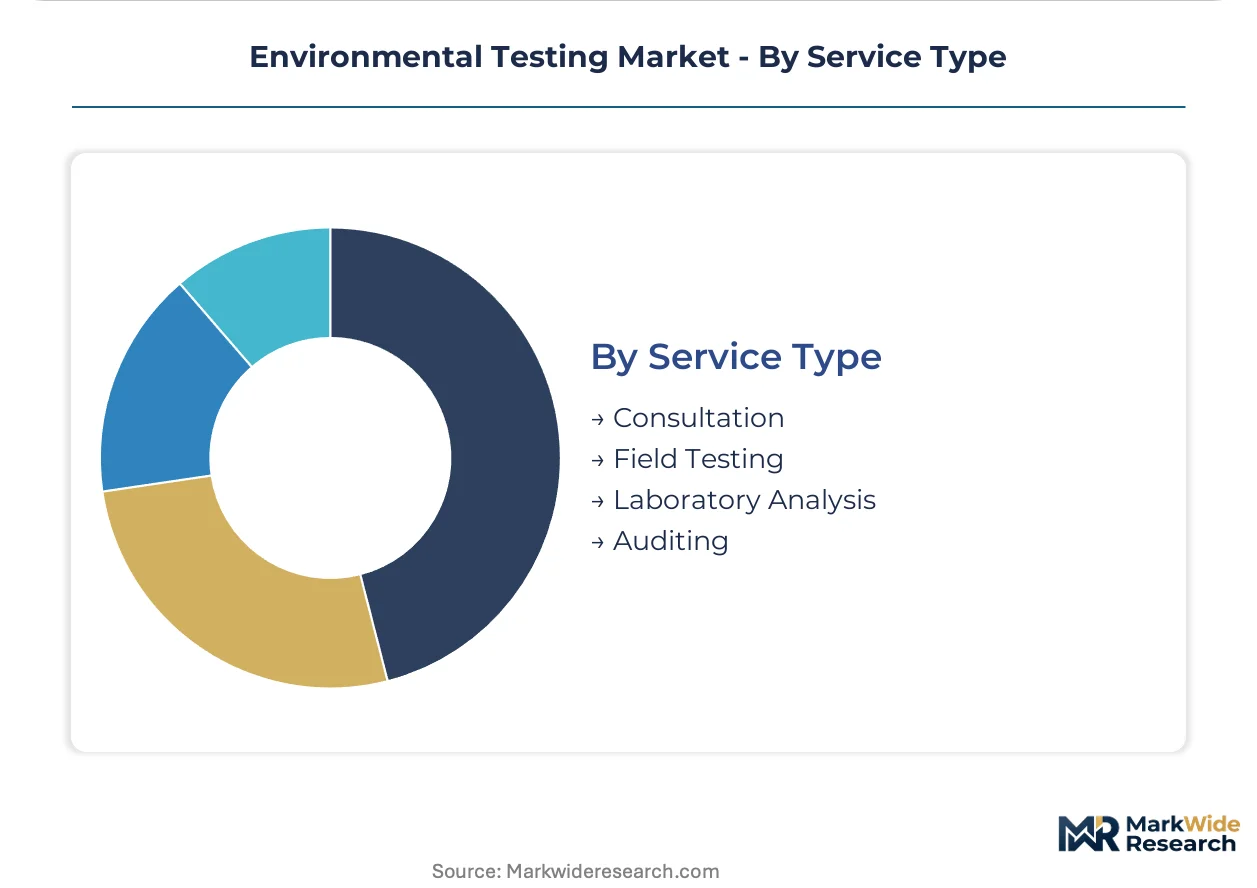
| Segmentation | Application: Water Quality Testing, Soil Analysis, Air Quality Assessment, Waste Management Technology: Chromatography, Spectroscopy, Sampling, Biological Testing Industry Vertical: Manufacturing, Agriculture, Construction, Energy Service Type: Consultation, Field Testing, Laboratory Analysis, Auditing |
| Companies Covered | SGS SA, Bureau Veritas, Eurofins Scientific, Intertek Group plc, ALS Limited, TÜV SÜD, Mérieux NutriSciences, Microbac Laboratories, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Environmental Testing Market Emerging Trajectories
Instrumentation convergence and regulatory precision requirements are compressing detection timelines while elevating technical certification barriers across environmental compliance service delivery.
High-throughput chromatography workflows are unifying sample preparation, separation, and detection stages into integrated platforms. Municipal utilities and industrial facilities with continuous discharge monitoring obligations adopt these systems to compress turnaround times for water and soil matrices. This unification is enabling laboratories to absorb higher sample volumes without proportional staffing expansion, reshaping competitive positioning around speed-to-certificate metrics.
REACH compliance obligations in Europe mandate chemical substance registration and safety assessment across industrial supply chains. The regulation's industrial consequence extends testing volumes into downstream manufacturing sectors previously exempt from environmental monitoring. Chemical producers and formulators in Germany, France, and the Netherlands face the steepest compliance cost escalation, driving consolidation of testing contracts toward full-service laboratories with cross-media capabilities.
Multi-source outsourcing among industrial facilities is consolidating into single-source environmental compliance programs. Manufacturing corridors in the United States and Germany increasingly award comprehensive contamination monitoring contracts to single providers, displacing fragmented laboratory relationships. This concentration is most visible among emission-intensive sectors—petrochemical, metals processing, and electronics manufacturing—where integrated reporting reduces regulatory audit exposure.
Environmental Testing Market Segmentation
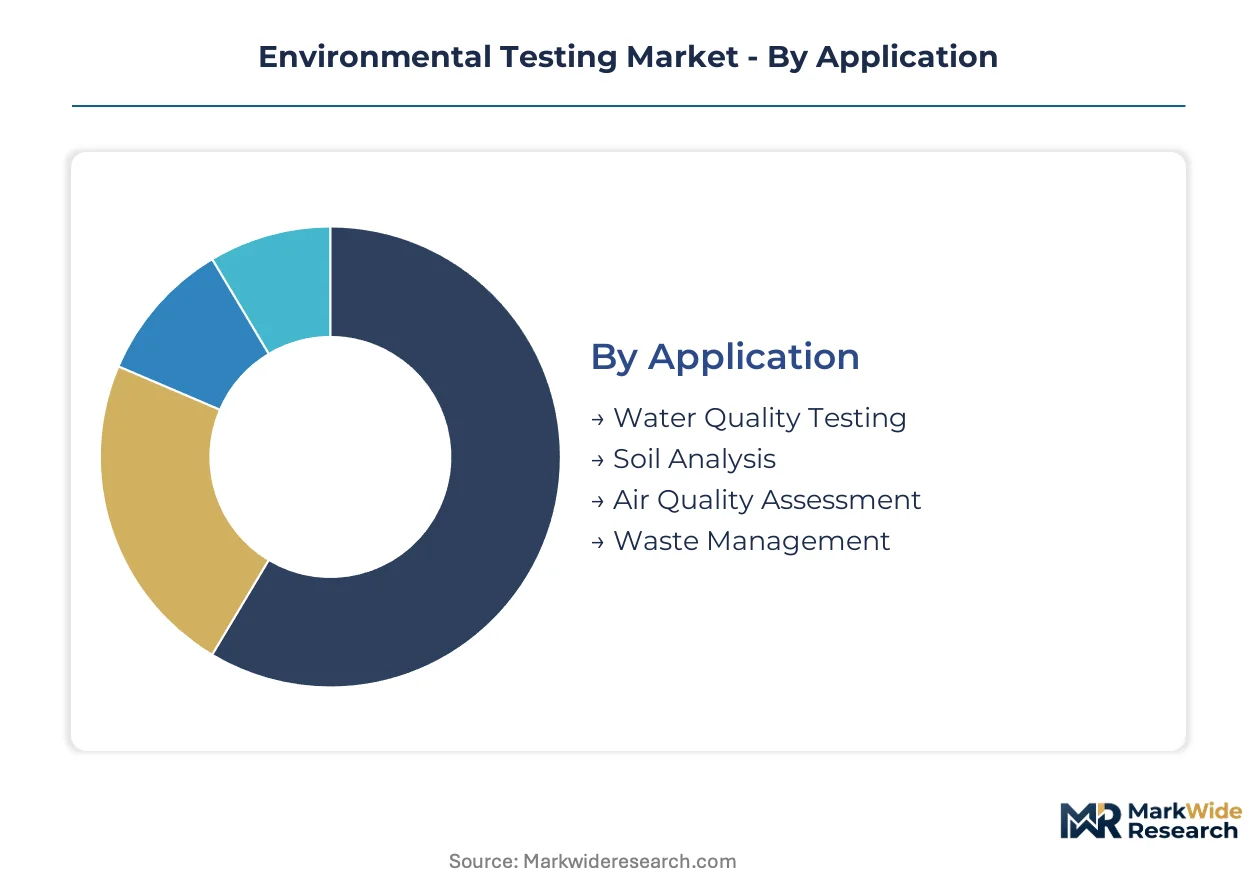
Environmental testing procurement patterns diverge sharply across application domains, technology platforms, and service delivery models. Laboratories configure specialized workflows around contaminant matrices, detection thresholds, and regulatory reporting frequencies that vary by end-use sector.
Application:
Technical specifications for sample collection, preservation, and analysis vary by contaminant matrix and regulatory jurisdiction.
- Water Quality Testing:Municipal utilities deploy automated samplers and on-site analyzers for continuous discharge monitoring under EPA Safe Drinking Water Act protocols. Germany's Rhine corridor laboratories anchor concentrated demand for surface water and groundwater matrices, driven by industrial cluster compliance obligations and dense laboratory network availability.
- Soil Analysis:Brownfield redevelopment projects in post-manufacturing urban corridors require heavy metals, petroleum hydrocarbons, and emerging contaminant screening. California's Proposition 65 enforcement and European REACH soil screening values are elevating extraction precision requirements for site assessment protocols.
- Air Quality Assessment:Stationary source emission testing uses EPA Method 5 and Method 202 protocols for particulate matter and condensable particulate.
- Waste Management:Hazardous waste characterization follows RCRA toxicity characteristic leaching procedure standards for landfill disposal decisions.
Mature deployment sits with Water Quality Testing. Newer deployment is concentrated in Soil Analysis.
Technology:
Capital intensity and certification barriers stratify competitive positioning across instrumental platforms.
- Chromatography:Gas chromatography-mass spectrometry systems achieve parts-per-billion detection thresholds for volatile organic compounds and semi-volatile organic compounds in water and soil matrices. High-throughput workflow integration is compressing turnaround times for municipal utilities with continuous monitoring obligations.
- Spectroscopy:Atomic absorption and inductively coupled plasma optical emission spectrometry deliver elemental analysis for heavy metals screening. Energy sector groundwater monitoring and mining remediation projects sustain concentrated demand for metals detection capabilities.
- Sampling:Automated composite samplers and passive diffusion devices standardize field collection protocols.
- Biological Testing:Genomic and microbiological methods penetrate ecological risk assessment protocols.
Chromatography commands the deepest margin pools due to technical certification barriers. Biological Testing is gaining share fastest as genomic methods displace traditional toxicity assays.
Industry Vertical:
Regulatory exposure and contamination liability vary by sector-specific discharge profiles.
- Manufacturing:Petrochemical, metals processing, and electronics facilities face multi-media monitoring obligations across air, water, and waste streams. Single-source outsourcing consolidation is concentrating contract awards among full-service laboratories with cross-media capabilities.
- Energy:Oil and gas operators require groundwater baseline monitoring and produced water characterization for hydraulic fracturing operations. Texas Railroad Commission and Colorado Oil and Gas Conservation Commission rules mandate pre-drill and post-drill water quality verification.
- Agriculture:Nutrient management plans and pesticide runoff monitoring drive seasonal testing demand.
- Construction:Stormwater pollution prevention plans mandate sediment and erosion control monitoring.
Manufacturing anchors the highest contract values per facility. Energy is expanding most quickly around shale development corridors.
Service Type:
Delivery model selection depends on regulatory audit exposure and internal technical capacity.
- Laboratory Analysis:ISO 17025 accredited facilities process samples under chain-of-custody protocols for defensible enforcement actions. Bureau Veritas and Eurofins Scientific compete on turnaround time and geographic coverage for manufacturing corridor clients.
- Field Testing:Mobile laboratories and portable analyzers deliver rapid screening for emergency response and remediation oversight. California Air Resources Board portable analyzer certification requirements create equipment-specific market access barriers.
- Consultation:Regulatory strategy and remediation design services attach to complex site assessments.
- Auditing:Third-party compliance verification supports corporate sustainability reporting and lender environmental due diligence.
Laboratory Analysis captures the most stable revenue streams. Field Testing is climbing the fastest around real-time monitoring mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in industrial corridors where dense manufacturing clusters intersect with stringent regulatory enforcement, creating sustained laboratory network expansion. Germany's Rhine corridor and the United States Gulf Coast sustain the deepest service penetration, while emerging shale development corridors in Canada and Australia's mining regions accelerate contract growth.
United States
Municipal utilities deploy advanced chromatography infrastructure under EPA Safe Drinking Water Act amendments tightening contaminant thresholds. The agency's method-specific protocols dictate allowable analytical techniques for permitted dischargers. California's state-level ambient air standards and Texas Railroad Commission groundwater verification rules anchor concentrated laboratory demand across the Gulf Coast and West Coast manufacturing corridors.
Germany
Industrial clusters around the Rhine corridor sustain dense laboratory networks for soil and water matrices testing. REACH compliance obligations mandate chemical substance registration across industrial supply chains. The country's national environmental regulator enforces soil screening values that elevate extraction precision requirements for brownfield redevelopment projects in the Ruhr industrial region.
Canada
Oil and gas operators require groundwater baseline monitoring under provincial conservation authority rules in Alberta and British Columbia. The country's national standards body governs laboratory accreditation frameworks creating bidding barriers for uncertified competitors. Shale development corridors in Western Canada drive seasonal contract expansion for produced water characterization and pre-drill verification protocols.
Australia
Mining remediation projects sustain concentrated demand for metals detection capabilities using atomic absorption spectrometry. The country's national therapeutic goods regulator extends jurisdiction to environmental laboratory competence standards. Queensland and Western Australia anchor service expansion around coal seam gas development and legacy mine site rehabilitation programs.
France
Chemical producers in the Lyon industrial corridor face steep REACH compliance cost escalation driving contract consolidation. The country's national medicines safety agency enforces laboratory quality standards for environmental matrices. Île-de-France and Provence-Alpes-Côte d'Azur concentrate air quality assessment demand from petrochemical facilities under EU industrial emissions directives.
Environmental Testing Market Vendor Landscape
Single-source outsourcing consolidation dominates the current landscape as manufacturing corridors displace fragmented laboratory relationships. The vendor base stratifies into three tiers: global full-service networks, regional specialists with cross-media capabilities, and single-technology boutiques. Two archetypes anchor positioning—accredited laboratories with ISO 17025 certification and high-throughput operators compressing turnaround times. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players adding biological testing and field testing capabilities to capture real-time monitoring mandates.
Within the global full-service tier, SGS SA, Bureau Veritas, and Eurofins Scientific occupy positions exemplifying divergent specialization vectors. SGS SA represents the geographic coverage archetype with laboratory footprints spanning manufacturing corridors across multiple jurisdictions. Bureau Veritas exemplifies the air quality assessment specialist position, while Eurofins Scientific anchors the high-throughput chromatography workflow segment. These Switzerland-based, France-based, and Luxembourg-based entities respectively illustrate how regulatory audit exposure and speed-to-certificate metrics reshape contract awards among emission-intensive sectors.
| Leading Market Players |
|---|
| SGS SA |
| Bureau Veritas |
| Eurofins Scientific |
| Intertek Group plc |
| ALS Limited |
| TÜV SÜD |
| Mérieux NutriSciences |
| Microbac Laboratories |
| Agilent Technologies |
| Others |
Supply Flow & Price Mechanics
Helium spot price volatility cascades through chromatography equipment manufacturing into tiered service pricing for environmental laboratories, compressing margins on high-precision detection while elevating capital recovery premiums for gas chromatography-mass spectrometry platforms.
Pricing Analysis
High-volume routine testing commands thinner margins than specialized PFAS analysis with method-development surcharges. Three-tier pricing structure across accredited reference labs, mid-tier regional networks, and unaccredited screening facilities reflects ISO 17025 certification grade and detection threshold guarantees. Pricing pressure stems from municipal utility budget constraints delaying contract renewals. Manufacturing facilities with audit exposure show least price sensitivity; small agricultural operators exhibit highest.
Supply Chain Analysis
Freight costs for liquid nitrogen and high-purity carrier gases constrain laboratory siting decisions near industrial corridors. Analytical instrument manufacturing concentrates in Germany, Japan, and the United States. Chromatography columns, certified reference standards, and mass spectrometer consumables draw from specialized chemical suppliers in Switzerland and the United Kingdom. Single-source vulnerability sits with isotopically labeled internal standards for PFAS quantification. Distribution runs through manufacturer-direct service contracts and third-party leasing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as laboratories pursue captive production of high-throughput sample preparation workflows to defend margin pools against equipment vendor pricing power.
For Market Incumbents: Cement ISO 17025 accreditation moats through multi-jurisdiction certification expansion before PFAS method deadlines tighten. Acquire field-testing capabilities to capture real-time monitoring mandates displacing laboratory analysis. Threat: genomic method startups eroding biological testing premiums. Lever: backward integration into automated sample preparation robotics. For New Entrants and Emerging Players: Mid-scale shale operators in Alberta and British Columbia present underserved demand for rapid-turnaround produced water characterization. Target brownfield redevelopment consultancies lacking in-house analytical capacity with mobile laboratory partnerships. White-space: portable air quality assessment for California wildfire response contracts. Go-to-market: equipment-lease-plus-service bundling. For Investors and Strategic Acquirers: Distressed-cycle entries favor chromatography-focused regional laboratories in Germany's Rhine corridor facing REACH compliance cost escalation. Long-term viability hinges on biological testing capability integration and PFAS method validation speed. Target archetype: accredited facilities with underutilized high-resolution mass spectrometry capacity. Signal: EPA enforcement calendar acceleration on drinking water thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Multi-Jurisdiction Accreditation | Creates bidding barriers against uncertified competitors under EPA and ECHA enforcement frameworks. |
| High-Throughput Workflow Integration | Compresses turnaround times for municipal utilities with continuous discharge monitoring obligations. |
| Biological Testing Capability Addition | Captures genomic method demand in ecological risk assessment protocols displacing traditional assays. |
| Mobile Laboratory Fleet Expansion | Addresses real-time monitoring mandates from California Air Resources Board and emergency response agencies. |
| PFAS Method Validation Investment | Secures contract positioning before proposed EPA threshold reductions trigger laboratory retooling waves. |
Methodological Framework
Multi-period observation of municipal utility capital expenditure patterns and laboratory accreditation timelines anchored the trend analysis, supplemented by interviews with environmental laboratory directors, EPA compliance officers at manufacturing facilities, chromatography equipment sales engineers, and brownfield redevelopment project managers. Secondary validation drew from EPA enforcement and compliance data, ISO 17025 accreditation registries, state-level ambient air quality monitoring disclosures, and REACH registration dossiers. Bottom-up facility-level testing volume estimates triangulated against top-down regulatory mandate projections.
Segment-weighting applied technology platform shares, application matrix volumes, and service delivery model splits across the projection horizon. Analytical frameworks modeled water quality testing, soil analysis, air quality assessment, and waste characterization as distinct demand pools with varying regulatory enforcement intensity. CAGRs derived from facility expansion timelines, equipment replacement cycles, and emerging contaminant method adoption curves. Forecast inputs incorporated PFAS regulatory threshold proposal trajectories and shale development corridor drilling permit velocities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA rulemaking delays, helium supply disruptions affecting chromatography operations, and genomic method standardization timelines. Forecasts reflect documented assumptions about regulatory enforcement intensity and capital availability for municipal infrastructure. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Indoor Air Quality Service Market
Environmental Monitoring
Real-Time Flood Monitoring and Warning System Market
Environmental Monitoring
Industrial Site Carbon Footprint Verification and Metering Test Equipment Market
Environmental Monitoring
Global Environmental Sensor Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Water Testing Market
Environmental Monitoring
Food Security Technology Market
Environmental Monitoring
Global Water Quality Monitoring Market
Environmental Monitoring
Emission Monitoring Systems Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Testing, Inspection, and Certification for Natural Resources Market