
 Sewage Pump Market | 2026-2036
Sewage Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Sewage Pump Market Outlook
EPA effluent limitation guidelines is broadening the cost-of-entry calculus for sewage pump manufacturers serving North American municipal contracts. Xylem leverages its vertical integration across pump design and digital monitoring platforms to sustain pricing power in specification-driven bids. Sulzer anchors its position through specialized wear-resistant metallurgy for abrasive wastewater streams. Grundfos competes on intelligent variable-frequency drive integration that cuts energy draw in continuous-duty installations.
A sewage pump is a centrifugal or positive-displacement machine engineered to transport wastewater and solids-laden effluent through pressurized piping networks, typically constructed from cast iron or stainless steel housings with vortex or channel impeller geometries capable of passing spherical solids up to three inches in diameter. Its primary purpose is to maintain hydraulic head in sewer collection systems, lift stations, and treatment plant influent channels where gravity flow proves insufficient. Submersible pumps command the largest installed base due to flood-proof motor encapsulation and reduced civil works, while grinder pumps capture faster growth as decentralized low-pressure sewer systems penetrate exurban residential developments. Electric technology dominates current shipments, though solar-powered units are gaining traction in off-grid municipal extensions across arid zones.
The EPA enforces Clean Water Act discharge standards that mandate specific pump reliability thresholds to prevent bypass events, while the EU Urban Wastewater Treatment Directive sets secondary treatment requirements that drive lift station redundancy investments across member states. ISO 9906 hydraulic performance testing protocols further shape procurement specifications by standardizing efficiency measurement methods that filter non-compliant vendors from public tenders. Stakeholders must monitor how emerging per- and polyfluoroalkyl substances remediation rules will force retrofit cycles in legacy pump stations where sealing materials face replacement mandates.
Market Dynamics
Centralized wastewater infrastructure buildouts in developing urban corridors are compressing procurement cycles for submersible and grinder pump systems, while tightening effluent discharge standards under the EPA and EU Urban Wastewater Treatment Directive force equipment upgrade mandates across legacy installations.
Growth Catalysts
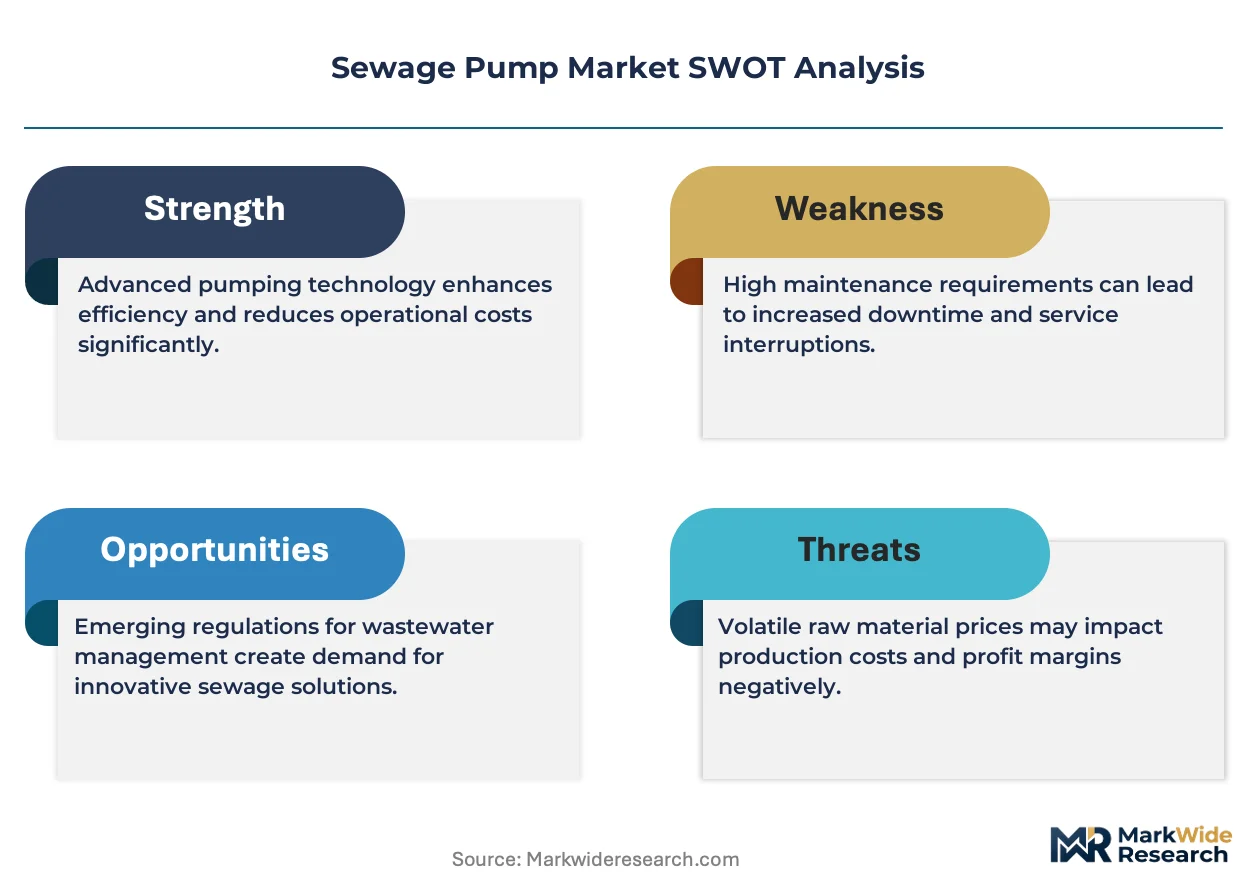
- EPA effluent limitation guidelines:Municipalities across the United States face binding reliability thresholds that prevent bypass events, compelling lift station redundancy investments and pump replacement cycles.
- Submersible motor encapsulation technology:Flood-proof designs reduce civil works requirements and installation footprints, accelerating adoption in flood-prone metropolitan zones.
- Southeast Asian sewer network expansion:Metropolitan authorities in Vietnam, Indonesia, and the Philippines accelerate procurement as centralized collection system coverage remains below saturation thresholds.
Market Restraints
- Cast iron and stainless steel input volatility:Foundry-grade metal price swings compress margin stability for housing and impeller manufacturers dependent on commodity supply chains.
- Specialized wear-resistant metallurgy concentration:Premium alloy supply for abrasive wastewater applications concentrates among limited European and Japanese specialty foundries.
- Grinder pump technical limitation in high-head applications:Cutter mechanism wear rates restrict deployment in deep lift stations exceeding 25-meter static heads.
Strategic Opportunities
- Indian metropolitan procurement acceleration:Smart Cities Mission funding channels municipal capital toward sewer network densification in Bangalore, Hyderabad, and Pune corridors.
- Solar-electric technology convergence:Photovoltaic array integration with DC motor drives opens off-grid municipal extensions in arid zones lacking grid infrastructure.
- EU Green Deal regulatory tailwind:Energy efficiency mandates for water infrastructure create specification preference for intelligent variable-frequency drive integration.
Industry Challenges
- Hydraulic performance certification timeline:ISO 9906 testing protocol compliance extends vendor qualification periods for public tender participation.
- Per- and polyfluoroalkyl substances sealing material retrofit:Emerging remediation rules force unscheduled replacement cycles in legacy pump stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sewage Pump Market |
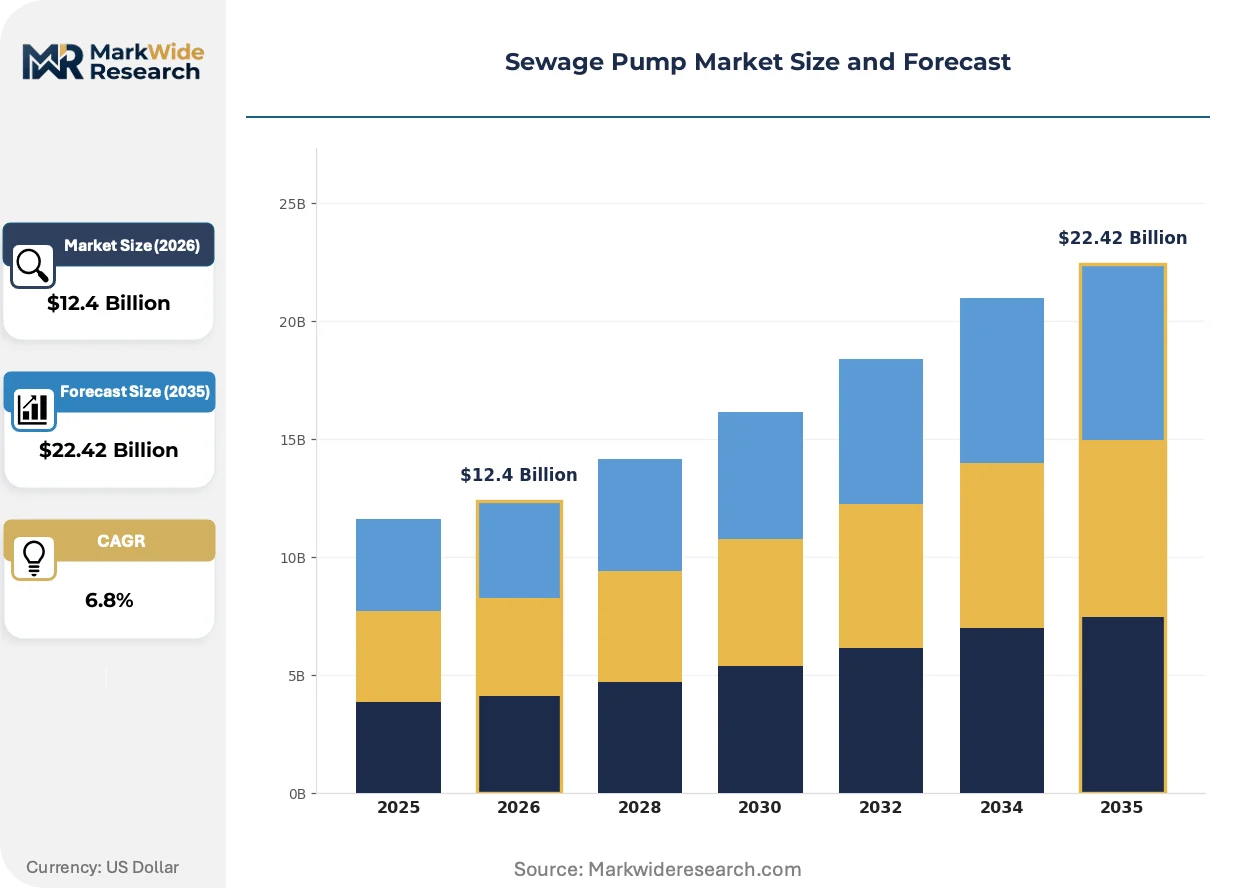
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Non-clogging Pumps, Grinder Pumps, Diaphragm Pumps Application: Municipal Wastewater, Industrial Wastewater, Residential Sewage, Commercial Use End User: Construction Companies, Municipalities, Industrial Facilities, Homeowners Technology: Hydraulic Technology, Electric Technology, Solar Technology, Pneumatic Technology |
| Companies Covered | Xylem, Sulzer, Grundfos, Ebara Corporation, KSB, Pentair, Crane Pumps & Systems, Franklin Electric, Wilo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sewage Pump Market Strategic Shifts
Digital monitoring platforms and intelligent drive systems are compressing the operational cost structure of continuous-duty installations, while regulatory pressure on energy efficiency and sealing material safety accelerates hardware refresh cycles.
Intelligent variable-frequency drive integration is electrifying sewage pump operational profiles by modulating motor speed against real-time hydraulic demand. Municipal operators in Germany and the Netherlands deploy these systems to shave peak energy draw during diurnal flow variation. The technology is electrifying competitive positioning around total cost-of-ownership rather than upfront capital expenditure.
The EU Urban Wastewater Treatment Directive's secondary treatment requirements are mandating lift station redundancy investments across member states. Treatment plant operators in Poland and Romania face compliance deadlines that compress procurement timelines for backup pump configurations. Submersible duplex installations capture preference as flood-proof alternatives to dry-pit configurations in these retrofit markets.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance bundling as municipal buyers separate capital and operating budgets. Independent service contractors in Australia's urban water utilities now capture preventive maintenance contracts previously held by original equipment manufacturers. This pattern concentrates most visibly in metropolitan zones with mature asset management frameworks and digitized maintenance record systems.
Sewage Pump Market Segmentation
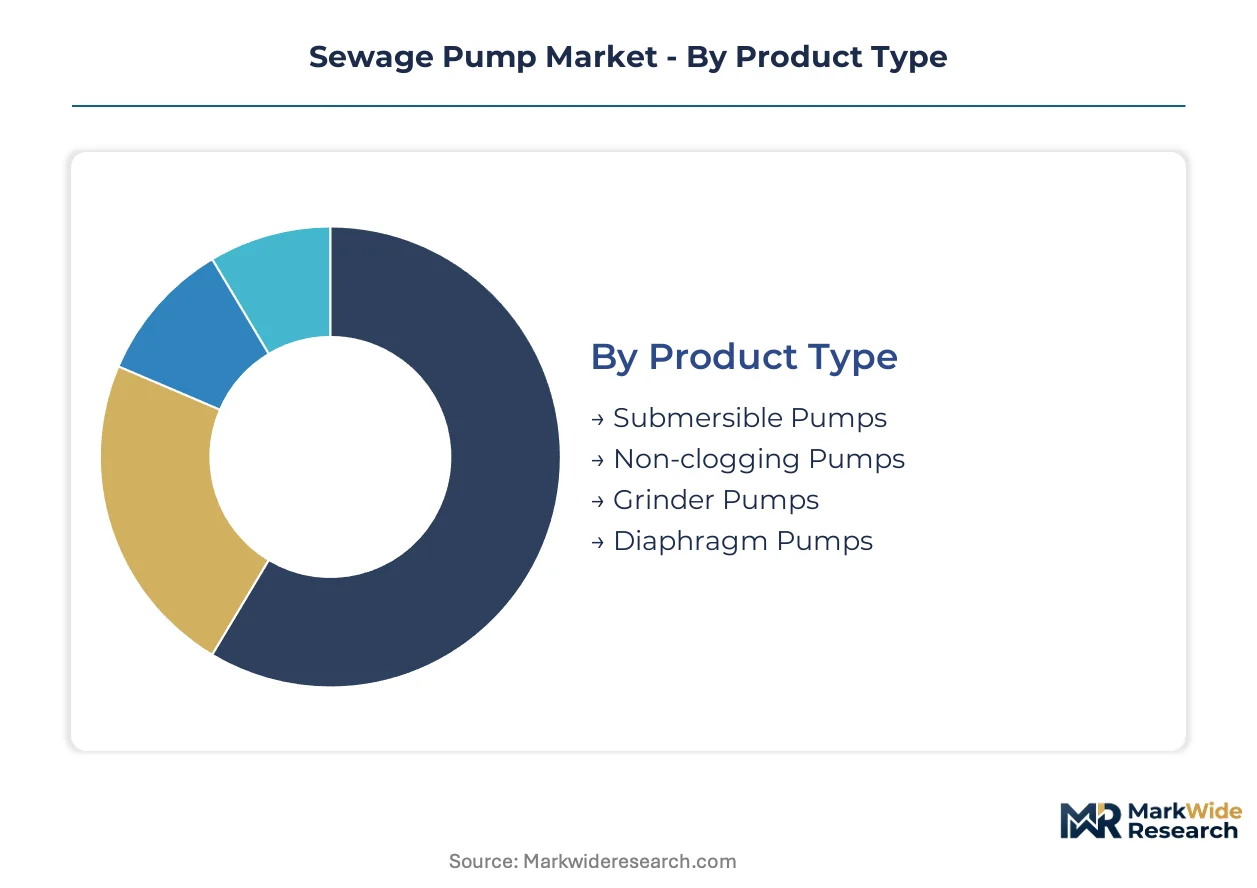
Sewage pump procurement patterns diverge sharply between capital-intensive municipal infrastructure and fragmented residential replacement cycles. Understanding where volume concentrates versus where premium pricing holds determines supplier resource allocation and R&D prioritization across product architectures.
Product Type:
Submersible pumps dominate unit shipments through flood-proof motor encapsulation that eliminates dry-pit civil works, while grinder pumps command margin premiums in decentralized low-pressure sewer extensions where terrain prevents gravity collection.
- Submersible Pumps:Flood-proof motor encapsulation within cast iron or stainless steel housings enables direct immersion in wet wells and lift stations. Municipal procurement in Vietnam, Indonesia, and the Philippines concentrates here as centralized collection systems expand into flood-prone metropolitan zones with limited dry-pit construction capacity.
- Grinder Pumps:Cutter mechanisms macerate solids before pumping through small-diameter pressure sewers, enabling decentralized service in exurban residential developments where gravity infrastructure proves cost-prohibitive. Demand concentrates in American and Australian low-density housing corridors where terrain fragmentation prevents conventional sewer extension.
- Non-clogging Pumps:Vortex or channel impeller geometries pass spherical solids up to three inches without obstruction, serving high-solids industrial effluent and raw sewage applications where reliability thresholds override energy efficiency considerations.
- Diaphragm Pumps:Positive-displacement action handles viscous sludge and abrasive grit in specialized dewatering and septage transfer operations where centrifugal designs face rapid wear.
Mature deployment sits with submersible pumps across established municipal networks. Newer deployment is concentrated in grinder pumps as decentralized infrastructure penetrates previously unserved exurban territories.
Application:
Municipal contracts anchor revenue stability through multi-year capital programs, while industrial wastewater applications drive specification complexity around corrosive effluent and variable solids loading.
- Municipal Wastewater:Centralized collection systems and treatment plant influent channels require continuous-duty pumps with redundant configurations mandated by EPA and EU discharge regulations. Procurement cycles in India and Southeast Asia accelerate as Smart Cities Mission funding channels capital toward sewer network densification.
- Industrial Wastewater:Manufacturing effluent with chemical loading, temperature extremes, and abrasive solids demands specialized metallurgy and sealing systems. Food processing and pulp mill operators in Germany and the Netherlands specify intelligent variable-frequency drives to modulate energy draw against diurnal flow variation.
- Residential Sewage:Basement sump systems and septic tank effluent pumps serve individual dwellings through retail and contractor channels, with replacement cycles driven by failure events rather than planned maintenance.
- Commercial Use:Hotels, hospitals, and retail complexes require mid-scale lift stations with duplex redundancy to prevent service disruption, typically procured through mechanical contractors rather than direct municipal tender.
Specification complexity peaks in industrial wastewater where abrasive and corrosive effluent demands customized metallurgy. Volume scale concentrates in municipal wastewater where standardization enables manufacturing economies.
End User:
Capital allocation authority separates this dimension: municipalities deploy multi-year infrastructure budgets while homeowners react to emergency failures through spot purchases.
- Municipalities:Public works departments specify ISO 9906-certified pumps through competitive tender processes where life-cycle cost analysis overrides upfront capital minimization. Indian metropolitan authorities in Bangalore, Hyderabad, and Pune corridors accelerate procurement as centralized coverage targets tighten.
- Construction Companies:Project-based procurement for greenfield residential and commercial developments favors standardized submersible packages with rapid availability and simplified installation protocols.
- Industrial Facilities:In-house engineering teams specify customized configurations with process-integrated controls, often maintaining captive spare inventories to prevent production downtime.
- Homeowners:Emergency replacement of failed basement sump or septic effluent pumps drives retail channel purchases, with selection criteria dominated by immediate availability and contractor recommendation rather than technical specification.
Procurement sophistication concentrates with municipalities and industrial facilities where total cost-of-ownership frameworks govern selection. Price sensitivity dominates homeowner purchases where emergency replacement timelines compress evaluation periods.
Technology:
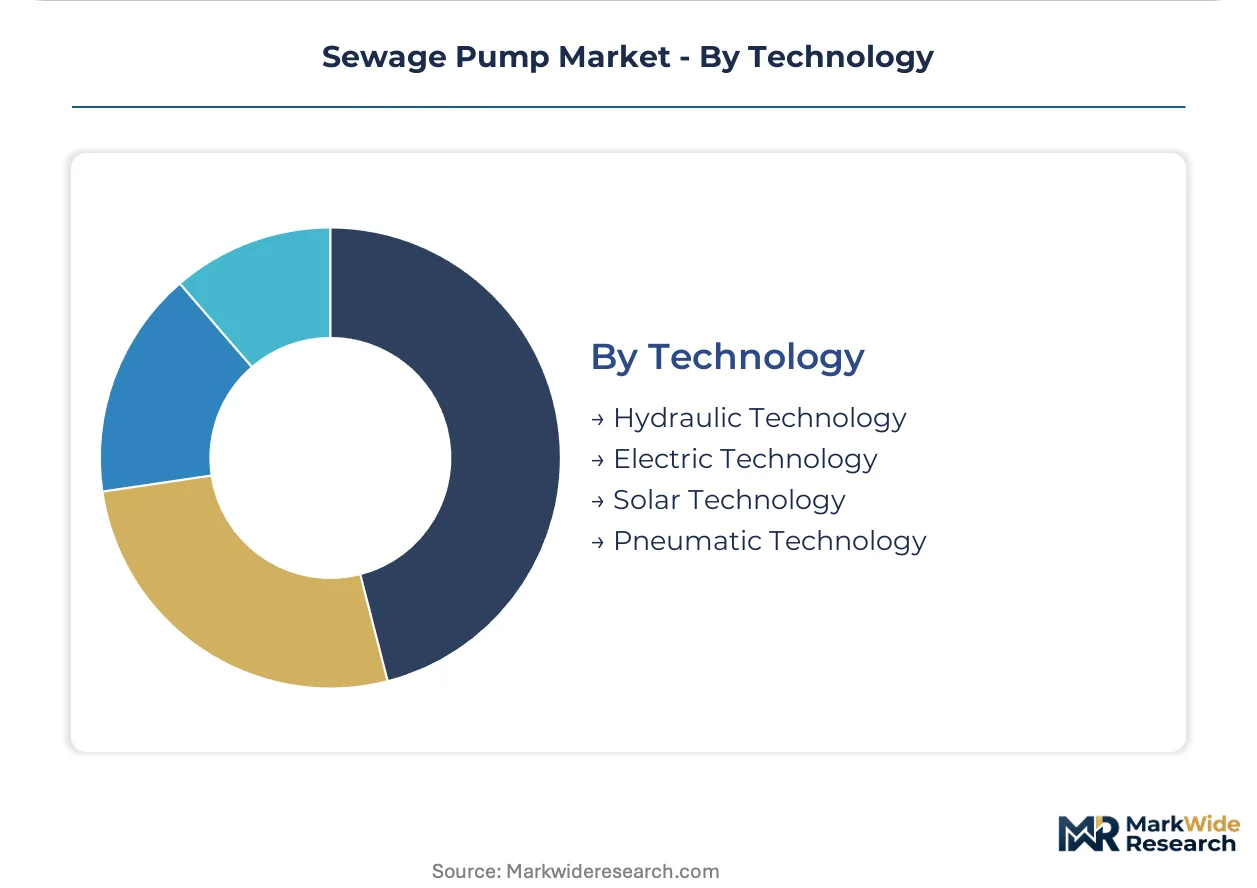
Electric motor drives retain overwhelming share through grid reliability and power density, though solar-electric convergence opens off-grid applications in arid zones lacking distribution infrastructure.
- Electric Technology:AC induction and permanent magnet motors deliver continuous-duty reliability with established maintenance protocols. German and Dutch municipal operators deploy intelligent variable-frequency drive integration to satisfy EU Green Deal energy efficiency mandates for water infrastructure.
- Solar Technology:Photovoltaic array integration with DC motor drives enables municipal sewer extensions in Australian and Middle Eastern arid zones where grid infrastructure remains uneconomic for low-density settlement patterns.
- Hydraulic Technology:Fluid power drives serve explosion-risk environments and submerged applications where electrical isolation proves critical, maintaining niche presence in petrochemical and mining effluent handling.
- Pneumatic Technology:Compressed air-driven diaphragm and piston pumps handle viscous sludge in temporary dewatering and confined-space applications where electrical supply is restricted or hazardous.
Installed base concentration remains with electric technology across established municipal networks. Steepest expansion trajectory belongs to solar technology as off-grid infrastructure extends into previously unserved settlement corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and Indonesia accelerate wastewater infrastructure procurement as manufacturing relocation concentrates effluent treatment demand. These zones offer tax holidays and import duty exemptions that compress capital recovery timelines for municipal pump installations.
United States
Municipalities in Florida and Louisiana accelerate submersible pump procurement as coastal flood resilience programs expand lift station networks. EPA effluent limitation guidelines mandate backup pump configurations that prevent bypass events during storm surges. Houston-Galveston corridor utilities deploy redundant installations as Hurricane Harvey reconstruction funds channel toward hardened wastewater infrastructure.
Germany
Ruhr Valley industrial cities retrofit aging combined sewer systems with intelligent variable-frequency drive pumps to satisfy EU Green Deal energy efficiency mandates. The EU Urban Wastewater Treatment Directive's secondary treatment requirements compress procurement timelines for treatment plant upgrades. Bavarian municipalities in Munich and Nuremberg metropolitan zones specify ISO 9906-certified duplex configurations for compliance-driven replacement cycles.
India
Smart Cities Mission funding channels municipal capital toward sewer network densification in Bangalore, Hyderabad, and Pune corridors. Central Public Health and Environmental Engineering Organisation standards mandate specific reliability thresholds for urban wastewater collection systems. Maharashtra state utilities in Mumbai-Thane metropolitan region accelerate grinder pump procurement as low-pressure sewer systems extend into informal settlement zones lacking gravity infrastructure.
Vietnam
Ho Chi Minh City and Hanoi metropolitan authorities expand centralized collection systems as urban population density exceeds gravity sewer coverage capacity. Ministry of Construction technical standards for urban drainage infrastructure mandate specific pump performance specifications in public tenders. Da Nang and Can Tho secondary cities concentrate procurement activity as provincial capital programs channel central government funding toward wastewater treatment plant construction.
Australia
Perth and Adelaide utilities deploy solar-electric pump systems as off-grid municipal extensions reach arid zone settlements lacking distribution infrastructure. National Water Initiative framework agreements prioritize energy-efficient water infrastructure investments across state water utilities. Queensland regional councils in Townsville and Cairns corridors specify flood-proof submersible installations as cyclone resilience programs expand lift station redundancy.
Sewage Pump Market Competitive Environment
European producers anchor specification-driven premium tiers; Asian fabricators hold volume-scale positions in emerging market procurement. The vendor base stratifies across three functional tiers: integrated pump-and-digital-platform suppliers, specialized wear-resistant metallurgy foundries, and regional assembly operations serving price-sensitive municipal tenders. Consolidation pressure intensifies as intelligent drive integration raises R&D thresholds. Dominant competitive moves include backward integration into foundry operations and technology licensing agreements for variable-frequency control systems.
Within the integrated systems tier, Xylem and Grundfos exemplify archetypes combining pump manufacturing with digital monitoring platform development. Sulzer occupies a position among specialized metallurgy-focused suppliers serving abrasive wastewater applications. These three entities represent contrasting strategic postures: specification-driven bidding power through vertical control, energy efficiency positioning through intelligent drive integration, and material science differentiation for high-wear industrial effluent handling.
| Leading Market Players |
|---|
| Xylem |
| Sulzer |
| Grundfos |
| Ebara Corporation |
| KSB |
| Pentair |
| Crane Pumps & Systems |
| Franklin Electric |
| Wilo |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap foundries in Italy and Japan anchor premium-tier supply for wear-resistant pump components, translating metallurgical specialization into pricing discipline that resists commoditization pressure from Asian volume producers.
Pricing Analysis
Short lead-time premiums of 15-25% apply to ISO 9906-certified submersible pumps held in regional distribution inventory, while spot-market cast iron housings trade at discounts to contract offtake agreements. Three-tier pricing structure across premium, standard, and economy levels separates European metallurgy specialists from Asian fabricators and local assembly operations. Pricing pressure stems from foundry-grade stainless steel input volatility compressing margins at the standard tier. Municipal procurement teams exhibit lowest price sensitivity due to life-cycle cost frameworks, while construction contractors in greenfield residential developments drive hardest bargain negotiations.
Supply Chain Analysis
Regional distribution centers in Germany, Singapore, and Texas maintain hub-and-spoke patterns that position finished pumps within 48-hour delivery windows of municipal tender sites. Manufacturing concentration rests on China for cast iron housings, Germany for precision-machined impellers, and Japan for specialized wear-resistant alloys. Raw material dependencies draw from Brazilian iron ore, Indonesian nickel, and South African chromium. Single-source vulnerability concentrates in European specialty foundries supplying abrasive-wastewater metallurgy. Distribution runs through authorized dealer networks for municipal specifications and direct-to-contractor channels for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA effluent limitation guidelines and EU Urban Wastewater Treatment Directive compliance costs erect barrier-to-entry moats that protect incumbent positions while forcing sub-scale competitors toward exit or acquisition.
For Market Incumbents: Acquire captive foundry capacity in wear-resistant alloy production to secure margin control against Japanese and European specialty supplier concentration. Defensive consolidation should prioritize digital monitoring platform capabilities as intelligent variable-frequency drive integration raises R&D thresholds beyond mid-tier engineering capacity. Threat of solar-electric technology convergence in Australian and Middle Eastern arid zones demands pre-emptive DC motor drive development investment. For New Entrants and Emerging Players: Intelligent drive system software offers the clearest technology-first wedge for penetrating specification-driven municipal procurement in India and Vietnam where energy efficiency mandates create evaluation criteria openness. White-space targets concentrate in grinder pump aftermarket service contracts previously held by original equipment manufacturers, particularly in Australian urban water utilities with digitized maintenance frameworks. Go-to-market positioning should emphasize total cost-of-ownership analytics against upfront capital minimization procurement bias. For Investors and Strategic Acquirers: Distressed-cycle entries favor sub-scale European metallurgy specialists with ISO 9906 certification assets in Poland and Romania facing EU compliance deadline pressure. Long-term viability across the analysis window hinges on backward integration into foundry operations or technology licensing agreements for variable-frequency control systems. Signal to watch is municipal procurement unbundling separating capital and operating budgets, which accelerates independent service contractor capture of preventive maintenance revenue streams.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive supply of wear-resistant alloys insulates margin from Japanese specialty supplier pricing power. |
| Intelligent Drive System Development | Variable-frequency integration satisfies EU Green Deal energy efficiency mandates in German municipal tenders. |
| Digital Monitoring Platform Launch | Real-time pump performance data captures aftermarket service contracts from incumbent OEMs in Australian utilities. |
| Solar-Electric Product Line Extension | Photovoltaic DC motor drives open off-grid procurement in Perth and Adelaide arid zone extensions. |
| ISO 9906 Certification Investment | Hydraulic performance testing compliance qualifies vendors for Indian Smart Cities Mission public tenders. |
Study Parameters
Document review covered EPA enforcement actions, EU Urban Wastewater Treatment Directive implementation reports, and ISO 9906 testing protocol documentation, complemented by interviews with municipal public works directors, wastewater treatment plant operators, pump OEM procurement managers, and aftermarket service contractors. Secondary validation drew from customs trade data for cast iron and stainless steel pump component flows, SEC filings of publicly traded pump manufacturers, and tender databases from Indian Smart Cities Mission and Vietnamese Ministry of Construction. Bottom-up unit shipment estimates triangulated against top-down infrastructure investment forecasts.
Segment-level projections across product type, application, end user, and technology dimensions were generated through installed base analysis and replacement cycle modeling over the projection horizon. CAGRs were derived from regression against municipal capital expenditure trends and regulatory compliance deadline clustering. Industry-specific inputs incorporated foundry capacity utilization rates, effluent discharge standard tightening schedules, and solar-electric technology cost curves for arid zone off-grid applications.
Several conditions sit outside the modeled scope, including potential per- and polyfluoroalkyl substances sealing material bans forcing unscheduled retrofit cycles, and geopolitical disruption to Brazilian iron ore or Indonesian nickel supply corridors. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and commodity price band stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Global Wastewater Treatment Services Market
Water and Wastewater Treatment
Commercial Atmospheric Water Generator Market
Water and Wastewater Treatment
Water Aeration System Market
Water and Wastewater Treatment
Wastewater Clarifier Market
Water and Wastewater Treatment
Javelle Water Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Sludge Dewatering Equipment Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Global Wastewater Diffused Aerator Market
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
Borehole Yield Testing Market