
 Water Aeration System Market | 2026-2036
Water Aeration System Market Size, Share, and Industry Trends Forecast 2026-2036
Water Aeration System Market Analytics
ISO 14001 environmental management certification is collapsing as a baseline qualifier for municipal tender participation across major water infrastructure markets. Sulzer leverages its integrated pump-and-aeration platform to anchor European utility contracts with combined mechanical reliability guarantees. Xylem competes through digital service overlays that extend equipment life cycles and reduce unplanned downtime in North American treatment networks. Otterbine specializes in surface aeration for aesthetic water bodies, occupying a niche where oxygen transfer rates matter less than visual footprint and noise control.
Water aeration systems are engineered assemblies of blowers, diffusers, impellers, or jet nozzles that force atmospheric oxygen into aqueous environments, typically achieving standard oxygen transfer efficiencies between 1.5 and 7.0 kilograms oxygen per kilowatt-hour depending on bubble size and basin depth. These systems serve the primary industrial purpose of maintaining aerobic biological activity in wastewater treatment basins, aquaculture ponds, and impaired water bodies where dissolved oxygen must sustain microbial populations or aquatic species. Diffused aeration dominates municipal installations where fine-pore membrane diffusers deliver superior oxygen transfer efficiency in deep oxidation ditches, while surface aeration retains share in industrial lagoons with shallow profiles and high solids loading. Membrane technology represents the fastest-growing technology segment as submerged hollow-fiber modules combine aeration with solids separation in compact MBR plants serving space-constrained urban sites.
EPA effluent limitation guidelines under the Clean Water Act mandate minimum dissolved oxygen levels in treated wastewater discharges, directly shaping blower sizing and diffuser specification for US municipal contractors. The EU Urban Wastewater Treatment Directive, enforced by national regulators in Germany, France, and the Netherlands, drives replacement cycles toward energy-optimized fine-bubble systems through binding energy-efficiency benchmarks for large treatment works. China's MEE enforces GB 18918 discharge standards that tighten ammonia and total nitrogen limits, forcing industrial park treatment plants to upgrade aeration capacity and control systems. Stakeholders must monitor how tightening energy-efficiency regulations in multiple jurisdictions reshape total-cost-of-ownership calculations and shift procurement criteria from capital expenditure minimization toward lifecycle performance guarantees.
Market Dynamics
Fine-bubble diffused aeration technology is displacing mechanical surface aerators across energy-intensive municipal treatment plants, driven by binding energy-efficiency benchmarks and lifecycle cost guarantees that favor oxygen transfer efficiency over capital expenditure minimization.
Growth Catalysts
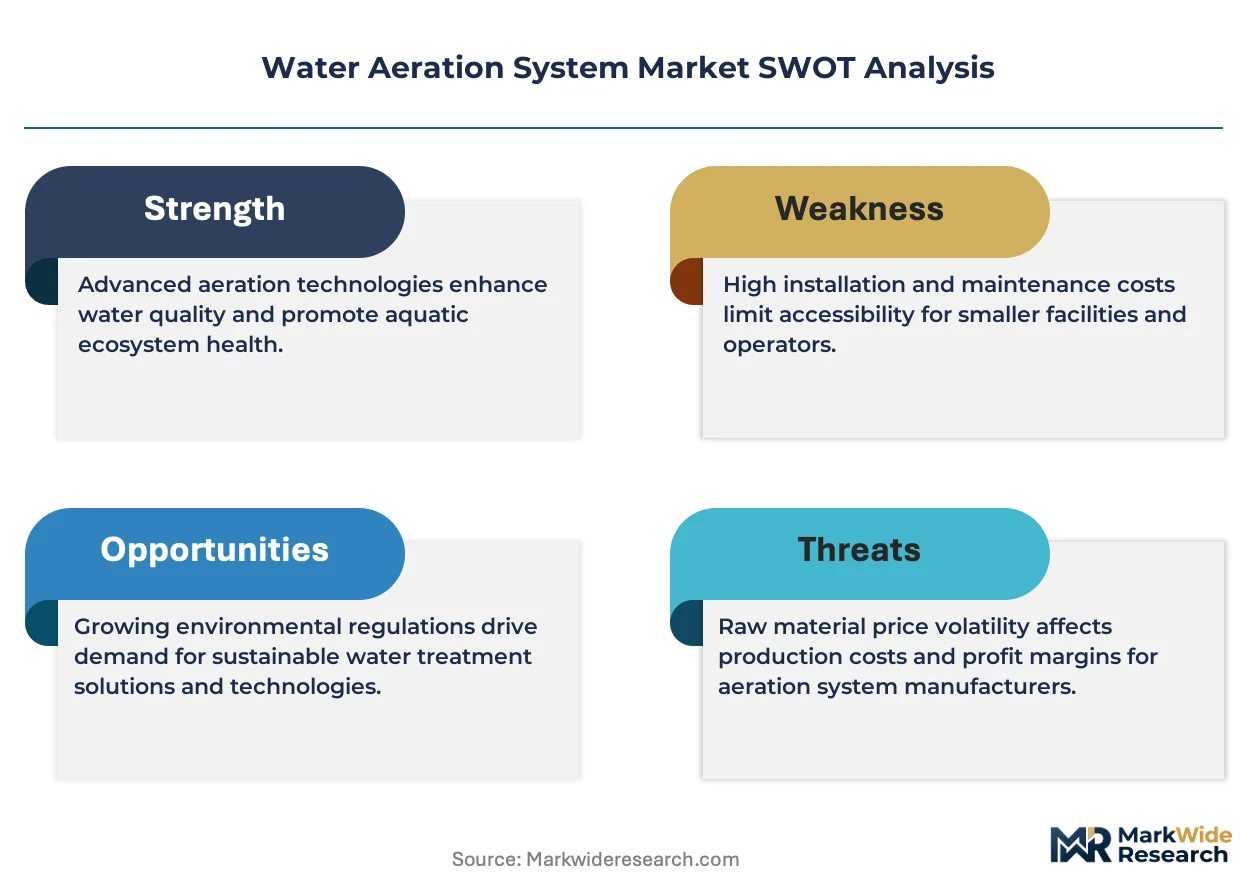
- EU Urban Wastewater Treatment Directive:Binding energy-efficiency benchmarks for large treatment works in Germany, France, and the Netherlands force replacement cycles toward optimized fine-bubble systems.
- Coastal Chinese industrial clusters:Provincial environmental protection bureaus in Jiangsu and Zhejiang enforce stricter dissolved oxygen standards for marine outfalls, compelling aeration capacity expansions.
- Membrane bioreactor (MBR) technology:Submerged hollow-fiber modules combining aeration with solids separation gain share in space-constrained urban treatment sites.
Market Restraints
- Specialized polymer supply concentration:Fine-pore membrane diffusers depend on fluoropolymer feedstocks concentrated among Japanese and German chemical suppliers.
- High-solids loading incompatibility:Membrane diffusers face fouling limitations in industrial lagoons with elevated suspended solids, preserving mechanical aerator demand.
- Extended EPA permitting timelines:National Pollutant Discharge Elimination System permit modifications delay aeration upgrade timelines for US municipal utilities.
Strategic Opportunities
- India's industrial park wastewater sector:Central Pollution Control Board enforcement of stricter effluent norms creates first-mover openings for energy-efficient diffused aeration.
- Digital service overlay convergence:Equipment manufacturers combining blowers with predictive maintenance analytics capture recurring revenue streams.
- Aquaculture intensification:Recirculating aquaculture systems in Norway and Chile require precision aeration for high-density salmon production.
Industry Challenges
- ISO 14001 certification collapse:Environmental management certification no longer suffices as a tender qualifier, forcing suppliers to demonstrate operational performance data.
- Legacy mechanical aerator integration:Diffuser retrofits into existing oxidation ditches require basin drainage and concrete modifications that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Aeration System Market |
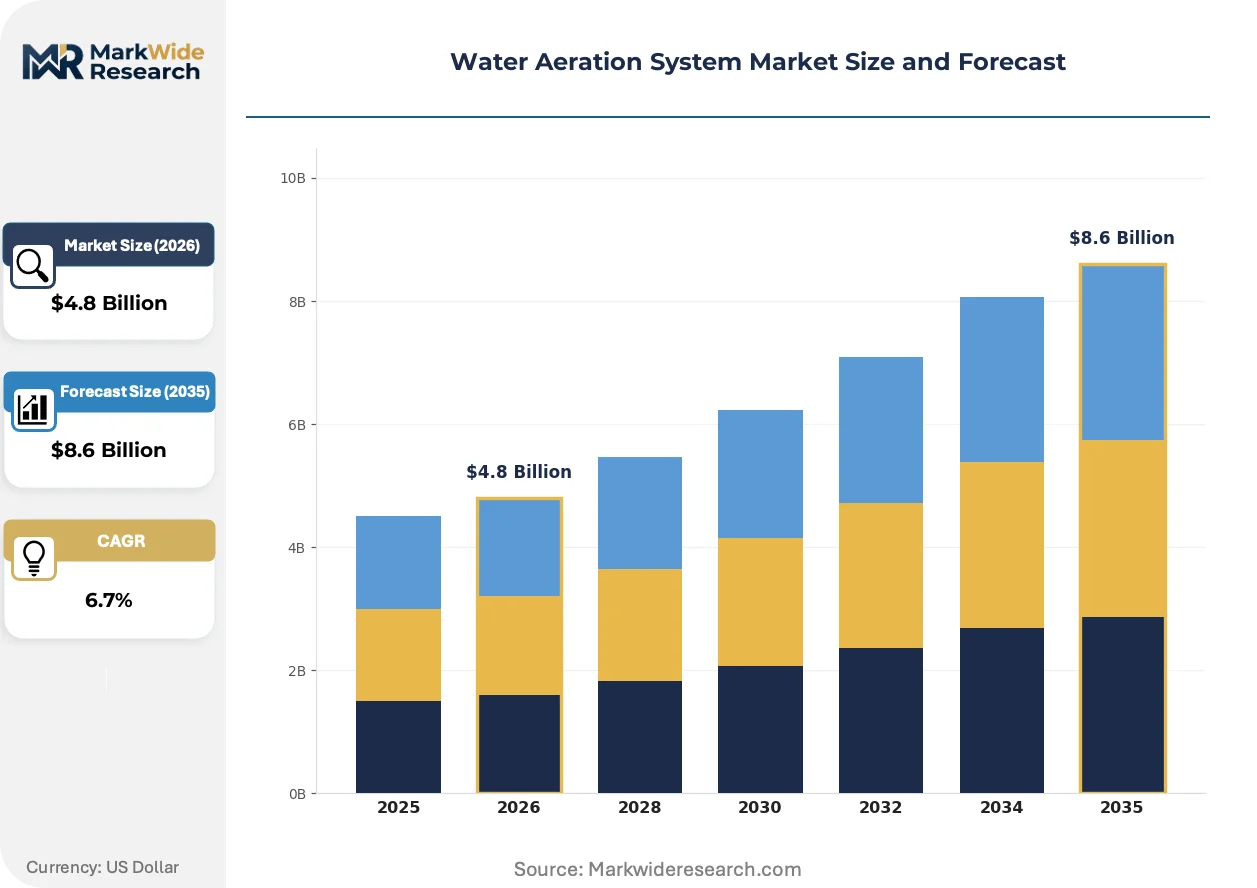
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
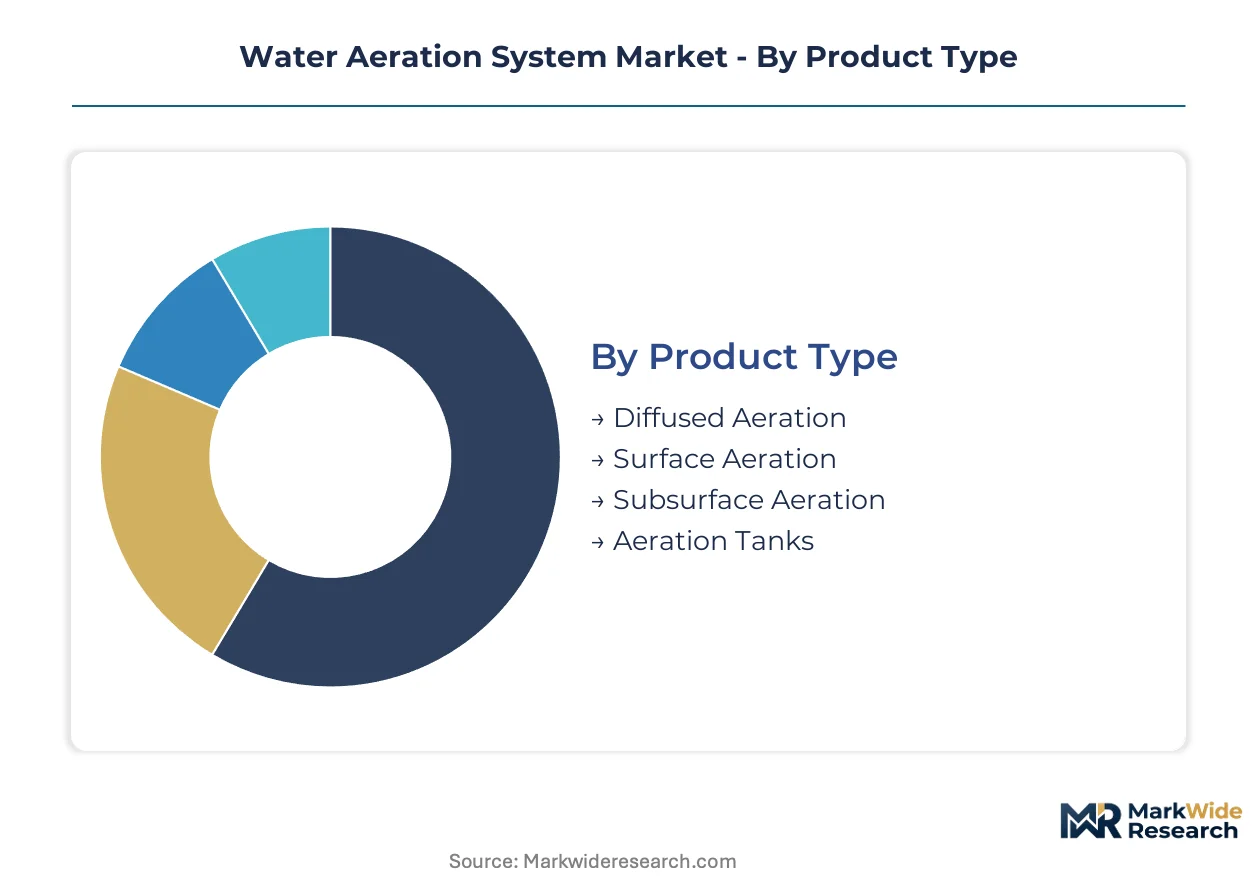
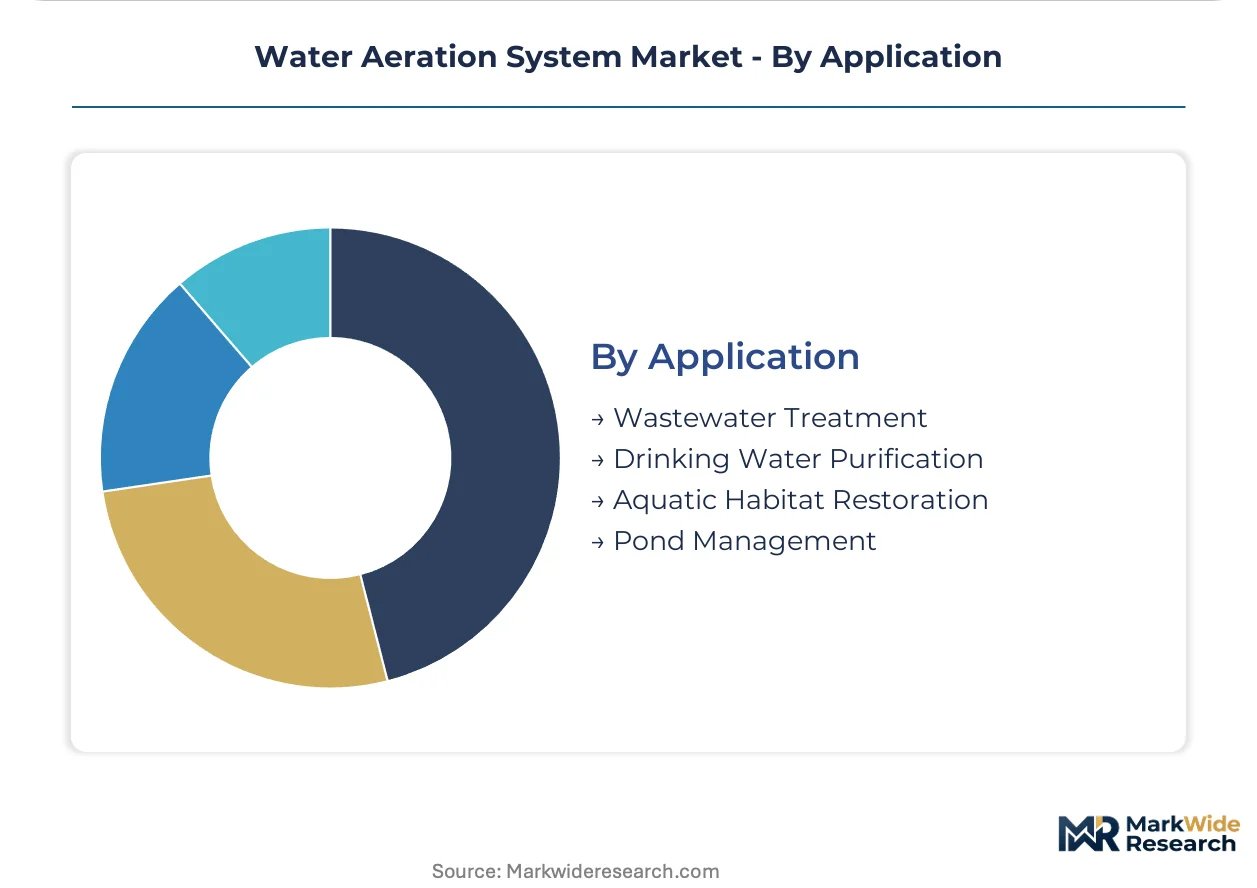
| Segmentation | Product Type: Diffused Aeration, Surface Aeration, Subsurface Aeration, Aeration Tanks Technology: Mechanical Aeration, Biological Aeration, Chemical Aeration, Membrane Technology End User: Municipal Water Treatment, Industrial Wastewater Treatment, Aquaculture, Residential Systems Application: Wastewater Treatment, Drinking Water Purification, Aquatic Habitat Restoration, Pond Management |
| Companies Covered | Aquasystems International, Otterbine, Sulzer, Landia, Hydro Logic Products, Xylem, Ashbrook Simon-Hartley, EPS Pumping & Treatment Systems, Tsurumi Pump, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Aeration System Market Evolving Landscape
Digitalization and materials science are compressing equipment footprints while extending service intervals, shifting competitive advantage from hardware durability to data-enabled lifecycle optimization.
Advanced membrane materials are miniaturizing diffuser pore structures below 0.5 millimeters, enabling municipal utilities in Germany and the Netherlands to achieve oxygen transfer efficiencies exceeding 6.0 kilograms per kilowatt-hour in deep oxidation ditches. These ultrafine bubbles reduce blower energy consumption by 30-40 percent compared to coarse-bubble alternatives. Equipment suppliers now bundle membrane replacement schedules with energy performance guarantees.
EPA effluent limitation guidelines under the Clean Water Act mandate minimum dissolved oxygen levels in treated discharges, compelling US municipal contractors to resize blowers and specify premium diffusers. The regulatory pressure intensifies in watersheds with nutrient-impaired receiving waters. Contractors respond by front-loading energy modeling in design phases.
Service unbundling is fragmenting traditional equipment-procurement relationships, with North American treatment networks purchasing blowers and diffusers separately from predictive maintenance subscriptions. Xylem and Sulzer compete through digital platforms that monetize uptime guarantees rather than hardware margins. This shift concentrates in utilities with constrained in-house instrumentation expertise.
Water Aeration System Market Segmentation
Water aeration system procurement channels diverge sharply across municipal tender processes, industrial direct sales, and aquaculture distributor networks. Equipment specifications and service bundling requirements reshape how manufacturers configure product portfolios for each pathway.
Product Type:
Channel mix varies by aeration mechanism — municipal utilities procure diffused systems through multi-year framework agreements, while surface aerators flow through industrial equipment distributors serving lagoon operators.
- Diffused Aeration:Fine-bubble membrane diffusers achieve oxygen transfer efficiencies exceeding 6.0 kilograms per kilowatt-hour in deep oxidation ditches. German and Dutch municipal utilities concentrate demand here under binding EU energy-efficiency benchmarks for large treatment works.
- Surface Aeration:Mechanical impellers and brush rotors operate at shallower depths with lower capital costs but 30-40% higher energy consumption. Industrial lagoons in Jiangsu and Zhejiang provinces preserve this technology where high solids loading fouls membrane alternatives.
- Subsurface Aeration:Jet aerators combine pumping and oxygen transfer for specific industrial applications.
- Aeration Tanks:Integrated basin-and-aeration packages serve compact urban retrofit projects.
Diffused aeration dominates installed base. Surface aeration is where expansion concentrates in high-solids industrial segments.
Technology:
Margin profiles separate mature mechanical systems from digitally-enabled membrane platforms commanding premium pricing through energy performance guarantees.
- Membrane Technology:Submerged hollow-fiber modules combine aeration with solids separation in MBR plants, compressing footprints for space-constrained urban sites. Coastal Chinese provinces and Norwegian aquaculture facilities drive fastest adoption.
- Mechanical Aeration:Rotors, impellers, and brush systems rely on proven motor-and-gearbox architectures with standardized maintenance protocols. Shallow industrial lagoons and emergency backup systems sustain residual demand.
- Biological Aeration:Biofilm carriers and fixed-growth media enhance microbial colonization density.
- Chemical Aeration:Ozonation and peroxide injection systems address specific contaminant profiles.
Mechanical aeration anchors legacy installed base. Membrane technology is climbing the fastest as MBR adoption accelerates.
End User:
Customer type determines contract structure — municipal frameworks emphasize lifecycle cost guarantees while industrial buyers prioritize rapid deployment and modular scalability.
- Municipal Water Treatment:City and regional utilities operate under EPA NPDES permits or EU Urban Wastewater Treatment Directive mandates, procuring through competitive tender with 15-20 year service agreements. Fine-bubble diffuser retrofits dominate capital planning.
- Industrial Wastewater Treatment:Chemical, food processing, and textile facilities face tightening MEE discharge standards in China and emerging enforcement in India's industrial parks. On-site treatment capacity expansion drives equipment demand.
- Aquaculture:Recirculating systems in Norway and Chile require precision dissolved oxygen control for high-density salmon production.
- Residential Systems:Small-scale pond aerators serve ornamental and private fishery applications.
Municipal water treatment commands largest contract values. Industrial wastewater treatment is where volume expansion concentrates.
Application:
Application context shapes oxygen transfer requirements — biological nutrient removal demands precise dissolved oxygen staging that aesthetic pond management does not.
- Wastewater Treatment:Activated sludge processes require sustained aerobic conditions for BOD reduction and nitrification, with blower systems sized for peak hydraulic and organic loading. EPA effluent guidelines and EU energy benchmarks drive technology selection.
- Drinking Water Purification:Aeration strips volatile organic compounds and oxidizes iron and manganese in groundwater treatment trains. Smaller installed base with specialized blower and tray requirements.
- Aquatic Habitat Restoration:Hypoxic water body remediation uses floating aerators and diffusers to support fish populations.
- Pond Management:Algae control and aesthetic water quality maintenance in golf courses and residential developments.
Wastewater treatment dominates equipment throughput. Aquatic habitat restoration is where project-based expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal utilities and industrial park operators concentrate procurement authority across five national markets where effluent regulations and energy-efficiency mandates reshape equipment specifications. Coastal manufacturing clusters and river-basin treatment networks drive divergent technology preferences.
United States
EPA National Pollutant Discharge Elimination System permits compel utilities in the Chesapeake Bay and Great Lakes watersheds to resize blower systems for nutrient-impaired receiving waters. The agency's effluent limitation guidelines under the Clean Water Act mandate minimum dissolved oxygen thresholds. Texas and California municipal authorities dominate capital planning for aeration retrofits.
Germany
Binding energy-efficiency benchmarks for large treatment works under the EU Urban Wastewater Treatment Directive accelerate fine-bubble diffuser replacement cycles. Länder environmental agencies enforce compliance through operational audits. The Ruhr industrial corridor and Bavarian municipal networks anchor demand for oxygen transfer optimization.
China
Provincial environmental protection bureaus in Jiangsu and Zhejiang enforce stricter dissolved oxygen standards for marine outfalls from industrial parks. The Ministry of Ecology and Environment's GB 18918 discharge standards tighten ammonia and total nitrogen limits. Yangtze River Delta chemical clusters upgrade on-site aeration capacity.
India
Central Pollution Control Board enforcement of stricter effluent norms for industrial parks creates first-mover openings for energy-efficient diffused aeration. State pollution control boards in Gujarat and Maharashtra implement discharge monitoring. Mumbai-Pune and Ahmedabad-Vadodara industrial corridors expand treatment infrastructure.
Netherlands
Rijnmond-Drechtsteden urban water authorities procure through framework agreements emphasizing lifecycle cost guarantees over capital expenditure minimization. National regulators transpose EU energy-efficiency benchmarks into tender evaluation criteria. Rotterdam harbor industrial zones and Randstad municipal networks drive membrane diffuser adoption.
Water Aeration System Market Competitive Landscape
Player mix skews toward integrated pump-and-aeration platforms and digitally-enabled service providers, with tiered concentration across municipal framework agreements and industrial direct sales. European and North American engineering groups anchor premium-tier positioning through combined mechanical reliability guarantees. Asian fabricators compete on rapid deployment for industrial lagoon applications. Dominant competitive moves include predictive maintenance subscription bundling and geographic expansion through distributor partnerships in emerging industrial park markets.
Among European engineering groups, Sulzer and Xylem exemplify contrasting strategic archetypes. Sulzer anchors European utility contracts through integrated pump-and-aeration platforms with combined mechanical reliability guarantees. Xylem occupies the digitally-enabled service tier, competing through predictive maintenance overlays that monetize uptime guarantees. Otterbine represents the specialized surface aeration niche, serving aesthetic water bodies where oxygen transfer rates matter less than visual footprint and noise control.
| Leading Market Players |
|---|
| Aquasystems International |
| Otterbine |
| Sulzer |
| Landia |
| Hydro Logic Products |
| Xylem |
| Ashbrook Simon-Hartley |
| EPS Pumping & Treatment Systems |
| Tsurumi Pump |
| Others |
Value Network & Pricing Analysis
Fine-pore membrane diffuser adoption replacing coarse-bubble and mechanical alternatives redraws procurement geography toward Japanese and German fluoropolymer suppliers while compressing energy-based lifecycle pricing models for municipal utilities.
Pricing Analysis
Cost-plus contracts with fluoropolymer feedstock indexation dominate municipal framework agreements, tying diffuser replacement schedules to resin price volatility. Pricing stratifies across membrane technology tiers, with ultrafine-pore systems commanding premiums for oxygen transfer efficiency guarantees. Cost compression in standard-grade mechanical aeration is intensifying because Asian fabricators compete on rapid deployment timelines. Industrial lagoon operators exhibit highest price sensitivity, while Dutch and German municipal utilities prioritize lifecycle performance over capital expenditure minimization.
Supply Chain Analysis
Inbound logistics costs from Rotterdam and Hamburg port congestion ripple through European municipal procurement timelines, extending blower and diffuser delivery schedules. Manufacturing concentrates in Germany, Japan, and China, with fluoropolymer membrane feedstocks drawing from specialized chemical suppliers in Osaka and Frankfurt. Single-source vulnerability permeates fine-pore polymer resin channels. Distribution runs through multi-year framework agreements with integrated pump-and-aeration platforms in European utility markets and direct industrial sales channels in Chinese coastal provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water aeration system demand follows municipal capital expenditure cycles, with replacement waves accelerating as EU energy-efficiency benchmarks force fine-bubble diffuser retrofits across aging European treatment infrastructure.
For Market Incumbents: Shield installed base relationships by embedding predictive maintenance subscriptions into blower service contracts, countering unbundling pressure from digitally-native competitors. Deepen backward integration into fluoropolymer membrane manufacturing to reduce exposure to Japanese chemical supplier concentration. Anchor municipal framework renewals through combined mechanical reliability guarantees spanning pumps and aeration.
For New Entrants and Emerging Players: Certification fast-track through EU-type examination routes opens municipal tender participation in the Netherlands and Germany without decade-long track record requirements. Target India's industrial park wastewater sector where Central Pollution Control Board enforcement creates first-mover openings for energy-efficient diffused aeration. Pursue distributor partnerships with established industrial equipment channels in Gujarat and Maharashtra rather than direct municipal sales.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed engineering groups holding European municipal framework portfolios ripe for operational consolidation. Long-term viability hinges on digital service overlay capabilities that monetize recurring revenue streams rather than hardware margins. Monitor EPA NPDES permit modification timelines as inflection signal for US municipal upgrade cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Xylem and Sulzer monetize uptime guarantees through sensor-enabled blower diagnostics in North American treatment networks. |
| Backward Integration into Membrane Manufacturing | European engineering groups reduce fluoropolymer resin exposure by acquiring specialized diffuser production capabilities. |
| Industrial Park Distributor Partnerships | New entrants bypass municipal tender barriers by channeling diffused aeration through established equipment distributors in India. |
| EU-Type Certification Fast-Track | Accelerated conformity assessment enables framework agreement participation in Dutch and German municipal procurement. |
| Aquaculture Precision Aeration Development | Norwegian and Chilean salmon producers drive demand for dissolved oxygen control systems in high-density recirculating facilities. |
Research Methodology
A standing panel of municipal utility operations directors, industrial wastewater plant managers, membrane technology R&D leads, and aftermarket service heads provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA effluent limitation guideline filings, EU Urban Wastewater Treatment Directive transposition documents, Chinese MEE discharge standard updates, and customs trade data on fluoropolymer resin flows. Bottom-up equipment shipment analysis and top-down utility capital expenditure tracking were triangulated against regulatory mandate timelines.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across aeration mechanism type, membrane versus mechanical technology, end-user category spanning municipal and industrial, and geographic regulatory cluster. CAGRs were derived from equipment replacement cycle analysis tied to binding energy-efficiency benchmark implementation schedules. Forecast inputs incorporated blower energy modeling, dissolved oxygen standard tightening trajectories, and membrane fouling rate assumptions in high-solids industrial applications.
Underlying assumptions cover EU directive enforcement continuity, fluoropolymer supply stability, and municipal capital availability, with deviation risk concentrated in EPA permitting timeline extensions and Chinese provincial environmental bureau implementation variance. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Sludge Dewatering Equipment Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Global Wastewater Treatment Services Market
Water and Wastewater Treatment
Sewage Treatment Service Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Javelle Water Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
Latin America Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market
Water and Wastewater Treatment
Global Smart Leak Detection Solutions for Water and Wastewater Industries Market
Water and Wastewater Treatment
Packaged Wastewater Treatment Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market
Water and Wastewater Treatment
Wastewater Clarifier Market