
 Water Testing Market | 2026-2036
Water Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Water Testing Market Outlook
Industrial facility buyers are gaining share as municipal procurement budgets tighten, and the Water Testing Market is bifurcating between large-scale utility contracts and decentralized industrial compliance spending. Danaher Corporation anchors its position through vertical integration in chromatography consumables. Thermo Fisher Scientific, Inc. leverages its R&D intensity to dominate mass spectrometry-based water contaminant detection. SGS SA competes through its geographic dominance in third-party environmental certification across European industrial corridors.
Water testing encompasses the analytical determination of chemical, biological, and physical parameters in aqueous matrices using methods with detection thresholds ranging from parts per million to parts per trillion, depending on contaminant class and regulatory limit. Its primary commercial purpose is to verify compliance with health-based standards, protect industrial process integrity, and support environmental remediation decisions. Laboratory instruments command the largest revenue pool due to capital intensity and recurring reagent demand, while sensors represent the fastest-expanding category as utilities deploy continuous monitoring nodes. PCR technology is displacing culture-based methods for pathogen detection in drinking water applications, creating new margin pools for molecular diagnostic workflows.
The EPA Safe Drinking Water Act amendments and EU Drinking Water Directive revisions are forcing utilities to expand testing panels for emerging contaminants including PFAS and antibiotic residues. ISO 17025 accreditation requirements and the EU Water Framework Directive shape market access by filtering out uncertified regional laboratories. Stakeholders must decide whether to build in-house analytical capacity or outsource to multi-site accredited networks as regulatory breadth outpaces single-facility capability expansion.
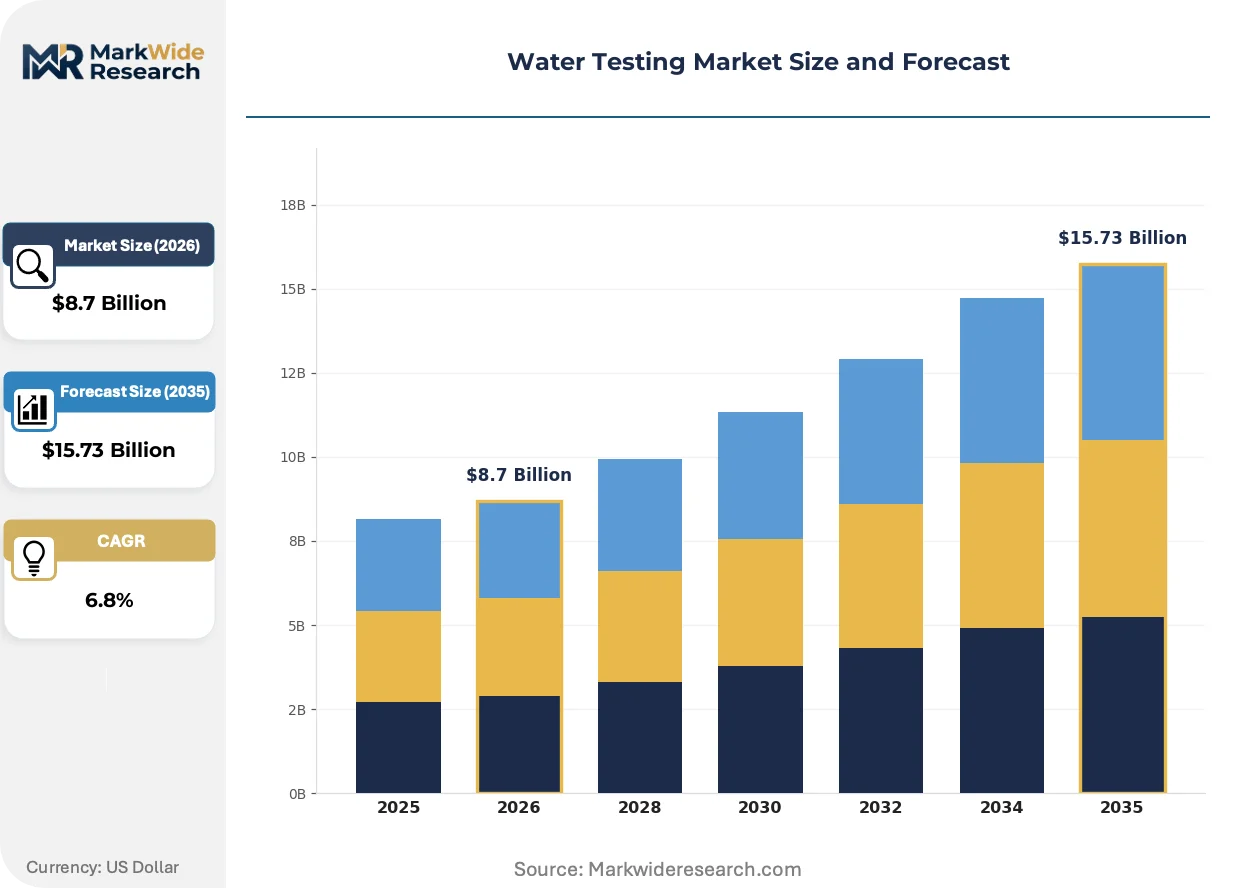
Market Dynamics
The transition from laboratory batch analysis to continuous electrochemical sensor networks is compressing testing cycles and redistributing capital expenditure from centralized facilities to distributed infrastructure nodes.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:Municipal utilities across the United States face accelerated compliance timelines for corrosion control and sampling protocols, forcing procurement of real-time monitoring systems.
- Germany's Pharmaceutical Screening Mandates:The Federal Environment Agency's expanded surface water testing requirements for active pharmaceutical ingredients and microplastic residues are generating new analytical service contracts.
- PCR Technology Adoption:Molecular diagnostic workflows for pathogen detection in drinking water are replacing culture-based methods, creating recurring revenue streams for reagent suppliers and instrument manufacturers.
Market Restraints
- Platinum Group Metal Volatility:Electrochemical sensor electrodes depend on ruthenium and iridium coatings, exposing manufacturers to precious metal price swings and supply disruption from South African concentrate exports.
- ISO 17025 Accreditation Barriers:The capital and technical documentation burden for laboratory certification filters out regional competitors, concentrating analytical service provision in multi-site networks.
- Optical Spectroscopy Substitution:UV-Vis and fluorescence-based systems for organic contaminant detection threaten electrochemical sensor margins in industrial process water applications.
Strategic Opportunities
- Industrial Self-Monitoring Expansion:Food and beverage processors in the United States are building captive analytical capacity to bypass third-party laboratory queues and reduce compliance reporting latency.
- EU Drinking Water Directive Convergence:The 2021 recast mandates uniform emerging contaminant monitoring across member states, harmonizing product certification requirements and reducing market entry friction for sensor vendors.
- AI-Enabled Predictive Maintenance:Machine learning integration with sensor networks enables failure anticipation and calibration optimization, creating software subscription revenue atop hardware sales.
Industry Challenges
- Field Spectroscopist Shortage:The specialized skill set for mass spectrometry operation and data interpretation constrains laboratory throughput expansion and drives wage inflation in accredited facilities.
- Legacy SCADA Integration Friction:Municipal utilities operate decades-old distribution control systems with proprietary communication protocols, complicating sensor network deployment and data aggregation.
- Multi-Jurisdictional Certification Complexity:Equipment vendors must navigate divergent approval pathways through EPA, state environmental agencies, and NSF International standards, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Testing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Sensors, Laboratory Instruments, Field Equipment Application: Drinking Water, Wastewater Treatment, Industrial Water, Environmental Monitoring Technology: Electrochemical, Spectrophotometry, Chromatography, PCR End User: Municipalities, Industrial Sectors, Environmental Agencies, Private Laboratories |
| Companies Covered | Thermo Fisher Scientific, Inc., SGS SA, Eurofins Scientific SE, Danaher Corporation, Hach, Bureau Veritas SA, Intertek Group plc, ALS Limited, Honeywell International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Testing Market Strategic Shifts
Digital twin architectures and autonomous calibration algorithms are converging with electrochemical sensing hardware, collapsing the latency between contaminant detection and system response in distribution networks.
Membrane-based solid-state ion-selective electrodes are fragmenting the traditional glass electrode market for pH and heavy metal detection. Water utilities in the Netherlands and Denmark are deploying these ruggedized sensors in buried distribution nodes with ten-year replacement cycles. The technology is fragmenting vendor hierarchies by enabling smaller manufacturers to bypass the electrochemical expertise barrier that previously protected incumbents.
The EU Water Framework Directive's 2027 milestone for good ecological status in all surface water bodies is compressing national monitoring program timelines. Member states must expand sampling frequency and parameter breadth for river basin management plans, redirecting public analytical procurement toward high-throughput automated systems. Germany and France are consolidating regional laboratory networks to achieve the detection thresholds required for priority substance compliance.
Industrial buyers are unbundling analytical services from capital equipment procurement, preferring performance-based contracts with guaranteed uptime and data delivery specifications. Chemical manufacturers in the US Gulf Coast region are negotiating sensor-as-a-service agreements that transfer calibration, maintenance, and regulatory reporting liability to instrument vendors. This procurement evolution is most visible in semiconductor fabrication, where ultrapure water specifications exceed municipal drinking water standards by orders of magnitude.
Water Testing Market Segmentation
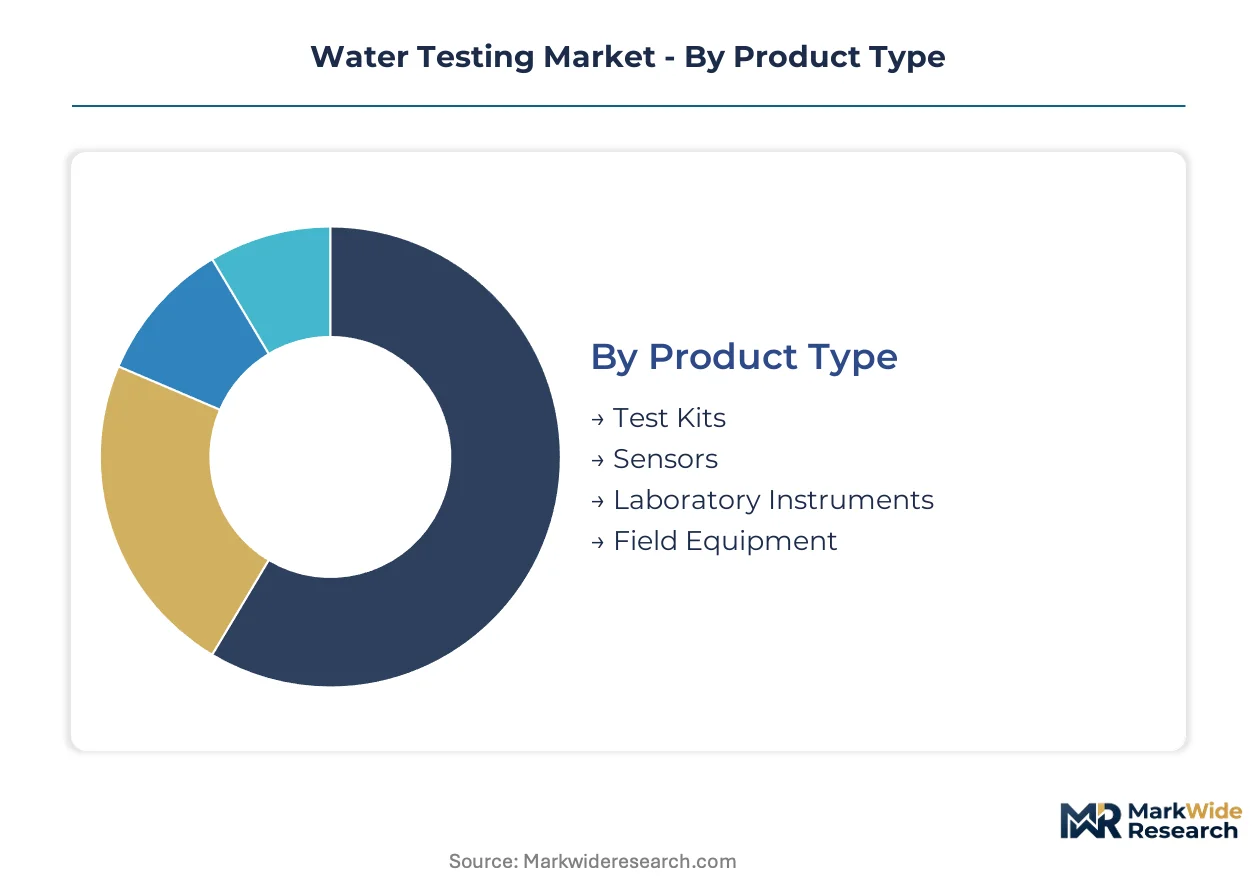
Water testing procurement patterns diverge sharply across product categories, with laboratory infrastructure dominating capital budgets while sensor networks capture incremental spending. Regulatory complexity in Germany and the United States is fragmenting demand across compliance tiers, forcing vendors to align technical specifications with jurisdiction-specific detection thresholds.
Product Type:
Domestic production concentrates laboratory instruments and sensors in Germany, the United States, and Japan, while test kits and field equipment flow from contract manufacturers in China and India serving export markets.
- Test Kits:Portable colorimetric and titration-based assays deliver rapid on-site screening for chlorine residual, pH, and heavy metals without laboratory infrastructure. Municipal field crews in the United States deploy these for distribution system spot checks, though detection limits struggle against EPA's revised lead action levels.
- Sensors:Electrochemical and optical probes enable continuous real-time monitoring of dissolved oxygen, conductivity, and specific ions in distribution networks. Utilities in Denmark and the Netherlands are burying solid-state ion-selective electrodes with decade-long replacement cycles, bypassing traditional glass electrode maintenance regimes.
- Laboratory Instruments:Mass spectrometry and chromatography systems anchor centralized analytical capacity for emerging contaminant quantification at parts-per-trillion thresholds.
- Field Equipment:Ruggedized spectrophotometers and portable GC-MS units extend laboratory-grade detection to remote sampling locations.
Laboratory instruments command the established base. The steepest expansion runs through sensors.
Application:
Cost tier stratification separates high-frequency municipal drinking water monitoring from episodic industrial compliance testing, with environmental monitoring occupying a mid-tier pricing band.
- Drinking Water:Distribution system surveillance demands continuous residual disinfectant monitoring and periodic pathogen screening under Safe Drinking Water Act mandates. German utilities are expanding pharmaceutical and microplastic panels beyond EU minimums, stretching analytical capacity.
- Wastewater Treatment:Effluent discharge permits require nutrient load quantification and emerging contaminant screening at increasing sensitivity. Advanced oxidation process validation in the Netherlands drives demand for TOC and specific organic compound tracking.
- Industrial Water:Process integrity specifications in semiconductor fabrication and power generation exceed municipal standards by orders of magnitude.
- Environmental Monitoring:River basin management plans under the EU Water Framework Directive mandate expanded spatial and temporal sampling density.
Drinking water absorbs the largest procurement volume. Industrial water is climbing the fastest as captive analytical capacity expands.
Technology:
Application maturity separates electrochemical methods with decades of regulatory acceptance from PCR and advanced chromatography still navigating approval pathways.
- Electrochemical:Potentiometric and amperometric techniques deliver continuous ion-selective measurement with minimal reagent consumption. Ruthenium and iridium electrode coatings expose manufacturers to South African concentrate supply volatility.
- Spectrophotometry:UV-Vis and fluorescence systems quantify organic contaminant loads through absorbance and emission characteristics. Industrial process water applications in the US Gulf Coast favor these over electrochemical alternatives for specific compound tracking.
- Chromatography:HPLC and GC-MS workflows separate and identify complex contaminant mixtures at regulatory detection thresholds.
- PCR:Quantitative polymerase chain reaction displaces culture-based pathogen enumeration in drinking water laboratories, collapsing detection time from days to hours.
Electrochemical methods anchor routine monitoring. PCR is gaining share fastest as molecular diagnostics displace legacy microbiology.
End User:
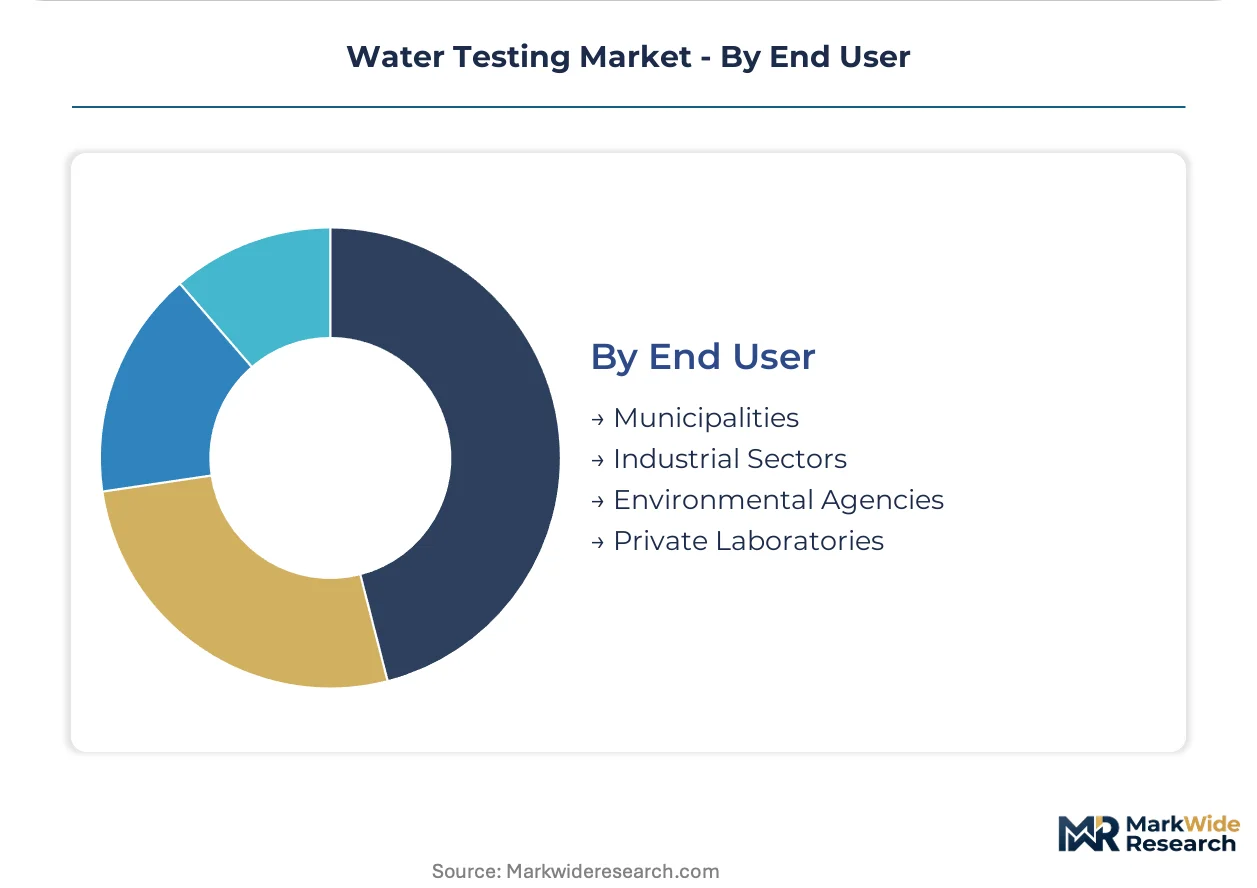
Customer type determines procurement modality, with municipalities favoring capital purchase and industrial buyers migrating toward performance-based service contracts.
- Municipalities:Public utilities operate under fixed regulatory compliance schedules with budget cycles tied to rate case approvals. EPA enforcement of revised lead and copper rules is compressing procurement timelines for real-time monitoring infrastructure.
- Industrial Sectors:Food and beverage processors and chemical manufacturers are building captive laboratories or negotiating sensor-as-a-service agreements to bypass third-party queue delays. Semiconductor fabricators demand ultrapure water specifications unmatched by municipal supply.
- Environmental Agencies:Federal and state regulators operate reference laboratories and contract analytical services for enforcement monitoring.
- Private Laboratories:ISO 17025-accredited networks consolidate regional capacity to achieve economies of scale in high-throughput automated systems.
Municipalities retain the largest installed base. Industrial sectors are expanding most quickly through alternative procurement structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Germany's central role in European analytical procurement, connecting industrial basins from Rotterdam to the Black Sea with continuous monitoring infrastructure.
United States
Municipal utilities in the Great Lakes region are replacing legacy lead service lines under EPA corrosion control mandates. The Safe Drinking Water Act amendments compress compliance timelines for real-time distribution monitoring. Chicago and Milwaukee metropolitan water districts are deploying electrochemical sensor networks with decade-long replacement cycles.
Germany
The Federal Environment Agency's pharmaceutical screening mandates are expanding analytical service contracts for active ingredient detection in surface waters. EU Water Framework Directive deadlines for good ecological status are consolidating regional laboratory networks in the Rhine-Ruhr and Upper Bavaria industrial corridors.
China
Yangtze River Delta municipalities are installing continuous monitoring nodes for ultrapure water specifications in semiconductor fabrication clusters. MEE enforcement of surface water quality standards is tightening discharge permit requirements for chemical manufacturers in the Shanghai-Suzhou corridor.
Netherlands
Water utilities in the Randstad are burying solid-state ion-selective electrodes with autonomous calibration algorithms. Advanced oxidation process validation for emerging contaminant removal is driving TOC tracking demand in the Rotterdam port-industrial complex.
Japan
Kanto region utilities are adopting PCR-based pathogen detection workflows under revised drinking water quality standards. METI support for smart water infrastructure is accelerating sensor network deployment in the Tokyo-Yokohama metropolitan supply zone.
Water Testing Market Competitive Environment
Concentration sits with diversified life science conglomerates and third-party certification networks that span multiple regulatory jurisdictions. The vendor base separates into instrument manufacturers with captive reagent streams, accredited analytical service providers with geographic density, and industrial automation specialists with sensor integration expertise. Dominant competitive moves include backward integration into chromatography consumables and geographic expansion through multi-site laboratory consolidation.
Among US-based conglomerates, Thermo Fisher Scientific, Inc. and Danaher Corporation exemplify the instrument-reagent integration archetype. Eurofins Scientific SE and SGS SA represent the accredited service network model with European regulatory density. These anchors occupy positions across the value chain from hardware supply to compliance certification.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| SGS SA |
| Eurofins Scientific SE |
| Danaher Corporation |
| Hach |
| Bureau Veritas SA |
| Intertek Group plc |
| ALS Limited |
| Honeywell International, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term sensor-as-a-service contracts lock in supply access for platinum-group electrode coatings while anchoring price visibility for municipal utilities navigating EPA compliance timelines. These arrangements transfer calibration liability to vendors and compress working capital cycles for buyers.
Pricing Analysis
Volume-discount tiering separates ISO 17025-accredited laboratory networks from regional competitors lacking certification density. Pricing stratifies across premium, standard, and economy tiers based on detection threshold capability and after-sales service bundling. Cost compression in economy-tier test kits is intensifying because Chinese contract manufacturers are scaling colorimetric assay production. Municipal utilities exhibit the highest price sensitivity due to rate-case budget constraints, while semiconductor fabricators accept premium positioning for ultrapure water specifications.
Supply Chain Analysis
Germany and the United States anchor laboratory instrument manufacturing, while China and India feed test kit and field equipment exports through contract manufacturers. Electrochemical sensor production draws from South African ruthenium and iridium concentrate, exposing coating operations to commodity price volatility. Single-source vulnerability concentrates in precious metal electrode supply. Distribution runs through multi-site accredited laboratory networks and direct municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized mass spectrometry operation skills are scarce enough to constrain laboratory throughput expansion and drive wage inflation in accredited facilities. This capability gap shapes competitive positioning across the value chain.
For Market Incumbents: Shield chromatography consumable revenue streams by backward integration into reagent manufacturing. Secure ISO 17025 accreditation density across Rhine-Ruhr and Upper Bavaria corridors before EU Water Framework Directive deadlines consolidate regional networks. Field spectroscopist shortages threaten throughput expansion.
For New Entrants and Emerging Players: AI-enabled predictive maintenance software layers present a service gap where incumbents under-serve legacy SCADA integration needs. Target semiconductor fabrication clusters in the US Gulf Coast with sensor-as-a-service agreements that transfer calibration liability. Lead with guaranteed uptime specifications rather than hardware specifications.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap accredited laboratory networks with geographic density across multiple EPA regions. Long-term viability hinges on consolidation economies in high-throughput automated systems. Watch for EPA enforcement acceleration on revised lead and copper rules as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromatography Consumables | Danaher Corporation secures recurring reagent revenue and protects instrument margins. |
| Multi-Site Laboratory Network Consolidation | Eurofins Scientific SE achieves ISO 17025 density across EU industrial corridors. |
| Sensor-as-a-Service Contract Expansion | Hach transfers calibration liability to vendors and locks in municipal procurement cycles. |
| PCR Workflow Platform Development | Thermo Fisher Scientific displaces culture-based pathogen detection in drinking water labs. |
| Solid-State Ion-Selective Electrode Deployment | Netherlands utilities bypass glass electrode maintenance with decade-long replacement cycles. |
Study Parameters
Desk research of EPA enforcement records, EU Water Framework Directive implementation timelines, and ISO 17025 accreditation databases preceded structured interviews with municipal water utility procurement officers, laboratory directors at accredited analytical facilities, electrochemical sensor manufacturing engineers, and environmental regulatory compliance consultants. Primary fieldwork captured procurement modality shifts and technology substitution patterns. Secondary validation drew from customs trade data, SEC 10-K filings of listed instrument manufacturers, and national surface water quality monitoring program disclosures. Bottom-up segment sizing triangulated against top-down regulatory spend estimates.
Variance decomposition across product type, application, technology, and end user dimensions shaped the analytical framework over the projection horizon. Modeled segmentation captured laboratory instruments versus sensors versus test kits, drinking water versus industrial water applications, electrochemical versus PCR versus chromatography technologies, and municipalities versus industrial sectors as end users. CAGRs were derived from regression against regulatory compliance spend trajectories and technology substitution elasticities. Forecast inputs incorporated EPA lead and copper rule revision timelines and EU Drinking Water Directive recast implementation schedules.
Underlying assumptions cover stable precious metal electrode supply from South African concentrate exports and sustained EPA enforcement intensity, with deviation risk concentrated in platinum-group metal price volatility and municipal budget austerity cycles. Recalibration cycles align with material shifts in regulatory enforcement patterns and technology approval pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Water Quality Analyzer Market
Environmental Monitoring
US Environmental Testing Market
Environmental Monitoring
Environmental Monitoring (Surface Water) Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
Air Quality Monitoring Equipment Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Smart Water Monitoring Market
Environmental Monitoring
Water Pipeline Leak Detection System Market
Environmental Monitoring
Indoor Air Quality Service Market
Environmental Monitoring
Food Security Technology Market
Environmental Monitoring
Environmental Remediation Technologies Market
Environmental Monitoring
Carbon Monoxide Analyzers Market
Environmental Monitoring
Radon Gas Test Kits Market
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Global Weather Forecasting Services Market