
 Zero Liquid Discharge (ZLD) Systems Market | 2026-2036
Zero Liquid Discharge (ZLD) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Zero Liquid Discharge (ZLD) Systems Market Analysis
Saudi Arabia's industrial city build-outs at Jubail and Yanbu is rewriting regional demand patterns for advanced water recovery infrastructure. Evoqua Water Technologies leverages its thermal process expertise to anchor large-scale refinery deployments across the Middle East. Praj Industries competes through its hybrid technology portfolio that integrates bioethanol distillation with zero-discharge wastewater systems. GEA Group Aktiengesellschaft dominates evaporation crystallization modules with manufacturing scale that sustains cost leadership across EMEA power projects.
Zero Liquid Discharge (ZLD) Systems comprise integrated wastewater treatment trains combining membrane filtration, brine concentration, and thermal crystallization to recover over 95% of inlet water as distillate while producing solid salt residues for disposal or recovery. These systems operate at total dissolved solids thresholds exceeding 300,000 ppm in final crystallizer stages, serving industries where effluent discharge restrictions or water scarcity eliminate conventional treatment options. Reverse osmosis and evaporation crystallization command the largest installed base, though membrane distillation represents the fastest-growing system type as photovoltaic-thermal hybrid configurations reduce specific energy consumption. Within end-user categories, chemical processing and electronics manufacturing concentrate margin pools due to high-purity water requirements and hazardous constituent recovery needs.
The US EPA enforces effluent limitation guidelines that prohibit liquid discharge from specific coal-fired power operations, while India's CEA mandates ZLD compliance for all new thermal capacity exceeding 500 MW, directly shaping procurement specifications for multi-effect distillation trains. China's MEE implements dual carbon goals that tighten industrial wastewater reuse rates, forcing technology upgrades across Shandong and Jiangsu chemical clusters. Stakeholders must monitor regulatory divergence between thermal-intensive crystallization mandates and emerging mechanical vapor recompression incentives that alter lifecycle cost calculations.
Market Dynamics
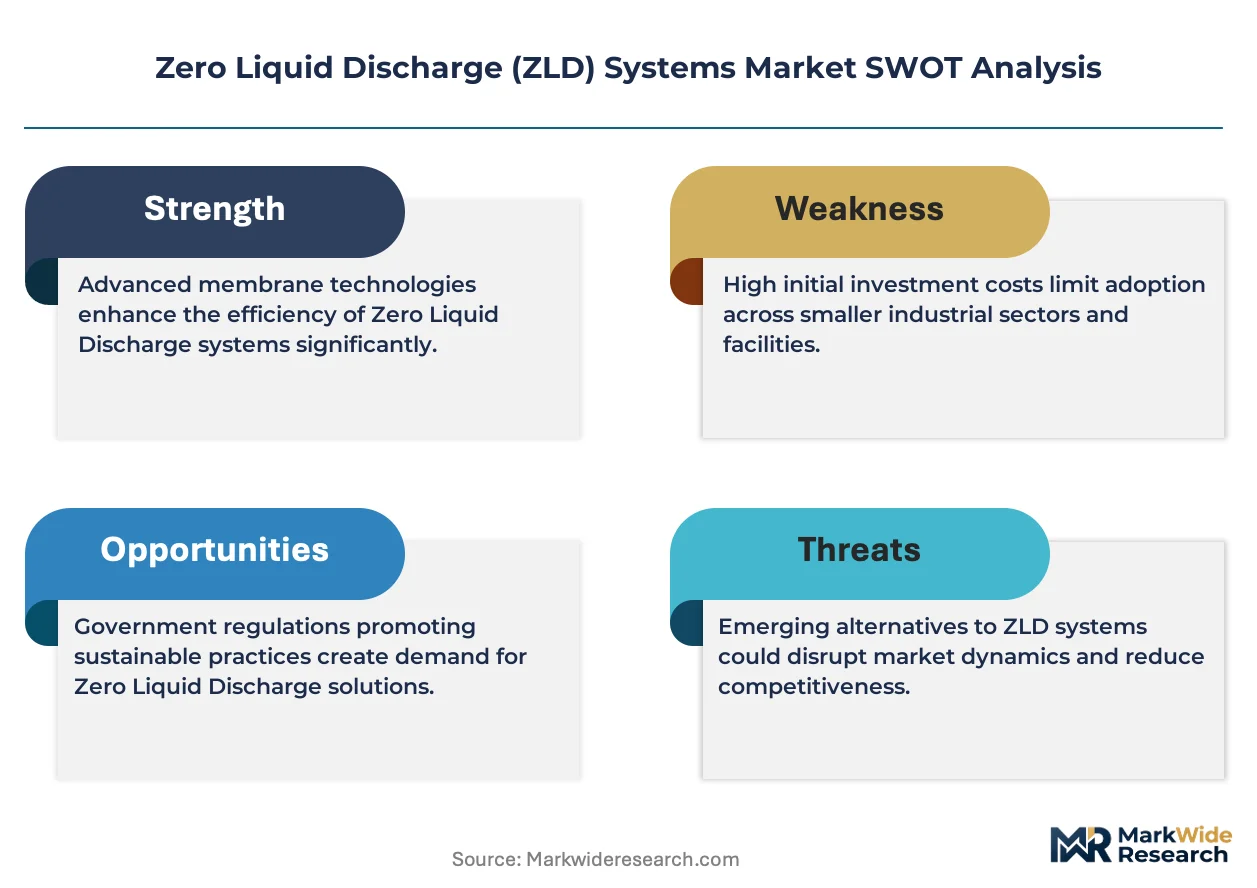
Membrane distillation technology is compressing energy requirements for thermal crystallization stages, forcing incumbent evaporation vendors to recalibrate lifecycle cost models or surrender share to hybrid system integrators.
Growth Catalysts
- India's CEA thermal mandates:New plants exceeding 500 MW must achieve zero effluent discharge, mandating multi-effect distillation procurement and creating guaranteed demand corridors.
- Photovoltaic-thermal hybrids:Solar-integrated membrane distillation configurations cut specific energy consumption, opening ZLD deployment to water-stressed regions without grid reliability.
- Electronics manufacturing clusters:High-purity water recovery requirements in semiconductor fabrication drive premium system specifications with hazardous constituent separation modules.
Market Restraints
- Specialty alloy supply concentration:Super duplex stainless steel for crystallizer vessels concentrates among Nordic and Japanese metallurgical suppliers, exposing project timelines to billet allocation delays.
- Energy price volatility:Thermal crystallization stages remain vulnerable to natural gas price swings, compressing project IRRs in markets without waste heat integration.
- Mechanical vapor recompression substitution:MVR evaporation offers lower opex for moderate salinity feeds, constraining thermal ZLD addressable market in chemical processing below 150,000 ppm TDS.
Strategic Opportunities
- Saudi Arabia's giga-project pipeline:Jubail and Yanbu industrial city expansions specify advanced water recovery infrastructure, creating anchor demand for decade-long service contracts.
- China's dual carbon enforcement:MEE wastewater reuse quotas for Shandong chemical clusters mandate technology upgrades, accelerating membrane distillation retrofit cycles.
- Lithium brine extraction convergence:Direct lithium extraction waste streams require ZLD finishing trains, positioning crystallization vendors at the nexus of battery mineral and water recovery value chains.
Industry Challenges
- Thermal process engineering talent scarcity:Crystallizer design and brine chemistry expertise concentrates among aging specialists, constraining execution capacity for simultaneous large-scale deployments.
- Legacy DCS integration complexity:Brownfield chemical plants require ZLD trains to interface with decades-old distributed control systems, extending commissioning timelines and inflating customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero Liquid Discharge (ZLD) Systems Market |
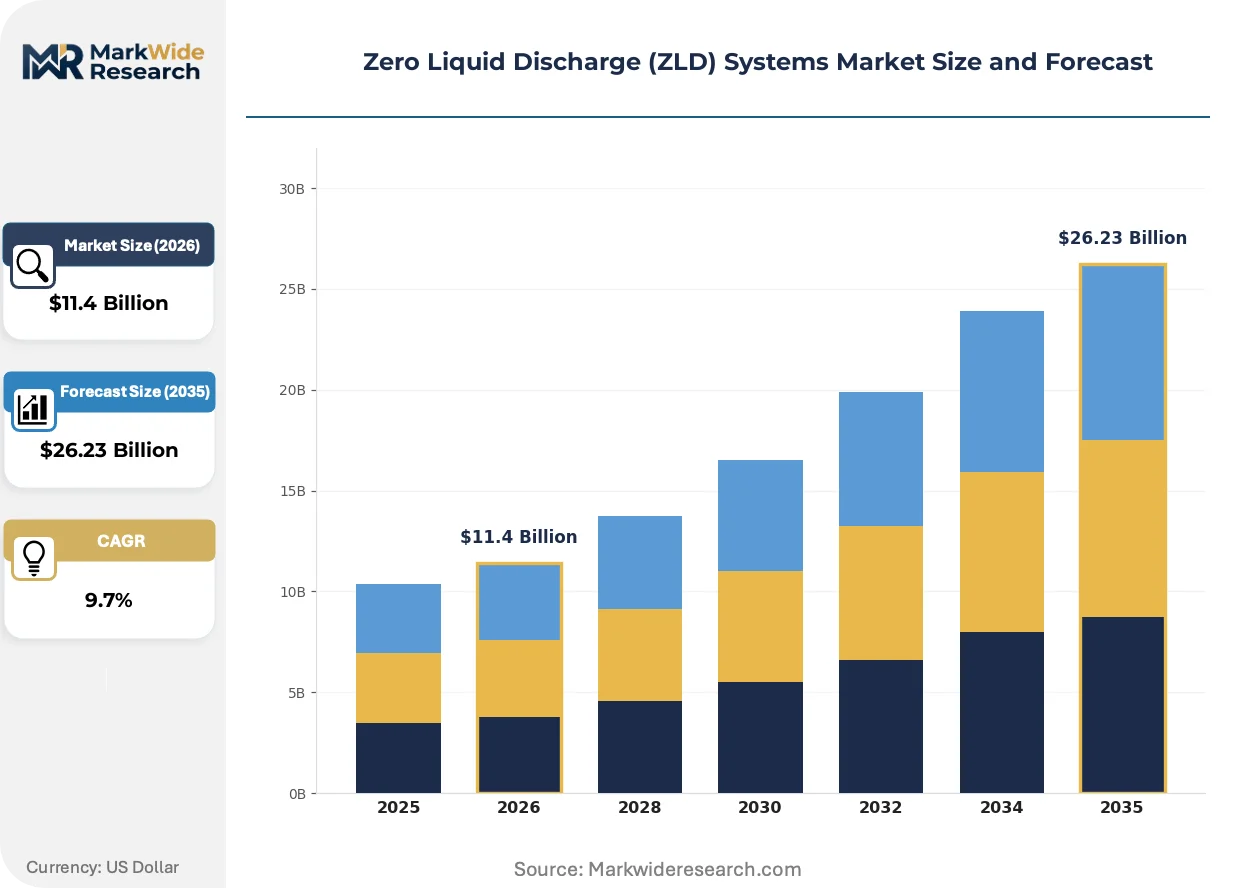
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $26.23 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Membrane Distillation, Reverse Osmosis, Evaporation Crystallization, Multi-effect Distillation Application: Textile Industry, Power Generation, Mining, Food Processing End User: Manufacturing, Pharmaceuticals, Chemical Processing, Electronics Technology: Thermal, Mechanical Vapor Recompression, Photovoltaic, Hybrid |
| Companies Covered | Evoqua Water Technologies LLC, Praj Industries Ltd, GEA Group Aktiengesellschaft, H2O GmbH, IDE Technologies, Aquatech International LLC, Aquarion AG, Alfa Laval, Veolia Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero Liquid Discharge (ZLD) Systems Market Emerging Trajectories
Photovoltaic-thermal hybrid configurations are rewriting the energy economics of membrane-based brine concentration, compressing the historical dominance of fossil-fired thermal evaporation in arid-region deployments.
Membrane distillation modules paired with waste heat recovery loops are rendering obsolete conventional multi-effect distillation trains in coal-fired power retrofit applications. Indian thermal operators facing CEA mandates now specify hybrid configurations that halve steam extraction requirements. The technology shift is compressing the addressable market for standalone thermal crystallization vendors.
REACH chemical safety registrations and EU Green Deal industrial emissions frameworks are tightening discharge limits for European chemical processing clusters. German and Dutch regulators now require mass-balance documentation for salt recovery streams, forcing crystallizer vendors to certify residue purity grades. The compliance burden is accelerating preference for integrated system suppliers with in-house analytical validation.
After-sales service unbundling is disrupting traditional EPC contracting in Middle Eastern refinery deployments. Saudi Aramco and ADNOC now separate process guarantees from long-term membrane replacement and chemical supply agreements, fragmenting vendor relationships. The procurement model shift is compressing margins for equipment-only suppliers while expanding recurring revenue pools for chemical and membrane specialists.
Zero Liquid Discharge (ZLD) Systems Market Segmentation
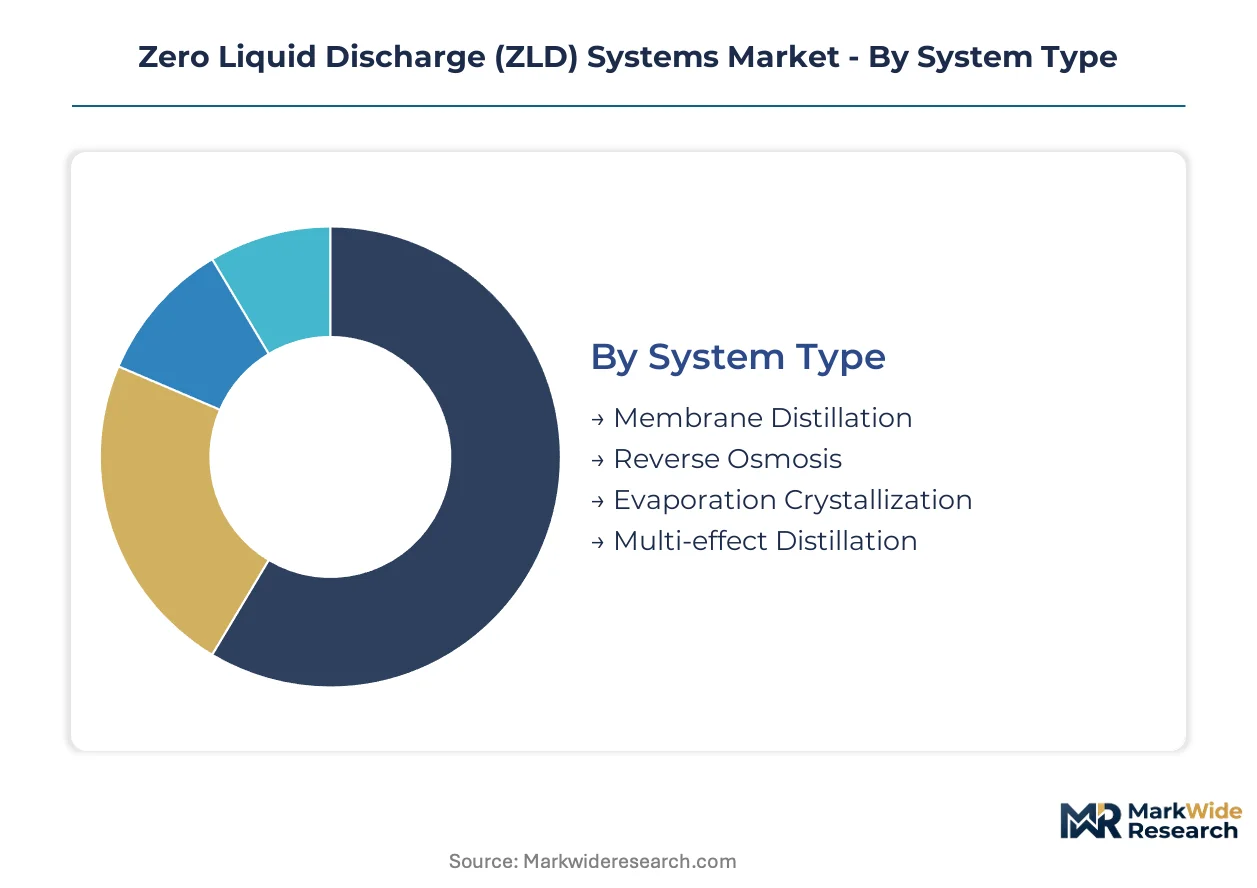
ZLD system architectures vary dramatically across salinity thresholds, energy availability, and discharge constraints. Procurement specifications diverge between thermal-intensive crystallization for high-TDS brines and membrane-based trains for moderate-salinity industrial streams.
System Type:
Use-case spectrum spans thermal evaporation for saturated brines through membrane separation for pre-concentration stages.
- Membrane Distillation:Vacuum-enhanced vapor transport across hydrophobic membranes achieves brine concentration at 60-80°C operating temperatures. Photovoltaic-thermal hybrid configurations in Saudi Arabia's Jubail industrial city are displacing conventional thermal trains for refinery wastewater recovery.
- Evaporation Crystallization:Forced-circulation crystallizers with scraped-surface heat exchangers precipitate solid salts from 300,000+ ppm TDS brines. India's CEA-mandated thermal power installations specify these units as the terminal stage for zero effluent compliance.
- Reverse Osmosis:Spiral-wound polyamide membranes handle bulk water recovery ahead of thermal concentration stages.
- Multi-effect Distillation:Steam-driven evaporation cascades dominate legacy refinery and desalination brine concentration applications.
Established volume favors multi-effect distillation; emerging adoption favors membrane distillation.
Application:
Cost tier stratification separates capex-intensive power sector deployments from opex-sensitive food processing installations.
- Power Generation:Flue gas desulfurization blowdown and cooling tower blowdown require 95%+ recovery rates under US EPA effluent guidelines. India's new thermal capacity mandates from the CEA guarantee procurement pipelines for multi-effect distillation trains exceeding 500 MW plant thresholds.
- Chemical Processing:Hazardous constituent recovery and high-purity water recycling drive premium system specifications. China's Shandong and Jiangsu clusters face MEE wastewater reuse quotas that accelerate membrane distillation retrofit cycles.
- Textile Industry:Dye bath recovery and salt reuse applications concentrate demand in India's Tiruppur and Surat manufacturing belts.
- Mining:Acid mine drainage and process water recovery operate at extreme TDS variability requiring modular hybrid configurations.
- Food Processing:Dairy whey concentration and beverage wastewater recovery prioritize mechanical vapor recompression for thermal efficiency.
Margin concentration sits with chemical processing; steepest expansion trajectory belongs to power generation retrofits.
End User:
Customer type fragmentation separates multinational electronics fabricators from regional pharmaceutical manufacturers.
- Electronics:Semiconductor wafer fabrication demands ultrapure water recovery with parts-per-trillion contaminant rejection. Hazardous constituent separation modules command 40-60% system cost premiums over standard configurations.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturing generates solvent-laden wastewater requiring explosion-rated thermal processing equipment.
- Manufacturing:Automotive and general industrial applications concentrate demand for standardized membrane-thermal hybrid skids.
- Chemical Processing:Chlor-alkali and petrochemical operations specify super duplex stainless steel crystallizer vessels for corrosive brine handling.
Specification intensity peaks in electronics; standardization opportunities concentrate in general manufacturing.
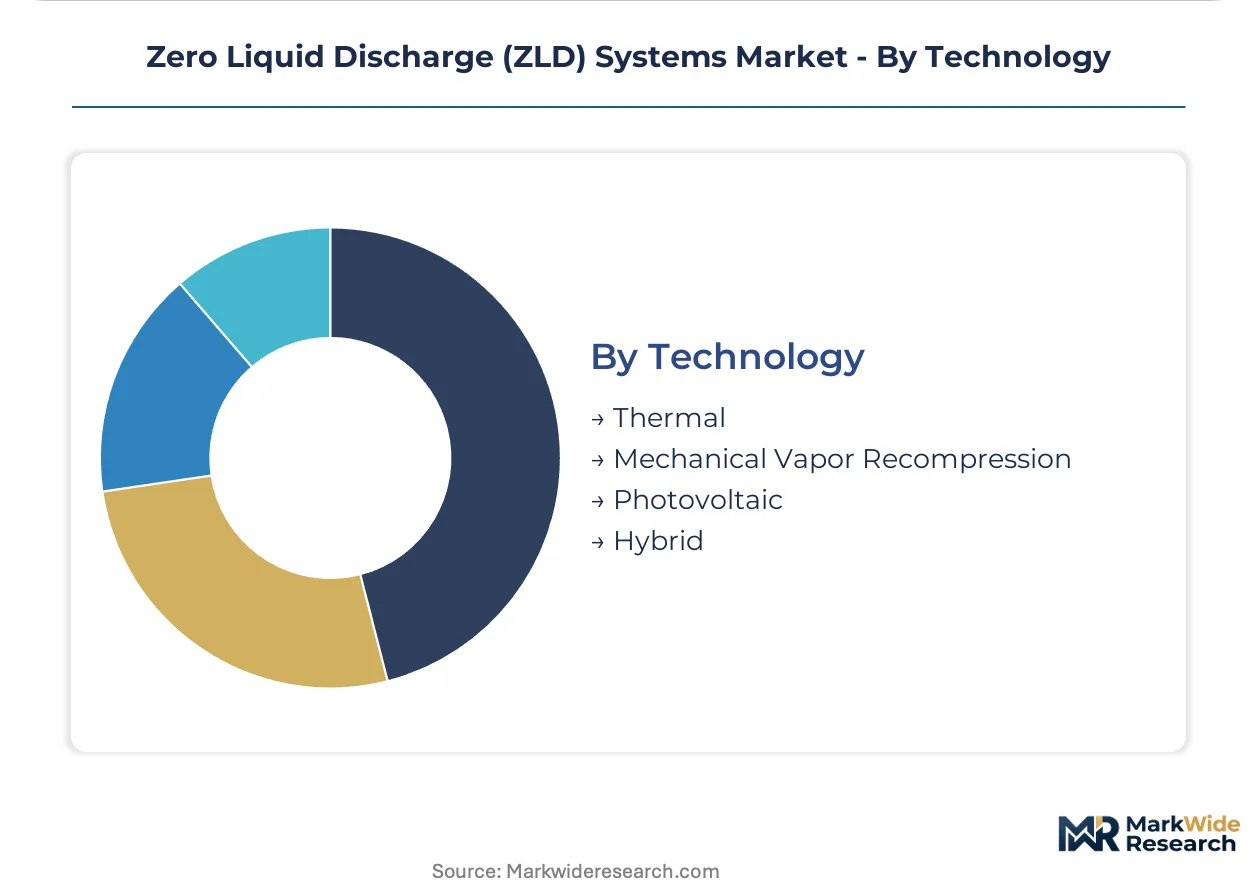
Technology:
Maturity gradient separates proven thermal evaporation from emerging photovoltaic-thermal integration.
- Thermal:Fossil-fired steam or waste heat-driven evaporation crystallization commands the largest installed base across coal-fired power and refinery applications.
- Mechanical Vapor Recompression:Electrically driven compression of vapor for heat recovery offers lower opex than thermal evaporation for feeds below 150,000 ppm TDS.
- Photovoltaic:Solar-thermal collectors paired with membrane distillation modules enable off-grid ZLD deployment in water-stressed regions without reliable electricity infrastructure.
- Hybrid:Integrated membrane-thermal trains optimize energy consumption by matching separation technologies to salinity thresholds across concentration stages.
Technology selection hinges on energy pricing, waste heat availability, and grid reliability at specific installation sites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between thermal-intensive markets where waste heat integration dominates and solar-hybrid territories where photovoltaic-thermal configurations are displacing conventional evaporation trains.
United States
Coal-fired power retrofits and refinery wastewater recovery anchor demand volumes. The EPA enforces effluent limitation guidelines prohibiting liquid discharge from specific coal-fired operations. Texas Gulf Coast and Louisiana chemical processing clusters specify super duplex stainless steel crystallizer vessels for corrosive brine handling.
China
Shandong and Jiangsu chemical corridors face accelerated membrane distillation retrofit cycles under tightening wastewater mandates. The Ministry of Ecology and Environment implements dual carbon goals that tighten industrial wastewater reuse rates. Yangtze River Delta electronics manufacturing hubs demand ultrapure water recovery with parts-per-trillion contaminant rejection.
India
New thermal capacity exceeding 500 MW must achieve zero effluent discharge under Central Electricity Authority mandates. Tiruppur and Surat textile belts concentrate dye bath recovery and salt reuse applications. Gujarat and Maharashtra industrial corridors procure multi-effect distillation trains for guaranteed compliance corridors.
Saudi Arabia
Jubail and Yanbu industrial city build-outs specify advanced water recovery infrastructure for decade-long service contracts. Refinery operators separate process guarantees from long-term membrane replacement agreements. Photovoltaic-thermal hybrid configurations in desert deployments displace conventional thermal trains for refinery wastewater recovery.
Germany
EU Green Deal industrial emissions frameworks tighten discharge limits for chemical processing clusters. REACH chemical safety registrations require mass-balance documentation for salt recovery streams. German regulators now force crystallizer vendors to certify residue purity grades through in-house analytical validation.
Zero Liquid Discharge (ZLD) Systems Market Vendor Landscape
Capability concentration sits with thermal process engineering specialists; scale advantage sits with diversified water technology conglomerates. The market structure segments into three tiers: integrated system suppliers with crystallization and membrane expertise, pure-play thermal equipment fabricators, and regional EPC contractors assembling third-party components. Strategic moves center on hybrid technology licensing partnerships and long-term service contract unbundling from equipment-only sales.
Among the integrated tier, Evoqua Water Technologies LLC and Veolia Water Technologies occupy positions as full-service providers spanning thermal and membrane process trains. GEA Group Aktiengesellschaft exemplifies the thermal equipment archetype with evaporation crystallization module manufacturing scale. Praj Industries Ltd represents the hybrid specialist segment with integrated bioethanol and wastewater system portfolios.
| Leading Market Players |
|---|
| Evoqua Water Technologies LLC |
| Praj Industries Ltd |
| GEA Group Aktiengesellschaft |
| H2O GmbH |
| IDE Technologies |
| Aquatech International LLC |
| Aquarion AG |
| Alfa Laval |
| Veolia Water Technologies |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Nordic and Japanese super duplex stainless steel suppliers compresses project timelines and widens pricing tier spreads between premium crystallizer configurations and standardized membrane skids. This metallurgical chokepoint forces buyers to commit to long-lead procurement schedules or absorb spot-market premiums, directly shaping how supply chain risk allocates across EPC contracts and equipment-only sales.
Pricing Analysis
Geographic price spreads separate Indian thermal power installations under CEA mandates from Middle Eastern refinery deployments with unbundled service contracts. Project-based pricing dominates, with after-sales bundling versus equipment-only sales representing the primary differentiation driver alongside super duplex steel grade certification. Cost compression in standardized membrane skids is intensifying because photovoltaic-thermal hybrid configurations displace thermal crystallization in moderate-salinity applications. Municipal and small-scale industrial buyers exhibit highest price sensitivity; semiconductor fabricators and lithium brine operators demonstrate lowest sensitivity due to hazardous constituent recovery requirements.
Supply Chain Analysis
Export-control regimes on advanced membrane distillation module manufacturing equipment limit technology transfer to certain jurisdictions, constraining localization efforts in emerging markets. Supply concentrates in Germany, Japan, and the United States for precision-engineered crystallizer vessels and high-performance membrane modules. Production draws from super duplex stainless steel billets, specialized ceramic membranes, and photovoltaic-thermal collector arrays. Single-source vulnerability in Nordic metallurgical suppliers exposes project timelines to allocation delays. Distribution runs through EPC contractors for large-scale power and refinery deployments, with direct OEM relationships dominating aftermarket membrane and chemical supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as procurement unbundling separates process guarantees from long-term service agreements, creating niches for specialized membrane and chemical suppliers alongside integrated system vendors.
For Market Incumbents: Pre-empt mechanical vapor recompression substitution in chemical processing below 150,000 ppm TDS by accelerating hybrid system certifications and anchoring long-term service contracts in Saudi giga-projects. Backward integration into super duplex steel billet sourcing mitigates Nordic supplier allocation risk. Thermal process engineering talent scarcity constrains simultaneous large-scale deployment capacity; secure specialist teams through acquisition or exclusive contracting. For New Entrants and Emerging Players: Pursue lithium brine extraction ZLD finishing trains as battery mineral investment converges with water recovery demand. India's Tiruppur and Surat textile belts represent penetrable territory for standardized dye bath recovery skids with salt reuse modules. Go-to-market through regional EPC partnerships bypasses incumbent direct sales relationships. For Investors and Strategic Acquirers: India's CEA thermal mandate reshapes the acquisition landscape by guaranteeing decade-long demand corridors for multi-effect distillation procurement. Long-term viability centers on hybrid technology portfolios spanning membrane and thermal process trains. Acquisition target archetype: mid-cap crystallizer specialists with in-house brine chemistry expertise and existing CEA-compliant reference installations. Signal to watch: MEE enforcement intensity across Shandong and Jiangsu chemical clusters as indicator of membrane distillation retrofit cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Technology Licensing Partnership | Photovoltaic-thermal configurations displace conventional thermal trains in Saudi refinery deployments. |
| Super Duplex Steel Backward Integration | In-house billet sourcing insulates crystallizer manufacturing from Nordic supplier allocation delays. |
| Long-term Service Contract Unbundling | Saudi Aramco and ADNOC procurement models fragment vendor relationships toward recurring revenue pools. |
| Thermal Process Engineering Talent Acquisition | Crystallizer design expertise concentrates among aging specialists, constraining execution capacity. |
| Lithium Brine Extraction ZLD Integration | Direct lithium extraction waste streams position crystallization vendors at battery mineral nexus. |
Methodological Framework
Operator-level perspectives from thermal power plant engineers, refinery wastewater managers, crystallizer design specialists, and EPC procurement leads anchored the qualitative base. Primary interviews combined with secondary validation from EPA effluent limitation guidelines, CEA thermal mandate circulars, MEE wastewater reuse directives, and SEC filings of listed water technology providers. Bottom-up installation tracking across power generation, chemical processing, and electronics manufacturing facilities triangulated with top-down market sizing from trade customs data and industrial water treatment expenditure surveys.
Scenario-bracketing framed the analytical approach across the projection horizon, with regulatory enforcement intensity and energy price volatility as sensitivity dimensions. Segmentation dimensions modeled include system architecture type, salinity threshold, end-use industry, waste heat availability, and regional regulatory framework. CAGRs derived from installed base evolution and replacement cycle analysis incorporated photovoltaic-thermal hybrid adoption curves and mechanical vapor recompression substitution thresholds.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, specialty alloy commodity costs, or solar equipment tariffs would shift the trajectory. Forecasts reflect assumptions around regulatory enforcement continuity and technology cost reduction curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market
Water and Wastewater Treatment
Water Aeration System Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Mobile Wastewater Treatment Plant Market
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Javelle Water Market
Water and Wastewater Treatment
Global Wastewater Diffused Aerator Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Sewage Treatment Service Market