
 Commercial Atmospheric Water Generator Market | 2026-2036
Commercial Atmospheric Water Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Atmospheric Water Generator Market Insights
Direct-to-commercial distribution channels is reconfiguring as manufacturers bypass traditional water equipment distributors to serve enterprise buyers directly. Watergen leverages its technology leadership in cooling condensation systems to command premium positioning in fixed installations. SkyWater Air Water Machines anchors its presence in the mobile and disaster relief segments through specialized product engineering. Dew Point Manufacturing competes on manufacturing scale, sustaining cost advantages in high-volume commercial orders.
A commercial atmospheric water generator extracts potable water from ambient air through thermodynamic processes, typically achieving extraction rates of 50 to 10,000 liters per day depending on relative humidity and temperature conditions. The device serves commercial end users requiring decentralized, off-grid water supply without dependence on groundwater or municipal infrastructure. Cooling condensation technology dominates current installations due to its maturity and predictable performance across varied climates, while desiccant-based systems are gaining traction in arid environments where humidity drops below 30 percent. The hospitality end-user segment represents the most concentrated margin pool as hotels and resorts prioritize brand-aligned sustainability credentials, whereas disaster relief applications drive volume through government and NGO procurement cycles despite thinner margins.
EPA energy efficiency standards and state-level water stress declarations in California and Arizona shape product certification requirements and accelerate replacement cycles for inefficient legacy equipment. ISO 14001 environmental management frameworks increasingly filter into commercial procurement specifications, particularly for hospitality and agriculture buyers with stated sustainability targets. Stakeholders must monitor evolving state-level water rights regulations and utility tariff structures that could either subsidize or penalize atmospheric water extraction relative to conventional sources.
Market Dynamics
Cooling condensation technology maturation is compressing unit economics while EPA energy efficiency mandates force premature replacement of legacy commercial water extraction equipment.
Growth Catalysts
- California water stress declarations:State-level drought emergencies trigger enterprise procurement of decentralized atmospheric water systems for hospitality and agriculture operations.
- Desiccant-based extraction advancement:Improved sorbent materials enable viable operation below 30% relative humidity, unlocking arid climate deployment previously unreachable by condensation methods.
- Hospitality sustainability frameworks:ISO 14001 certification requirements and brand-aligned ESG targets drive premium positioning for atmospheric water generators in resort and hotel procurement specifications.
Market Restraints
- Refrigerant cost volatility:F-Gas Regulation phase-down schedules in Europe and EPA SNAP restrictions in the United States elevate cooling system input costs and compress manufacturer margins.
- Power infrastructure dependency:High electricity consumption per liter extracted ties operational viability to regional utility tariff structures, disadvantaging markets with penalizing commercial electricity rates.
- Municipal water subsidy persistence:Artificially suppressed conventional water pricing in drought-prone jurisdictions delays commercial payback calculations and defers capital deployment.
Strategic Opportunities
- Disaster relief procurement cycles:FEMA and NGO emergency response frameworks create predictable volume demand for mobile atmospheric water units with rapid deployment specifications.
- Agriculture irrigation integration:Controlled-environment agriculture operators in water-stressed regions seek hybrid systems combining atmospheric extraction with precision irrigation.
- Direct-to-enterprise distribution:Manufacturers bypassing traditional water equipment distributors capture margin and accelerate specification influence with facility managers and sustainability officers.
Industry Challenges
- Thermodynamics engineering talent scarcity:Specialized expertise in psychrometric system design and refrigerant cycle optimization concentrates among a limited pool of HVAC veterans and academic researchers.
- Certification timeline compression:EPA ENERGY STAR and state-level water quality certifications require extensive third-party testing, delaying product launch windows and freezing development capital.
- Legacy building integration complexity:Retrofit installations in existing commercial structures face spatial constraints, electrical capacity limitations, and HVAC system incompatibility requiring costly customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Atmospheric Water Generator Market |
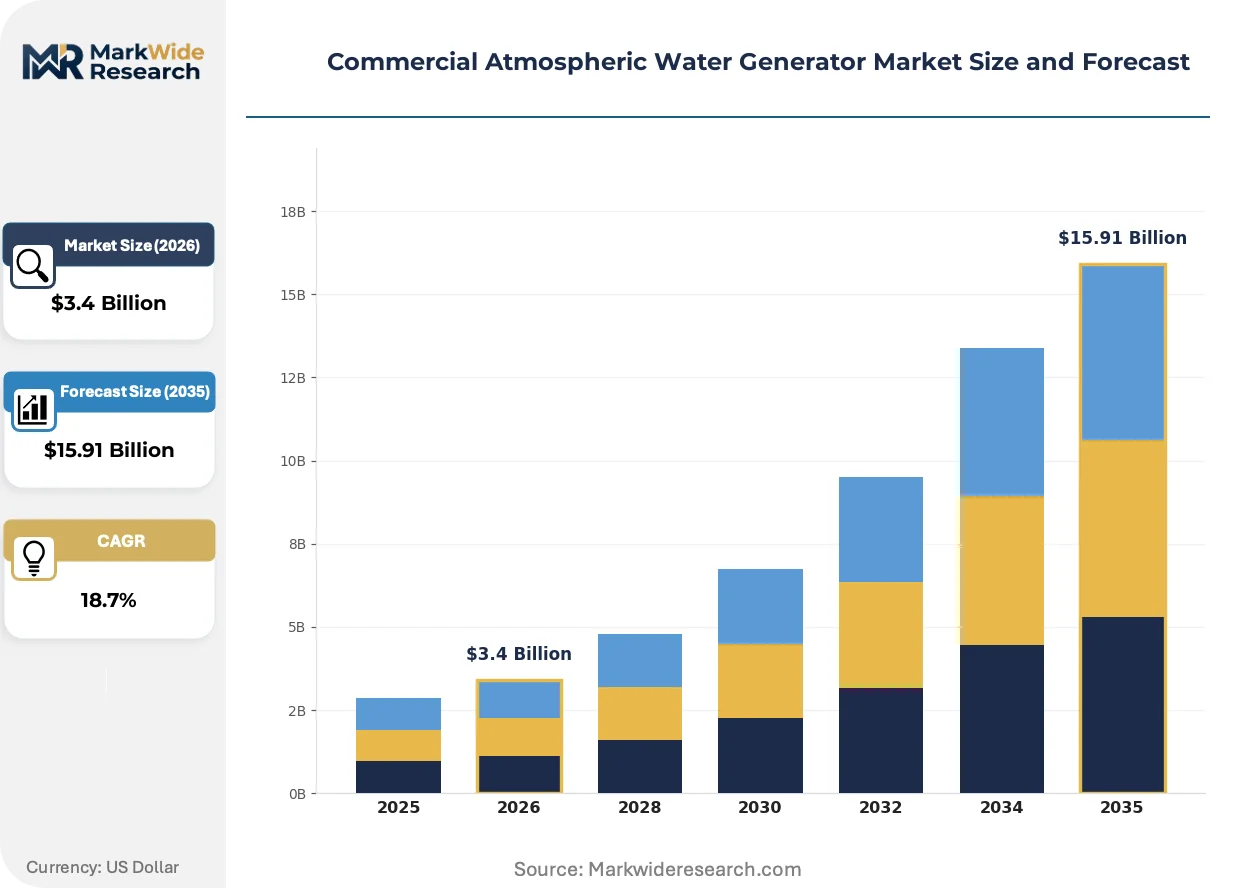
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $15.91 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Industrial, Portable, Commercial Technology: Cooling Condensation, Desiccant-Based, Hybrid, Membrane End User: Hospitality, Agriculture, Disaster Relief, Military Installation: Fixed, Mobile, On-Site, Off-Grid |
| Companies Covered | Akvo Atmospheric Water Systems Pvt. Ltd., Dew Point Manufacturing, Ray Agua, WaterMaker India Pvt. Ltd., PlanetsWater, Water Technologies International, Inc., SkyWater Air Water Machines, Drinkable Air, Watergen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Atmospheric Water Generator Market Trends and Innovations
Three simultaneous vectors are compressing commercial atmospheric water generator deployment timelines: thermodynamic efficiency breakthroughs, tightening environmental compliance frameworks, and procurement authority migration from facilities managers to sustainability executives.
Solid-state desiccant wheels with hygroscopic polymer coatings are rendering obsolete traditional compressor-based cooling condensation in sub-40% humidity environments. Controlled-environment agriculture operators in Arizona and Nevada are specifying these systems for greenhouse humidity management coupled with water extraction. The technology is rendering obsolete the geographic limitation that previously confined atmospheric water viability to coastal and tropical markets.
EPA SNAP program restrictions on high-GWP refrigerants are accelerating cooling system redesigns across commercial equipment categories. Manufacturers face mandatory transition to low-global-warming-potential alternatives with inferior thermodynamic properties, necessitating heat exchanger redesign and capacity derating. California and Arizona procurement specifications now exclude pre-2024 refrigerant technologies from state-funded installations.
Sustainability officers are displacing facilities managers as primary specification authorities in hospitality and corporate real estate procurement. Enterprise buyers now bundle atmospheric water generators with renewable energy certificates and carbon accounting disclosures rather than evaluating standalone utility cost savings. This authority migration is most visible in California resort developments where brand-level water neutrality commitments override traditional capex payback thresholds.
Commercial Atmospheric Water Generator Market Segmentation
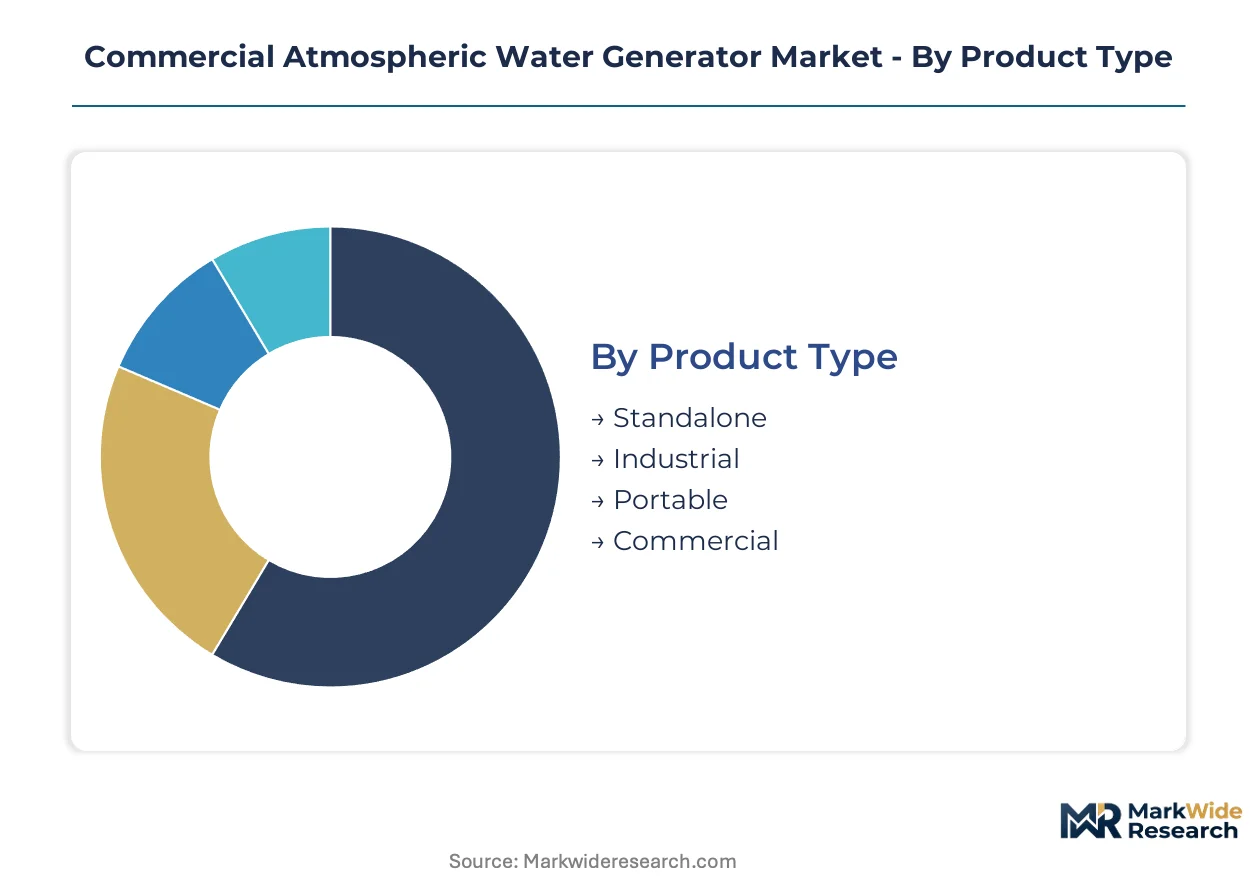
Commercial atmospheric water generator deployment patterns diverge sharply across product configurations, extraction methods, and operational contexts. Understanding these segment boundaries clarifies where capital concentrates and which specifications command premium positioning.
Product Type:
Cost tier structures the competitive landscape, with capital intensity and operational scale determining procurement authority and margin capture.
- Standalone:Self-contained units operate without external infrastructure, typically extracting 500-2,000 liters daily for mid-sized commercial facilities. Demand concentrates in California boutique hotels seeking LEED certification without utility dependency.
- Industrial:High-capacity systems achieve 10,000+ liter daily output through modular array configurations. Arizona agriculture operators in Yuma and Imperial Valleys deploy these for greenhouse irrigation, driven by state water stress declarations and falling groundwater allocations.
- Portable:Compact units under 500 liters suit rapid deployment scenarios.
- Commercial:Mid-range systems serve retail and office installations with moderate humidity requirements.
Industrial holds installed capacity. Standalone is rotating up the share rankings.
Technology:
Application suitability varies with ambient humidity, energy access, and water quality specifications.
- Cooling Condensation:Compressor-driven refrigeration cycles condense atmospheric moisture on cooled coils, achieving predictable output above 40% relative humidity. The technology dominates current installations across the United States due to maturity and service infrastructure density.
- Desiccant-Based:Hygroscopic sorbent materials capture moisture at humidity levels below 30%, enabling viable extraction in arid climates previously inaccessible. Nevada and Arizona operators are specifying these for desert agriculture and remote mining camps.
- Hybrid:Combined cooling and desiccant stages optimize across variable humidity conditions.
- Membrane:Selective permeability barriers separate water vapor without phase change, reducing energy intensity.
Cooling Condensation anchors current deployment. Desiccant-Based is climbing the fastest.
End User:
Customer type determines specification complexity, procurement cycle length, and sustainability disclosure requirements.
- Hospitality:Hotels and resorts prioritize brand-aligned water neutrality credentials over pure utility economics. California coastal properties lead specification activity, bundling atmospheric water with renewable energy certificates for guest-facing sustainability narratives.
- Agriculture:Controlled-environment operators in water-stressed regions seek extraction-to-irrigation integration. Arizona greenhouse clusters specify hybrid systems combining atmospheric water with precision fertigation, responding to Colorado River shortage declarations.
- Disaster Relief:FEMA and NGO procurement frameworks create volume demand for mobile units with rapid deployment specifications.
- Military:Forward operating base requirements drive ruggedized, off-grid capable designs with minimal logistics footprint.
Hospitality commands premium positioning. Agriculture is gaining share fastest.
Installation:
Volume and mobility requirements shape system architecture and distribution channel configuration.
- Fixed:Permanent installations integrate with building HVAC and electrical infrastructure, serving as primary water supply for new construction. California resort developments in drought-designated counties specify these for water independence compliance.
- Mobile:Trailer-mounted or skid-based units relocate between sites, serving construction camps and temporary events. Arizona mining operations lease these for workforce housing in remote locations lacking municipal connections.
- On-Site:Systems operate at the point of consumption without distribution networks.
- Off-Grid:Solar-coupled configurations eliminate utility dependency entirely.
Fixed holds installed base. Mobile is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in drought-designated US states while European markets face refrigerant cost compression from F-Gas Regulation phase-down schedules. Deployment velocity diverges sharply between jurisdictions with active water stress declarations and those maintaining subsidized municipal supply.
United States
California and Arizona drive enterprise procurement through state-level drought emergencies and Colorado River shortage declarations. EPA SNAP restrictions on high-GWP refrigerants force cooling system redesigns, compressing manufacturer margins. Yuma and Imperial Valley agriculture clusters deploy industrial-scale desiccant systems for greenhouse irrigation.
Australia
Controlled-environment agriculture operators in water-stressed regions seek atmospheric extraction for irrigation independence. The country's national environmental regulator enforces refrigerant management standards aligned with global phase-down commitments. New South Wales mining camps specify mobile units for remote workforce housing.
United Arab Emirates
Hospitality developments in Dubai and Abu Dhabi bundle atmospheric water with renewable energy certificates for guest-facing sustainability narratives. The federal environmental authority mandates building efficiency standards that favor decentralized water systems. NEOM Northwest integrates fixed installations into smart city infrastructure planning.
India
Commercial facilities in water-scarce states deploy standalone units to bypass unreliable municipal supply. The Bureau of Indian Standards certifies water quality and energy performance for commercial equipment. Maharashtra and Gujarat industrial zones pilot hybrid systems for manufacturing process water.
Saudi Arabia
Resort developments in the Western Region specify atmospheric water to meet brand-level water neutrality commitments. The national food and drug authority regulates potable water quality from non-conventional sources. Riyadh commercial real estate procurement increasingly requires ISO 14001-aligned sustainability disclosures.
Commercial Atmospheric Water Generator Market Competitive Landscape
Technology specialists and manufacturing-scale operators split the market into distinct competitive spheres. The vendor base concentrates around cooling condensation expertise and desiccant material science capabilities. Three archetypes dominate: thermodynamic engineering houses, volume fabricators with cost advantages, and integrated solution providers bundling hardware with service contracts. Capacity expansion and direct-to-enterprise distribution channels represent the dominant competitive moves.
Within the engineering-specialist tier, Watergen and SkyWater Air Water Machines exemplify divergent strategic positioning. Watergen anchors premium fixed-installation specifications through cooling condensation leadership. SkyWater occupies the mobile and disaster relief vector with rapid-deployment product architectures. Dew Point Manufacturing represents the scale-driven archetype, sustaining cost advantages in high-volume commercial orders through manufacturing efficiency.
| Leading Market Players |
|---|
| Akvo Atmospheric Water Systems Pvt. Ltd. |
| Dew Point Manufacturing |
| Ray Agua |
| WaterMaker India Pvt. Ltd. |
| PlanetsWater |
| Water Technologies International, Inc. |
| SkyWater Air Water Machines |
| Drinkable Air |
| Watergen |
| Others |
Pricing and Supply Chain Analysis
Long Beach Port freight corridors carry refrigerant compressors and hygroscopic sorbent materials from East Asian manufacturing hubs to Arizona and California assembly facilities, with container cost volatility compressing margins on standard units while configured-to-order industrial systems command 40-60% premiums through bypass distribution.
Pricing Analysis
Configured-to-order pricing spreads 35-50% above standard SKUs for industrial-scale desiccant arrays with site-specific humidity calibration. Three-tier pricing structure across premium, standard, and economy levels separates EPA ENERGY STAR-certified hospitality units from uncertified commercial models and portable disaster relief configurations. Price differentiation hinges on ISO 14001 environmental management documentation and bundled after-sales service contracts. Cost compression in standard cooling condensation tiers is intensifying because F-Gas Regulation phase-down schedules elevate refrigerant input costs. Agriculture buyers in Yuma and Imperial Valleys exhibit highest price sensitivity due to thin commodity margins, while California resort developers show lowest sensitivity when sustainability disclosure requirements are embedded in brand mandates.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn Industrial Internet, Jabil, and Flex holding capacity for compressor assembly and control system integration in Mexico, China, and Vietnam. Geographic supply concentration centers on China for rare-earth desiccant substrates and precision-machined heat exchangers, South Korea for variable-speed compressor motors, and Germany for refrigerant management valves. Raw material dependencies rest on lithium chloride sorbent compounds, copper tubing for cooling coils, and low-GWP refrigerant blends subject to EPA SNAP allocation quotas. Single-source vulnerability runs through Chinese rare-earth processing for advanced desiccant formulations. Distribution runs through direct-to-enterprise channels for hospitality and agriculture verticals, with traditional water equipment distributors retaining disaster relief and municipal procurement routes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from predictive maintenance contracts and water quality monitoring subscriptions is expanding faster than hardware unit sales, with annual recurring revenue per installed unit approaching 15-20% of original equipment value in hospitality deployments.
For Market Incumbents: Harden defensive positions by securing captive supply of low-GWP refrigerant alternatives through backward integration into refrigerant reclamation facilities in Texas and Louisiana, and accelerate EPA ENERGY STAR certification timelines to exclude pre-2024 technology competitors from California state-funded installations. Desiccant material science startups in Israel and Australia pose emerging substitution threats to cooling condensation incumbents. For New Entrants and Emerging Players: Establish a beachhead in Arizona controlled-environment agriculture by offering hybrid cooling-desiccant systems with integrated fertigation controllers, bypassing established distributor relationships through direct sales to greenhouse operators in Yuma and Maricopa counties. The agriculture segment shows lowest incumbent loyalty and fastest specification turnover among commercial end users. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors desiccant material science specialists with patented sorbent formulations over compressor-dependent hardware fabricators, as solid-state extraction renders obsolete geographic humidity limitations. Long-term viability across the analysis window rests on regulatory tailwinds from water stress declarations rather than commodity cost advantages. Acquisition target archetype: mid-scale desiccant technology holders with Arizona or Nevada reference installations. The signal to watch is EPA refrigerant allocation quota tightening, which would accelerate stranded asset risk in cooling condensation capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Desiccant Material Patent Acquisition | Secures sorbent formulation IP that unlocks sub-30% humidity operation in Arizona and Nevada desert applications. |
| Direct-to-Enterprise Distribution Buildout | Bypasses traditional water equipment distributors to capture margin and accelerate specification influence with California sustainability officers. |
| EPA ENERGY STAR Certification Acceleration | Excludes pre-2024 refrigerant technology competitors from state-funded installations in drought-designated counties. |
| Refrigerant Reclamation Facility Investment | Captures supply of low-GWP alternatives amid EPA SNAP allocation constraints and F-Gas Regulation phase-down schedules. |
| Hybrid System Development Partnership | Combines cooling condensation with desiccant stages for variable humidity optimization in controlled-environment agriculture. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with atmospheric water generator engineering directors, hospitality sustainability officers, Arizona greenhouse operations managers, and EPA regulatory affairs specialists; and secondary validation through EPA SNAP refrigerant filings, California State Water Resources Control Board drought declarations, ISO 14001 certification databases, and customs records of compressor and desiccant material imports. Bottom-up unit deployment estimates triangulated against top-down market value reconstructions.
Forecast inputs considered cooling condensation technology maturation curves, desiccant material cost reduction trajectories, and state-level water stress declaration frequencies across the projection horizon. Segmentation dimensions modeled include product configuration tier, extraction technology type, end-user vertical, installation mobility class, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to early-adopter penetration patterns in California hospitality and Arizona agriculture, with cross-validation against utility tariff elasticity assumptions and municipal water subsidy persistence scenarios.
Macroeconomic conditions sit as an overlay; deviation in commercial electricity rate structures, rare-earth commodity prices, or EPA refrigerant allocation policies would shift the trajectory. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory enforcement intensity. Quarterly review of state-level water stress declarations, FEMA disaster relief procurement awards, and EPA SNAP refrigerant quota announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Wastewater Screening Equipment Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Mobile Wastewater Treatment Plant Market
Water and Wastewater Treatment
Sewage Pump Market
Water and Wastewater Treatment
Backwash Pre-Filters Market
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
Water Aeration System Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Sewage Treatment Service Market
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market