
 Solar Water Purifiers Market | 2026-2036
Solar Water Purifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Water Purifiers Market Analytics
The capital-intensity divergence between photovoltaic-integrated manufacturers and conventional filtration specialists is rotating competitive advantage toward firms with captive solar cell supply. LONGi Green Energy Technology leverages its upstream polysilicon dominance to control module costs for purification systems. JinkoSolar anchors its position through high-efficiency PERC cell integration with reverse-osmosis units. Kent RO Systems differentiates via established channel density in emerging economies where after-sales service determines repeat procurement.
Solar water purifiers combine photovoltaic energy generation with physical or chemical treatment processes—typically incorporating membrane filtration rated to 0.01 micron pore size or UV-C sterilization at 254 nanometer wavelength—to produce potable water without grid dependency. Stand-Alone Units dominate current deployment volumes due to minimal installation complexity, while Hybrid Systems command the strongest margin pools as they pair solar generation with battery storage and multi-stage filtration. Photocatalytic Filtration occupies a nascent but expanding position where titanium dioxide catalysts enable contaminant breakdown without consumable filter replacement.
India's BIS and CDSCO frameworks mandate microbiological safety testing for solar purification devices sold through government rural health programs. The EPA in the United States enforces Safe Drinking Water Act compliance for imported systems, while WHO guidelines on solar disinfection set the baseline for NGO procurement tenders across humanitarian corridors. Stakeholders must monitor how national renewable energy agencies fold water purification into distributed generation subsidy schemes, as this integration determines effective end-user pricing and deployment velocity.
Market Dynamics
Capital allocation in solar water purification is pivoting toward captive polysilicon supply as module cost volatility compresses margins for assemblers without upstream integration.
Growth Catalysts
- India's BIS certification tightening:The Bureau of Indian Standards is mandating stricter microbiological testing for rural health program procurement, filtering out low-grade imports and creating demand for certified domestic production.
- Photocatalytic titanium dioxide advancement:Catalyst-driven contaminant breakdown eliminates consumable filter replacement cycles, reducing lifetime operating costs for remote installations in sub-Saharan Africa.
- Off-grid solar infrastructure deployment:Kenya, Ethiopia, and Tanzania are witnessing accelerated stand-alone unit adoption where acute water scarcity intersects with distributed photovoltaic rollout.
Market Restraints
- Polysilicon supply concentration:Upstream ingot and wafer production clusters in Xinjiang and Inner Mongolia create geopolitical exposure for module assemblers without diversified sourcing.
- Reverse osmosis membrane cost structure:Thin-film composite polyamide elements remain import-dependent for most regional manufacturers, exposing margins to petrochemical feedstock volatility.
- UV-C LED wavelength stability:Germicidal efficacy at 254 nanometer output degrades faster than mercury-vapor alternatives in high-temperature operating environments, limiting deployment latitude.
Strategic Opportunities
- Battery-integrated hybrid systems:Pairing lithium iron phosphate storage with multi-stage filtration commands premium positioning in institutional procurement where 24-hour potable water availability is mandatory.
- CE marking pathway expansion:The EU Green Deal's circular economy requirements are creating certification arbitrage for manufacturers who design modular, field-serviceable components ahead of competitors.
- Humanitarian corridor NGO tenders:WHO solar disinfection guidelines are becoming mandatory evaluation criteria for UNHCR and Red Cross procurement frameworks across the Sahel and Horn of Africa.
Industry Challenges
- Field technician certification gaps:After-sales service density in emerging economies determines repeat procurement, yet membrane replacement and electrical fault diagnosis require trained personnel absent in rural Kenya and Tanzania.
- Multi-agency compliance timelines:India's CDSCO microbiological safety testing runs parallel to BIS electrical safety certification, extending product launch cycles by eight to fourteen months for imported systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Water Purifiers Market |
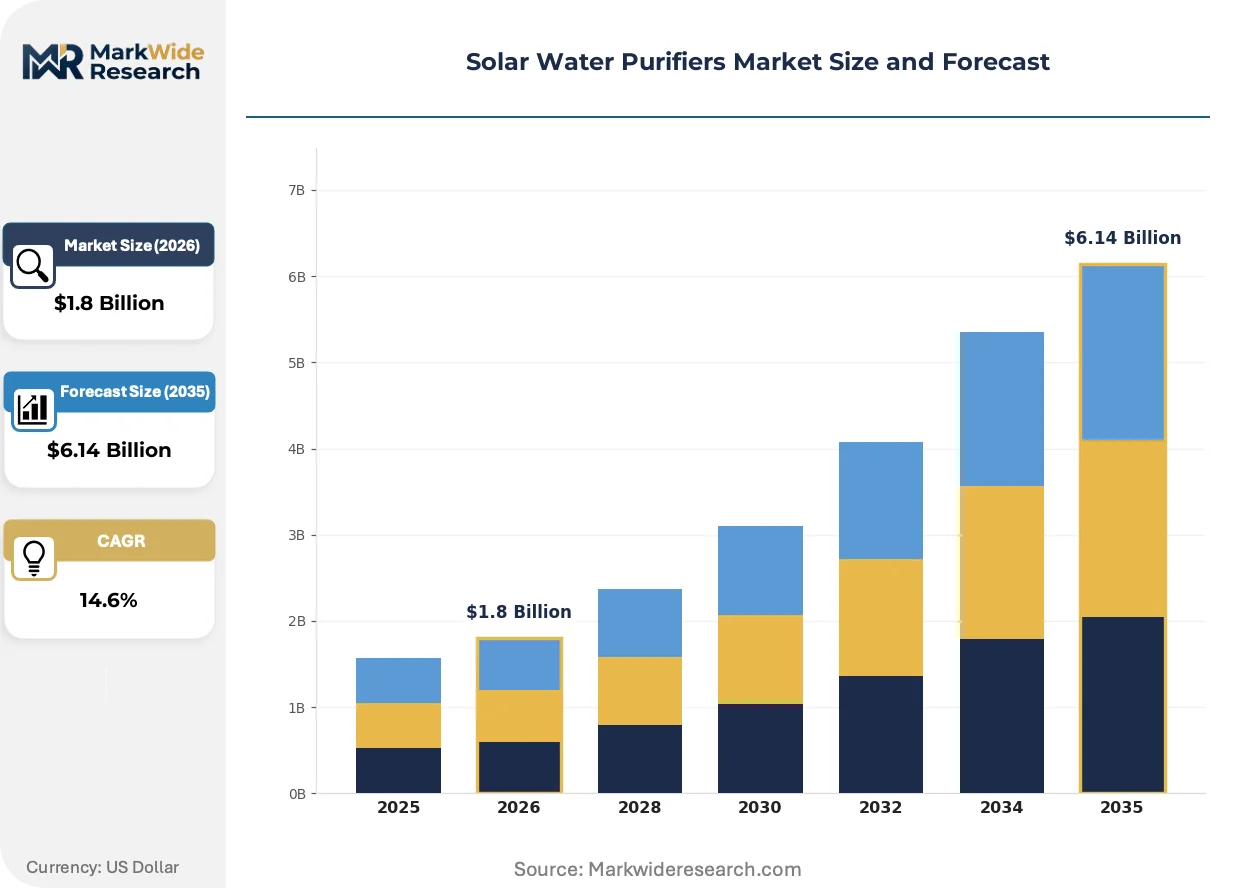
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Alone Units, Solar Powered Systems, Hybrid Systems, Portable Purifiers Technology: Solar Distillation, UV Purification, Photocatalytic Filtration, Membrane Filtration End User: Households, NGOs, Rural Communities, Disaster Relief Agencies Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | LONGi Green Energy Technology, A.O. Smith Corporation, JinkoSolar, Kent RO Systems, Culligan International Company, JA Solar, Tongwei Solar, LG Electronics, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Water Purifiers Market Evolving Landscape
Technology convergence between high-efficiency photovoltaic cells and advanced filtration membranes is compressing system footprints while elevating performance benchmarks for off-grid deployment.
Photocatalytic titanium dioxide catalysts integrated with UV-LED arrays are displacing conventional membrane-replacement schedules in remote installations. Aid organizations operating across Ethiopia's lowland regions are piloting these systems for borehole water treatment. The elimination of consumable filter logistics is compressing total cost of ownership calculations for humanitarian procurement officers.
REACH substance restrictions on persistent organic pollutants are forcing membrane manufacturers to reformulate polyamide active layers. European importers now demand full material disclosure for thin-film composite elements. The compliance burden is accelerating supplier consolidation toward vertically integrated compounders with in-house polymer synthesis capabilities.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance contracts in India's rural health programs. State governments in Maharashtra and Gujarat are separating capital procurement from multi-year service agreements, enabling specialized regional operators to bid on maintenance tenders independently. This disintermediation is elevating channel density and technical response speed as competitive differentiators over upfront equipment pricing.
Solar Water Purifiers Market Segmentation
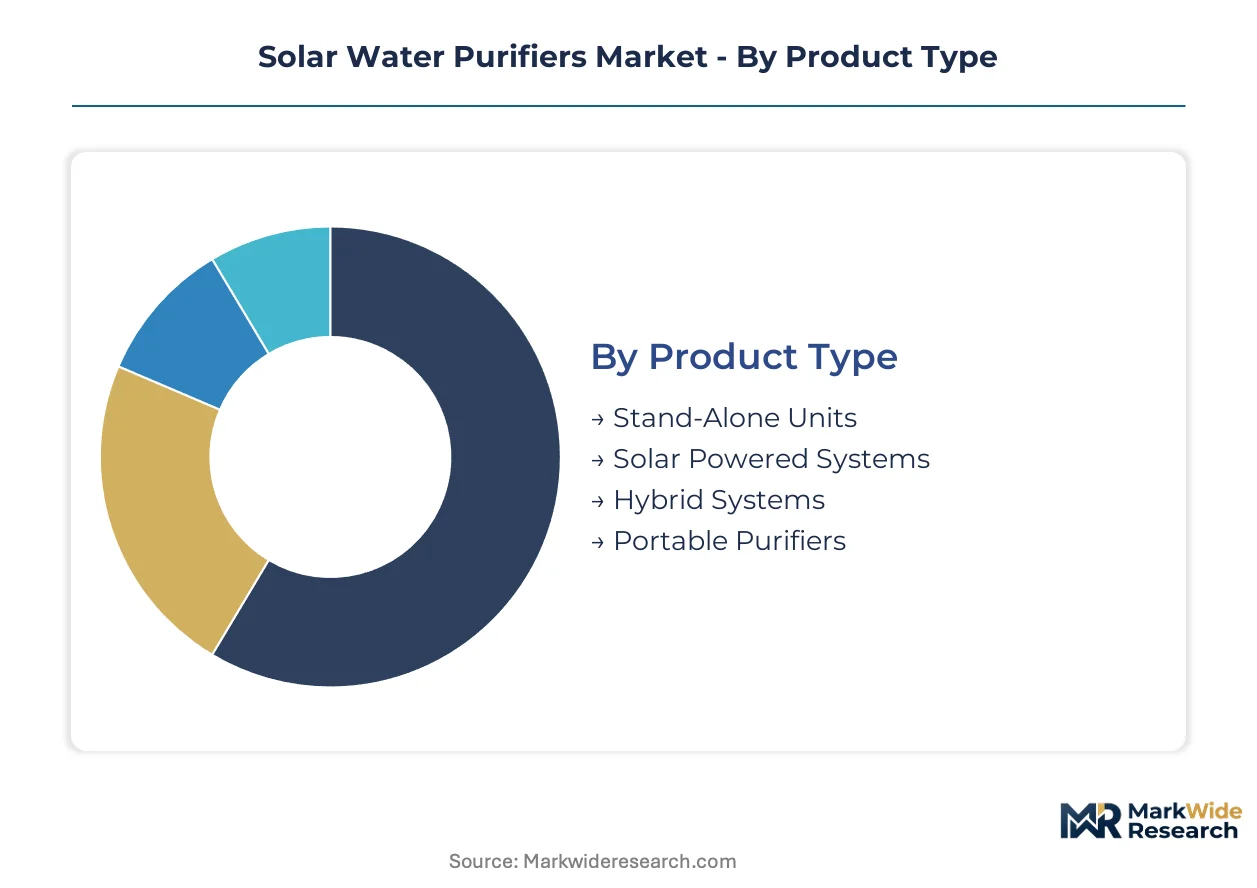
Channel economics in solar water purification diverge sharply between institutional procurement and retail distribution. Understanding which segments flow through which channels determines margin capture and working capital requirements for manufacturers.
Product Type:
Stand-Alone Units move primarily through government rural health tenders and NGO procurement frameworks, while Hybrid Systems concentrate in direct sales to institutional buyers requiring 24-hour operational continuity.
- Stand-Alone Units:Self-contained photovoltaic panels paired with single-stage filtration or UV-C sterilization rated for 1,000-5,000 liters daily output. Demand concentrates in Kenya's ASAL counties where county water departments issue decentralized procurement tenders for borehole-adjacent installations.
- Hybrid Systems:Multi-stage purification trains integrated with lithium iron phosphate battery storage and grid-tie capability for institutional resilience. Expansion concentrates in Ethiopia's lowland health centers where the Ministry of Health mandates uninterrupted potable water supply for surgical theaters.
- Solar Powered Systems:Modular panel arrays driving reverse-osmosis skids with containerized deployment options. Channel flow splits between UNHCR emergency tenders and commercial agricultural estates in Tanzania.
- Portable Purifiers:Backpack or cart-mounted units under 50 watts peak output for rapid deployment scenarios. Red Cross disaster response teams in the Sahel represent the core procurement channel.
Stand-Alone Units dominate installed base. Hybrid Systems are where expansion concentrates.
Technology:
Cost tiers separate mature membrane technologies from emerging photocatalytic approaches, with UV purification occupying the mid-market institutional segment.
- Membrane Filtration:Thin-film composite polyamide elements rated to 0.01 micron pore size for bacterial and viral exclusion. Thin-film composite polyamide elements rated to 0.01 micron pore size for bacterial and viral exclusion. Volume concentrates in India's BIS-certified rural health programs where membrane replacement logistics favor established supply chains.
- Photocatalytic Filtration:Titanium dioxide catalysts activated by UV-A irradiation enabling contaminant mineralization without consumable replacement. Titanium dioxide catalysts activated by UV-A irradiation enabling contaminant mineralization without consumable replacement. Pilots in Ethiopia's Afar region are eliminating filter logistics costs for borehole treatment at remote pastoralist settlements.
- UV Purification:Mercury-vapor or LED-based germicidal irradiation at 254 nanometer wavelength for flow-through sterilization. LED-based systems are gaining procurement share in Kenyan schools where mercury disposal regulations complicate maintenance.
- Solar Distillation:Passive evaporation-condensation cycles producing distilled water from brackish or contaminated sources. Niche deployment persists in coastal Tanzania where salinity exceeds membrane tolerance thresholds.
Membrane Filtration commands current revenue concentration. Photocatalytic Filtration is climbing the fastest.
End User:
Customer type determines specification rigor and payment security, with rural communities presenting working capital challenges absent from institutional accounts.
- Rural Communities:Village-level water committees managing shared infrastructure with partial government subsidy support. Payment reliability varies with county fiscal cycles in Kenya and Ethiopia.
- NGOs:Multilateral and faith-based organizations operating across humanitarian corridors with WHO guideline compliance requirements. Procurement cycles align with annual funding allocations and emergency response triggers.
- Households:Individual family units purchasing sub-100 liter daily capacity units through microfinance or pay-as-you-go models. Channel density in Maharashtra and Gujarat determines vendor selection.
- Disaster Relief Agencies:Rapid deployment units for conflict and climate emergency response with 72-hour activation requirements. UNHCR and Red Cross maintain pre-qualified supplier rosters with regional stockholding mandates.
Rural Communities anchor unit deployment volumes. NGOs are gaining share fastest.
Distribution Channel:
Supply concentration in module manufacturing clusters shapes which channels can support technical service requirements.
- Direct Sales:Manufacturer-to-institutional contracts with integrated installation and multi-year service agreements. Dominates hybrid system procurement for Ethiopian health infrastructure.
- Distributors:Regional stockholders providing inventory financing and field technician networks. Critical for Kenya's county-level tender fulfillment where response time determines contract awards.
- Online Retail:E-commerce platforms serving household segment with courier-delivered compact units. Growing share in Indian urban periphery where awareness precedes rural rollout.
- Specialty Stores:Physical retail with demonstration capability and basic maintenance support. Concentrated in Tanzanian commercial centers with expatriate and safari tourism demand.
Direct Sales captures premium-margin institutional volume. Distributors are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Indian domestic manufacturing while Kenyan import-dependent markets absorb margin compression from currency volatility and logistics costs. The divergence reflects India's BIS certification moat versus East Africa's fragmented tender administration.
India
Maharashtra and Gujarat host the densest channel networks for rural health program fulfillment. BIS electrical safety certification and CDSCO microbiological testing run in parallel, extending product launch cycles for imported systems. Domestic manufacturers in Pune and Ahmedabad exploit this compliance gap to capture county-level water department tenders.
Kenya
Arid and Semi-Arid Lands (ASAL) counties issue decentralized procurement for borehole-adjacent stand-alone units. County fiscal cycles create payment reliability challenges for vendors without established distributor financing relationships. Nairobi-based distributors with field technician networks dominate contract awards where response time determines selection.
Ethiopia
The Ministry of Health mandates uninterrupted potable water for lowland health center surgical theaters, driving hybrid system specifications. Pilots in Afar region deploy photocatalytic titanium dioxide systems to eliminate consumable filter logistics at remote pastoralist settlements. Addis Ababa procurement offices coordinate with UNHCR for emergency stockholding mandates.
Tanzania
Coastal salinity exceeding membrane tolerance thresholds preserves niche demand for solar distillation in Dar es Salaam periphery. Commercial agricultural estates in Arusha and Kilimanjaro regions source containerized reverse-osmosis skids through direct manufacturer contracts. Zanzibar's tourism corridor generates specialty store demand with demonstration capability requirements.
United States
EPA Safe Drinking Water Act compliance shapes import evaluation for humanitarian procurement officers based in Washington and Atlanta. Off-grid deployment concentrates in Southwest tribal lands and Puerto Rico where grid resilience intersects with water quality challenges. California's Title 24 building efficiency standards are beginning to incorporate solar-powered treatment for new rural construction.
Solar Water Purifiers Market Competitive Landscape
Concentration sits with photovoltaic-integrated manufacturers possessing captive polysilicon supply, while conventional filtration specialists defend position through channel density and after-sales service networks. The market structure tilts toward upstream integration as module cost volatility compresses assembler margins. Three archetypes dominate: polysilicon-to-module vertically integrated energy conglomerates, membrane-specialist water treatment incumbents, and hybrid-system integrators targeting institutional resilience requirements. Competitive moves center on backward integration into wafer production and geographic expansion through distributor financing partnerships in East African tender markets.
Among polysilicon-integrated conglomerates, LONGi Green Energy Technology and JinkoSolar occupy positions where upstream cost control translates into purification system pricing flexibility. Kent RO Systems exemplifies the channel-density archetype, with established service networks determining repeat procurement in emerging economies. These three anchors illustrate how competitive advantage rotates between cost structure and local presence depending on procurement channel.
| Leading Market Players |
|---|
| LONGi Green Energy Technology |
| A.O. Smith Corporation |
| JinkoSolar |
| Kent RO Systems |
| Culligan International Company |
| JA Solar |
| Tongwei Solar |
| LG Electronics |
| Trina Solar |
| Others |
Value Network & Pricing Analysis
Polysilicon ingot capacity utilization above 85 percent in Xinjiang and Inner Mongolia compresses module cost floors for photovoltaic-integrated manufacturers while stranding assemblers without captive wafer supply on thinner margins. This scale asymmetry concentrates pricing power with upstream-integrated conglomerates and forces second-tier competitors toward service bundling or regional certification arbitrage to defend position.
Pricing Analysis
Configured-to-order hybrid systems command 40-60 percent premiums over standard stand-alone units due to lithium iron phosphate battery integration and multi-stage membrane customization. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified institutional procurement from county-level tender fulfillment and household microfinance segments. Cost compression in economy tiers is intensifying because Kenyan import-dependent markets absorb currency volatility and logistics surcharges that domestic Indian manufacturers avoid. Rural community water committees exhibit highest price sensitivity, while Ethiopian Ministry of Health surgical theater mandates show lowest sensitivity due to 24-hour operational continuity requirements.
Supply Chain Analysis
Strategic stockpiling of thin-film composite polyamide membranes dominates procurement strategy among Kenyan distributors managing county tender fulfillment timelines, while Indian manufacturers maintain just-in-time polysilicon flows from captive ingot facilities. Module assembly concentrates in China, India, and Vietnam, with membrane chemistry anchored in the United States, Japan, and Germany. Raw material dependencies span metallurgical-grade silicon, lithium iron phosphate cathode materials, and titanium dioxide photocatalyst precursors. Single-source vulnerability in Xinjiang polysilicon exposes margin structures to geopolitical disruption. Distribution runs through regional stockholders with field technician networks in East African tender markets and direct manufacturer contracts for Ethiopian institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained field technician density in rural Kenya and Tanzania represents the binding constraint on after-sales service velocity, creating acquisition premiums for distributors with established certification programs and compressing valuations for equipment-only vendors unable to guarantee membrane replacement response times.
For Market Incumbents: Consolidate distributor financing relationships in Kenya's ASAL counties where county fiscal cycle payment delays threaten working capital for undercapitalized competitors. Deepen backward integration into wafer production to insulate module cost structures from Xinjiang supply concentration risk. Capture BIS certification moats in Maharashtra and Gujarat before CDSCO microbiological testing timelines extend further for imported systems. For New Entrants and Emerging Players: Differentiate on photocatalytic titanium dioxide technology to eliminate consumable filter logistics costs in Ethiopia's Afar region remote pastoralist settlements. Target humanitarian corridor NGO tenders where WHO solar disinfection guidelines are becoming mandatory evaluation criteria for UNHCR and Red Cross procurement frameworks. Pursue CE marking pathway expansion ahead of EU Green Deal circular economy modular design requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional distributors with multi-year service agreements separated from capital procurement in India's Maharashtra and Gujarat state programs. Long-term viability across the projection horizon favors acquisition targets combining lithium iron phosphate battery integration capability with established East African field technician networks. Signal to monitor: BIS certification tightening velocity and parallel CDSCO testing timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Ingot Production | Captive wafer supply insulates module cost structures from Xinjiang concentration risk. |
| Photocatalytic Titanium Dioxide R&D Partnership | Eliminates consumable filter replacement cycles for remote Ethiopian pastoralist installations. |
| Field Technician Certification Program Expansion | After-sales service density determines repeat procurement in Kenya's county tender markets. |
| BIS-CDSCO Parallel Certification Investment | Domestic manufacturing in Pune and Ahmedabad exploits compliance gaps for imported systems. |
| Lithium Iron Phosphate Battery Supply Agreement | Institutional hybrid system specifications mandate 24-hour operational continuity in Ethiopian health centers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with photovoltaic module procurement officers at health ministries, membrane replacement service technicians in Kenya's ASAL counties, lithium iron phosphate battery sourcing managers, and rural water committee treasurers managing pay-as-you-go models. Secondary validation drew from BIS certification registries, CDSCO microbiological testing disclosure filings, UNHCR pre-qualified supplier rosters, and county-level tender award databases in Kenya and Ethiopia. Bottom-up unit deployment estimates triangulated against top-down addressable population calculations across sub-Saharan Africa and South Asian rural health programs.
Across the analysis window, the forecasting framework modeled product type segmentation separating stand-alone units from hybrid systems and portable purifiers, technology tier differentiation between membrane filtration and photocatalytic approaches, end-user channel economics across rural communities and institutional procurement, and geographic regulatory cluster divergence between India's certification-moat markets and East Africa's import-dependent tender structures. CAGRs derived from installed base growth trajectories, replacement cycle compression, and subsidy scheme integration timelines. Industry-specific inputs included photovoltaic module cost curves, membrane replacement logistics cost structures, and battery storage cost decline assumptions.
Forecasts assume regulatory continuity in India's BIS and CDSCO frameworks and Kenya's county-level decentralized procurement administration; material policy shifts would require re-modeling deployment velocity assumptions. Photocatalytic technology performance validation in Ethiopian field conditions and lithium iron phosphate supply contract renegotiation represent specific risk factors that could revise trajectory. Revision becomes warranted when BIS certification timeline compression or CDSCO parallel testing extension crosses thresholds that alter domestic-versus-imported competitive balance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Water Ionizers Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Global RO Water Purifier Market
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market
Water Treatment Systems
Zero Liquid Discharge Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
Point of Use Water Treatment Systems Market
Water Treatment Systems
Indonesia Gravity-Based Water Purifier Market
Water Treatment Systems
Global Desalination System Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Residential Water Treatment Equipment Market