
 Europe Water Purifier Market | 2026-2036
Europe Water Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Water Purifier Market Intelligence
The capital-intensity divergence between membrane manufacturers and filter-assemblers is unwinding competitive stability across the European purifier landscape. Brita GmbH leverages its captive activated-carbon supply chain to dominate retail shelf space in German-speaking markets. Pentair plc anchors its position through industrial-scale reverse osmosis systems serving healthcare and food-processing facilities. BWT Aktiengesellschaft differentiates via magnesium-enrichment technology, occupying a premium niche in Austrian and Swiss residential segments.
Europe water purifiers are electromechanical or passive devices engineered to reduce dissolved solids, microbial loads, chemical contaminants, and particulate matter from potable water streams, typically achieving total dissolved solids rejection rates of 90-99% in reverse osmosis configurations and 4-6 log pathogen reduction in certified ultraviolet units. Their primary commercial purpose spans household safety assurance, industrial process-water preparation, and hospitality compliance with national hygiene codes. Reverse osmosis product types command the steepest installed-cost premiums but capture the deepest margin pools in industrial and healthcare end-user verticals. Point-of-use configurations are expanding fastest in Mediterranean residential markets where consumers bypass whole-building plumbing retrofits. Activated carbon segments sustain volume leadership in Central European retail channels due to lower replacement-part friction and established consumer familiarity.
The EU Drinking Water Directive, REACH chemical compliance protocols, and national implementations of the F-Gas Regulation collectively mandate stricter contaminant thresholds, material safety disclosures, and refrigerant-free cooling in purification equipment, compressing market access for non-certified suppliers and accelerating R&D spend toward compliant membrane chemistries. EMA-aligned healthcare water-quality standards in Germany and France further segment demand between clinical-grade and consumer-grade purification tiers. Stakeholders must monitor pending revisions to the EU Green Deal's product-ecodesign criteria, as these will likely embed recyclability mandates for filter cartridges and energy-consumption caps for electrically powered units.
Market Dynamics
Membrane chemistry R&D is bifurcating competitive positioning across Europe as REACH compliance costs and F-Gas refrigerant bans force suppliers to choose between premium certified systems and lower-tier unbranded alternatives, compressing mid-market viability.
Growth Catalysts
- EU Drinking Water Directive revision:Tightened thresholds for lead, PFAS, and microplastics in municipal supplies are accelerating household upgrade cycles in Germany and France.
- Healthcare water-quality standards:EMA-aligned clinical-grade specifications in German hospitals are segmenting demand tiers and deepening specification rigor for point-of-entry systems.
- Mediterranean supply variability:Seasonal drought stress and infrastructure aging in Southern Europe are driving point-of-use adoption among residential consumers bypassing whole-building retrofits.
Market Restraints
- Activated carbon feedstock concentration:Coconut-shell carbon supply concentrates in Southeast Asian processing clusters, exposing European filter assemblers to freight cost volatility and tariff friction.
- Reverse osmosis energy intensity:Pump electricity consumption and wastewater ratios create operational cost barriers for price-sensitive residential segments in Central Europe.
- F-Gas Regulation refrigerant bans:Cooling-dependent purification units face phase-out timelines that compress product development cycles and strand existing inventory.
Strategic Opportunities
- Eastern European underpenetration:Polish and Romanian residential markets show low point-of-use saturation relative to Western European benchmarks, creating whitespace for entry-level UV systems.
- EU Green Deal ecodesign criteria:Pending recyclability mandates for filter cartridges will favor suppliers with closed-loop logistics infrastructure and modular component architectures.
- Smart connectivity convergence:Integration of IoT sensors with membrane monitoring is enabling predictive replacement services and subscription revenue models in premium Austrian and Swiss segments.
Industry Challenges
- Membrane fabrication talent scarcity:Specialized polymer chemistry and thin-film composite engineering expertise concentrates among a limited pool of German and Swiss research institutions.
- CE marking timeline compression:MDR and machinery directive convergence is extending certification cycles for multi-technology purification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Water Purifier Market |
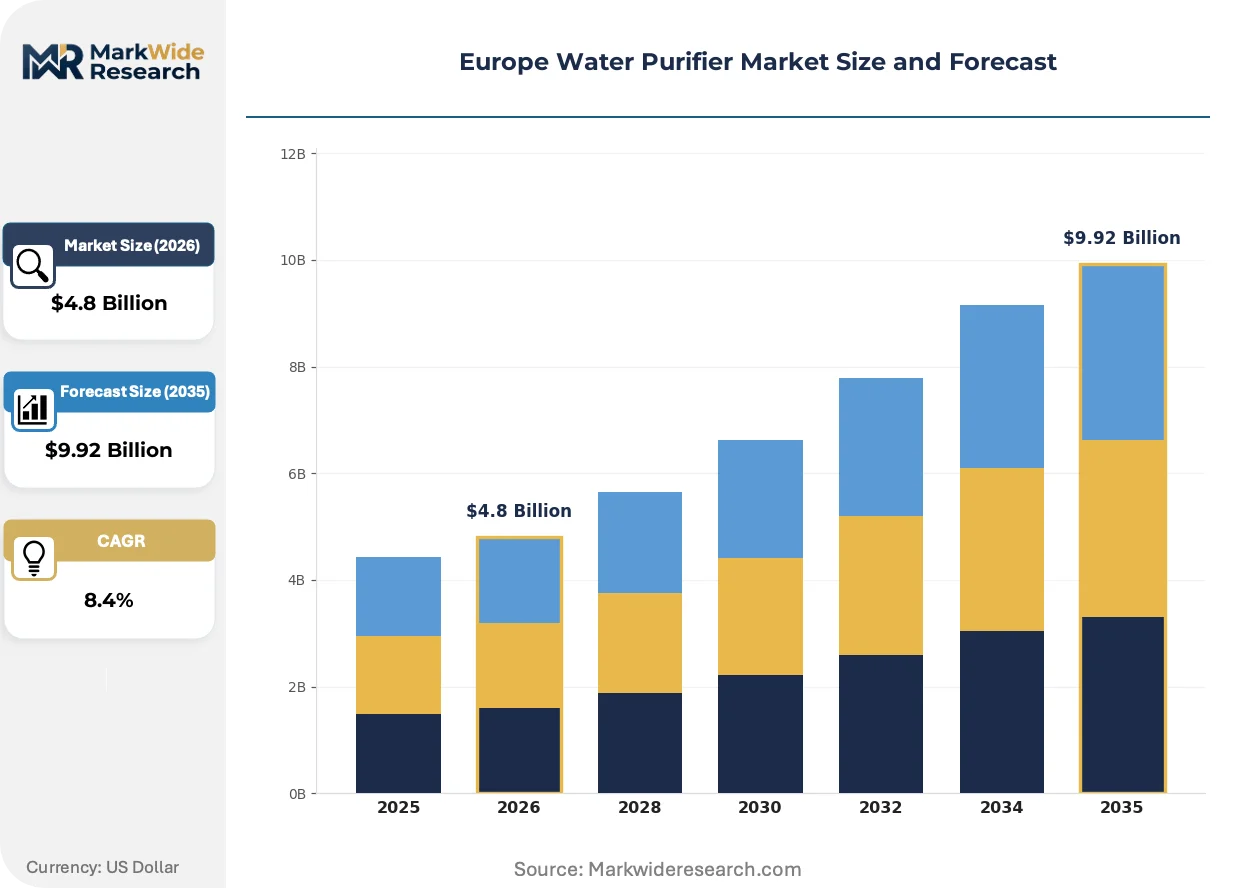
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Activated Carbon, UV, Point-of-Use End User: Residential, Hospitality, Healthcare, Industrial Technology: Filtration, Ion Exchange, Distillation, Ultraviolet Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Brita GmbH, Culligan International Company, Pentair plc, Ecosoft, A.O. Smith Corporation, BWT Aktiengesellschaft, 3M Company, Aquafilter Ltd., AQUAPHOR, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Water Purifier Market Strategic Shifts & Innovations
Electrochemical and biological treatment modalities are displacing conventional physical filtration across multiple end-use verticals, while regulatory pressure on material safety and energy consumption is forcing architectural redesigns of established product platforms.
Photocatalytic oxidation using titanium dioxide coatings is bifurcating the residential treatment landscape. German and Austrian households are adopting these systems for chemical contaminant degradation without the wastewater penalties of reverse osmosis. The technology is compressing addressable market share for traditional activated-carbon pitchers by offering single-unit pathogen and VOC reduction.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing membrane manufacturers to reformulate hydrophobic coating chemistries. Industrial water preparation facilities in France and the Netherlands face supply discontinuity risks as legacy PTFE-based materials lose regulatory approval. Healthcare and food-processing verticals are responding by accelerating qualification timelines for ceramic and graphene-oxide alternatives.
Direct-to-consumer subscription models are displacing retail channel dominance in filter replacement. British and Nordic residential buyers are bypassing hardware stores for auto-ship cartridge programs tied to smart-faucet integration. This pattern is most visible in urban UK markets where Amazon and dedicated water-tech platforms have captured replacement-part volume from traditional distributors.
Europe Water Purifier Market Segmentation
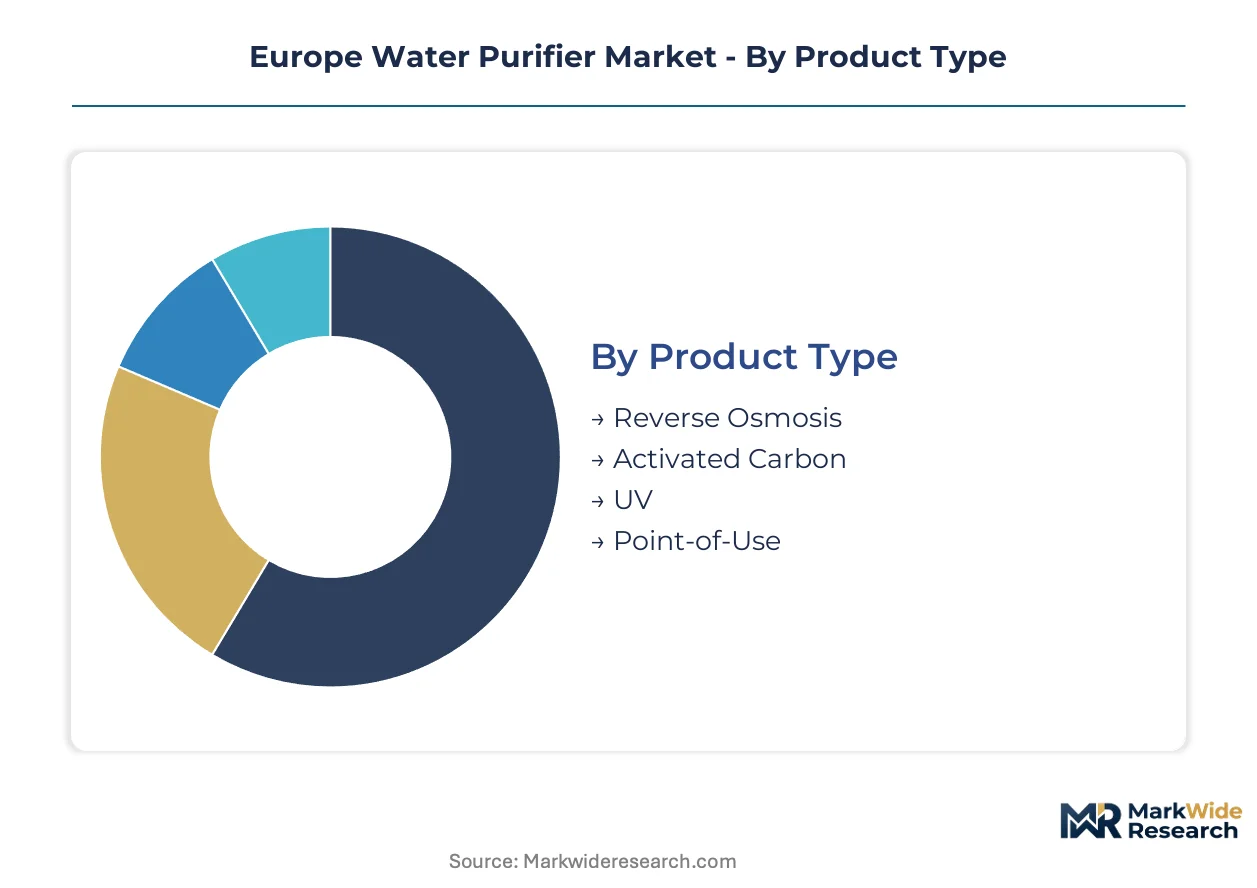
Segmentation in the Europe Water Purifier Market reveals how regulatory pressure and infrastructure heterogeneity split demand across technology tiers and customer profiles. Manufacturers must align certification depth and distribution reach to the specific compliance burdens and replacement economics of each slice.
Product Type:
Substitution pressure from photocatalytic oxidation and electrochemical alternatives is fragmenting the traditional product hierarchy, forcing incumbents to defend their installed base through service bundling and smart monitoring.
- Reverse Osmosis:Thin-film composite membranes achieve dissolved solids rejection rates of 90-99% through pressurized cross-flow filtration. German healthcare facilities and French food-processing plants specify these systems for process-water compliance with EMA-aligned quality standards, though wastewater ratios and pump electricity costs constrain residential penetration in price-sensitive Central European households.
- Activated Carbon:Coconut-shell and bituminous carbon adsorbents reduce chlorine, VOCs, and organic contaminants through surface-area binding. Central European retail channels sustain volume leadership here, driven by lower replacement-part friction and established consumer familiarity in German-speaking markets, despite vulnerability to Southeast Asian feedstock concentration and freight volatility.
- UV:Mercury-vapor and LED-based units deliver 4-6 log pathogen reduction without chemical residuals. Polish and Romanian residential markets show particular receptivity to entry-level configurations.
- Point-of-Use:Countertop and under-sink configurations bypass whole-building plumbing retrofits. Mediterranean households facing seasonal supply variability drive fastest adoption here.
Activated Carbon anchors the volume base while Point-of-Use gains share at the steepest rate.
End User:
Compliance tiering splits the customer base into segments with radically different specification rigor and procurement authority structures.
- Residential:Household safety assurance motivates upgrade cycles, particularly in Germany and France where the EU Drinking Water Directive's tightened thresholds for lead, PFAS, and microplastics trigger infrastructure investment.
- Hospitality:National hygiene codes mandate point-of-entry and point-of-use systems for guest safety. Southern European tourism corridors show concentrated retrofit demand.
- Healthcare:Clinical-grade specifications in German hospitals segment demand into premium tiers with extended qualification timelines and membrane traceability requirements.
- Industrial:Process-water preparation for pharmaceutical and food manufacturing commands the deepest margin pools, with REACH-compliant membrane chemistries becoming non-negotiable for French and Dutch facilities.
Residential commands the broadest addressable base while Healthcare exhibits the steepest specification escalation trajectory.
Technology:
Material safety revisions under REACH authorization protocols are forcing architectural pivots across multiple technology platforms simultaneously.
- Filtration:Physical barrier methods using ceramic, polymeric, and metallic media. Austrian and Swiss premium segments favor ceramic alternatives as PTFE-based hydrophobic coatings lose regulatory approval.
- Ion Exchange:Resin-based hardness and contaminant removal. BWT Aktiengesellschaft's magnesium-enrichment variants occupy differentiated niches in Alpine residential markets.
- Distillation:Thermal phase-separation for high-purity output. Energy intensity limits deployment to laboratory and specialized healthcare settings.
- Ultraviolet:Photonic pathogen inactivation without chemical dosing. British and Nordic markets integrate these units with IoT sensors for predictive replacement services.
Filtration retains the widest deployment footprint while Ultraviolet climbs fastest on connectivity convergence.
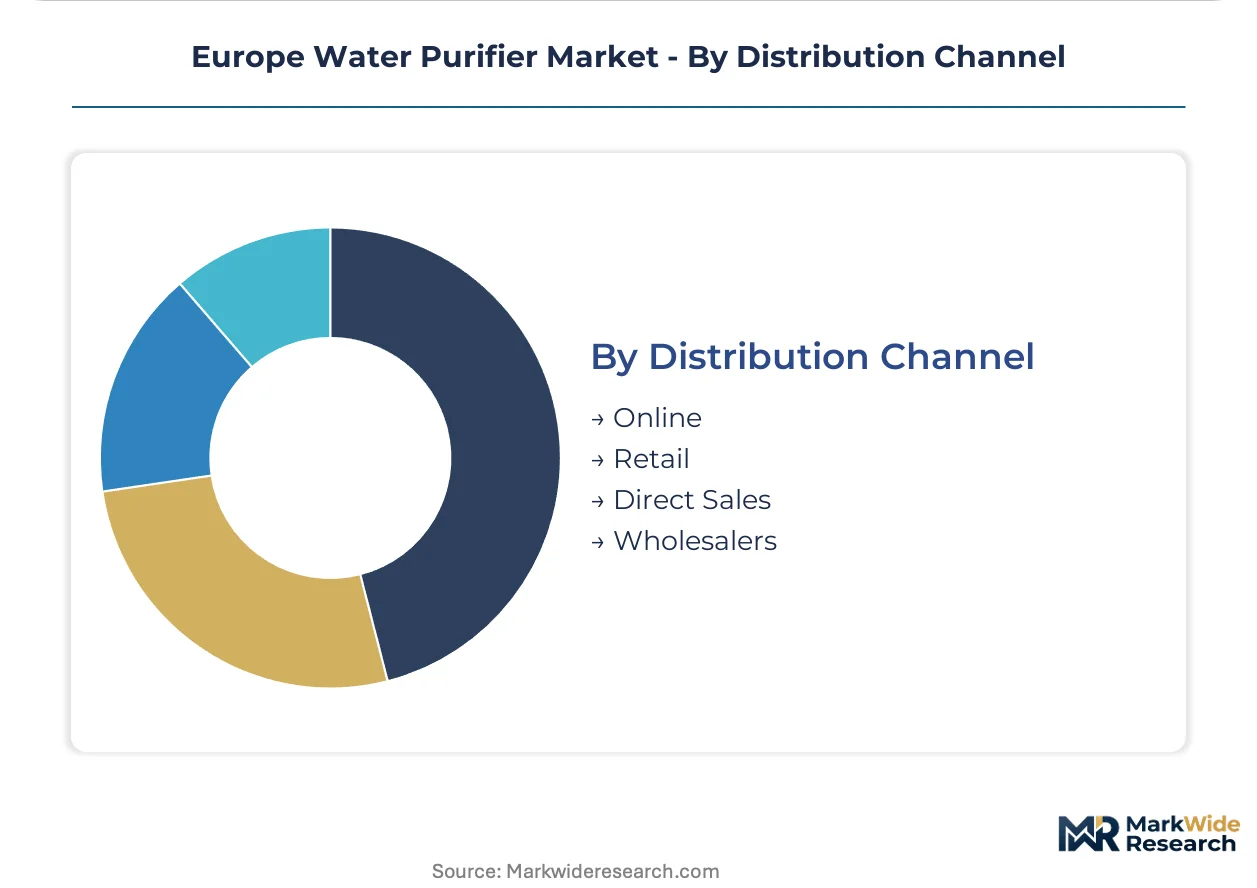
Distribution Channel:
Channel economics are bifurcating between high-touch specification sales and automated replenishment platforms.
- Online:Amazon and dedicated water-tech platforms capture replacement-part volume through auto-ship cartridge programs, particularly visible in urban UK markets where smart-faucet integration enables subscription revenue models.
- Retail:Hardware stores and home-improvement chains dominate in German-speaking markets where Brita GmbH leverages captive activated-carbon supply chains for shelf-space dominance.
- Direct Sales:Specification-driven procurement for industrial and healthcare verticals requires technical consultation and extended qualification support.
- Wholesalers:Plumbing and HVAC trade channels serve contractor-led installation for point-of-entry systems in new construction and major renovation.
Retail sustains the highest transaction frequency while Online expands most quickly on subscription attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Europe. Central European buyers accept premium reverse osmosis systems for healthcare compliance. Southern European households favor low-cost point-of-use units amid municipal supply instability. Eastern Europe presents whitespace for entry-level UV configurations.
Germany
German healthcare facilities drive specification escalation for clinical-grade point-of-entry systems. The EU Drinking Water Directive's tightened thresholds for lead and PFAS trigger residential upgrade cycles. Bavarian membrane fabrication clusters concentrate thin-film composite expertise for industrial process-water compliance.
France
French food-processing plants mandate REACH-compliant membrane chemistries for pharmaceutical-grade output. EMA-aligned water-quality standards segment demand between clinical and consumer tiers. The Lyon-Grenoble corridor anchors photocatalytic oxidation R&D for residential chemical degradation.
United Kingdom
British urban consumers bypass retail channels for auto-ship cartridge subscriptions tied to smart-faucet integration. The F-Gas Regulation compresses product development timelines for cooling-dependent units. London and Southeast England concentrate direct-to-consumer platform adoption.
Italy
Italian Mediterranean households facing seasonal drought stress drive fastest point-of-use expansion. National hygiene codes mandate purification systems across hospitality corridors. Tourism-heavy regions in Tuscany and Sicily show concentrated retrofit demand for guest safety compliance.
Poland
Polish residential markets exhibit low point-of-use saturation relative to Western benchmarks. Entry-level UV systems capture whitespace among price-sensitive households. Warsaw and Krakow manufacturing zones assemble filter components for re-export to German retail channels.
Europe Water Purifier Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in Europe's water purifier structure. Membrane manufacturers and filter assemblers diverge on capital intensity, unwinding mid-market stability. Three archetypes dominate: captive supply-chain operators, industrial-scale system providers, and premium niche specialists. Competitive moves center on smart connectivity convergence and closed-loop logistics infrastructure for pending recyclability mandates.
Within the integrated tier, Brita GmbH and Pentair plc exemplify divergent strategic positions. BWT Aktiengesellschaft anchors the premium niche archetype through differentiated technology positioning. German and Swiss specialists concentrate in magnesium-enrichment and ceramic filtration segments respectively.
| Leading Market Players |
|---|
| Brita GmbH |
| Culligan International Company |
| Pentair plc |
| Ecosoft |
| A.O. Smith Corporation |
| BWT Aktiengesellschaft |
| 3M Company |
| Aquafilter Ltd. |
| AQUAPHOR |
| Others |
Cost & Logistics Intelligence
Membrane fabrication scale economies in Bavarian and Swiss research clusters concentrate thin-film composite expertise among a limited supplier pool, elevating price floors for REACH-compliant systems while compressing margins for non-certified assemblers sourcing from fragmented Southeast Asian feedstock networks.
Pricing Analysis
Replacement cartridge subscriptions now drive lifetime value more than initial hardware sales. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade membrane systems with EMA traceability from consumer-grade activated-carbon pitchers. Cost compression in entry-level UV segments is intensifying because Polish and Romanian assemblers compete on import substitution. Residential households in Mediterranean markets exhibit highest price sensitivity; German healthcare procurement shows least.
Supply Chain Analysis
Container availability constraints on Southeast Asian trade lanes expose European filter assemblers to freight volatility for coconut-shell carbon feedstock. Manufacturing concentrates in Germany, Switzerland, and China for membranes, activated carbon, and ceramic media respectively. Supply chains rest on coconut-shell carbon, thin-film composites, and magnesium-enrichment resins. Single-source vulnerability concentrates in Southeast Asian carbon processing clusters. Distribution runs through plumbing trade channels for point-of-entry systems and Amazon-led platforms for replacement cartridges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filter replacement subscriptions and predictive maintenance services expand faster than hardware sales, reframing the market as a recurring-revenue attach opportunity rather than transactional equipment.
For Market Incumbents: Compound service bundling with smart-faucet IoT integration to lock in replacement-part volume before Amazon and dedicated water-tech platforms capture urban UK and Nordic markets. Deepen backward integration into activated-carbon feedstock to offset Southeast Asian supply concentration. Accelerate CE marking timelines ahead of MDR and machinery directive convergence.
For New Entrants and Emerging Players: CE marking fast-tracks for UV-based point-of-use systems unlock Polish and Romanian residential whitespace where saturation lags Western benchmarks. Target entry-level configurations priced below reverse osmosis alternatives. Deploy direct-to-consumer subscription models with auto-ship cartridge programs to bypass retail channel dominance in German-speaking markets.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with closed-loop logistics infrastructure and modular component architectures aligned to pending EU Green Deal recyclability mandates. Five-to-ten year viability favors membrane manufacturers with REACH-compliant coating chemistries over legacy PTFE-dependent assemblers. Watch EMA-aligned healthcare specification escalation as signal for premium tier margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Connectivity Integration | IoT sensor deployment enables predictive replacement services in Austrian and Swiss premium segments. |
| Closed-Loop Logistics Buildout | Recyclability mandates under EU Green Deal favor suppliers with cartridge return infrastructure. |
| REACH-Compliant Membrane R&D | Reformulated hydrophobic coatings secure access to French and Dutch healthcare verticals. |
| Eastern European Distribution Expansion | Entry-level UV penetration captures whitespace in Polish and Romanian residential markets. |
| Direct-to-Consumer Platform Launch | Auto-ship subscriptions displace retail dominance in British urban replacement-part markets. |
Research Approach
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. Conversations with membrane R&D directors, hospital biomedical engineers, plumbing trade distributors, and activated-carbon procurement managers inform technology trajectory assessments. Secondary sources include EMA water-quality standards, REACH authorization databases, EU Drinking Water Directive implementation texts, and customs records for carbon feedstock imports. Bottom-up unit economics triangulate against top-down sector spending estimates.
Sensitivity analysis around membrane replacement cycles and regulatory compliance timelines shapes the analytical framework. Segmentation dimensions span product type, end-user vertical, technology platform, and distribution channel across the projection horizon. CAGRs derive from installed base growth rates and replacement frequency modeling. Forecast inputs incorporate EU Green Deal ecodesign criteria progression and F-Gas Regulation phase-out timelines.
Decision-makers should treat outputs as directional under stable REACH enforcement and continued EU Drinking Water Directive threshold tightening; material deviation would warrant model refresh. Specific risks include Southeast Asian supply disruption, ceramic membrane qualification delays, and subscription platform customer acquisition cost inflation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
Indonesia Gravity-Based Water Purifier Market
Water Treatment Systems
Home Water Filtration Unit Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
MENA Point of Use Water Purifiers Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Mobile Water Treatment Services Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Zero Liquid Discharge Market
Water Treatment Systems
Water Purifier/Filter Market
Water Treatment Systems
Wastewater Recovery Systems Market