
 Home Water Filtration Unit Market | 2026-2036
Home Water Filtration Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Home Water Filtration Unit Market Intelligence
The substitution of standard plastics with BPA-free polymers and stainless steel in filter housings is consolidating product designs around health and durability benchmarks. A. O. Smith Corporation leverages its manufacturing scale to offer a broad portfolio of both under-sink and whole-house systems. Pentair PLC differentiates through its focus on advanced membrane technologies for complex contaminant removal. Culligan International sustains a strong market presence via its dealer network that provides installation and maintenance services.
A home water filtration unit is a point-of-use or point-of-entry appliance designed to reduce contaminants from a municipal or well water supply. These systems operate using various media to achieve specific impurity reduction, often rated by their ability to remove particles down to a certain micron size. Activated carbon filters command the largest volume share due to their affordability and effectiveness against chlorine, while reverse osmosis systems represent the premium tier. Membrane filtration technology, central to reverse osmosis, is seeing innovation to improve water efficiency and reduce wastewater.
Product performance and material safety are governed by a patchwork of international standards, including NSF/ANSI certifications in the United States. In Europe, CE marking ensures electrical safety for powered units, while China’s GB standards regulate materials that come into contact with drinking water. Manufacturers must now balance demands for higher contaminant removal efficacy with the total cost of ownership and the environmental impact of filter cartridge disposal.
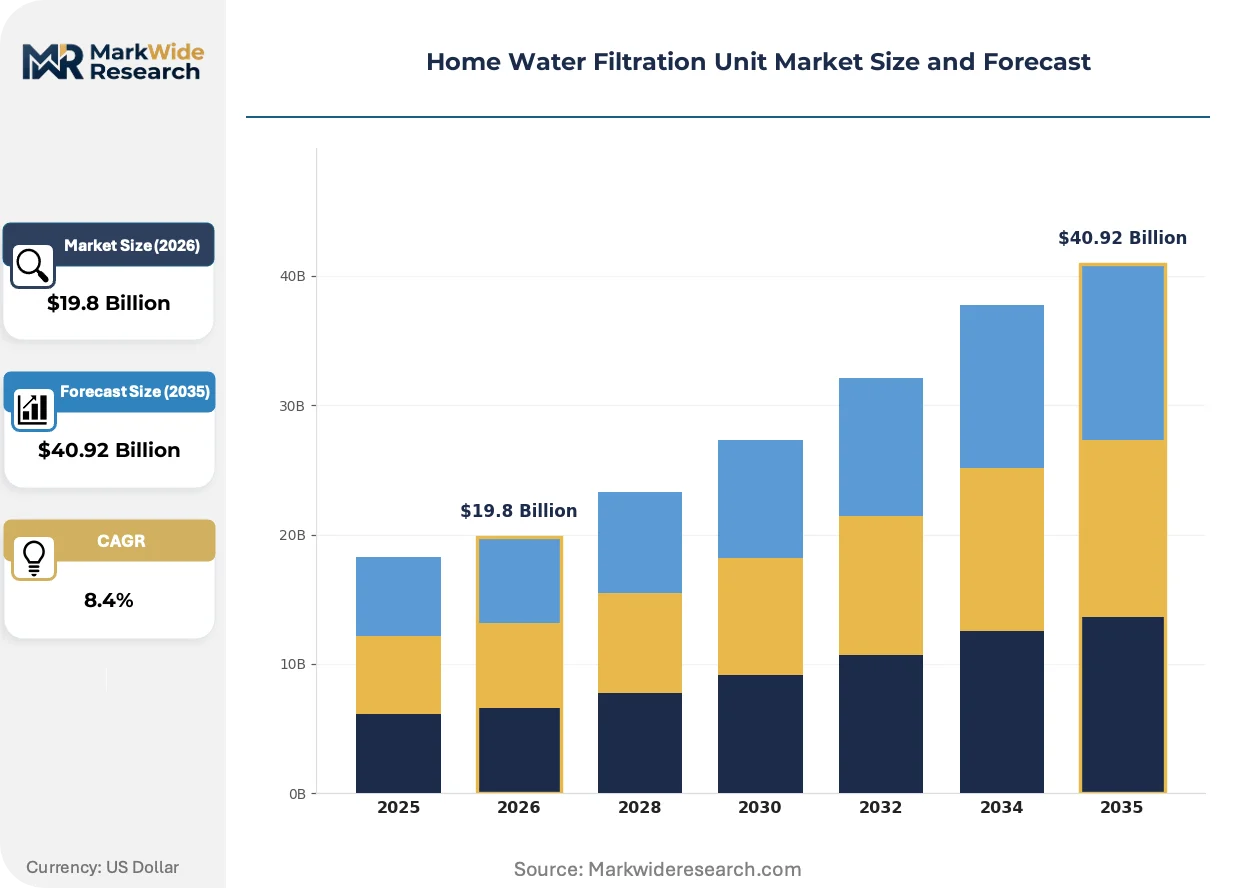
Market Dynamics
The market's central dynamic is the tension between consumer demand for advanced contaminant removal and the total cost of ownership. This is amplified by regulatory scrutiny on material safety and growing awareness of micropollutants in municipal water supplies.
Growth Catalysts
- NSF/ANSI Certification:Consumer preference for products certified under standards like NSF/ANSI 42 and 53 drives sales, providing third-party validation of contaminant reduction claims and material safety.
- Centralized Residential Systems:The adoption of point-of-entry systems in new multi-family residential buildings expands the market beyond single-family homes, particularly in high-density urban areas.
- Smart System Integration:The integration of IoT-based monitoring for filter life and water quality appeals to consumers seeking convenience and performance assurance.
Market Restraints
- High Initial Capital Outlay:The significant upfront cost of premium systems like reverse osmosis units acts as a barrier for many households, limiting adoption to higher-income segments.
- Reverse Osmosis Wastewater:The inherent wastewater generation from reverse osmosis systems is a drawback, especially in water-scarce regions, creating environmental and efficiency concerns.
- Inconsistent Water Pressure:Performance of many systems depends on stable municipal water pressure, which can be unreliable in parts of developing economies, affecting filtration efficacy.
Strategic Opportunities
- Filter Cartridge Recycling:Developing closed-loop recycling programs for spent filter cartridges addresses environmental concerns and builds brand loyalty among eco-conscious consumers.
- Southeast Asian Urban Centers:Rapidly urbanizing cities in Vietnam and Indonesia, with growing middle-class populations, represent underpenetrated markets for point-of-use systems.
- Targeted Contaminant Removal:Engineering filters for emerging contaminants like PFAS allows for product differentiation and addresses specific regional health advisories.
Industry Challenges
- Navigating Global Standards:Manufacturers face complexity and cost in securing certifications across jurisdictions like the US (NSF/ANSI), Europe (CE marking), and China (GB standards).
- Cartridge Disposal Logistics:The environmental impact and logistics of managing filter cartridge disposal and replacement cycles remain a significant operational hurdle for the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Water Filtration Unit Market |
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $40.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, Reverse Osmosis, UV Purification, Ceramic Filters End User: Residential, Commercial, Industrial, Institutions Technology: Membrane Filtration, Chemical Treatment, Physical Filtration, Electrochemical Treatment Service Type: Installation, Maintenance, Replacement, Consulting |
| Companies Covered | Aquasana, Inc., SpringWell, A. O. Smith Corporation, GE Water Filtration, Whirlpool Corporation, Culligan International, Pentair PLC, iSpring, EcoWater Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Water Filtration Unit Market Strategic Shifts & Innovations
Product development is shifting from general-purpose filtration to specialized systems addressing specific health threats and environmental impacts. This evolution is driven by advances in material science and a more informed consumer base demanding performance transparency.
Advanced membrane filtration, including ultrafiltration and nanofiltration, provides a more selective barrier against contaminants than traditional activated carbon alone. Residential and light commercial segments are adopting these technologies to target specific micropollutants. This targeted removal capability is overtaking the one-size-fits-all approach of older systems, especially in markets with known water quality issues.
Regulations like Europe’s REACH directive and China’s GB standards for food-contact materials are imposing stricter controls on polymers and metals used in filter housings. This forces manufacturers to re-evaluate supply chains for materials like BPA-free plastics and certified stainless steel. The under-sink and countertop segments are most affected, as material safety is a primary consumer purchasing criterion.
Subscription-based models for filter replacement are gaining traction over one-time hardware sales. This model shifts the consumer focus from a large initial purchase to a recurring service fee, bundling automatic filter shipments and maintenance reminders. This trend is most visible in North America and Europe, where convenience and performance consistency are highly valued.
Home Water Filtration Unit Market Segmentation
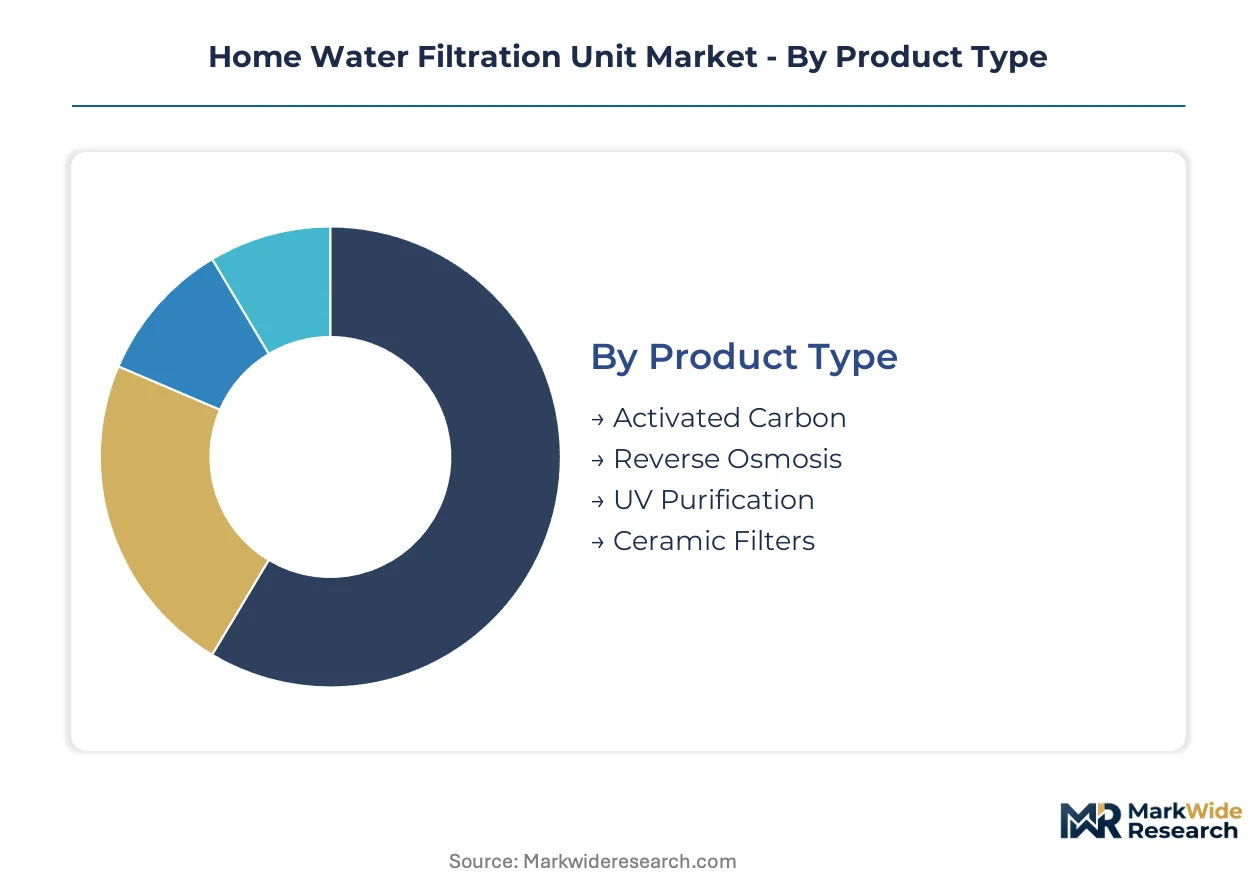
Understanding the varied needs of consumers and the technological landscape is crucial for strategic positioning within the home water filtration unit market. This segmentation analysis categorizes the market by product type, end user, technology, and service type, revealing distinct demand patterns and competitive dynamics.
Product Type:
Supply concentration in the home water filtration unit market heavily influences product type availability and innovation cycles.
- Activated Carbon:These filters utilize granular or block carbon to adsorb chlorine, odors, and organic compounds, representing the largest volume share due to their affordability and broad effectiveness. Demand concentrates in general residential applications seeking basic taste and odor improvement in municipal water.
- Reverse Osmosis:Reverse osmosis systems employ a semi-permeable membrane to remove dissolved solids, heavy metals, and micropollutants, positioning them as the premium tier. Consumer demand is concentrating in regions with known water quality concerns, driven by smart monitoring features.
- UV Purification:Ultraviolet purification systems use UV light to inactivate bacteria, viruses, and other microorganisms, providing an effective chemical-free disinfection method.
- Ceramic Filters:Ceramic filters physically block sediment, bacteria, and cysts through a porous ceramic structure, often used for point-of-use filtration in areas with less treated water.
Today's leader: Activated Carbon. Tomorrow's challenger: Reverse Osmosis.
End User:
Customer type dictates system scale and service requirements within the home water filtration sector.
- Residential:This segment includes single-family homes and multi-family dwellings, utilizing both point-of-use and whole-house systems for household water purification. Demand is driven by health concerns, taste preferences, and convenience for drinking, cooking, and bathing.
- Commercial:Commercial end users encompass offices, restaurants, hotels, and small businesses requiring water filtration for operational needs or customer consumption. These applications often demand higher flow rates and specific contaminant removal for food preparation or equipment protection.
- Industrial:Industrial applications involve large-scale water treatment for manufacturing processes, cooling towers, or boiler feed water, where water quality directly impacts operational efficiency and product integrity.
- Institutions:Institutions like schools, hospitals, and government facilities require reliable water filtration to ensure public health and safety, often adhering to stringent regulatory standards.
The residential segment maintains the largest volume, while commercial applications are expanding most quickly.
Technology:
Cost tier often differentiates the technological sophistication available for home water filtration solutions.
- Membrane Filtration:This technology includes reverse osmosis, ultrafiltration, and nanofiltration, providing a selective barrier against dissolved solids, bacteria, and viruses. Innovation in membrane materials improves water efficiency and contaminant rejection rates for advanced systems.
- Chemical Treatment:Chemical treatment methods involve adding substances like chlorine or polyphosphates to water for disinfection, scale inhibition, or pH adjustment. These are often used as pre-treatment or specialized solutions.
- Physical Filtration:Physical filtration encompasses methods like sediment filters and activated carbon, which remove larger particles and adsorb contaminants through mechanical or adsorptive processes. This forms the foundational layer for most multi-stage systems.
- Electrochemical Treatment:Electrochemical processes utilize electrical currents to remove specific contaminants, such as heavy metals or certain organic compounds, offering specialized treatment capabilities.
Membrane filtration technology shows the steepest expansion trajectory, driven by performance demands.
Service Type:
Application-specific demands shape the portfolio of services required for effective water filtration unit deployment.
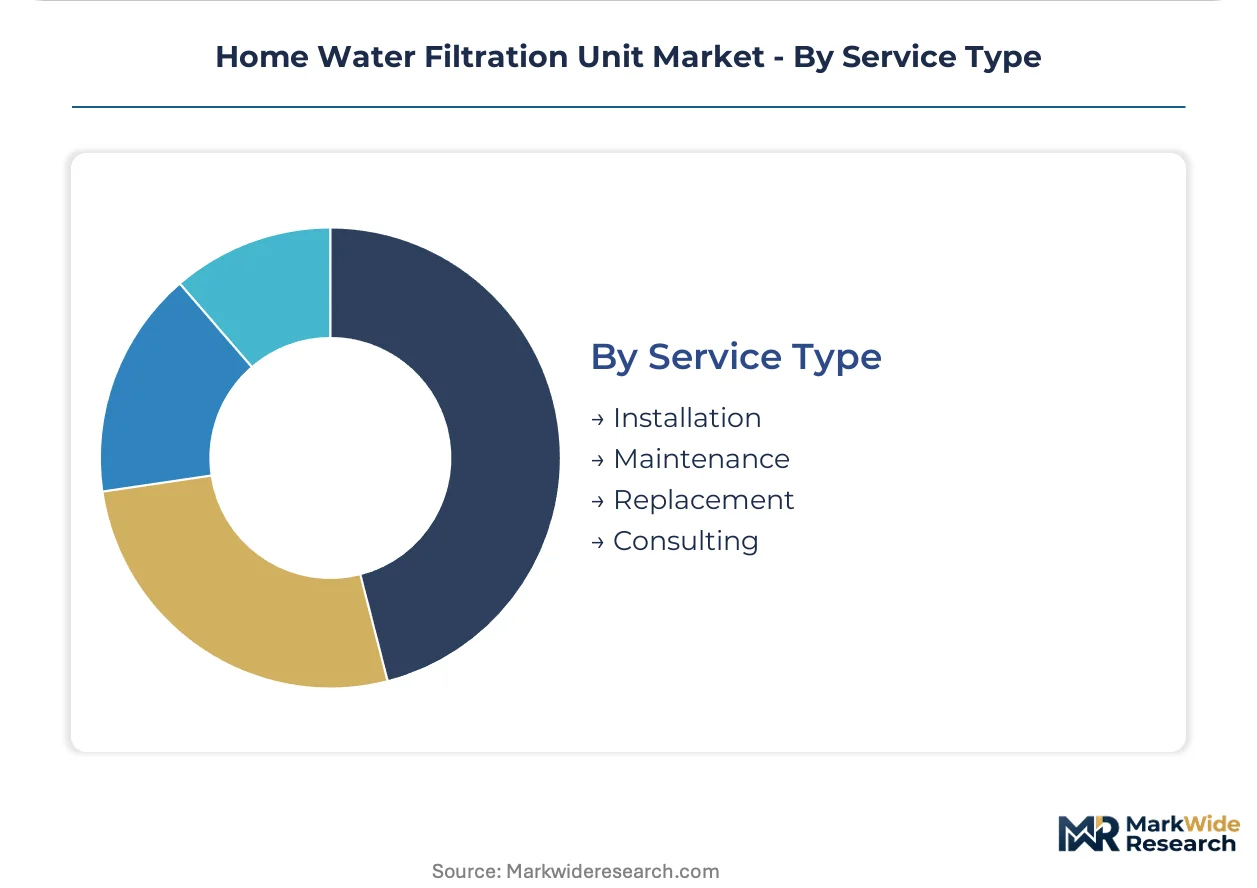
- Installation:This service involves the professional setup and integration of filtration units into existing plumbing systems, ensuring proper function and adherence to safety standards. Correct installation is critical for system warranty and performance.
- Maintenance:Maintenance services include routine inspections, cleaning, and preventative measures to ensure optimal performance and longevity of the filtration system. Regular filter changes are a core component of this service.
- Replacement:Replacement services focus on the timely exchange of spent filter cartridges or components, which is essential for maintaining filtration efficacy and water quality. This often occurs on a scheduled basis.
- Consulting:Consulting services provide expert advice on water quality assessment, system selection, and customized filtration solutions tailored to specific water challenges and consumer needs.
Installation services command significant upfront value, with maintenance services generating consistent recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rapidly urbanizing areas of China and India drive significant demand for home water filtration units. These regions, alongside developed markets, shape global consumption patterns. Regulatory frameworks and consumer health awareness profoundly influence market dynamics across diverse geographies.
China
Chinese urban centers exhibit substantial demand for advanced contaminant removal due to municipal water quality concerns. China's GB standards strictly regulate materials in contact with drinking water, ensuring product safety and consumer confidence. Major metropolitan areas like Shanghai and Beijing drive the adoption of smart monitoring features in residential filtration systems.
India
Consumer concerns over water quality and rapid urbanization propel the demand for point-of-use systems across India. BIS certification ensures product quality and builds consumer trust in local offerings. Cities such as Mumbai and Delhi-NCR exhibit strong growth for both affordable activated carbon and advanced reverse osmosis filtration solutions.
United States
United States consumers prioritize products certified under NSF/ANSI 42 and 53, validating contaminant reduction claims and material safety. EPA regulations influence material safety and system design for residential applications. California and Texas show high demand for whole-house systems, particularly in new multi-family residential developments.
Germany
Germany sees demand for advanced membrane technologies, targeting complex contaminant removal in residential settings. CE marking ensures electrical safety for powered units sold throughout Europe. Urban areas in Bavaria and North Rhine-Westphalia focus on sustainable filtration solutions and pioneering filter cartridge recycling programs.
Vietnam
Growing middle-class populations in Vietnamese urban centers like Ho Chi Minh City and Hanoi create underpenetrated markets for point-of-use systems. The country's Ministry of Health establishes drinking water quality standards, guiding consumer choices. These cities show increasing interest in both basic activated carbon and advanced filtration systems.
Home Water Filtration Unit Market Key Industry Players
Global majors compete with regional champions across product portfolio breadth and technological specialization within the home water filtration market. The competitive landscape exhibits a tiered structure, with large diversified conglomerates and specialized technology firms vying for market share. Portfolio diversification to address varied consumer needs and strategic partnerships for technology co-development are dominant competitive moves among industry participants.
On the premium-tier vector, A. O. Smith Corporation and Pentair PLC exemplify advanced filtration solutions. A. O. Smith Corporation, a US-based entity, occupies a position focused on manufacturing scale and broad portfolio offerings across various product types, including under-sink and whole-house systems. Pentair PLC, with its global presence, represents companies differentiating through advanced membrane technologies for complex contaminant removal and water efficiency improvements. Culligan International, another global player, anchors the service-oriented segment through its extensive dealer network that provides installation, maintenance, and replacement services, sustaining a strong market presence.
| Leading Market Players |
|---|
| Aquasana, Inc. |
| SpringWell |
| A. O. Smith Corporation |
| GE Water Filtration |
| Whirlpool Corporation |
| Culligan International |
| Pentair PLC |
| iSpring |
| EcoWater Systems LLC |
| Others |
Cost & Logistics Intelligence
Consumer preference for NSF/ANSI certified products elevates manufacturing compliance costs. This demand-side pressure forces suppliers to invest in rigorous testing and materials, directly influencing the final product pricing across all tiers.
Pricing Analysis
Rising costs for advanced membrane materials and certified BPA-free polymers pass through to final product prices. The market employs a hybrid pricing model, combining transactional hardware sales with recurring subscription fees for filter replacements, differentiating across premium, standard, and economy tiers. Price differentiation stems from NSF/ANSI certification levels and integrated smart monitoring features. Pricing softness reflects intense competition within the activated carbon segment, making residential consumers highly price-sensitive compared to less sensitive commercial and institutional end-users.
Supply Chain Analysis
China’s GB standards for materials in contact with drinking water mandate specific sourcing for filter housings and internal components, reshaping global procurement. Supply concentration centers in China for manufacturing, with specialized membrane technologies often originating from Germany and the United States, relying on activated carbon, polymer resins, and reverse osmosis membranes. Single-source vulnerability for advanced membrane components presents a structural risk. Distribution runs through specialized dealer networks, direct-to-consumer online channels, and large retail outlets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The home water filtration market is evolving into a late-cycle quality story, driven by consumer demand for advanced contaminant removal. Smart monitoring features integrated into reverse osmosis systems exemplify this shift toward premium specifications and performance assurance.
For Market Incumbents:Acquire specialized membrane technology firms to counter emerging micropollutant challenges and enhance product differentiation. Incumbents should invest heavily in NSF/ANSI certification for new product lines, reinforcing consumer trust. Expanding dealer networks, particularly in Southeast Asian urban centers, defends market share against new entrants. Developing closed-loop filter cartridge recycling programs mitigates environmental concerns and builds brand loyalty.
For New Entrants and Emerging Players:Plumbing contractors and home improvement retailers offer critical access points for new entrants targeting residential segments. Focus on underpenetrated urban centers in Vietnam and Indonesia, offering point-of-use systems engineered for emerging contaminants like PFAS. A subscription-based filter replacement model provides a compelling go-to-market angle, reducing initial capital outlay for consumers and ensuring recurring revenue. This strategy bypasses established dealer networks by offering convenience and specialized solutions.
For Investors and Strategic Acquirers:Asymmetric upside sits with vertically integrated specialists possessing proprietary advanced membrane technology or smart monitoring platforms. The market offers long-term viability due to persistent global water quality concerns and urbanization trends. Investors should target niche players with strong intellectual property in targeted contaminant removal, particularly for PFAS. Regulatory mandates for micropollutant removal, especially in developed economies, serve as a key inflection indicator for investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Filter Cartridge Recycling Program | This initiative addresses environmental concerns and cultivates brand loyalty among eco-conscious consumers. |
| Advanced Membrane Technology R&D | Research into new membranes improves water efficiency and targets specific emerging contaminants like PFAS. |
| Smart Monitoring Feature Integration | This enhances user convenience and provides performance assurance for premium reverse osmosis systems. |
| Dealer Network Expansion | Expanding service networks secures installation and maintenance revenue, especially for Culligan International. |
| NSF/ANSI Certification Investment | Certification validates contaminant reduction claims and builds strong consumer trust in product efficacy. |
Research Approach
Direct dialogue with water utility managers, product engineers, procurement heads at multi-family residential developers, and retail channel managers informed primary insights. This qualitative data was rigorously validated against secondary sources including NSF/ANSI certification databases, government water quality reports, and company annual filings. A comprehensive bottom-up and top-down triangulation approach ensured data accuracy and market sizing integrity.
Market volume and value projections were generated through a robust supply-demand balancing analytical framework across the analysis window. The model integrated segmentation dimensions including product type, end user, technology, service type, and regional urbanization rates. Compound annual growth rates were derived from historical growth trends and projected demand drivers. Key industry-specific forecast inputs included municipal water quality indices and new multi-family residential housing starts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory shifts or sustained supply chain disruptions. These forecasts reflect inherent assumptions about market evolution and technological adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
MENA Point of Use Water Purifiers Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Mobile Water Treatment Services Market
Water Treatment Systems
Malaysia Water Purifier Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Water Treatment Ozone Generator Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Point of Entry Water Treatment Systems Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
Water Desalination Equipment Market
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
Packaged Water Treatment System Market