
 Leak Detection Equipment Market | 2026-2036
Leak Detection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Leak Detection Equipment Market Foresight
EPA methane performance standards is expanding the cost-of-entry calculus for leak detection equipment suppliers across North American oil and gas corridors. Honeywell International Inc. leverages its distributed sensor architecture to anchor long-term service contracts with integrated operators. Siemens AG competes through digital twin integration that sustains recurring software revenue alongside hardware placements.
Leak detection equipment encompasses instruments that identify unintended fluid or gas egress through acoustic emission signatures, optical absorption spectra, or pressure differential monitoring, typically achieving sensitivity thresholds below one part per million depending on the sensing modality. These systems serve primarily to prevent catastrophic failure, reduce commodity loss, and ensure environmental compliance across pressurized infrastructure. Ultrasonic detectors dominate retrofit installations in aging pipeline networks where non-invasive mounting preserves operational continuity. Optical sensors represent the fastest-expanding category as fiber optic technology enables distributed temperature and strain monitoring across kilometer-scale infrastructure with minimal maintenance overhead. Wireless systems are maturing rapidly in water distribution applications where battery-powered nodes eliminate trenching costs for municipal utilities.
The EPA enforces methane emission thresholds that directly shape product certification requirements and procurement specifications for upstream operators. EMA safety standards and EU Green Deal carbon accounting rules are tightening equivalently across European process industries, forcing vendors to maintain dual certification portfolios. Stakeholders must monitor how regulatory divergence between EPA and EU frameworks influences R&D allocation and regional product line specialization.
Market Dynamics
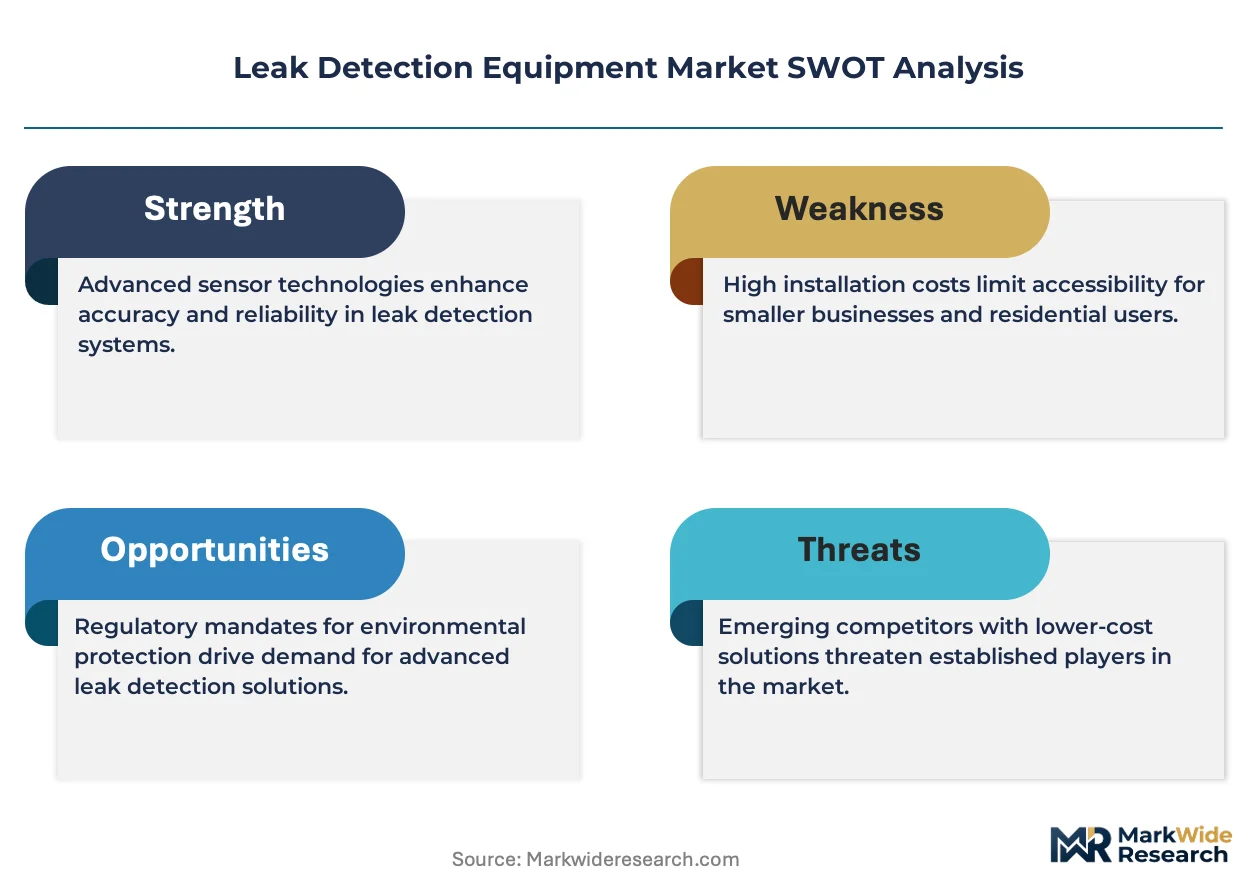
The EPA's methane performance standards are compressing replacement cycles for continuous monitoring infrastructure across North American oil and gas corridors. Operators now face capital allocation trade-offs between retrofitting aging acoustic systems and deploying fiber-optic distributed sensing arrays.
Growth Catalysts
- Fugitive emission mandates:The EPA's methane performance standards in the United States compel upstream and midstream operators to install continuous monitoring systems, accelerating hardware replacement cycles across compressor stations and gathering lines.
- Hydrogen infrastructure retrofit:Germany's hydrogen pipeline conversion programs are driving sensor replacement demand as existing leak detection equipment lacks compatibility with hydrogen's distinct permeation and embrittlement characteristics.
- Fiber-optic distributed sensing:Kilometer-scale temperature and strain monitoring via fiber-optic cables eliminates maintenance overhead in subsea and remote terrestrial pipelines, displacing point-source detector arrays.
Market Restraints
- Specialized photonics supply concentration:Distributed acoustic sensing interrogator units rely on narrow-band laser sources concentrated among German and Japanese optical component suppliers, creating input bottlenecks.
- Dual certification burden:Vendors must maintain parallel EPA and EU Green Deal compliance portfolios, inflating R&D overhead and extending product launch timelines by 12-18 months.
- Ultrasonic detector substitution:Thermal imaging drones and satellite-based hyperspectral methane mapping are capturing inspection applications previously served by ground-based ultrasonic arrays.
Strategic Opportunities
- Municipal water wireless deployment:Battery-powered wireless nodes eliminate trenching costs for aging water distribution networks in the United States, opening retrofit opportunities among cash-constrained municipal utilities.
- Digital twin convergence:Integration of real-time leak detection data with pipeline simulation models enables predictive maintenance contracts, shifting revenue from hardware sales to recurring software subscriptions.
- EU Green Deal carbon accounting:Mandatory Scope 3 emission disclosures under EU Green Deal rules are forcing process industries to install certified leak detection systems for supply chain verification.
Industry Challenges
- Multi-physics simulation expertise:Designing sensors for hydrogen compatibility requires rare cross-disciplinary capabilities spanning materials science, fluid dynamics, and optical engineering, constraining vendor R&D throughput.
- Legacy SCADA integration:New continuous monitoring systems must interface with decades-old supervisory control architectures, extending deployment timelines and inflating commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leak Detection Equipment Market |
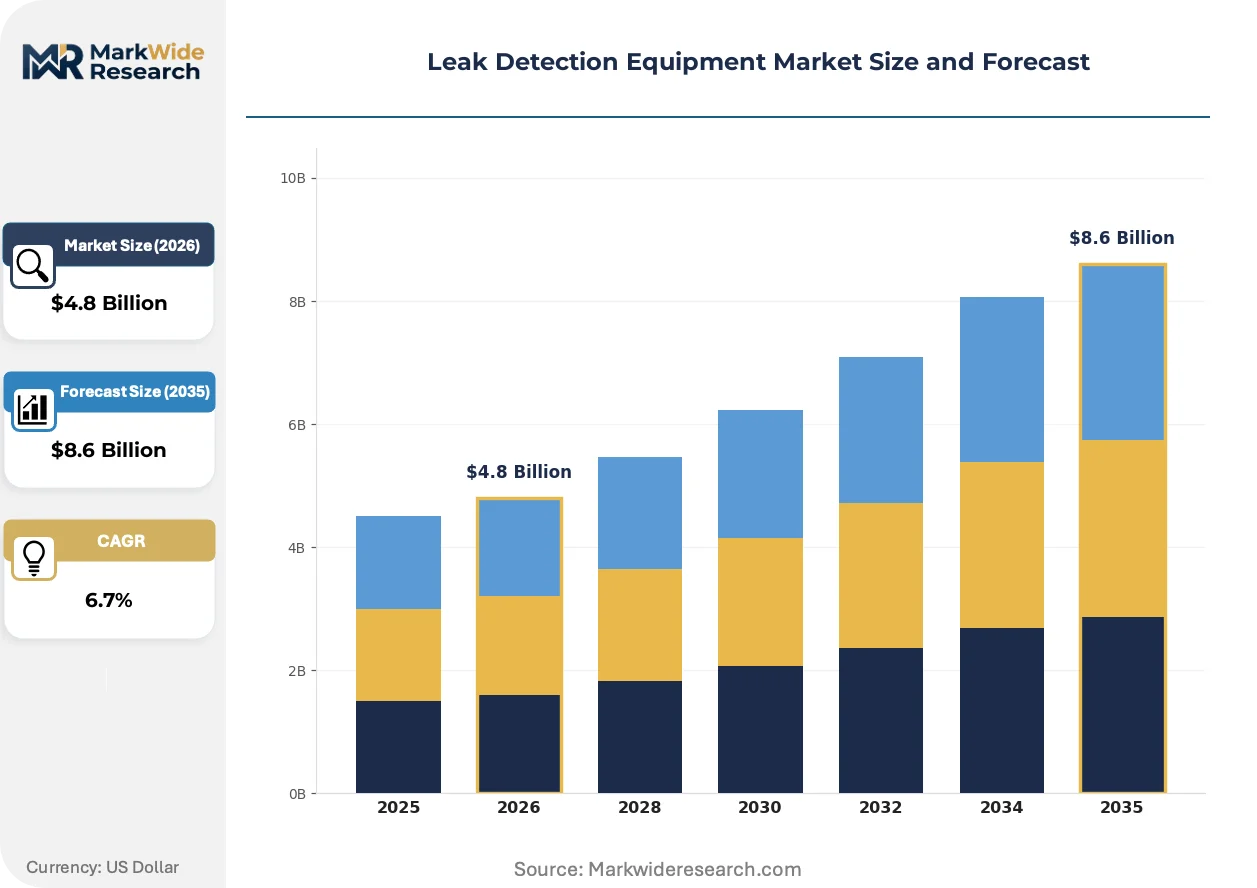
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Detectors, Optical Sensors, Infrared Sensors, Wireless Systems Application: Oil & Gas, Water Distribution, HVAC Systems, Chemical Processing End User: Utilities, Manufacturing, Construction, Residential Technology: Acoustic Emission, Capacitance-based, Pressure-based, Fiber Optic |
| Companies Covered | Honeywell International Inc., Siemens AG, Schneider Electric SE, Emerson Electric Co., INFICON Holding AG, Pentair plc, Teledyne Technologies, ATEQ Corp., Testo SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leak Detection Equipment Market Shifts & Advancements
Optical sensing modalities are displacing acoustic and pressure-based detection in high-value infrastructure monitoring applications. Regulatory carbon accounting mandates are forcing interoperability between hardware vendors and enterprise emission management platforms.
Photonic integrated circuits are expanding into miniaturized methane-specific absorption spectrometers for unmanned aerial vehicle deployment. Pipeline operators in the Permian Basin are adopting these chip-scale sensors for rapid well pad surveys, reducing inspection labor costs by two-thirds. The technology is expanding into fixed-wing drone platforms for midstream corridor monitoring.
REACH restrictions on perfluorinated compounds are constraining seal and membrane materials in optical sensor housings. European manufacturers are reformulating elastomer specifications to maintain IP ratings while eliminating restricted substances. The F-Gas Regulation is simultaneously tightening refrigerant-based cooling systems in portable detection equipment, compressing product redesign cycles.
Asset owners are unbundling after-sales service contracts from initial hardware procurement. Integrated oil and gas operators now source leak detection maintenance through separate RFP processes, enabling third-party specialty service firms to capture recurring revenue streams. This pattern is most visible in the United States, where independent midstream companies lack captive technical service organizations.
Leak Detection Equipment Market Segmentation
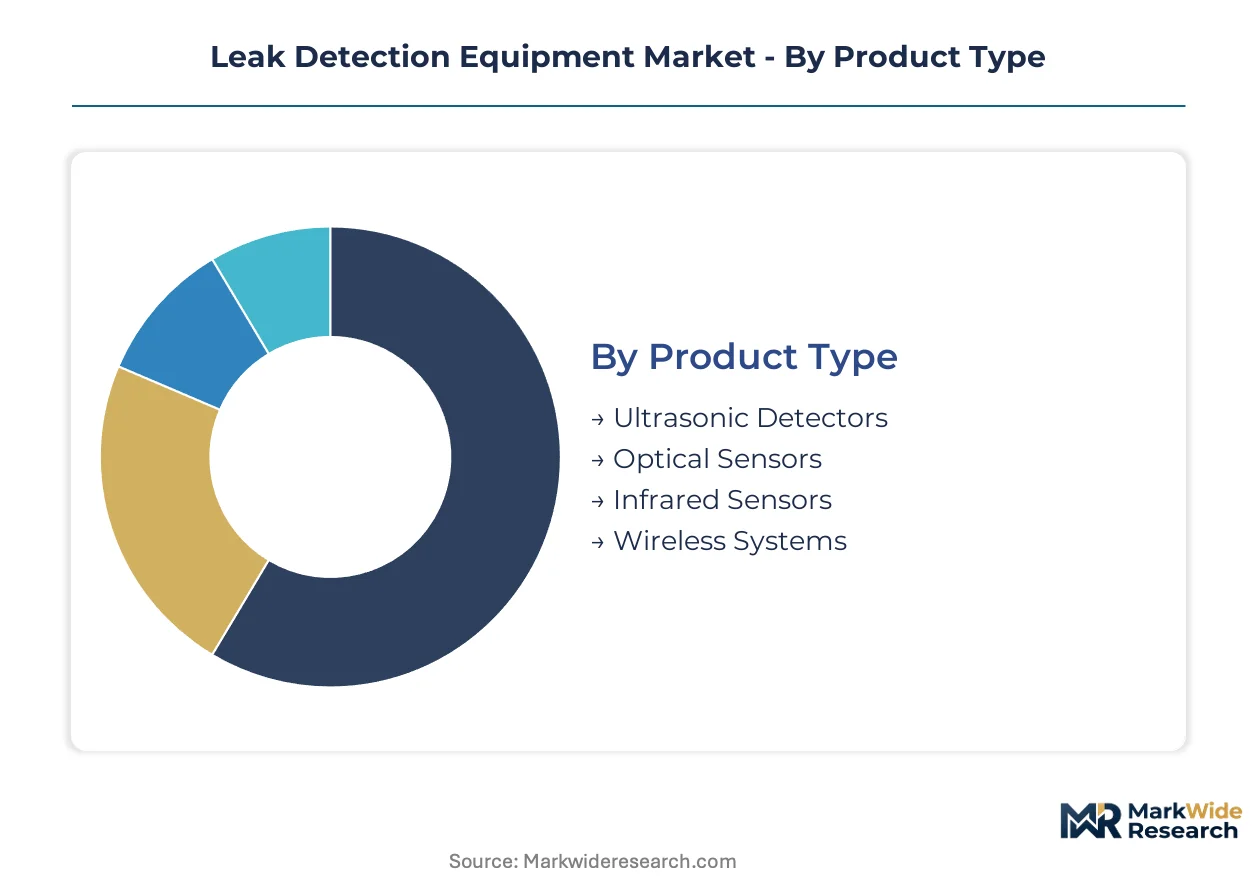
Leak detection equipment procurement varies sharply by operational environment, with oil and gas operators prioritizing continuous monitoring sensitivity while municipal utilities weigh installation cost against maintenance access. Segmentation reveals how technology choices cascade through certification requirements, service contract structures, and replacement cycle timing.
Product Type:
Buyers differentiate primarily by detection sensitivity thresholds versus total cost of ownership across multi-decade infrastructure lifespans.
- Ultrasonic Detectors:These instruments detect high-frequency acoustic signatures generated by pressurized gas escaping through pipeline fractures. Demand concentrates in aging North American pipeline networks where non-invasive mounting preserves operational continuity during retrofit installations.
- Optical Sensors:Systems employing laser absorption spectroscopy or fiber-optic distributed sensing achieve parts-per-million sensitivity for methane and hydrogen. Germany's hydrogen pipeline conversion programs are accelerating replacement cycles as existing optical installations lack compatibility with hydrogen's distinct permeation characteristics.
- Infrared Sensors:Thermal imaging arrays deployed for rapid area surveys and unmanned aerial vehicle integration.
- Wireless Systems:Battery-powered nodes eliminating trenching costs for municipal water utilities with constrained capital budgets.
Volume sits with Ultrasonic Detectors; growth tilts toward Optical Sensors.
Application:
Regulatory stringency and commodity value density determine capital allocation priorities across end-use environments.
- Oil & Gas:Upstream and midstream operators deploy continuous monitoring to satisfy EPA methane performance standards across compressor stations and gathering lines. Fiber-optic distributed sensing is displacing point-source arrays in high-value subsea corridors.
- Water Distribution:Municipal utilities prioritize wireless acoustic and pressure-based systems for non-revenue water reduction. Battery-powered nodes are gaining share fastest in United States cities with aging cast-iron infrastructure.
- HVAC Systems:Refrigerant leak detection for commercial buildings and industrial cooling installations.
- Chemical Processing:Process safety monitoring for toxic and flammable material containment.
Revenue concentrates in Oil & Gas; expansion is steepest in Water Distribution.
End User:
Procurement sophistication spans from centralized utility technical specifications to fragmented residential contractor preferences.
- Utilities:Electric, gas, and water utilities specify certified equipment with decade-long service contracts. Germany's hydrogen network operators are driving sensor replacement demand through technical compatibility requirements.
- Manufacturing:Process industries under EU Green Deal Scope 3 disclosure mandates install verified leak detection for supply chain carbon accounting.
- Construction:Mechanical contractors source portable detection for commissioning and quality assurance.
- Residential:Smart home integration and consumer-grade natural gas alarms.
Contract value peaks with Utilities; penetration is climbing fastest in Manufacturing.
Technology:
Underlying physical principles determine maintenance overhead, calibration frequency, and integration complexity with legacy control systems.
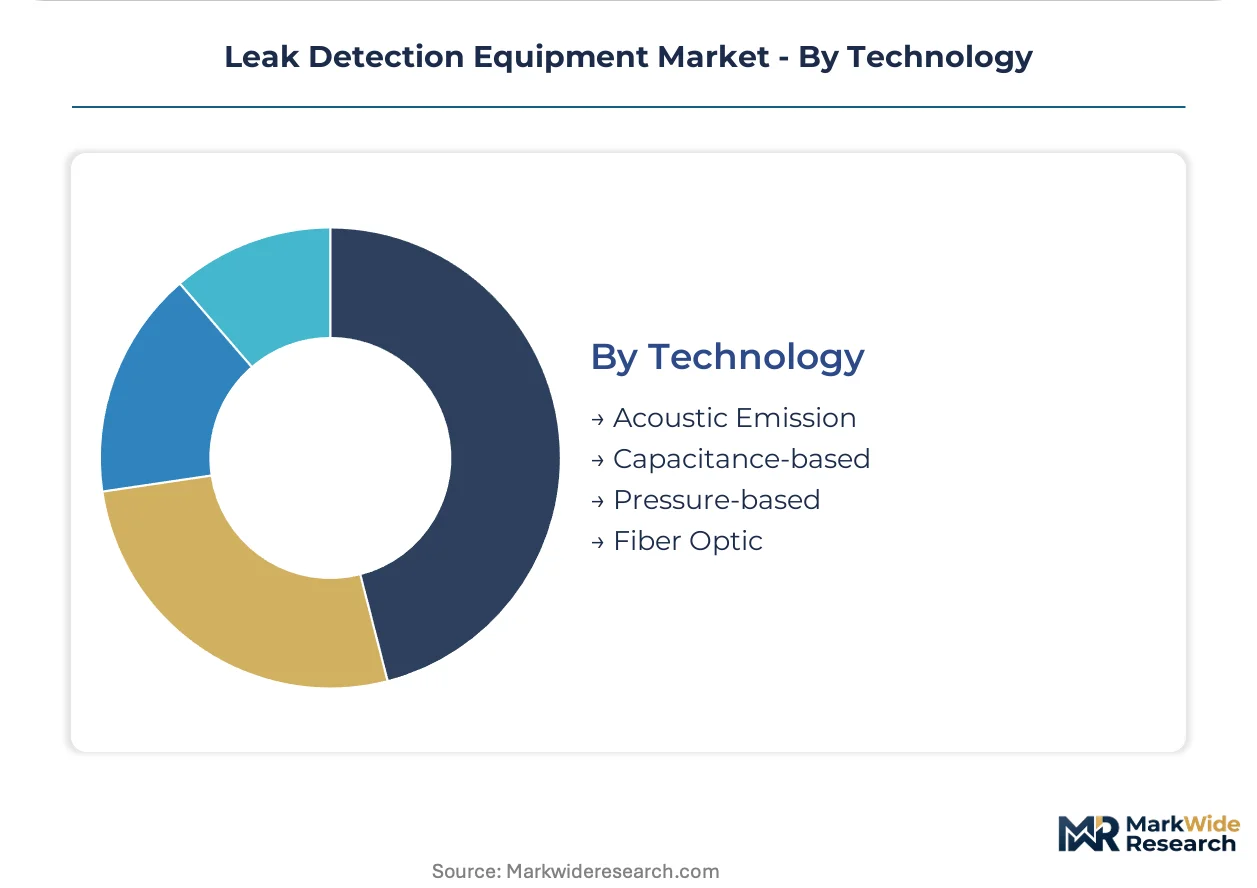
- Fiber Optic:Kilometer-scale distributed temperature and strain monitoring via standard telecommunications cable eliminates powered electronics in the field. Subsea pipeline operators in the North Sea and Gulf of Mexico are adopting this modality to reduce offshore maintenance visits.
- Acoustic Emission:Piezoelectric sensors detecting stress-wave energy from crack propagation and leakage. United States municipal water utilities favor this approach for its independence from fluid chemistry and temperature.
- Capacitance-based:Dielectric measurement systems for liquid leak detection in contained environments.
- Pressure-based:Differential monitoring for pipeline integrity management in regulated oil and gas corridors.
Deployment volume favors Acoustic Emission; capability investment is concentrating in Fiber Optic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin special economic zone concentrates upstream oil and gas infrastructure investment, drawing continuous monitoring system deployments from integrated operators seeking EPA compliance. Hydrogen pipeline conversion programs in Germany's industrial heartland accelerate sensor replacement cycles. Subsea corridor developments in the North Sea and Gulf of Mexico favor fiber-optic distributed sensing to reduce offshore maintenance visits.
United States
Upstream operators in the Permian Basin and Appalachian shale corridors deploy continuous monitoring to satisfy EPA methane performance standards across compressor stations. The IRA's enhanced tax credits for methane abatement infrastructure compress capital recovery timelines for fiber-optic sensing arrays. Houston anchors midstream technical service concentration, with independent pipeline companies sourcing leak detection maintenance through competitive RFP processes.
Germany
Hydrogen pipeline retrofit programs in the Ruhr industrial cluster drive sensor replacement demand as existing optical installations lack hydrogen compatibility. The EU Green Deal's Scope 3 disclosure mandates force process industries to install certified systems for supply chain carbon accounting. Bavaria's precision photonics suppliers concentrate narrow-band laser sources for distributed acoustic sensing interrogator units.
China
MIIT's industrial safety standards tighten emission monitoring requirements across petrochemical corridors in the Yangtze River Delta. State pipeline operators invest in kilometer-scale fiber-optic monitoring for West-East gas transmission infrastructure. Shanghai's industrial automation cluster hosts system integrators bridging legacy SCADA architectures with new continuous monitoring platforms.
United Kingdom
North Sea subsea pipeline operators adopt fiber-optic distributed sensing to eliminate powered electronics in offshore installations. The North Sea Transition Authority's decommissioning timelines accelerate integrity monitoring investments across aging infrastructure. Aberdeen's energy technology cluster concentrates vendors serving platform operators with predictive maintenance contracts.
United Arab Emirates
ADNOC's infrastructure expansion in the Al Dhafra region drives demand for high-temperature optical sensors in desert pipeline corridors. The country's national petroleum regulator mandates continuous monitoring for sour gas processing facilities. Dubai's industrial free zones host regional technical service centers supporting deployment across GCC pipeline networks.
Leak Detection Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology modalities and service contract structures. The vendor base stratifies between integrated industrial automation groups and dedicated sensing technology developers. Three archetypes dominate: full-stack automation providers bundling leak detection into broader infrastructure contracts; photonics specialists concentrating on fiber-optic interrogator hardware; and third-party service firms capturing unbundled maintenance revenue from independent operators. Competitive positioning hinges on dual EPA-EU certification portfolios and predictive maintenance software integration.
Among diversified industrial technology groups, Honeywell International Inc. and Siemens AG anchor the automation-integrated tier, exemplifying full-stack providers that bundle sensing hardware with enterprise control platforms. INFICON Holding AG occupies a position within the precision instrumentation specialist tier, representing pure-play developers focused on gas analysis and leak detection technologies. These three entities illustrate how competitive positioning diverges between scale-driven conglomerates and technology-focused specialists.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Schneider Electric SE |
| Emerson Electric Co. |
| INFICON Holding AG |
| Pentair plc |
| Teledyne Technologies |
| ATEQ Corp. |
| Testo SE & Co. KGaA |
| Others |
Supply & Pricing Matrix
Narrow-band laser sources from German and Japanese optical component suppliers cascade through distributed acoustic sensing interrogator pricing tiers, with premium units commanding substantial markups over standard configurations due to extended calibration lead times and dual EPA-EU certification overhead.
Pricing Analysis
Short lead-time premiums for certified optical sensors compress margins on standard ultrasonic detector configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in economy-tier ultrasonic arrays stems from thermal imaging drone substitution in routine inspection applications. Municipal water utilities exhibit highest price sensitivity, while integrated oil and gas operators prioritize sensitivity thresholds over unit economics.
Supply Chain Analysis
Precision photonics workforce availability in Bavaria and Tokyo metropolitan clusters constrains interrogator unit output capacity. Manufacturing concentrates in Germany, Japan, and the United States for core sensing modalities. Supply chains draw from specialized germanium substrates, erbium-doped fiber amplifiers, and hermetic sealing ceramics. Single-source vulnerability in coherent laser sources threatens distributed sensing deployment timelines. Distribution runs through direct OEM contracts for oil and gas operators and regional system integrators for municipal utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The leak detection equipment market functions as a vertical-integration race where captive control over photonics component supply separates margin leaders from price-takers in optical sensing categories.
For Market Incumbents: Deepen backward integration into narrow-band laser source manufacturing to escape German and Japanese supplier bottlenecks. Acquire hydrogen-compatible materials science capabilities ahead of pipeline retrofit demand acceleration. Satellite-based methane mapping and thermal imaging drones threaten ground-based ultrasonic array maintenance contracts. For New Entrants and Emerging Players: The mid-tier price-point gap between fiber-optic distributed sensing and point-source acoustic arrays opens white-space in wireless battery-powered nodes for United States municipal water utilities. Target cash-constrained cities with aging cast-iron infrastructure through hardware-as-a-service financing structures. Pursue third-party maintenance contracts unbundled from initial procurement by independent midstream operators lacking captive technical service organizations. For Investors and Strategic Acquirers: ADNOC's infrastructure expansion in the Al Dhafra region is the leading indicator that high-temperature optical sensor demand in desert pipeline corridors warrants long-term capability bets. Acquire photonics specialists with hydrogen compatibility R&D pipelines and dual EPA-EU certification portfolios. Watch for MIIT industrial safety standard tightening across Yangtze River Delta petrochemical corridors as inflection signal for China market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Photonics Component Backward Integration | Captive laser source production in Bavaria eliminates supply bottlenecks for distributed acoustic sensing interrogators. |
| Hydrogen Compatibility Certification Investment | Dual EPA-EU approval for hydrogen-permeation sensors captures Germany's Ruhr industrial cluster retrofit demand. |
| Wireless Node Hardware-as-a-Service Launch | Battery-powered acoustic sensors eliminate trenching costs for United States municipal water utilities with constrained capital budgets. |
| Predictive Maintenance Software Platform Development | Digital twin integration with real-time leak detection data shifts revenue from hardware sales to recurring subscriptions. |
| Regional Technical Service Center Expansion | Dubai industrial free zone positioning captures ADNOC sour gas processing facility maintenance contracts across GCC pipeline networks. |
Research Methodology
Document review covered EPA methane performance standard filings, EU Green Deal technical documentation, and MIIT industrial safety circulars, complemented by interviews with pipeline integrity managers at integrated oil and gas operators, municipal water utility maintenance directors, and photonics component procurement leads at distributed sensing system manufacturers. Secondary validation drew from FERC infrastructure investment disclosures, ECHA REACH restriction updates, and customs trade data for optical sensor imports. Bottom-up equipment shipment analysis and top-down infrastructure investment tracking were triangulated against regulatory compliance timeline assumptions.
Historical capital expenditure patterns across compressor station and gathering line deployments were cross-referenced against panel input from midstream planning officers and EPC contractors. Segmentation modeling spanned product type, application environment, end-user procurement sophistication, and underlying detection technology across the analysis window. CAGRs were derived from infrastructure replacement cycle compression under fugitive emission mandates and hydrogen pipeline conversion program acceleration. Forecast inputs incorporated SCADA integration complexity premiums and predictive maintenance contract attach rates.
Inputs from EPA enforcement action databases and EU Green Deal implementation timelines were available through the study window; gaps in hydrogen embrittlement sensor field performance data introduce uncertainty bands around technology transition assumptions. Forecasts reflect documented regulatory compliance trajectories and infrastructure investment commitments. Material deviation in methane performance standard enforcement intensity or hydrogen pipeline conversion funding authorization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Chemical Detection Armband Market
Detection and Regulation Devices
Wireless Gas Detection System Market
Detection and Regulation Devices
Underwater Signaling Devices Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Radiation Detection Device Market
Detection and Regulation Devices
Global Wireless Gas Detection Market
Detection and Regulation Devices
Portable Metal Detectors Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Middle East and Africa Trace Detection Market
Detection and Regulation Devices
Compliance Monitoring Devices Market
Detection and Regulation Devices
Europe Gas Detectors Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market
Detection and Regulation Devices
Frequency Counter Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
Global Gas Sensors Market