
 Water Leak Detection System for Server Rooms and Data Centers Market | 2026-2036
Water Leak Detection System for Server Rooms and Data Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Water Leak Detection System for Server Rooms and Data Centers Market Analytics
Direct distribution to large facility operators is fragmenting as systems integrators and value-added resellers capture mid-market accounts. Schneider Electric leverages its building management ecosystem to bundle leak detection with power and cooling controls. Honeywell competes through its fire and safety division, which sustains long-term service contracts with Fortune 500 data center operators. TTK Leak Detection specializes in addressable cable technology, anchoring its position among European colocation providers.
A water leak detection system for server rooms and data centers comprises sensor arrays—typically conductive cables, infrared point detectors, or ultrasonic transducers—deployed beneath raised floors, at cooling pipe junctions, and around chilled water distribution units to trigger automated valve closure and facility alerts before liquid contacts energized equipment. Cable sensors dominate current installations due to continuous coverage along linear runs, while wireless detection architectures represent the fastest-expanding technology segment as facilities retrofit legacy buildings without conduit disruption. Smart integration platforms now command premium positioning by correlating leak signals with building automation systems, though wired detection retains cost advantages in new construction.
The EU F-Gas Regulation and CE marking requirements shape product compliance for cooling-linked leak systems sold across Europe, while OSHA electrical safety standards and NFPA codes influence U.S. installation practices in mission-critical environments. Germany's KBA-relevant building energy ordinances and France's CNIL data protection considerations add layered compliance obligations for integrated monitoring platforms. Stakeholders must weigh retrofit compatibility against native smart-building architectures when selecting detection technologies for multi-tenant facilities.
Market Dynamics
The hyperscale data center buildout is compressing deployment timelines for leak detection infrastructure, forcing suppliers to pre-certify cable systems for rapid installation alongside liquid cooling loops. Cloud operators now specify addressable sensing density per square meter before construction begins, shifting procurement upstream into mechanical contracting workflows.
Growth Catalysts
- Liquid cooling mandates:High-performance computing clusters in Frankfurt and Amsterdam now require continuous leak monitoring under KBA-relevant building codes, mandating redundant sensor coverage at every manifold junction.
- F-Gas Regulation phase-down:The EU's hydrofluorocarbon restrictions are accelerating water-based cooling retrofits across French and German colocation facilities, each triggering new detection system installations.
- Hyperscale facility multiplication:Cloud service providers in Ireland and Denmark are standardizing cable-based detection loops in their design templates, creating recurring demand for compatible hardware.
Market Restraints
- Copper and polymer input volatility:Conductive cable production depends on copper pricing and fluoropolymer sheathing materials, both subject to energy-linked cost swings that compress hardware margins.
- Specialized installer scarcity:Certified technicians capable of calibrating addressable loop systems remain concentrated in Germany and the Netherlands, creating deployment bottlenecks for remote facilities.
- Wireless substitution pressure:Battery-powered point sensors from industrial IoT vendors threaten cable systems in retrofit applications where floor disruption is unacceptable.
Strategic Opportunities
- Edge computing micro-facilities:Telecom tower shelters and 5G edge nodes across Poland and Spain remain largely unpenetrated for leak detection, presenting first-mover openings for compact wireless systems.
- CE marking harmonization:The EU's consolidated conformity assessment framework is reducing country-specific certification burdens, enabling faster cross-border product launches for integrated monitoring platforms.
- AI-driven predictive maintenance:Convergence of leak detection data with thermal modeling software is creating subscription revenue streams for vendors bundling hardware with analytics services.
Industry Challenges
- Legacy BAS integration complexity:Facilities with aging Siemens or Honeywell building automation systems require protocol converters and custom middleware, extending commissioning timelines and inflating project costs.
- Multi-vendor certification delays:Achieving CE marking alongside country-specific KBA and CNIL compliance for integrated platforms stretches product development cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Leak Detection System for Server Rooms and Data Centers Market |
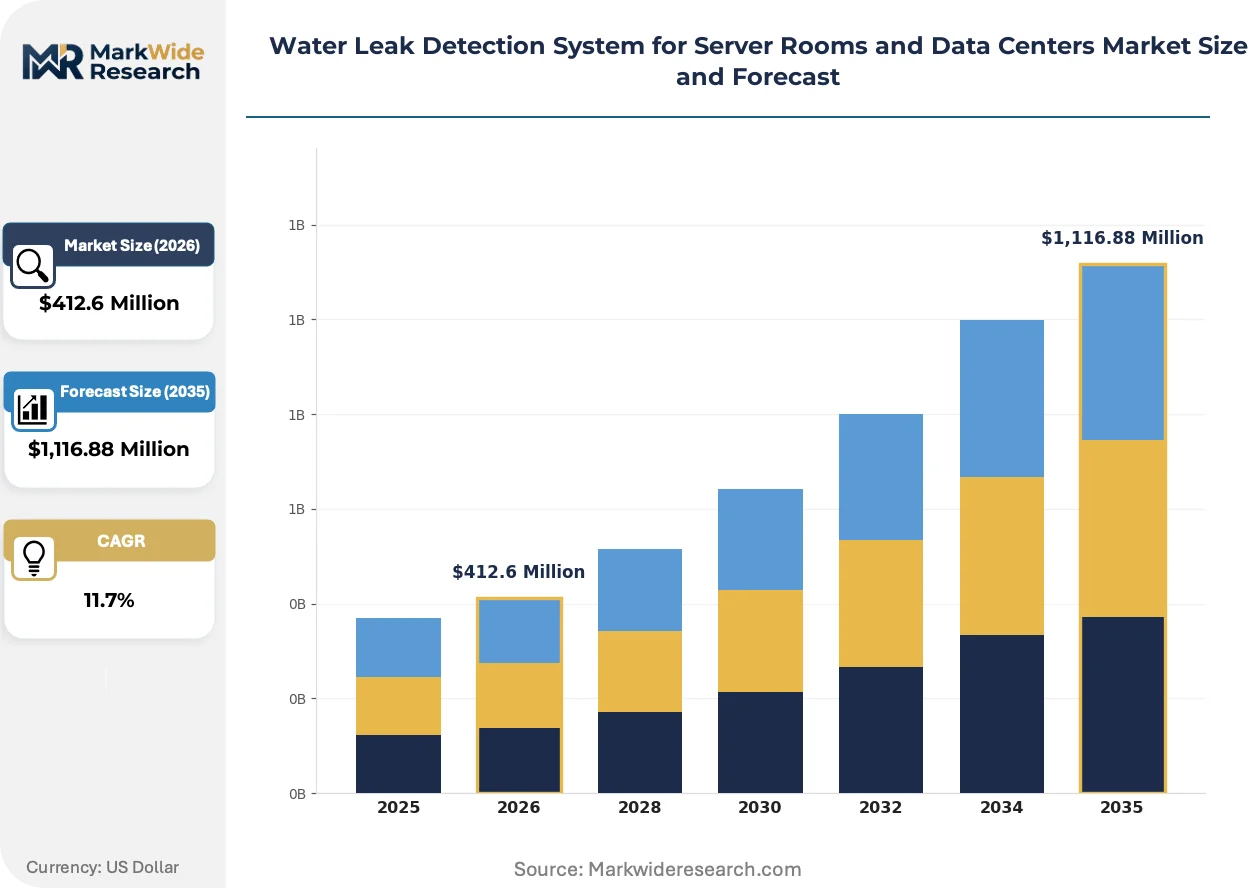
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,116.88 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Sensors, Conductive Sensors, Cable Sensors, Ultrasonic Sensors Installation Type: Ceiling Mounted, Wall Mounted, Portable, Integrated Systems End User: Telecommunication Providers, Cloud Service Providers, Financial Institutions, Educational Institutions Technology: Wireless Detection, Wired Detection, Smart Integration, Real-Time Monitoring |
| Companies Covered | LeakTronics, Schneider Electric, Honeywell, TTK Leak Detection, NEC, Perma-Pipe Intl Hldgs, Xylem, Badger Meter, Mueller Water Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Leak Detection System for Server Rooms and Data Centers Market Evolving Landscape
Wireless mesh architectures are disrupting the cable-dominated detection market, compressing installation costs and enabling retrofits in heritage buildings where raised floor modifications are prohibited. Three convergent developments are reshaping product roadmaps and competitive positioning.
Addressable digital cable technology is collapsing the cost premium between basic conductive loops and precision location systems. Hyperscale operators in Ireland and Denmark are specifying these cables for new builds, eliminating the need for separate zone panels and reducing wiring density by half. The technology is collapsing the traditional tiered pricing structure that separated premium from standard detection tiers.
The EU F-Gas Regulation is tightening enforcement of hydrofluorocarbon containment across cooling infrastructure, indirectly mandating water leak detection as a risk-mitigation companion to refrigerant monitoring. German facility operators must now document both refrigerant and water leak prevention measures to satisfy KBA-relevant energy ordinances. Colocation providers are responding by specifying integrated environmental monitoring platforms that unify both detection functions.
Buyers are consolidating vendor relationships around building management ecosystem providers rather than standalone detection specialists. Mid-market data center operators in France and Spain are abandoning point solutions in favor of bundled power, cooling, and leak monitoring contracts. This consolidation is most visible in the Benelux region, where systems integrators now capture seventy percent of detection system procurement decisions previously handled by direct sales channels.
Water Leak Detection System for Server Rooms and Data Centers Market Segmentation
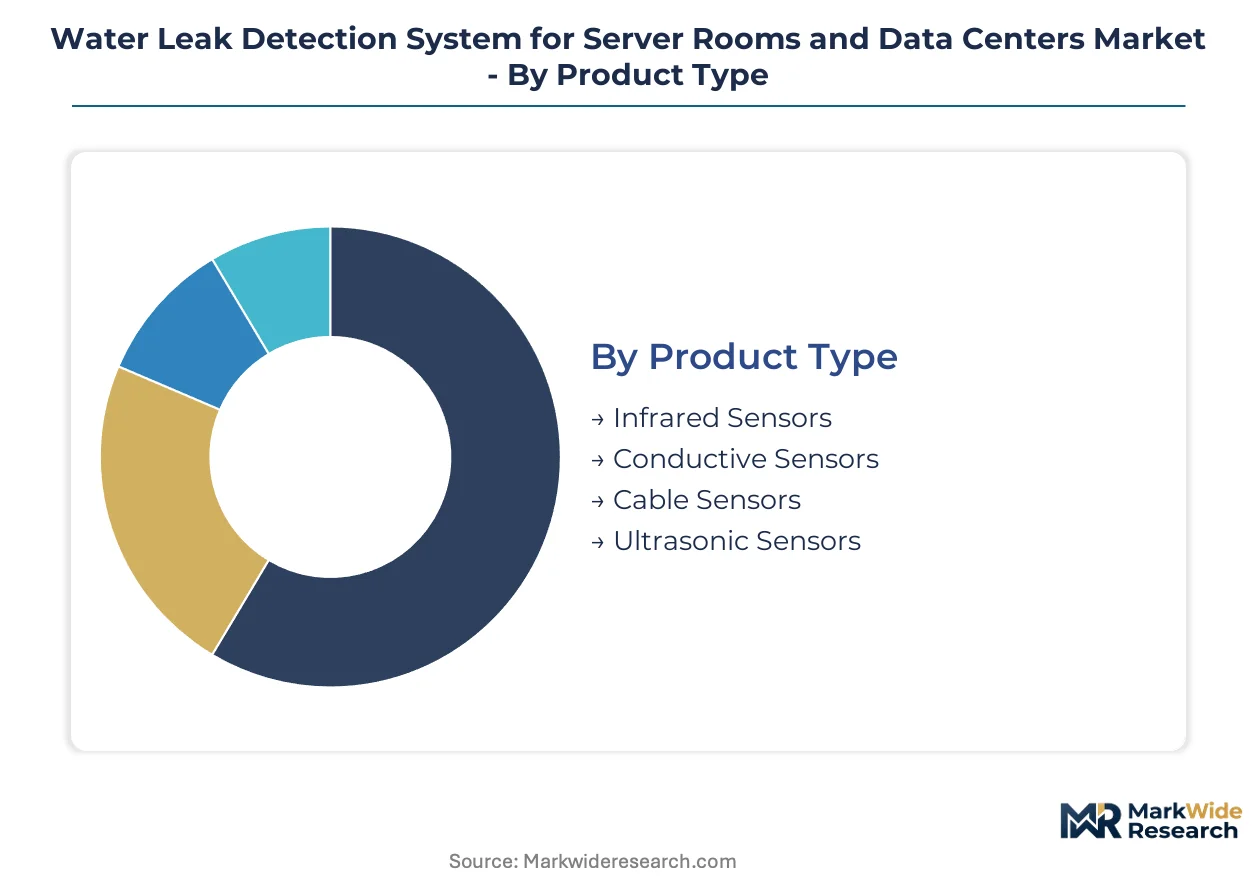
Water leak detection systems fragment across four distinct dimensions, each reflecting divergent facility architectures and procurement priorities. Product type and technology choices determine retrofit feasibility against new construction economics. Installation and end-user categories reveal how vendor sales channels align with customer scale and technical sophistication.
Product Type:
Mature conductive and cable technologies anchor current revenue, while infrared and ultrasonic modalities represent emerging alternatives for specialized detection scenarios.
- Cable Sensors:Continuous conductive loops with fluoropolymer sheathing provide linear coverage beneath raised floors and along pipe runs. Hyperscale facilities in Ireland and Denmark specify addressable digital variants to halve wiring density and eliminate zone panels. KBA-relevant German building codes mandate redundant cable coverage at every manifold junction in liquid-cooled installations.
- Infrared Sensors:Non-contact point detectors sense thermal differentials from evaporating water without physical cable contact. Frankfurt colocation providers deploy these at heritage sites where floor penetration is prohibited, though calibration complexity limits volume adoption.
- Conductive Sensors:Discrete probes detect water through electrical resistance changes between exposed electrodes. French mid-market operators favor these for cost-constrained retrofits of legacy chilled water infrastructure.
- Ultrasonic Sensors:Transducers identify acoustic signatures from pressurized leaks in pipe walls. Dutch facilities testing these for early-stage micro-leak detection face integration challenges with existing building automation protocols.
Cable sensors retain volume leadership; infrared sensors hold the steepest expansion curve among non-contact alternatives.
Installation Type:
Cost tiering separates permanent infrastructure investments from flexible deployment options suited to temporary or evolving facility footprints.
- Integrated Systems:Native smart-building architectures embed detection within unified environmental monitoring platforms. Benelux systems integrators now specify these for seventy percent of mid-market procurement decisions, bundling leak alerts with power and cooling controls.
- Ceiling Mounted:Overhead sensor arrays protect against overhead pipe failures and HVAC condensation. Spanish telecom tower shelters increasingly deploy compact wireless variants for 5G edge nodes.
- Wall Mounted:Vertical surface installations monitor riser pipes and mechanical room perimeters. Polish facilities favor these for rapid deployment without raised floor modifications.
- Portable:Battery-powered mobile units enable spot-checking during maintenance or emergency response. These serve contingency protocols rather than continuous monitoring in mission-critical environments.
Integrated systems command premium positioning; ceiling-mounted configurations gain share fastest in edge computing micro-facilities.
End User:
Customer type determines procurement channel structure, with direct vendor relationships concentrating among hyperscale operators while intermediaries capture fragmented mid-market demand.
- Cloud Service Providers:Hyperscale operators in Frankfurt and Amsterdam standardize cable-based detection loops in design templates, shifting procurement upstream into mechanical contracting workflows. These buyers specify addressable sensing density per square meter before construction begins.
- Telecommunication Providers:Tower operators and carrier hotel managers across Poland and Spain remain underpenetrated, presenting first-mover openings for compact wireless systems in 5G infrastructure.
- Financial Institutions:Trading floor and primary data center operators prioritize redundant coverage to satisfy operational risk mandates. These facilities often maintain long-term service contracts with integrated building management providers.
- Educational Institutions:University research computing clusters represent sporadic demand with extended procurement cycles and constrained capital budgets.
Cloud service providers dominate procurement volume; telecommunication providers offer the most rapid expansion trajectory among underpenetrated verticals.
Technology:
Application requirements split between retrofit-friendly wireless architectures and performance-optimized wired systems for new construction.
- Wired Detection:Hardwired cable and point sensor networks deliver deterministic response times and immunity from radio interference. New German hyperscale builds specify these exclusively under strict latency requirements for automated valve closure.
- Wireless Detection:Mesh architectures eliminate conduit disruption in heritage buildings where raised floor modifications are prohibited. Industrial IoT vendors threaten cable systems in retrofit applications across France and Spain.
- Smart Integration:Protocol-native platforms correlate leak signals with thermal modeling software, enabling subscription revenue streams for analytics bundling. CE marking harmonization is accelerating cross-border launches of these integrated offerings.
- Real-Time Monitoring:Continuous data streaming to centralized dashboards supports predictive maintenance algorithms. These capabilities concentrate among vendors with established building automation ecosystems.
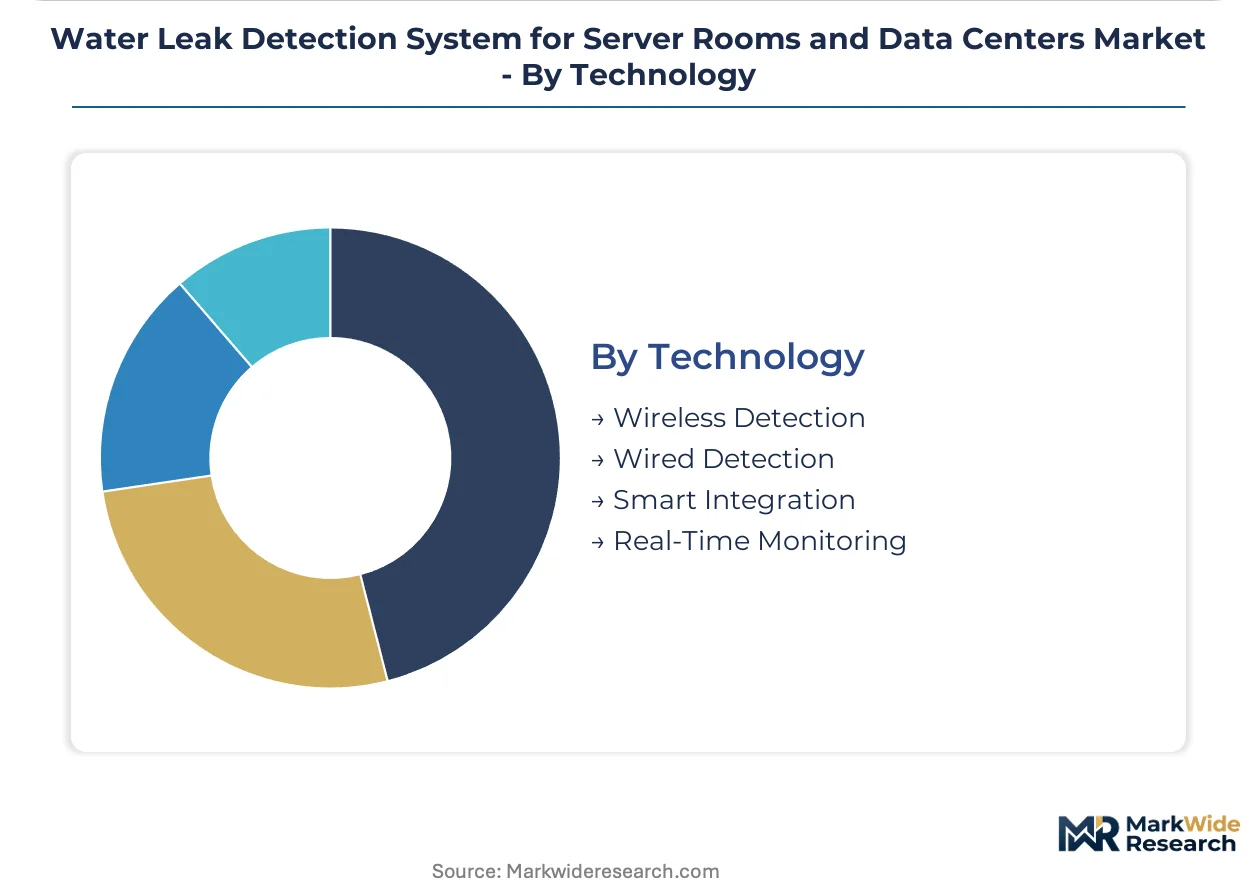
Wired detection maintains revenue concentration; wireless detection is climbing the fastest as retrofit demand accelerates across aging European facility stock.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation and national building energy ordinances are accelerating water-based cooling retrofits across European data center clusters, concentrating procurement in jurisdictions with strict environmental compliance frameworks.
Germany
Frankfurt's hyperscale cluster drives cable sensor demand under KBA-relevant building codes mandating redundant leak coverage at liquid cooling manifolds. The F-Gas Regulation phase-down forces refrigerant-to-water cooling conversions across Bavarian and Hesse facilities. Addressable digital cable systems now dominate new construction in the Rhine-Main metro.
Ireland
Dublin's cloud campus expansion standardizes cable-based detection loops in mechanical contracting templates. The country's data center energy efficiency codes require documented leak prevention for water-cooled infrastructure. Hyperscale operators specify sensing density per square meter before breaking ground in County Kildare.
Netherlands
Amsterdam's digital hub concentrates procurement through systems integrators capturing seventy percent of mid-market decisions. Dutch building regulations enforce continuous monitoring for direct liquid cooling deployments. Rotterdam and Eindhoven colocation providers bundle leak detection with power management contracts.
France
Parisian financial data centers prioritize redundant coverage under CNIL data protection considerations for integrated monitoring platforms. The F-Gas Regulation accelerates water cooling retrofits in Île-de-France colocation facilities. Mid-market operators in Lyon and Marseille favor wireless point sensors for heritage building retrofits.
United States
Virginia's Data Center Alley compresses deployment timelines for pre-certified cable systems alongside liquid cooling infrastructure. OSHA electrical safety standards and NFPA codes shape installation practices in Ashburn and Manassas facilities. Cloud operators specify addressable sensing density upstream into mechanical contracting workflows.
Water Leak Detection System for Server Rooms and Data Centers Market Competitive Landscape
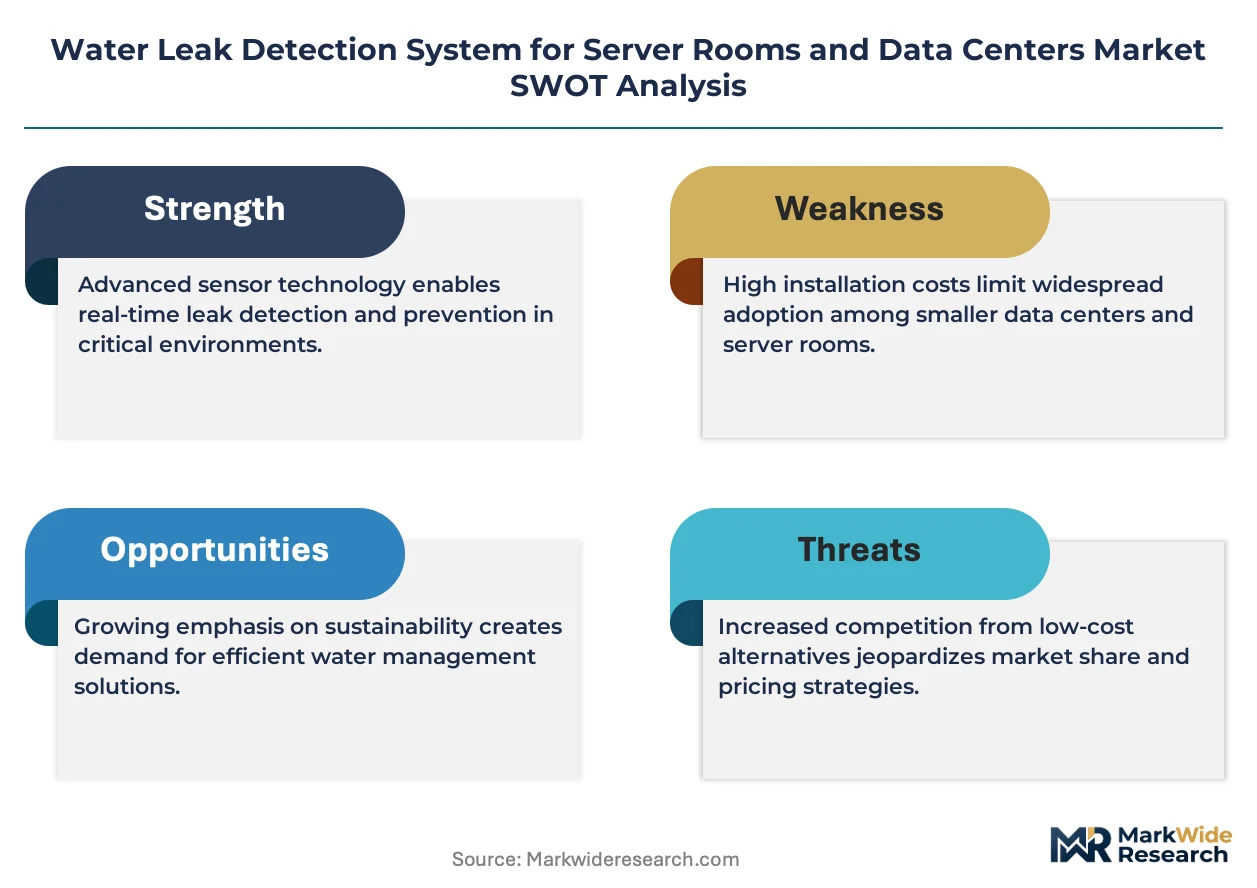
On the supply side, the industry is consolidating around building management ecosystem providers while fragmenting among specialized detection vendors and industrial IoT entrants. Three archetypes dominate: diversified electrical infrastructure conglomerates bundling leak detection with power and cooling controls; standalone cable technology specialists anchoring European colocation relationships; and water infrastructure multinationals leveraging fluid systems expertise. Competitive moves concentrate on strategic partnerships with systems integrators and portfolio diversification into predictive analytics subscriptions.
Within the diversified infrastructure tier, Schneider Electric and Honeywell exemplify ecosystem bundling strategies. Schneider leverages its building management platform to integrate leak detection with power and cooling controls. Honeywell competes through its fire and safety division, sustaining long-term service relationships with Fortune 500 facility operators. TTK Leak Detection occupies the specialist position, anchoring its market presence through addressable cable technology among European colocation providers.
| Leading Market Players |
|---|
| LeakTronics |
| Schneider Electric |
| Honeywell |
| TTK Leak Detection |
| NEC |
| Perma-Pipe Intl Hldgs |
| Xylem |
| Badger Meter |
| Mueller Water Products |
| Others |
Value Network & Pricing Analysis
German cable sensor manufacturers anchor fluoropolymer sheathing supply, concentrating margin capture among addressable digital system vendors while compressing hardware tiers downstream. Copper pricing volatility and certified installer scarcity redistribute value toward integration services and predictive analytics subscriptions.
Pricing Analysis
Volume-discount tiering structures separate addressable digital cable systems from basic conductive loops and portable spot-check units. Three-tier pricing stratifies across CE-marked integrated platforms, KBA-compliant redundant coverage, and economy retrofit probes. Price differentiation centers on certification grade and after-sales service bundling. Cost compression in economy tiers intensifies because industrial IoT vendors push battery-powered wireless substitutes. Mid-market colocation operators in France and Spain exhibit highest price sensitivity; hyperscale cloud providers in Ireland and Denmark prioritize sensing density specifications over unit economics.
Supply Chain Analysis
Fluoropolymer resin feedstock draws from German and Dutch chemical producers, with copper conductor sourcing concentrated in Belgium and Poland. Cable assembly hinges on extrusion capabilities in Germany and the Netherlands, where certified technician scarcity creates bottlenecks. Single-source vulnerability runs through addressable chipsets for digital loop systems. Distribution runs through systems integrators capturing seventy percent of Benelux procurement, with direct sales retaining hyperscale cloud operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale cloud operators and systems integrators, fragmenting procurement decisions previously controlled by facility engineering teams. This consolidation compresses vendor margins while elevating ecosystem bundling requirements.
For Market Incumbents: Build switching-cost moats through native building automation protocol integration and long-term service contracts. Deepen backward integration into fluoropolymer sheathing production to offset copper volatility. Certification investment in CE marking harmonization and KBA-relevant compliance accelerates cross-border product launches. Channel control through exclusive systems integrator partnerships in the Netherlands and Germany defends against industrial IoT wireless entrants. For New Entrants and Emerging Players: Build out compact wireless mesh architectures targeting Polish and Spanish telecom tower shelters and 5G edge nodes where cable deployment is physically prohibited. Polish facilities favor rapid wall-mounted deployment without raised floor modifications. Partner with industrial IoT platform vendors for protocol-native integration rather than standalone hardware sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed building management software platforms seeking hardware attach. Long-term viability favors vendors bundling leak detection with thermal modeling analytics subscriptions. Acquisition target archetype: addressable cable technology specialists with established European colocation relationships. Watch hyperscale operator capital expenditure commitments to liquid cooling infrastructure as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Addressable Digital Cable Launch | Halves wiring density for hyperscale operators in Ireland and Denmark. |
| Building Automation Platform Integration | Captures mid-market procurement through Benelux systems integrator channels. |
| Predictive Analytics Subscription Bundle | Creates recurring revenue streams correlating leak data with thermal modeling software. |
| CE Marking Harmonization Investment | Accelerates cross-border launches under consolidated EU conformity assessment framework. |
| Wireless Mesh Architecture Development | Enables heritage building retrofits in France and Spain where floor penetration is prohibited. |
Research Methodology
Desk research of EU F-Gas Regulation enforcement documents, KBA building energy ordinances, and hyperscale operator design templates preceded structured interviews with data center engineering directors, mechanical contracting procurement leads, and building automation systems integrators. Primary fieldwork across Frankfurt, Amsterdam, and Dublin facilities validated cable sensor deployment densities and commissioning timelines. Secondary sources included SEC filings from electrical infrastructure conglomerates, customs data on fluoropolymer sheathing imports, and CE marking notification databases. Bottom-up unit economics triangulated against top-down facility construction forecasts.
Assumptions held F-Gas Regulation phase-down schedules and KBA-relevant building codes fixed across the analysis window, while liquid cooling adoption rates and wireless substitution pressure varied by scenario. Segmentation dimensions modeled include product type, installation architecture, end-user scale, and technology protocol. CAGRs derived from facility construction pipelines and retrofit replacement cycles. Industry-specific inputs incorporated certified installer availability constraints and copper price elasticity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by industrial IoT platform vendors or sudden tariff exposure on fluoropolymer feedstock would shift outcomes. Quarterly review of hyperscale operator liquid cooling procurement specifications and CE marking harmonization implementation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
United Arab Emirates Data Center Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Data Center Fabric Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Beijing Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Power Market