
 North America Data Center Construction Market | 2026-2036
North America Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
North America Data Center Construction Market Insights
Electrical trades labor availability is bifurcating project timelines across North America, with some markets facing eighteen-month commissioning delays while others advance on schedule. DPR Construction leverages its self-perform electrical capability to compress delivery schedules in constrained labor markets. Jacobs Solutions Inc. sustains engineering throughput across multiple hyperscale programs through modular design standardization. Hensel Phelps anchors its position in Texas and Arizona markets where trade density supports faster workforce mobilization.
Data center construction encompasses the design, engineering, and physical build-out of facilities housing servers, storage, and networking equipment, with critical infrastructure specifications including N+1 or 2N redundancy in power distribution and cooling systems rated to maintain temperatures within ASHRAE thermal guidelines. These structures serve as the physical backbone for cloud computing, enterprise IT, and artificial intelligence workloads. Tier 3 and Tier 4 building types command premium construction margins due to fault-tolerant redundancy requirements that extend mechanical and electrical scope. Modular structure types are gaining share as repeatability reduces field labor exposure and compresses time-to-revenue for operator clients. Design-build delivery models are displacing traditional design-bid-build sequences as single-source accountability aligns contractor incentives with speed-to-market objectives.
OSHA standards govern worker safety protocols during high-voltage electrical installation and confined-space mechanical work, while the U.S. EPA oversees refrigerant management in cooling systems and stormwater discharge during site development. State-level utility commissions in Virginia, Texas, and Arizona shape interconnection timelines that directly constrain project completion dates. Stakeholders must monitor interconnection queue depth and local permitting velocity as primary determinants of executable project pipelines.
Market Dynamics
The North America data center construction market faces acute electrical trades labor scarcity that bifurcates project timelines across jurisdictions, compressing margins in constrained markets while rewarding contractors with captive workforce capabilities.
Growth Catalysts
- The U.S. Inflation Reduction Act:Tax credits for renewable energy procurement accelerate solar and wind-powered facility development across Arizona and Texas, reducing long-term operational expenditure for hyperscale operators.
- Hyperscale cloud expansion:Amazon Web Services, Microsoft Azure, and Google Cloud are commissioning multi-gigawatt campuses in Northern Virginia's Data Center Alley, creating sustained demand for Tier 4 redundant infrastructure.
- Liquid cooling adoption:Direct-to-chip and immersion cooling technologies enable higher rack densities for artificial intelligence training clusters, extending mechanical scope and construction contract values.
Market Restraints
- Copper and electrical equipment cost volatility:Transformer lead times now extend twelve to eighteen months, forcing contractors to pre-purchase critical path components and absorb working capital strain.
- Utility interconnection queue depth:Regional transmission organizations in PJM and ERCOT territories face multi-year backlogs that delay energization dates regardless of construction completion.
- Permitting velocity fragmentation:Loudoun County, Virginia maintains ninety-day approval windows while Prince William County extends beyond two hundred days, creating site selection arbitrage that concentrates risk in fewer jurisdictions.
Strategic Opportunities
- Modular prefabrication convergence:Factory-built power modules and cooling skids reduce field labor exposure by forty percent, compressing commissioning schedules in constrained markets.
- Dallas-Fort Worth expansion:Texas markets offer lower land costs, favorable tax treatment, and denser electrical trades availability compared to Northern Virginia saturation.
- State renewable portfolio standards:California and New York mandates for carbon-neutral operations by 2030 create retrofit and greenfield construction demand for on-site generation and battery storage integration.
Industry Challenges
- High-voltage electrician certification gaps:OSHA 1910.269 qualified worker requirements exceed available training pipeline output, forcing wage escalation and schedule compression tactics.
- Integrated system commissioning complexity:Simultaneous energization of multi-vendor electrical, mechanical, and fire suppression systems requires specialized commissioning agents that remain in short supply.
- N+1 redundancy validation:Tier Institute certification demands documented failover testing that extends project closeout timelines and exposes contractors to liquidated damages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Data Center Construction Market |
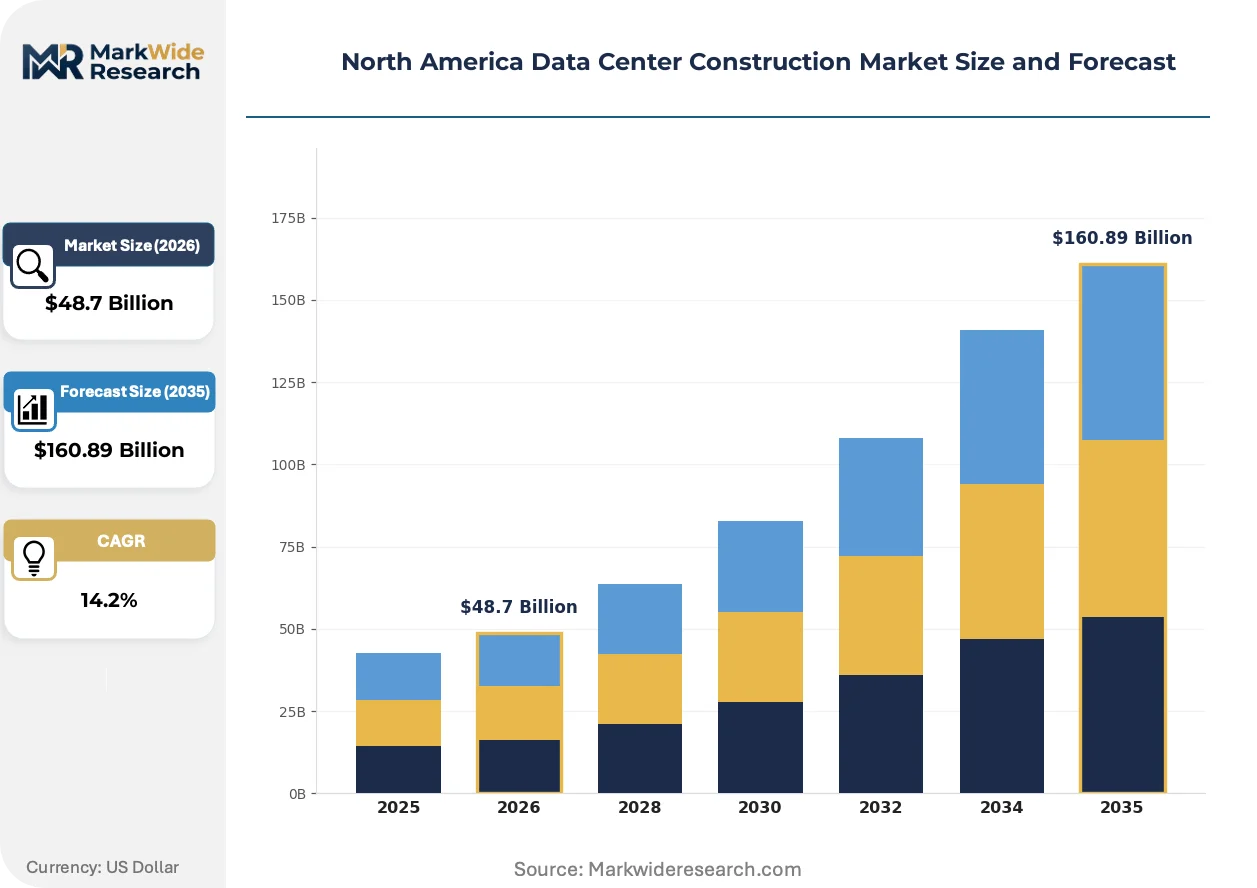
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Tier 1, Tier 2, Tier 3, Tier 4 Structure Type: Pre-engineered, Modular, Infill, Greenfield Power Source: Renewable, Non-renewable, Hybrid, Backup Delivery Model: Design-Bid-Build, Design-Build, Turnkey, Integrated |
| Companies Covered | Equinix, Inc., Digital Realty, DPR Construction, Jacobs Solutions Inc., Skanska AB, Balfour Beatty plc, Whiting-Turner Contracting Co., Hensel Phelps, Gensler, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Data Center Construction Market Trends and Innovations
Artificial intelligence workload density is rewriting mechanical and electrical specifications across North American data center construction, favoring liquid-cooled designs and higher-voltage power distribution that legacy air-cooled facilities cannot accommodate.
Immersion cooling using dielectric fluids is supplanting traditional raised-floor air conditioning in hyperscale facilities targeting fifty kilowatt-plus rack densities. Meta Platforms and Microsoft have specified single-phase immersion for 2025 campus expansions. This technology is supplanting conventional chiller plants and enabling construction in markets previously rejected for insufficient water access or ambient cooling capacity.
The U.S. EPA's phasedown of hydrofluorocarbon refrigerants under the American Innovation and Manufacturing Act is accelerating adoption of natural refrigerant systems using ammonia and carbon dioxide. Equipment manufacturers are retooling production lines to meet 2027 GWP limits. Texas and Arizona projects are specifying transcritical CO2 systems to future-proof against state-level refrigerant restrictions that typically follow federal precedent.
Design-build delivery models now dominate hyperscale procurement, displacing traditional design-bid-build sequences that fragmented accountability between architect, engineer, and constructor. Single-source contractors assume performance risk for power usage effectiveness guarantees and energization schedules. This shift concentrates most visibly in Northern Virginia where Dominion Energy interconnection dates function as hard commercial deadlines that design-build teams optimize against.
North America Data Center Construction Market Segmentation
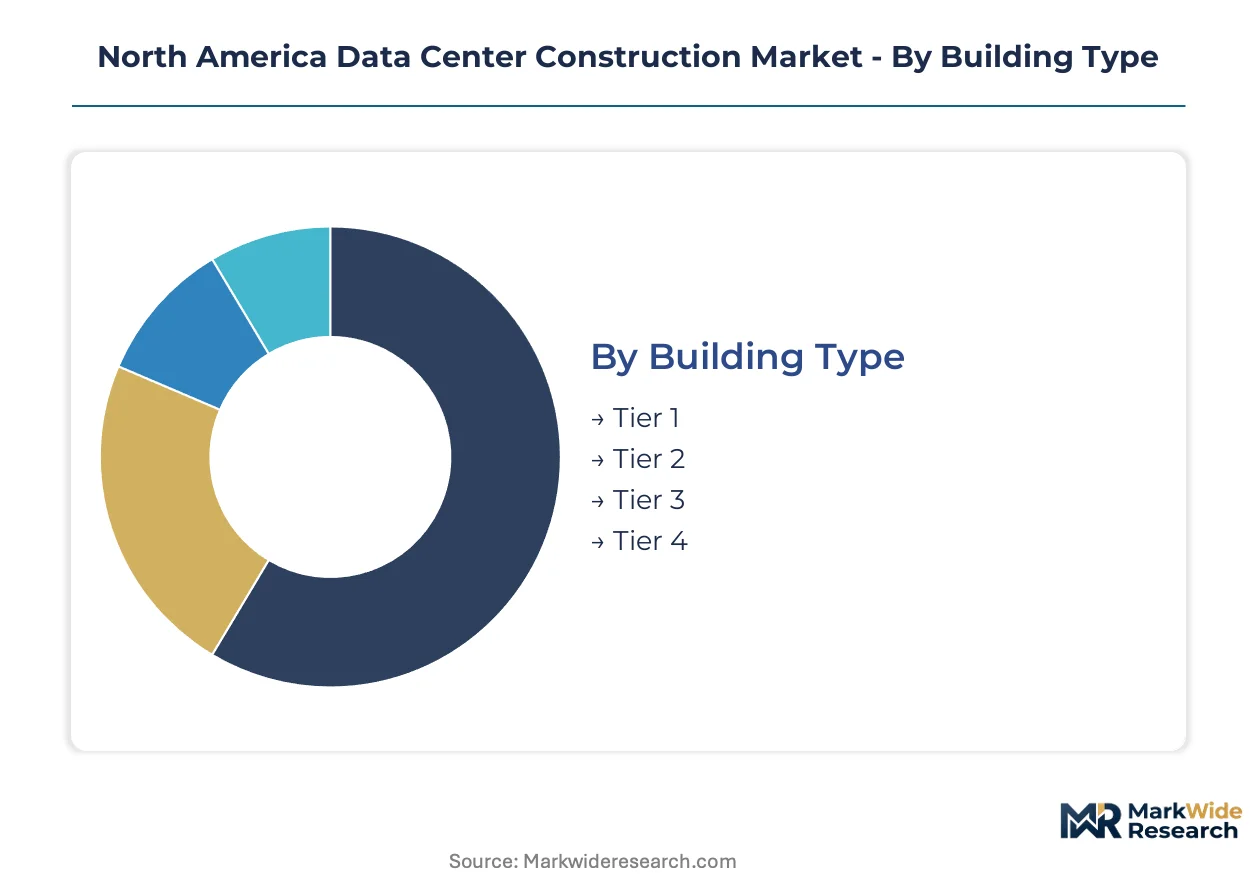
Data center construction segmentation reveals how facility specifications, structural approaches, and procurement methods align with operator risk tolerance and speed-to-market requirements. Tier certification, modularity choices, and delivery models directly determine capital deployment patterns across Northern Virginia, Texas, and Arizona markets.
Building Type:
Domestic hyperscale demand concentrates in Tier 3 and Tier 4 specifications, while Tier 1 and Tier 2 deployments serve edge computing and enterprise colocation with shorter development cycles.
- Tier 4:Fault-tolerant infrastructure with 2N+1 redundancy across all critical systems. Amazon Web Services and Microsoft Azure mandate Tier 4 specifications for flagship campuses in Loudoun County, Virginia, where Dominion Energy interconnection dates function as hard commercial deadlines requiring maximum uptime guarantees.
- Tier 3:Concurrently maintainable systems with N+1 redundancy that permit any single component failure without workload interruption. Meta Platforms and Google Cloud specify Tier 3 for Dallas-Fort Worth expansions where land costs and permitting velocity favor slightly reduced redundancy compared to Northern Virginia saturation.
- Tier 2:Partial redundancy with single distribution paths serving regional enterprise and telecommunications facilities.
- Tier 1:Basic capacity with no redundancy, deployed for remote edge locations and temporary compute capacity.
Tier 3 commands the established base. The steepest expansion runs through Tier 4.
Structure Type:
Cost tier segmentation separates capital-intensive greenfield developments from lower-investment retrofit and modular alternatives.
- Modular:Factory-built power modules, cooling skids, and IT enclosures reduce field labor exposure by forty percent. Hensel Phelps and DPR Construction deploy modular structures in Phoenix and Austin markets where electrical trades scarcity compresses traditional construction schedules.
- Greenfield:Purpose-built facilities on undeveloped land enabling optimized layout for liquid cooling and high-voltage power distribution. Northern Virginia's Data Center Alley and Dallas-Fort Worth corridor dominate greenfield investment due to available transmission capacity and tax incentives.
- Pre-engineered:Standardized structural systems with accelerated procurement timelines for mid-scale deployments.
- Infill:Retrofit of existing industrial or commercial buildings, constrained by ceiling heights and power infrastructure but offering speed advantages in permitted urban locations.
Greenfield commands the established base. The steepest expansion runs through Modular.
Power Source:
Application-driven segmentation tracks how artificial intelligence training clusters and sustainability mandates reshape energy procurement specifications.
- Hybrid:Grid power supplemented with on-site solar, wind, and battery storage to meet carbon-neutral commitments. California and New York mandates for carbon-neutral operations by 2030 accelerate hybrid system integration across new construction.
- Renewable:Dedicated solar or wind power purchase agreements securing 100 percent clean energy, qualifying for U.S. Inflation Reduction Act tax credits in Arizona and Texas markets.
- Non-renewable:Conventional grid power from fossil-fuel generation, still prevalent in ERCOT territories where interconnection queue depth delays renewable project completion.
- Backup:Diesel or natural gas generators providing emergency power during grid outages, required for Tier 3 and Tier 4 certification regardless of primary power source.
Non-renewable commands the established base. The steepest expansion runs through Hybrid.
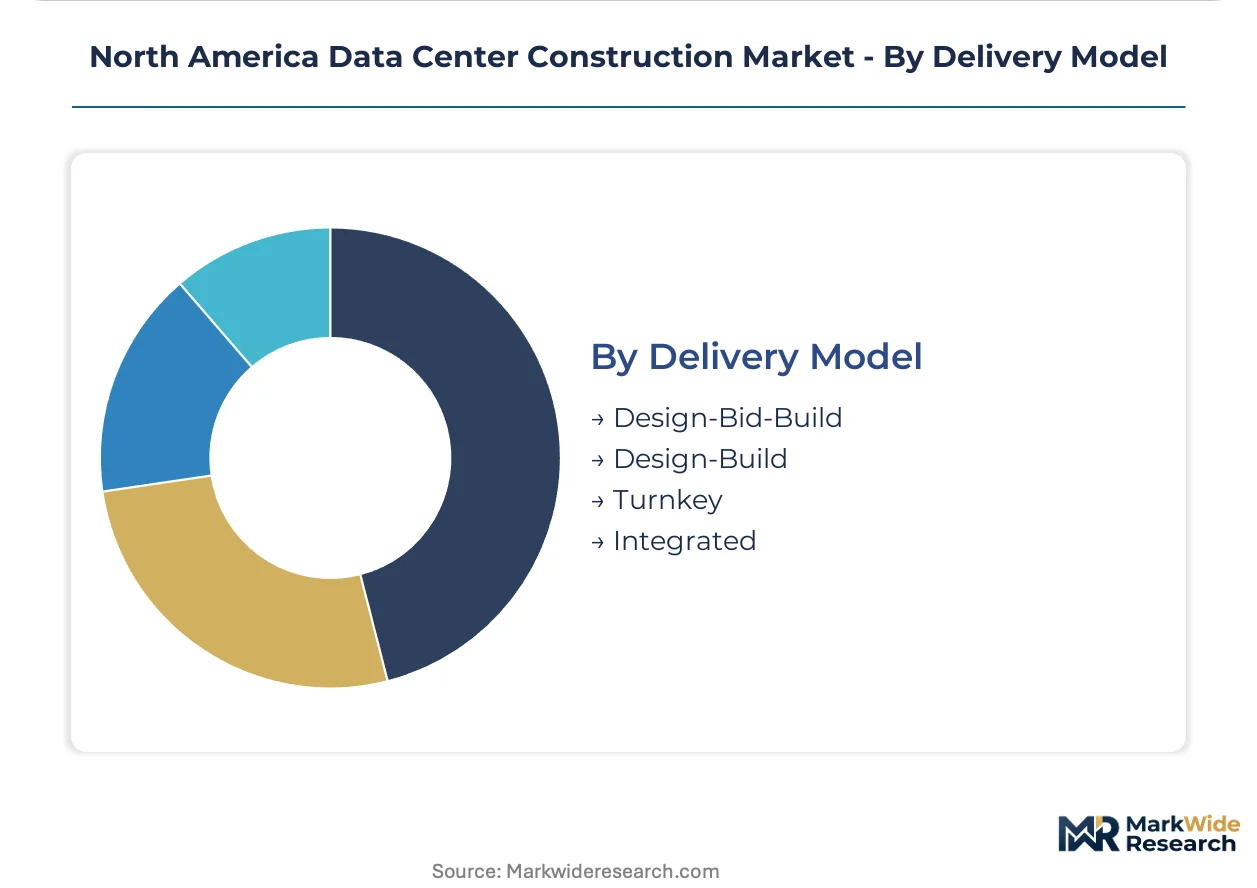
Delivery Model:
Customer type segmentation distinguishes single-source accountability models preferred by hyperscale operators from traditional fragmented procurement.
- Design-Build:Single contractor assumes performance risk for power usage effectiveness guarantees and energization schedules. This model dominates Northern Virginia where Dominion Energy interconnection dates require integrated accountability to avoid liquidated damages.
- Turnkey:Fixed-price contracts transferring all construction and commissioning risk to contractors, favored by private equity-backed colocation operators seeking predictable returns.
- Design-Bid-Build:Sequential architect-engineer-contractor procurement with fragmented accountability, declining in hyperscale segments but retained for enterprise and government facilities with strict public procurement requirements.
- Integrated:Owner-operated development with in-house construction management, deployed by Amazon Web Services and Microsoft for repeat campus expansions where institutional knowledge reduces contractor markup.
Design-Bid-Build commands the established base. The steepest expansion runs through Design-Build.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA governs electrical worker safety standards that shape project timelines across the continent's dominant construction corridors. The U.S. Inflation Reduction Act channels investment toward renewable-powered facilities in sunbelt states. Interconnection queue management by FERC-jurisdictional grid operators determines energization schedules regardless of physical build completion.
United States
Virginia's Data Center Alley and Texas markets absorb the majority of hyperscale investment. The Inflation Reduction Act accelerates solar and wind-powered campus development through production tax credits. Dominion Energy's interconnection timeline in Loudoun County functions as a hard commercial deadline that compresses construction schedules.
Canada
Quebec and Ontario provinces attract operators seeking hydroelectric power and cooler ambient temperatures for air-cooled facilities. Natural Resources Canada administers clean technology investment tax credits that offset capital expenditure for carbon-neutral designs. Toronto's financial district drives enterprise colocation demand with shorter development cycles than hyperscale campuses.
Mexico
Querétaro and Mexico City metro areas emerge as nearshore alternatives for U.S.-serving edge capacity. The Secretariat of Economy's manufacturing incentives extend to data center equipment assembly operations. Monterrey's industrial corridor offers cross-border fiber connectivity and lower land costs than Texas saturation markets.
North America Data Center Construction Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in North American data center construction. Tier 1 contractors with self-perform electrical capabilities capture premium margins in labor-constrained markets. Three archetypes dominate: full-service design-build integrators, specialized mechanical-electrical firms, and hyperscale-captive construction managers. Consolidation pressure intensifies as operators demand single-source accountability for power usage effectiveness guarantees and fixed energization dates.
Among integrated construction specialists, DPR Construction, Jacobs Solutions Inc., and Hensel Phelps occupy positions that exemplify the design-build archetype. DPR Construction leverages captive electrical trades capacity to compress delivery schedules in markets facing eighteen-month commissioning delays. Jacobs Solutions Inc. sustains engineering throughput across hyperscale programs through modular design standardization. Hensel Phelps anchors market presence in Texas and Arizona where trade density supports faster workforce mobilization than Northern Virginia saturation.
| Leading Market Players |
|---|
| Equinix, Inc. |
| Digital Realty |
| DPR Construction |
| Jacobs Solutions Inc. |
| Skanska AB |
| Balfour Beatty plc |
| Whiting-Turner Contracting Co. |
| Hensel Phelps |
| Gensler |
| Others |
Pricing and Supply Chain Analysis
OSHA 1910.269 qualified worker requirements gate both contractor qualification and project pricing simultaneously, compressing margins for firms without captive electrical trades while rewarding integrated players with schedule certainty premiums. Tier 4 certification demands and Dominion Energy interconnection deadlines create price stratification between fault-tolerant hyperscale campuses and standard enterprise builds.
Pricing Analysis
Construction contract values spread widely between Northern Virginia saturation markets and Texas expansion corridors, with labor-constrained jurisdictions commanding fifteen to twenty percent schedule risk premiums. Three-tier pricing structure across Tier 4 redundant, Tier 3 concurrent maintainability, and Tier 2 partial redundancy specifications drives differentiation, with certification grade and local permitting velocity as primary cost drivers. Pricing pressure stems from copper volatility and transformer scarcity forcing working capital pre-commitment. Private equity-backed colocation operators exhibit highest price sensitivity, while hyperscale cloud providers prioritize energization certainty over unit cost.
Supply Chain Analysis
Transformer and switchgear inventories now stretch twelve to eighteen months, forcing contractors to secure critical path electrical components before site mobilization. Manufacturing concentrates in the United States, Mexico, and Germany for power distribution equipment, with China dominating cooling system components and dielectric fluids. Raw material dependencies center on copper cathode, electrical steel, and aluminum extrusions. Single-source vulnerability runs through domestic transformer OEMs with constrained foundry capacity. Distribution runs through direct manufacturer relationships and specialized electrical distributors serving data center verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscale operators' captive construction management capabilities threaten traditional design-build contractors, forcing incumbents to demonstrate irreplaceable value in schedule compression and risk absorption.
For Market Incumbents: Consolidate electrical trades capacity through apprenticeship pipeline investments and acquisition of regional specialty contractors. Lock in transformer and switchgear allocation agreements with OEMs to secure critical path components against twelve-to-eighteen-month lead times. Vertical integration into modular prefabrication reduces field labor exposure and defends margin position against hyperscale self-build alternatives. For New Entrants and Emerging Players: Differentiate on liquid cooling integration expertise as artificial intelligence training clusters rewrite mechanical specifications. Target Dallas-Fort Worth and Phoenix markets where permitting velocity and trade density enable faster workforce mobilization than Northern Virginia saturation. Pursue design-build partnerships with emerging cloud operators seeking single-source accountability without established captive construction arms. For Investors and Strategic Acquirers: Carve-out targets emerge from engineering firms with modular design standardization capabilities and established relationships with Dominion Energy, ERCOT, and Arizona Public Service interconnection teams. Long-term viability hinges on exposure to renewable-powered campus development and battery storage integration scope. Watch liquid cooling adoption curves as the signal for mechanical-electrical contractor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Investment | Factory-built power modules reduce field labor exposure by forty percent in constrained markets. |
| Electrical Trades Apprenticeship Expansion | OSHA 1910.269 qualified worker pipelines defend schedule performance in PJM and ERCOT territories. |
| Transformer OEM Allocation Agreements | Pre-purchase commitments secure critical path components against eighteen-month lead time extension. |
| Liquid Cooling System Integration | Direct-to-chip and immersion expertise captures artificial intelligence training cluster construction demand. |
| Renewable Power Purchase Structuring | U.S. Inflation Reduction Act tax credit optimization reduces long-term operational expenditure for operator clients. |
Research Methodology
Cross-validation between primary fieldwork with data center developers and secondary validation through FERC interconnection filings anchors the qualitative findings. Primary interviews engaged hyperscale facility planners, electrical contractor operations directors, Dominion Energy and ERCOT interconnection managers, and modular equipment OEM sales executives. Secondary sources encompassed EIA power plant databases, EPA refrigerant phase-down documentation, state utility commission dockets, and hyperscaler capital expenditure disclosures. Bottom-up project pipeline aggregation and top-down market sizing triangulate volume estimates.
Sensitivity analysis around interconnection queue depth, copper price volatility, and electrical trades wage escalation shapes the analytical framework across the analysis window. Segmentation modeling incorporated building type, structure type, power source, and delivery model dimensions with regional regulatory cluster differentiation. CAGRs derive from installed base retirement patterns and announced hyperscale campus commitments. Forecast inputs center on Dominion Energy transmission expansion timelines and Arizona Public Service renewable procurement schedules.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscale cloud expansion and stable federal tax credit treatment; material deviation in utility interconnection velocity or refrigerant regulation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
New Zealand Data Center Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
Italy Data Center Power Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
Shanghai Data Center Market
Data Center Infrastructure
Taiwan Data Center Rack Market
Data Center Infrastructure
Multi-Tenant Data Center Market