
 Global Data Center Structured Cabling Market | 2026-2036
Global Data Center Structured Cabling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Center Structured Cabling Market Analysis
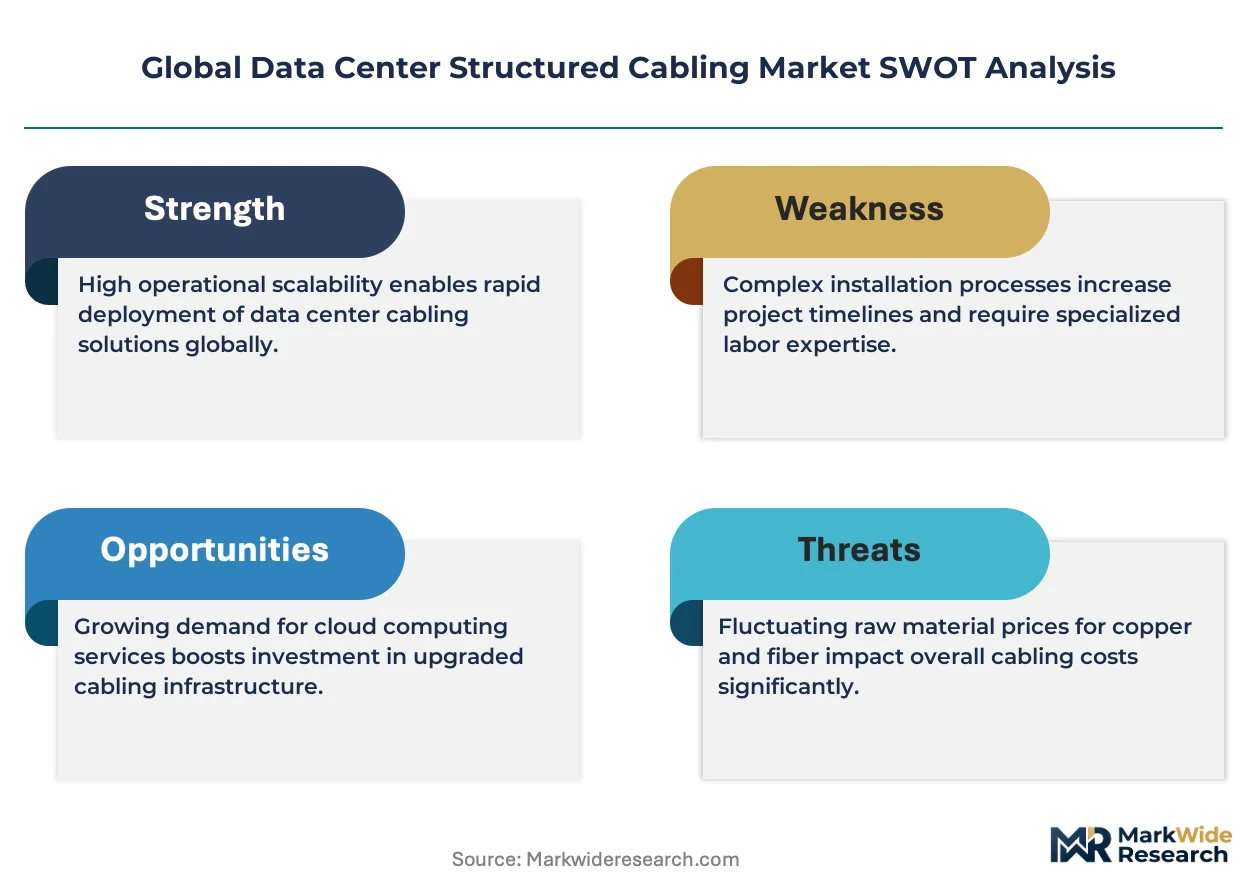
Power-purchase-agreement-backed leasing models are reshaping how data center developers fund structured cabling infrastructure, lowering barriers for non-traditional operators. CommScope leverages its integrated fiber-copper portfolio to anchor large-scale hyperscale contracts across North America. Furukawa Electric Co., Ltd. sustains competitive positioning through advanced bend-insensitive fiber R&D. Legrand specializes in modular connectivity solutions that reduce deployment timelines for colocation providers.
Data center structured cabling encompasses the organized subsystem of copper and fiber-optic pathways, patch panels, and connectivity hardware that transmits data between servers, storage, and network equipment, typically engineered to support speeds from 10 Gbps to 400 Gbps with strict insertion-loss budgets. Fiber optic cables dominate new hyperscale builds where single-mode solutions enable 100 Gbps and 400 Gbps links over extended reaches, while copper cables retain share in top-of-rack and short-reach applications where cost and power efficiency matter. Installation type segmentation shows new builds capturing the largest value pool as cloud service providers and telecommunications firms construct greenfield campuses, though upgrades and modular installations represent faster-growing channels as legacy facilities refresh to support AI workloads.
The Telecommunications Industry Association enforces TIA-942 standards that dictate cabling topology, redundancy, and performance tiers for data center certification, directly influencing procurement specifications for mission-critical facilities. ISO/IEC 11801 and EN 50173 provide international benchmarks for channel performance and electromagnetic compatibility, shaping product design requirements for vendors serving European and Asian markets. Stakeholders must monitor evolving standards for 800 Gbps Ethernet and liquid-cooled architectures, as these will redefine cable density, thermal ratings, and pathway engineering in next-generation facilities.
Market Dynamics
Fiber-to-the-server architectures are compressing copper's role in hyperscale builds, forcing cable vendors to rebalance R&D portfolios toward bend-insensitive single-mode solutions while maintaining legacy copper revenue streams in enterprise refreshes.
Growth Catalysts
- AI Training Clusters:GPU-dense facilities require 400 Gbps and 800 Gbps optical links between compute nodes and storage arrays, expanding fiber port counts per rack by an order of magnitude.
- TIA-942 Tier III/IV Certification:Mission-critical financial and healthcare facilities in the United States mandate redundant cabling pathways, doubling physical infrastructure spend per square meter.
- Liquid Cooling Retrofits:Immersion and direct-to-chip cooling systems in Germany and China necessitate sealed fiber connectors rated for elevated thermal and humidity exposure.
Market Restraints
- Copper Raw Material Volatility:LME copper price swings above $9,000 per tonne compress margin on Cat 6A and Cat 8 cable contracts with fixed pricing terms.
- Single-Mode Fiber Supply Concentration:Preform and draw tower capacity clusters in the United States, Japan, and China, creating 14-18 month lead times for custom bend-insensitive fiber specifications.
- OM5 Multimode Obsolescence:Shortwave wavelength division multiplexing failed to achieve economies of scale against single-mode alternatives, stranding early-adopter capital in legacy installations.
Strategic Opportunities
- India Data Center Buildout:PLI scheme incentives for electronics manufacturing are attracting hyperscale operators to Mumbai, Chennai, and Hyderabad, creating greenfield demand for structured cabling infrastructure.
- Edge Micro-Data Centers:5G base station aggregation points and autonomous vehicle roadside units require ruggedized, temperature-hardened connectivity solutions outside traditional climate-controlled environments.
- EU Green Deal Alignment:CSRD disclosure requirements are pressuring colocation providers to source low-carbon fiber and recyclable copper sheathing, rewarding vendors with verified lifecycle assessments.
Industry Challenges
- Fiber Splicing Technician Shortage:Precision fusion splicing for single-mode MPO/MTP connectors requires certification levels that training pipelines in North America and Europe cannot currently satisfy at buildout velocity.
- Legacy TIA-942-A to TIA-942-B Migration:Facilities certified under the 2012 standard must re-document pathway separation and firestopping details to maintain Tier III/IV status during insurance renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Center Structured Cabling Market |
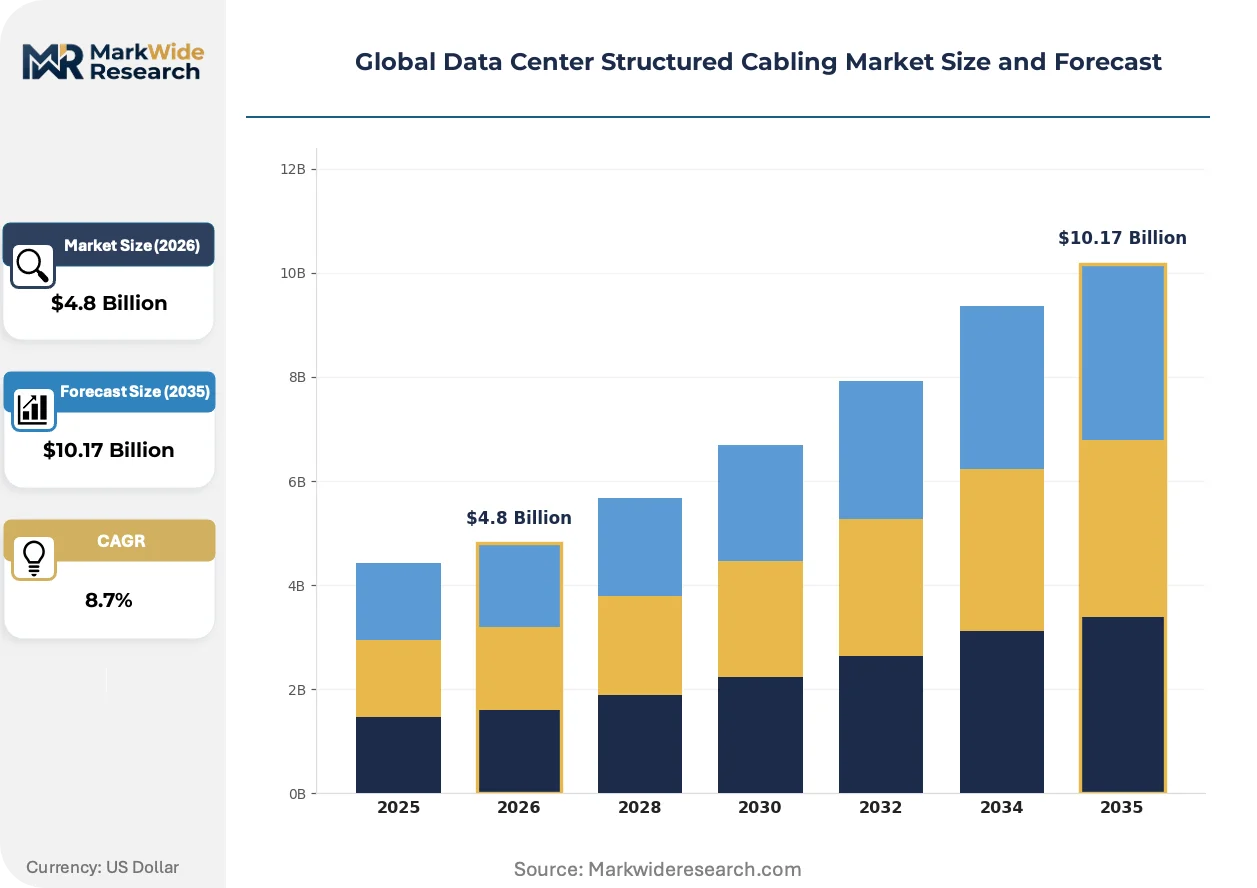
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic Cables, Copper Cables, Patch Panels, Connectivity Solutions Installation Type: New Builds, Upgrades, Retrofit, Modular End User: Cloud Service Providers, Enterprise, Telecommunications, Colocation Service Type: Design Services, Installation Services, Maintenance Services, Consulting Services |
| Companies Covered | Legrand, Belden Inc, CommScope, R&M, The Siemon Company, Corning Incorporated, Nexans, Furukawa Electric Co., Ltd., Panduit Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Center Structured Cabling Market Emerging Trajectories
Speed tier compression and thermal density limits are forcing simultaneous evolution in cable construction, connector density, and installation methodology across hyperscale and enterprise segments.
Bend-insensitive single-mode fiber is migrating from long-haul outside-plant applications into intra-data-center spine-leaf architectures. Hyperscale operators in the United States and China are specifying G.657.A2 fiber for 100-meter reach links previously served by OM4 multimode. This migration is collapsing the historical multimode/single-mode boundary inside the data center, reducing transceiver inventory complexity but requiring tighter bend radius management in dense cable trays.
REACH Annex XVII restrictions on halogenated flame retardants are accelerating adoption of low-smoke zero-halogen jacketing compounds in European data center builds. The regulation's industrial consequence is a supply chain bifurcation: vendors must maintain dual SKUs for EU-compliant and legacy PVC-sheathed cables serving other markets. German and Dutch colocation providers are now specifying LSZH as default, compressing PVC's addressable market share in Western Europe.
Direct-to-chip liquid cooling is compressing traditional raised-floor installation practices. Buyers in Singapore and the United States are procuring overhead cable tray systems and sealed fiber feedthroughs as standard, displacing underfloor copper distribution in new builds. This behavioral shift is most visible in AI training facilities where thermal loads exceed 50 kW per rack, rendering conventional airflow-based cooling and cabling layouts obsolete.
Global Data Center Structured Cabling Market Segmentation
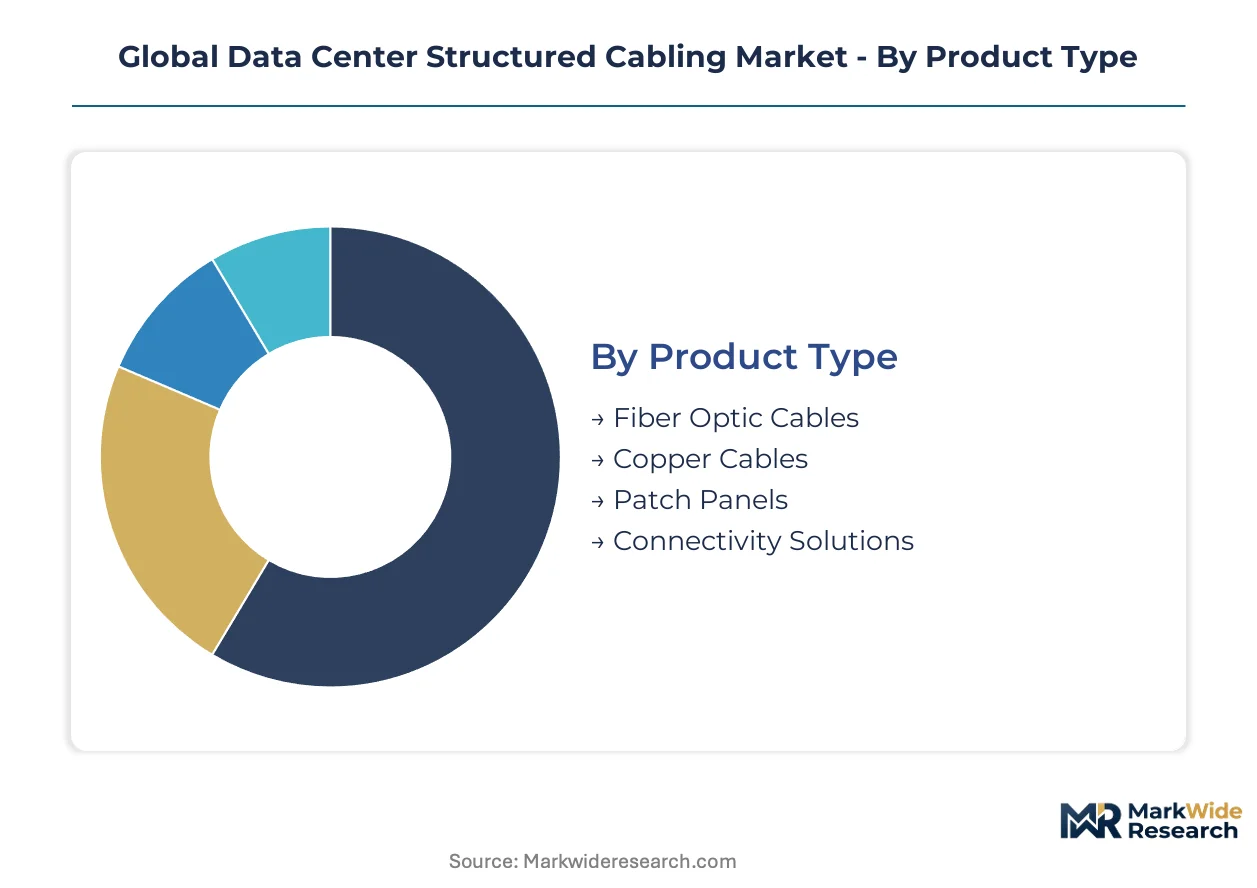
Segmentation in data center structured cabling reveals divergent procurement rhythms across infrastructure layers. Product categories exhibit starkly different replacement cycles, with fiber assets turning over faster than copper as speed tiers advance. Understanding these temporal patterns helps vendors align inventory and service capacity with actual deployment velocity.
Product Type:
Fiber optic cables refresh fastest as hyperscale operators chase bandwidth scaling, while copper cables and passive hardware endure longer in enterprise footprints. Patch panels and connectivity solutions sit between these extremes, turning over with rack reconfigurations rather than full infrastructure rebuilds.
- Fiber Optic Cables:Single-mode and multimode solutions engineered for 100 Gbps to 400 Gbps transmission with strict insertion-loss budgets. Demand concentrates in United States and China hyperscale campuses where GPU clusters mandate optical spine-leaf architectures. Bend-insensitive G.657.A2 specifications are displacing legacy multimode in intra-facility links.
- Copper Cables:Cat 6A and Cat 8 twisted-pair assemblies for top-of-rack and short-reach interconnects where power efficiency trumps bandwidth scaling. Enterprise data centers in Germany retain copper for 10 Gbps server connections, though share compresses as fiber economics improve.
- Patch Panels:Modular termination points enabling cross-connect flexibility between backbone and horizontal cabling subsystems.
- Connectivity Solutions:MPO/MTP trunk assemblies, fiber cassettes, and copper jacks that bridge permanent infrastructure to active equipment.
Fiber optic cables dominate installed base value in new hyperscale construction. Copper cables is where expansion concentrates in cost-sensitive enterprise refreshes.
Installation Type:
Capital deployment patterns split sharply between greenfield construction with multi-year planning horizons and tactical upgrades responding to workload shifts. Modular installations are gaining favor as operators seek to defer full-facility commitments amid demand uncertainty.
- New Builds:Comprehensive cabling infrastructure deployed in greenfield data center campuses prior to server installation. Cloud service providers in India and Saudi Arabia are procuring single-mode fiber at scale for facilities exceeding 50 MW power capacity.
- Upgrades:Selective replacement of backbone or horizontal cabling to support higher speed tiers without facility overhaul. Financial services firms in Singapore execute upgrades to maintain TIA-942 Tier III certification during lease renewals.
- Retrofit:Adaptation of existing pathways for liquid cooling compatibility or denser fiber counts.
- Modular:Prefabricated cabling zones deployed as discrete capacity units within larger facilities.
New Builds dominate installed base. Modular is expanding most quickly as operators seek deployment flexibility.
End User:
Procurement sophistication varies dramatically across customer archetypes, from hyperscale self-builders with internal engineering teams to colocation tenants specifying infrastructure by proxy. Volume concentration and technical specification authority sit with different parties in each relationship structure.
- Cloud Service Providers:Hyperscale operators designing proprietary fiber-to-the-server architectures with custom bend-radius and connector specifications. Amazon Web Services, Microsoft Azure, and Google Cloud facilities in Northern Virginia and Frankfurt drive specification-setting for the supply base.
- Enterprise:Corporate data center owners balancing legacy copper preservation against selective fiber adoption for storage networking. Healthcare systems in the United States prioritize TIA-942 Tier IV redundancy for electronic medical record availability.
- Telecommunications:Carrier-neutral and integrated operators building edge aggregation points for 5G traffic.
- Colocation:Multi-tenant facility operators procuring standardized cabling to accommodate diverse tenant requirements.
Cloud Service Providers dominate installed base. Colocation is where expansion concentrates as third-party facility share rises.
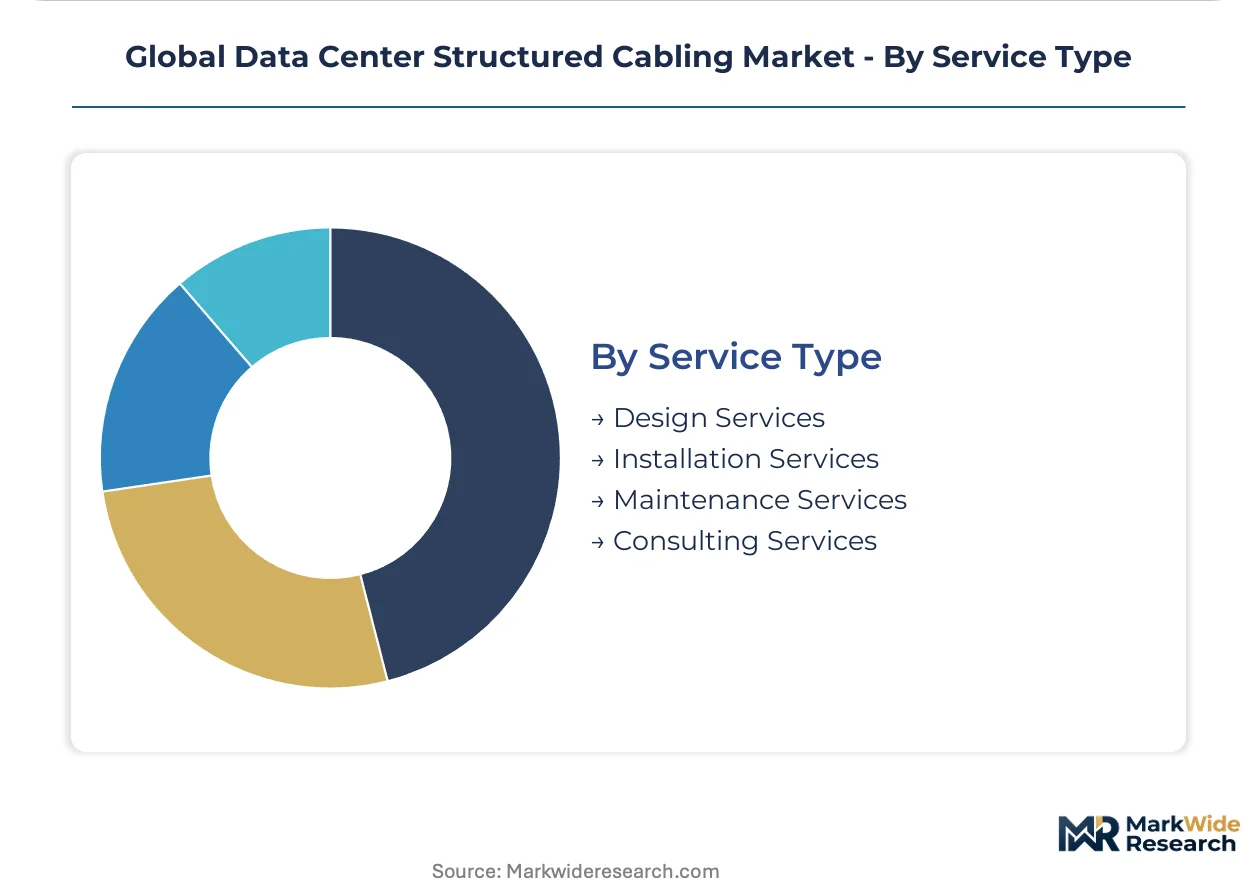
Service Type:
Revenue attachment rates differ across the project lifecycle, with design and installation services front-loaded while maintenance and consulting extend over decades of facility operation. Vendor capabilities in each phase determine account stickiness and upgrade cycle access.
- Design Services:Pathway engineering, loss-budget modeling, and standards compliance documentation for TIA-942 and ISO/IEC 11801 certification. Engineering firms in the Netherlands specialize in liquid-cooling-compatible routing for high-density AI facilities.
- Installation Services:Field termination, fusion splicing, and certification testing performed by technician crews. The United States faces acute technician shortages for precision MPO/MTP splicing at current buildout velocity.
- Maintenance Services:Periodic re-certification, fault location, and physical layer cleaning.
- Consulting Services:Strategic advisory on technology migration roadmaps and sustainability disclosure alignment.
Installation Services dominate installed base. Consulting Services is where expansion concentrates as CSRD and similar disclosure regimes proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives in India and CSRD disclosure mandates across the European Union are redirecting capital flows toward compliant infrastructure builds. Cloud service providers in the United States, China, and Germany anchor hyperscale deployment volumes. TIA-942 Tier III/IV certification requirements in mission-critical facilities tighten procurement specifications regionally.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth are procuring single-mode fiber at scale for GPU-dense AI training clusters. The Telecommunications Industry Association enforces TIA-942-B pathway separation standards that double documentation requirements for Tier IV certification. Phoenix and Atlanta data center campuses are specifying bend-insensitive G.657.A2 fiber for 100-meter spine-leaf architectures.
China
MIIT dual carbon goals are pressuring data center operators in Beijing and Shanghai to source low-carbon fiber and improve Power Usage Effectiveness ratios. GB standards for structured cabling align with ISO/IEC 11801 while adding domestic electromagnetic compatibility testing. Yangtze River Delta facilities in Jiangsu and Zhejiang are deploying sealed fiber connectors for liquid-cooled AI infrastructure.
Germany
REACH Annex XVII restrictions on halogenated flame retardants are accelerating LSZH jacketing adoption in Frankfurt and Berlin colocation builds. The country's national data center regulator enforces redundant cabling pathways for financial services facilities under BSI IT-Grundschutz frameworks. Bavarian hyperscale campuses near Munich are retrofitting overhead cable tray systems to accommodate direct-to-chip cooling architectures.
India
PLI scheme incentives for electronics manufacturing are attracting AWS, Microsoft Azure, and Google Cloud to Mumbai, Chennai, and Hyderabad greenfield sites. TRAI infrastructure sharing regulations are reducing redundant backbone deployment costs for multi-tenant facilities. Telangana's Hyderabad data center cluster is procuring modular cabling zones as discrete capacity units to defer full-facility commitments.
Singapore
Infocomm Media Development Authority guidelines on tropical data center design are mandating temperature-hardened connectivity solutions for edge micro-data centers. The city-state's national sustainability regulator is enforcing CSRD-aligned disclosure for colocation providers sourcing structured cabling. Tuas and Changi North facilities are specifying sealed fiber feedthroughs rated for elevated humidity exposure in immersion cooling deployments.
Global Data Center Structured Cabling Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fiber, copper, and connectivity hardware categories. The vendor base organizes around three strategic archetypes: integrated fiber-copper portfolios, bend-insensitive fiber specialists, and modular connectivity solution providers. M&A activity concentrates on acquiring fusion splicing technician networks and regional installation service capabilities. Portfolio diversification toward liquid-cooling-compatible sealed connectors represents the dominant competitive move.
Among integrated portfolio players, CommScope and Legrand occupy positions spanning fiber, copper, and passive hardware categories. Furukawa Electric Co., Ltd. exemplifies the bend-insensitive fiber specialist archetype with advanced single-mode R&D capabilities. These three companies anchor distinct competitive vectors: CommScope leverages scale across North American hyperscale contracts, Legrand targets modular deployment timelines for colocation providers, and Furukawa sustains positioning through technical specifications for high-density AI facilities.
| Leading Market Players |
|---|
| Legrand |
| Belden Inc |
| CommScope |
| R&M |
| The Siemon Company |
| Corning Incorporated |
| Nexans |
| Furukawa Electric Co., Ltd. |
| Panduit Corp |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta fiber preform capacity anchors global supply of bend-insensitive single-mode specifications, translating upstream draw-tower concentration into pricing power for vendors serving hyperscale cloud operators in Northern Virginia and Frankfurt.
Pricing Analysis
Certification level creates the primary spread between TIA-942 Tier IV-compliant infrastructure and uncertified alternatives, with redundant pathway documentation adding substantial project premiums. Three-tier pricing structure separates mission-critical financial services deployments from standard colocation builds and economy-grade enterprise refreshes. Pricing pressure stems from copper raw material volatility compressing margins on fixed-price Cat 6A and Cat 8 contracts. Cloud service providers exhibit lowest price sensitivity due to total-cost-of-ownership framing, while cost-conscious enterprise buyers in Germany prioritize copper preservation over fiber migration.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for structured cabling vendors with cross-border component flows. Preform and draw tower capacity clusters in the United States, Japan, and China, creating concentrated dependency for custom G.657.A2 fiber specifications. Raw material inputs draw from high-purity silicon tetrachloride, germanium tetrachloride dopants, and LME-grade copper cathodes. Single-source vulnerability persists for precision MPO/MTP connector ferrules sourced from Japanese ceramic specialists. Distribution runs through direct OEM relationships with hyperscale operators and tiered channel partners serving mid-market enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fusion splicing technician certification gaps in North America and Europe constrain deployment velocity, creating acute capability scarcity that rewards vendors with captive training pipelines or acquisition-ready technician networks.
For Market Incumbents: Harden defensive positioning through backward integration into preform manufacturing and captive technician certification programs in Arizona and Texas. CommScope and Legrand should prioritize acquisition of regional installation service capabilities to offset labor scarcity threatening Tier IV certification timelines. Certification investment in TIA-942-B pathway separation documentation capabilities protects renewal revenue from legacy facility audits. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-backed greenfield data center corridor, where hyperscale operator entry creates first-mover advantages for modular cabling zone specialists. Edge micro-data centers in tropical climates represent the most penetrable white-space, with temperature-hardened connectivity solutions underserved by incumbent portfolios. A go-to-market angle anchored in liquid-cooling-compatible sealed fiber feedthroughs bypasses direct competition with integrated portfolio leaders. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bend-insensitive fiber specialists with proven G.657.A2 specifications over legacy multimode incumbents facing obsolescence. Long-term viability across the next technology cycle hinges on 800 Gbps Ethernet readiness and liquid-cooling thermal rating capabilities. Acquisition target archetype: regional installation service providers with certified MPO/MTP splicing capabilities in supply-constrained North American markets. The signal to watch is hyperscale operator specification shifts from OM4 multimode to single-mode for intra-facility links under 100 meters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Manufacturing | Captive supply of G.657.A2 fiber specifications reduces 14-18 month lead time exposure for hyperscale contracts. |
| Technician Certification Program Expansion | Fusion splicing labor scarcity in Northern Virginia and Dallas-Fort Worth threatens Tier IV certification velocity. |
| Liquid-Cooling-Compatible Product Line Launch | Sealed fiber connectors rated for immersion cooling address Singapore and Germany AI facility procurement specifications. |
| Regional Installation Service Acquisition | MPO/MTP splicing capabilities in supply-constrained markets defend account stickiness during upgrade cycles. |
| LSZH Jacketing SKU Rationalization | REACH Annex XVII compliance bifurcation requires dual inventory management for EU versus legacy PVC markets. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center engineering directors, fiber cable procurement managers, TIA-942 certification auditors, and hyperscale facility construction leads. Secondary validation drew from SEC 10-K filings of publicly traded cabling vendors, TRAI infrastructure sharing regulations, MIIT dual carbon policy documents, and ECHA REACH restriction updates. Bottom-up project pipeline analysis triangulated against top-down hyperscale capex disclosures to establish market sizing boundaries.
Calibration against historical deployment velocity in Northern Virginia, Frankfurt, and Yangtze River Delta facilities anchored growth assumptions across the projection horizon. Segmentation modeling incorporated product type, installation category, end-user archetype, and regional regulatory cluster dimensions. CAGRs were derived from weighted average of vendor shipment data and facility completion timelines. Industry-specific forecast inputs included GPU cluster port density requirements and liquid cooling retrofit penetration curves.
Stress conditions across copper price volatility bands, single-mode fiber supply lead times, and technician availability constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding TIA-942-B migration timelines and hyperscale operator specification shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Bengaluru Data Center Market