
 Residential Water Leak Detection System Market | 2026-2036
Residential Water Leak Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Water Leak Detection System Market Insights
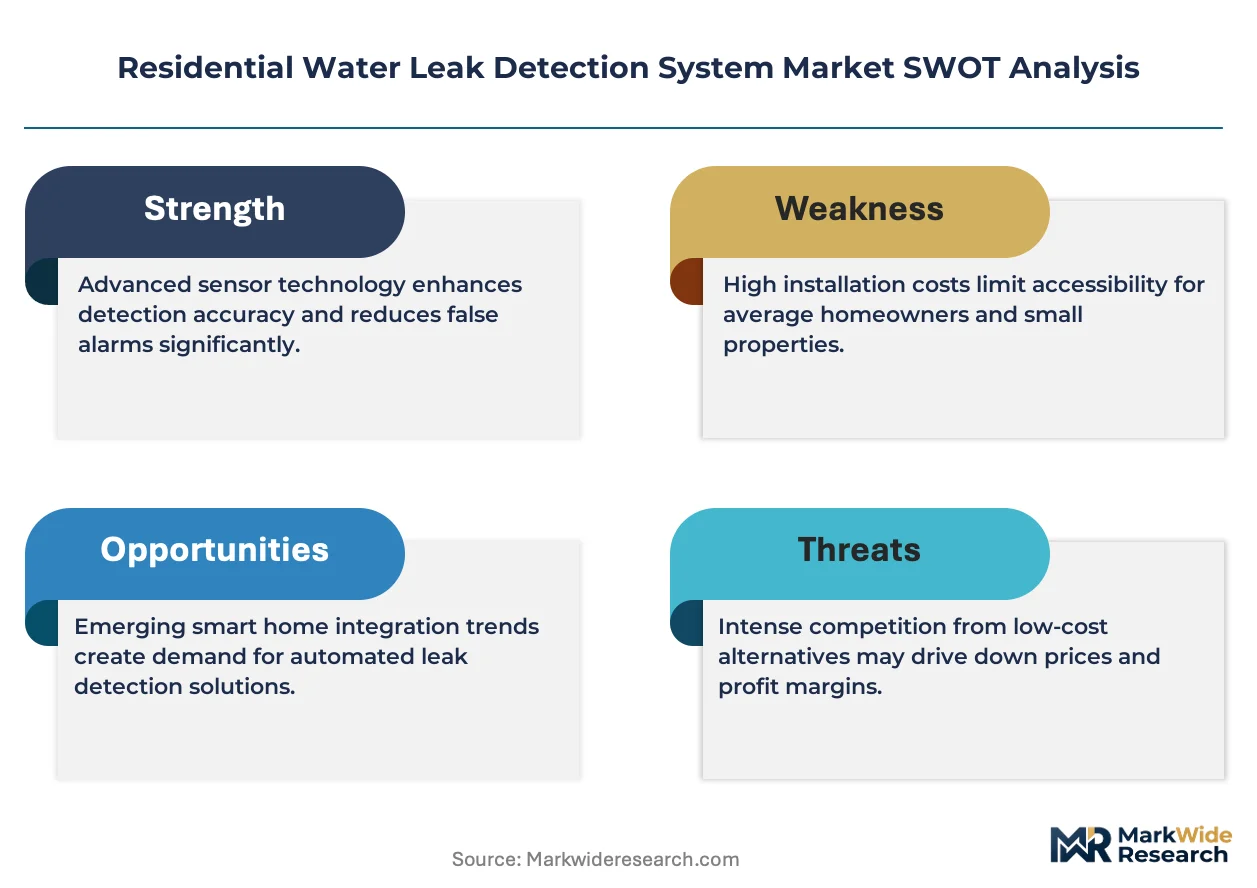
EPA WaterSense certification is rebalancing the cost-of-entry calculus for new entrants, forcing baseline compliance with flow-monitoring accuracy thresholds. Honeywell International leverages its building automation heritage to sustain channel control across professional installation networks. Siemens anchors European demand through its scalar sensor integration in multifamily retrofit programs. Phyn differentiates via machine-learning pressure analytics that compete with conventional acoustic methods.
A residential water leak detection system encompasses sensor arrays, shutoff actuators, and communication hubs engineered to identify abnormal flow patterns and automatically interrupt supply, typically operating within pressure ranges of 15 to 80 psi and detecting leaks as small as 0.1 gallons per minute. Fixed sensors dominate installed base volume while smart home devices capture the fastest expansion as interoperability protocols standardize. Wireless sensors command premium positioning in retrofit applications where invasive plumbing modification is impractical. Acoustic technology leads unit shipments but optical sensing is gaining traction in high-value residential construction where false-positive tolerance approaches zero.
FCC equipment authorization governs radio-frequency communications in connected systems sold in the United States, while the EU Green Deal and F-Gas Regulation indirectly shape demand by linking water efficiency to broader building decarbonization mandates. ISO 9001 quality management and IEC 60730 automatic electrical controls standards frame product liability exposure for manufacturers exporting across jurisdictions. Stakeholders must monitor evolving insurance underwriting criteria, as carriers increasingly mandate certified leak detection hardware for policy eligibility in flood-prone zones.
Market Dynamics
Smart home interoperability mandates are compressing technology refresh cycles as homeowners demand seamless integration with existing automation platforms. This pressure is forcing sensor manufacturers to prioritize protocol standardization over proprietary lock-in.
Growth Catalysts
- EPA WaterSense certification thresholds:Federal flow-monitoring accuracy mandates are elevating baseline product specifications and disqualifying non-compliant imports from federal procurement channels.
- Aging copper pipe infrastructure:Pre-1980 residential plumbing in the United States, Germany, and Japan is driving replacement-driven demand for whole-home monitoring systems.
- Machine-learning pressure analytics:Algorithmic leak signature recognition is reducing false-positive rates below acoustic methods, accelerating adoption in premium housing segments.
Market Restraints
- Semiconductor supply concentration:RF transceiver chip fabrication concentrated in Taiwan creates vulnerability for wireless sensor production schedules.
- Retrofit installation labor costs:Plumber-certified shutoff valve integration in finished basements adds substantial project expense beyond hardware.
- Acoustic sensing substitution ceiling:Mature ultrasonic technology limits pricing power for optical sensing entrants despite superior accuracy.
Strategic Opportunities
- India smart city water metering convergence:Municipal digitization programs create channel overlap for residential leak detection vendors with utility-grade credentials.
- Insurance underwriting mandate expansion:Carriers in Florida and coastal Texas are piloting leak detection hardware requirements for flood zone policy renewal.
- EU Green Deal building decarbonization linkage:Water efficiency credits tied to renovation subsidies are opening multifamily retrofit pipelines in Germany and France.
Industry Challenges
- Cross-platform integration complexity:Fragmented smart home ecosystems demand redundant certification cycles for Matter, Zigbee, and Z-Wave compatibility.
- Plumber-electrician coordination friction:Dual-trade installation requirements delay project completion and inflate contractor management overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Water Leak Detection System Market |
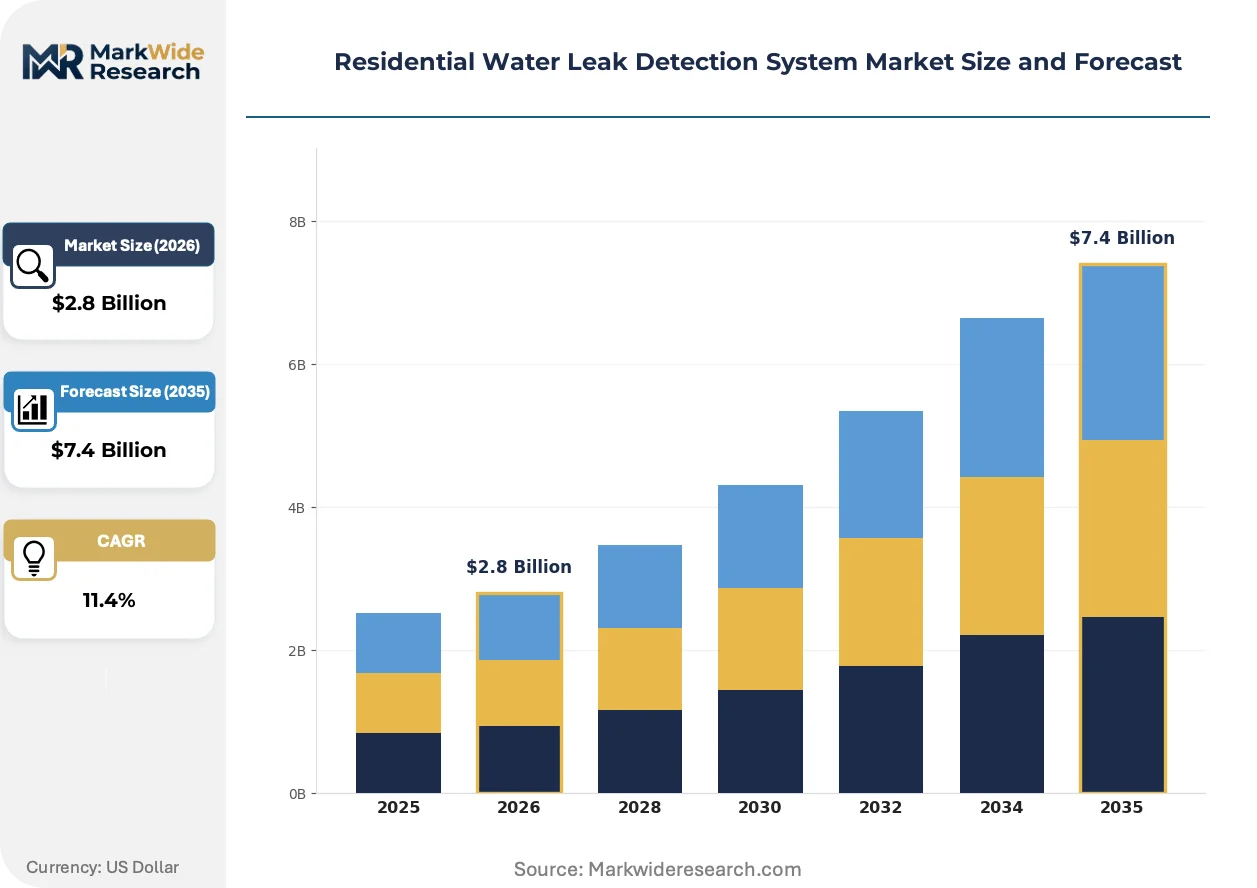
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Sensors, Portable Systems, Smart Home Devices, Wireless Sensors Technology: Acoustic, Ultrasonic, Scalar, Optical End User: Homeowners, Property Managers, Insurance Companies, Contractors Installation: DIY, Professional, Integrated Systems, Retrofitting |
| Companies Covered | Honeywell International, Siemens, Johnson Controls, TTK, Aquilar, Badger Meter, LeakSmart, Phyn, American Leak Detection, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Water Leak Detection System Market Trends and Innovations
Edge computing migration is redistributing analytical workloads from cloud servers to sensor nodes, reducing latency for automatic shutoff decisions. This architectural shift is compressing hardware cost curves while elevating firmware sophistication requirements.
Sensor hardware is modularizing around interchangeable detection cartridges that separate acoustic, optical, and pressure-sensing elements from communication backplanes. Homeowners in renovation-heavy markets are adopting cartridge-swappable systems to upgrade detection methods without full replacement. This modularity is fragmenting vendor revenue streams from one-time hardware sales toward recurring sensor refresh cycles.
The EU F-Gas Regulation is indirectly accelerating water efficiency hardware deployment by linking building envelope and mechanical system retrofits to comprehensive utility monitoring requirements. Residential developers in Germany and the Netherlands are bundling leak detection with heat pump installations to satisfy integrated efficiency audits. Multifamily property managers are responding by specifying scalar-integrated systems that consolidate water, thermal, and refrigerant monitoring.
Buyer preference is gravitating toward unbundled hardware and monitoring service contracts rather than upfront capital purchases. Channel partners in the United States are repositioning as subscription facilitators, capturing recurring revenue from cloud analytics and insurer compliance reporting. This transition is most visible in coastal California markets where homeowner association bulk purchasing concentrates decision authority with property managers seeking operational expenditure treatment.
Residential Water Leak Detection System Market Segmentation
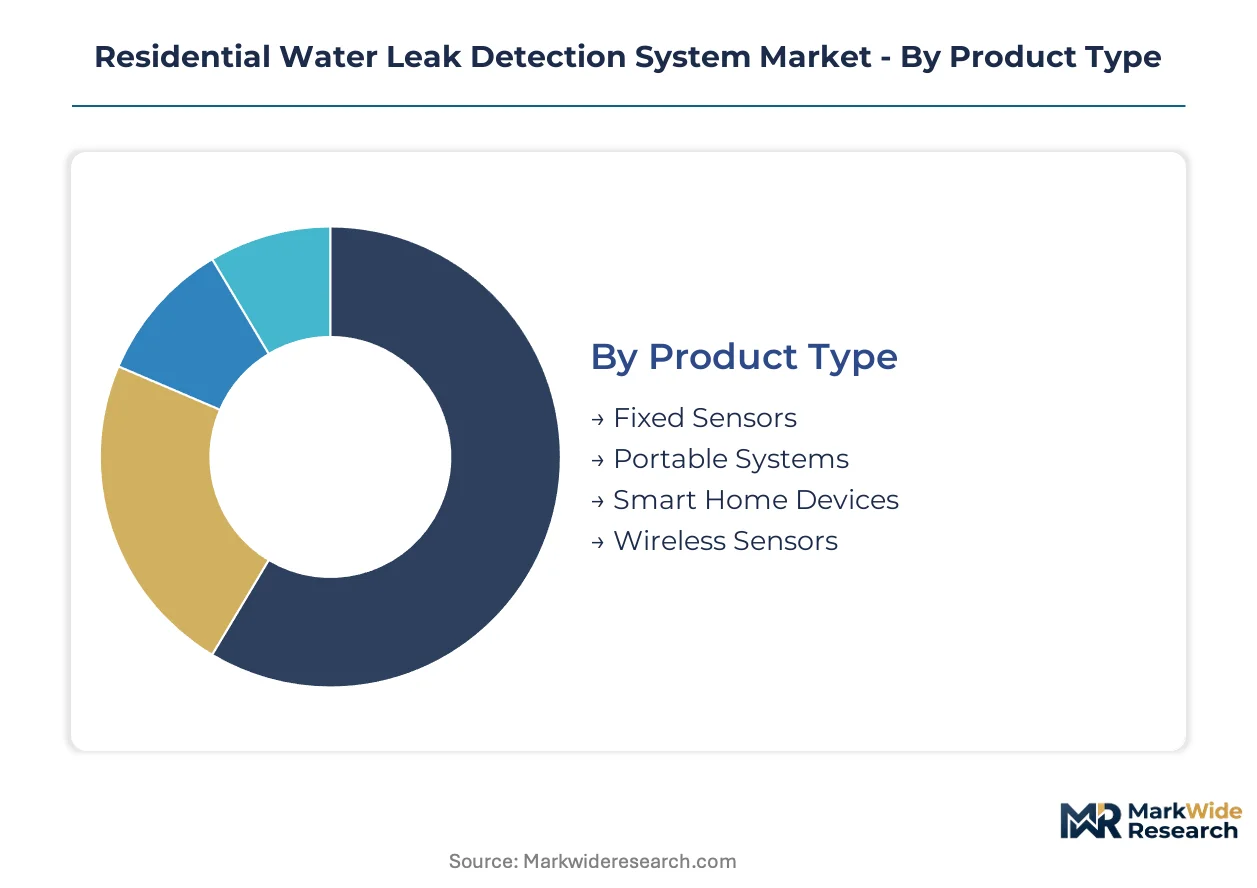
Segmentation in residential water leak detection reveals how hardware specifications, installation constraints, and buyer sophistication create distinct commercial battlegrounds. Upgrade cycles vary dramatically across categories, from annual sensor cartridge replacements to decade-long infrastructure retrofits.
Product Type:
Replacement and upgrade dynamics differ sharply across hardware categories, with retrofit compatibility and smart home interoperability driving refresh decisions.
- Fixed Sensors:Permanently mounted detection nodes typically deploy near water heaters, washing machines, and sump pumps with hardwired power connections. Demand concentrates in new construction across the United States and Germany where builder-grade specifications favor cost-certain permanent installations over modular alternatives. The installed base dominance here creates aftermarket cartridge revenue streams for vendors with swappable sensing elements.
- Smart Home Devices:Interoperable hubs and connected sensors leverage Matter, Zigbee, and Z-Wave protocols for platform-agnostic integration. Premium housing stock in coastal California and Tokyo drives demand as homeowners prioritize seamless automation ecosystem participation over standalone functionality. Protocol standardization is compressing refresh cycles as compatibility mandates force hardware updates.
- Portable Systems:Battery-operated, repositionable units target renters and temporary monitoring needs without permanent installation.
- Wireless Sensors:RF-enabled nodes eliminate wiring requirements, commanding price premiums in finished basement retrofits where invasive plumbing access is impractical.
Volume placements concentrate in Fixed Sensors; the faster expansion belongs to Smart Home Devices.
Technology:
Detection methodology selection hinges on false-positive tolerance, with premium applications accepting higher hardware costs for near-zero error rates.
- Acoustic:Ultrasonic listening devices detect leak signatures through pipe vibration analysis, dominating unit shipments due to mature manufacturing economics and established plumber familiarity. Mass-market adoption across the United States relies on acoustic simplicity despite higher false-positive rates in multi-fixture environments.
- Optical:Camera-based and infrared systems identify moisture through visual spectrum analysis, penetrating high-value residential construction in Japan and Germany where insurance underwriting mandates approach zero tolerance for undetected leaks. The technology's superior accuracy justifies 3-4x hardware premiums in flood-zone markets.
- Ultrasonic:High-frequency pulse measurement calculates flow anomalies through time-of-flight differential detection.
- Scalar:Volumetric flow measurement integrated with pressure differential sensors enables whole-home monitoring through single-point installation.
Acoustic technology commands current volume leadership; Optical sensing climbs the fastest as regulatory tolerance tightens.
End User:
Procurement authority fragmentation creates channel complexity, with individual decision-makers, institutional buyers, and compliance-driven intermediaries each demanding distinct value propositions.
- Homeowners:Individual purchasers drive the steepest expansion trajectory as smart home integration becomes standard expectation rather than premium upgrade. Replacement cycles accelerate in the United States where EPA WaterSense certification awareness elevates baseline specifications and disqualifies non-compliant imports from consideration.
- Insurance Companies:Carrier-mandated hardware requirements are emerging in Florida and coastal Texas flood zones, with policy renewal contingent on certified leak detection installation. This intermediated demand shifts procurement authority from homeowners to underwriters seeking loss ratio improvement.
- Property Managers:Multifamily and HOA bulk purchasing concentrates decision authority with operational expenditure preference over capital outlay.
- Contractors:Professional installation networks specify hardware based on labor efficiency and warranty support reliability.
Volume concentrates with Homeowners; Insurance Companies are gaining share fastest through mandate expansion.
Installation:
Labor cost structure and trade coordination requirements segment the market between self-directed and professionally managed deployment pathways.
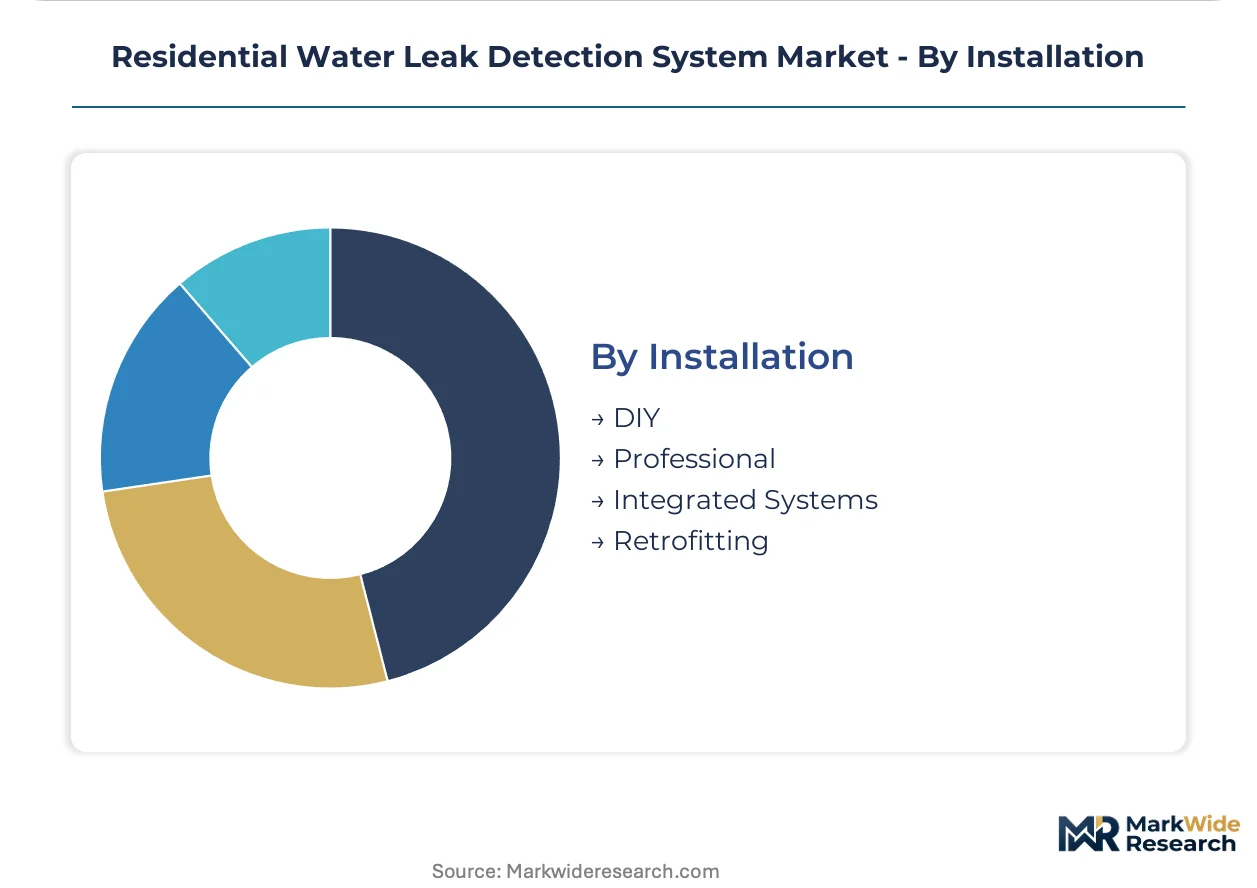
- Professional:Plumber-certified shutoff valve integration dominates whole-home system deployment, particularly in Germany and Japan where regulatory compliance documentation requires licensed trade verification. The dual-trade coordination between plumbers and electricians inflates project management overhead and extends completion timelines.
- Retrofitting:Post-construction installation in finished spaces demands wireless and battery-powered solutions that bypass invasive wall and ceiling access. Aging copper infrastructure in pre-1980 housing stock across the United States and Germany drives this segment's commercial significance despite higher per-unit hardware costs.
- DIY:Consumer self-installation targets point-of-leak sensors with adhesive mounting and smartphone configuration.
- Integrated Systems:New construction pre-wiring enables hardwired, whole-home monitoring with central shutoff actuation.
Professional installation captures current volume leadership; Retrofitting expands most quickly as housing stock ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Homeowner demand concentrates in the United States, Germany, and Japan where aging copper infrastructure and premium housing stock drive replacement cycles. Regulatory efficiency mandates across multiple jurisdictions are tightening installation requirements and reshaping procurement patterns.
United States
Pre-1980 residential plumbing stock and EPA WaterSense certification thresholds drive whole-home monitoring adoption. The FCC governs radio-frequency communications in connected systems, creating compliance complexity for wireless sensor imports. California's coastal markets and Florida's flood zones concentrate insurance-mandated hardware deployment.
Germany
Multifamily retrofit programs and EU Green Deal building decarbonization linkage create integrated efficiency audit demand. The F-Gas Regulation indirectly accelerates water efficiency hardware through comprehensive utility monitoring requirements. Scalar-integrated systems consolidate water, thermal, and refrigerant monitoring in the Rhine-Ruhr and Bavarian housing clusters.
Japan
Zero-tolerance insurance underwriting in high-value residential construction drives optical sensing adoption over acoustic methods. METI efficiency standards and JIS quality frameworks elevate baseline product specifications. Tokyo and Osaka metropolitan areas concentrate premium housing stock with integrated smart home automation requirements.
United Kingdom
Post-war housing stock deterioration and water utility efficiency programs accelerate leak detection retrofit demand. Building regulations linking water efficiency to renovation subsidies open multifamily pipelines in London and Southeast England. The Environment Agency's water stress designations concentrate policy attention in Southern regions.
India
Municipal smart city water metering convergence creates channel overlap for vendors with utility-grade credentials. Bureau of Indian Standards certification requirements and state-level urban digitization programs in Maharashtra and Karnataka reshape procurement specifications. Mumbai and Bangalore metropolitan authorities pilot integrated residential monitoring in premium developments.
Residential Water Leak Detection System Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positioning through regulatory integration depth. The market exhibits moderate concentration with building automation conglomerates controlling professional installation channels while sensor technology specialists capture retrofit and smart home segments. Three archetypes dominate: diversified industrial conglomerates with building controls heritage, pure-play sensor technology developers, and utility-scale metering incumbents expanding downstream. Competitive moves center on protocol standardization alliances and cartridge-based hardware modularity to capture recurring sensor refresh revenue.
Among diversified industrial conglomerates, Honeywell International and Siemens exemplify the building automation heritage archetype, leveraging channel control across professional installation networks. Johnson Controls occupies a comparable position in North American commercial-to-residential crossover applications. Phyn represents the machine-learning pressure analytics specialization, competing with conventional detection methodologies through algorithmic differentiation. These three anchors illustrate how technology heritage shapes competitive positioning without dictating specific strategic outcomes.
| Leading Market Players |
|---|
| Honeywell International |
| Siemens |
| Johnson Controls |
| TTK |
| Aquilar |
| Badger Meter |
| LeakSmart |
| Phyn |
| American Leak Detection |
| Others |
Pricing and Supply Chain Analysis
Copper price volatility on the London Metal Exchange cascades through sensor housing and shutoff valve manufacturing, compressing margins on economy-tier fixed sensors while premium optical systems absorb input swings through subscription bundling.
Pricing Analysis
Volume leadership in acoustic sensors runs on thin margins, while optical and pressure-analytic systems command substantial premiums. Three-tier pricing structure across premium, standard, and economy levels separates EPA WaterSense-certified whole-home systems from uncertified point sensors and DIY battery units. Cost compression in the economy tier is intensifying because Taiwanese RF chip supply constraints force hardware redesigns. Property managers exhibit highest price sensitivity due to bulk procurement authority, whereas individual homeowners in flood-zone markets show lowest sensitivity when insurance mandates apply.
Supply Chain Analysis
Domestic-content mandates in India's Bureau of Indian Standards certification reshape sourcing for vendors targeting Maharashtra and Karnataka smart city pilots. RF transceiver chip fabrication concentrates in Taiwan, South Korea, and China, while precision pressure sensor manufacturing anchors in Germany and Japan. Supply chain vulnerability rests on single-source dependency for machine-learning inference chips. Distribution runs through professional installation networks in developed markets and utility-channel partnerships in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protocol standardization pressure from Matter and Zigbee certifications is forcing subscale sensor vendors toward distressed exits, creating consolidation opportunities for well-capitalized building automation incumbents.
For Market Incumbents: Acquire machine-learning engineering teams to counter Phyn's algorithmic differentiation. Honeywell International and Siemens should prioritize backward integration into RF chip supply through foundry partnerships in South Korea, insulating production schedules from Taiwan concentration risk. Certification depth in EPA WaterSense and EU Green Deal audit frameworks remains the priority lever for channel control.
For New Entrants and Emerging Players: Renters and multifamily tenants in urban India represent the most underserved buyer archetype. Portable battery-powered systems bypass landlord permission barriers in Mumbai and Bangalore premium developments. A direct utility-partnership go-to-market angle leverages municipal smart city procurement channels without competing for retail shelf space.
For Investors and Strategic Acquirers: Distressed-cycle entries favor sensor-technology specialists with cartridge-modular hardware architectures in Germany and the Netherlands. Long-term viability hinges on recurring sensor refresh revenue streams rather than one-time hardware sales. Watch for insurance carrier mandate expansion beyond Florida and coastal Texas as the inflection signal for intermediated demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine-Learning Acquisition | Algorithmic pressure analytics displace acoustic methods in premium housing segments. |
| Cartridge Modularity Investment | Swappable sensing elements capture recurring revenue from hardware upgrade cycles. |
| Utility-Channel Partnership | Municipal smart city convergence in India creates overlap with residential leak detection. |
| Insurance Compliance Integration | Carrier-mandated hardware requirements in flood zones shift procurement authority. |
| RF Chip Supply Diversification | Taiwan concentration risk forces foundry partnerships in South Korea and Japan. |
Research Methodology
Independent corroboration across sensor manufacturer product managers, professional installation network heads, and insurance carrier risk officers underwrites the qualitative findings. Secondary validation draws from EPA WaterSense certification databases, FCC equipment authorization filings, EU Green Deal implementation reports, and Bureau of Indian Standards registration records. Bottom-up sensor shipment estimates triangulate against top-down building automation revenue disclosures.
Rate-of-change decomposition separates volume expansion from price-mix effects across the analysis window. Segmentation dimensions include product type, detection technology, end-user procurement authority, and installation pathway. CAGRs derive from fitted growth curves applied to annual shipment estimates. Industry-specific inputs incorporate copper price indices, semiconductor lead time surveys, and insurance underwriting criteria evolution.
Revisions become necessary when EPA WaterSense certification thresholds tighten, Taiwan semiconductor export restrictions materialize, or insurance mandate expansion accelerates beyond pilot regions. Forecasts reflect documented assumptions about smart home protocol adoption curves and retrofit labor cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Indoor Air Quality Monitor Market
Sensors
Asset Tags Market
Sensors
2D Barcode Reader Market
Sensors
Global Smart Leak Detection Solutions Market
Sensors
Vibration Monitoring Market
Sensors
Global Heat Stress Monitor (HSM) Market
Sensors
Transport Monitoring System Market
Sensors
Data Buoy Market
Sensors
In-Counter Barcode Scanners Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
Portable Iris Recognition Scanner Market
Sensors
Smart Beacon Market
Sensors
Machine Health Monitoring Market
Sensors
Lidar Market
Sensors
Bluetooth Beacons Market
Sensors
Mobile Lidar Scanner Market