
 Saudi Arabia Data Center Power Market | 2026-2036
Saudi Arabia Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Data Center Power Market Insights
Saudi Arabia's data center power infrastructure is consolidating around hyperscale commitments in Riyadh and Jeddah. Schneider Electric SE leverages its prefabricated modular power portfolio to anchor large-scale deployments across the Kingdom. ABB Ltd sustains competitive positioning through its medium-voltage UPS and grid-integration expertise. Vertiv Group Corp. differentiates via thermal-electrical co-design for high-density AI workloads.
Data center power encompasses the electrical generation, conditioning, distribution, and backup systems that maintain continuous operation of compute facilities, typically operating at voltages from 480V to 34.5kV with redundancy tiers from N to 2N+1. Its primary purpose is eliminating downtime for mission-critical digital infrastructure. Diesel generators retain dominant installed share across existing facilities, yet renewable energy integration is accelerating fastest as PPA structures mature. Enterprise-level capacity deployments concentrate margin pools given their bespoke engineering requirements and long-term service attach rates.
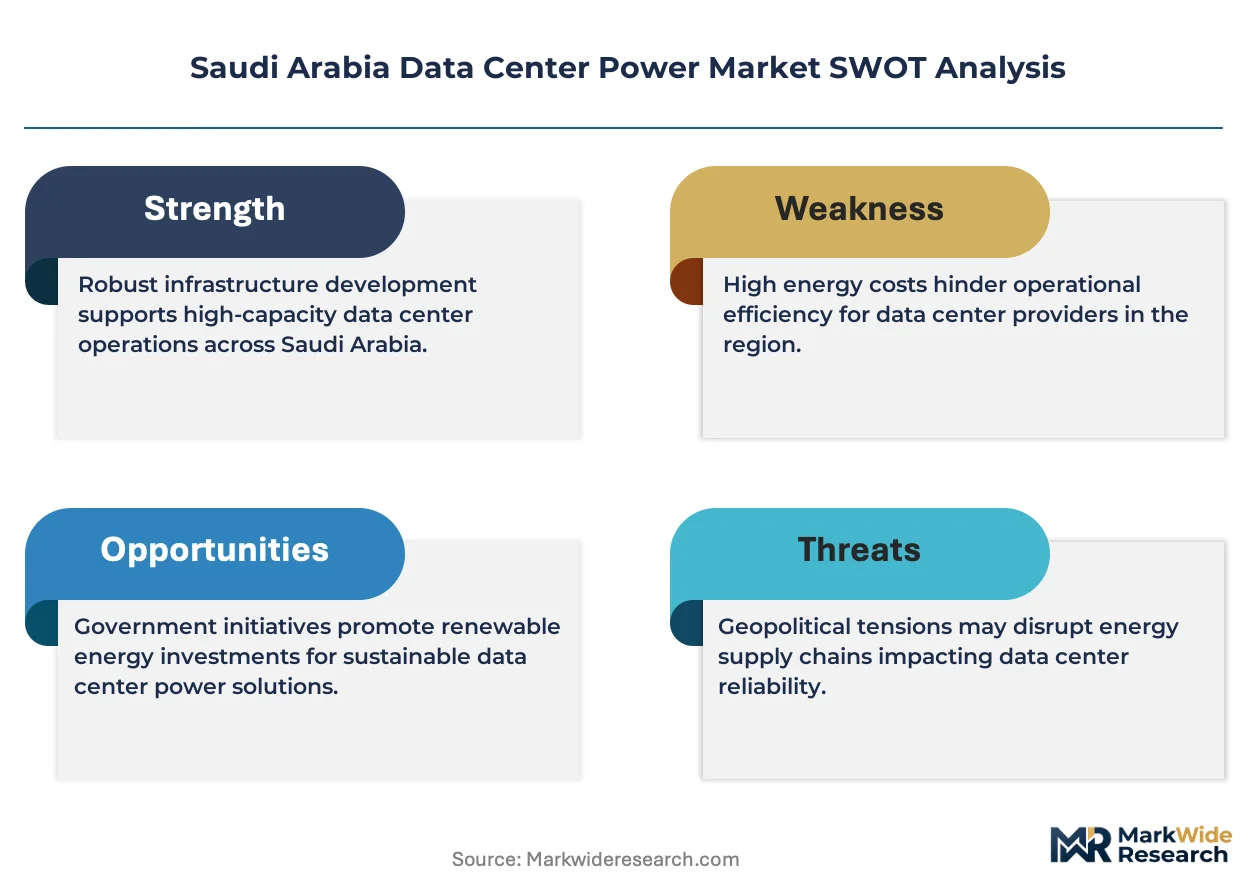
SFDA, the Saudi Energy Efficiency Center, and SASO standards govern equipment efficiency certifications and building energy performance thresholds for data center operations. These frameworks directly shape procurement specifications, mandating minimum Power Usage Effectiveness targets and restricting import of non-compliant electrical equipment. Stakeholders must monitor how NEOM's zero-carbon commitments and evolving SASO efficiency tiers will reconfigure supplier qualification criteria and total cost of ownership models.
Market Dynamics
Hyperscale facility commitments in Riyadh and Jeddah are concentrating procurement power among cloud operators, forcing power infrastructure suppliers to reconfigure delivery models around modular, renewable-ready architectures.
Growth Catalysts
- NEOM Zero-Carbon Mandates:The smart city's 100% renewable energy requirement is accelerating demand for solar-integrated UPS and battery storage systems in western corridor developments.
- SASO Efficiency Tier Upgrades:Revised equipment certification standards are phasing out legacy transformer and generator imports, creating replacement cycles for compliant power distribution units.
- AI Training Clusters:Domestic cloud providers are deploying GPU-intensive workloads that require 50-100MW per facility, driving procurement of high-density busway and switchgear configurations.
Market Restraints
- Copper and Rare Earth Input Volatility:Price swings in copper busbars and neodymium magnets for high-efficiency transformers compress margin predictability for equipment fabricators serving the Kingdom.
- European Component Supply Concentration:Critical medium-voltage switchgear and intelligent power management controllers remain dependent on German and Swiss manufacturing, exposing lead time risks.
- Diesel Generator Lock-In:Existing facilities carry 15-20 year depreciation schedules on backup gensets, slowing hybrid renewable-diesel transition timelines despite carbon reduction targets.
Strategic Opportunities
- Eastern Province Data Corridor:Dammam and Khobar remain underpenetrated relative to Riyadh-Jeddah concentration, offering first-mover positioning for prefabricated power module deployments.
- Saudi Energy Efficiency Center Incentive Programs:Rebate structures for PUE improvements below 1.3 are creating attach-rate opportunities for continuous monitoring and predictive maintenance services.
- Thermal-Electrical Co-Design Convergence:Integration of liquid cooling manifolds with power busway systems is enabling single-vendor accountability for AI facility energy infrastructure.
Industry Challenges
- High-Voltage Commissioning Expertise Gap:Local shortages of 34.5kV switchgear specialists and protection relay technicians are extending project handover timelines by 4-6 months.
- SFDA Equipment Certification Backlogs:Safety and electromagnetic compatibility approvals for imported power electronics are creating inventory holding costs and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Data Center Power Market |
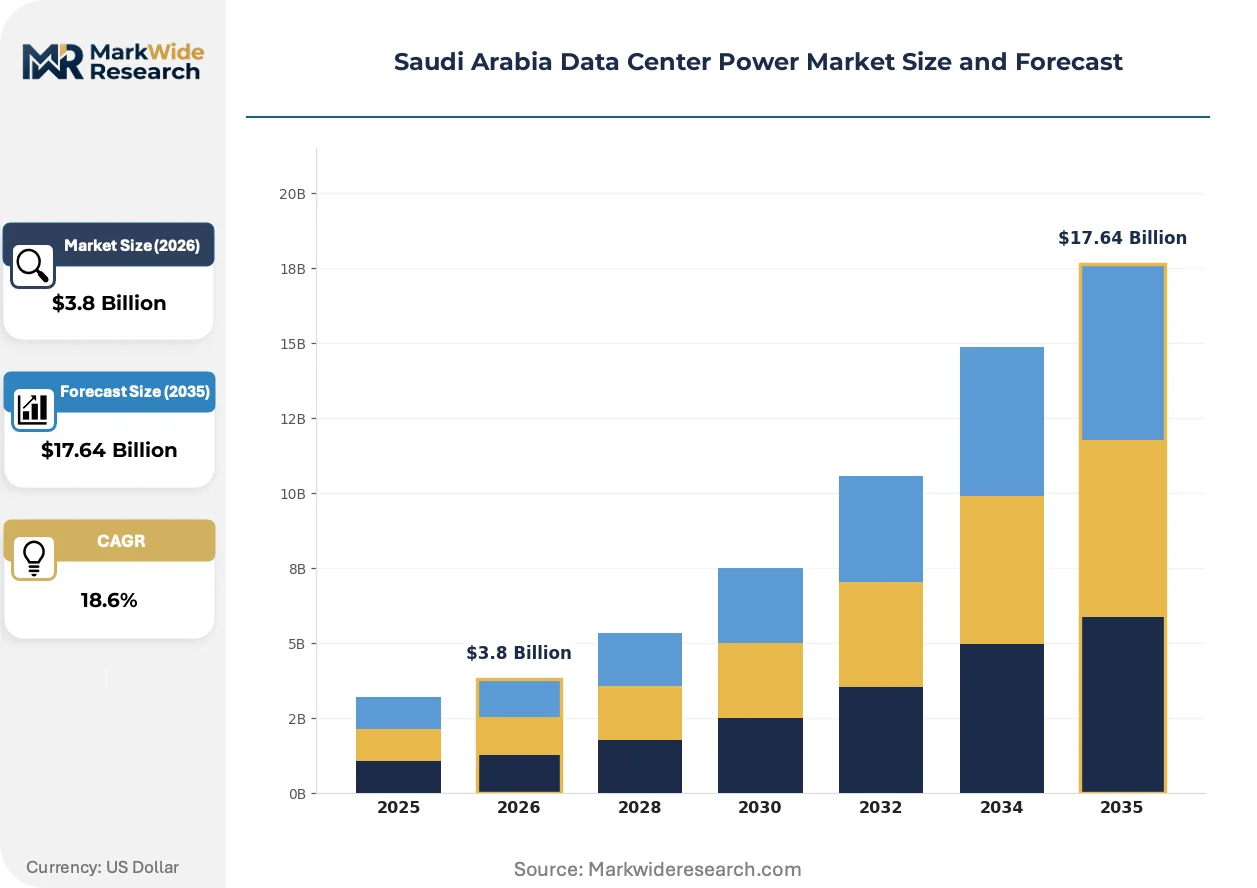
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Grid Power, Renewable Energy, Diesel Generators, UPS Systems Service Type: Colocation Services, Managed Hosting, Cloud Services, Hybrid Solutions End User: Telecommunications, IT & Software, Financial Services, Healthcare Capacity: Small Scale, Medium Scale, Large Scale, Enterprise Level |
| Companies Covered | Schneider Electric SE, ABB Ltd, Vertiv Group Corp., Eaton Corporation plc, Caterpillar Inc., Cummins Inc., Legrand Group, Rolls-Royce Power Systems, Rittal GmbH & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Data Center Power Market Trends and Innovations
Lithium-ion battery energy storage systems are displacing traditional valve-regulated lead-acid configurations across Tier III and Tier IV facilities, while intelligent power management software layers are embedding predictive analytics into hardware procurement decisions.
Solid-state transformer technology is expanding into hyperscale substation designs, enabling direct medium-voltage-to-480V conversion without conventional liquid-filled transformers. Cloud operators in Riyadh are specifying these units for 50MW+ deployments to reduce footprint and cooling loads. The technology is expanding into vendor qualification programs as a prerequisite for NEOM-related tenders.
Saudi Energy Efficiency Center building codes are mandating real-time PUE monitoring and annual efficiency reporting for facilities above 1MW capacity. Equipment suppliers must now bundle metering hardware and cloud-based analytics dashboards to maintain procurement eligibility. Western corridor developments face the strictest enforcement timelines, compressing vendor certification cycles.
Power purchase agreement structures are displacing capital-heavy on-site generation for renewable-ready facilities. Hyperscale operators are contracting 20-year solar and wind supply contracts through ACWA Power and similar developers, reducing direct ownership of generation assets. This financialization is most visible in Jeddah Islamic Port adjacent zones where land constraints favor off-site renewable integration.
Saudi Arabia Data Center Power Market Segmentation
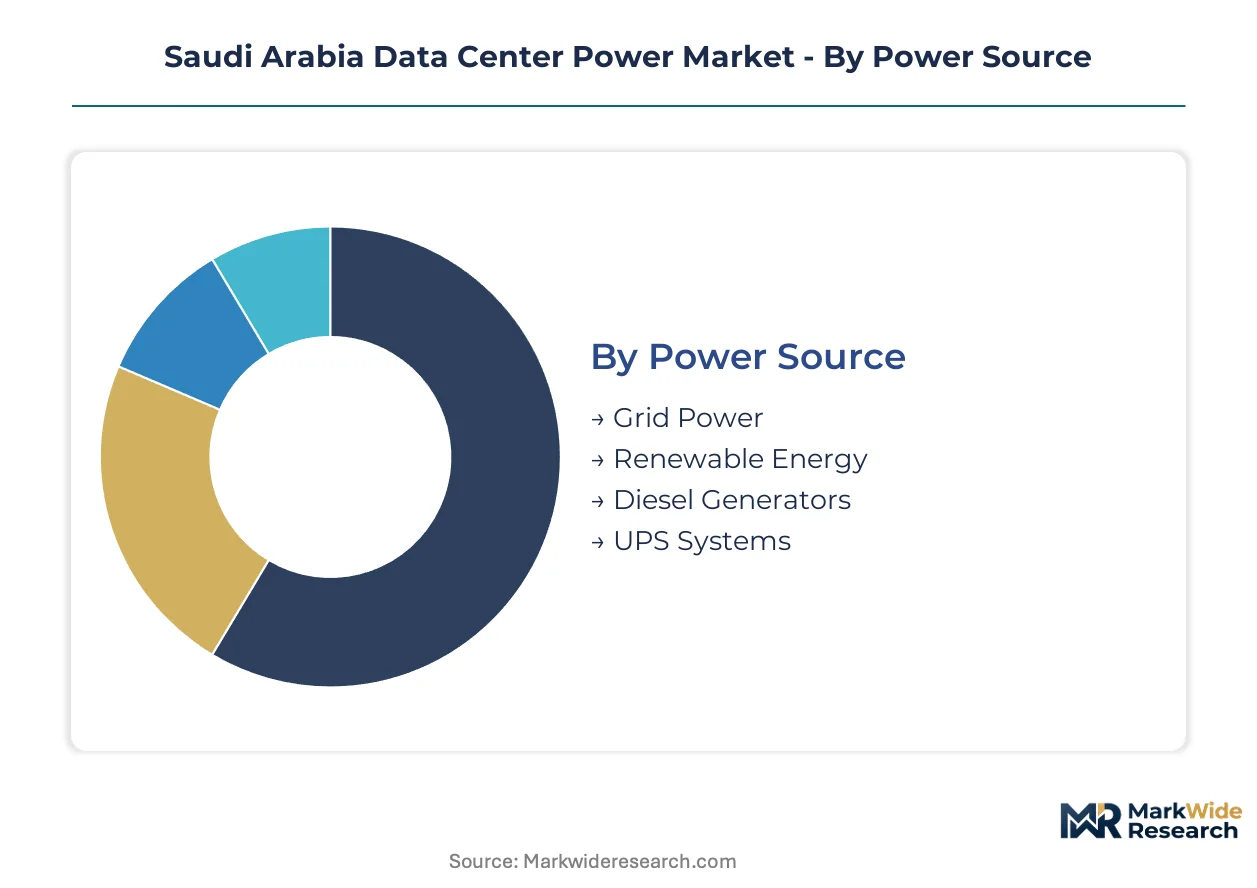
Power infrastructure procurement in Saudi Arabia fragments across four dimensions that reshape vendor qualification requirements. Equipment suppliers must align product portfolios with hyperscale operator specifications while navigating SASO efficiency mandates and NEOM's zero-carbon procurement thresholds.
Power Source:
Upgrade and replacement cycles dominate procurement decisions as legacy diesel infrastructure ages and SASO efficiency tiers disqualify non-compliant imports.
- Grid Power:Utility-fed 34.5kV and 13.8kV substations supply baseline load for Riyadh and Jeddah hyperscale campuses. Procurement concentrates among SEC-interconnected facilities where grid stability supports N+1 redundancy without excessive on-site generation.
- Renewable Energy:Solar-integrated microgrids and battery storage systems serve NEOM western corridor developments under 100% clean energy mandates. ACWA Power PPAs are displacing capital-heavy on-site solar ownership among cloud operators seeking carbon compliance without asset burden.
- Diesel Generators:Traditional backup gensets retain installed base across existing Tier II and Tier III facilities carrying 15-20 year depreciation schedules.
- UPS Systems:Lithium-ion configurations are displacing valve-regulated lead-acid units in new Tier III and Tier IV deployments.
Volume placements concentrate in Grid Power; the faster expansion belongs to Renewable Energy.
Service Type:
Customer concentration among cloud operators is reconfiguring margin structures across service delivery models.
- Cloud Services:Hyperscale operator self-builds and direct leases command the largest power infrastructure procurement volumes. GPU-intensive AI training clusters in Riyadh are specifying 50-100MW per facility with liquid-cooled busway integration.
- Colocation Services:Wholesale and retail colo providers in Jeddah Islamic Port adjacent zones are bundling renewable-backed power with space leases. SFDA equipment certification requirements extend commissioning timelines for imported switchgear.
- Managed Hosting:Enterprise-dedicated infrastructure with bespoke SLAs attracts premium engineering attach rates.
- Hybrid Solutions:On-premise and cloud-integrated architectures are gaining traction among financial services compliance requirements.
Revenue pools concentrate in Cloud Services; the steepest expansion trajectory belongs to Colocation Services.
End User:
Vertical-specific uptime requirements and regulatory exposure shape redundancy tier selection and service contract structures.
- IT & Software:Domestic cloud providers and SaaS operators drive procurement of high-density busway and intelligent power management systems. AI workload deployment is forcing thermal-electrical co-design specifications.
- Financial Services:SAMA-regulated banks mandate 2N+1 redundancy with documented disaster recovery testing. Riyadh-based institutions are consolidating data center footprints into certified Tier IV facilities.
- Telecommunications:STC and Mobily network infrastructure requires distributed edge power systems across the Kingdom.
- Healthcare:SFDA data residency rules are accelerating localized facility construction with strict electromagnetic compatibility standards.
Contract values concentrate in IT & Software; the fastest share gain belongs to Financial Services.
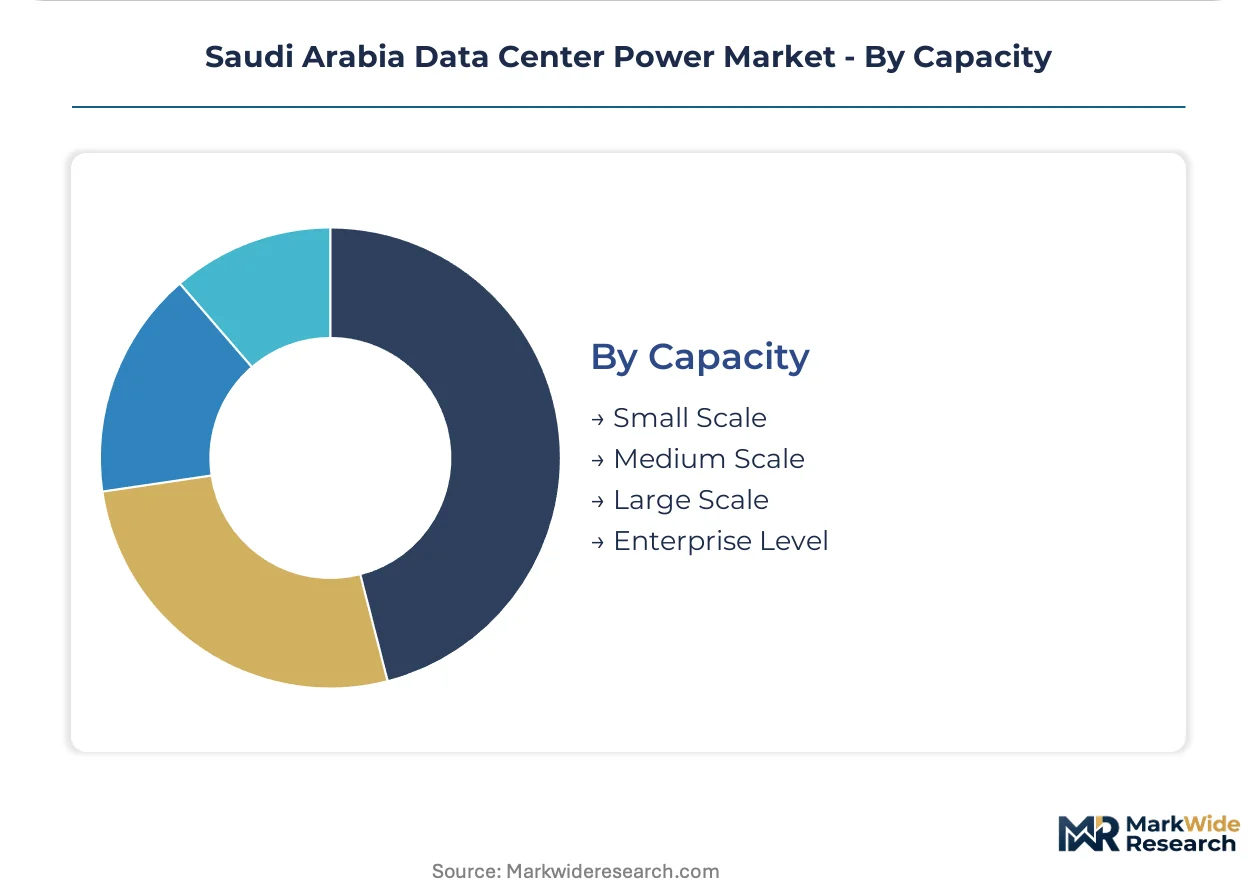
Capacity:
Scale thresholds determine whether facilities qualify for utility-scale grid interconnection or remain captive to distributed generation.
- Enterprise Level:Single-tenant facilities above 10MW command bespoke engineering and long-term service attach rates. NEOM smart city mandates are specifying solid-state transformer technology for these deployments.
- Large Scale:5-10MW facilities in Jeddah and Riyadh are standardizing on prefabricated modular power skids to compress construction schedules.
- Medium Scale:1-5MW deployments in Dammam and Khobar are attracting first-mover modular power module positioning.
- Small Scale:Sub-1MW edge and branch office installations face the strictest Saudi Energy Efficiency Center PUE monitoring requirements.
Margin concentration sits with Enterprise Level; the quickest climb belongs to Large Scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper concentrate from Jeddah Islamic Port anchors power infrastructure fabrication across the Kingdom's western corridor. Rare earth magnet imports through King Abdulaziz Port in Dammam feed transformer manufacturing for eastern deployments. Grid interconnection capacity at 34.5kV determines facility siting economics across all major load centers.
Riyadh
Hyperscale cloud campuses in King Abdullah Financial District and KAFD Tech Zone drive 50-100MW power procurement clusters. SASO efficiency tier upgrades mandate real-time PUE monitoring above 1MW capacity. STC and Mobily data centers in the capital standardize on prefabricated modular power skids with lithium-ion UPS integration.
Jeddah
Jeddah Islamic Port adjacent zones concentrate colocation builds bundling renewable-backed power leases. ACWA Power PPAs displace on-site solar ownership among cloud operators facing land constraints. SFDA equipment certification requirements extend commissioning timelines for imported medium-voltage switchgear.
Eastern Province
Dammam and Khobar remain underpenetrated relative to Riyadh-Jeddah concentration, offering first-mover positioning for modular power module deployments. Aramco digital infrastructure investments and SABIC enterprise facilities create anchor demand for 5-10MW standardized configurations. SEC grid stability in the region supports N+1 redundancy without excessive on-site generation.
NEOM Northwest
The smart city's 100% renewable energy mandate accelerates solar-integrated UPS and battery storage procurement. Solid-state transformer technology enters vendor qualification programs as prerequisite for zero-carbon tenders. Western corridor developments face strictest Saudi Energy Efficiency Center enforcement timelines.
Saudi Arabia Data Center Power Market Competitive Landscape
Global majors compete with regional champions across power infrastructure fabrication and grid integration capabilities. Market structure tilts toward consolidated procurement power among hyperscale operators, compressing vendor margins while demanding modular, renewable-ready architectures. Three archetypes dominate: integrated electrical-multinational conglomerates, thermal-electrical co-design specialists, and diesel-generator incumbents defending installed base. Competitive moves concentrate on M&A for lithium-ion battery technology and strategic partnerships for local manufacturing qualification.
Within the integrated electrical tier, Schneider Electric SE and ABB Ltd occupy anchor positions across medium-voltage and low-voltage power distribution. Vertiv Group Corp. exemplifies the thermal-electrical co-design archetype serving high-density AI workload specifications. These three entities represent the dominant vendor qualification set for Tier III and Tier IV facility tenders.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd |
| Vertiv Group Corp. |
| Eaton Corporation plc |
| Caterpillar Inc. |
| Cummins Inc. |
| Legrand Group |
| Rolls-Royce Power Systems |
| Rittal GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Copper busbar and neodymium magnet costs cascade from German and Swiss component manufacturers through to equipment fabricators serving Riyadh and Jeddah hyperscale campuses, with warranty bundling and predictive maintenance attach rates determining final procurement tiers across enterprise and large-scale deployments.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers from unbundled transactional competitors in the Saudi market. Three-tier pricing structure across premium, standard, and economy levels tracks SASO certification grade and lithium-ion UPS integration depth. Cost compression in mid-tier switchgear is intensifying because European component lead times stretch project margins. Cloud operators in King Abdullah Financial District show lowest price sensitivity given AI cluster uptime requirements, while Dammam-based industrial facilities negotiate hardest on generator replacement cycles.
Supply Chain Analysis
Regional distribution centers in Jeddah Islamic Port and King Abdulaziz Port in Dammam anchor hub-and-spoke patterns for copper concentrate and rare earth magnet flows. Manufacturing concentration rests on Germany, Switzerland, and China for medium-voltage switchgear, intelligent power controllers, and solid-state transformer components. Single-source vulnerability in European protection relay supply creates commissioning bottlenecks extending project timelines. Distribution runs through SEC-interconnected substation contractors for grid-fed hyperscale campuses, with prefabricated modular skids bypassing traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi data center power market is becoming a vertical-integration race as suppliers pursue captive lithium-ion battery production to secure margin control against raw material volatility and certification backlogs.
For Market Incumbents: Deploy solid-state transformer R&D partnerships to preempt NEOM zero-carbon qualification requirements. Incumbent suppliers must secure Saudi Energy Efficiency Center pre-certification for intelligent power management software to defend against modular power skid competitors entering from European manufacturing bases. Backward integration into copper busbar fabrication mitigates margin compression from Jeddah Islamic Port concentrate price swings. For New Entrants and Emerging Players: Enter via Dammam and Khobar underpenetrated zones with standardized 5-10MW prefabricated power modules targeting Aramco and SABIC enterprise demand. Eastern Province grid stability supports N+1 redundancy without excessive on-site generation, lowering capital barriers. Go-to-market leverage rests on SEC interconnection expertise and 34.5kV commissioning capability where local specialist shortages extend incumbent project timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor thermal-electrical co-design specialists with NEOM vendor qualification progress amid SFDA certification backlogs. Long-term viability over the coming decade hinges on renewable-integrated microgrid execution capability. Watch ACWA Power PPA contracting velocity as inflection signal for capital-light renewable adoption displacing on-site generation ownership.| Strategic Initiative | Industry Significance |
|---|---|
| Lithium-Ion Battery Vertical Integration | Captive cell production secures margin control against neodymium and copper volatility for UPS manufacturers. |
| Solid-State Transformer Partnership | Direct medium-voltage conversion technology meets NEOM zero-carbon procurement thresholds without liquid-filled transformer footprint. |
| Prefabricated Modular Power Skid Deployment | Compressed construction schedules attract hyperscale operators facing SASO efficiency tier upgrade deadlines in Riyadh and Jeddah. |
| SFDA Pre-Certification Investment | Accelerated safety and electromagnetic compatibility approvals reduce inventory holding costs and revenue recognition delays. |
| Eastern Province Distribution Expansion | First-mover positioning in Dammam and Khobar captures Aramco and SABIC anchor demand before incumbent saturation. |
Research Methodology
Independent corroboration across hyperscale facility engineering directors, SEC grid interconnection planners, and SFDA certification officers underwrites the qualitative findings in this study. Primary interviews with EPC contractors, power distribution unit procurement leads, and lithium-ion battery system integrators combined with secondary validation from SASO efficiency tier documentation, ACWA Power PPA disclosure filings, and NEOM smart city technical specifications. Bottom-up equipment shipment tracking and top-down utility interconnection capacity modeling triangulate market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from value mix shift across power source segmentation, service type tiering, and capacity scale thresholds. The analytical framework projects adoption curves for renewable-integrated architectures against diesel generator replacement cycles throughout the forecast period. CAGRs derive from facility-level power density specifications, PUE improvement trajectories, and hyperscale operator capex commitment patterns modeled against Saudi Energy Efficiency Center enforcement timelines.
Revisions become necessary when copper and rare earth commodity volatility exceeds modeled bands, when SFDA certification processing times shift materially, or when NEOM zero-carbon procurement thresholds tighten beyond current vendor qualification standards. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Austria Data Center Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
IT Infrastructure Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
High Frequency Trading Server Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
UAE Data Center Server Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
Italy Data Center Rack Market
Data Center Infrastructure
Data Center Support Infrastructure Market