
 United Arab Emirates Data Center Market | 2026-2036
United Arab Emirates Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Data Center Market Insights
Modular rack-scale deployments with integrated power and cooling is recalibrating procurement patterns among hyperscale tenants. Khazna Data Centers leverages its Abu Dhabi footprint to anchor government and enterprise workloads. Digital Realty competes through global interconnection fabrics that extend into the UAE. Core42 G42 Company differentiates via AI-optimized infrastructure designed for sovereign cloud requirements.
A data center comprises purpose-built facilities housing servers, storage systems, and networking equipment with controlled environmental parameters including power density exceeding 20 kW per rack and precision cooling maintaining temperatures between 18°C and 27°C, serving as the physical backbone for enterprise IT, cloud computing, and digital service delivery. Colocation and cloud services command the largest revenue pools as enterprises shed owned infrastructure. Edge computing deployments represent the fastest-expanding deployment category, driven by latency-sensitive applications in autonomous systems and industrial IoT. Managed hosting maintains steady uptake among mid-market firms seeking operational outsourcing without full cloud migration.
MOHAP enforces health data residency rules that mandate domestic storage of patient records, while the UAE's central bank imposes operational risk frameworks requiring financial institutions to maintain auditable disaster recovery capabilities. TRAI-equivalent spectrum and data governance policies reinforce infrastructure localization as a compliance necessity. Stakeholders must monitor evolving sovereign AI regulations that could mandate domestic training infrastructure and reshape capacity planning timelines.
Market Dynamics
MOHAP's health data residency mandates and the UAE's sovereign AI strategy are forcing immediate capacity buildouts in Abu Dhabi and Dubai, compressing deployment timelines from 36 months to 18 months for compliant infrastructure.
Growth Catalysts
- MOHAP Health Data Localization:Patient record storage requirements mandate domestic facilities, pulling healthcare providers into colocation contracts.
- AI Training Infrastructure:Sovereign cloud mandates under the UAE AI Strategy 2031 require domestic GPU clusters for government workloads.
- BFSI Cloud Migration:Financial institutions are relocating core banking systems off-premises to meet central bank operational risk frameworks.
Market Restraints
- Liquid Cooling Supply Concentration:Precision cooling equipment relies on concentrated European and East Asian component suppliers, exposing projects to 20-24 week lead times.
- Power Grid Interconnection Queues:DEWA and ADDC high-voltage connection approvals extend 14-18 months for hyperscale loads above 50 MW.
- Land Zoning Restrictions:Free zone authorities limit data center development to designated districts, constraining site selection in Dubai and Abu Dhabi.
Strategic Opportunities
- Ras Al Khaimah Expansion:Lower land costs and emerging fiber connectivity create white space for secondary market entry outside the Abu Dhabi-Dubai corridor.
- Edge Computing for Autonomous Systems:Latency requirements for port automation and industrial IoT are driving micro-data center deployments in Khalifa Industrial Zone.
- Green Hydrogen Power Purchase Agreements:ADNOC and Masdar renewable energy frameworks offer carbon-neutral power sourcing for sustainability-mandated tenants.
Industry Challenges
- Specialized Engineering Talent Scarcity:Hyperscale mechanical and electrical design expertise concentrates with international contractors, inflating project management costs.
- Multi-Tenant Security Certification:UAE IA and ADSIA compliance timelines add 4-6 months to facility commissioning for government-facing deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Data Center Market |
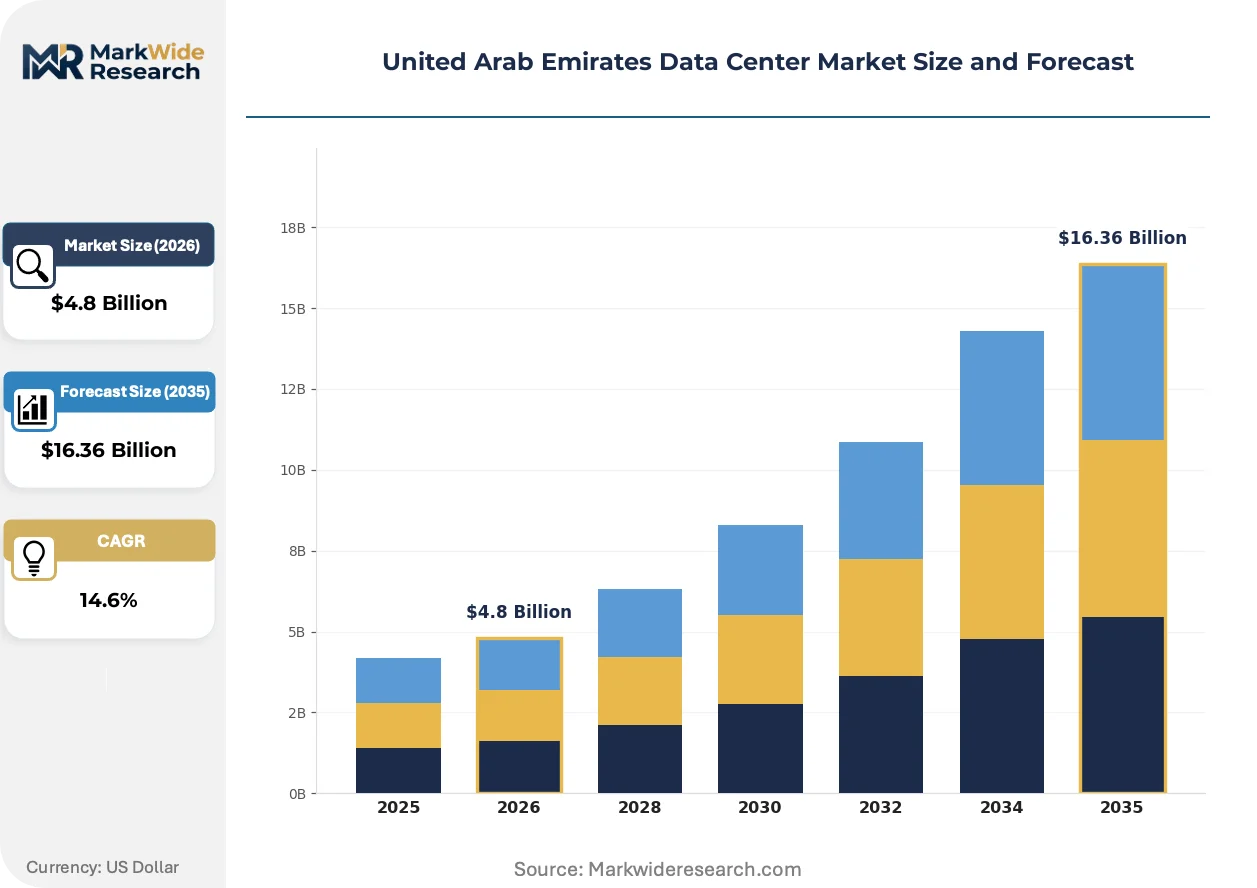
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Managed Hosting, Cloud Services, Hybrid Solutions End User: Government, BFSI, IT & Telecom, Healthcare Deployment: On-Premises, Off-Premises, Hybrid, Edge Computing Service Type: Disaster Recovery, Security Services, Network Management, IT Support |
| Companies Covered | Digital Realty, du (Emirates Integrated Telecommunications Company), Khazna Data Centers, Core42 G42 Company, NTT Global Data Centers, Equinix, Etisalat, Pacific Controls Data Center, Gulf Data Hub, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Data Center Market Trends and Innovations
Modular rack-scale architectures are displacing traditional raised-floor designs as hyperscale tenants demand factory-integrated power and cooling. This shift compresses construction schedules and reduces on-site labor dependencies.
Direct liquid cooling is expanding into high-density AI training racks as GPU power draw exceeds 40 kW per unit. Hyperscale operators in Masdar City and Dubai Silicon Oasis are adopting cold plate and immersion systems at scale. The technology is expanding into standard enterprise colocation as density requirements rise across tenant segments.
MOHAP's 2023 health data residency circular tightens enforcement of patient record domesticity, requiring healthcare providers to certify sub-10 millisecond latency to storage. Hospital systems and health insurers are renegotiating cloud contracts to include UAE-based primary infrastructure. The regulation is accelerating sovereign cloud specialization among local operators.
Enterprise procurement of data center capacity is consolidating through multi-year reserved instance contracts rather than month-to-month colocation. Mid-market firms in Sharjah and Ajman are abandoning owned server rooms for managed infrastructure subscriptions. This pattern is most pronounced in BFSI and healthcare verticals facing compliance-driven infrastructure audits.
United Arab Emirates Data Center Market Segmentation
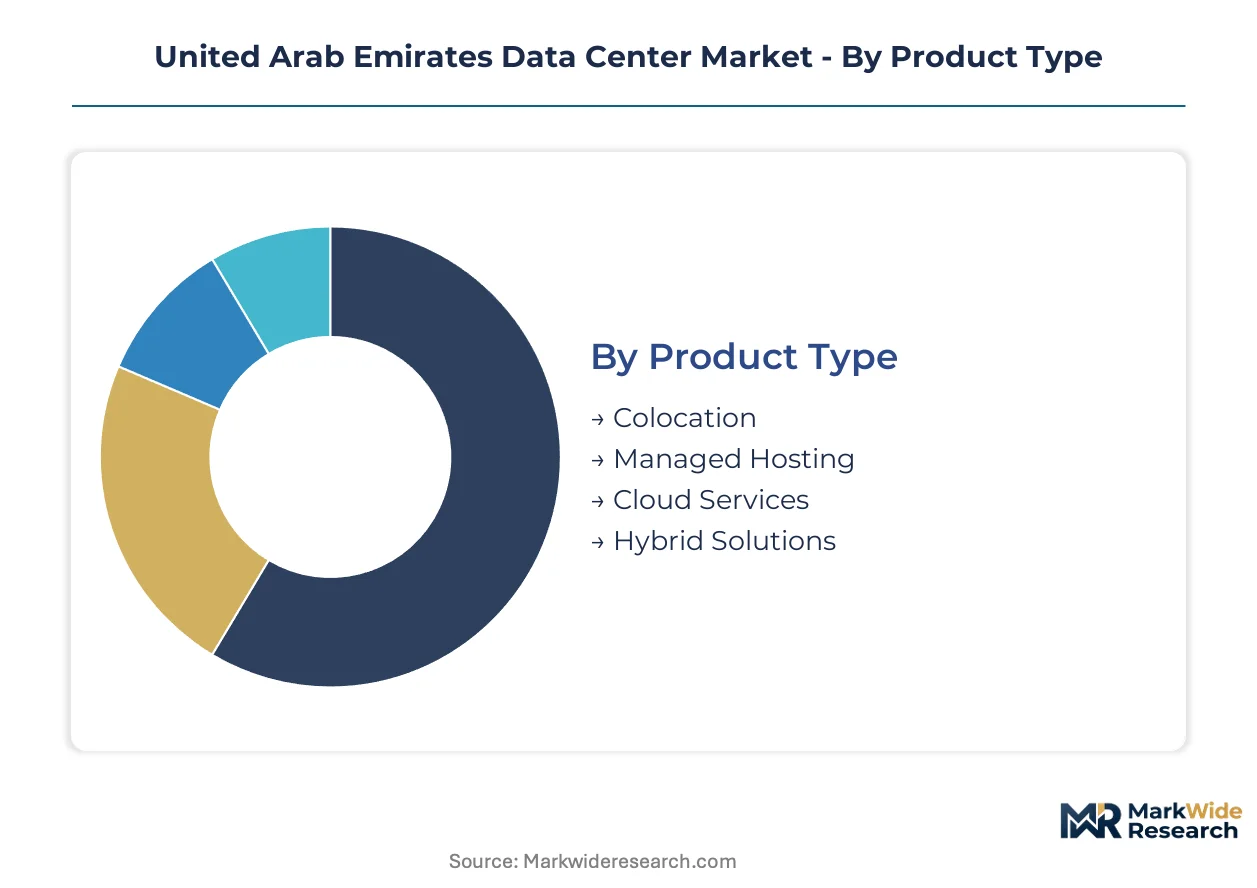
Procurement patterns across the UAE data center market diverge sharply by workload sensitivity and compliance exposure. Buyers segment infrastructure choices based on sovereignty requirements, latency thresholds, and operational control needs rather than cost optimization alone.
Product Type:
Enterprise procurement decisions pivot on capital efficiency versus operational control trade-offs, with compliance mandates increasingly dictating deployment architecture.
- Colocation:Facilities offering leased rack space with shared power and cooling infrastructure. Healthcare providers in Abu Dhabi are consolidating here to satisfy MOHAP data residency rules without facility ownership burdens.
- Managed Hosting:Fully outsourced server management with vendor-operated hardware layers. Mid-market BFSI firms in Dubai favor this model to meet central bank audit requirements while avoiding internal IT scale.
- Cloud Services:On-demand compute and storage via hyperscale platforms.
- Hybrid Solutions:Integrated on-premises and cloud orchestration environments.
Volume sits with Colocation; growth tilts toward Hybrid Solutions.
End User:
Regulatory intensity varies dramatically across verticals, creating divergent infrastructure specifications and certification timelines.
- Government:Sovereign workloads requiring UAE IA and ADSIA compliance with dedicated security clearances. Abu Dhabi Smart City initiatives and federal AI training clusters anchor demand for domestically controlled GPU infrastructure.
- BFSI:Banking, financial services, and insurance institutions subject to central bank operational risk frameworks. Core banking migrations off-premises are accelerating reserved instance contracting with local operators.
- IT & Telecom:Technology and telecommunications service providers building regional delivery platforms.
- Healthcare:Hospital systems and insurers responding to MOHAP patient record localization mandates.
Revenue concentrates with BFSI; Healthcare is expanding most quickly.
Deployment:
Latency requirements and data gravity determine physical placement strategy across the Emirates.
- On-Premises:Enterprise-owned facilities with captive infrastructure. Legacy government datacenters in Dubai remain entrenched for classified workloads despite efficiency penalties.
- Off-Premises:Third-party facility utilization without hybrid integration. Standard enterprise productivity workloads are migrating here as managed service penetration deepens in Sharjah and Ajman.
- Hybrid:Orchestrated on-premise and cloud resource pools.
- Edge Computing:Distributed micro-facilities positioned for sub-10 millisecond response. Khalifa Industrial Zone port automation and autonomous logistics are pulling deployments outside the Abu Dhabi-Dubai corridor.
Off-Premises dominates current capacity; Edge Computing claims the steepest expansion trajectory.
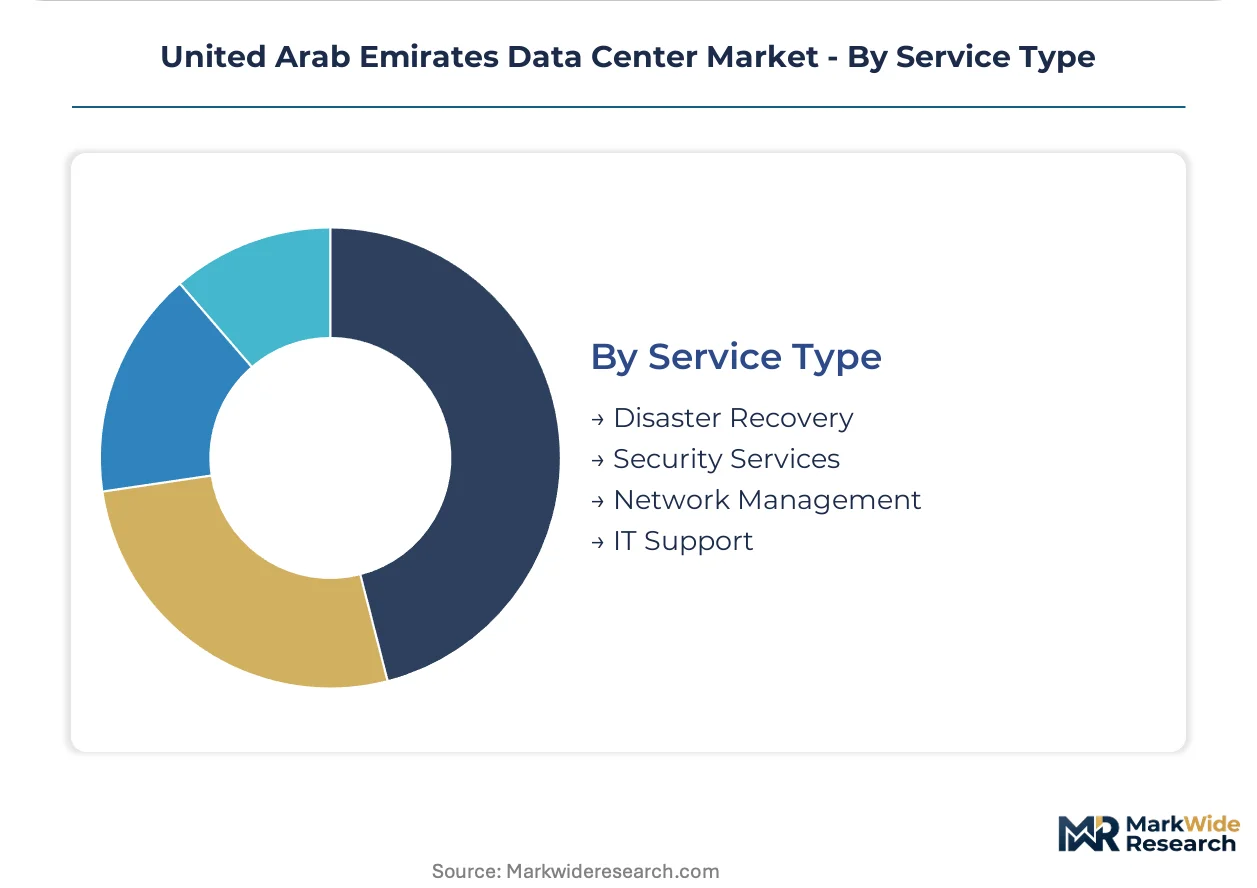
Service Type:
Risk transfer mechanisms and operational specialization shape vendor selection within managed service layers.
- Disaster Recovery:Replicated infrastructure ensuring business continuity with defined recovery point objectives. Central bank frameworks mandate auditable DR capabilities, forcing BFSI institutions into contracted secondary site arrangements.
- Security Services:Threat monitoring, access management, and compliance certification support. Multi-tenant facilities serving government workloads face 4-6 month UAE IA approval extensions that security service vendors must navigate.
- Network Management:Connectivity orchestration and bandwidth optimization.
- IT Support:Technical assistance and infrastructure maintenance services.
Security Services commands premium pricing; Disaster Recovery shows the fastest contract velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production of data center capacity in the United Arab Emirates outpaces regional neighbors, yet consumption concentrates heavily in Abu Dhabi and Dubai. This geographic split shapes infrastructure investment patterns across the Emirates.
Dubai
Financial services migration to cloud platforms drives hyperscale leasing in Dubai Internet City and Dubai Silicon Oasis. The emirate's central bank operational risk frameworks mandate auditable disaster recovery capabilities. Jebel Ali Free Zone anchors cross-border connectivity infrastructure serving Gulf Cooperation Council markets.
Abu Dhabi
Government sovereign workloads and AI training clusters dominate demand in Masdar City and Khalifa Industrial Zone. MOHAP health data residency rules require domestic patient record storage, pulling healthcare providers into certified facilities. ADNOC and Masdar renewable energy frameworks enable carbon-neutral power sourcing for sustainability-mandated tenants.
Sharjah
Mid-market enterprises abandoning owned server rooms create steady colocation uptake in Sharjah Research Technology and Innovation Park. The emirate's lower operational costs attract managed hosting contracts from Ajman and Ras Al Khaimah-based firms. Hamriyah Free Zone emerging fiber connectivity supports secondary market data center development.
Ras Al Khaimah
Port automation and autonomous logistics in Khalifa Industrial Zone drive edge computing deployments for sub-10 millisecond latency requirements. Lower land costs and reduced power tariffs create white space for hyperscale builds outside the Abu Dhabi-Dubai corridor. Al Hamra Industrial Zone attracts disaster recovery secondary sites from Dubai-based financial institutions.
Northern Emirates
Fujairah's submarine cable landing stations position the emirate as a connectivity hub for international bandwidth aggregation. Ajman-based manufacturing firms adopt hybrid cloud arrangements through Sharjah facility access. Umm Al Quwain remains underpenetrated, with limited fiber infrastructure constraining enterprise-grade deployment.
United Arab Emirates Data Center Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the United Arab Emirates data center market. Telecommunications incumbents leverage existing fiber networks and spectrum holdings to anchor integrated service portfolios. Independent operators differentiate through sovereign cloud certifications and AI-optimized infrastructure designs. Consolidation pressures intensify as hyperscale tenants demand multi-megawatt contiguous footprints with sub-18-month delivery timelines. Strategic partnerships between local developers and international technical contractors accelerate specialized engineering access.
Among global platform operators, Digital Realty and Equinix occupy positions emphasizing interconnection fabrics and enterprise cloud on-ramps. Khazna Data Centers and Core42 G42 Company exemplify the sovereign-specialist archetype, anchoring government and AI workload requirements through Abu Dhabi-centric footprints. These three represent divergent competitive vectors: global reach versus domestic compliance depth versus AI infrastructure optimization.
| Leading Market Players |
|---|
| Digital Realty |
| du (Emirates Integrated Telecommunications Company) |
| Khazna Data Centers |
| Core42 G42 Company |
| NTT Global Data Centers |
| Equinix |
| Etisalat |
| Pacific Controls Data Center |
| Gulf Data Hub |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between UAE IA-compliant sovereign facilities and standard enterprise colocation creates parallel pricing architectures that track supply chain specialization. Premium-tier operators absorb 4-6 month compliance extension costs through dedicated security-cleared engineering teams, while commodity providers compete on power density and interconnection latency without certification overhead.
Pricing Analysis
Margin tightening in standard colocation reflects hyperscale tenants consolidating procurement through multi-year reserved instance contracts rather than month-to-month arrangements. Three-tier pricing structure across premium sovereign, standard enterprise, and economy edge deployments differentiates on compliance certification and power density guarantees. Cost-down pressure on mid-market managed hosting accelerates because Sharjah and Ajman firms abandon owned infrastructure for subscription models. Healthcare providers facing MOHAP audits show least price sensitivity; mid-market manufacturing firms in Northern Emirates exhibit highest elasticity.
Supply Chain Analysis
Specialized mechanical and electrical engineering talent scarcity in Germany, the Netherlands, and South Korea constrains hyperscale project delivery timelines. Precision cooling equipment draws from concentrated European and East Asian component suppliers, while GPU clusters for AI training rest on Taiwan and South Korea semiconductor fabrication. Single-source vulnerability in liquid cooling cold plate manufacturing exposes UAE projects to extended procurement cycles. Distribution runs through international EPC contractors with UAE delivery partnerships rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE data center market sits in a liquid cooling transition phase, with direct liquid cooling and immersion systems displacing traditional raised-floor precision cooling as GPU power densities exceed air-cooled thresholds.
For Market Incumbents: Acquire specialized liquid cooling engineering capabilities through technical contractor partnerships or talent recruitment from European hyperscale buildout programs. Incumbents must defend against modular rack-scale competitors compressing deployment timelines by anchoring government sovereign workloads through UAE IA certification maintenance and ADSIA security clearance investments. For New Entrants and Emerging Players: Mid-market healthcare providers in Sharjah and Ras Al Khaimah represent an underserved buyer archetype seeking MOHAP-compliant colocation without Abu Dhabi-Dubai premium pricing. New entrants should target secondary emirate edge computing for Khalifa Industrial Zone port automation, leveraging lower land costs and reduced power tariffs against established operators. Go-to-market positioning should emphasize sub-10 millisecond latency guarantees for autonomous logistics workloads. For Investors and Strategic Acquirers: Exit pathways concentrate in sovereign-specialist operators with Abu Dhabi-centric footprints and established government contracting relationships. Long-term viability hinges on AI training infrastructure deployment capacity under UAE Strategy 2031 mandates. Acquisition target archetypes include modular construction specialists with 18-month delivery capabilities and renewable energy PPA structuring expertise. Watch DEWA and ADDC grid interconnection queue clearance rates as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Direct liquid cooling adoption enables 40+ kW GPU rack densities required for sovereign AI training clusters. |
| UAE IA Security Certification Investment | UAE IA and ADSIA compliance opens government and healthcare verticals with 4-6 month approval timelines. |
| Green Hydrogen PPA Structuring | ADNOC and Masdar renewable frameworks attract sustainability-mandated hyperscale tenants to Abu Dhabi facilities. |
| Modular Rack-Scale Manufacturing Partnership | Factory-integrated power and cooling compresses construction schedules against traditional raised-floor competitors. |
| Ras Al Khaimah Secondary Market Entry | Lower land costs and emerging fiber connectivity create white space outside Abu Dhabi-Dubai concentration. |
Research Methodology
Document review covered hyperscaler capital expenditure disclosures, UAE regulatory circulars from MOHAP and the central bank, and DEWA grid interconnection records, complemented by interviews with data center facility directors, EPC project managers, healthcare IT procurement leads, and BFSI infrastructure heads. Secondary validation drew from customs equipment import data, free zone authority development permits, and renewable energy framework documentation. Bottom-up capacity buildout tracking and top-down demand segmentation triangulation anchored market sizing.
Cross-referencing historical deployment timelines against expert panel input on compression factors shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment type, service tier, end-user vertical, and emirate-level geographic cluster. CAGRs derived from capacity pipeline analysis weighted by regulatory mandate enforcement probability. Forecast inputs incorporated GPU cluster density trajectories and sovereign cloud procurement pattern shifts.
Revisions become necessary when MOHAP regulatory enforcement intensity shifts, DEWA grid interconnection approval timelines extend materially, or sovereign AI training infrastructure mandates expand beyond current Strategy 2031 parameters. Forecasts reflect documented assumptions on hyperscale tenant consolidation behavior and modular construction adoption curves. Regulatory circular amendments, power grid capacity constraints, and specialized engineering labor availability warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Hong Kong Data Center Construction Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
Ireland Data Center Market
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
Connected Distribution Center Market
Data Center Infrastructure
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
Global Datacenter Deployment Spending Market