
 LAMEA Virtual Desktop Infrastructure Market | 2026-2036
LAMEA Virtual Desktop Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Virtual Desktop Infrastructure Market Insights
Healthcare delivery across Latin America is decoupling from traditional workstation models as hospitals deploy virtual desktops for clinician mobility. Microsoft Corporation leverages its Azure stack to anchor cloud-based VDI contracts with Brazilian hospital networks. Citrix Systems, Inc. specializes in high-latency optimization protocols that dominate telemedicine use cases across Andean corridors. Huawei Technologies Co., Ltd. competes on price-performance hardware bundles in African public-sector tenders.
Virtual Desktop Infrastructure refers to a centralized computing architecture where desktop environments run on remote servers or data centers, with display protocols such as HDX, PCoIP, or RDP streaming pixel data to endpoint devices for local input rendering. The primary purpose is to decouple user workspace logic from physical hardware, enabling centralized security patching, data sovereignty compliance, and elastic workforce scaling across distributed geographies. Cloud-based deployment models capture the fastest expansion as telco edge infrastructure matures across São Paulo and Johannesburg, while on-premises configurations retain margin concentration in defense and intelligence verticals with strict air-gapping requirements. Small and medium enterprises represent an underpenetrated end-user tier where Desktop as a Service bundles lower capital barriers.
Brazil's LGPD enforcement through the ANPD and South Africa's POPIA framework are tightening data residency mandates that directly shape VDI architecture decisions across the region. ISO 27001 certification has become a de facto procurement filter for financial institutions selecting managed service providers in Mexico City and Lagos. Stakeholders must monitor how national data localization statutes fragment cross-border cloud orchestration strategies.
Market Dynamics
Data residency mandates across Brazil and South Africa are forcing architectural fragmentation as financial institutions redesign VDI stacks for jurisdictional compliance rather than operational efficiency.
Growth Catalysts
- POPIA encryption mandates:South Africa's Protection of Personal Information Act drives endpoint security upgrades across Gauteng financial services clusters.
- Healthcare mobility:Brazilian hospital networks deploy virtual desktops to untether clinicians from fixed workstations.
- Edge infrastructure maturation:Telco deployments in São Paulo and Johannesburg compress latency for cloud-based VDI workloads.
Market Restraints
- Bandwidth cost volatility:Enterprise-grade connectivity pricing fluctuates across Andean corridors, squeezing total cost of ownership for remote desktop deployments.
- Hardware import dependencies:African public-sector tenders face concentration risk from Asian server component suppliers.
- Air-gap requirements:Defense and intelligence verticals in the region maintain on-premises configurations that resist cloud migration economics.
Strategic Opportunities
- SME Desktop-as-a-Service:Small and medium enterprises across Mexico City represent an underpenetrated tier where bundled subscriptions lower capital barriers.
- Telemedicine protocol optimization:High-latency corridors in the Andes create demand for specialized display streaming technologies.
- LGPD compliance services:Brazil's ANPD enforcement timeline generates managed service opportunities around data localization architecture.
Industry Challenges
- ISO 27001 certification timelines:Financial institutions in Lagos and Mexico City face procurement delays as managed service providers navigate audit backlogs.
- Legacy endpoint integration:Hospital networks struggle to virtualize specialized medical imaging workstations with proprietary GPU dependencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Virtual Desktop Infrastructure Market |
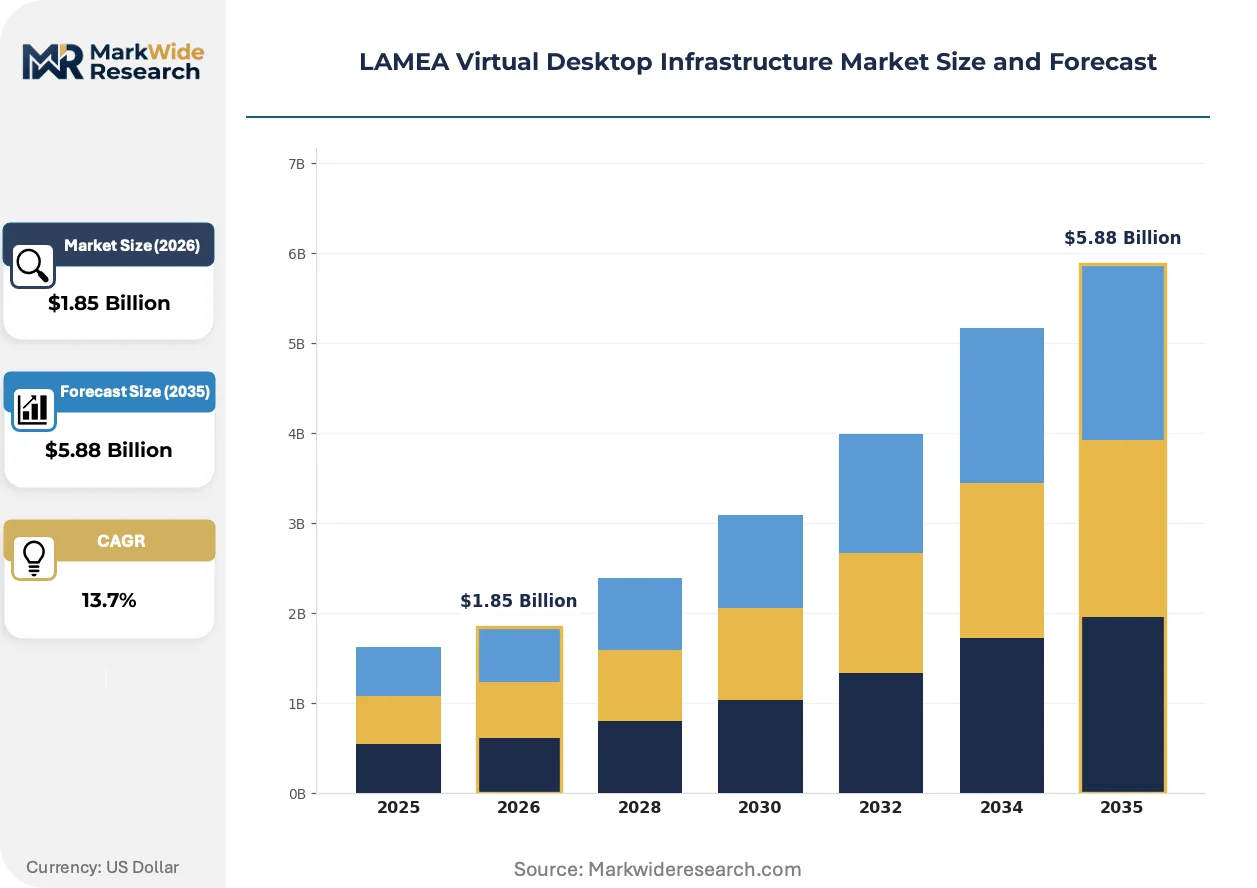
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Desktop as a Service End User: Small Enterprises, Medium Enterprises, Large Enterprises, Government Institutions Component: Software, Hardware, Services, Support Application: Remote Work, Training, Software Development, Data Processing |
| Companies Covered | VMware, Inc., Citrix Systems, Inc., Microsoft Corporation, Cisco Systems, Inc., Hewlett Packard Enterprise Company, IBM Corporation, Amazon Web Services, Inc., Huawei Technologies Co., Ltd., Red Hat, Inc., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Virtual Desktop Infrastructure Market Trends and Innovations
Virtual desktop architectures are splitting between cloud-native elasticity and hardened on-premises stacks as regulatory boundaries harden across the region.
GPU virtualization for medical imaging is unifying radiology workstation requirements with standard clinical desktops. Brazilian hospital networks are consolidating vendor relationships around single-stack solutions. This convergence is compressing the distinction between high-performance and general-purpose VDI tiers.
LGPD enforcement through Brazil's ANPD is mandating data residency certifications for cross-border cloud orchestration. Financial institutions in São Paulo are segmenting workloads across domestic and international availability zones. Trading floor deployments now require explicit jurisdictional tagging for every virtual machine instance.
Subscription-based procurement is displacing perpetual licensing across mid-market buyers in Johannesburg and Lagos. Channel partners are unbundling implementation services from recurring platform fees. Healthcare networks in South Africa show the fastest adoption velocity for consumption-based desktop pricing models.
LAMEA Virtual Desktop Infrastructure Market Segmentation
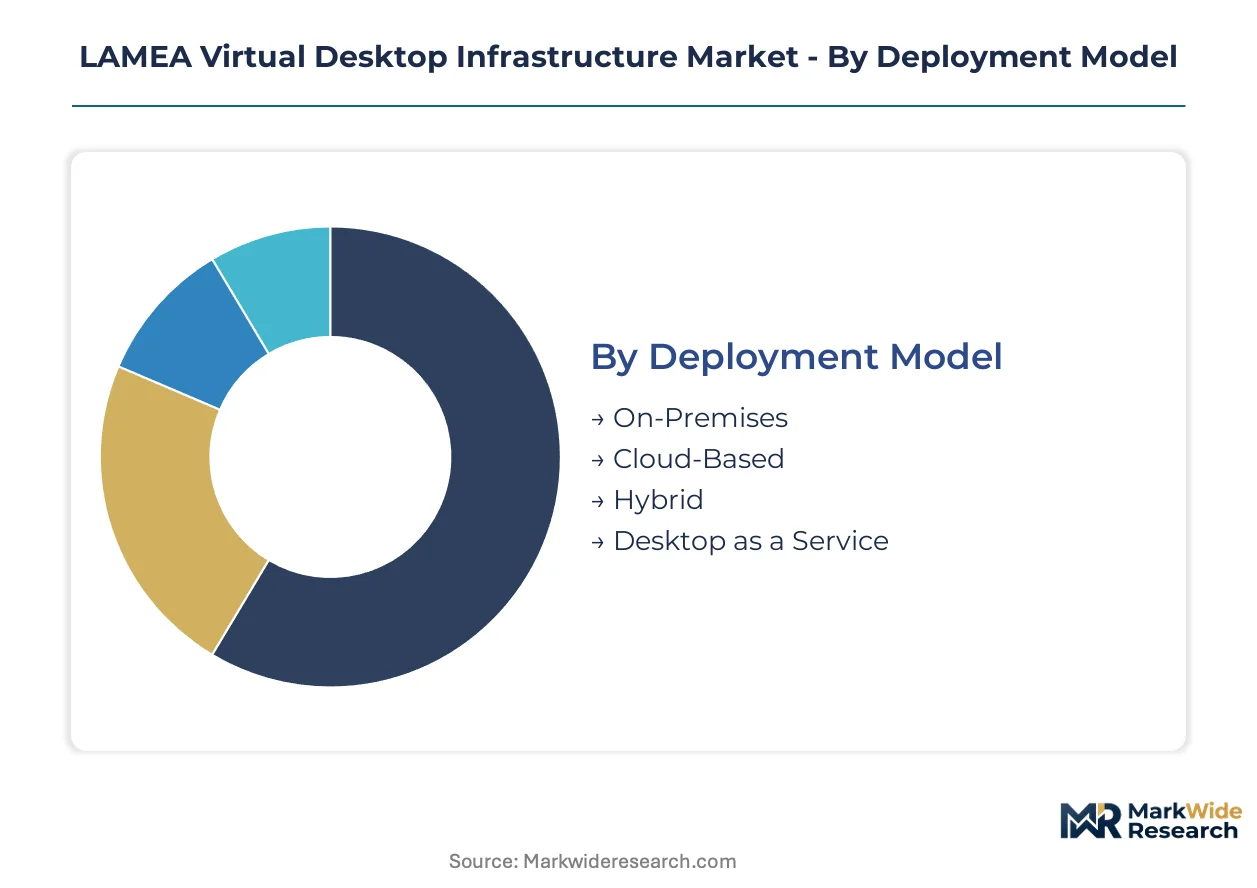
VDI procurement patterns across Latin America, Middle East, and Africa diverge sharply by deployment sophistication and compliance posture. Buyers in São Paulo financial districts prioritize cloud elasticity, while defense contractors in South Africa and Gulf states demand air-gapped control. Segmentation reveals where margin pools concentrate versus where volume expansion accelerates.
Deployment Model:
Cost tier separates buyers most cleanly in this category, with capital availability and risk tolerance driving architectural choice.
- Cloud-Based:Multi-tenant architectures stream pixel data from hyperscale availability zones to endpoint devices. Brazilian hospital networks in São Paulo and Minas Gerais anchor demand here, with LGPD compliance requirements forcing domestic data center selection.
- On-Premises:Dedicated server clusters within client facilities maintain complete data sovereignty and offline operation capability. South African defense and intelligence verticals in Pretoria and Cape Town sustain this tier, with POPIA encryption mandates layered onto physical access controls.
- Hybrid:Workload portability between private infrastructure and public cloud resources. Nigerian financial institutions in Lagos deploy this model for burst capacity during trading windows.
- Desktop as a Service:Fully managed subscription delivery eliminating capital expenditure. Mexican mid-market buyers in Mexico City and Monterrey represent the fastest uptake cohort.
On-Premises leads volumes today; Desktop as a Service is gaining share fastest.
End User:
Application criticality and regulatory exposure shape buyer behavior across enterprise tiers.
- Large Enterprises:Multi-thousand seat deployments with dedicated IT operations centers. South African banking groups in Johannesburg's Sandton district drive sophisticated VDI stacks with integrated endpoint detection and response.
- Government Institutions:Procurement through tender processes with strict localization and certification requirements. Brazilian federal agencies and UAE ministries concentrate demand here, with ANPD and NESA compliance frameworks respectively.
- Medium Enterprises:Departmental deployments of 100-500 seats with managed service overlays. Colombian logistics operators in Bogotá adopt this tier for distributed warehouse management.
- Small Enterprises:Sub-hundred seat implementations with heavy reliance on channel partner support. Kenyan agricultural cooperatives and Peruvian retail chains represent emerging demand pockets.
Government Institutions lead volumes today; Medium Enterprises are expanding most quickly.
Component:
Margin structure varies dramatically between recurring service revenue and one-time hardware capture.
- Software:Hypervisor licenses, connection brokers, and display protocol stacks. Citrix and VMware dominate this layer across Brazilian healthcare networks, with perpetual licensing giving way to subscription terms in Johannesburg.
- Services:Implementation, migration, and ongoing managed operations. South African systems integrators in Gauteng province capture the highest attach rates here, with ISO 27001-certified delivery teams commanding premium pricing.
- Hardware:Server infrastructure, thin clients, and zero endpoints. Huawei and Dell EMC compete aggressively in African public-sector tenders, with price-performance bundling decisive in Nairobi and Lagos evaluations.
- Support:Break-fix, patch management, and tiered helpdesk operations. Mexican channel partners unbundle this from platform fees to improve renewal economics.
Software leads volumes today; Services show the steepest expansion trajectory.
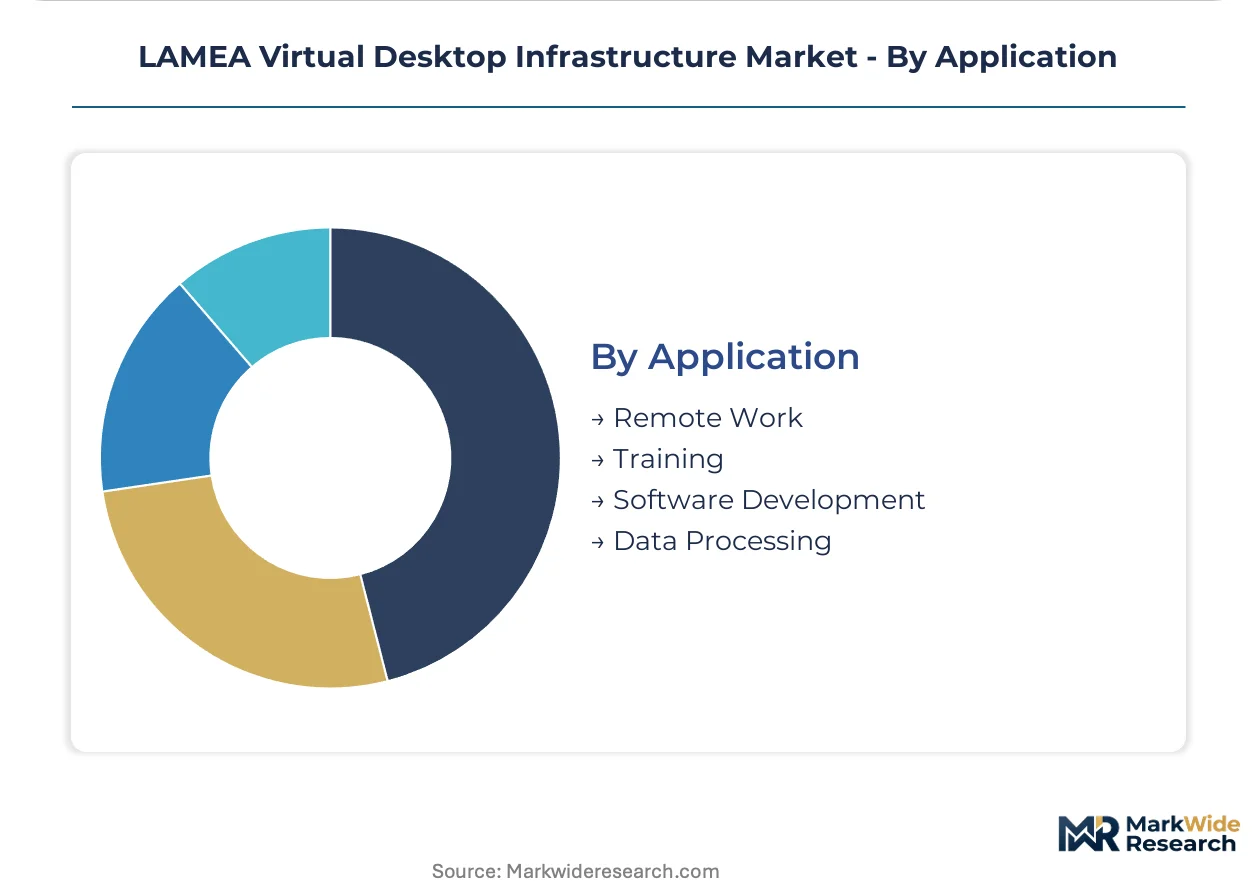
Application:
Workload characteristics determine latency tolerance, GPU requirements, and security segmentation needs.
- Remote Work:General productivity desktop delivery for distributed employees. Brazilian financial services firms in São Paulo's Faria Lima corridor scaled this dramatically post-LGPD enforcement, with explicit jurisdictional tagging per virtual machine.
- Software Development:Containerized build environments with elevated privilege requirements. Israeli and UAE technology subsidiaries across the Middle East concentrate demand, with source code residency mandates shaping architecture.
- Data Processing:Batch analytics and back-office operations with relaxed latency constraints. South African insurance processors in Cape Town optimize cost per seat here.
- Training:Non-persistent desktop pools for temporary skill development. Saudi vocational institutes and Colombian corporate academies deploy this model with heavy session concurrency.
Remote Work leads volumes today; Software Development is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping VDI deployment patterns across Latin America, Middle East, and Africa as compliance cost differentials between jurisdictions drive architectural decisions. Financial institutions migrate workloads toward data centers in jurisdictions with clearer localization statutes, while healthcare networks prioritize proximity to edge infrastructure over pure cost optimization.
Brazil
ANPD enforcement of LGPD mandates is segmenting cloud workloads across domestic and international availability zones. São Paulo's Faria Lima financial corridor anchors the largest concentration of trading-floor VDI deployments with explicit jurisdictional tagging per virtual machine. Hospital networks in Minas Gerais are consolidating vendor relationships around single-stack solutions that unify radiology workstations with standard clinical desktops.
South Africa
POPIA encryption requirements are accelerating endpoint security upgrades across Gauteng's Sandton banking district. The Protection of Personal Information Act drives procurement decisions that favor ISO 27001-certified managed service providers with domestic delivery teams. Defense and intelligence verticals in Pretoria sustain on-premises configurations with strict air-gapping requirements that resist cloud migration economics.
Mexico
Mid-market buyers in Mexico City and Monterrey are displacing perpetual licensing with subscription-based Desktop as a Service procurement. Channel partners are unbundling implementation services from recurring platform fees to improve renewal economics. Logistics operators in Bogotá—serving cross-border supply chains—adopt departmental VDI deployments for distributed warehouse management.
United Arab Emirates
NESA compliance frameworks are shaping government procurement through tender processes with strict localization requirements. Dubai-based technology subsidiaries concentrate demand for containerized development environments with source code residency mandates. Telco edge infrastructure maturation across Abu Dhabi is compressing latency for cloud-based VDI workloads in financial services.
Nigeria
Financial institutions in Lagos deploy hybrid architectures that burst capacity to public cloud during trading windows while maintaining core systems on private infrastructure. ISO 27001 certification timelines are creating procurement delays as managed service providers navigate audit backlogs. Systems integrators with certified delivery teams command premium pricing for implementation and ongoing operations.
LAMEA Virtual Desktop Infrastructure Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers capturing cloud-based deployments while legacy virtualization vendors retain on-premises strongholds. The vendor base concentrates around three strategic archetypes: hyperscale platforms with integrated infrastructure stacks, specialized protocol optimizers for high-latency corridors, and price-performance hardware bundlers for public-sector tenders. Dominant competitive moves include strategic partnerships between software vendors and regional systems integrators, plus geographic expansion through certified delivery team investments in Johannesburg and São Paulo.
Within the hyperscale platform tier, Microsoft Corporation and Amazon Web Services, Inc. anchor cloud-native VDI offerings across Brazilian and South African financial services clusters. Citrix Systems, Inc. exemplifies the protocol optimization archetype with specialized display streaming technologies for telemedicine use cases. Huawei Technologies Co., Ltd. occupies the price-performance position in African public-sector tenders, competing on hardware bundling economics in Nairobi and Lagos evaluations.
| Leading Market Players |
|---|
| VMware, Inc. |
| Citrix Systems, Inc. |
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Hewlett Packard Enterprise Company |
| IBM Corporation |
| Amazon Web Services, Inc. |
| Huawei Technologies Co., Ltd. |
| Red Hat, Inc. |
| Others |
Pricing and Supply Chain Analysis
LGPD-mandated data residency certifications are forcing Brazilian financial institutions to segment procurement across domestic and international availability zones, compelling hyperscale providers to establish local data center presence and compressing margins on cross-border orchestration services. This buyer-driven fragmentation is reshaping how vendors price cloud-based VDI stacks versus on-premises alternatives.
Pricing Analysis
Distributor margins for channel-delivered VDI implementations run 15-25 points above direct hyperscale procurement, with South African systems integrators in Gauteng commanding premium attach rates for ISO 27001-certified deployment teams. Subscription-based SaaS tiers are displacing perpetual licensing across Johannesburg and Lagos mid-markets, with pricing stratifying across enterprise-grade compliance bundles, standard departmental deployments, and economy-tier SMB offerings. Cost compression in the hardware layer stems from Asian server component competition, while managed service premiums expand. Small enterprises in Kenya and Peru exhibit highest price sensitivity; defense contractors in Pretoria show lowest.
Supply Chain Analysis
Specialized engineering talent shortages in São Paulo and Johannesburg are constraining implementation capacity for complex hybrid deployments, pushing vendors to train domestic delivery teams or absorb travel costs. Server hardware concentrates in China, Taiwan, and South Korea, with GPU components for medical imaging workloads drawing from NVIDIA and AMD supply allocations. Memory and storage components hinge on Korean and Japanese manufacturers. Single-source vulnerability runs through ASIC-based display protocol processors. Distribution runs through regional systems integrators with certified delivery capabilities in Lagos, Nairobi, and Mexico City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LAMEA VDI market functions as a regulatory compounder, with Brazil's ANPD enforcement timeline accelerating demand for jurisdictional workload segmentation and domestic data center investment.
For Market Incumbents: Lock in certification moats by deepening ISO 27001 audit capabilities across Johannesburg and São Paulo delivery teams before compliance backlogs clear. Acquire regional systems integrators with existing ANPD and POPIA consulting practices to preempt emerging pure-play compliance vendors from capturing managed service attach rates in financial services clusters. For New Entrants and Emerging Players: Cloud-native DaaS marketplaces represent the most penetrable entry vector, with Mexican mid-market buyers in Mexico City and Monterrey underserved by incumbent perpetual-license incumbents. Target departmental deployments of 100-500 seats in Colombian logistics and Peruvian retail chains with consumption-based pricing and unbundled implementation services to bypass capital barrier friction. For Investors and Strategic Acquirers: Asymmetric upside sits with protocol optimization specialists possessing high-latency corridor expertise for Andean telemedicine use cases, as edge infrastructure maturation compresses addressable market timelines for generic cloud VDI. Watch for LGPD enforcement consistency as inflection signal—accelerated ANPD penalties would trigger enterprise procurement urgency and expand services attach rates.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Center Certification | ANPD-compliant availability zones in São Paulo capture LGPD-mandated financial services workloads. |
| Protocol Optimization R&D | Specialized display streaming for high-latency Andean corridors differentiates telemedicine offerings. |
| ISO 27001 Delivery Team Investment | Certified implementation capacity in Gauteng commands premium pricing from POPIA-affected buyers. |
| Channel Partner Unbundling | Separating platform fees from professional services improves renewal economics in Mexican mid-market. |
| GPU Virtualization Integration | Unified radiology-clinical desktop stacks consolidate vendor relationships in Brazilian hospital networks. |
Research Methodology
Coverage spans Latin America, Middle East, and Africa, with primary inputs from each region combining structured interviews with IT procurement officers, platform engineers at hyperscale providers, channel partners, and healthcare technology directors with secondary validation. Sources include SEC filings from listed virtualization vendors, hyperscaler capex disclosures, ANPD enforcement bulletins, and hospital procurement databases. Bottom-up seat-count modeling triangulates against top-down market sizing from infrastructure spend tracking.
Rate-of-change decomposition separates volume expansion from value-per-seat evolution across the projection horizon, with segmentation dimensions covering deployment model, end-user tier, component type, and application workload. CAGRs derive from fitted growth curves applied to base-year sizing, with cross-checks against telco edge infrastructure deployment timelines in São Paulo and Johannesburg and regulatory enforcement calendars from Brazil's ANPD and South Africa's Information Regulator.
The model assumes a particular technology adoption path; alternative pathways for browser-based remote desktop protocols would alter the outlook if latency compression outpaces native client optimization. Forecasts reflect assumptions around POPIA and LGPD enforcement consistency, with material deviation in regulatory penalty timelines or data localization statute expansion warranting pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Asia-Pacific Hyperscale Data Center Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
Global Telecommunication Equipment Cabinet and Racks Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Germany Data Center Rack Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
Global Datacenter Deployment Spending Market
Data Center Infrastructure
Philippines Data Center Rack Market