
 Denmark Data Center Market | 2026-2036
Denmark Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Data Center Market Insights
Hyperscale cloud architecture is reshaping how data center capacity is provisioned across Denmark. Meta anchors its Nordic operations with large-scale campus developments near Odense, leveraging direct access to offshore wind interconnects. Apple sustains its carbon-neutral facility commitments through vertical integration into on-site renewable generation. Digital Realty competes by extending its Interxion-branded colocation footprint across Copenhagen's fiber-dense corridors.
A data center constitutes a purpose-built facility housing servers, storage systems, and networking equipment within controlled environments typically maintaining temperatures between 18°C and 27°C and humidity levels of 40-60% relative humidity, designed to ensure continuous availability of digital services for enterprises and consumers. Colocation services dominate revenue generation as enterprises divest owned infrastructure, while edge computing deployments represent the fastest-expanding technology segment driven by latency-sensitive applications in autonomous systems and industrial IoT. Cloud services command the largest margin pools among service types due to multi-tenant economics and software-layer value capture.
The Danish Energy Agency enforces stringent power usage effectiveness thresholds for new data center construction permits, while the Danish Business Authority applies EU CSRD sustainability disclosure rules to facility operators above reporting thresholds. These frameworks channel investment toward liquid cooling retrofits and waste heat recovery integrations with municipal district heating networks. Stakeholders must weigh the trade-off between Esbjerg's submarine cable landing advantages and Copenhagen's enterprise demand density when siting new capacity.
Market Dynamics
Hyperscale facility deployment in Denmark is compressing traditional colocation economics through direct renewable energy procurement and liquid cooling integration at scale.
Growth Catalysts
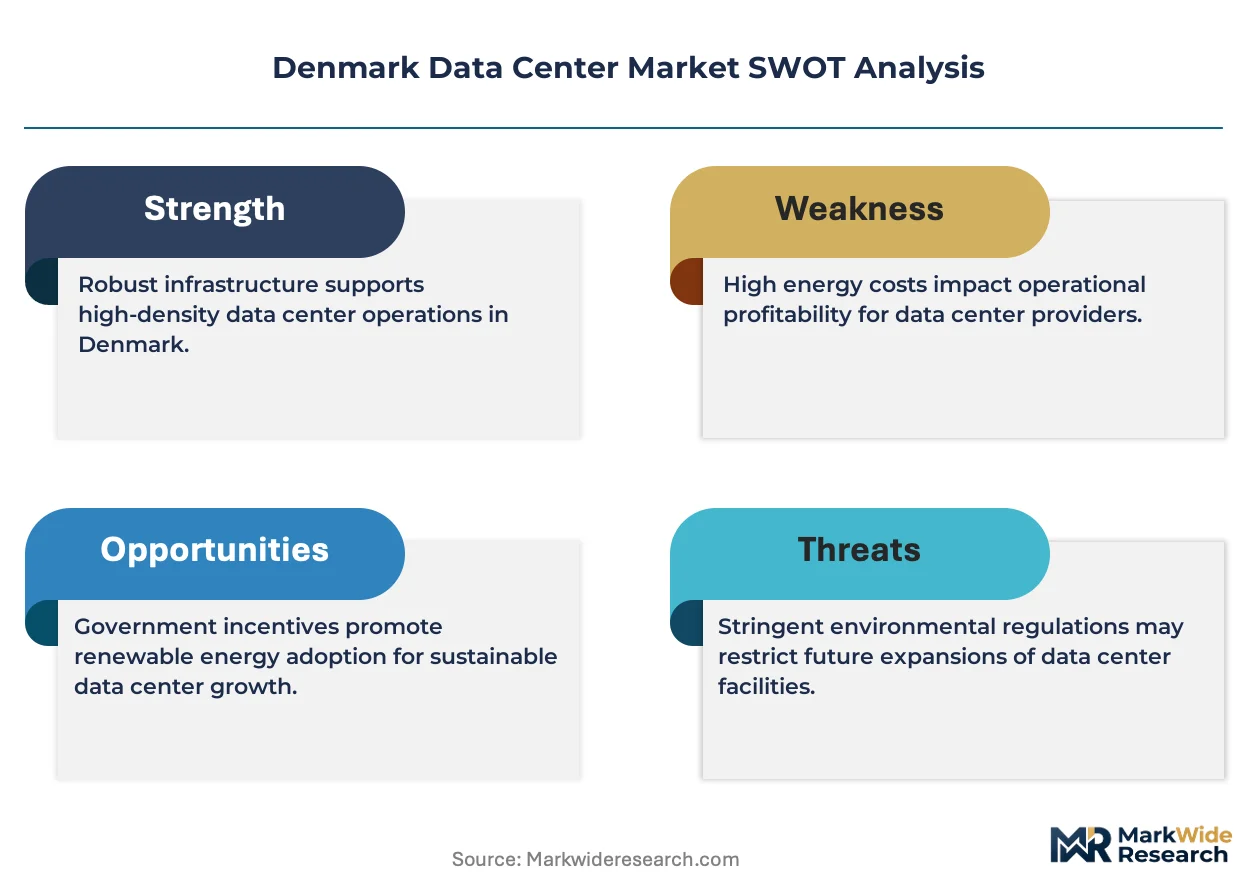
- EU CSRD sustainability disclosure rules:The Danish Business Authority applies these mandates to facility operators above reporting thresholds, accelerating capital flows into certified green construction.
- Submarine cable landing zones:Esbjerg's North Sea interconnects to continental Europe position the city as a natural traffic aggregation point for transcontinental data flows.
- Waste heat recovery systems:Municipal district heating networks in Odense and Copenhagen now contract with facilities for baseload thermal supply, improving project IRRs.
Market Restraints
- Land scarcity in Copenhagen metropolitan zone:Zoning restrictions and competing real estate uses constrain greenfield campus expansion for facilities above 50MW capacity.
- Grid interconnection queues:Energinet's transmission upgrade timelines delay power delivery to Esbjerg developments by 18-36 months beyond construction completion.
- Skilled construction labor pools:Specialized mechanical and electrical trades for liquid cooling infrastructure concentrate in Aarhus and Copenhagen, creating wage pressure.
Strategic Opportunities
- Edge computing nodes in Jutland industrial corridors:Manufacturing automation and autonomous logistics create sub-10ms latency requirements underserved by centralized hyperscale campuses.
- Danish Energy Agency efficiency permit thresholds:Stricter PUE requirements for new construction create first-mover advantage for operators with proprietary cooling IP.
- Carbon capture integration:Emerging direct air capture deployments adjacent to data centers enable shared infrastructure and negative emissions accounting.
Industry Challenges
- Legacy mechanical cooling retrofits:Existing Copenhagen colocation facilities face stranded asset risk as tenant contracts demand liquid-cooled density.
- Cross-border data sovereignty compliance:Operators serving EU and non-EU clients simultaneously must architect network segmentation satisfying GDPR and foreign access statutes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Data Center Market |
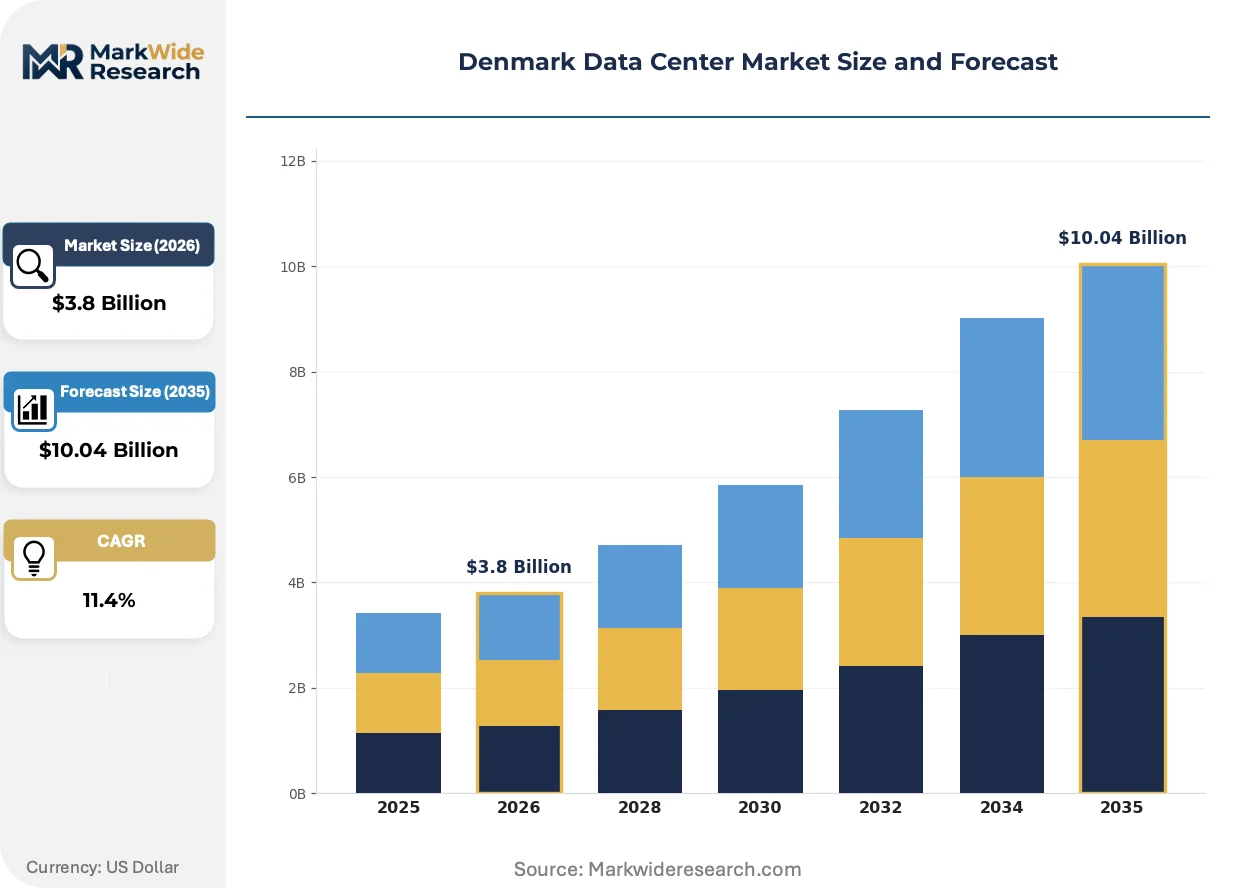
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Hosting, Cloud Services, Dedicated Servers Technology: Virtualization, Hyperconverged Infrastructure, Edge Computing, Big Data Analytics End User: Retail, Telecommunications, Finance, Healthcare Infrastructure: Cooling Systems, Power Supply, Security Solutions, Network Infrastructure |
| Companies Covered | Digital Realty, Apple, Meta, Equinix, Schneider Electric, Vertiv Group, ABB, AtlasEdge, Telia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Data Center Market Trends and Innovations
Liquid cooling architectures and AI-optimized thermal management are restructuring facility design standards across Danish deployment zones. These shifts compress legacy infrastructure valuations while opening new service layers around heat export and carbon accounting.
Immersion cooling systems are collapsing the physical footprint required for high-density GPU clusters. Hyperscale operators in Odense are adopting single-phase dielectric fluid baths for AI training workloads, cutting facility square meterage per megawatt by 40 percent. This density compression enables campus expansion on constrained plots without grid interconnection delays.
The EU F-Gas Regulation phase-down is accelerating refrigerant transition timelines for Danish mechanical cooling fleets. Operators must retrofit or replace vapor compression systems using hydrofluorocarbons before 2030, redirecting maintenance capex toward natural refrigerant or liquid alternatives. Colocation providers with older Copenhagen assets face accelerated depreciation schedules.
Enterprise procurement of data center capacity is fragmenting across multi-cloud and sovereign hosting requirements. Financial services and public sector buyers in Denmark now split workloads between hyperscale cloud, national cloud, and on-premises edge, unbundling the monolithic colocation contracts that dominated prior decades. This pattern concentrates in Copenhagen's enterprise corridor and Odense's fintech cluster.
Denmark Data Center Market Segmentation
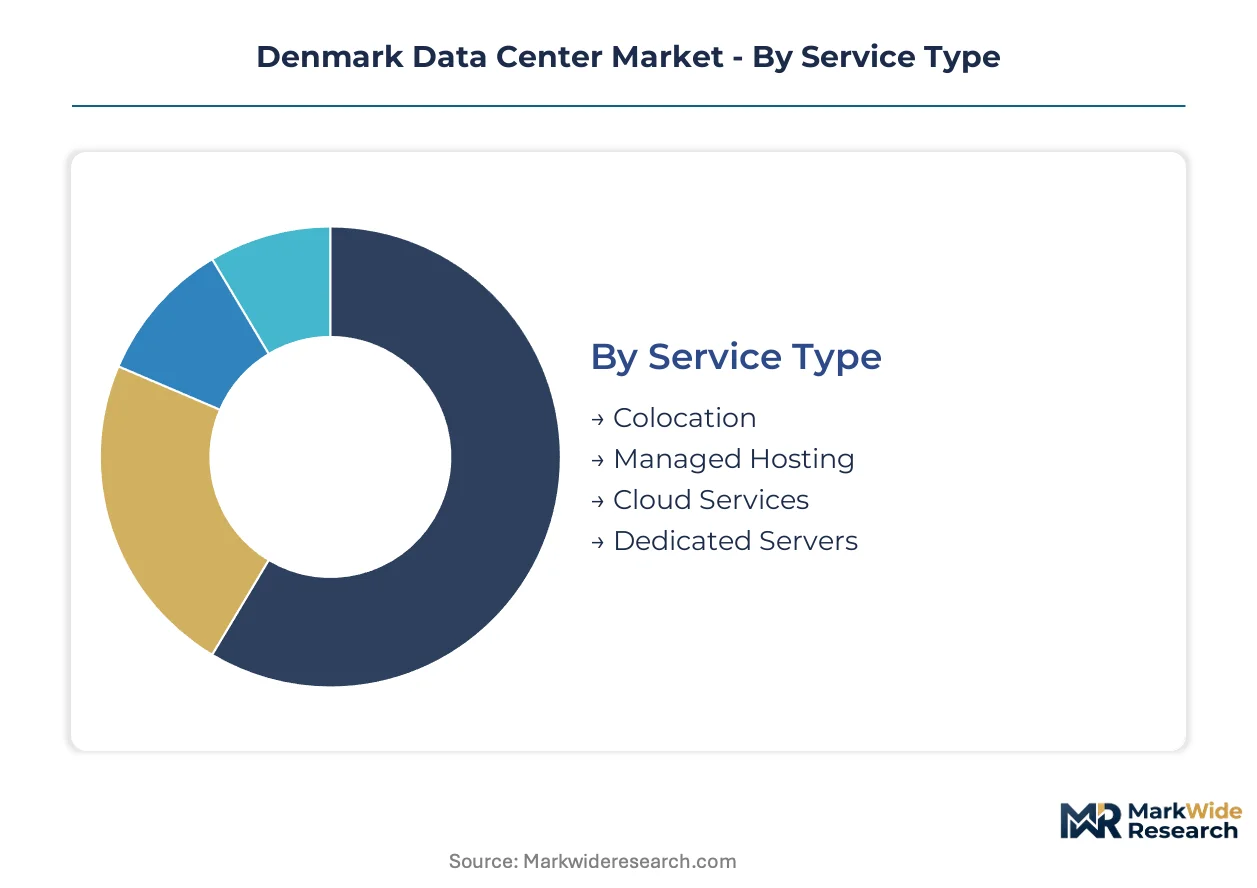
Segmentation reveals how Danish data center operators align capabilities with divergent client risk profiles and workload densities. Each dimension exposes distinct margin structures and capital intensity requirements across the market.
Service Type:
Cost tiers separate operational responsibility models, with higher-touch services commanding premium pricing for compliance-sensitive workloads.
- Colocation:Physical space leasing with power, cooling, and cross-connect provisioning. Copenhagen's enterprise corridor drives demand as financial services firms divest owned facilities to meet Danish Energy Agency efficiency mandates.
- Managed Hosting:Hardware ownership plus operational management including patching, monitoring, and backup. Healthcare providers in the capital region concentrate procurement here due to strict patient data sovereignty requirements under GDPR.
- Cloud Services:Multi-tenant compute and storage with API-driven provisioning. Hyperscale campuses near Odense anchor Nordic cloud expansion through direct offshore wind interconnects.
- Dedicated Servers:Single-tenant bare metal with customized network segmentation. Telecommunications operators deploy these for latency-sensitive 5G core network functions.
Colocation holds installed capacity. Cloud Services is rotating up the share rankings.
Technology:
Application workloads dictate infrastructure architecture choices, with latency requirements and data gravity determining deployment patterns.
- Virtualization:Abstracted compute resources enabling server consolidation and workload mobility. Legacy Copenhagen colocation facilities rely heavily on VMware and KVM stacks to extend asset lifecycles amid liquid cooling retrofits.
- Hyperconverged Infrastructure:Integrated compute, storage, and networking in scale-out clusters. Mid-market enterprises in Aarhus favor HCI for simplified operations without specialized infrastructure teams.
- Edge Computing:Distributed processing nodes positioned proximal to data sources. Manufacturing automation in Jutland industrial corridors generates sub-10ms latency requirements that centralized hyperscale campuses cannot satisfy.
- Big Data Analytics:Distributed processing frameworks for large-scale dataset manipulation. Fintech clusters in Odense drive GPU-accelerated analytics deployments for real-time risk modeling.
Virtualization dominates current deployments. Edge Computing is climbing the fastest as industrial IoT accelerates.
End User:
Customer type segmentation maps regulatory exposure and uptime requirements against facility certification tiers.
- Retail:E-commerce platforms and omnichannel fulfillment systems. Seasonal demand spikes around holiday periods drive elastic cloud procurement patterns.
- Telecommunications:Network function virtualization and subscriber data management. 5G rollout timelines concentrate investment in edge nodes with sub-5ms latency to base stations.
- Finance:Trading infrastructure, risk systems, and customer banking platforms. Danish Financial Supervisory Authority guidelines mandate geographic redundancy for critical payment systems.
- Healthcare:Electronic health records, medical imaging archives, and telemedicine platforms. Patient data localization requirements under GDPR block cross-border cloud deployment for primary systems.
Finance commands premium pricing tiers. Healthcare is gaining share fastest on digitalization mandates.
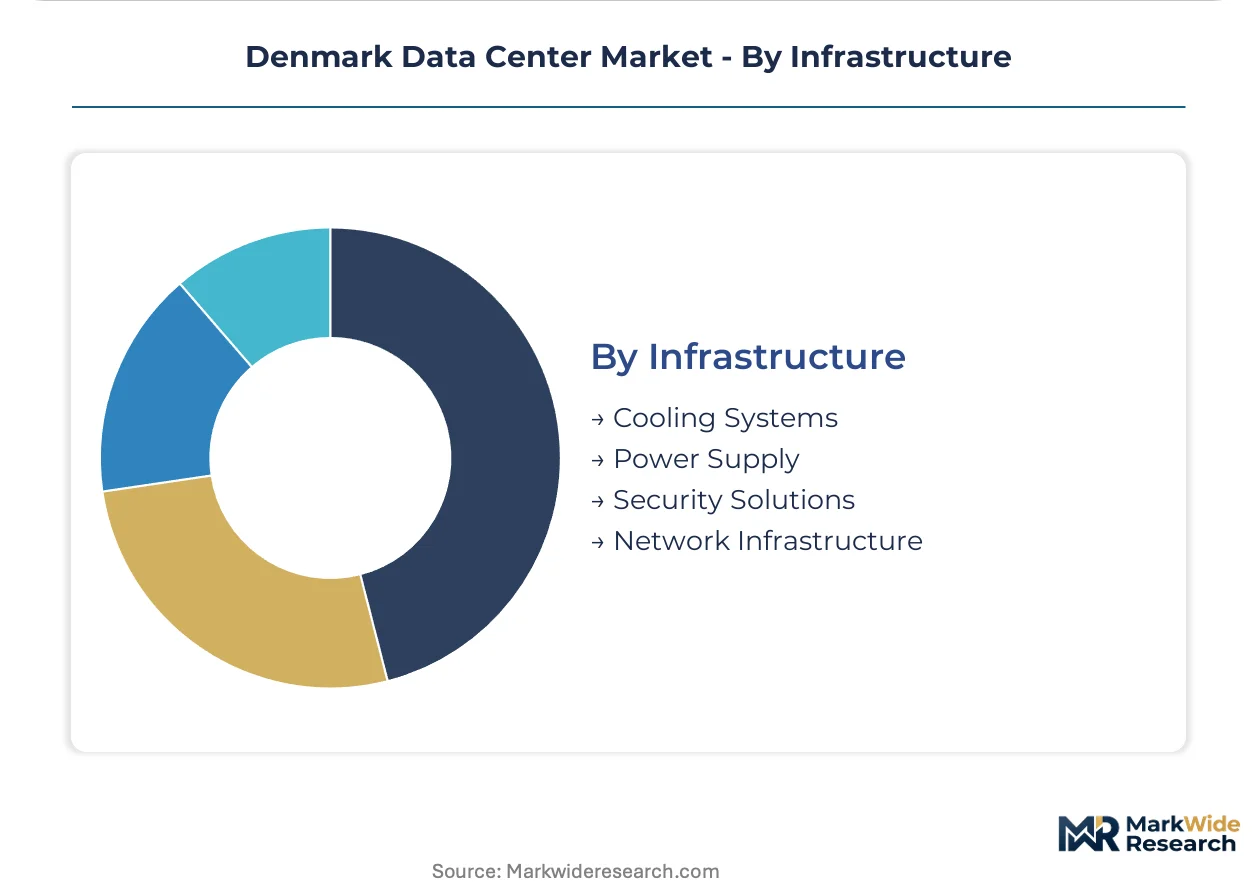
Infrastructure:
Supply concentration varies by subsystem, with specialized mechanical and electrical trades creating geographic bottlenecks.
- Cooling Systems:Thermal management encompassing mechanical refrigeration, liquid cooling, and heat rejection. Single-phase immersion deployments in Odense compress facility footprints by forty percent for AI training clusters.
- Power Supply:Uninterruptible power systems, switchgear, and medium-voltage distribution. Grid interconnection queues through Energinet delay Esbjerg campus energization by eighteen to thirty-six months.
- Security Solutions:Physical access control, video surveillance, and cybersecurity frameworks. EU NIS2 directives tighten incident reporting obligations for operators of essential services.
- Network Infrastructure:Fiber cross-connects, internet exchanges, and submarine cable landings. Esbjerg's North Sea interconnects position the city as a natural aggregation point for transcontinental traffic.
Power Supply absorbs the largest capital allocation. Cooling Systems is rotating up the share rankings on liquid cooling retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's data center sector operates as a net capacity exporter, with submarine cable interconnects positioning the country as a Nordic-European traffic exchange node rather than a domestic consumption market. Cross-border power trading through Energinet's interconnectors to Germany, Norway, and Sweden enables renewable energy arbitrage that underpins facility economics.
Capital Region
Copenhagen's enterprise density concentrates colocation demand from financial services and public sector buyers. The Danish Business Authority applies EU CSRD disclosure mandates to facility operators above reporting thresholds, channeling investment toward certified green construction. Fiber-dense corridors in Ørestad and Nordhavn anchor Digital Realty's Interxion-branded expansion.
Southern Denmark
Odense anchors Meta's Nordic hyperscale campus through direct offshore wind interconnect access. The Danish Energy Agency enforces power usage effectiveness thresholds for new construction permits, favoring operators with liquid cooling intellectual property. Apple's carbon-neutral facility commitments drive vertical integration into on-site renewable generation.
Region of Southern Denmark
Esbjerg's North Sea submarine cable landings position the city as a transcontinental traffic aggregation point. Grid interconnection queues through Energinet delay campus energization by eighteen to thirty-six months beyond construction completion. Municipal district heating networks contract with facilities for baseload thermal supply, improving project returns.
Central Denmark Region
Aarhus concentrates specialized mechanical and electrical trades for liquid cooling infrastructure, creating wage pressure across the construction labor pool. Mid-market enterprises favor hyperconverged infrastructure deployments to simplify operations without dedicated infrastructure teams. Manufacturing automation in Jutland industrial corridors generates sub-ten-millisecond latency requirements for edge computing nodes.
Denmark Data Center Market Competitive Landscape
On the supply side, the industry is bifurcated between hyperscale cloud operators building captive capacity and third-party colocation providers serving enterprise divestment demand. Two strategic archetypes dominate: vertically integrated technology giants controlling renewable energy procurement and cooling IP, and carrier-neutral platform operators aggregating network interconnection density. Competitive moves concentrate on liquid cooling retrofit partnerships and waste heat recovery integrations with municipal utilities.
Among hyperscale operators, Meta and Apple occupy positions exemplifying direct renewable energy procurement at scale, while Digital Realty anchors the colocation tier through Interxion-branded platform expansion. These three entities represent the dominant competitive vectors shaping facility economics and sustainability certification standards across Danish deployment zones.
| Leading Market Players |
|---|
| Digital Realty |
| Apple |
| Meta |
| Equinix |
| Schneider Electric |
| Vertiv Group |
| ABB |
| AtlasEdge |
| Telia |
| Others |
Pricing and Supply Chain Analysis
Esbjerg's North Sea freight corridors channel equipment import costs through Hamburg and Rotterdam gateways, concentrating supply-side leverage among Nordic distributors while compressing margin pools for Copenhagen-based colocation operators serving price-sensitive mid-market enterprises.
Pricing Analysis
Liquid-cooled hyperscale facilities command forty percent premiums over legacy air-cooled Copenhagen colocation, while next-generation immersion deployments for AI training clusters price at standard-tier multiples. Three-tier pricing structure across premium certification, standard compliance, and economy utility tiers separates PUE-certified greenfield campuses from stranded mechanical-cooling assets. Cost compression in economy tiers intensifies as Meta and Apple internalize renewable procurement, eroding third-party margin capture. Healthcare and financial services buyers exhibit lowest price sensitivity due to GDPR-mandated data sovereignty requirements, while retail e-commerce platforms drive elastic procurement patterns.
Supply Chain Analysis
Tariff exposure between Germany and Denmark dominates switchgear and medium-voltage transformer procurement, with lead times extending through Hamburg port congestion. Supply concentrates in Germany for precision cooling components, China for server and storage hardware, and Denmark for specialized mechanical and electrical construction trades. Raw material dependencies span copper for busbar distribution, lithium for battery-backed UPS systems, and fluorinated gases facing EU F-Gas Regulation phase-down restrictions. Single-source vulnerability concentrates in single-phase dielectric fluid formulations for immersion cooling. Distribution runs through carrier-neutral interconnection platforms and direct hyperscale procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise procurement consolidation among Danish financial services and healthcare buyers has shifted negotiating leverage toward volume-commitment contracts, fragmenting the colocation customer base into hyperscale-direct and platform-aggregator archetypes.
For Market Incumbents: Build renewable energy procurement moats through long-term power purchase agreements with Energinet-interconnected offshore wind developers. Digital Realty and Equinix must defend Copenhagen fiber-dense positions against Meta's captive campus expansion by securing district heating integration contracts with HOFOR and Odense Forsyning. Liquid cooling intellectual property investments represent the critical lever against stranded asset risk from Danish Energy Agency efficiency permit thresholds. For New Entrants and Emerging Players: Pursue edge computing node deployment in Jutland industrial corridors where sub-ten-millisecond latency requirements exceed hyperscale campus reach. Manufacturing automation and autonomous logistics in Aarhus and Randers present the most penetrable white-space. AtlasEdge and regional specialists should anchor go-to-market through direct equipment manufacturer partnerships rather than carrier-neutral interconnection. For Investors and Strategic Acquirers: District heating-integrated facility operators with established waste heat recovery contracts offer the most defensible acquisition profile. Long-term viability hinges on renewable energy arbitrage capabilities across Energinet's cross-border interconnectors. The signal to monitor is Danish Energy Agency PUE threshold acceleration, which would compress valuations for mechanical-cooling-dependent assets. Continuous validation against operating reality is the recommended discipline.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Retrofit Partnership | Schneider Electric and Vertiv capture PUE compliance premiums from Copenhagen legacy facilities facing Danish Energy Agency mandates. |
| Waste Heat Recovery Integration | Meta's Odense campus contracts with municipal district heating networks, improving project IRRs through baseload thermal supply. |
| Submarine Cable Landing Expansion | Esbjerg's North Sea interconnect positioning attracts transcontinental traffic aggregation, delaying campus energization through grid queues. |
| Renewable Energy Procurement | Apple's vertical integration into on-site generation secures carbon-neutral commitments independent of Energinet trading. |
| Edge Computing Node Deployment | Telia targets Jutland manufacturing corridors with sub-five-millisecond latency for 5G network function virtualization. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center development executives, facility operations directors, municipal utility planning officers, and hyperscale cloud procurement leads; and secondary validation through Energinet transmission planning documents, Danish Energy Agency permit filings, EU CSRD sustainability disclosures, submarine cable landing zone registries, and district heating network integration contracts. Bottom-up capacity aggregation across Odense, Esbjerg, Copenhagen, and Aarhus deployment zones triangulated against top-down hyperscale capex tracking.
Forecast inputs incorporated power usage effectiveness trajectory modeling, renewable energy interconnect availability, liquid cooling adoption curves across virtualization and edge computing segments, and municipal heat export contract penetration. Segmentation dimensions spanned service type, infrastructure technology, end-user vertical, and regional grid interconnection status. CAGRs derived from facility pipeline tracking and operator disclosed expansion timelines. Industry-specific inputs included Energinet queue duration distributions and Danish Business Authority CSRD reporting threshold applications.
The forecast holds incumbent behavior within observed patterns; aggressive renewable procurement acceleration by Meta or Apple would shift competitive dynamics and margin compression timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Advanced Data Center Infrastructure Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
South Africa Data Center Power Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
Middle East Data Center Rack Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
New York Data Center Market
Data Center Infrastructure
New Jersey Data Center Market
Data Center Infrastructure
APAC Data Center Server Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
Norway Data Center Power Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Data Center Rack Market