
 Data Center Fabric Market | 2026-2036
Data Center Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Fabric Market Intelligence
Buyer concentration among cloud providers is pivoting as hyperscalers consolidate procurement while edge computing fragments demand across distributed enterprises. Arista Networks dominates high-density Ethernet switching for AI clusters. Cisco Systems leverages its installed base to anchor enterprise hybrid deployments. Huawei Technologies competes aggressively in Asia-Pacific markets through vertically integrated optical and switch portfolios.
Data center fabric denotes the integrated network architecture connecting servers, storage, and services within and across facilities, typically operating at 100 Gbps to 800 Gbps port speeds with sub-microsecond latency targets. Its primary purpose is enabling scalable east-west traffic flows essential for distributed computing and real-time analytics workloads. Ethernet technology leads volume shipments for general-purpose cloud fabrics, while InfiniBand commands premium positioning in AI training environments where lossless transport matters. Edge computing deployments represent the fastest-growing deployment segment as latency-sensitive applications push processing closer to endpoints.
FCC spectrum and equipment authorization rules shape US market access for wireless fabric extensions, while EU CSRD disclosure requirements force European operators to document energy efficiency across network infrastructure. ISO 27001 and IEC 62443 standards increasingly filter procurement decisions for financial and critical infrastructure buyers. Stakeholders must monitor how AI workload density reshapes port speed roadmaps and power envelope constraints before committing to multi-year fabric refresh cycles.
Market Dynamics
Hyperscale cloud providers are consolidating procurement power while simultaneously fragmenting demand through distributed edge deployments, creating a bifurcated supply chain where high-volume AI cluster contracts coexist with low-volume, high-customization enterprise orders.
Growth Catalysts
- EU AI Act:The regulation mandates certified, energy-transparent infrastructure for high-risk AI systems, forcing European operators toward audited fabric architectures that vendors can certify.
- AI training clusters:Cloud providers are expanding fabric deployments to support GPU-intensive workloads, driving demand for lossless transport at 400 Gbps and 800 Gbps port speeds.
- Northern Virginia concentration:Hyperscale campuses in Ashburn and Loudoun County are procuring switches and cables at unprecedented scale, anchoring North American demand.
Market Restraints
- Optical component concentration:Supply of coherent DSPs and high-speed transceivers concentrates among a handful of Asian suppliers, creating vulnerability to export controls or logistics disruption.
- Power envelope constraints:800 Gbps switch silicon pushes thermal design power beyond 500 watts per device, limiting deployment density in legacy facilities without mechanical cooling upgrades.
- InfiniBand switching costs:Premium pricing for lossless fabrics in AI training environments creates a cost barrier for mid-tier cloud providers and enterprise adopters.
Strategic Opportunities
- Phoenix metro expansion:New hyperscale campuses in Arizona offer greenfield deployment opportunities for liquid-cooled fabric architectures unconstrained by legacy infrastructure.
- Edge computing nodes:Latency-sensitive applications in manufacturing and autonomous systems are creating demand for micro-fabrics operating at 25 Gbps to 100 Gbps in distributed locations.
- CSRD disclosure alignment:European operators subject to Corporate Sustainability Reporting Directive requirements are seeking fabric vendors with documented Scope 3 emissions and energy efficiency metrics.
Industry Challenges
- Optical engineering talent scarcity:Design of 112 Gbps PAM4 SerDes and co-packaged optics requires specialized signal integrity expertise that outpaces university pipeline output.
- Multi-vendor interoperability certification:Enterprise buyers demand validated configurations across switch, cable, and NIC suppliers, extending sales cycles and pre-deployment testing burdens.
- Retrofit complexity:Facilities built for 10 Gbps to 40 Gbps eras face fiber plant and physical layer constraints when upgrading to 400 Gbps without full rebuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Fabric Market |
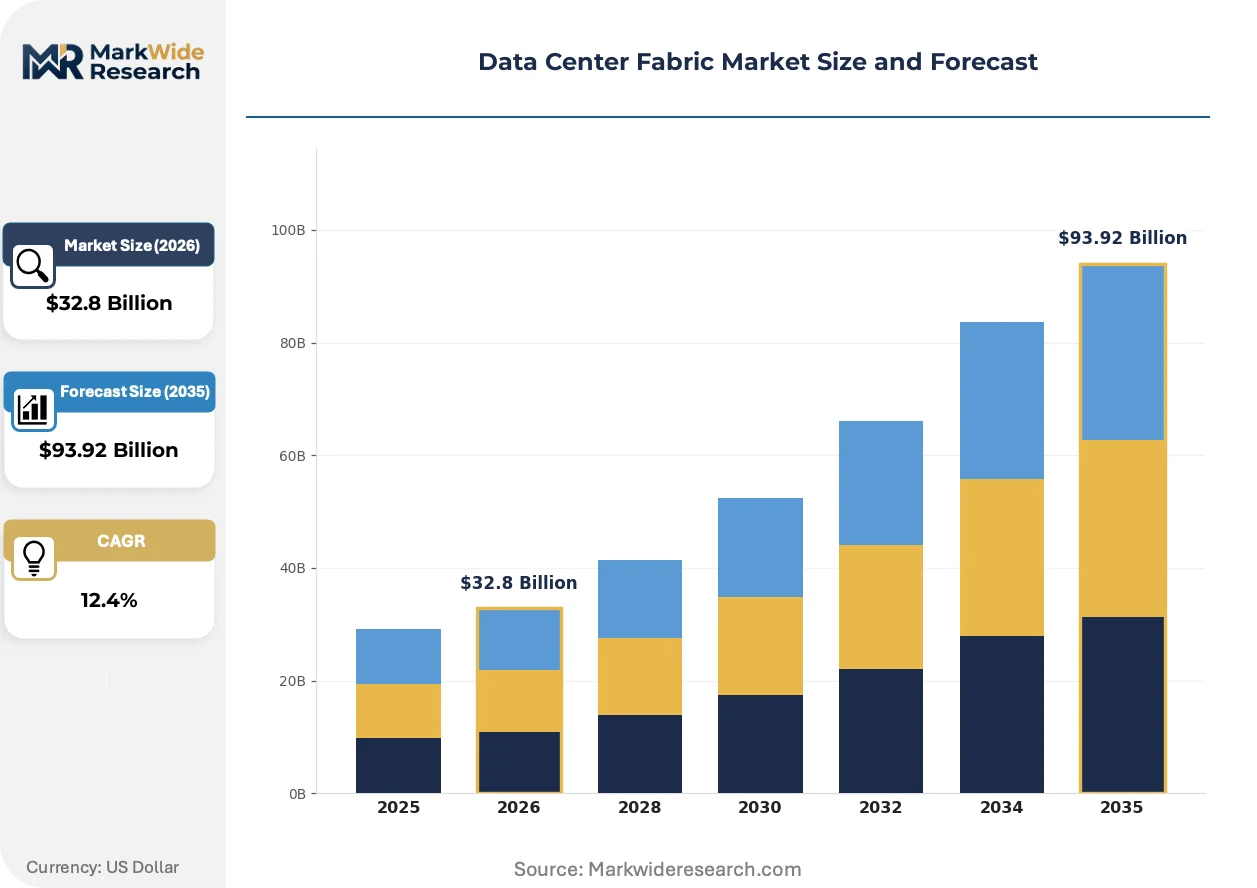
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $93.92 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Routers, Cables, Adapters Technology: Ethernet, InfiniBand, Optical, Fibre Channel End User: Cloud Providers, Enterprises, Telecommunications, Colocation Deployment: On-Premises, Hybrid, Edge Computing, Managed Services |
| Companies Covered | Juniper Networks, Huawei Technologies, Cisco Systems, IBM Corporation, Extreme Networks, Arista Networks, Dell Technologies, Broadcom, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Fabric Market Strategic Shifts & Innovations
Co-packaged optics and liquid cooling integration are compressing the traditional three-year refresh cycle for high-density fabrics, while regulatory pressure on energy disclosure is elevating efficiency metrics to primary procurement criteria alongside raw bandwidth.
Co-packaged optics (CPO) is rewriting the power-performance tradeoff for AI clusters by eliminating retimer chips and reducing electrical trace lengths between switch silicon and optical engines. Hyperscalers in the United States are piloting CPO deployments in 51.2 Tbps switch platforms during 2024-2025 qualification cycles. The technology is compressing the viable window for pluggable transceivers in highest-density racks.
EU CSRD disclosure requirements are forcing European operators to document energy efficiency across network infrastructure, including granular power-per-bit metrics for fabric components. Vendors must now provide audited environmental product declarations to maintain eligibility for procurement shortlists. Financial services and critical infrastructure buyers in Germany, France, and the Netherlands are filtering decisions through ISO 27001 and IEC 62443 compliance frameworks.
Consolidated procurement contracts are displacing multi-vendor best-of-breed strategies among the largest cloud providers, who now negotiate direct silicon supply agreements with switch ASIC vendors. Systems integrators and traditional channel distributors are losing share in the hyperscale segment while gaining importance in fragmented enterprise edge deployments. This bifurcation is most visible in the United States, where Northern Virginia and Phoenix campuses operate on direct procurement models while regional enterprise colocation facilities rely on distributor-led fulfillment.
Data Center Fabric Market Segmentation
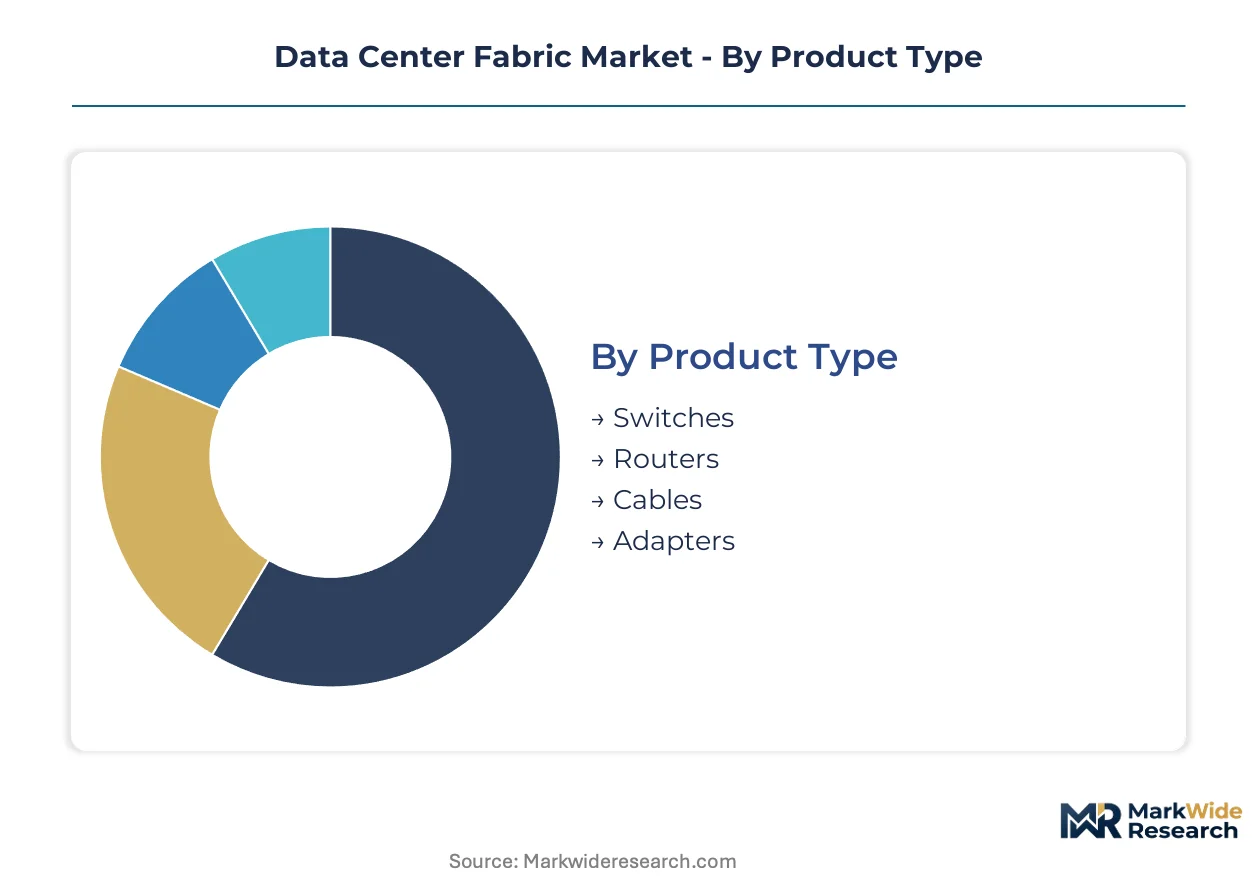
Data center fabric segmentation reveals how procurement power concentrates around specific technology stacks while deployment patterns fragment across facility generations. Understanding these divides enables vendors to align roadmaps with divergent customer capabilities and workload requirements.
Product Type:
Port speed hierarchies and thermal envelopes differentiate hardware procurement decisions across customer tiers.
- Switches:High-density Ethernet switches at 400 Gbps to 800 Gbps anchor AI cluster builds. Hyperscalers in Northern Virginia and Phoenix are procuring these devices at unprecedented scale for GPU-intensive training environments.
- Cables:Active optical cables and direct attach copper assemblies carry signal integrity burdens as PAM4 modulation pushes lane rates to 112 Gbps. Cloud providers expanding fabric deployments for AI training clusters are driving demand for lossless, low-latency interconnects.
- Routers:Border and spine-layer platforms manage inter-fabric traffic flows with deep buffer architectures for congestion management.
- Adapters:SmartNICs and DPUs offload network virtualization and security processing from host CPUs in compute-intensive racks.
Mature deployment sits with switches in legacy enterprise facilities. Newer deployment is concentrated in cables for greenfield AI cluster builds.
Technology:
Transport protocol selection hinges on loss tolerance, latency budgets, and ecosystem maturity for target workloads.
- Ethernet:Dominates general-purpose cloud fabrics through economies of scale and interoperability. Volume shipments concentrate among cloud providers building multi-tenant infrastructure where cost-per-bit efficiency outweighs absolute latency minimization.
- InfiniBand:Commands premium positioning in AI training environments through hardware-accelerated congestion control and sub-microsecond latency. NVIDIA's end-to-end stack dominance creates vendor lock-in concerns for procurement teams.
- Optical:Co-packaged optics and pluggable transceivers bridge electrical-optical boundaries as port speeds escalate.
- Fibre Channel:Persists in storage-area network segments serving legacy enterprise workloads with deterministic performance requirements.
Volume concentration favors Ethernet in established cloud regions. Steepest expansion trajectory belongs to InfiniBand as AI training clusters proliferate.
End User:
Procurement scale and customization requirements diverge sharply across buyer categories.
- Cloud Providers:Hyperscalers consolidate procurement around direct silicon supply agreements, bypassing traditional channel distributors. These buyers negotiate switch ASIC contracts directly and demand custom firmware for fleet management automation.
- Enterprises:Hybrid cloud deployments fragment demand across distributed locations with heterogeneous legacy infrastructure. Financial services and critical infrastructure buyers filter decisions through ISO 27001 and IEC 62443 compliance frameworks.
- Telecommunications:5G core and edge computing requirements drive distributed fabric architectures with strict latency service-level agreements.
- Colocation:Multi-tenant facilities balance standardized offerings against tenant-specific customization requests.
Procurement consolidation sits with cloud providers. Procurement fragmentation is expanding most quickly among enterprises adopting edge computing nodes.
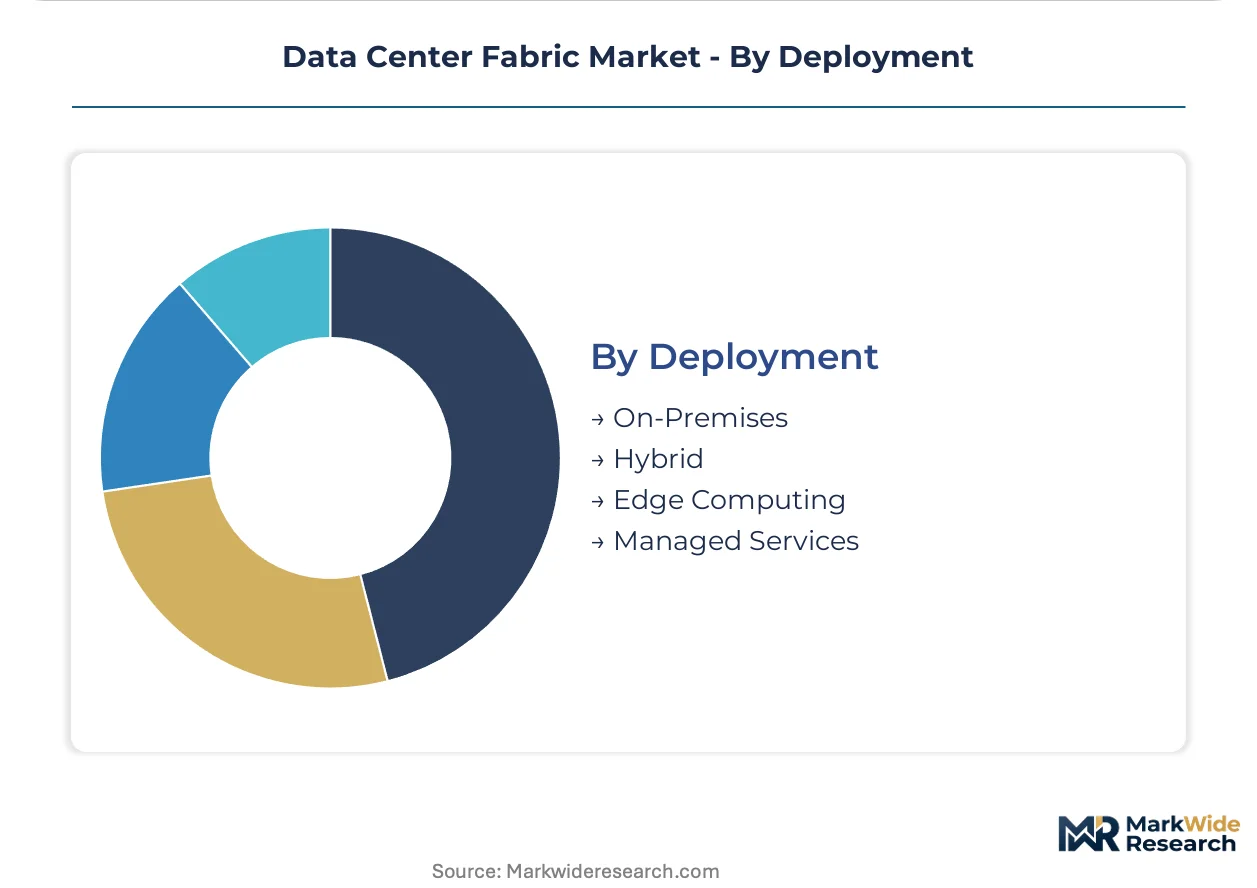
Deployment:
Facility ownership models and operational responsibility allocation shape vendor engagement strategies.
- On-Premises:Enterprise-owned facilities carry full capital burden and operational staffing requirements. Retrofit complexity limits upgrade velocity in facilities built for 10 Gbps to 40 Gbps eras.
- Hybrid:Split workload placement between owned infrastructure and cloud resources demands consistent fabric policy enforcement across administrative boundaries.
- Edge Computing:Latency-sensitive applications in manufacturing and autonomous systems create demand for micro-fabrics operating at 25 Gbps to 100 Gbps in distributed locations.
- Managed Services:Outsourced network operations appeal to mid-market enterprises lacking specialized optical engineering talent.
Established footprint sits with on-premises deployments in legacy enterprise data centers. Gaining share fastest are edge computing nodes supporting real-time analytics workloads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale procurement concentrates in the United States, where Northern Virginia and Phoenix campuses drive switch and cable demand at unprecedented scale. European operators face EU AI Act compliance pressure toward certified, energy-transparent infrastructure. Asia-Pacific markets fragment between cloud expansion and domestic vendor preferences.
United States
Ashburn and Loudoun County hyperscale campuses anchor North American switch procurement for GPU-intensive AI clusters. FCC spectrum and equipment authorization rules shape market access for wireless fabric extensions. Phoenix metro greenfield deployments offer liquid-cooled architecture opportunities unconstrained by legacy thermal limits.
Germany
Financial services and critical infrastructure buyers in Frankfurt and Berlin filter procurement through ISO 27001 and IEC 62443 compliance frameworks. EU CSRD disclosure requirements force operators to document granular power-per-bit metrics for fabric components. Vendors must provide audited environmental product declarations to maintain procurement eligibility.
China
Domestic cloud providers and AI training facilities drive demand for high-density Ethernet and optical interconnects. MIIT standards and dual carbon goals shape infrastructure procurement toward energy-efficient deployments. Vertically integrated domestic vendors compete aggressively through captive optical and switch portfolios in Beijing and Shanghai metro areas.
Japan
METI industrial policy supports domestic semiconductor and AI infrastructure investments with targeted efficiency requirements. Enterprise hybrid deployments fragment demand across Tokyo and Osaka metro facilities with heterogeneous legacy infrastructure. Colocation operators balance standardized offerings against tenant-specific customization for latency-sensitive financial workloads.
United Kingdom
London financial services buyers anchor enterprise demand for compliant, low-latency fabric architectures. GDPR and emerging AI governance frameworks filter procurement decisions toward auditable infrastructure supply chains. Slough and Docklands data center clusters concentrate cloud provider expansion alongside enterprise colocation growth.
Data Center Fabric Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in co-packaged optics and liquid-cooled architectures. The vendor base stratifies around three tiers: hyperscale-direct ASIC suppliers, systems integrators serving fragmented enterprise demand, and component specialists in high-speed optical engines. Dominant competitive moves include direct silicon supply agreements that bypass traditional distribution channels, and vertical consolidation into captive optical component production.
Within the hyperscale-direct tier, Arista Networks and Cisco Systems exemplify divergent strategic positioning—one through high-density Ethernet specialization for AI clusters, the other through installed-base leverage in hybrid enterprise deployments. Huawei Technologies occupies a distinct geography-anchored position, competing through vertically integrated optical and switch portfolios in Asia-Pacific markets. Juniper Networks sits within the border-and-spine layer specialization, managing inter-fabric traffic flows with deep buffer architectures.
| Leading Market Players |
|---|
| Juniper Networks |
| Huawei Technologies |
| Cisco Systems |
| IBM Corporation |
| Extreme Networks |
| Arista Networks |
| Dell Technologies |
| Broadcom |
| Hewlett Packard Enterprise |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud provider procurement concentration in Northern Virginia and Phoenix anchors contract-based long-term offtake pricing for high-density switches and cables, displacing transactional spot markets in the AI cluster segment.
Pricing Analysis
Volume-vs-margin splits sharply across buyer tiers. Three-tier pricing structure across premium, standard, and economy levels separates InfiniBand lossless fabrics from high-density Ethernet and legacy enterprise deployments. Certification under EU AI Act energy-transparency requirements and ISO 27001 security frameworks commands measurable premiums. Cost compression in standard-tier Ethernet switches is intensifying because coherent DSP and optical transceiver supply bottlenecks force ASIC vendors to absorb margin pressure. Mid-tier cloud providers exhibit highest price sensitivity, while hyperscalers negotiating direct silicon supply agreements prioritize performance density over unit cost.
Supply Chain Analysis
Optical engineering talent scarcity in Taiwan, South Korea, and Japan constrains expansion of 112 Gbps PAM4 SerDes and co-packaged optics manufacturing. Fabric hardware production draws from specialized foundry capacity for switch ASICs, captive optical component lines, and precision cable assembly operations. Single-source vulnerability concentrates in coherent DSP supply among a handful of Asian suppliers, exposing procurement to export control disruption. Distribution runs through direct hyperscale contracts for cloud providers, with systems integrators and channel distributors serving fragmented enterprise edge deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around procurement power concentration, with hyperscale direct-silicon agreements forcing weaker systems integrators toward insolvency or niche specialization.
For Market Incumbents: Acquire optical component engineering talent pools to secure 800 Gbps and 1.6 Tbps roadmap execution. Cisco Systems and Arista Networks should deepen backward integration into captive transceiver production, reducing exposure to Asian supplier concentration. Certification investment under EU AI Act and IEC 62443 frameworks creates switching costs that lock enterprise buyers into validated vendor relationships, defending against emerging entrants pitching unproven interoperability. For New Entrants and Emerging Players: Begin with edge computing micro-fabric deployments at 25 Gbps to 100 Gbps, where procurement fragmentation among distributed manufacturing and autonomous systems buyers lowers incumbent scale advantages. Phoenix metro greenfield campuses offer greenfield qualification opportunities for liquid-cooled architectures without legacy retrofit burdens. Channel partnership with regional colocation operators provides bypass around hyperscale direct-procurement barriers. For Investors and Strategic Acquirers: The window for entry favors component specialists with co-packaged optics or liquid cooling IP. Long-term viability hinges on positioning upstream of switch ASIC commoditization. Target acquisition archetypes include optical signal integrity engineering teams and thermal management technology holders. Watch for inflection when hyperscale capex disclosure patterns shift from pluggable transceiver toward CPO-dominated procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Silicon Supply Agreement | Bypasses channel distributors to secure ASIC allocation for Northern Virginia and Phoenix campuses. |
| Co-packaged Optics Qualification | Reduces power-per-bit metrics below pluggable transceiver thresholds for EU CSRD compliance. |
| Liquid Cooling Architecture Deployment | Enables 800 Gbps switch density in greenfield facilities without mechanical cooling retrofit. |
| EU AI Act Certification Investment | Creates audited eligibility for high-risk AI infrastructure procurement in Frankfurt and Berlin. |
| Edge Computing Channel Partnership | Captures fragmented demand from manufacturing and autonomous systems outside hyperscale concentration. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with data center procurement officers, network architects at cloud providers, optical component engineering directors, and channel distribution executives combined with hyperscaler capex disclosures, FCC equipment authorization databases, EU CSRD sustainability reports, and SEC 10-K infrastructure spending filings. Bottom-up port shipment estimates and top-down facility investment analysis were triangulated against switch ASIC vendor production data.
Data-stream reconciliation across shipment volumes, pricing benchmarks, and deployment timelines informed the analytical framework. Segmentation dimensions modeled include port speed tier, transport protocol, end-user category, and deployment type across the projection horizon. CAGRs were derived from facility pipeline analysis and workload density assumptions for AI training clusters. Forecast inputs incorporated thermal design power trajectories and optical component availability constraints.
Export control expansion, hyperscale capex volatility, and optical component supply disruption are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about coherent DSP supply continuity and EU AI Act implementation timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
US Multi-Tenant (Colocation) Data Center Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
Canada Data Center Construction Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Physical Security Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
Asia-Pacific Hosting Infrastructure Services Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
Taiwan Data Center Market