
 Middle East and Africa Data Center Infrastructure Management Market | 2026-2036
Middle East and Africa Data Center Infrastructure Management Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Data Center Infrastructure Management Market Foresight
Liquid cooling is realigning thermal management economics across the Middle East and Africa Data Center Infrastructure Management landscape as operators confront extreme ambient temperatures. Schneider Electric leverages its integrated power and cooling portfolio to anchor large-scale deployments in the Gulf. Vertiv Group Corp. specializes in thermal infrastructure and competes aggressively on precision cooling performance. Huawei Technologies Co., Ltd. controls significant share of the telecommunications-linked DCIM segment through its carrier relationships.
Data Center Infrastructure Management encompasses the integrated monitoring, control, and optimization of physical data center assets including power distribution units, cooling systems, and environmental sensors through centralized software platforms. These systems typically operate across IT load ranges from 500 kW to 100+ MW facilities, maintaining Power Usage Effectiveness targets below 1.4 in advanced installations. Software and analytics segments command expanding margin pools as operators prioritize predictive maintenance and energy optimization over basic hardware telemetry. Cloud Computing deployment models within DCIM are attracting the fastest investment growth, while colocation providers represent the most concentrated end-user demand channel.
Saudi Arabia's Communications and Information Technology Commission and South Africa's Independent Communications Authority enforce data sovereignty and localization requirements that directly expand DCIM addressable market scope. The UAE's National In-Country Value certification program and Egypt's data protection regulations further shape procurement standards and vendor qualification criteria. Stakeholders must monitor evolving carbon disclosure mandates and grid interconnection rules as these will determine which facility designs achieve operational permits.
Market Dynamics
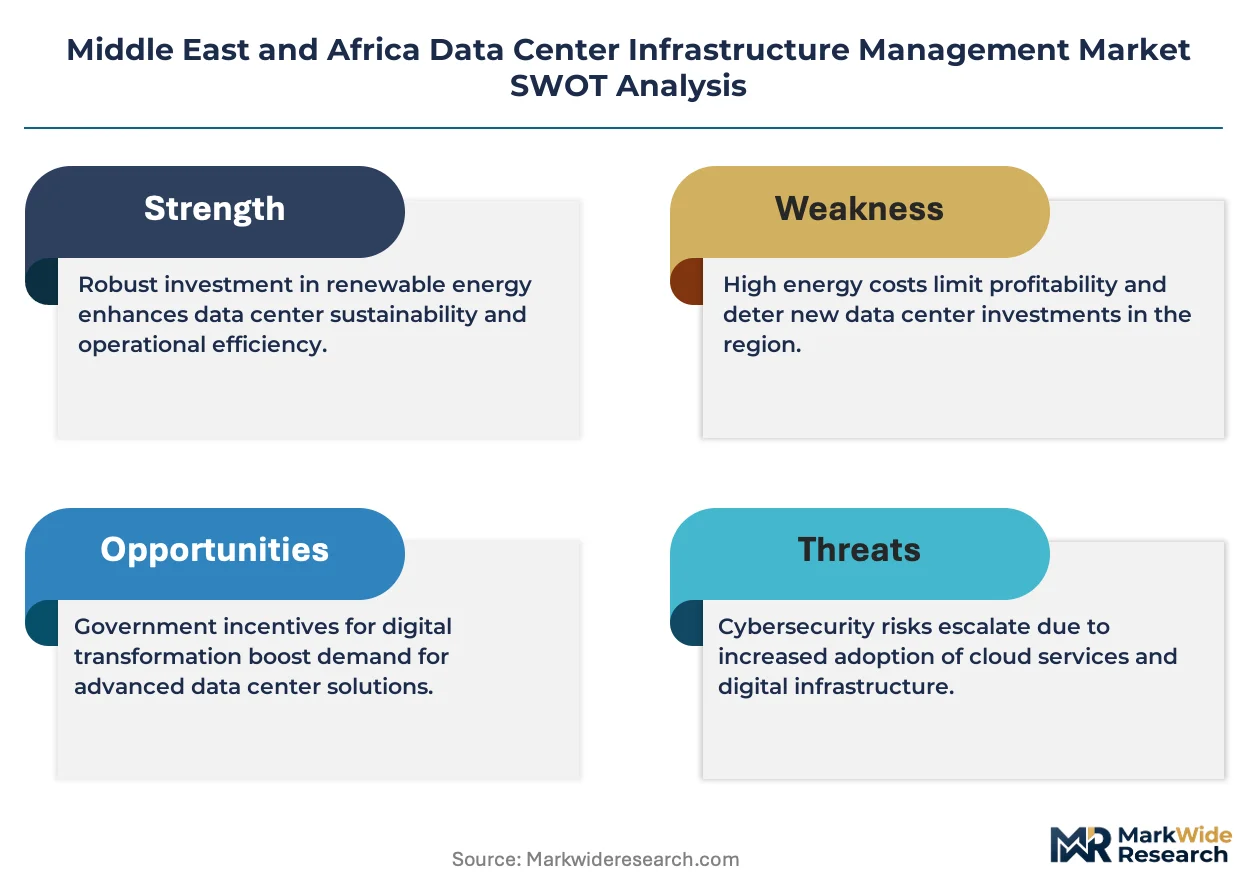
Liquid cooling architectures are compressing thermal management economics across the Middle East and Africa Data Center Infrastructure Management landscape as operators confront ambient temperatures exceeding 45°C in Gulf Cooperation Council markets. This structural shift is redrawing vendor positioning and facility design standards.
Growth Catalysts
- Saudi Vision 2030 localization mandates:The Communications and Information Technology Commission requires data residency for government workloads, forcing hyperscale buildouts that embed DCIM platforms from construction phase.
- Edge computing proliferation:Telecommunications carriers are deploying micro-data centers across secondary African cities, creating distributed monitoring demand that centralized legacy systems cannot serve.
- South Africa's renewable energy procurement:The Independent Communications Authority's power purchase agreement frameworks enable off-grid solar-powered facilities requiring predictive load-balancing software.
Market Restraints
- Copper and aluminum price volatility:Busbar and heat exchanger input costs swing unpredictably, squeezing margins on precision cooling hardware deployments.
- Skilled technician scarcity:The Gulf states rely on expatriate labor pools with restricted mobility, creating commissioning bottlenecks for complex thermal infrastructure.
- Grid interconnection delays:Egypt's electricity utility approval timelines extend facility energization by 18-24 months, freezing DCIM software activation schedules.
Strategic Opportunities
- Nigeria's unpenetrated financial services sector:Lagos-based banks are consolidating server rooms into Tier III facilities, opening first-mover DCIM deployment windows.
- AI-driven predictive maintenance convergence:Machine learning algorithms fused with IoT sensor networks enable fault anticipation 72 hours before thermal excursions.
- Kenya's Special Economic Zone incentives:Konza Technopolis tax holidays attract colocation investors seeking integrated monitoring platforms for multi-tenant optimization.
Industry Challenges
- Certification timeline compression:Uptime Institute Tier certification reviews now average 14 months in the region, misaligning with hyperscale construction schedules.
- Legacy building management system integration:Brownfield facilities in Dubai Internet City and Johannesburg require protocol translation layers that degrade real-time data fidelity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Data Center Infrastructure Management Market |
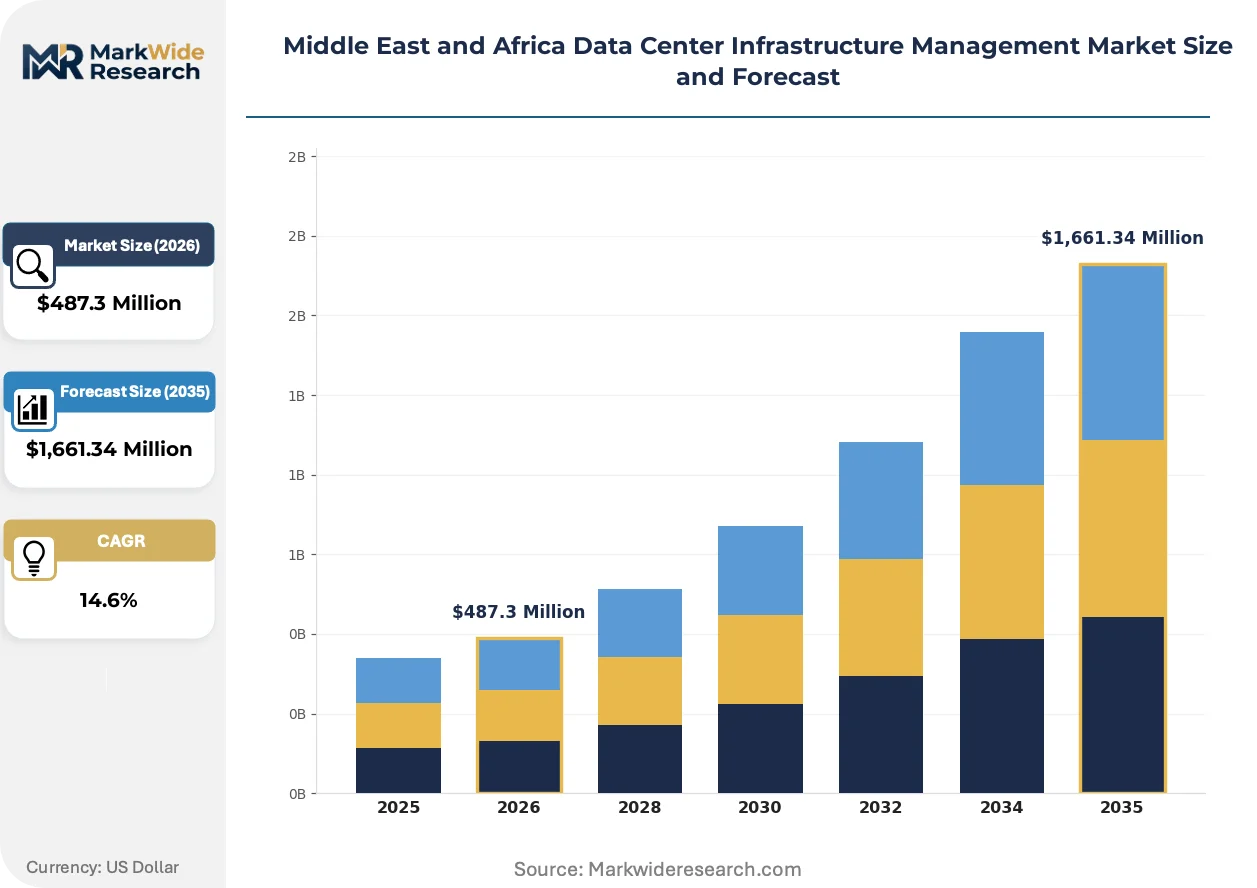
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
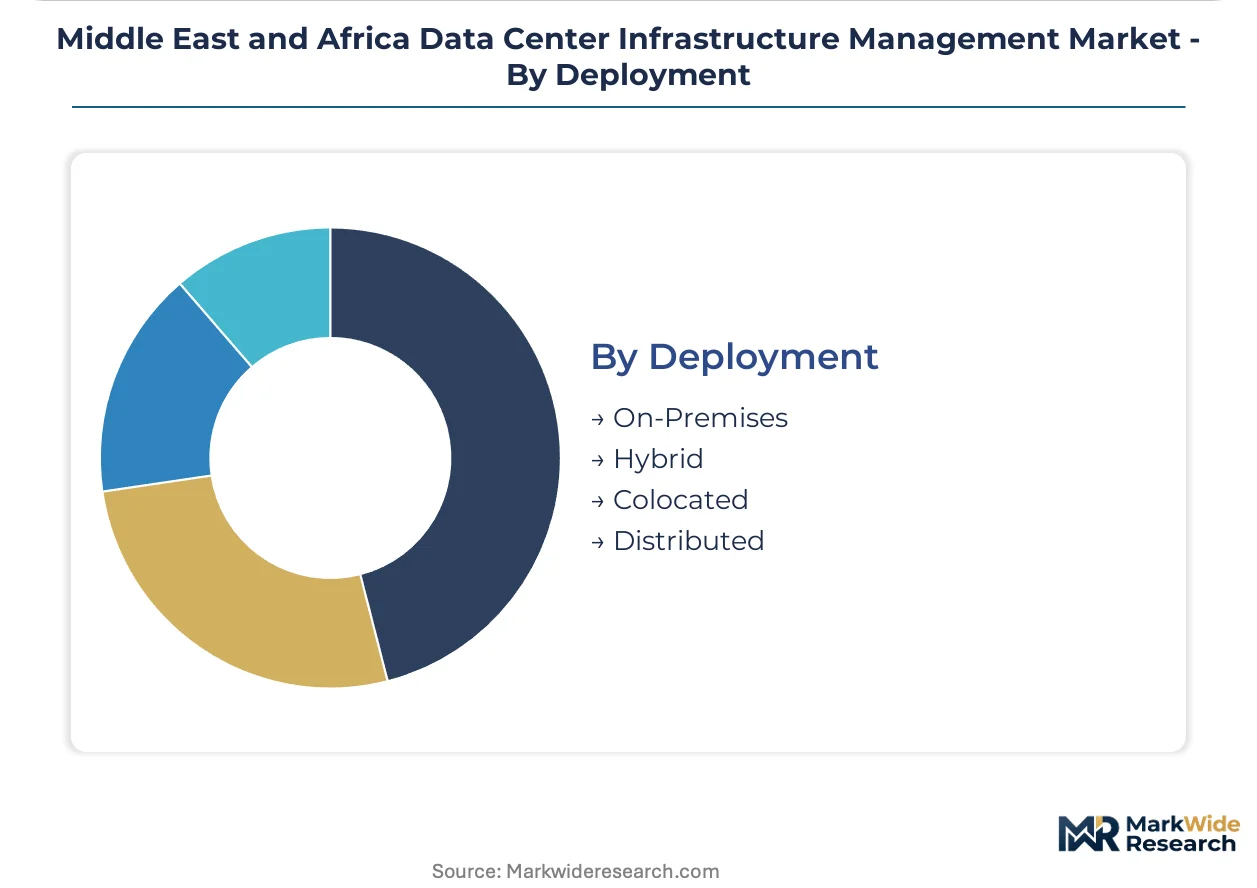
| Segmentation | Product Type: Hardware, Software, Services, Tools Technology: Cloud Computing, Virtualization, Automation, Analytics End User: IT Enterprises, Telecommunication Firms, Government Agencies, Colocation Providers Deployment: On-Premises, Hybrid, Colocated, Distributed |
| Companies Covered | Schneider Electric, Vertiv Group Corp., Huawei Technologies Co., Ltd., ABB, Eaton, Cisco Systems, Inc., Intel Corporation, Fujitsu, Microsoft, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Data Center Infrastructure Management Market Shifts & Advancements
Artificial intelligence inference workloads are forcing thermal design power densities beyond 50 kW per rack across Middle East and Africa facilities. This compression is accelerating adoption of immersion and direct-to-chip cooling modalities while rewriting DCIM software requirements for predictive thermal mapping.
Immersion cooling is expanding into hyperscale deployments across the UAE and Saudi Arabia as operators seek to maintain Power Usage Effectiveness below 1.15 in desert climates. Masdar City and NEOM projects are specifying dielectric fluid systems from initial design phase. This technology is expanding into colocation provider procurement criteria, forcing traditional air-cooled vendors to reengineer product portfolios or cede premium segment share.
Saudi Arabia's Communications and Information Technology Commission data classification rules now mandate encrypted environmental telemetry for government-anchored facilities. The regulation forces DCIM vendors to deploy sovereign cloud instances with localized encryption key management. Financial services operators in Riyadh are responding by bifurcating their monitoring stacks between compliant and non-compliant workloads.
Subscription-based DCIM licensing is displacing perpetual software purchases among mid-sized colocation providers in South Africa and Nigeria. Monthly operational expenditure models align cash outflows with tenant revenue cycles. This pattern is most visible in Cape Town and Lagos, where private equity-backed facility rollups prioritize capital-light technology stacks to accelerate portfolio expansion timelines.
Middle East and Africa Data Center Infrastructure Management Market Segmentation
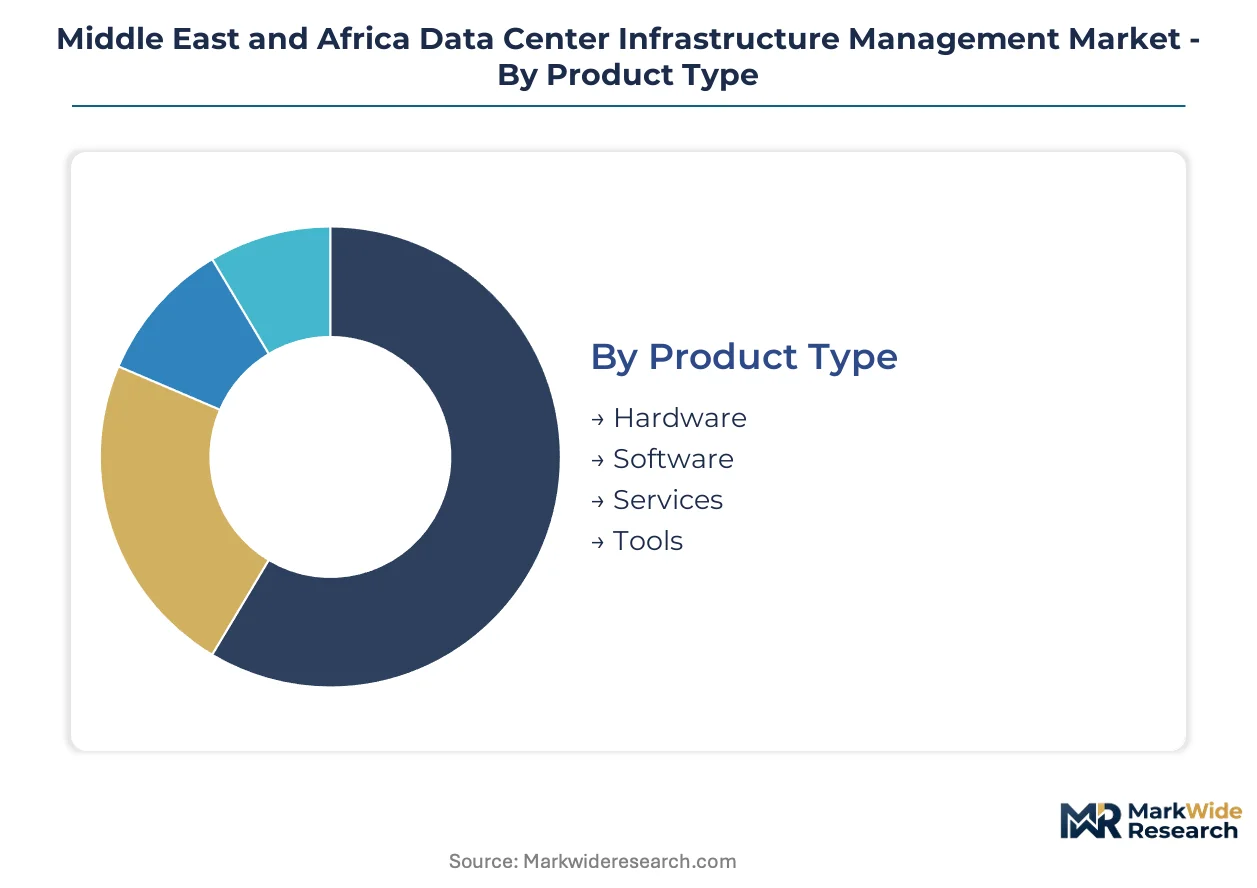
DCIM procurement patterns diverge sharply across the Middle East and Africa based on facility scale, regulatory exposure, and thermal complexity. Buyers in this market prioritize integrated platforms that reconcile data sovereignty mandates with extreme climate operational demands.
Product Type:
Buyers in this category differentiate by capital intensity tolerance and in-house technical capability, with hyperscale operators favoring integrated bundles while mid-tier facilities unbundle procurement.
- Hardware:Physical sensors, power distribution units, and cooling controllers form the telemetry foundation. Demand concentrates among Saudi Arabian and UAE hyperscale builds where Schneider Electric and Vertiv anchor turnkey thermal infrastructure deployments amid 45°C ambient conditions.
- Software:Centralized monitoring platforms with predictive analytics capabilities command expanding margin pools. South African colocation providers drive subscription licensing growth as private equity-backed portfolios prioritize operational expenditure alignment with tenant revenue cycles.
- Services:Integration, commissioning, and managed support offerings address skilled technician scarcity across Gulf states.
- Tools:Diagnostic and configuration utilities supplement core platform functionality for specialized maintenance workflows.
Volume sits with Hardware; growth tilts toward Software.
Technology:
Technology selection tracks workload density evolution and cloud migration maturity, with AI inference demands forcing thermal design power densities beyond 50 kW per rack.
- Cloud Computing:Cloud-based DCIM deployment models enable distributed monitoring across edge micro-data centers. Telecommunications carriers in secondary African cities adopt these architectures as centralized legacy systems fail to serve geographically dispersed infrastructure.
- Virtualization:Abstracted compute resource management optimizes utilization across multi-tenant facilities.
- Automation:Policy-driven environmental control reduces manual intervention requirements in labor-constrained markets.
- Analytics:Machine learning algorithms fused with IoT sensor networks enable fault anticipation 72 hours before thermal excursions, with Riyadh financial services operators bifurcating compliant and non-compliant monitoring stacks under CITC encryption mandates.
Cloud Computing captures current deployment share; Analytics climbs the fastest as predictive maintenance converges with sovereign data requirements.
End User:
End user segmentation reflects divergent regulatory exposure and data sovereignty risk profiles, with government-anchored workloads imposing strictest compliance burdens.
- IT Enterprises:Corporate data center operators consolidate fragmented server estates into monitored facilities. Lagos-based Nigerian banks are consolidating server rooms into Tier III facilities, opening first-mover DCIM deployment windows amid financial services digitization.
- Telecommunication Firms:Carriers deploying micro-data centers across secondary African cities create distributed monitoring demand that centralized legacy platforms cannot serve, with edge computing proliferation accelerating procurement timelines.
- Government Agencies:Saudi Vision 2030 localization mandates and CITC data residency requirements force hyperscale buildouts embedding DCIM from construction phase.
- Colocation Providers:Multi-tenant optimization requirements prioritize tenant-visible environmental transparency and sub-metering accuracy.
Colocation Providers concentrate procurement volume; Government Agencies expand most quickly under localization mandates.
Deployment:
Deployment model selection correlates with grid reliability, data classification requirements, and facility energization timelines that stretch 18-24 months in Egypt.
- On-Premises:Fully captive infrastructure maintains maximum environmental control and security isolation. Demand concentrates among Saudi government-anchored facilities subject to CITC encrypted telemetry mandates requiring sovereign cloud instances with localized encryption key management.
- Hybrid:Split workload architectures balance sensitive data custody with cloud scalability.
- Colocated:Shared facility environments leverage provider-managed DCIM platforms for cost efficiency.
- Distributed:Geographically dispersed monitoring architectures serve edge computing deployments across African telecommunications networks where centralized systems lack reach.
On-Premises retains dominant share; Distributed gains share fastest as edge infrastructure proliferates beyond primary hub markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the UAE, Saudi Arabia, and South Africa as primary hub markets, with secondary expansion accelerating across Nigeria and Kenya. Cloud service providers are expanding their footprint across the region, drawn by data sovereignty requirements and extreme climate operational challenges.
United Arab Emirates
Masdar City and Dubai Internet City anchor hyperscale facility construction as operators target Power Usage Effectiveness below 1.15. The National In-Country Value certification program shapes procurement standards and vendor qualification criteria. Abu Dhabi and Dubai dominate deployment volume, with colocation providers adopting subscription-based DCIM licensing to align cash outflows with tenant revenue cycles.
Saudi Arabia
Vision 2030 localization mandates and data residency requirements for government workloads are forcing hyperscale buildouts that embed DCIM platforms from construction phase. The Communications and Information Technology Commission enforces encrypted environmental telemetry rules for government-anchored facilities. NEOM and Riyadh financial services operators are bifurcating monitoring stacks between compliant and non-compliant workloads under sovereign cloud requirements.
South Africa
Independent Communications Authority power purchase agreement frameworks enable off-grid solar-powered facilities requiring predictive load-balancing software. Cape Town and Johannesburg concentrate colocation provider procurement as private equity-backed portfolios prioritize capital-light technology stacks. Renewable energy procurement is reshaping facility design standards across the Western Cape and Gauteng provinces.
Nigeria
Lagos-based banks are consolidating server rooms into Tier III facilities, opening first-mover DCIM deployment windows amid financial services digitization. The central bank's data protection regulations and payment system mandates create compliance-driven monitoring demand. Lagos anchors deployment concentration, with edge computing infrastructure expanding into secondary cities as telecommunications carriers deploy micro-data centers.
Kenya
Konza Technopolis tax holidays and Special Economic Zone incentives attract colocation investors seeking integrated monitoring platforms for multi-tenant optimization. The national communications regulator's data localization guidance expands addressable market scope for sovereign-compliant DCIM deployments. Nairobi and the Konza corridor dominate facility planning, with distributed architectures serving edge computing demand beyond primary hub infrastructure.
Middle East and Africa Data Center Infrastructure Management Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated power and cooling portfolios commanding premium positioning in Gulf hyperscale deployments. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with cross-sector energy management expertise, thermal infrastructure pure-plays competing on precision cooling performance, and telecommunications-linked systems integrators leveraging carrier relationships. Geographic expansion through local certification partnerships and portfolio diversification into predictive analytics software represent the dominant competitive moves reshaping market structure.
Within the diversified industrial tier, Schneider Electric and ABB exemplify integrated platform providers anchoring large-scale deployments across extreme climate markets. Vertiv Group Corp. occupies a specialist position focused on thermal infrastructure performance. Huawei Technologies Co., Ltd. sits within the telecommunications-anchored segment, controlling significant share through carrier-linked DCIM relationships.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv Group Corp. |
| Huawei Technologies Co., Ltd. |
| ABB |
| Eaton |
| Cisco Systems, Inc. |
| Intel Corporation |
| Fujitsu |
| Microsoft |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up colocation specialists across South Africa and Nigeria anchor supply consolidation while enforcing pricing discipline through subscription-based licensing models that align cash outflows with tenant revenue cycles.
Pricing Analysis
Volume concentrates in hardware-led turnkey deployments while margin pools shift toward software analytics. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service bundling. Cost compression in mid-market segments intensifies as copper and aluminum input volatility squeezes precision cooling hardware margins. Government-anchored facilities in Saudi Arabia exhibit lowest price sensitivity due to sovereign compliance mandates, while Lagos-based banks consolidating server rooms represent the most price-conscious buyer archetype.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand across the UAE and Saudi Arabia, while distributor-led models serve mid-tier African facilities. Manufacturing concentrates in China, Germany, and the USA for power distribution units and precision cooling controllers. Supply chains draw from copper busbar, aluminum heat exchanger, and dielectric fluid inputs. Single-source vulnerability in semiconductor-based sensor components creates exposure to extended lead times. Distribution runs through certified systems integrators in Gulf Cooperation Council markets where CITC encryption mandates require localized vendor qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's Communications and Information Technology Commission data residency requirements create a cost-of-compliance moat that favors incumbent DCIM vendors with sovereign cloud infrastructure already deployed.
For Market Incumbents: Deepen vertical integration into predictive analytics software to capture expanding margin pools as AI-driven thermal mapping becomes standard. Anchor capacity expansion in Riyadh and NEOM where Vision 2030 localization mandates force hyperscale buildouts embedding DCIM from construction phase. Defend against emerging telecommunications-linked systems integrators by tightening channel control through exclusive certification partnerships with national regulators. For New Entrants and Emerging Players: Capture first-mover windows in Nigeria's unpenetrated financial services sector where Lagos-based banks are consolidating server rooms into Tier III facilities. Kenya's Konza Technopolis Special Economic Zone offers tax-advantaged entry points for colocation-focused monitoring platforms. Pursue edge computing infrastructure deployments across secondary African cities where centralized legacy systems fail to serve geographically dispersed telecommunications networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-specialist targets in South Africa where private equity-backed portfolio rollups prioritize capital-light technology stacks. Long-term viability hinges on predictive maintenance capability convergence with sovereign data requirements. Monitor CITC encryption mandate enforcement intensity as the signal for compliant-vendor valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Instance Deployment | Enables CITC-compliant telemetry capture in Saudi government-anchored facilities. |
| Immersion Cooling Portfolio Expansion | Secures positioning in Masdar City and NEOM dielectric fluid specifications. |
| Edge Computing Platform Integration | Addresses distributed monitoring gaps across secondary African telecommunications networks. |
| Predictive Analytics Acquisition | Accelerates fault anticipation capability for 72-hour thermal excursion prevention. |
| Local Certification Partnership | Unlocks procurement eligibility under UAE National In-Country Value program requirements. |
Research Methodology
Multi-period observation of hyperscale construction timelines, CITC enforcement patterns, and colocation M&A velocity anchored the trend analysis, supplemented by interviews with data center engineering directors, facilities procurement officers, telecommunications infrastructure planners, and sovereign cloud architects. Secondary validation drew from SEC filings of listed industrial conglomerates, hyperscaler capex disclosure reports, Uptime Institute certification databases, and national regulator procurement bulletins. Bottom-up facility counts triangulated against top-down addressable market sizing.
The input-output matrix framed demand modeling across deployment scale, thermal complexity tier, regulatory exposure level, and cloud migration maturity. Segmentation dimensions included product type, technology architecture, end-user vertical, and deployment model. CAGRs were derived from facility pipeline tracking and software licensing pattern analysis. Forecast inputs incorporated renewable energy procurement timelines and grid interconnection approval durations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper price volatility and Gulf state expatriate labor mobility restrictions. Practitioners should monitor CITC encryption mandate expansion scope and ICASA power purchase agreement framework adoption for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Hong Kong Data Center Market
Data Center Infrastructure
Norway Data Center Rack Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
United Kingdom Data Center Physical Security Market
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
United Arab Emirates Data Center Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Asia-Pacific Hyperscale Data Center Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Data Center Virtualization Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
New Zealand Data Center Market