
 Fermented Foods and Beverages Market | 2026-2036
Fermented Foods and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Foods and Beverages Market Foresight
European artisan dairy production is decoupling from mass-market yogurt capacity as specialized fermentation infrastructure expands. Danone S.A. leverages its strain libraries and cold-chain logistics to dominate European probiotic distribution. Nestlé S.A. sustains global reach through dairy and plant-based fermented portfolios spanning multiple continents. Yakult Honsha Co. Ltd. anchors Asia-Pacific demand with dedicated Lactobacillus casei Shirota manufacturing and direct-store delivery networks.
Fermented foods and beverages comprise products transformed by controlled microbial activity—bacteria, yeast, or molds metabolizing substrates to produce organic acids, alcohol, or bioactive compounds under defined temperature, pH, and anaerobic conditions. These products serve commercial purposes spanning shelf-life extension, sensory modification, and targeted delivery of live microorganisms for gastrointestinal and immune modulation. Kombucha and kefir occupy premium growth trajectories within product type segmentation as functional beverage seekers migrate from sugary soft drinks. Supermarkets and online retail channels capture expanding volume within distribution channel segmentation, though health stores retain higher margin pools through curated strain-specific offerings and practitioner referrals.
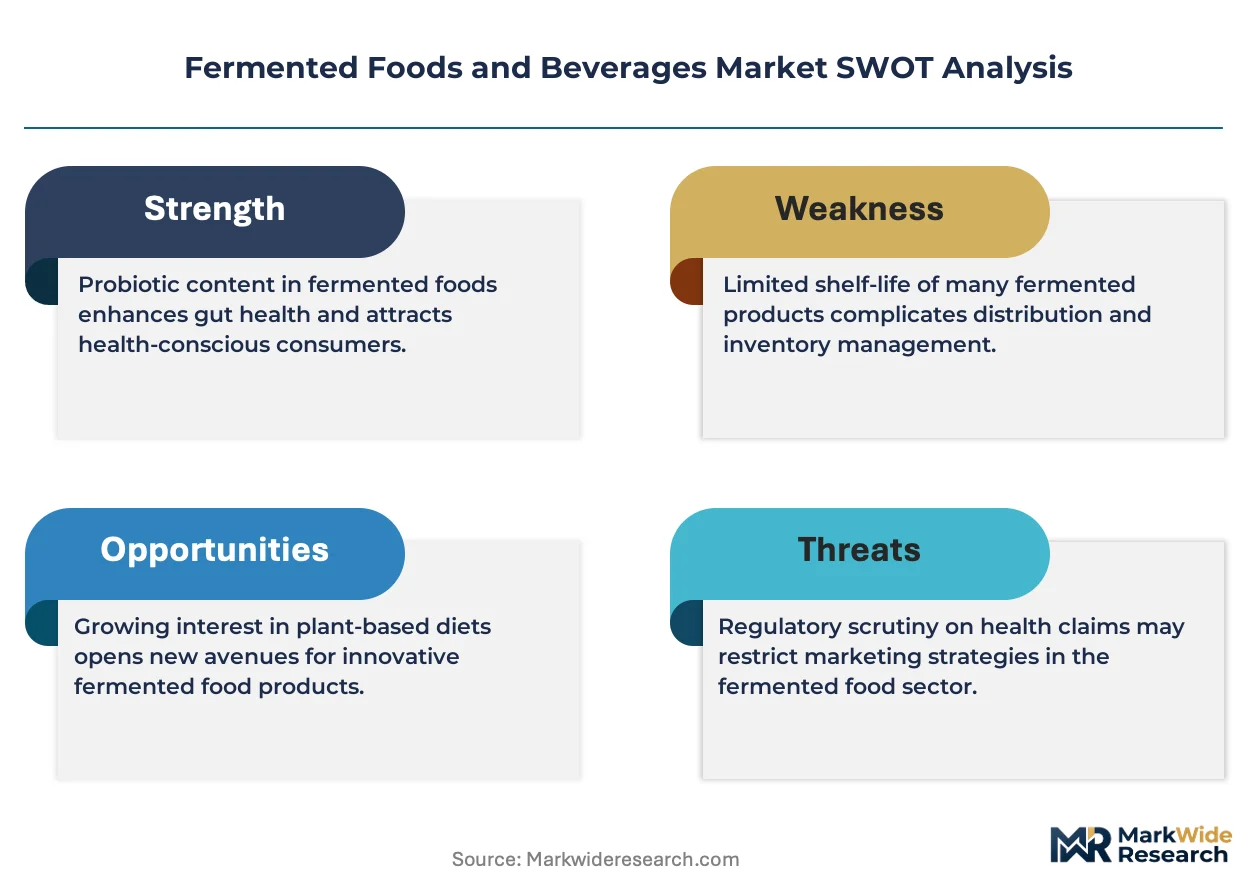
EFSA novel food evaluations and FDA GRAS notifications for live microbial ingredients shape formulation pathways and cross-border market access for fermented product developers. The EU Green Deal's packaging waste directives and USDA organic certification standards add compliance layers that favor domestic producers with established supply chain documentation. Stakeholders must monitor evolving strain-level health claim substantiation requirements across multiple jurisdictions to anticipate reformulation costs and label restriction risks.
Market Dynamics
Live-culture stability requirements are forcing capital reallocation toward cold-chain fermentation infrastructure as restaurants and retailers demand extended shelf-life guarantees for unpasteurized products.
Growth Catalysts
- EFSA novel food pathways:Streamlined safety evaluations for traditional fermented products accelerate cross-border distribution within the European single market.
- Functional beverage migration:Consumers exit high-sugar soft drink categories for kombucha and water kefir, expanding addressable volume in convenience retail.
- South Korean production clusters:Kimchi export infrastructure and domestic probiotic consumption anchor regional manufacturing scale.
Market Restraints
- Dairy input volatility:Milk powder and whey concentrate price swings compress margin predictability for yogurt and kefir processors.
- Live-culture spoilage risk:Temperature excursions in last-mile distribution destroy viable cell counts, limiting expansion into ambient retail channels.
- FDA GRAS notification delays:Strain-specific safety dossiers for new probiotic candidates extend time-to-market by 18-24 months.
Strategic Opportunities
- Plant-based fermentation white space:Oat, coconut, and cashew substrates enable dairy-free positioning in North American specialty retail.
- Direct-to-consumer subscription models:Refrigerated home delivery bypasses traditional distributor markups for artisan producers.
- USDA organic certification tailwinds:Premium pricing for certified organic fermented vegetables attracts conventional produce growers.
Industry Challenges
- Microbiology talent scarcity:Industrial fermentation expertise concentrates in pharmaceutical bioprocessing, creating recruitment competition for food-grade facilities.
- Strain IP fragmentation:Proprietary Lactobacillus and Bifidobacterium libraries trigger licensing disputes between ingredient suppliers and finished product manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Foods and Beverages Market |
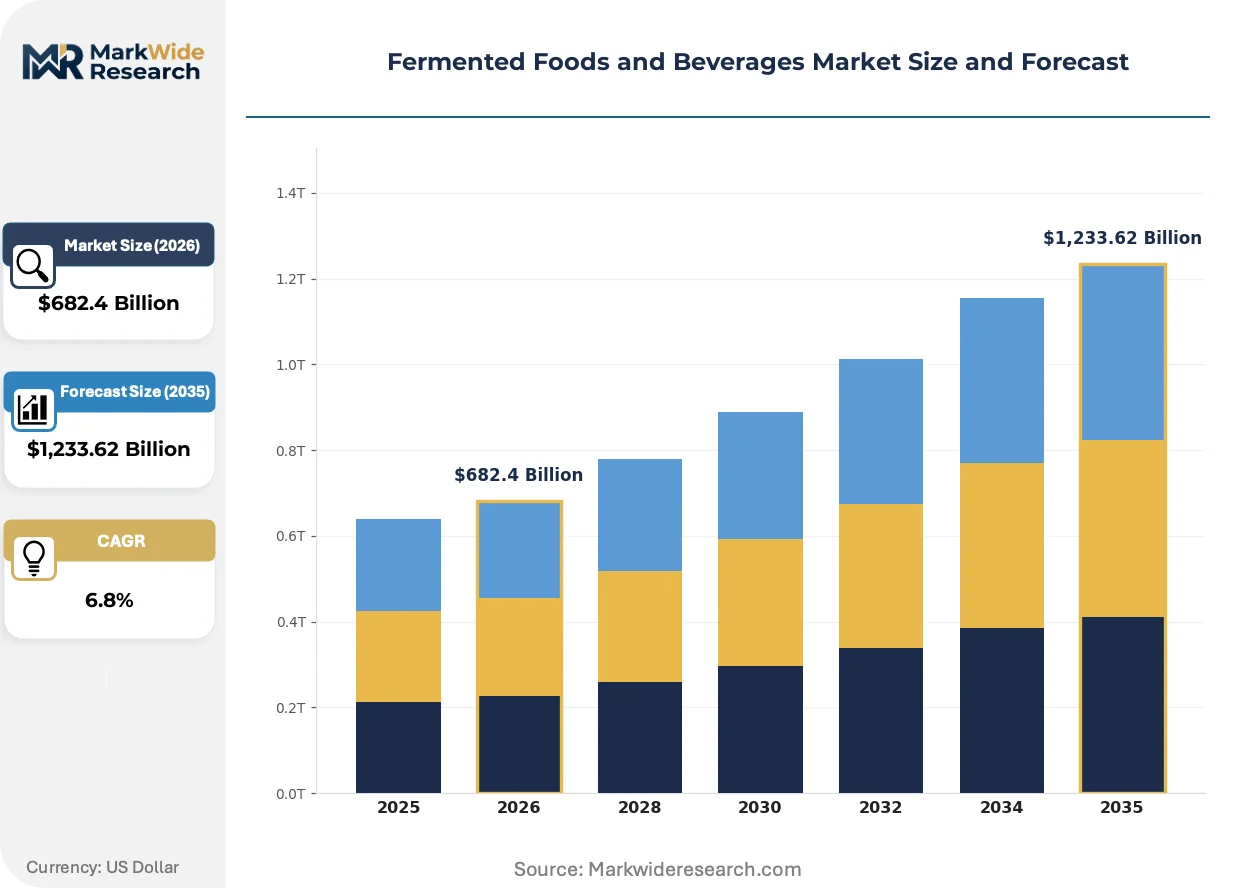
| Market Size in 2026 | $682.4 Billion |
| Market Size in 2035 | $1,233.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kefir, Sauerkraut, Kimchi, Kombucha Application: Food Preservation, Probiotic Supplementation, Flavor Enhancement, Digestive Health Distribution Channel: Supermarkets, Online Retail, Health Stores, Specialty Shops Customer Type: Health-Conscious Consumers, Food Enthusiasts, Restaurants, Nutritional Supplements |
| Companies Covered | PepsiCo Inc., Fonterra Co-operative Group, Danone S.A., Chobani LLC, Kerry Group plc, Nestlé S.A., The Coca-Cola Company, Unilever PLC, Yakult Honsha Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Foods and Beverages Market Shifts & Advancements
Precision fermentation and AI-driven strain optimization are compressing development cycles while regulatory frameworks struggle to categorize novel biomass ingredients.
Cell-cultured dairy proteins produced via precision fermentation are absorbing investment from conventional dairy majors seeking to decouple from livestock supply chains. Food service operators in Germany and the Netherlands trial these ingredients in fermented applications where texture and mouthfeel dominate consumer acceptance. The technology is absorbing market share from plant-based analogues that fail on taste benchmarks.
REACH chemical safety registrations now capture fermentation-derived enzymes and processing aids previously exempt under food-grade exemptions. ECHA data requirements for novel microbial metabolites add 12-18 months to ingredient approval timelines. Small-scale European artisan producers lack toxicology dossier budgets, consolidating formulation advantage with mid-cap specialists.
Practitioner-channel certification is displacing mass-market advertising as the primary trust mechanism for clinical-grade probiotic sales. Functional medicine clinics in the United States and Australia now prescribe strain-specific formulations with documented CFU counts at expiration. This channel commands 40-60% price premiums over supermarket equivalents despite identical manufacturing inputs.
Fermented Foods and Beverages Market Segmentation
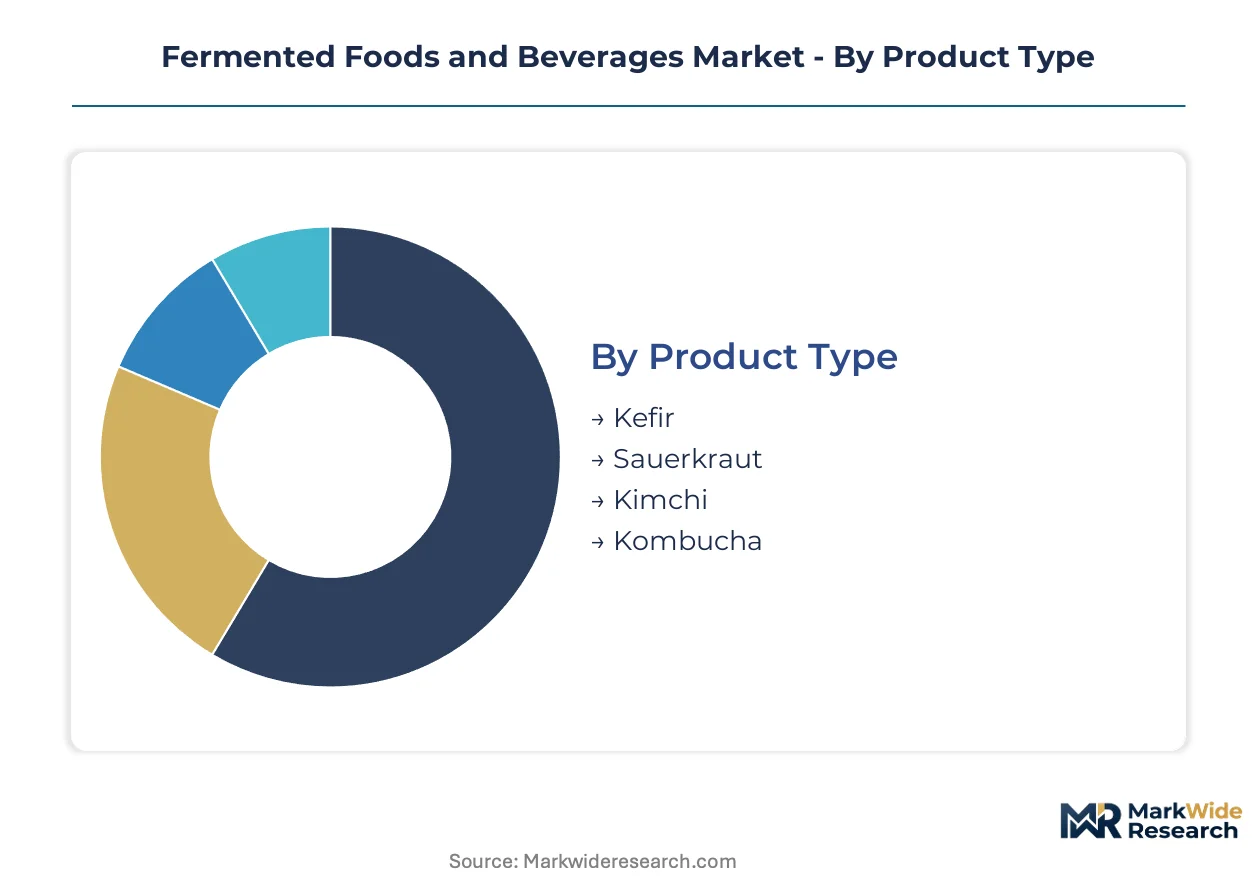
Fermented product categories diverge sharply in capital requirements, from low-investment vegetable fermentation to precision-controlled dairy bioprocessing. Understanding these structural differences reveals where margin pools concentrate and which segments attract infrastructure investment.
Product Type:
Kefir and kombucha demand the heaviest upfront capital for cold-chain fermentation infrastructure, while vegetable-based segments require lower equipment investment but face longer maturation cycles.
- Kefir:Fermented milk beverage produced through mesophilic or thermophilic bacterial cultures at controlled pH levels. Demand concentrates in Eastern European heritage markets and North American functional beverage aisles, where consumers prioritize live-culture counts over flavor variety. Cold-chain requirements limit ambient retail penetration.
- Kombucha:Tea-based effervescent drink fermented by symbiotic culture of bacteria and yeast (SCOBY) under aerobic conditions. Premium positioning in Germany, Australia, and coastal US cities drives SCOBY propagation facility expansion, though alcohol content thresholds trigger regulatory complexity.
- Sauerkraut:Lacto-fermented cabbage with minimal processing infrastructure. German and Polish consumption traditions sustain volume, with artisan producers in Pennsylvania and Wisconsin supplying domestic demand.
- Kimchi:Korean fermented vegetable preparation involving napa cabbage, radish, and chili paste with defined fermentation stages. South Korean export infrastructure and MFDS certification requirements shape commercial scale.
Most installed capacity flows through kefir. Expansion is steepest in kombucha.
Application:
Probiotic supplementation commands the highest formulation precision and strain documentation costs, while flavor enhancement applications tolerate broader microbial diversity.
- Probiotic Supplementation:Strain-specific live microorganism delivery targeting documented CFU counts at expiration. Practitioner channels in the United States and Australia prescribe clinical-grade formulations with 40-60% price premiums over retail equivalents.
- Digestive Health:General gastrointestinal wellness positioning without strain-level claims. European EFSA health claim restrictions force reformulation toward general wellness messaging.
- Food Preservation:Traditional shelf-life extension through organic acid production. Artisan vegetable fermenters in Pennsylvania and Wisconsin supply regional markets with minimal regulatory burden.
- Flavor Enhancement:Umami and acidity modification in culinary applications. Restaurant fermentation programs in Copenhagen and San Francisco drive small-batch ingredient demand.
Probiotic supplementation captures the steepest margin expansion. Food preservation offers the most stable volume base.
Distribution Channel:
Health stores and specialty shops demand the highest working capital investment for curated inventory and staff training, while supermarkets prioritize volume throughput over strain specificity.
- Health Stores:Curated strain-specific offerings with practitioner referral networks. Higher margins compensate for inventory turnover constraints and refrigeration requirements.
- Supermarkets:Mass-market placement requiring extended shelf-life guarantees and pasteurization trade-offs. Chilled dairy aisles in France and Germany dominate volume.
- Online Retail:Direct-to-consumer subscription models bypassing distributor markups. Refrigerated last-mile logistics determine viable shipping radii.
- Specialty Shops:Localized artisan production with minimal scale economies. Farmers market circuits in Vermont and Oregon sustain micro-producers.
Supermarkets move the highest absolute volume. Online retail is climbing the fastest.
Customer Type:
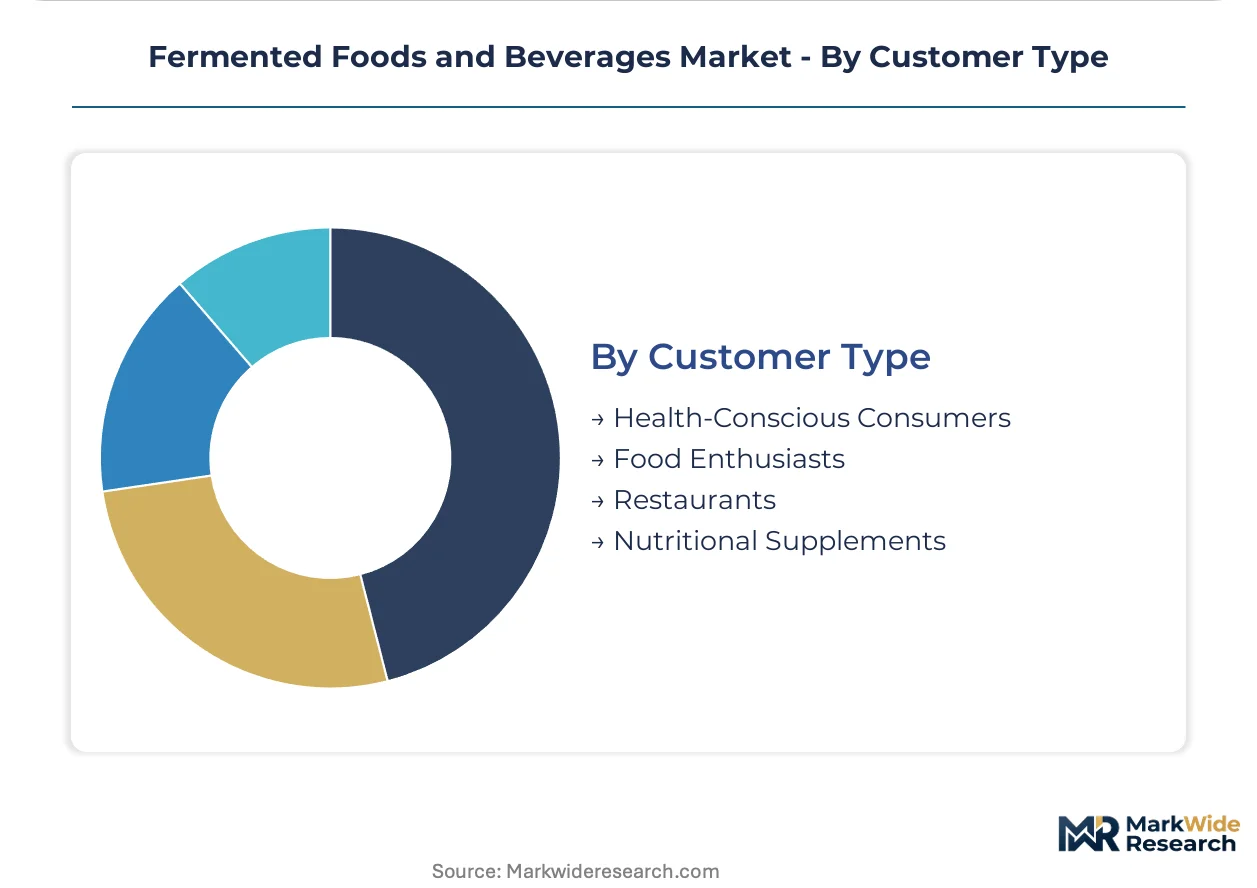
Restaurants and nutritional supplements require the most technical specification documentation, while health-conscious consumers drive volume through less stringent purchase criteria.
- Nutritional Supplements:Strain-level CFU documentation and expiration stability testing. Capsule and powder formats bypass refrigerated distribution constraints.
- Restaurants:House-fermented menu items requiring HACCP protocols and staff training. Copenhagen and San Francisco operators lead functional dining integration.
- Health-Conscious Consumers:Mass-market purchasers prioritizing convenience and price over strain specificity. German and Polish retail chains capture this base.
- Food Enthusiasts:Hobbyist and small-batch purchasers with high engagement but limited scale. Home fermentation kit sales correlate with urban density.
Health-conscious consumers represent the largest addressable base. Nutritional supplements deliver the highest per-unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting fermentation capacity toward jurisdictions with streamlined novel-food pathways and established cold-chain infrastructure. Producers migrate operations to exploit compliance-cost differentials between EFSA-administered markets and FDA-parallel systems.
United States
Kombucha taprooms in Austin and Los Angeles drive experiential consumption formats. FDA GRAS notification requirements for new probiotic strains extend product development timelines. Colorado and Vermont host expanding artisan kefir cooperatives supplying direct-to-consumer subscription channels.
Germany
Water kefir and jun tea variants capture functional beverage migration from conventional soft drinks. EFSA health claim restrictions force reformulation toward general wellness positioning. Berlin and Munich fermentation kitchens supply restaurant programs across the Rhine-Ruhr industrial corridor.
South Korea
Domestic probiotic consumption and kimchi export demand anchor regional manufacturing scale. MFDS certification requirements shape commercial production standards. Gwangju and Jeolla Province maintain heritage fermentation clusters supplying both domestic retail and international food service.
Australia
Practitioner-channel probiotic prescriptions command premium pricing in Sydney and Melbourne functional medicine clinics. TGA therapeutic goods regulations govern strain-specific health claim substantiation. Queensland dairy cooperatives are expanding kefir processing capacity for Asian export markets.
Netherlands
Precision fermentation startups in Eindhoven and Wageningen attract venture capital for cell-cultured dairy protein applications. REACH chemical safety registrations now capture fermentation-derived enzymes. Dutch food service operators trial precision-fermented ingredients in traditional dairy applications.
Fermented Foods and Beverages Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision-fermentation platforms and direct-to-consumer cold-chain models. Market structure concentrates around multinational dairy portfolios with strain libraries and captive distribution. Three archetypes dominate: heritage dairy conglomerates with global cold-chain networks, Asian specialists with dedicated probiotic manufacturing, and beverage multinationals diversifying into functional categories. Competitive moves center on strain IP licensing disputes and refrigerated last-mile infrastructure acquisition.
Among heritage dairy conglomerates, Danone S.A. and Nestlé S.A. occupy positions defined by continental European strain libraries and multi-continent distribution reach. Yakult Honsha Co. Ltd. exemplifies the Asian specialist archetype with dedicated Lactobacillus manufacturing and direct-store delivery networks. These three entities represent contrasting scale models: European diversified portfolios versus Japanese single-strain focus.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| Fonterra Co-operative Group |
| Danone S.A. |
| Chobani LLC |
| Kerry Group plc |
| Nestlé S.A. |
| The Coca-Cola Company |
| Unilever PLC |
| Yakult Honsha Co. Ltd. |
| Others |
Supply & Pricing Matrix
Industrial microbiology expertise clustering in the Netherlands and Denmark widens labor-cost differentials between heritage fermentation hubs and emerging precision-fermentation facilities, compressing margin spreads across premium and mass-market tiers. Cold-chain infrastructure investments in South Korea and Germany further stratify pricing power by locking in shelf-life guarantees that ambient-channel competitors cannot match.
Pricing Analysis
Distributor margins in refrigerated fermented beverages absorb 25-35% of shelf price before retailer markup, while direct-to-consumer subscription models bypass both layers entirely. Three-tier pricing structure across premium practitioner-grade, standard retail, and economy private-label levels separates strain-documented probiotics from generic live-culture products. Pricing pressure stems from dairy input volatility squeezing kefir and yogurt processors. Health-conscious consumers in German supermarket chains exhibit highest price sensitivity; functional medicine clinics in Australia show least.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised live-culture products remain underdeveloped, destroying viable cell counts that cannot be refurbished or remanufactured. Supply concentrates in South Korea, Germany, and the United States for kimchi, kefir, and kombucha respectively. Raw material dependencies span napa cabbage from Jeolla Province, milk powder from New Zealand cooperatives, and tea substrates from Sri Lankan estates. Single-source vulnerability in SCOBY propagation facilities threatens kombucha continuity. Distribution runs through refrigerated supermarket dairy aisles and direct-store delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Producers arbitrage EFSA novel-food compliance costs against FDA GRAS notification timelines, relocating strain development to jurisdictions with faster safety evaluation pathways. This geographic cost differential rewards early regulatory positioning.
For Market Incumbents: Hedge against precision-fermentation disruption by acquiring cold-chain logistics networks in North America and securing exclusive licensing for proprietary Lactobacillus strain libraries. Consolidate formulation advantage through backward integration into starter culture production. Defensive capacity expansion in South Korean kimchi clusters counters emerging plant-based competitors from Dutch fermentation startups. For New Entrants and Emerging Players: Enter via practitioner-channel certification in Australia and the United States where 40-60% price premiums reward strain-specific documentation. Target direct-to-consumer refrigerated subscription models in Colorado and Vermont where artisan kefir cooperatives lack national scale. White space exists in oat and coconut-based dairy-free fermentation for North American specialty retail. For Investors and Strategic Acquirers: Dairy conglomerates with captive cold-chain infrastructure are the most active acquirer in this space, consolidating mid-cap specialists with toxicology dossier capabilities. Long-term viability hinges on regulatory arbitrage sustainability across EFSA and FDA jurisdictions. Acquisition target archetype: precision-fermentation platforms with cell-cultured protein applications. Signal to watch: REACH registration cost escalation forcing small-scale European artisan exits.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Acquisition | Refrigerated last-mile networks in Austin and Los Angeles secure unpasteurized product viability. |
| Strain Library Licensing Agreement | Exclusive Lactobacillus casei Shirota access from Yakult Honsha blocks competitor formulation pathways. |
| Direct-to-Consumer Channel Launch | Subscription models in Vermont and Oregon bypass distributor markups for artisan kefir producers. |
| Precision-Fermentation Platform Investment | Cell-cultured dairy proteins from Eindhoven startups decouple supply from livestock volatility. |
| Practitioner-Channel Certification Program | TGA-compliant strain documentation unlocks 40-60% pricing premiums in Sydney functional medicine clinics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation facility managers, cold-chain logistics operators, regulatory affairs specialists at EFSA and FDA, and functional medicine practitioners with secondary validation. Customs records for kimchi and kefir trade flows, EFSA novel-food submission databases, MFDS certification registries, and SEC filings from listed dairy conglomerates anchored supply-side estimates. Bottom-up capacity counts and top-down consumption surveys were triangulated against cold-chain infrastructure investment disclosures.
Segment-weighting approaches modeled product type, application, distribution channel, and customer type dimensions across the analysis window. Kefir and kombucha growth trajectories were derived from refrigerated aisle expansion rates and practitioner-channel prescription volumes. CAGRs incorporated EFSA health claim restriction impacts on reformulation costs and FDA GRAS notification timeline assumptions for novel probiotic strains.
Inputs from EFSA submission databases and MFDS certification records were available through the study window; gaps in small-scale artisan producer financial disclosures introduce uncertainty bands around margin estimates. Forecasts reflect assumptions on cold-chain infrastructure buildout rates and regulatory harmonization progress. Practitioners should monitor REACH registration cost trajectories and precision-fermentation yield improvements for early signals of competitive displacement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Fruit Water Market
Beverages
China Orange Juice Market
Beverages
Water Flavor Market
Beverages
Hot Cocoa Mix Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
Premium Water Market
Beverages
Ready to Drink Margarita Market
Beverages
North America Energy Drink Market
Beverages
Botanical Infused Beverages Market
Beverages
Packaged Natural Mineral Water Market
Beverages
North America Cold Pressed Juices Market
Beverages
Canned Beverages Market
Beverages
Hydrogen Water Dispenser Market
Beverages
Kvass Market
Beverages
Reconstituted Juice Market
Beverages
Popping Bobas Market