
 Flavor and Flavor Enhancers Market | 2026-2036
Flavor and Flavor Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
Flavor and Flavor Enhancers Market Foresight
Subscription-based flavor formulation services is repositioning how mid-sized food manufacturers access custom taste profiles without maintaining in-house labs. Kerry Group leverages its integrated taste and nutrition platform to anchor long-term supply contracts with global beverage brands. Givaudan sustains R&D intensity through dedicated biotechnology centers that engineer microbial-derived flavor molecules.
Flavor and flavor enhancers comprise volatile aromatic compounds, taste-active molecules, and modulators synthesized through extraction, fermentation, or chemical processes to deliver or intensify sensory perception in finished foods. Natural flavors, derived from plant and animal sources via distillation or enzymatic treatment, command premium positioning as clean-label demand hardens across retail channels. The application split shows beverages and dairy alternatives absorbing disproportionate innovation investment, while confectionery and meat products retain mature, cost-optimized supply relationships with flavor houses.
The FDA governs flavor ingredient safety through GRAS determinations and food additive petitions, while the EMA and EFSA coordinate on novel extraction solvent approvals and allergen labeling thresholds that directly shape product development pipelines for European export. China's SAMR enforces GB standards on synthetic flavor limits in processed foods, forcing reformulation for brands serving both domestic and international markets. Stakeholders must monitor divergence between regional maximum permissible levels for key enhancers and build modular formulation platforms that adapt to jurisdiction-specific compliance without duplicating entire product lines.
Market Dynamics
Clean-label mandates are compressing synthetic flavor margins while biotechnology-derived alternatives capture formulation budgets across beverage and dairy verticals.
Growth Catalysts
- EU Green Deal solvent restrictions:The F-Gas Regulation and REACH amendments are forcing flavor houses to invest in supercritical CO2 extraction infrastructure, accelerating natural flavor capacity expansion.
- China's premium beverage segment:Domestic manufacturers scaling functional drink lines are pulling high-intensity natural flavor volumes from international suppliers.
- Precision fermentation platforms:Microbial-derived aromatic molecules now match organoleptic profiles of plant extracts at substantially lower agricultural land intensity.
Market Restraints
- Vanillin feedstock volatility:Guaiacol and lignin supply disruptions from Brazilian pulp mill concentration transmit directly to vanilla flavor cost structures.
- Extraction solvent approval timelines:EMA novel solvent petitions average 18-24 months, freezing formulation pipelines for European export products.
- Natural flavor yield limitations:Agricultural sourcing for citrus and mint extracts faces climate-driven harvest variability that synthetic alternatives bypass.
Strategic Opportunities
- India's processed food acceleration:FSSAI enforcement of stricter additive labeling is creating first-mover advantage for natural flavor positioning in snack and convenience categories.
- Cell-cultured meat flavor systems:Fat mimetic and Maillard reaction modulators represent uncaptured formulation white space as cultivated protein scales toward commercial volumes.
- Subscription formulation services:Mid-sized manufacturers without captive R&D are outsourcing taste profile development through recurring service contracts rather than spot ingredient purchasing.
Industry Challenges
- Flavor chemist talent scarcity:Cross-disciplinary expertise spanning analytical chemistry, sensory science, and food safety auditing commands premium compensation and extended recruitment cycles.
- Modular compliance architecture:Divergent maximum permissible levels for enhancers like MSG and nucleotides across FDA, EFSA, and SAMR jurisdictions force redundant testing protocols.
- Biotechnology IP fragmentation:Microbial strain patents and enzyme production licenses are distributed across academic institutions and venture-backed startups, complicating freedom-to-operate assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavor and Flavor Enhancers Market |
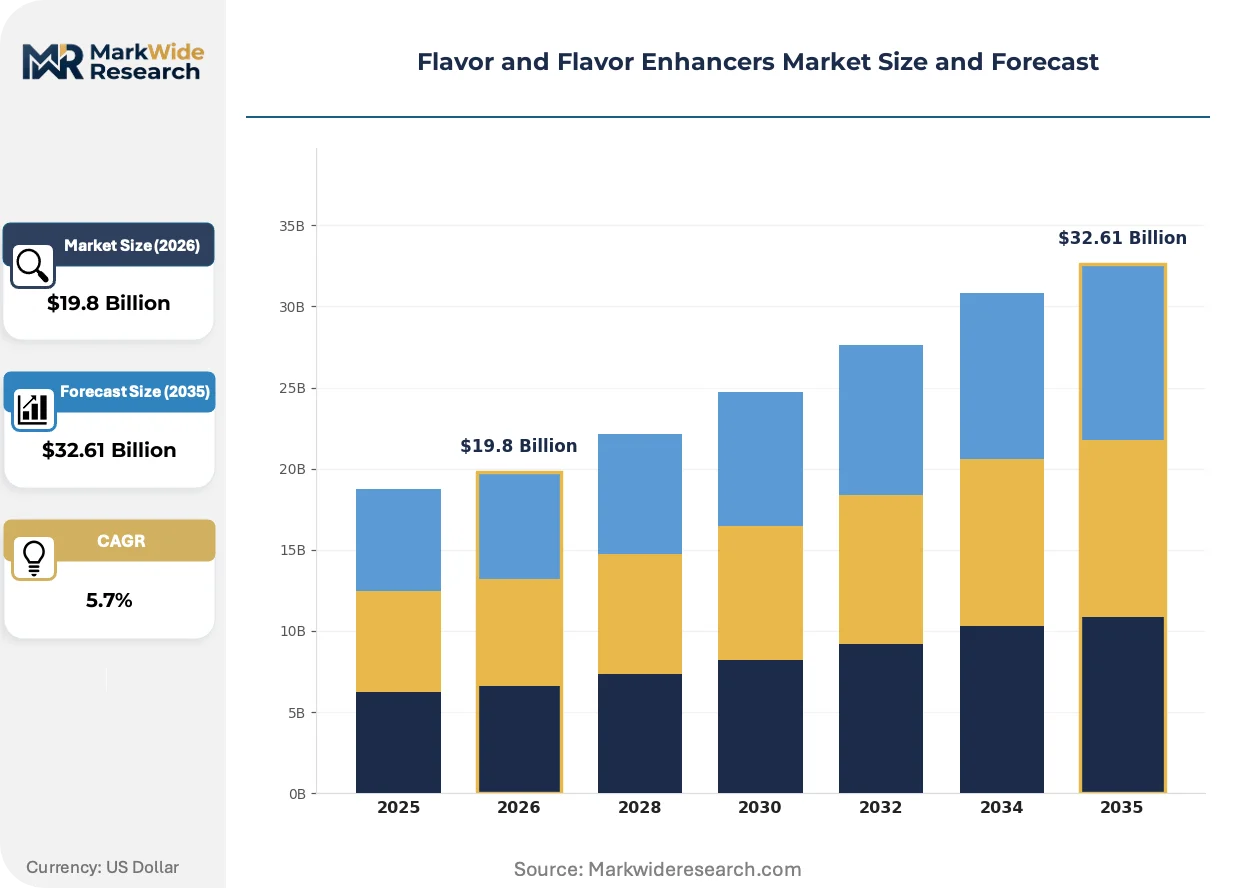
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $32.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Nature-Identical Flavors, Flavor Enhancers, Umami Agents, Sweeteners Application: Beverages, Confectionery, Bakery Products, Dairy Alternatives, Snacks, Meat Products End User: Food Manufacturers, Beverage Producers, Flavor Houses, Snack Producers, Meat Processors, Dairy Processors Form: Liquid, Powder, Gel, Spray-Dried, Paste, Granules |
| Companies Covered | Kerry Group, Firmenich, International Flavors & Fragrances, DSM-Firmenich, Corbion, Givaudan, Symrise, Sensient Technologies, Ajinomoto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavor and Flavor Enhancers Market Shifts & Advancements
Biotechnology is displacing agricultural extraction as the dominant production modality for high-value aromatic compounds, while regulatory chemistry restrictions reshape capital deployment patterns.
Precision fermentation for flavor molecules is absorbing venture funding and technical talent previously directed toward synthetic chemistry infrastructure. Beverage multinationals are integrating fermented-derived naturals into flagship product lines within 18-month formulation cycles. This shift is compressing reliance on tropical agricultural supply chains and associated climate exposure.
The EU F-Gas Regulation and REACH solvent restrictions are eliminating conventional extraction chemistries from European flavor house operations. Manufacturers are retrofitting facilities with supercritical fluid and molecular distillation equipment at substantial capital cost. Dairy alternative and plant-based meat segments face the steepest compliance burden given their dependence on complex lipid-soluble flavor systems.
Direct formulation partnerships between flavor houses and mid-sized food manufacturers are displacing traditional distributor-mediated ingredient purchasing. Subscription-based access to custom taste profiles and rapid prototyping services is consolidating procurement relationships around integrated taste-and-nutrition platforms. This pattern is most visible in North American and Western European markets where in-house R&D headcount constraints are most acute.
Flavor and Flavor Enhancers Market Segmentation
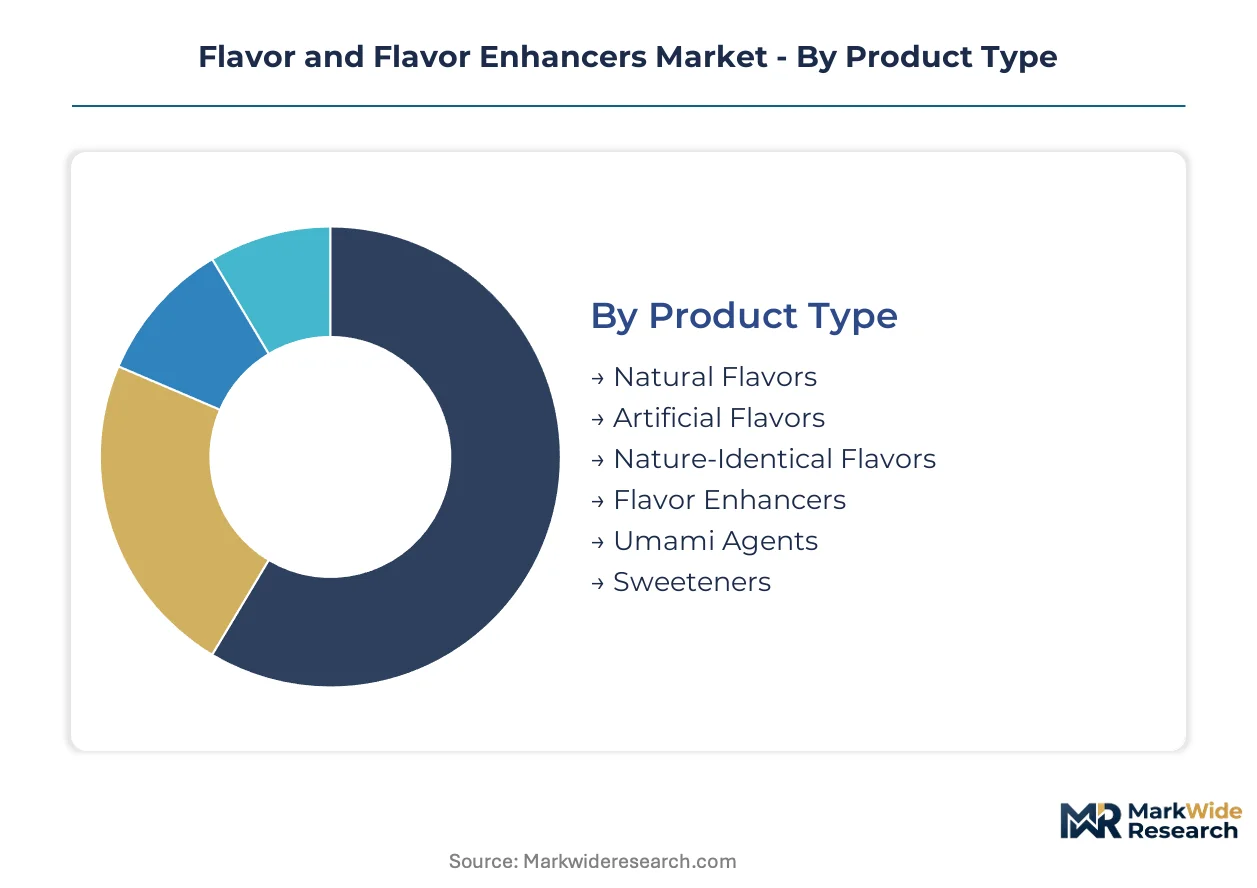
Flavor and flavor enhancers segment across molecular origin, delivery format, and downstream processing requirements. Each axis carries distinct regulatory footprints and capital intensity profiles that reshape supplier economics.
Product Type:
Biotechnology platforms and extraction chemistry specifications determine margin structures and compliance burdens across molecular categories.
- Natural Flavors:Compounds derived via steam distillation, enzymatic treatment, or supercritical CO2 extraction from botanical and animal sources. Beverage multinationals in the United States and Western Europe are locking in long-term supply contracts as FDA and EFSA labeling thresholds harden.
- Artificial Flavors:Chemically synthesized aromatic molecules engineered for cost stability and intensity consistency. Synthetic vanillin and ethyl maltol production concentrates in Chinese and Indian chemical manufacturing clusters facing SAMR and FSSAI additive limits.
- Nature-Identical Flavors:Molecularly identical to natural counterparts but produced through chemical synthesis rather than extraction. Mid-tier confectionery manufacturers favor these for price-stable reformulation when natural supply tightens.
- Flavor Enhancers:Mono-sodium glutamate, nucleotides, and yeast extracts that amplify existing taste perception without contributing distinct aroma. Asian processed food sectors absorb the highest volumes, with China's SAMR enforcing strict maximum permissible levels in infant and specialty foods.
- Umami Agents:Purified glutamates, nucleotide blends, and hydrolyzed vegetable proteins delivering savory depth. Japanese and South Korean instant noodle and soup manufacturers drive formulation innovation.
- Sweeteners:High-intensity compounds including steviol glycosides, sucralose, and aspartame that provide sweetness with reduced caloric load. Sugar taxation in the United Kingdom, France, and Mexico accelerates substitution in carbonated and still beverages.
Natural flavors lead on scale; umami agents lead on momentum across Asian convenience food expansion.
Application:
End-use processing temperatures, pH stability requirements, and shelf-life demands dictate flavor carrier selection and encapsulation investment.
- Beverages:Water-soluble liquid and spray-dried formats dominate, with clean-label natural citrus and berry extracts absorbing disproportionate R&D spend. Carbonated soft drink and functional drink lines in China and Brazil pull high-intensity natural volumes.
- Confectionery:Heat-stable encapsulated flavors and acid-resistant systems for hard candy and chewing gum. European Union REACH solvent restrictions force reformulation of traditional chocolate and fruit flavor profiles.
- Bakery Products:Oven-stable volatile compounds and Maillard reaction modulators that survive thermal processing. Artisan and industrial bakeries in Germany, Italy, and the United States drive demand for natural vanilla and butter alternatives.
- Dairy Alternatives:Masking systems for plant protein off-notes combined with creamy mouthfeel enhancers. Oat, almond, and soy milk processors require lipid-soluble flavor systems facing the steepest EU F-Gas Regulation compliance costs.
- Snacks:Savory seasoning blends and topical flavor coatings for extruded and fried products. India's FSSAI enforcement of stricter additive labeling creates first-mover positioning for natural flavor suppliers.
- Meat Products:Smoke, cure, and savory depth systems for processed and cultured protein applications. Cell-cultured meat scaling in the United States and Netherlands generates uncaptured demand for fat mimetic and browning reaction modulators.
Beverages lead on scale; dairy alternatives expand most quickly on plant-based protein proliferation.
End User:
Captive R&D capacity and formulation autonomy determine whether procurement flows through integrated platforms or distributor-mediated spot purchasing.
- Food Manufacturers:Diversified processed food conglomerates with internal sensory labs and regulatory affairs teams. These buyers negotiate direct formulation partnerships with Givaudan, Firmenich, and IFF for proprietary taste profiles.
- Beverage Producers:Carbonated, functional, and alcoholic drink specialists requiring rapid flavor rotation and seasonal limited editions. Subscription-based formulation services are consolidating procurement relationships among mid-sized players lacking captive R&D.
- Flavor Houses:Specialized ingredient suppliers offering custom compounding, regulatory dossier preparation, and sensory validation. These firms anchor long-term supply contracts through integrated taste-and-nutrition platforms.
- Snack Producers:Extruded, fried, and baked snack specialists with high-volume, low-margin procurement profiles. Cost-optimized artificial and nature-identical systems dominate outside premium positioning.
- Meat Processors:Traditional slaughter and further-processing operations alongside emerging cultivated protein ventures. Cell-cultured meat commercialization in Singapore, the United States, and Israel pulls novel flavor system development.
- Dairy Processors:Fluid milk, cheese, yogurt, and ice cream manufacturers with stringent microbiological and labeling requirements. Clean-label natural positioning accelerates across European and North American premium lines.
Food manufacturers lead on scale; beverage producers lead on momentum through direct formulation partnerships.
Form:
Physical state determines stability, dosing precision, and compatibility with downstream processing equipment.
- Liquid:Solvent-based or aqueous solutions offering easy incorporation into mixing tanks and beverage bases. Standard format for high-volume beverage and sauce applications.
- Powder:Spray-dried or plated carriers enabling extended shelf life and dry blending compatibility. Dominant in seasoning blends, bakery mixes, and powdered drink applications.
- Gel:Concentrated matrices for controlled release and topical application in confectionery and meat injection systems.
- Spray-Dried:Encapsulated volatiles protected against oxidation and moisture, essential for heat-sensitive aromatic compounds in coffee and tea extracts.
- Paste:High-viscosity formats for incorporation into doughs, batters, and emulsified meat systems where uniform distribution challenges powder dispersion.
- Granules:Free-flowing agglomerated particles for topical seasoning application on snacks and ready-to-eat cereals.
Liquid leads on scale; spray-dried leads on momentum through encapsulation technology advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's premium beverage expansion absorbs natural flavor volumes at a scale Germany's dairy alternative processors cannot match, while regulatory chemistry restrictions in both markets reshape capital deployment patterns for extraction infrastructure.
United States
Beverage multinationals in Atlanta and Chicago are locking in long-term supply contracts for natural citrus and berry extracts as FDA labeling thresholds harden. The FDA's GRAS determination process governs novel flavor ingredient approvals, creating compliance lead times that favor established supplier relationships. California's Central Valley agricultural clusters supply mint and citrus feedstocks facing climate-driven harvest variability.
Germany
Dairy alternative processors in Hamburg and Cologne require lipid-soluble flavor systems facing the steepest EU F-Gas Regulation compliance costs. ECHA's REACH amendments are eliminating conventional extraction chemistries, forcing retrofit investments in supercritical CO2 infrastructure. Bavaria's industrial food manufacturing corridor concentrates reformulation demand for clean-label natural positioning.
China
Domestic functional drink manufacturers in Shanghai and Guangzhou are pulling high-intensity natural flavor volumes from international suppliers at unprecedented scale. SAMR enforces GB standards on synthetic flavor limits in processed foods, forcing dual-formulation strategies for export-oriented brands. The Yangtze River Delta anchors biotechnology-derived flavor molecule production through precision fermentation platforms.
India
FSSAI enforcement of stricter additive labeling is creating first-mover advantage for natural flavor positioning in Mumbai and Delhi snack manufacturing corridors. The regulator's maximum permissible level divergence from FDA and EFSA standards forces modular compliance architecture. Gujarat's processed food acceleration concentrates demand for cost-optimized nature-identical systems alongside premium natural extracts.
Brazil
Guaiacol and lignin supply disruptions from São Paulo state pulp mill concentration transmit directly to vanilla flavor cost structures for confectionery manufacturers. ANVISA's additive approval timelines lag FDA and EFSA by 12-18 months, freezing reformulation pipelines for export products. The São Paulo-Rio de Janeiro industrial corridor dominates South American flavor house distribution relationships.
Flavor and Flavor Enhancers Market Competitive Landscape
Top-tier vendors anchor integrated taste-and-nutrition platforms, while mid-sized specialists occupy formulation service and regional supply niches. The vendor base concentrates around biotechnology-derived production capabilities and supercritical extraction infrastructure investments. Three archetypes dominate: integrated nutrition-taste conglomerates, precision fermentation biotechnology specialists, and regional flavor compounding houses. Competitive moves center on direct formulation partnerships with beverage multinationals and subscription-based access models for mid-sized manufacturers lacking captive R&D.
Within the integrated platform tier, Kerry Group and Givaudan exemplify archetypes combining captive biotechnology infrastructure with long-term supply contract anchoring. Sensient Technologies occupies a position representing North American regional compounding specialization. These three entities sit within distinct strategic vectors: Kerry Group exemplifies nutrition-taste integration, Givaudan represents microbial-derived molecule engineering intensity, and Sensient Technologies anchors mid-market rapid prototyping services.
| Leading Market Players |
|---|
| Kerry Group |
| Firmenich |
| International Flavors & Fragrances |
| DSM-Firmenich |
| Corbion |
| Givaudan |
| Symrise |
| Sensient Technologies |
| Ajinomoto |
| Others |
Supply & Pricing Matrix
Captive biotechnology infrastructure anchors both supply security and pricing power for flavor houses serving beverage multinationals. Supercritical CO2 extraction investments in Germany and precision fermentation platforms in China create divergent cost structures that reshape competitive positioning across natural flavor tiers.
Pricing Analysis
Capacity additions in China are reshaping price floors for synthetic vanillin and ethyl maltol as domestic chemical clusters expand output. Three-tier pricing structure across premium natural extracts, standard nature-identical compounds, and economy artificial systems dominates procurement negotiations. Cost compression in the artificial tier is intensifying because Brazilian pulp mill concentration transmits guaiacol supply volatility directly to vanilla flavor cost structures. Snack producers in India exhibit the highest price sensitivity, while beverage multinationals in the United States and Western Europe absorb premium natural extract premiums with limited volume pushback.
Supply Chain Analysis
EU F-Gas Regulation and REACH solvent qualification requirements are gating facility retrofits and freezing conventional extraction chemistries from European flavor house operations. Supply concentrates in China, India, and Germany, with Yangtze River Delta biotechnology platforms, Gujarat chemical manufacturing clusters, and Bavaria supercritical extraction facilities anchoring regional output. Raw material dependencies span Brazilian guaiacol and lignin for vanillin, Indian mentha arvensis for mint extracts, and citrus peel oils from California and Sicily. Single-source vulnerability runs through Brazilian pulp mill concentration for vanilla precursors. Distribution runs through direct formulation partnerships with beverage multinationals and subscription-based service contracts with mid-sized manufacturers lacking captive R&D.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU F-Gas Regulation compliance costs in Germany and SAMR synthetic flavor limits in China creates divergent formulation economics that favor modular production footprints. Regulatory chemistry restrictions in Europe compress margins for lipid-soluble flavor systems while China's premium beverage pull rewards natural extract capacity.
For Market Incumbents: Lock in long-term supply contracts with global beverage brands through integrated taste-and-nutrition platforms before precision fermentation specialists capture formulation budgets. Anchor backward integration into microbial strain development to defend against biotechnology IP fragmentation. Expand supercritical CO2 capacity in European facilities to meet EU Green Deal solvent restrictions without surrendering dairy alternative market share. For New Entrants and Emerging Players: The price-point gap between premium natural extracts and economy artificial systems in India's snack manufacturing corridor offers white-space entry. Target FSSAI enforcement of stricter additive labeling as the most penetrable regulatory trigger. Pursue subscription-based formulation services as the go-to-market angle, offering rapid prototyping to mid-sized manufacturers lacking captive sensory labs. For Investors and Strategic Acquirers: Consolidation pressure builds where biotechnology IP fragmentation complicates freedom-to-operate assessments for microbial-derived flavor molecules. Long-term viability favors platforms combining precision fermentation capabilities with direct formulation partnerships. Acquire precision fermentation specialists with validated strain libraries. Watch EMA novel solvent petition timelines as the inflection indicator for European natural flavor capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial-derived aromatic molecules bypass agricultural climate exposure and EU extraction solvent restrictions. |
| Supercritical CO2 Infrastructure Retrofit | European flavor houses meet F-Gas Regulation compliance without abandoning lipid-soluble dairy alternative systems. |
| Direct Formulation Partnership | Beverage multinationals lock in proprietary taste profiles through integrated taste-and-nutrition platforms. |
| Subscription Service Launch | Mid-sized manufacturers access custom prototyping without maintaining captive R&D headcount. |
| Biotechnology IP Consolidation | Freedom-to-operate clarity emerges from unified microbial strain patent and enzyme license portfolios. |
Research Methodology
Multiple input streams — executive interviews with flavor house R&D directors, procurement leads at beverage multinationals, and regulatory affairs specialists — were reconciled against secondary validation from FDA GRAS filings, EFSA novel food opinions, SAMR GB standards, and customs trade data. Bottom-up triangulation across molecular origin segments and top-down cross-reference against end-use application demand produced volume and value estimates. Sensory science directors, food safety auditing consultants, and distribution channel partners provided operational context on formulation pipeline constraints.
Historical shipment data were cross-referenced against panel input from biotechnology platform operators and supercritical extraction equipment suppliers. Segmentation modeling spanned molecular origin, delivery format, downstream processing requirements, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections across the analysis window. Forecast inputs incorporated precision fermentation yield improvement curves and EU solvent restriction compliance cost trajectories.
The model assumes a particular technology adoption path; alternative pathways for microbial-derived flavor molecules would alter the outlook. Forecasts reflect assumptions regarding SAMR enforcement intensity and EMA novel solvent approval timelines. A model refresh is warranted upon material change in EU Green Deal chemistry restrictions or breakthrough precision fermentation scale economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
Bergamot Extract Market
Flavorings and Food Additives
Japan Food Flavor and Enhancer Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Global Syrup Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
Flavoring Oil Market
Flavorings and Food Additives
Asia-Pacific Food Colorants Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
Global Floral Flavors Market
Flavorings and Food Additives
Liquid Flavors Market