
 Water Bottle Market | 2026-2036
Water Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Water Bottle Market Intelligence
Specialized polymer engineering talent is unwinding as universities scale back materials science programs, forcing manufacturers to automate or outsource compound development. CamelBak leverages its military and outdoor heritage to sustain premium positioning in tactical and adventure channels. Hydro Flask anchors the insulated stainless steel category through proprietary TempShield technology and colorway exclusivity. Nalgene competes on polycarbonate durability and laboratory-grade credibility, occupying a defensible niche in institutional and educational procurement.
A water bottle is a portable, sealed vessel engineered for repeated personal hydration, typically constructed from food-grade polymers, austenitic stainless steel, borosilicate glass, or anodized aluminum with thermal insulation ratings spanning 12 to 24 hours. Stainless steel vacuum flasks command the highest unit margins due to copper-lined double-wall construction and powder-coat finishing complexity. Plastic sports bottles retain volume leadership in mass retail but face margin compression from resin volatility and sustainability mandates. Glass and aluminum alternatives are gaining shelf space in European and North American premium channels where EFSA compliance and REACH substance restrictions elevate material transparency as a purchase trigger.
FDA food-contact substance regulations, EU REACH chemical restrictions, and California Proposition 65 labeling requirements collectively constrain polymer selection and migration testing protocols for all brands accessing US and European retail. China's GB standards for food-contact materials and Japan's Food Sanitation Law add parallel compliance layers for Asia-Pacific manufacturing and export. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and state-level plastic reduction statutes across the United States to anticipate material transition costs and channel reconfiguration timelines.
Market Dynamics
Material substitution mandates from the FDA and EFSA are forcing rapid retooling across polymer-dependent supply chains, while specialized engineering talent scarcity compounds automation urgency.
Growth Catalysts
- EFSA BPA restrictions:Migration limits on polycarbonate food-contact materials are redirecting R&D budgets toward stainless steel and glass innovation pipelines.
- Gen Z fitness culture:Gym membership density in urban China and the United States is expanding demand for portable hydration with integrated tracking features.
- Copper vacuum insulation:Double-wall manufacturing advances are extending thermal retention windows, enabling premium positioning in outdoor recreation channels.
Market Restraints
- Resin cost volatility:Petroleum-derived polymer feedstock fluctuations compress margins for mass-market plastic bottle producers without long-term supply contracts.
- GB standards compliance:China's evolving food-contact material testing protocols create export friction for manufacturers lacking in-country certification infrastructure.
- Glass fragility:Transportation breakage rates and weight penalties limit aluminum and borosilicate alternatives to premium urban retail channels.
Strategic Opportunities
- EU extended producer responsibility:Packaging waste directives in Germany and France are creating first-mover advantage for refillable and returnable bottle systems.
- Smart hydration convergence:Integration of UV-C purification with Bluetooth consumption tracking opens enterprise wellness contracting.
- India organized retail expansion:Modern trade penetration in Mumbai and Bangalore corridors is building branded bottle visibility beyond traditional general trade.
Industry Challenges
- Materials science talent pipeline:University program contraction in polymer engineering forces reliance on automated compound formulation or outsourced development partnerships.
- REACH substance authorization timelines:ECHA screening processes for novel coatings and additives extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Bottle Market |
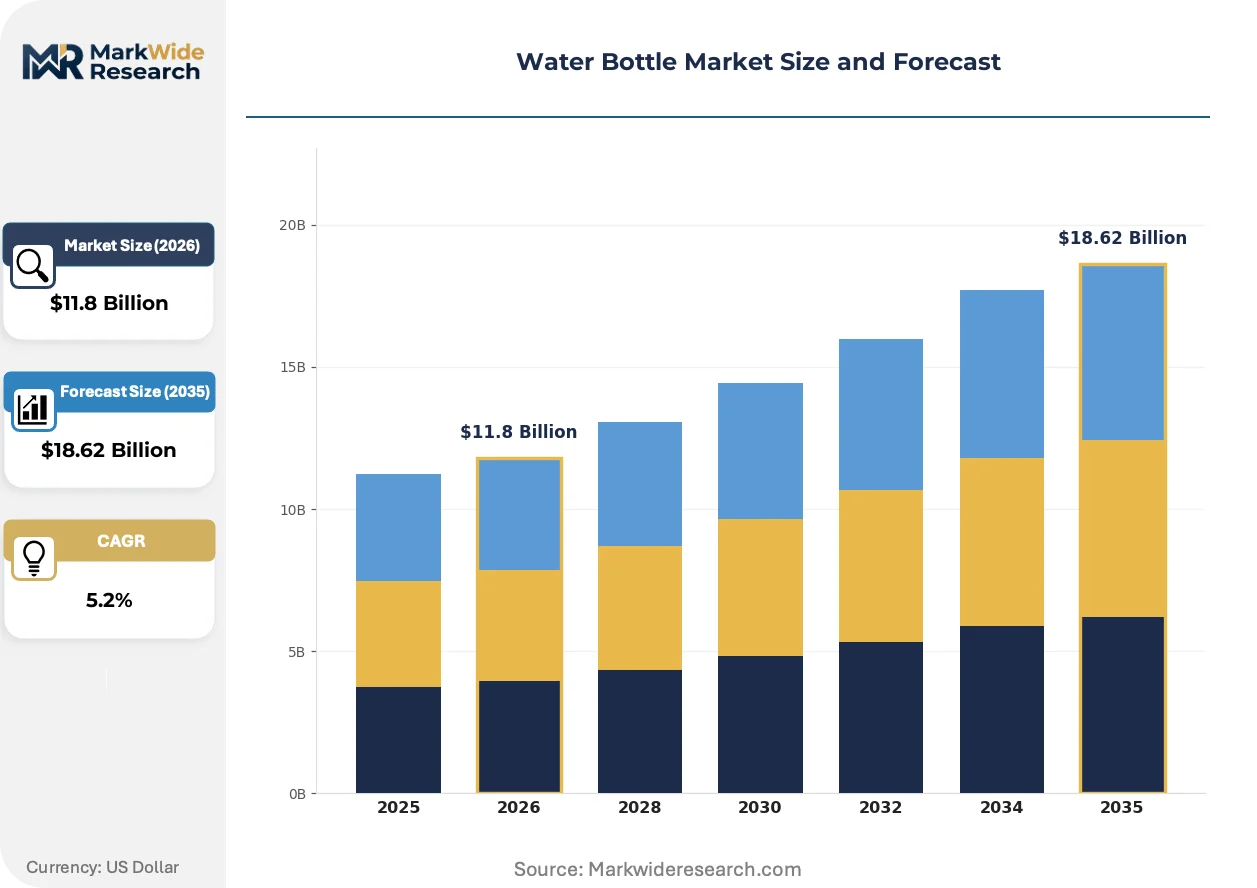
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.62 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Stainless Steel, Glass, Aluminum Product Type: Sports Bottles, Vacuum Flasks, Kids Bottles, Travel Mugs Cap Type: Screw Cap, Flip Top, Straw Cap, Spout Cap Usage: Gym, Hiking, Everyday Use, Camping |
| Companies Covered | CamelBak, Klean Kanteen, Thermos L.L.C., Contigo, S'well, Tupperware Brands Corporation, Nalgene, Zojirushi Corporation, Hydro Flask, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Bottle Market Strategic Shifts & Innovations
Active material science and regulatory chemistry are compressing traditional polymer dominance while digital integration redefines hydration hardware value propositions.
Vacuum insulation technology is miniaturizing through thinner copper deposition layers and laser-welded seam construction. Adventure travel and commuter segments in the United States and Japan are adopting these lighter thermal vessels at replacement rates exceeding conventional single-wall bottles. The structural consequence is margin compression for legacy aluminum and uninsulated steel producers unable to fund retooling.
REACH substance restrictions and California Proposition 65 enforcement are eliminating phthalate plasticizers and certain epoxy coatings from food-contact applications. Manufacturers serving European and North American retail must now maintain parallel material certification streams or abandon polymer-dependent SKUs entirely. Laboratory-grade polycarbonate bottles face the steepest compliance cost escalation.
Bulk procurement through corporate wellness programs and athletic team contracts is displacing individual retail purchasing for premium insulated categories. Human resources departments and sports federations in Germany, Australia, and South Korea now specify BPA-free certification and end-of-life recyclability as mandatory vendor criteria. This concentrates volume with suppliers possessing multi-standard compliance documentation.
Water Bottle Market Segmentation
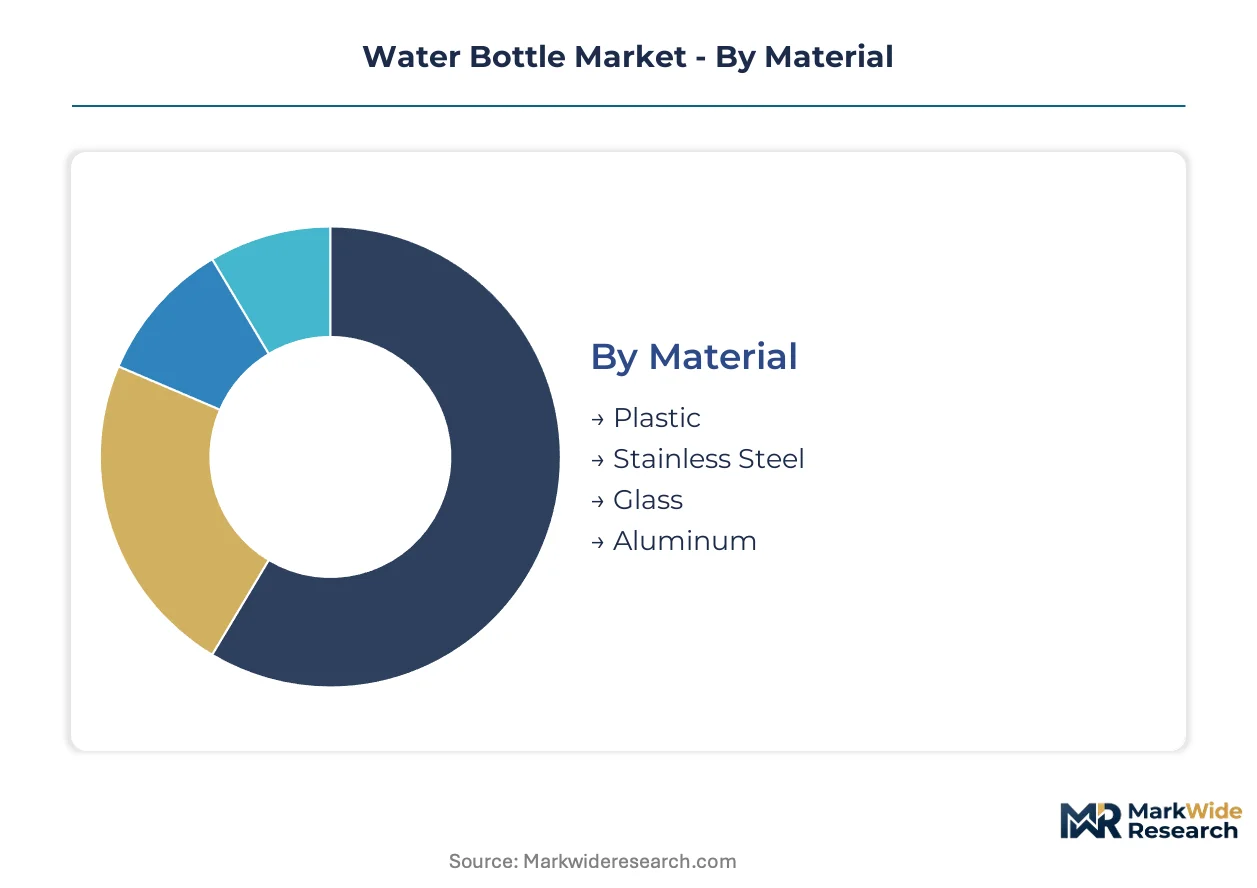
Material composition and cap mechanism determine channel placement and margin structure across the water bottle market. Product type and usage occasion further segment demand between mass retail, specialty outdoor, and institutional procurement channels.
Material:
Plastic bottles flow through mass retail and promotional channels, while stainless steel and glass alternatives concentrate in premium outdoor and wellness-focused e-commerce platforms.
- Plastic:Food-grade polymers including Tritan copolyester and polypropylene dominate unit volume through supermarket and big-box retail. FDA and EFSA migration testing mandates are elevating compliance costs for polycarbonate variants, compressing margins for producers without compound certification infrastructure.
- Stainless Steel:Austenitic grades with copper-lined double-wall vacuum construction command premium positioning in outdoor recreation and corporate gifting channels. Germany, Japan, and the United States represent concentrated demand for thermal retention ratings exceeding 12 hours.
- Glass:Borosilicate vessels with silicone sleeves occupy premium urban retail in European cities where REACH substance transparency drives purchase decisions. Weight and fragility constrain distribution to direct-to-consumer and specialty channels.
- Aluminum:Anodized single-wall construction serves cycling and adventure segments requiring lightweight durability. REACH restrictions on certain anodization chemistries limit European market access for uncertified producers.
By volume, plastic leads. By growth pace, stainless steel is expanding most quickly.
Product Type:
Margin structure varies sharply: vacuum flasks and travel mugs sustain premium pricing, while kids bottles compete on safety certification and licensed character partnerships.
- Sports Bottles:Single-wall and insulated variants with integrated carry loops and measurement markers serve gym and athletic team procurement. Gen Z fitness culture in urban China and the United States is concentrating demand for bottles with Bluetooth-enabled consumption tracking.
- Vacuum Flasks:Double-wall copper deposition technology extends thermal windows to 24 hours, enabling positioning in commuter and outdoor adventure channels. Japanese and German consumers demonstrate highest willingness-to-pay for laser-welded seam construction and powder-coat finish durability.
- Kids Bottles:BPA-free certification and spill-proof straw mechanisms dominate parental purchase criteria. School district procurement in the United States and nursery chain specifications in the United Kingdom require third-party safety testing documentation.
- Travel Mugs:Automotive cup-holder compatibility and one-handed operation features target commuter segments. Corporate wellness programs in South Korea and Australia specify leak-proof guarantees and end-of-life recyclability as mandatory vendor criteria.
By volume, sports bottles lead. By margin expansion, vacuum flasks are climbing the fastest.
Cap Type:
Closure complexity correlates with replacement part revenue and brand loyalty, with straw and spout mechanisms generating recurring accessory sales.
- Screw Cap:Standard threaded closures dominate institutional and promotional bottle procurement due to cost efficiency and universal compatibility. Laboratory and educational settings in the United States specify Nalgene-style wide-mouth screw caps for cleaning accessibility.
- Flip Top:Hinged lids with locking mechanisms serve cycling and running segments requiring single-handed operation. European consumers prioritize EFSA-compliant silicone gaskets over standard rubber seals.
- Straw Cap:Integrated bite valves and internal straw assemblies target children and convenience-focused everyday users. Replacement straw kits generate recurring revenue for brands with proprietary fitting systems.
- Spout Cap:Narrow pour openings with dust covers dominate hiking and camping channels where contamination prevention matters. Military and tactical procurement specifications in the United States favor spout caps with MOLLE attachment compatibility.
By volume, screw caps lead. By innovation velocity, straw caps are gaining share fastest.
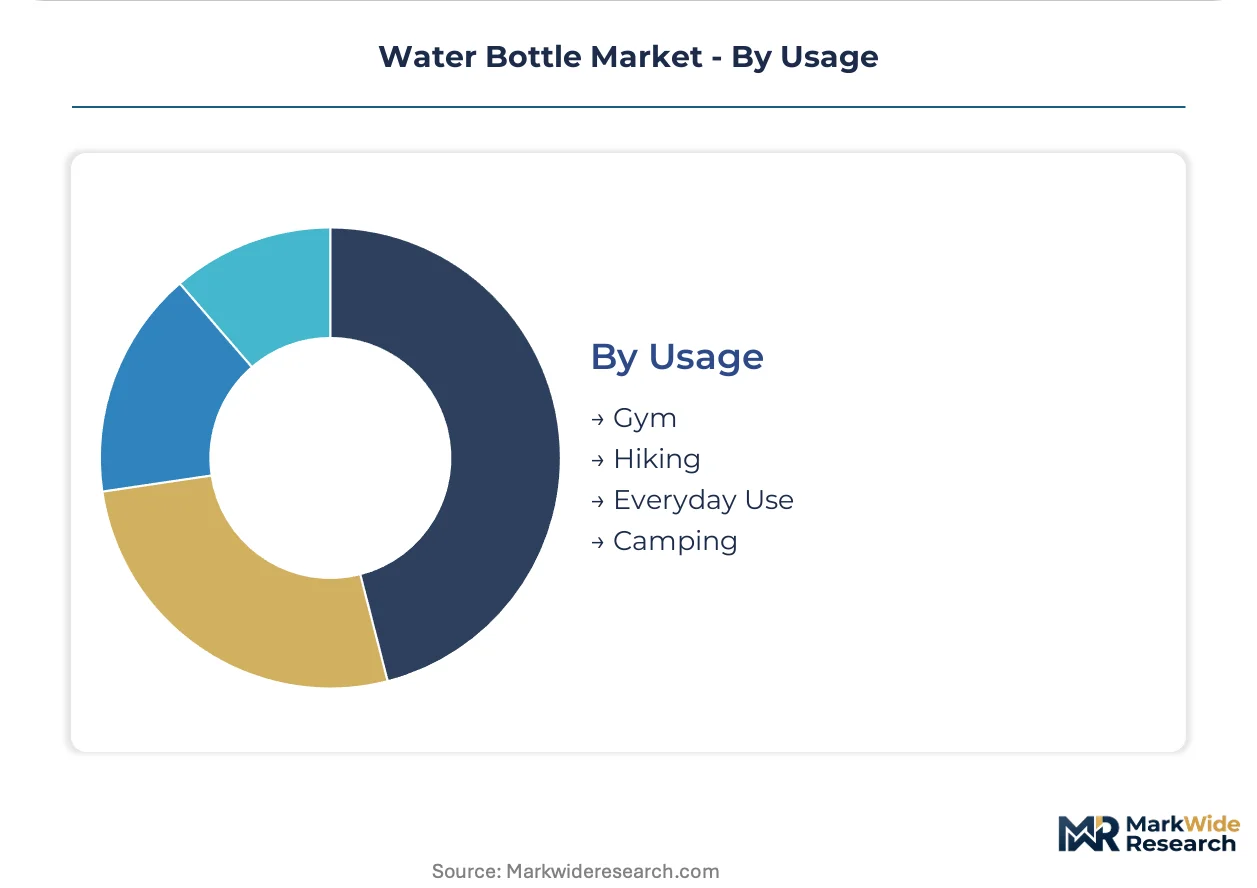
Usage:
Application-specific durability and feature requirements create distinct procurement channels, from disposable promotional gym bottles to heirloom-quality camping vessels.
- Gym:Lightweight single-wall construction with volume markings and shaker-ball compatibility serves fitness center retail and protein supplement bundling. Urban China and United States gym membership density is concentrating demand for integrated tracking features.
- Hiking:Carabiner-compatible loops and filtration-ready wide mouths serve trail and backcountry users. German and Austrian alpine club specifications influence European product development priorities.
- Everyday Use:Aesthetic-driven design and desk-friendly footprints dominate commuter and home office placement. Colorway exclusivity and limited edition collaborations sustain premium pricing in direct-to-consumer channels.
- Camping:Extreme durability and multi-fuel compatibility (stovetop heating) characterize expedition-grade vacuum flasks. Japanese outdoor retailers and United States national park concessionaires represent concentrated distribution for certified bear-resistant designs.
By volume, everyday use leads. By premiumization potential, camping is expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact substance regulations anchor the United States as the dominant geography, while EFSA REACH restrictions and China's GB standards create parallel compliance architectures across manufacturing and retail channels.
United States
Gen Z fitness culture and corporate wellness procurement drive insulated stainless steel adoption. FDA BPA-free mandates and California Proposition 65 labeling requirements constrain polymer selection. Manufacturing concentrates in Pacific Northwest clusters where Hydro Flask and CamelBak anchor outdoor recreation supply chains.
Germany
Extended producer responsibility frameworks and alpine club procurement specifications shape refillable bottle demand. EFSA migration limits and ECHA REACH substance authorizations elevate compliance costs for polycarbonate variants. Production gravity centers on Bavaria and North Rhine-Westphalia where vacuum flask engineering expertise concentrates.
China
Domestic e-commerce distribution and gym membership density in urban corridors expand portable hydration demand. GB standards for food-contact materials and SAMR market supervision create certification friction for export-oriented manufacturers. Yangtze River Delta and Pearl River Delta clusters dominate stainless steel fabrication capacity.
Japan
Commuter culture and outdoor retail channel sophistication sustain premium thermal vessel pricing. Food Sanitation Law and METI industrial standards mandate rigorous migration testing protocols. Kanto and Kansai regions concentrate Zojirushi Corporation and precision manufacturing suppliers.
Australia
Corporate wellness contracting and athletic federation procurement displace individual retail purchasing. TGA-aligned substance safety expectations and state-level plastic reduction statutes elevate material transparency requirements. Procurement concentrates in Sydney and Melbourne corridors where direct-to-consumer brands build visibility.
Water Bottle Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with vacuum insulation technology and multi-standard compliance documentation serving as primary differentiation vectors. The structure bifurcates between mass-market polymer producers facing margin compression and premium stainless steel fabricators capturing enterprise wellness contracts. Archetypes include heritage outdoor brands, laboratory-grade specialists, and thermal engineering houses. Competitive moves concentrate on portfolio diversification toward smart hydration features and geographic expansion through e-commerce platform partnerships.
Within the heritage outdoor tier, CamelBak and Hydro Flask exemplify military and adventure channel positioning. Nalgene occupies a position representing laboratory-grade credibility and institutional procurement defensibility. Zojirushi Corporation anchors precision thermal engineering expertise within Japanese manufacturing tradition. These three sit within distinct archetype boundaries while competing indirectly through channel specialization rather than direct product overlap.
| Leading Market Players |
|---|
| CamelBak |
| Klean Kanteen |
| Thermos L.L.C. |
| Contigo |
| S'well |
| Tupperware Brands Corporation |
| Nalgene |
| Zojirushi Corporation |
| Hydro Flask |
| Others |
Cost & Logistics Intelligence
Stainless steel substitution for polycarbonate is simultaneously relocating production gravity toward Yangtze River Delta fabrication clusters and compressing margin structures for polymer-dependent producers lacking vacuum insulation retooling capital. This material transition rewards integrated metal formers while penalizing resin converters facing FDA and EFSA compliance cost escalation.
Pricing Analysis
Long-term offtake contracts with corporate wellness programs and athletic federation procurement now anchor premium stainless steel pricing, insulating thermal vessel manufacturers from spot resin volatility that erodes mass-market plastic margins. Price differentiation hinges on GB standards certification tier and copper deposition finish complexity, with German and Japanese buyers least sensitive and promotional channel distributors most vulnerable to cost compression. Pricing pressure stems from petroleum-derived polymer feedstock fluctuations, forcing polycarbonate producers toward automated compound formulation or exit.
Supply Chain Analysis
China and Japan anchor stainless steel vacuum flask fabrication, with Germany retaining precision engineering for laser-welded seam construction. Raw material flows draw from Indonesian nickel ore, Australian bauxite, and Chilean copper cathode. Single-source vulnerability concentrates in Yangtze River Delta anodization chemistries facing REACH authorization delays. Distribution runs through Amazon and Tmall e-commerce platforms for direct-to-consumer premium placement, while Costco and REI big-box contracts sustain mass-market volume.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated corporate wellness procurement and athletic federation contracting, fragmenting individual retail influence as volume concentrates with multi-standard compliance documentation holders.
For Market Incumbents: Compound defensive positioning through backward integration into copper deposition equipment and captive GB standards certification infrastructure in Yangtze River Delta clusters. Deepen channel control via exclusive colorway partnerships with REI and MEC outdoor retailers to block private-label encroachment. Prioritize R&D in Bluetooth-enabled consumption tracking to meet Gen Z fitness procurement specifications.
For New Entrants and Emerging Players: Differentiate on smart hydration convergence with UV-C purification modules targeting enterprise wellness white space in South Korea and Australia. The most penetrable entry point sits with refillable bottle systems for EU extended producer responsibility frameworks in Germany and France. Go-to-market leverage runs through direct-to-consumer TikTok Shop launches with influencer-backed sustainability storytelling.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed outdoor heritage brands possessing military procurement relationships but lacking smart hydration R&D pipelines. Long-term viability favors targets with multi-standard compliance documentation spanning FDA, EFSA, and GB protocols. Watch for inflection when EU packaging waste directives trigger mandatory refillable system adoption in Germany and France.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Hydration Integration | Bluetooth consumption tracking opens enterprise wellness contracting with HR departments. |
| EU Refillable System Launch | Extended producer responsibility frameworks in Germany create first-mover structural advantage. |
| Copper Deposition Capacity Expansion | Yangtze River Delta fabrication clusters reduce thermal vessel unit cost through scale. |
| Multi-Standard Certification Investment | Parallel FDA, EFSA, and GB documentation unlocks corporate procurement gatekeeping. |
| Direct-to-Consumer Channel Buildout | TikTok Shop and Amazon Premium placement bypass big-box margin compression. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs records, Nielsen retail audit data, and SEC 10-K filings across the consumer durables sector. Interviews with brand managers at heritage outdoor manufacturers, category buyers at REI and Costco, supply planners at Yangtze River Delta fabrication clusters, and regulatory affairs leads at EFSA-notified bodies informed demand and compliance assumptions. Bottom-up SKU-level volume triangulation against top-down category spend estimates validated market sizing.
Segmentation dimensions modeled span material composition, product type, cap mechanism, and usage occasion across the analysis window. CAGRs derive from regression against gym membership density, corporate wellness program penetration, and e-commerce platform growth curves. Forecast inputs incorporate EFSA migration limit implementation timelines and China GB standards evolution.
Material uncertainties — ECHA REACH authorization delays for novel coatings, resin cost volatility from petroleum feedstock disruption, and EU extended producer responsibility enforcement variance — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification infrastructure buildout and smart hydration adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
North America Fruit Juice Market
Beverages
Beverages Market
Beverages
Citrus Water Market
Beverages
Packaged Coconut Water Market
Beverages
Still Drinks Market
Beverages
Fruit and Vegetable Juice Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
Global Soda Maker Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market
Beverages
Carbonate Drink Maker Market
Beverages
Asia-Pacific Vinegar Market
Beverages
Probiotic Beverage Market
Beverages
Ginger Beer Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
North America Yerba Mate Market
Beverages
Fruit Juice Market