
 Vegetable Juice Market | 2026-2036
Vegetable Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Juice Market Outlook
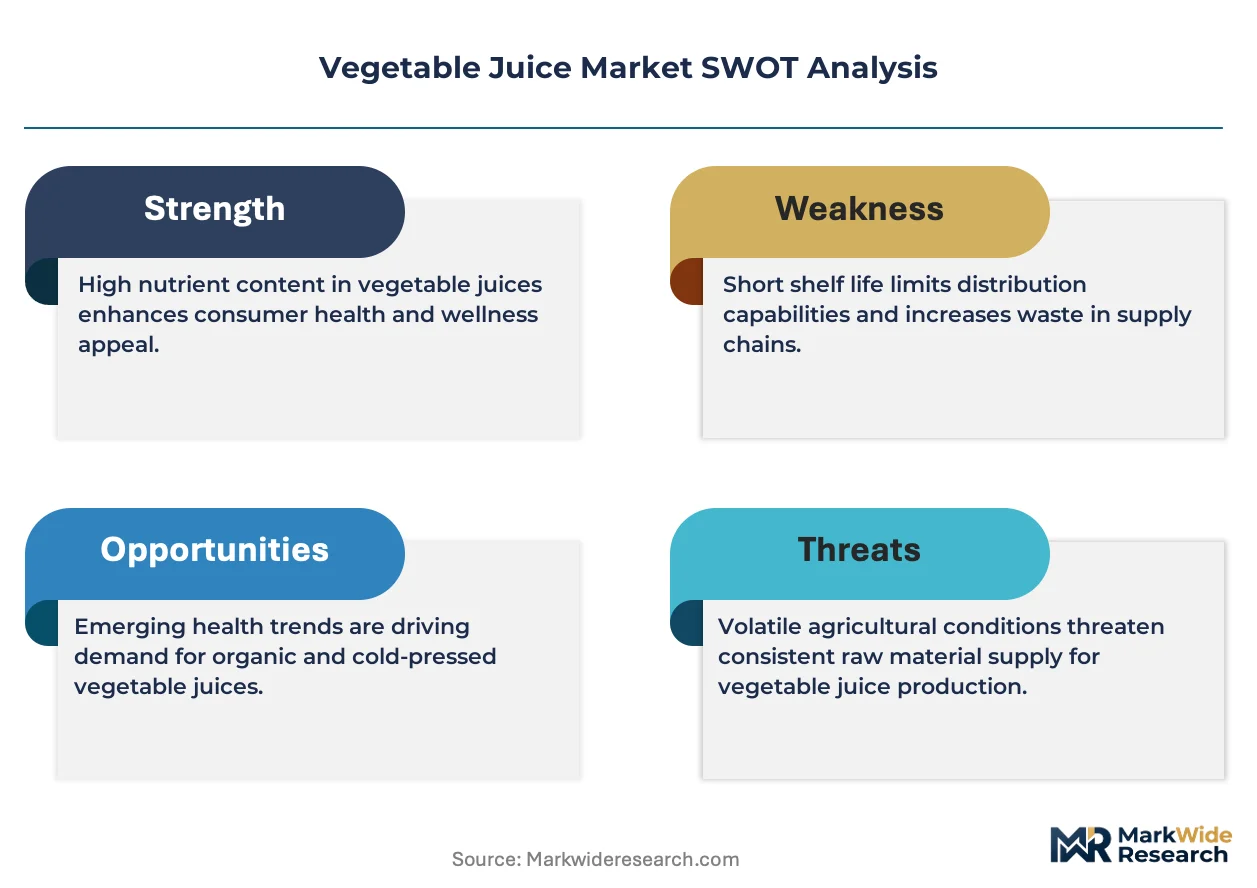
Asset-light contract manufacturing and co-packing arrangements is rewriting competitive entry economics for smaller vegetable juice brands that previously faced prohibitive capital requirements. PepsiCo leverages its global bottling network to sustain cost advantages across shelf-stable and chilled formats. The Kraft Heinz Company anchors its position through deep retail distribution partnerships in North American supermarkets. Bolthouse Farms specializes in premium cold-pressed and organic vegetable blends that command higher price positioning in health stores.
Vegetable juice comprises mechanically or hydraulically extracted liquid from vegetables such as carrot, beet, spinach, and kale, typically processed through cold-pressing or pasteurization to retain vitamins, minerals, and phytonutrients at specified brix levels and pH ranges for shelf stability. The product serves commercial purposes as a functional beverage delivering concentrated vegetable nutrition in ready-to-drink formats for health-oriented consumers. Chilled juice commands premium margins due to shorter shelf life and perceived freshness, while shelf-stable juice dominates volume through supermarket and convenience store channels. Powdered juice represents the fastest-growing format as consumers prioritize portability and reduced shipping weight in online retail.
The FDA enforces juice hazard analysis and critical control points regulations that mandate pathogen reduction treatments, directly shaping manufacturing process investments and product safety protocols for domestic producers. The EU Green Deal and F-Gas Regulation influence refrigeration and cold-chain requirements for chilled juice distribution across European markets. Stakeholders must monitor evolving clean-label enforcement and sugar-reduction mandates to determine reformulation priorities and geographic market access strategies.
Market Dynamics
Clean-label mandates from the FDA and EU are forcing manufacturers to strip additives and reduce sugar content, compressing formulation cycles while elevating capital requirements for processing equipment upgrades across the supply base.
Growth Catalysts
- EU Green Deal refrigeration standards:Chilled juice producers investing in compliant cold-chain infrastructure gain preferential retail placement in European supermarkets.
- Gen Z functional beverage demand:Younger consumers in the United States prioritize nutrient density over taste masking, pulling carrot and beet blends into mainstream convenience channels.
- High-pressure processing (HPP):This non-thermal pasteurization technology extends chilled juice shelf life without nutrient degradation, unlocking broader distribution radius for regional brands.
Market Restraints
- Organic vegetable input volatility:Weather-driven supply fluctuations for kale and spinach concentrate in California's Central Valley, squeezing margin predictability for premium cold-pressed lines.
- FDA juice HACCP compliance costs:Pathogen reduction mandates require dedicated thermal or HPP equipment that smaller co-packers cannot amortize across limited production runs.
- Plant-based milk substitution:Oat and almond beverages capture overlapping health-conscious shelf space in North American retail, constraining vegetable juice facings.
Strategic Opportunities
- India urban wellness corridors:Mumbai and Bangalore cold-pressed juice bars remain underpenetrated relative to population density, offering first-mover positioning before organized retail consolidation.
- CSRD-aligned carbon labeling:Early adoption of EU corporate sustainability reporting standards for supply chain emissions creates differentiation in European premium channels.
- Powder-to-liquid e-commerce formats:Direct-to-consumer subscriptions for dehydrated vegetable blends bypass refrigerated logistics entirely, collapsing last-mile costs.
Industry Challenges
- HACCP validation timelines:FDA facility inspections and process authority approvals stretch 12-18 months, freezing product launches for new market entrants.
- Cold-chain technician scarcity:Refrigeration maintenance expertise concentrates with legacy dairy and meat distributors, forcing juice brands into expensive third-party logistics contracts.
- Legacy ERP integration:Batch tracking and lot recall systems from ingredient sourcing through co-packing networks require middleware investments that mid-tier brands struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Juice Market |
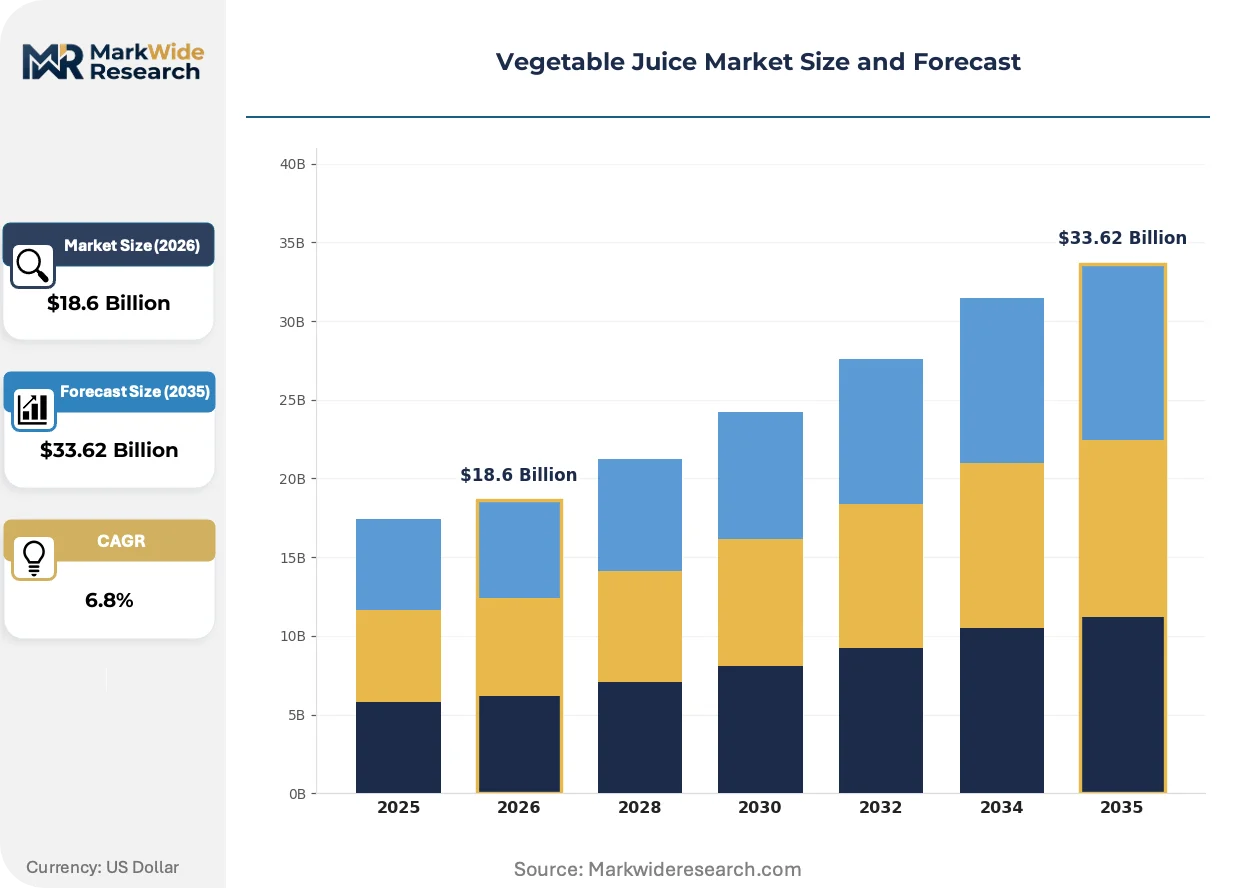
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chilled Juice, Shelf-Stable Juice, Concentrated Juice, Powdered Juice Ingredient Type: Carrot, Beet, Spinach, Kale Packaging Type: Carton, Glass Bottle, Plastic Bottle, Can Distribution Channel: Supermarkets, Health Stores, Online Retailers, Convenience Stores |
| Companies Covered | The Coca-Cola Company, PepsiCo, Campbell Soup Company, The Kraft Heinz Company, Del Monte Foods, Nestlé, Ocean Spray Cranberries, Bolthouse Farms, Dole Food Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Juice Market Strategic Shifts
Processing technology and regulatory disclosure requirements are compressing traditional formulation-to-shelf timelines while fragmenting consumer access points beyond conventional retail.
HPP equipment is migrating from boutique cold-pressed specialists toward mid-volume contract manufacturers serving multiple private-label clients. Regional co-packers in Texas and Florida are installing second-generation systems to capture shelf-stable brand conversions seeking fresher taste profiles. This technology diffusion is collapsing the historical premium-mass price gap in vegetable juice.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in chilled juice transport and retail display cases. Distributors are retrofitting fleets with CO2-based cooling systems or absorbing compliance penalties that compress already thin margins on conventional chilled lines. German and Dutch supermarket chains are accelerating supplier transition timelines ahead of statutory deadlines.
Subscription-based replenishment is displacing impulse supermarket purchases among core vegetable juice consumers. Direct-to-consumer platforms in California and New York bundle seasonal blends with personalized nutrition coaching, capturing lifetime value that traditional retail cannot match. This channel pivot concentrates most visibly among millennial households with children.
Vegetable Juice Market Segmentation
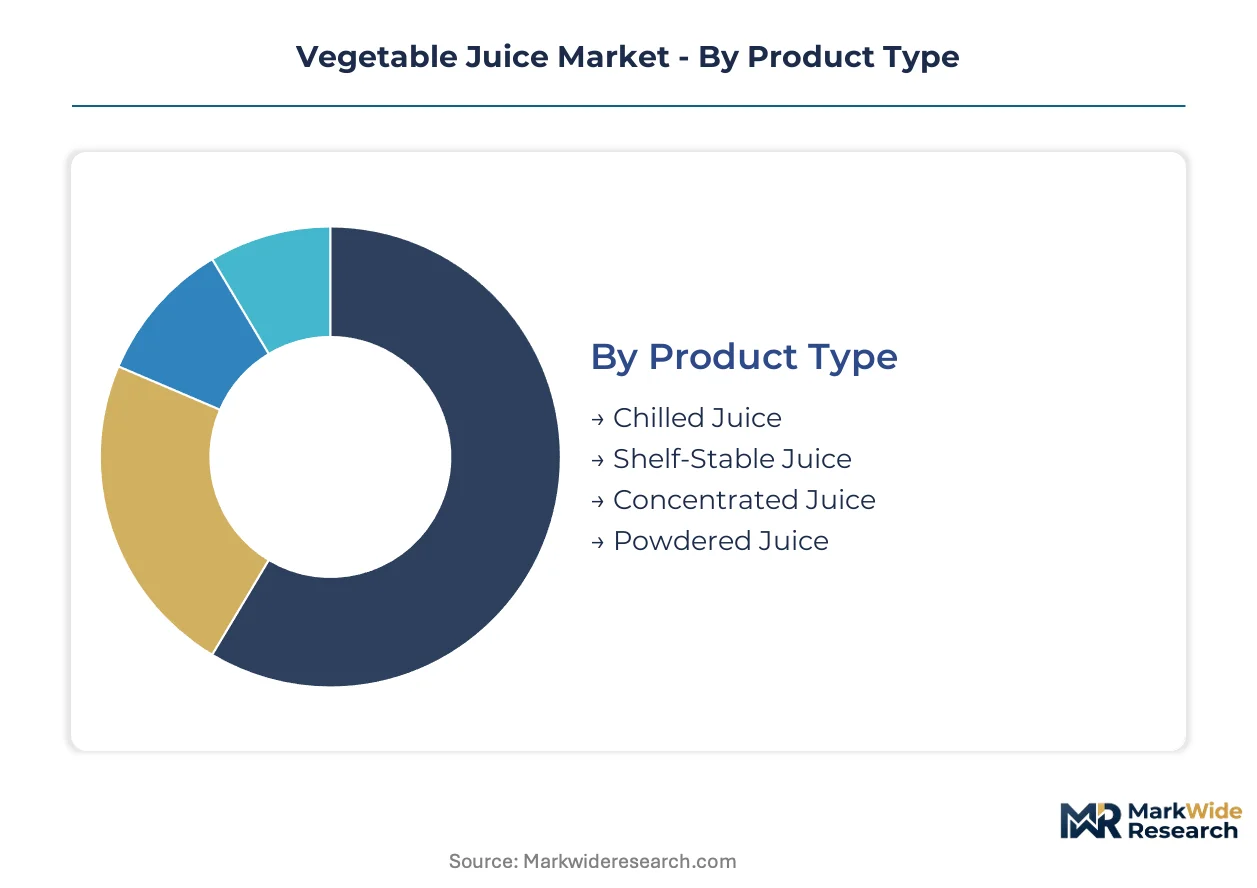
Vegetable juice segmentation reveals divergent velocity profiles across product formats and channel structures. Chilled formats turn inventory weekly while powdered alternatives sit in warehouse cycles measured in months.
Product Type:
Cycle times compress from powdered stockpiling to chilled just-in-time replenishment, with shelf-stable occupying the logistical middle ground.
- Chilled Juice:Cold-pressed or HPP-treated liquid requiring continuous refrigeration from production through consumption. Demand clusters in California and New York metro areas where juice bar density and premium supermarket penetration overlap with high-income millennial households.
- Shelf-Stable Juice:Thermal pasteurization enables ambient distribution with 12-18 month shelf life. Volume concentrates in Midwest and Southern US states where supermarket distribution networks prioritize logistical efficiency over freshness signaling.
- Concentrated Juice:Water-reduced format for dilution prior to consumption. Foodservice operators in institutional cafeterias and airline catering represent core procurement.
- Powdered Juice:Dehydrated vegetable solids reconstituted with water. E-commerce subscriptions and military ration contracts drive procurement patterns.
Shelf-stable juice anchors the volume base while chilled juice gains share at the steepest rate.
Ingredient Type:
Raw material sourcing economics stratify this category from commodity-scale carrot cultivation to boutique kale harvesting.
- Carrot:High-brix root vegetable with established mechanized harvesting infrastructure. Processing concentrates in California's Central Valley and Texas Panhandle where scale farming delivers cost-competitive feedstock for mass-market lines.
- Beet:Earthy root with nitrate concentration valued by athletic performance segments. Demand from endurance sports nutrition channels in Colorado and Oregon pulls beet blends into premium positioning.
- Spinach:Leafy green with rapid oxidation challenges requiring immediate processing. Organic certification premiums concentrate procurement among Arizona and Florida growers serving cold-pressed specialists.
- Kale:Fibrous brassica demanding intensive mastication or enzymatic treatment. Brooklyn and Austin wellness corridors sustain small-batch pricing for this ingredient.
Carrot underpins mainstream volume while beet climbs fastest among performance-oriented subsegments.
Packaging Type:
Material selection trades shelf-life extension against sustainability signaling and freight economics.
- Carton:Multi-layer paperboard with aluminum barrier for oxygen exclusion. European supermarket private-label programs favor this format for ambient lines.
- Glass Bottle:Inert material preserving flavor integrity without chemical migration. Premium positioning in Japanese and German health stores justifies freight weight penalties.
- Plastic Bottle:PET or HDPE with varying barrier properties. Convenience store channels in the United States and Mexico prioritize shatter resistance and lightweight logistics.
- Can:Aluminum format with internal epoxy lining. Emerging in Australian and UK markets for carbonated vegetable blends.
Plastic bottle dominates unit volume while glass gains fastest among sustainability-scrutinizing European consumers.
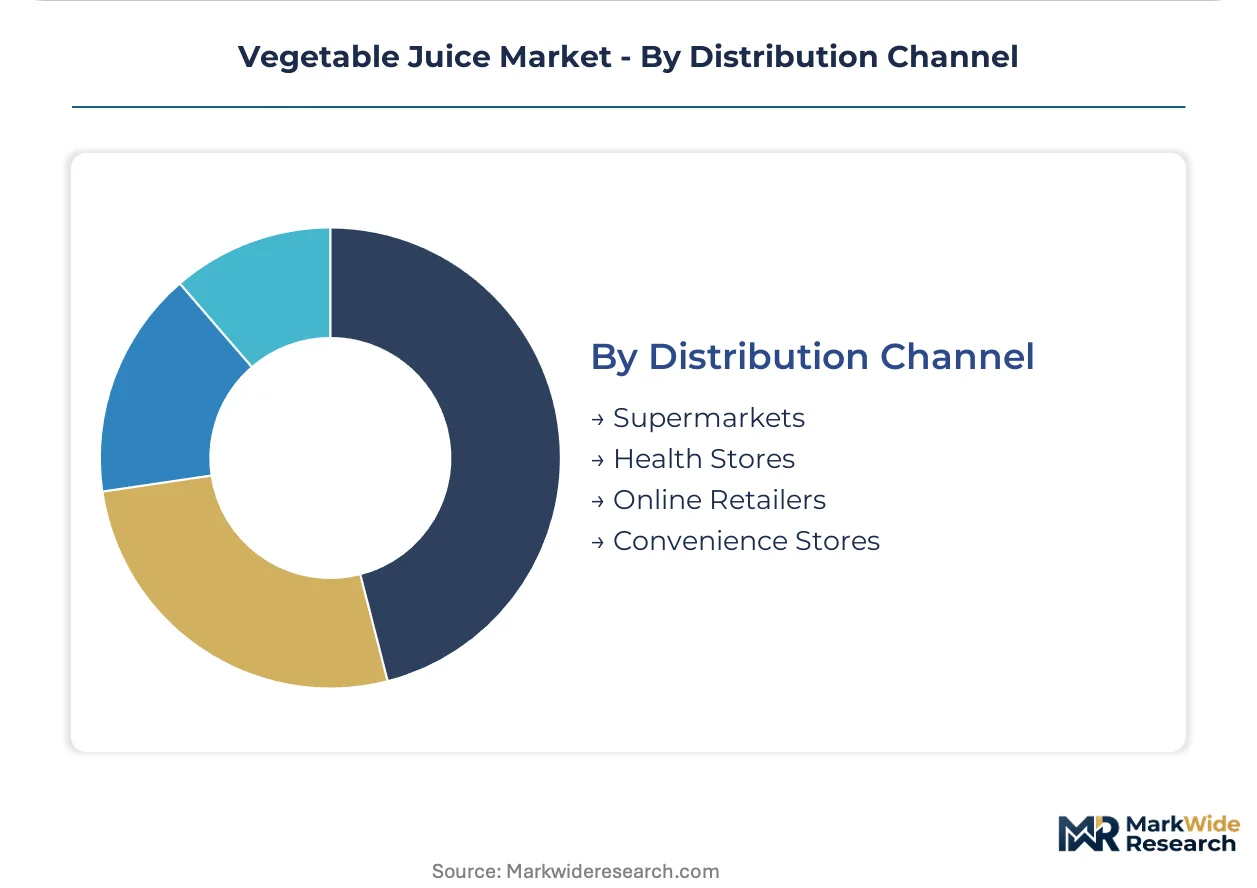
Distribution Channel:
Channel selection determines margin structure and consumer relationship depth.
- Supermarkets:Mass retail with slotting fee barriers and promotional calendar dependency. Kroger and Albertsons in the United States, Tesco in the UK, and Ahold Delhaize in the Netherlands control access to household penetration.
- Health Stores:Curated assortment with educated staff and supplement adjacencies. Whole Foods Market and Sprouts Farmers Market in the United States, Holland & Barrett in the UK, and dm-drogerie markt in Germany concentrate this channel.
- Online Retailers:Direct-to-consumer and marketplace platforms collapsing geographic constraints. Amazon and Thrive Market in the United States, Ocado in the UK, and Rakuten in Japan shape fulfillment expectations.
- Convenience Stores:Impulse-oriented with limited SKU count and grab-and-go positioning. 7-Eleven in the United States and Japan, Lawson in Japan, and BP/Shell forecourts in Europe capture commuter traffic.
Supermarkets anchor volume concentration while online retail expands most quickly among subscription-model adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation refrigerant phase-downs and FDA juice HACCP mandates are reshaping capital deployment across production geographies. Cold-chain infrastructure investments concentrate where regulatory enforcement timelines compress first-mover advantages.
United States
Functional beverage culture in California and New York metro areas pulls carrot and beet blends into mainstream convenience channels. FDA juice HACCP compliance costs force smaller brands toward contract manufacturing networks in Texas and Florida. Los Angeles and Brooklyn wellness corridors sustain premium cold-pressed positioning through direct-to-consumer subscription models.
Germany
EU Green Deal refrigeration standards drive supermarket chains to accelerate supplier transition timelines ahead of statutory deadlines. ECHA enforcement of F-Gas Regulation phase-downs concentrates retrofit investments in North Rhine-Westphalia distribution hubs. Berlin and Hamburg retail clusters favor carton-packaged ambient lines from private-label programs.
India
Mumbai and Bangalore cold-pressed juice bars remain underpenetrated relative to urban population density. FSSAI food safety compliance requirements shape local manufacturing investments in Maharashtra and Karnataka. Delhi-NCR organized retail consolidation threatens first-mover positioning in premium wellness corridors.
Japan
Health-conscious aging demographics sustain demand for nutrient-dense vegetable-based drinks in Tokyo and Osaka metro areas. METI energy efficiency standards influence refrigeration equipment selection in chilled juice distribution. Kanto region convenience store channels prioritize grab-and-go PET bottle formats for commuter traffic.
Australia
Endurance sports nutrition channels in Victoria and New South Wales pull nitrate-concentrated beet blends into premium positioning. TGA food standards enforcement shapes import compliance costs for international brands. Sydney and Melbourne health store clusters sustain glass bottle preference despite freight weight penalties.
Vegetable Juice Market Competitive Environment
Channel-controlling players compete with product-specialist players for shelf access and consumer relationship depth. Beverage conglomerates leverage global bottling networks and retail slotting fee capacity against regional cold-pressed specialists. Three archetypes dominate: multinational beverage conglomerates with diversified portfolios, premium organic specialists with direct-to-consumer platforms, and private-label contract manufacturers serving supermarket chains. Competitive moves concentrate on co-packing network expansion and clean-label reformulation acceleration.
Among multinational beverage conglomerates, The Coca-Cola Company and PepsiCo exemplify channel-control archetypes through extensive retail distribution partnerships. Campbell Soup Company occupies a position within the shelf-stable specialist tier, anchoring supermarket placement in North American mass retail. These three entities represent divergent strategic postures: beverage diversification, agricultural supply integration, and processed food portfolio extension respectively.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Campbell Soup Company |
| The Kraft Heinz Company |
| Del Monte Foods |
| Nestlé |
| Ocean Spray Cranberries |
| Bolthouse Farms |
| Dole Food Company |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in California's Central Valley cold-pressed processing infrastructure is compressing supplier margins while elevating spot pricing for organic vegetable feedstock. This utilization squeeze forces mid-tier brands toward contract manufacturing networks and accelerates price stratification between artisanal and mass-market tiers.
Pricing Analysis
Certification level creates the primary spread between organic cold-pressed lines and conventional shelf-stable alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects organic certification status, HPP treatment investment, and retail channel positioning. Cost compression in the mid-tier is intensifying because co-packer consolidation reduces negotiating leverage for emerging brands. Convenience store buyers exhibit highest price sensitivity, while direct-to-consumer subscribers accept premium positioning for personalized nutrition bundles.
Supply Chain Analysis
Extended payment terms from dominant supermarket chains are straining working capital for organic vegetable growers in California, Arizona, and Florida. Raw material procurement draws from mechanized carrot harvesting in California's Central Valley, hand-picked kale operations in Florida, and beet cultivation in Texas. Single-source vulnerability concentrates in spinach supply from California's Salinas Valley where climate-driven crop failures disrupt premium cold-pressed production. Distribution runs through refrigerated third-party logistics networks anchored by legacy dairy distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vegetable juice brands face substitution defense against oat and almond beverages capturing overlapping health-conscious shelf space in North American retail.
For Market Incumbents: Insulate core supermarket placements through exclusive distribution partnerships with Kroger and Albertsons while accelerating HPP capacity addition in Texas to capture shelf-stable brand conversions. Defend margin position against plant-based milk encroachment by bundling vegetable blends with personalized nutrition coaching subscriptions. For New Entrants and Emerging Players: Establish a beachhead in Mumbai and Bangalore cold-pressed juice bars where organized retail consolidation has not yet occurred. Target powder-to-liquid e-commerce formats for military ration contracts and direct-to-consumer wellness subscriptions as the most penetrable white-space segment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription platforms with personalized nutrition coaching capabilities. Long-term viability favors acquisition targets with captive organic vegetable supply agreements and established co-packer relationships. Watch FDA juice HACCP inspection backlogs as an inflection indicator for contract manufacturing capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Equipment Deployment | Extends chilled juice shelf life without nutrient degradation, unlocking broader distribution for regional brands. |
| Organic Certification Investment | Commands price premiums in Whole Foods and Sprouts Farmers Market channels where clean-label mandates dominate. |
| Direct-to-Consumer Platform Launch | Captures lifetime value through subscription bundles that traditional retail cannot match among millennial households. |
| Cold-Chain Infrastructure Expansion | EU F-Gas Regulation compliance requires CO2-based fleet retrofitting ahead of statutory deadlines in German distribution. |
| Powder-to-Liquid Format Development | Bypasses refrigerated logistics entirely, collapsing last-mile costs for e-commerce subscriptions and military procurement. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cold-pressed juice bar operators, co-packing facility managers, supermarket category buyers, organic vegetable growers, and FDA compliance consultants. Secondary validation drew from FDA juice HACCP guidance documents, EU F-Gas Regulation enforcement notices, FSSAI food safety circulars, Nielsen retail audit data, and customs import records. Bottom-up volume modeling triangulated against top-down category spending estimates.
Calibration against historical volume trajectories and documented capacity expansions anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, ingredient type, packaging material, and distribution channel. CAGRs were derived from regression analysis of correlated demand drivers. Forecast inputs incorporated organic vegetable yield volatility and cold-chain infrastructure investment cycles.
Sensitivities concentrate around FDA inspection timeline delays, EU refrigerant phase-down acceleration, and climate-driven organic crop failures. Forecasts reflect documented assumptions about substitution elasticity between vegetable juice and plant-based milk alternatives. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Beverage Premix Market
Beverages
North America Cold Pressed Juices Market
Beverages
Low Fat Drinks Market
Beverages
GCC Juice Market
Beverages
Reconstituted Juice Market
Beverages
Health Drinks Market
Beverages
Breakfast Drink Market
Beverages
North America Fruit Juice Market
Beverages
Gluten Free Beverages Market
Beverages
Japan Kombucha Market
Beverages
Popping Bobas Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
North America Energy Drink Market
Beverages
Semillon Market
Beverages
Asia-Pacific Energy Drink Market
Beverages
Packaged Milkshake Market