
 Water Bath Market | 2026-2036
Water Bath Market Size, Share, and Industry Trends Forecast 2026-2036
Water Bath Market Intelligence
The EU Green Deal is realigning laboratory equipment procurement criteria toward energy-efficient thermal systems across European research facilities. Thermo Fisher Scientific leverages its broad distribution network to sustain institutional contracts in academic and healthcare segments. JULABO anchors its position through specialized circulating bath technology for pharmaceutical applications. BIOBASE Group competes on manufacturing scale, supplying standard analog and digital units to industrial facilities across Asia.
A water bath is a temperature-controlled vessel that maintains samples within precise thermal parameters, typically ranging from ambient to 100°C, using heated water as a transfer medium for uniform heat distribution. The instrument serves essential functions in molecular biology protocols, chemical synthesis, and materials testing where thermal consistency prevents sample degradation. Digital water baths occupy the largest revenue share due to programmable setpoints and data logging capabilities demanded by regulated laboratories. Circulating water baths represent the fastest-expanding category, driven by pharmaceutical stability testing requirements that demand rapid temperature uniformity. Research laboratories generate the highest end-user margin pools, as grant-funded institutions prioritize precision over unit cost and specify multi-position programmable systems.
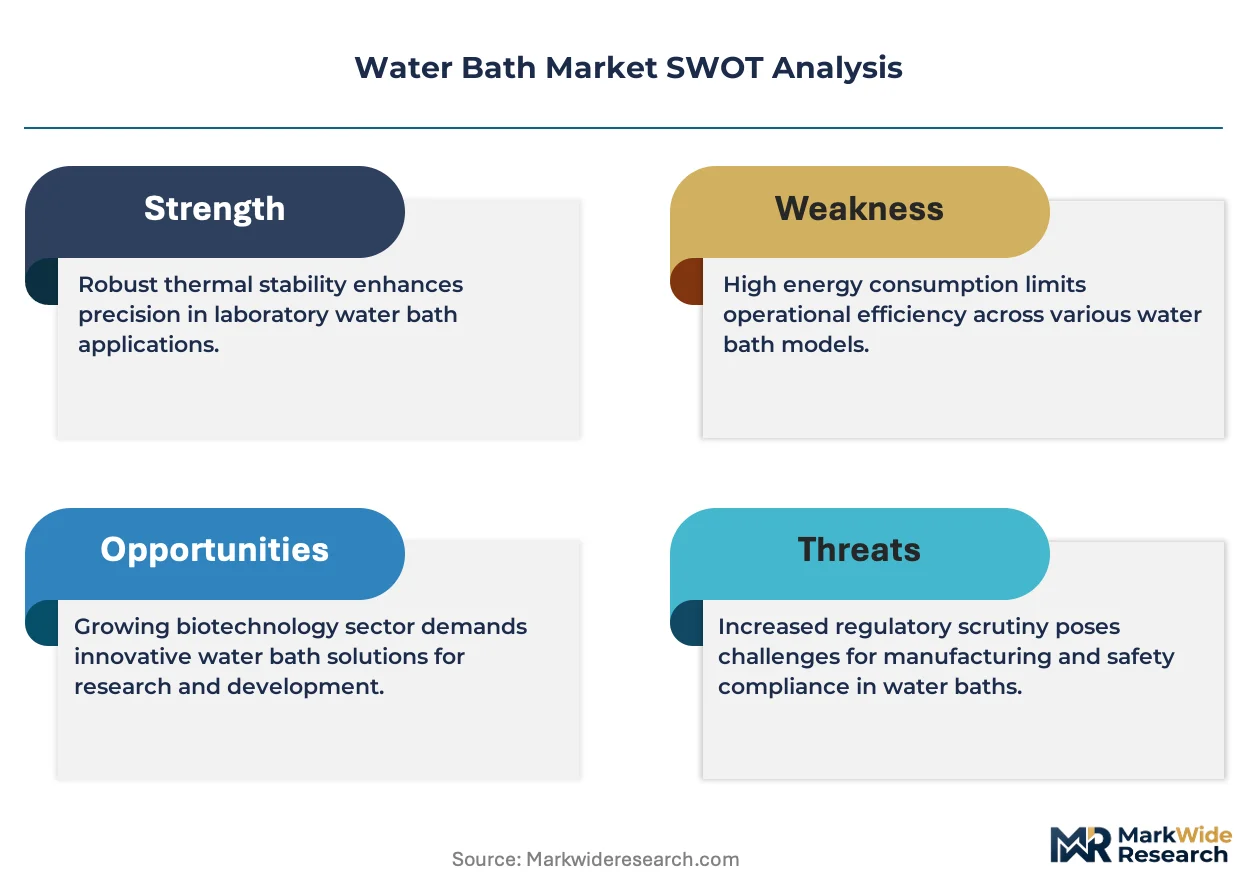
FDA 21 CFR Part 11 guidelines shape electronic records requirements for thermal equipment in drug development settings, while ISO 17025 mandates traceable calibration certificates that restrict market access for uncertified suppliers. EPA Good Laboratory Practice standards extend these compliance burdens to environmental testing laboratories using water baths for sample incubation. REACH compliance in Europe restricts certain polymer materials used in bath construction, redirecting specification toward stainless steel and approved polypropylene variants. Stakeholders must monitor evolving energy efficiency labeling schemes and material restriction lists that will determine competitive viability in institutional procurement channels.
Market Dynamics
ISO 17025 accreditation mandates are compressing vendor qualification timelines while pharmaceutical quality control laboratories expand temperature-controlled sample preparation capacity, creating a dual pressure on equipment suppliers to certify faster and perform more precisely.
Growth Catalysts
- EU Green Deal procurement realignment:European research facilities are redirecting capital toward energy-efficient thermal systems, expanding the addressable market for low-consumption circulating baths.
- Pharmaceutical stability testing protocols:Drug developers require rapid temperature uniformity for forced degradation studies, pulling demand toward advanced circulating water bath architectures.
- Stainless steel substitution:REACH polymer restrictions are accelerating specification shifts toward approved stainless steel and polypropylene bath construction materials.
Market Restraints
- Calibration certificate traceability costs:ISO 17025 mandates require documented thermal calibration chains that inflate total cost of ownership for budget-constrained industrial facilities.
- Heating element supply concentration:Precision resistance heating components concentrate among specialized German and Japanese component suppliers, exposing lead time vulnerabilities.
- Bead bath substitution in molecular biology:Aluminum bead thermal blocks are displacing water baths in PCR preparation workflows where contamination risk outweighs uniformity benefits.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO-aligned quality control laboratories in Hyderabad and Mumbai clusters are building thermal equipment capacity without incumbent vendor relationships.
- Cloud-connected calibration services:Remote temperature monitoring and automated compliance documentation are converging to create subscription-based equipment-as-a-service models.
- Environmental testing laboratory buildout:EPA Good Laboratory Practice standards are mandating thermal equipment for sample incubation across expanding state-level monitoring programs.
Industry Challenges
- Metrology technician scarcity:Qualified personnel capable of executing NIST-traceable temperature calibration are concentrated among aging workforce cohorts in regulated laboratory environments.
- FDA 21 CFR Part 11 software validation:Digital water bath electronic records systems require extensive IQ/OQ/PQ documentation that extends sales cycles by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Bath Market |
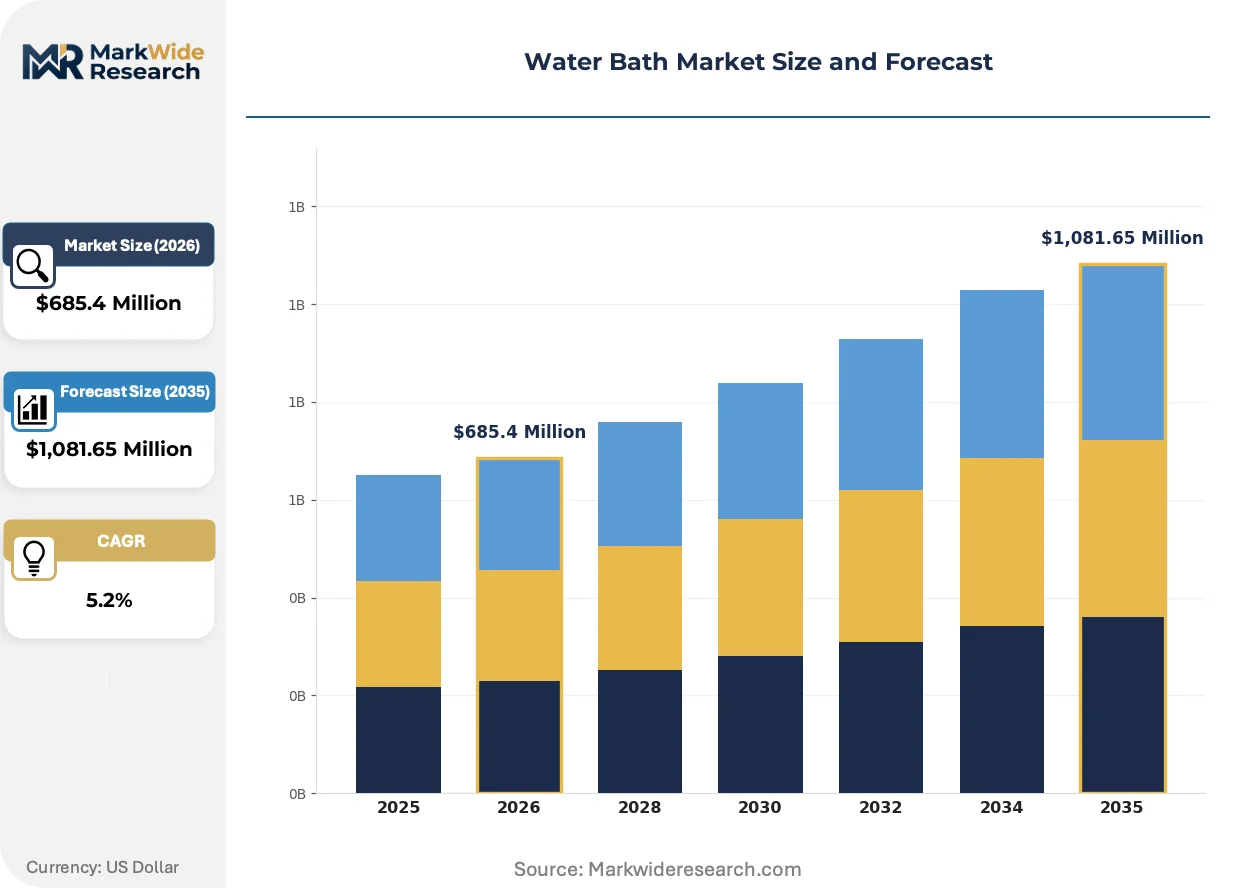
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Water Baths, Circulating Water Baths, Analog Water Baths, Shaking Water Baths End User: Academic Institutions, Research Laboratories, Industrial Facilities, Healthcare Organizations Temperature Range: Low-Temperature Baths, High-Temperature Baths, Ambient Temperature Baths, Programmable Temperature Baths Material: Stainless Steel, Polypropylene, Acrylic, Aluminum |
| Companies Covered | BIOBASE Group, Avantor, Thermo Fisher Scientific, Labmate Scientific, PolyScience, Labtron Equipment Ltd., JULABO, JP SELECTA, Lauda Brinkmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Bath Market Strategic Shifts & Innovations
Thermal equipment architecture is pivoting from isolated instruments toward integrated compliance systems that automate documentation and predictive maintenance. This shift is compressing the competitive advantage of traditional hardware-only suppliers.
Peltier-based solid-state temperature control is rewriting circulating bath design by eliminating mechanical compressors and heating elements. Pharmaceutical stability testing facilities are adopting these systems for vibration-sensitive applications. The technology is compressing maintenance intervals and enabling footprint reductions that matter in high-cost laboratory real estate markets.
REACH material restriction lists are tightening allowable polymer compositions in laboratory equipment construction. ECHA evaluations of plasticizer migration risks are redirecting bath specifications toward stainless steel reservoirs and fluoropolymer-coated surfaces. German precision engineering standards are accelerating this transition among European research procurement channels.
Grant-funded institutions are consolidating thermal equipment purchasing through shared service centers rather than departmental procurement. Academic research clusters in Boston and Heidelberg are centralizing water bath access through core facility models. This consolidation is visible most acutely in National Institutes of Health-funded institutions where indirect cost recovery incentives favor equipment pooling.
Water Bath Market Segmentation
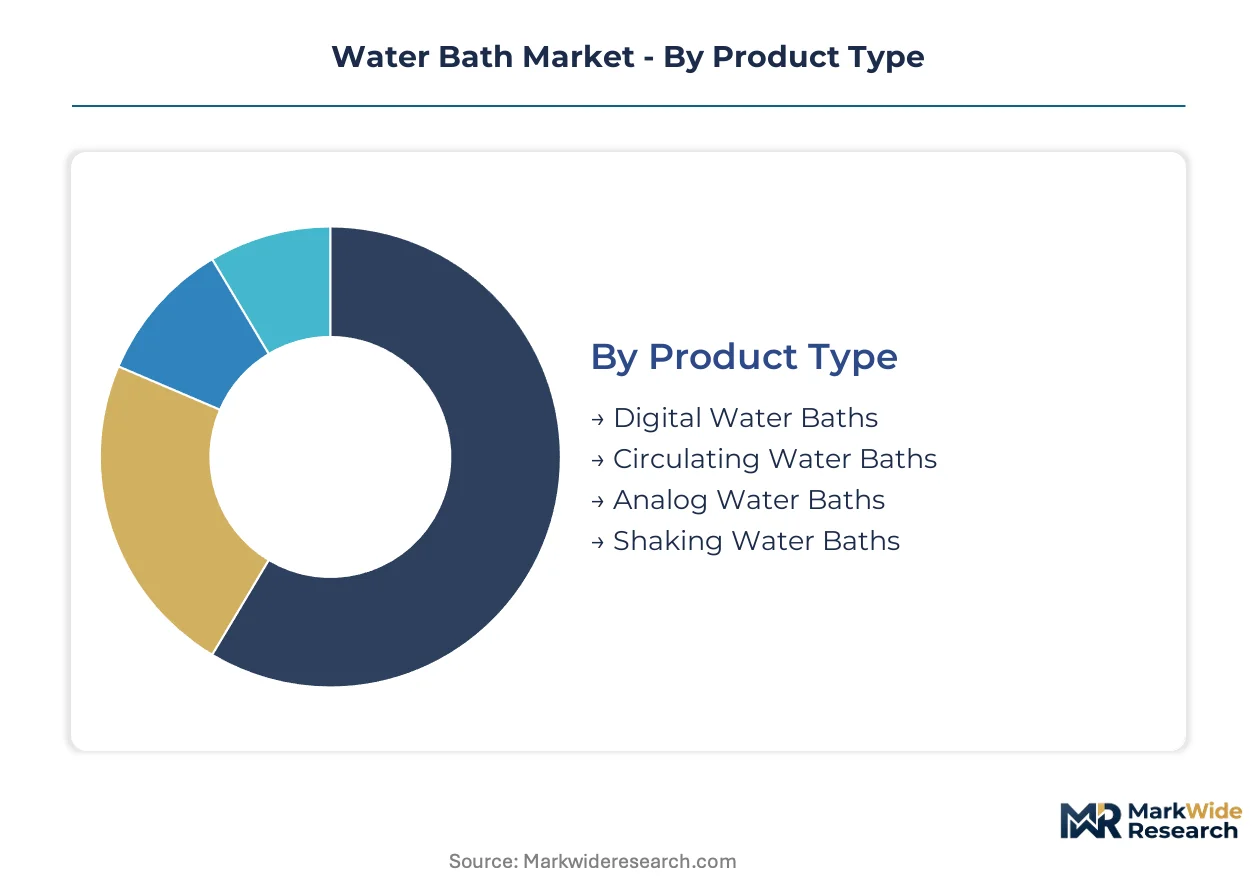
Water bath procurement decisions pivot on thermal precision requirements, regulatory compliance burdens, and total cost of ownership calculations that vary sharply across laboratory types. Segmentation reveals where premium engineering commands price premiums versus where standardized units satisfy functional needs.
Product Type:
Customization intensity spans from programmable digital systems with data logging to basic analog units without electronic controls.
- Digital Water Baths:Microprocessor-controlled units deliver programmable setpoints, PID temperature stability, and USB data export for FDA 21 CFR Part 11 compliance. Grant-funded institutions in Germany and Massachusetts specify these for multi-position enzymatic assays where thermal logging prevents protocol rejection.
- Circulating Water Baths:External pump architectures force fluid circulation for rapid temperature uniformity within ±0.1°C. Pharmaceutical stability testing facilities in Basel and Hyderabad are expanding capacity here for forced degradation studies under ICH guidelines.
- Analog Water Baths:Basic bimetallic thermostat control serves routine incubation in budget-constrained industrial quality control settings.
- Shaking Water Baths:Integrated orbital agitation combines thermal control with sample mixing for cell culture and hybridization protocols.
Most installed capacity flows through Digital Water Baths. Expansion is steepest in Circulating Water Baths.
End User:
Margin structures diverge between capital-rich research institutions and cost-optimized industrial operators.
- Research Laboratories:NIH-funded core facilities and Max Planck Institute clusters prioritize precision over unit cost. These buyers specify multi-position programmable systems with NIST-traceable calibration certificates and extended warranty terms.
- Academic Institutions:Shared service center consolidation in Boston and Heidelberg is centralizing procurement through core facility models rather than departmental buying.
- Industrial Facilities:Chemical manufacturing plants and food testing laboratories in Gujarat and Guangdong prioritize throughput and durability over documentation depth.
- Healthcare Organizations:Hospital clinical laboratories select compact footprint units for blood bank warming and specimen preparation workflows.
Research Laboratories command the highest average selling prices. Academic Institutions are consolidating fastest.
Temperature Range:
Specification complexity escalates with deviation from standard ambient-to-boiling protocols.
- Programmable Temperature Baths:Multi-step ramp-and-soak profiles enable automated thermal cycling for PCR annealing and materials aging studies. Contract research organizations in Cambridge and Singapore specify these for high-throughput screening automation.
- Low-Temperature Baths:Refrigerated circulators maintain sub-ambient conditions for enzyme kinetics and crystallography applications. Crystallography facilities at synchrotron sites in Grenoble and Tsukuba drive specification toward stability below 4°C.
- High-Temperature Baths:Oil-based heat transfer media extend operational range above 100°C for polymer testing and asphalt characterization.
- Ambient Temperature Baths:Unheated vessels with cooling coil compatibility serve moderate incubation in environmental monitoring laboratories.
Programmable Temperature Baths capture the premium tier. Low-Temperature Baths are gaining share fastest.
Material:
REACH compliance deadlines are accelerating substitution away from legacy polymer formulations.
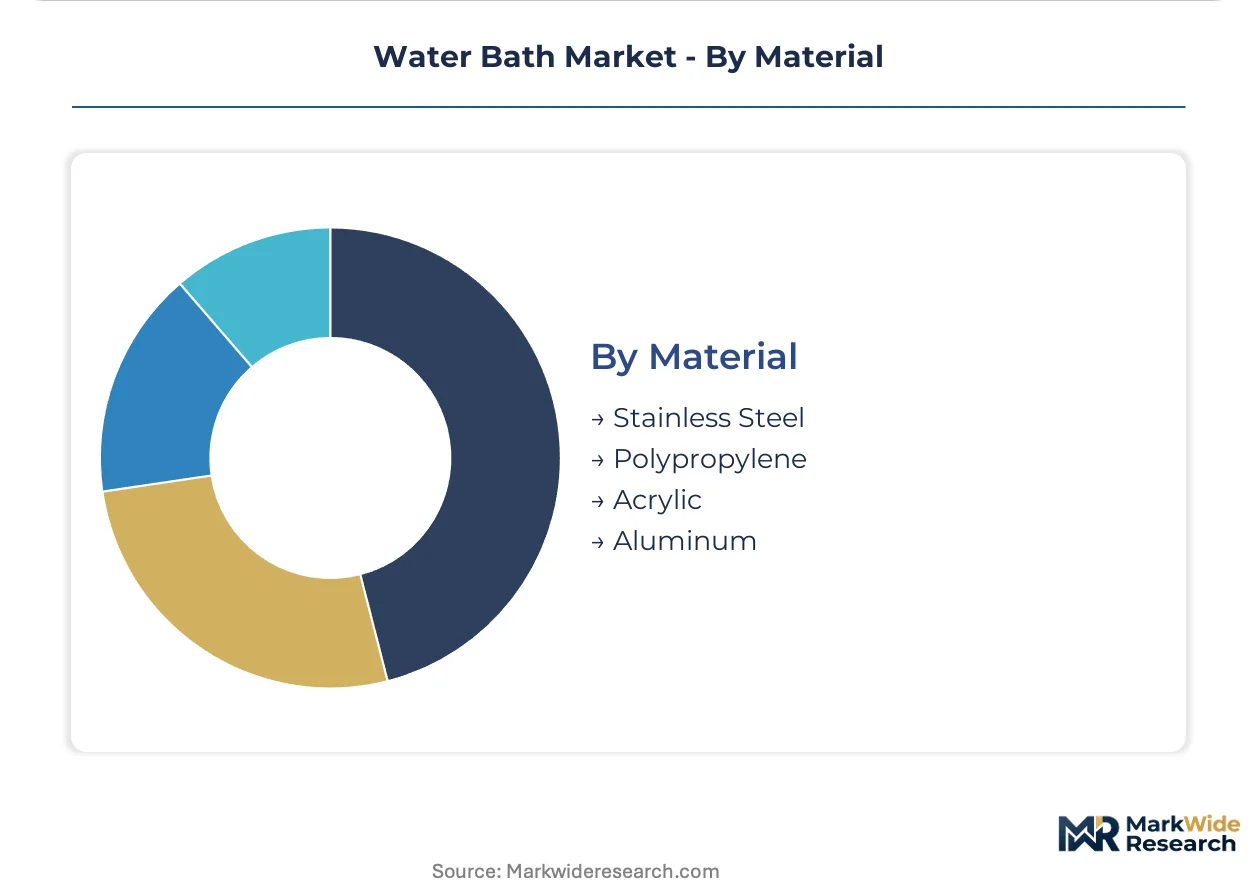
- Stainless Steel:316L grade reservoirs resist corrosive media and enable autoclave sterilization. ECHA plasticizer migration evaluations are redirecting European procurement toward these surfaces for pharmaceutical applications.
- Polypropylene:Chemically resistant, lightweight construction suits educational settings and high-throughput screening where unit cost constraints dominate.
- Acrylic:Transparent walls enable visual sample monitoring for teaching demonstrations and colorimetric assay observation.
- Aluminum:Bead bath configurations using aluminum beads are displacing water in PCR preparation workflows where contamination risk outweighs thermal uniformity benefits.
Stainless Steel dominates regulated laboratory procurement. Polypropylene retains volume leadership in education markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German metrology technicians and Swiss precision engineers anchor the specialized workforce supporting high-specification water bath manufacturing. Their concentration in Central European industrial clusters shapes procurement standards that cascade into adjacent markets. This talent distribution explains why regulatory stringency and engineering quality converge most intensely in specific national laboratory systems.
United States
NIH-funded core facilities and FDA-regulated pharmaceutical stability testing laboratories drive premium digital water bath procurement. The agency's 21 CFR Part 11 guidelines mandate electronic records capabilities that exclude uncertified suppliers from drug development settings. Greater Boston's academic research cluster centralizes thermal equipment purchasing through shared service centers rather than departmental acquisition.
Germany
Max Planck Institute laboratories and BASF-led pharmaceutical quality control operations specify circulating baths with ±0.1°C uniformity for forced degradation studies. The country's national accreditation body enforces ISO 17025 calibration protocols that compress vendor qualification timelines. Baden-Württemberg's precision engineering corridor concentrates manufacturing of resistance heating components supplying domestic and export markets.
India
CDSCO-aligned quality control laboratories in Hyderabad and Mumbai pharmaceutical manufacturing clusters are building thermal equipment capacity without incumbent vendor relationships. The national pharmaceutical regulator's alignment with ICH stability testing guidelines pulls specification toward programmable circulating architectures. Gujarat's chemical manufacturing belt prioritizes throughput and durability over documentation depth in industrial quality control settings.
Japan
Synchrotron crystallography facilities at Tsukuba and pharmaceutical stability testing operations in Osaka drive demand for low-temperature circulating baths below 4°C. The national standards body maintains JIS certification requirements that restrict market access for uncertified thermal equipment suppliers. Nagoya's industrial machinery corridor hosts specialized component fabricators serving precision laboratory instrument manufacturers.
China
NMPA-regulated pharmaceutical manufacturing expansion in Jiangsu and Zhejiang provinces is scaling temperature-controlled sample preparation capacity. The national medical products administration's quality control laboratory accreditation requirements are tightening calibration documentation standards. Shanghai's contract research organization cluster specifies multi-position programmable systems for high-throughput screening automation workflows.
Water Bath Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a market structure that fragments between precision engineering specialists and manufacturing-scale suppliers. German and Japanese component fabricators anchor the upstream supply of resistance heating elements, while downstream assembly concentrates among diversified laboratory equipment conglomerates and focused thermal system specialists. Three strategic archetypes dominate: precision engineering houses serving regulated pharmaceutical laboratories, manufacturing-scale suppliers competing on unit cost for industrial quality control settings, and diversified conglomerates leveraging distribution breadth across academic and healthcare segments. Competitive moves center on calibration service network expansion and cloud-connected compliance documentation capabilities that extend customer retention beyond hardware replacement cycles.
Within the precision engineering tier, JULABO and Lauda Brinkmann exemplify specialized circulating bath technology development for pharmaceutical applications. Thermo Fisher Scientific occupies a position leveraging broad distribution infrastructure to sustain institutional contracts across academic and healthcare segments. BIOBASE Group represents manufacturing-scale competition supplying standard analog and digital units to industrial facilities. These three anchors illustrate how competitive positioning diverges between specification-driven premium procurement and cost-optimized volume deployment.
| Leading Market Players |
|---|
| BIOBASE Group |
| Avantor |
| Thermo Fisher Scientific |
| Labmate Scientific |
| PolyScience |
| Labtron Equipment Ltd. |
| JULABO |
| JP SELECTA |
| Lauda Brinkmann |
| Others |
Cost & Logistics Intelligence
Family-owned German precision engineering houses anchor the upstream supply of resistance heating elements, compressing margin capture for downstream assemblers while sustaining premium pricing power through NIST-traceable calibration bundling. Their concentration in Baden-Württemberg and Nagoya industrial corridors shapes procurement timelines and certification costs that cascade through institutional sales channels.
Pricing Analysis
Calibration service bundling versus unbundled hardware-only procurement splits the market into divergent total-cost-of-ownership models. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 17025 certification depth and warranty extension terms. Pricing pressure stems from CDSCO-aligned Indian pharmaceutical laboratories demanding localized service networks without incumbent vendor premiums. Industrial quality control facilities in Gujarat and Guangdong exhibit highest price sensitivity, while NIH-funded core facilities prioritize precision documentation over unit cost.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Chicago, and Singapore orchestrate hub-and-spoke patterns for circulating bath assemblies. Component fabrication concentrates in Germany, Japan, and China, with 316L stainless steel reservoirs and precision resistance heating elements drawing from specialized metallurgical suppliers. Single-source vulnerability concentrates in German heating element fabricators serving JULABO and Lauda Brinkmann production lines. Distribution runs through laboratory equipment distributors holding ISO 17025-accredited service capabilities rather than direct manufacturer-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water bath market functions as a geographic-arbitrage play between European precision engineering premiums and Asian manufacturing scale, with CDSCO alignment costs in India running substantially below EU REACH compliance burdens while demand accelerates in both jurisdictions.
For Market Incumbents: Deepen backward integration into resistance heating element production to insulate against German and Japanese component supplier lead time volatility. Fortify calibration service network density in Hyderabad and Mumbai pharmaceutical clusters before emerging competitors establish CDSCO-aligned service footprints. Prioritize cloud-connected compliance documentation subscriptions that extend customer retention beyond hardware replacement cycles. For New Entrants and Emerging Players: The price-point gap between JULABO-grade circulating baths and BIOBASE-scale analog units creates white-space opportunity for mid-tier programmable systems with regional calibration support. Target CDSCO-aligned quality control laboratories in Indian pharmaceutical manufacturing clusters lacking incumbent vendor relationships. Pursue equipment-as-a-service subscription models bundling hardware, calibration, and compliance documentation to bypass capital budget constraints. For Investors and Strategic Acquirers: Valuations sit cheapest among analog water bath manufacturers serving industrial quality control settings, where bead bath substitution threats compress forward multiples. Long-term viability hinges on cloud-connected calibration service attach rates rather than hardware shipment volumes. Monitor Peltier-based solid-state temperature control adoption curves in pharmaceutical stability testing facilities as inflection indicator for compressor-based system obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Calibration Service Launch | FDA 21 CFR Part 11 documentation automation extends customer retention beyond replacement cycles. |
| Backward Integration into Heating Elements | German and Japanese component supplier concentration creates vulnerability for non-integrated assemblers. |
| CDSCO-Aligned Service Network Expansion | Hyderabad and Mumbai pharmaceutical clusters build capacity without incumbent vendor relationships. |
| Peltier-Based Product Line Development | Vibration-sensitive pharmaceutical stability testing applications favor solid-state over compressor architectures. |
| Core Facility Partnership Models | NIH-funded shared service centers in Boston consolidate procurement through equipment pooling agreements. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with laboratory equipment procurement managers, metrology technicians, pharmaceutical quality control directors, and thermal system maintenance heads with secondary validation against FDA 21 CFR Part 11 guidance documents, ISO 17025 accreditation standards, EPA Good Laboratory Practice regulations, and ECHA REACH restriction lists. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, temperature range, and material segmentation dimensions.
Historical reference periods anchored volume and value projections across the modeling period, with growth trajectories derived from pharmaceutical manufacturing expansion rates, academic research funding disbursement patterns, and regulatory accreditation timeline compression. Segmentation modeling incorporated product architecture complexity, calibration documentation depth, and regional regulatory alignment requirements. Forecast inputs included CDSCO ICH guideline adoption curves, EU Green Deal procurement realignment schedules, and Peltier technology cost reduction trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid-state Peltier temperature control would alter the outlook if vibration-sensitive pharmaceutical applications accelerate displacement of compressor-based circulating baths. Forecasts reflect assumptions regarding REACH material restriction enforcement timelines and NIH indirect cost recovery policy stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Microtome Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Nuclear Medicine Equipment Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
Cryopreservation Systems Market
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Electrophysiology Equipment and Recording Systems Market
Medical Equipment
Fluoroscopy Equipment Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Contact Type Liquid Handling Workstation Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Global Embryo Incubator Market
Medical Equipment
Animal Operating Table Market
Medical Equipment
Autoclaves Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Biomedical Refrigerators and Freezers Market