
 Healthcare Additive Manufacturing Market | 2026-2036
Healthcare Additive Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Additive Manufacturing Market Intelligence
The gap between prototype-grade and production-grade additive workflows is narrowing as laser powder bed fusion systems achieve repeatability thresholds for implantable titanium alloys. 3D Systems Inc. leverages its long-standing FDA master file database to accelerate orthopedic customer regulatory submissions. Stratasys Ltd. anchors its hospital presence through polyjet anatomical modeling contracts with major academic medical centers. Materialise NV dominates the surgical planning software layer that translates imaging data into printable file formats.
Healthcare additive manufacturing encompasses the layer-by-layer fabrication of patient-matched devices, anatomical models, and biological scaffolds from digital 3D data, typically using biocompatible polymers, titanium alloys, or cell-laden hydrogels processed through precision thermal or photopolymerization systems. Its primary purpose is to eliminate tooling costs and reduce geometric constraints inherent in subtractive or molding processes for personalized medicine. Bioprinting captures disproportionate R&D investment despite smaller current revenue, while 3D printed implants generate the dominant share of commercial revenue through titanium and PEEK orthopedic hardware. Surgical models represent a mature, high-volume segment where hospital billing codes now reimburse preoperative planning use.
FDA maintains active guidance on point-of-care 3D printing, while ISO/ASTM 52900 standards define process terminology and quality benchmarks for medical device submissions. The European Medicines Agency enforces MDR requirements that classify patient-specific implants under higher-risk device categories, extending conformity assessment timelines. Stakeholders must monitor whether regulatory harmonization between FDA breakthrough device pathways and EU notified body frameworks creates divergent market access conditions for distributed manufacturing models.
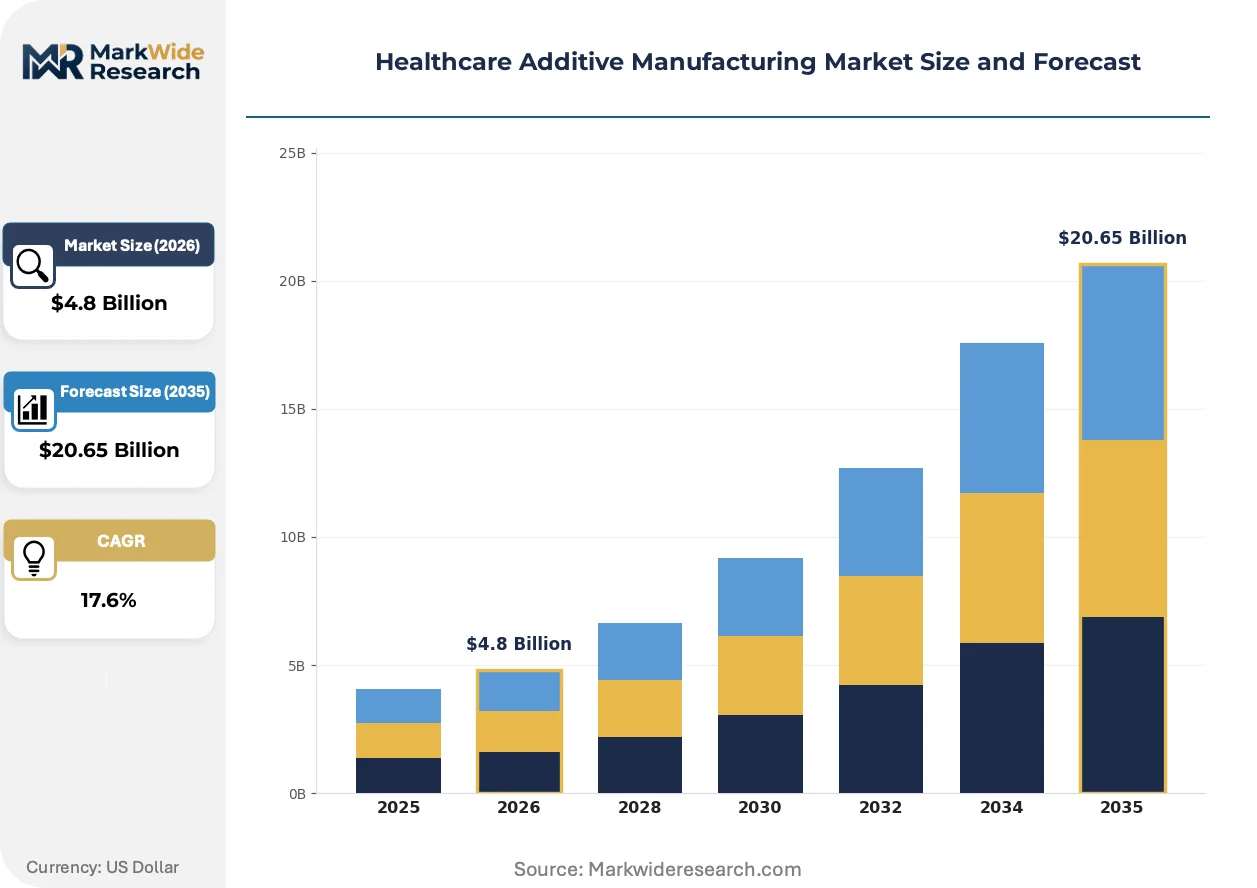
Market Dynamics
Laser powder bed fusion systems are collapsing the validation gap between prototype-grade and production-grade titanium orthopedic implants, compressing regulatory submission timelines as FDA master file databases accelerate premarket clearances.
Growth Catalysts
- FDA Breakthrough Device Pathway:Expedited premarket review timelines for patient-specific implant categories reduce regulatory friction for titanium hip cups and spinal cages derived from DICOM imaging data.
- Point-of-Care Manufacturing Programs:Major hospital systems in Cleveland, Mayo Clinic Minnesota, and VA medical centers establish distributed production nodes for surgical planning models and implantable hardware.
- Biocompatible Titanium Alloys:Repeatability thresholds in laser powder bed fusion systems enable direct fabrication of load-bearing orthopedic hardware from patient imaging data.
Market Restraints
- High-Purity Titanium Powder Concentration:Supply of spherical Ti-6Al-4V ELI powder concentrates among limited specialty gas atomization facilities, creating input cost volatility for implant manufacturers.
- EU MDR Conformity Assessment:European Medicines Agency classification of patient-specific implants under higher-risk device categories extends notified body review timelines versus FDA pathways.
- Subtractive CNC Milling:Established five-axis machining centers retain cost advantages for standardized implant geometries below minimum viable batch sizes for additive production.
Strategic Opportunities
- Cranio-Maxillofacial Reconstruction:Underpenetrated application segment for patient-specific titanium mandible and skull plates offers expansion beyond mature spinal and hip markets.
- ISO/ASTM 52900 Harmonization:Converging terminology and quality benchmarks between FDA guidance and European standards reduce dual-market compliance burden for distributed manufacturing models.
- Hospital Billing Code Expansion:Reimbursement pathways for preoperative anatomical modeling extend software and service revenue beyond hardware sales in academic medical centers.
Industry Challenges
- Process Validation Expertise Gap:Shortage of engineers trained in statistical process control for laser powder bed fusion systems constrains scale-up of point-of-care manufacturing programs.
- Post-Processing Bottlenecks:Hot isostatic pressing and precision machining requirements for titanium implants create throughput constraints that offset additive speed advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Additive Manufacturing Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioprinting, 3D Printed Implants, Surgical Models, Hearing Aids Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, DMLS End User: Hospitals, Clinics, Research Institutions, Pharmaceutical Companies Application: Prosthetics, Orthopedics, Tissue Engineering, Medical Devices |
| Companies Covered | 3D Systems Inc., Stratasys Ltd., Materialise NV, GE Additive, EnvisionTEC GmbH, regenHU, Allevi Inc., EOS GmbH, Nanoscribe GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Additive Manufacturing Market Strategic Shifts & Innovations
Workflow integration between surgical planning software and production hardware is collapsing traditional boundaries between imaging, design, and fabrication in personalized medicine.
Multi-laser powder bed fusion systems are collapsing the throughput ceiling for titanium orthopedic production, enabling mid-volume manufacturers to achieve lot sizes previously reserved for subtractive machining. Hospital-owned manufacturing cells in the United States are adopting these platforms for patient-specific spinal cages. The technology is collapsing minimum order quantity thresholds that previously blocked personalized implant economics.
EU MDR requirements for patient-specific implants are tightening conformity assessment protocols for notified bodies across Germany, France, and the Netherlands. Manufacturers face extended technical documentation reviews for titanium hardware classifications. European orthopedic device firms are responding by consolidating regulatory submissions under centralized quality management systems.
Surgeon demand for same-day anatomical modeling is compressing procurement cycles for hospital-based 3D printing services. Academic medical centers in the United States are unbundelling preoperative planning from device procurement, creating standalone software and service contracts. This behavioral shift concentrates purchasing authority within surgical departments rather than central supply chains.
Healthcare Additive Manufacturing Market Segmentation
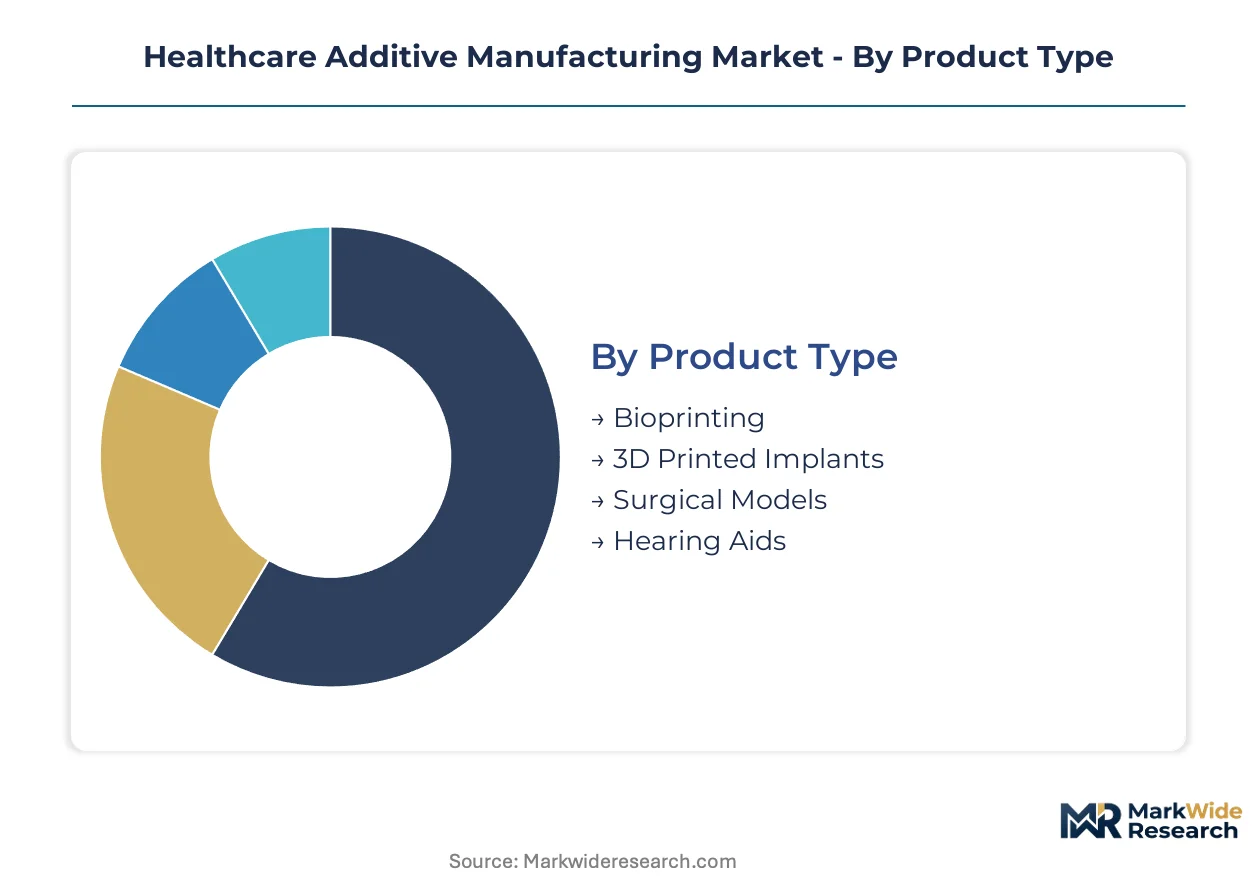
Segmentation in healthcare additive manufacturing reveals divergent commercial timelines: bioprinting absorbs R&D capital with decade-long development horizons, while surgical models and hearing aids convert to revenue within months. Understanding these cycle-time differentials shapes capital allocation and partnership priorities across the value chain.
Product Type:
Cycle times vary dramatically across product categories, with patient-matched hardware moving from scan to implant in weeks while biological constructs face multi-year validation timelines.
- Bioprinting:Layer-by-layer deposition of cell-laden hydrogels and bioinks constructs vascularized tissue scaffolds for organ regeneration research. Pharmaceutical companies in the United States and Germany fund preclinical platforms despite extended FDA and EMA pathways for living tissue products.
- 3D Printed Implants:Laser powder bed fusion fabricates load-bearing titanium hip cups and spinal cages directly from DICOM imaging data. Mayo Clinic and Cleveland Clinic procurement programs concentrate demand for patient-specific orthopedic hardware with compressed surgical scheduling.
- Surgical Models:Polyjet and stereolithography systems produce patient-matched anatomical replicas for preoperative planning. Hospital billing codes in the United States now reimburse these models, accelerating adoption in academic medical centers.
- Hearing Aids:Digital light processing of biocompatible resins enables same-day production of custom-fit earpieces. Audiology clinics leverage distributed manufacturing for rapid turnaround on personalized devices.
3D printed implants dominate installed base. Bioprinting is where expansion concentrates.
Technology:
Cost tiers separate prototyping-grade systems from production-validated platforms capable of regulatory submission for implantable devices.
- Fused Deposition Modeling:Thermoplastic extrusion systems offer lowest capital entry point for anatomical modeling applications. Hospital point-of-care programs deploy these platforms for rapid surgical planning model production where surface finish requirements remain moderate.
- Stereolithography:Photopolymer vat polymerization delivers finest feature resolution for cranio-maxillofacial surgical guides and dental applications. Research institutions leverage these systems for microfluidic device prototyping with sub-100-micron precision.
- Selective Laser Sintering:CO2 laser fusion of polyamide powders produces durable, sterilizable surgical instruments and patient-specific cutting guides. Orthopedic device manufacturers integrate these systems for PEEK spinal implant production.
- DMLS:Direct metal laser sintering of titanium and cobalt-chrome alloys generates fully dense, load-bearing orthopedic hardware. FDA master file databases accelerate regulatory submissions for DMLS-produced hip cups and spinal cages.
DMLS commands premium pricing. Fused deposition modeling captures volume.
End User:
Customer type determines procurement authority, with surgical departments gaining autonomy over centralized supply chains for patient-matched production.
- Hospitals:Academic medical centers establish point-of-care manufacturing cells for same-day anatomical modeling and implant production. VA medical centers deploy additive systems for veteran-specific orthopedic reconstruction programs.
- Clinics:Private audiology and orthopedic practices adopt desktop systems for custom hearing aid shells and surgical guides. Reimbursement pathways for preoperative planning extend software and service revenue to outpatient settings.
- Research Institutions:University hospitals and biomedical engineering departments drive bioprinting platform development. NIH and NSF funding concentrates in tissue engineering applications with extended commercialization horizons.
- Pharmaceutical Companies:Drug developers leverage 3D printing for personalized dosage forms and organ-on-chip platforms. Patient-specific tablet geometries enable precision dosing trials for narrow therapeutic index compounds.
Hospitals anchor equipment demand. Pharmaceutical companies are expanding most quickly.
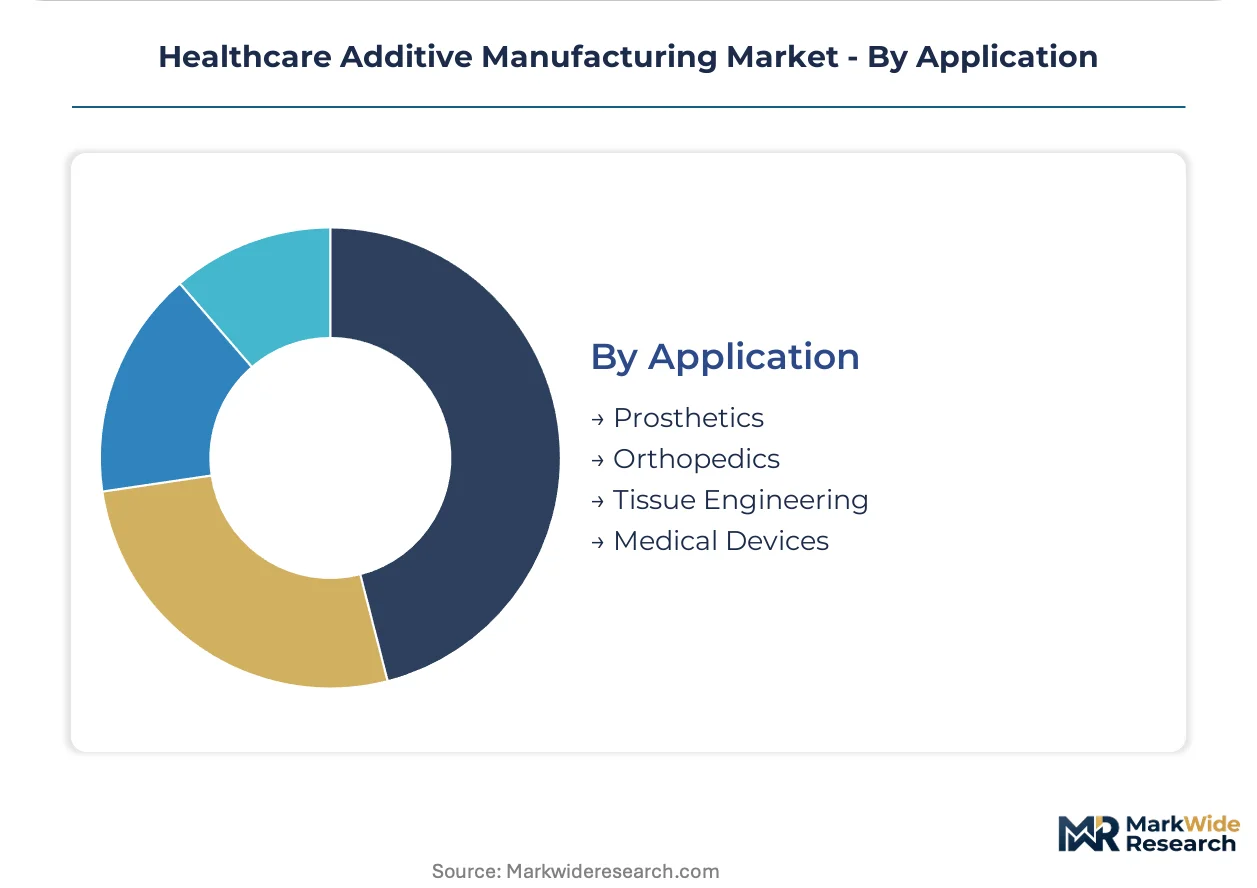
Application:
Maturity gradients separate established orthopedic markets from emerging tissue engineering frontiers with unproven regulatory pathways.
- Prosthetics:Custom socket liners and limb components match residual limb geometry for amputee patients. VA medical centers in the United States deploy additive production for veteran prosthetic programs with compressed fitting timelines.
- Orthopedics:Patient-specific titanium spinal cages and hip cups dominate commercial revenue. Cleveland Clinic and Mayo Clinic surgical departments specify additive hardware for complex revision cases.
- Tissue Engineering:Bioprinted vascular scaffolds and organ patches remain preclinical. EMA and FDA breakthrough device designations accelerate select cardiovascular applications.
- Medical Devices:Surgical instruments, patient-matched cutting guides, and dental aligners represent high-volume production. ISO 13485-certified contract manufacturers serve multiple OEMs from centralized production facilities.
Orthopedics dominates installed base. Tissue engineering is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and orthopedic device distributors concentrate purchasing authority for additive manufacturing systems. Academic medical centers in the United States, Germany, and Japan anchor equipment demand. Regulatory pathway divergence between FDA and EMA frameworks shapes geographic expansion strategies.
United States
VA medical centers and major hospital systems in Cleveland and Minnesota drive point-of-care manufacturing adoption for veteran-specific orthopedic programs. FDA breakthrough device pathways compress premarket review timelines for patient-specific titanium implants. The Midwest surgical corridor concentrates demand for laser powder bed fusion systems in academic medical centers.
Germany
Specialty gas atomization facilities supplying spherical Ti-6Al-4V ELI powder anchor the European titanium supply chain for implant manufacturers. EMA MDR requirements classify patient-specific implants under higher-risk device categories, extending notified body review timelines. The Bavarian industrial cluster hosts precision machining firms integrating additive post-processing capabilities.
Japan
PMDA regulatory frameworks for custom-made medical devices enable accelerated pathways for patient-matched orthopedic hardware. METI industrial policy supports domestic additive manufacturing capacity for aerospace and medical convergence applications. The Nagoya-Chubu region concentrates titanium powder metallurgy expertise serving implant OEMs.
Switzerland
Swissmedic oversight of custom device manufacturing maintains alignment with EU MDR standards while preserving national flexibility for innovative implant categories. The Basel-Zurich corridor hosts contract manufacturers serving multinational orthopedic device firms with ISO 13485-certified additive production cells. Precision engineering heritage supports micron-level surface finish requirements for spinal implant applications.
United Kingdom
NHS specialized commissioning frameworks for complex orthopedic cases create reimbursement pathways for patient-specific implant procedures. MHRA post-Brexit regulatory autonomy enables divergence from EU MDR timelines for certain additive device categories. The Oxford-Cambridge-London triangle concentrates bioprinting research platforms with pharmaceutical industry partnerships.
Healthcare Additive Manufacturing Market Key Industry Players
Channel-controlling players compete with product-specialist players across hardware, software, and service layers. The market structures around three tiers: integrated system vendors with FDA master file databases, surgical planning software specialists, and point-of-care service providers. Equipment manufacturers with regulatory pre-clearance capabilities anchor premium positioning. Strategic moves concentrate on workflow integration partnerships and hospital direct-sales expansion.
Among established system vendors, 3D Systems Inc. and Stratasys Ltd. occupy positions spanning hardware and materials portfolios. Materialise NV exemplifies the software-centric archetype, anchoring surgical planning and file preparation workflows. EOS GmbH represents European precision metal fabrication heritage in industrial additive systems. These three named entities illustrate the competitive segmentation between integrated platform providers and specialized workflow enablers.
| Leading Market Players |
|---|
| 3D Systems Inc. |
| Stratasys Ltd. |
| Materialise NV |
| GE Additive |
| EnvisionTEC GmbH |
| regenHU |
| Allevi Inc. |
| EOS GmbH |
| Nanoscribe GmbH |
| Others |
Cost & Logistics Intelligence
The Bavarian industrial cluster around Munich anchors spherical Ti-6Al-4V ELI powder production for implant-grade titanium, concentrating upstream capacity among three gas atomization facilities that extract premium pricing from orthopedic device manufacturers facing FDA master file compliance costs.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate titanium powder procurement, though surgical planning software licenses command subscription-tiered pricing based on hospital system scale and FDA 510(k) clearance status. Price differentiation separates ISO 13485-certified production cells from prototyping-grade service bureaus, with certification premiums widening as EU MDR technical documentation requirements intensify. Cost compression in polyjet anatomical modeling reflects desktop system commoditization and reimbursement code standardization. Academic medical centers exhibit lowest price sensitivity due to bundled research funding, while private audiology clinics face acute pressure from same-day turnaround competitors.
Supply Chain Analysis
Supplier-financing facilities from German specialty powder producers extend 90-day payment terms to mid-volume implant manufacturers, reducing working capital strain for lot sizes below traditional CNC milling minimums. Raw material supply concentrates in Germany, the United States, and Japan for spherical titanium alloys, with PEEK filament drawing from Belgian and Chinese polymer extrusion. Single-source vulnerability persists for electron beam melting filament wire, where two producers serve the global installed base. Distribution runs through ISO 13485-certified contract manufacturers in Switzerland and the United States, with hospital point-of-care cells bypassing traditional device distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where FDA master file databases create regulatory entrenchment that locks out unvalidated competitors and sustains incumbent pricing power across implant categories.
For Market Incumbents: Pre-empt software workflow integration by acquiring surgical planning platforms before hospital IT departments consolidate vendor relationships. Defend position by expanding point-of-care manufacturing service contracts with VA medical centers, neutralizing the threat of distributed production challengers. Prioritize backward integration into titanium powder recycling to offset gas atomization supply concentration.
For New Entrants and Emerging Players: Establish a beachhead in cranio-maxillofacial titanium plates, where patient-specific mandible reconstruction remains underpenetrated relative to mature spinal markets. Target audiology clinic networks for desktop DLP hearing aid production, leveraging same-day turnaround as the primary go-to-market wedge against centralized manufacturing competitors.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA breakthrough device pathways and EU MDR conformity bottlenecks concentrate market access among pre-cleared platform holders. Acquisition targets should display ISO 13485 certification with hospital GPO contract penetration. The signal to watch is CMS reimbursement expansion for preoperative anatomical modeling, which would inflect software revenue multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Master File Expansion | Accelerates 510(k) submissions for laser powder bed fusion orthopedic hardware. |
| Hospital System Partnership | Locks in multi-year point-of-care manufacturing contracts with Cleveland Clinic procurement. |
| Software Companion Development | Integrates DICOM-to-print workflows with Materialise surgical planning platforms. |
| CE Marking Pathway | Opens EU MDR conformity assessment for patient-specific spinal cages in Germany. |
| Reimbursement Strategy | Secures CPT code coverage for preoperative anatomical modeling in VA medical centers. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and orthopedic device regulatory leads; and secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and ISO/ASTM standards documentation. Bottom-up equipment shipment data triangulated against top-down implant procedure volumes across the analysis window.
Forecast inputs considered technology adoption curves, regulatory pathway timelines, and reimbursement expansion scenarios across product type, end user, application, and regional regulatory cluster dimensions. CAGRs derived from logistic diffusion modeling of point-of-care manufacturing penetration and titanium powder cost trajectories. Industry-specific inputs incorporated laser powder bed fusion system repeatability thresholds and EU MDR notified body capacity constraints.
Sensitivities concentrate around FDA guidance revisions for point-of-care 3D printing and EU MDR implementation delays affecting patient-specific implant classifications. Forecasts reflect documented assumptions about hospital capital expenditure cycles and titanium powder supply expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Home Dialysis Systems Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Photopheresis Products Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
United States Insulin Pumps Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Internal Trauma Fixation Device Market
Medical Devices
UHD Surgical Display Market
Medical Devices
Single-Use Centrifuge System Market
Medical Devices
Global Pessary Market
Medical Devices
Heart Failure POC and LOC Devices Market
Medical Devices
Global Disability Devices Market