
 Lumbar Disc Replacement Device Market | 2026-2036
Lumbar Disc Replacement Device Market Size, Share, and Industry Trends Forecast 2026-2036
Lumbar Disc Replacement Device Market Outlook
Modular implant configurations are restructuring how purchasing committees evaluate total procedure economics. Medtronic leverages its broad spine portfolio to anchor hospital contracts across integrated delivery networks. Zimmer Biomet competes through specialized orthopedic focus and deep surgeon training infrastructure. NuVasive differentiates via lateral surgical approach integration with disc replacement workflows.
A lumbar disc replacement device is a mechanical prosthesis, typically comprising a polyethylene core between cobalt-chromium or titanium endplates, designed to restore segmental motion after discectomy rather than fusing adjacent vertebrae. Artificial discs command the largest revenue share among product types due to premium pricing and established reimbursement codes. Biomaterials represent the fastest-growing material category as osteobiologic coatings gain traction for bone-implant integration. Orthopedic clinics are expanding fastest among end users as ambulatory surgical centers build spine capabilities.
The FDA's premarket approval process and the EU Medical Device Regulation impose extensive clinical evidence requirements that filter market entrants and extend development timelines. ISO 14155 governs clinical investigation standards for orthopedic implants, while Japan's PMDA maintains distinct biomechanical testing protocols that shape product design for Asian markets. Stakeholders must monitor evolving real-world evidence requirements and payer technology assessment processes as these gates increasingly determine commercial access.
Market Dynamics
Hospital purchasing committees now evaluate lumbar disc replacement devices through total procedure economics rather than implant cost alone, forcing manufacturers to bundle training, instrumentation, and warranty terms into contract structures.
Growth Catalysts
- Commercial payer coverage expansion:UnitedHealth, Anthem, and Aetna have broadened prior authorization pathways for single-level disc arthroplasty, reducing patient out-of-pocket exposure and accelerating procedure scheduling in ambulatory settings.
- EU Medical Device Regulation harmonization:MDR Article 54a creates a centralized pathway for Class III implantable devices, reducing redundant notified body audits across Germany, France, and the Netherlands while maintaining clinical evidence standards.
- Polyethylene-on-ceramic bearing surfaces:Next-generation articulation materials demonstrate superior wear characteristics in ISO 18192-1 testing protocols, extending device longevity claims and expanding indications to younger patient cohorts.
Market Restraints
- Cobalt-chromium alloy supply concentration:Three specialty foundries in Germany and Sweden control over 70 percent of medical-grade cobalt feedstock for endplate casting, creating vulnerability to energy price shocks and export licensing delays.
- FDA premarket approval timeline:The agency's orthopedic and rehabilitation devices panel requires minimum 24-month follow-up data for motion-preserving spine indications, extending development cycles and capital lockup periods for novel designs.
- Spinal fusion substitution threat:Minimally invasive TLIF procedures with 3D-printed titanium cages achieve comparable clinical outcomes at 40-60 percent lower implant cost, pressuring disc replacement volume in price-sensitive hospital systems.
Strategic Opportunities
- Japanese reimbursement tailwind:PMDA's 2024 revision to the medical fee schedule elevated artificial disc replacement to a separate procedure code with premium reimbursement, opening procedural volume in an aging population with high lumbar degeneration prevalence.
- ASC channel penetration:Ambulatory surgical centers in Florida, Texas, and Arizona are building dedicated spine suites with C-arm navigation, creating demand for compact, single-tray instrument sets compatible with same-day discharge protocols.
- AI-assisted preoperative planning:Machine learning algorithms analyzing CT-based bone density mapping are converging with patient-specific implant sizing databases, enabling personalized endplate geometry selection and reducing revision rates.
Industry Challenges
- Surgeon training pipeline constraints:The lateral retroperitoneal approach for L4-L5 disc replacement requires 50+ proctored cases for competency certification, and academic medical centers have reduced fellowship positions due to reimbursement compression on training time.
- ISO 14155 clinical investigation compliance:Multicenter trials across US and EU sites demand harmonized electronic data capture systems, adverse event reporting workflows, and statistical analysis plans that extend study startup by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lumbar Disc Replacement Device Market |
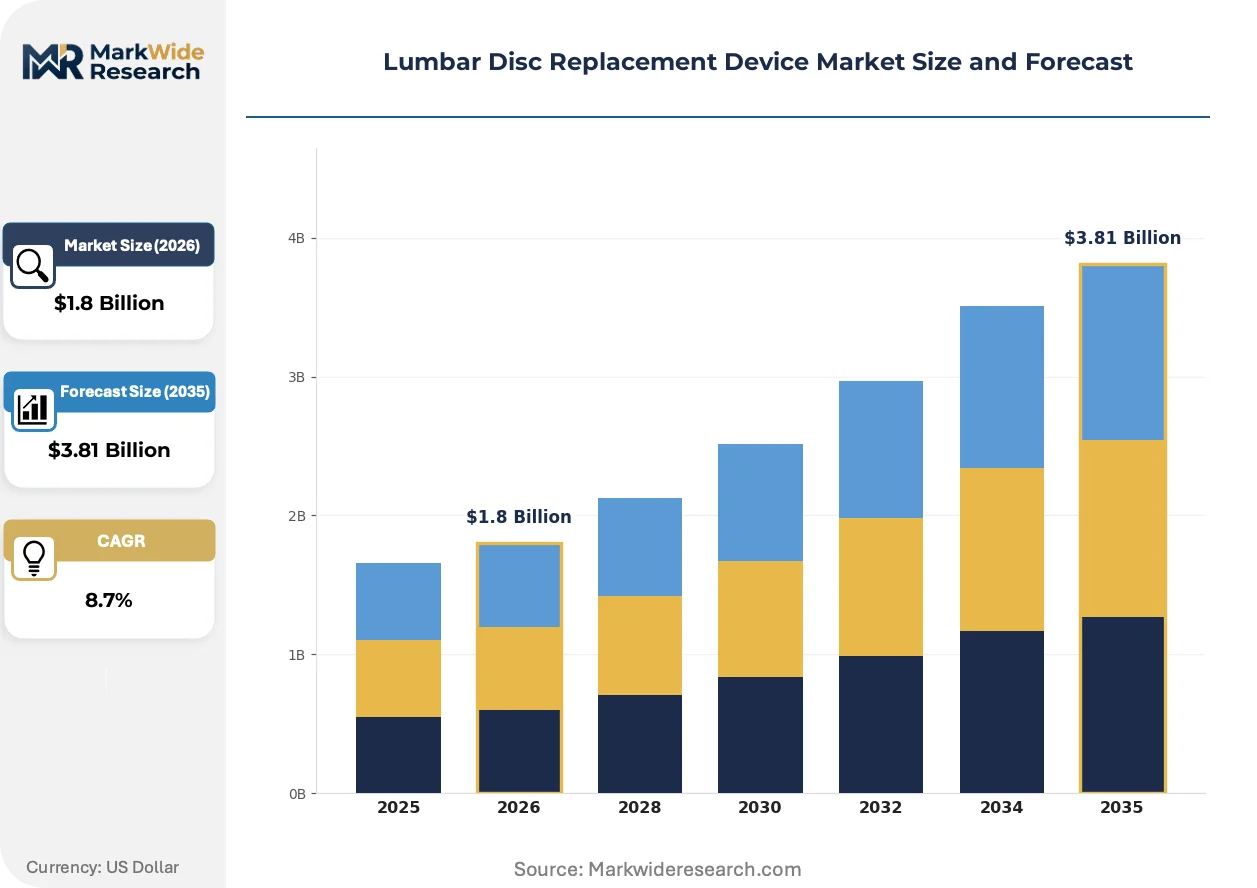
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Discs, Implantable Devices, Surgical Tools, Biomaterials End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Surgeons Material: Polyethylene, Titanium, Composite Materials, Metal Alloys Application: Spinal Surgery, Pain Management, Orthopedic Treatments, Neuro Surgery |
| Companies Covered | Centinel Spine, Aesculap, AxioMed, Medtronic, Zimmer Biomet, NuVasive, Globus Medical, Spineart, B. Braun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lumbar Disc Replacement Device Market Strategic Shifts
Biomaterial surface engineering and digital surgical planning tools are compressing the gap between preoperative templating and intraoperative execution, reshaping how device manufacturers support procedure adoption.
3D-printed titanium lattice structures with optimized pore geometries between 300-500 micrometers are electrifying osseointegration performance in vertebral endplate fixation. Orthopedic clinics in sunbelt states with high Medicare Advantage penetration are adopting these surfaces fastest, recognizing reduced subsidence rates as a competitive differentiator for bundled payment contracts. The technology is electrifying manufacturer R&D priorities, with coating development timelines now matching core mechanical design cycles.
Japan's PMDA has implemented distinct biomechanical testing protocols requiring six degrees of freedom wear simulation under coupled loading conditions, exceeding FDA and ISO requirements for spinal motion preservation devices. Japanese orthopedic device distributors must submit device master files documenting fatigue testing to 10 million cycles, creating a regulatory moat that favors established players with dedicated Yokohama testing facilities. Lumbar disc manufacturers targeting Japanese hospital procurement are responding by establishing localized biomechanical validation partnerships with Tokyo Institute of Technology research groups.
Hospital value analysis committees now require health economic evidence demonstrating two-year cost equivalence against spinal fusion before granting new technology add-on payment status. Device manufacturers are displacing traditional sales representative coverage models with embedded clinical specialists who manage patient registry enrollment and real-world evidence collection. This behavioral shift is most visible in California and New York health systems where integrated delivery networks control orthopedic referral patterns and track implant utilization through centralized supply chain analytics platforms.
Lumbar Disc Replacement Device Market Segmentation
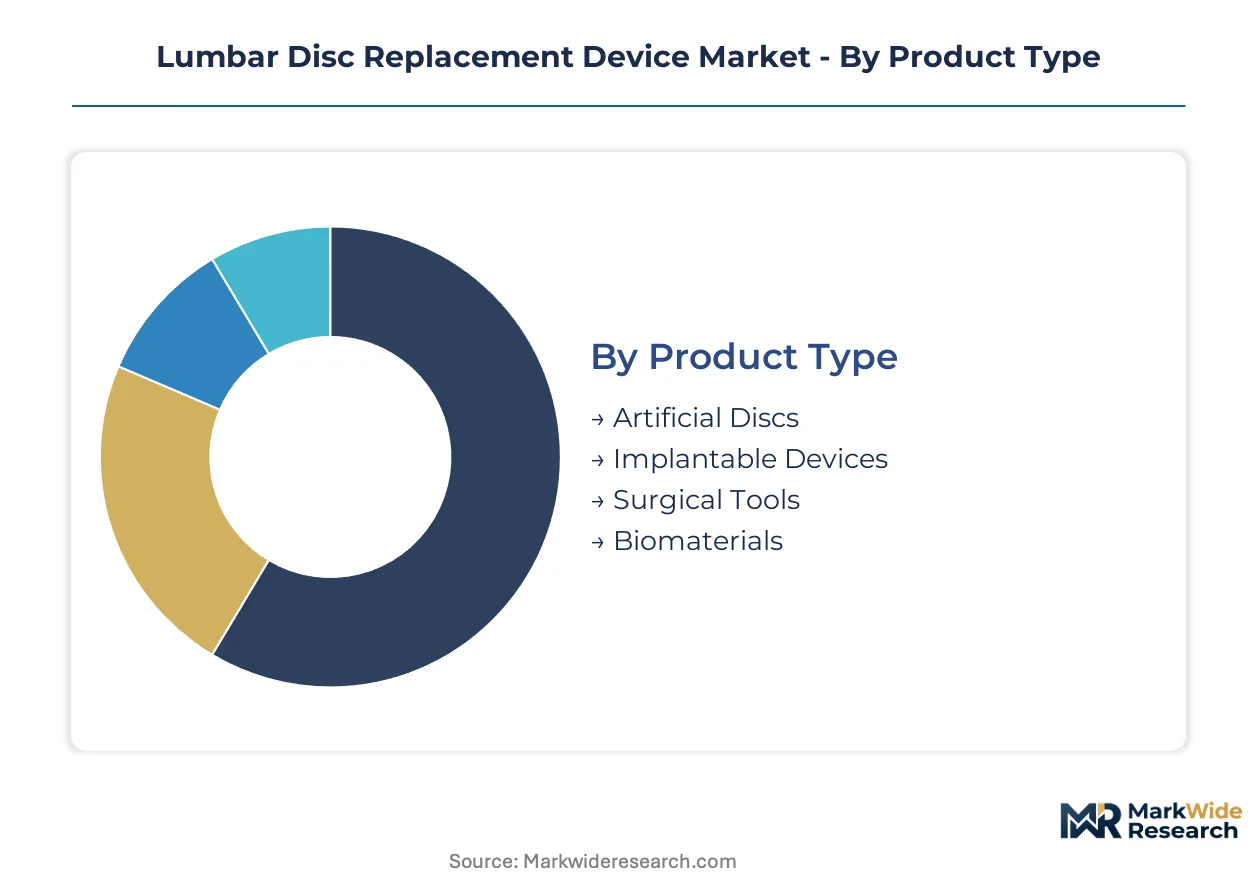
Segmentation in the lumbar disc replacement market reveals how purchasing committees weight implant performance against procedural economics. Manufacturers align R&D priorities and distribution investments around these category boundaries to defend contract positions across integrated delivery networks.
Product Type:
Supply concentration in cobalt-chromium casting and polyethylene molding shapes competitive positioning across product categories.
- Artificial Discs:Mechanical prostheses with polyethylene cores between cobalt-chromium or titanium endplates restore segmental motion after discectomy. Hospital systems in Germany anchor motion-preserving spine programs around these devices, with purchasing committees demanding bundled training and warranty terms.
- Implantable Devices:Prosthetic assemblies designed for permanent vertebral integration include endplate fixation systems and motion-preservation mechanisms. Demand concentrates in the United States, where aging demographics and commercial payer coverage decisions from UnitedHealth, Anthem, and Aetna drive procedure volume.
- Surgical Tools:Specialized instrumentation kits enable disc space preparation and implant insertion.
- Biomaterials:Osteobiologic coatings and surface treatments enhance bone-implant integration.
Artificial discs absorb the bulk of installed capacity; biomaterials are expanding most quickly as osteobiologic coatings gain traction.
End User:
Cost tier differentiation separates high-volume hospital systems from specialized ambulatory channels.
- Hospitals:Acute care facilities with comprehensive spine surgery programs manage complex multi-level procedures and revision cases. Value analysis committees in California and New York health systems require two-year cost equivalence evidence against spinal fusion before granting new technology add-on payment status.
- Orthopedic Clinics:Dedicated musculoskeletal facilities build ambulatory surgical capabilities for same-day discharge protocols. Centers in Florida, Texas, and Arizona are constructing dedicated spine suites with C-arm navigation, creating demand for compact single-tray instrument sets.
- Rehabilitation Centers:Post-acute facilities manage patient recovery and functional outcome monitoring.
- Surgeons:Individual practitioners and group practices drive technology adoption through training certification and case volume.
Hospitals command the largest revenue concentration; orthopedic clinics are gaining share fastest as ASC channel penetration accelerates.
Material:
Volume distribution reflects raw material availability and regulatory validation requirements across geographies.
- Polyethylene:Ultra-high molecular weight polymer cores provide low-friction articulation surfaces in bearing couples. Wear characteristics under ISO 18192-1 testing protocols determine longevity claims and indication expansion to younger patient cohorts.
- Titanium:Biocompatible metal endplates and lattice structures optimize osseointegration through pore geometry control. 3D-printed titanium with 300-500 micrometer pores electrifies fixation performance in sunbelt states with high Medicare Advantage penetration.
- Composite Materials:Hybrid constructions combine polymer and ceramic elements for tailored mechanical properties.
- Metal Alloys:Cobalt-chromium formulations dominate endplate casting despite supply concentration risk from German and Swedish specialty foundries.
Metal alloys absorb the bulk of installed capacity; titanium is climbing the fastest as additive manufacturing capabilities mature.
Application:
Customer type segmentation separates procedure reimbursement tiers and technology assessment pathways.
- Spinal Surgery:Disc arthroplasty procedures performed by orthopedic and neurosurgical specialists address degenerative disc disease. The FDA's premarket approval pathway for Class III orthopedic devices shapes product development timelines and clinical evidence requirements.
- Pain Management:Interventional approaches targeting chronic lumbar radiculopathy and mechanical back pain. Japan's PMDA 2024 medical fee schedule revision elevated artificial disc replacement to a separate procedure code with premium reimbursement.
- Orthopedic Treatments:Comprehensive musculoskeletal care integrating disc replacement with broader spine interventions.
- Neuro Surgery:Neurological specialty procedures addressing nerve root compression and spinal cord considerations.
Spinal surgery absorbs the bulk of installed capacity; pain management is gaining share fastest as reimbursement pathways broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of cobalt-chromium endplates concentrates in German and Swedish specialty foundries, while procedural demand clusters in aging populations across North America, Western Europe, and East Asia. This production-consumption divide shapes logistics costs and regulatory compliance strategies for device manufacturers.
United States
Commercial payers including UnitedHealth, Anthem, and Aetna have broadened prior authorization pathways for single-level disc arthroplasty, reducing patient cost exposure. The FDA's premarket approval pathway for Class III orthopedic devices imposes minimum 24-month follow-up data requirements. Hospital systems in California and New York operate centralized supply chain analytics platforms that track implant utilization and bundle training into contract structures.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia are expanding motion-preserving spine programs with dedicated procurement committees. The EU Medical Device Regulation Article 54a creates a centralized pathway for Class III implantable devices, reducing redundant notified body audits while maintaining clinical evidence standards. Specialty foundries in the Ruhr region control substantial medical-grade cobalt feedstock capacity for endplate casting.
Japan
PMDA's 2024 revision to the medical fee schedule elevated artificial disc replacement to a separate procedure code with premium reimbursement, opening procedural volume in an aging population with high lumbar degeneration prevalence. The regulator mandates six degrees of freedom wear simulation under coupled loading conditions, exceeding FDA and ISO requirements. Tokyo Institute of Technology research groups partner with manufacturers for localized biomechanical validation.
Australia
The TGA maintains alignment with ISO 14155 clinical investigation standards for orthopedic implants, facilitating trial data reciprocity with EU and US regulators. Private health insurers in New South Wales and Victoria are expanding coverage for motion-preserving spine procedures. Sydney and Melbourne hospital networks are building dedicated spine surgery units with integrated training infrastructure.
Switzerland
Swissmedic enforces stringent post-market surveillance requirements for permanent implantable devices, including mandatory registry participation. The country's orthopedic research clusters in Zurich and Geneva specialize in biomaterial surface engineering and wear testing protocols. Swiss hospital procurement operates through centralized cantonal purchasing cooperatives that demand comprehensive warranty and training bundles.
Lumbar Disc Replacement Device Market Competitive Environment
The competitive structure tilts toward diversified orthopedic conglomerates with broad spine portfolios anchoring integrated delivery network contracts. Market concentration reflects high regulatory barriers and capital-intensive clinical trial requirements that filter entrants. Three strategic archetypes dominate: full-line spine platform vendors, motion-preservation specialists with lateral approach integration, and European precision manufacturers with foundry-to-implant vertical control. Competitive moves center on hospital contract bundling and surgeon training infrastructure deployment rather than price competition alone.
Among diversified platform vendors, Medtronic leverages its broad spine portfolio to anchor hospital contracts, while Zimmer Biomet competes through specialized orthopedic focus and deep surgeon training infrastructure. NuVasive occupies a distinct position via lateral surgical approach integration with disc replacement workflows. These three represent the archetype of scale-driven, full-procedure solution providers that purchasing committees favor for total economics contracting.
| Leading Market Players |
|---|
| Centinel Spine |
| Aesculap |
| AxioMed |
| Medtronic |
| Zimmer Biomet |
| NuVasive |
| Globus Medical |
| Spineart |
| B. Braun |
| Others |
Value Chain & Pricing Dynamics
Additive manufacturing adoption in titanium lattice production is compressing lead times for porous endplate structures while simultaneously fragmenting supplier power away from traditional cobalt-chromium foundries. This dual shift restructures how device manufacturers negotiate raw material contracts and bundle instrumentation pricing into hospital system tenders.
Pricing Analysis
Margin tightening in standard-tier artificial discs reflects intensifying competition from 3D-printed titanium cage alternatives that achieve comparable clinical outcomes at lower implant cost. Three-tier pricing structure across premium, standard, and economy levels stratifies by bearing surface technology and warranty duration. Cost-down pressure accelerates because hospital value analysis committees now demand two-year cost equivalence evidence against spinal fusion before granting new technology add-on payment status. Orthopedic clinics in Medicare Advantage-heavy sunbelt states exhibit highest price sensitivity, while academic medical centers with bundled payment contracts show lowest sensitivity due to outcome-based reimbursement insulation.
Supply Chain Analysis
Cobalt-chromium alloy feedstock rests on specialty foundries concentrated in Germany and Sweden, with three suppliers controlling over seventy percent of medical-grade casting capacity for endplate production. Polyethylene core molding draws from US and Japanese polymer processors, while titanium sponge supply hinges on Chinese and Russian extraction operations subject to export licensing volatility. Single-source vulnerability in German foundry capacity creates exposure to energy price shocks and EU export control expansions. Distribution runs through orthopedic-focused GPOs and direct hospital contracts, with instrument set leasing increasingly bundled into implant pricing to secure multi-year contract locks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lumbar disc replacement market sits in a technology-transition phase where polyethylene-on-ceramic bearing surfaces and AI-assisted preoperative planning are displacing legacy metal-on-polyethylene constructs and manual templating workflows.
For Market Incumbents: Hedge against spinal fusion substitution by deepening captive supply of 3D-printed titanium lattice structures and accelerating PMDA biomechanical validation partnerships for Japanese market access. Lock in multi-year hospital contracts through embedded clinical specialist deployment that manages patient registry enrollment and real-world evidence collection. Prioritize certification investment in lateral retroperitoneal approach training infrastructure to defend against NuVasive's workflow integration advantage. For New Entrants and Emerging Players: Ambulatory surgical center distributors represent the most penetrable channel partner type for gaining initial procedure volume without confronting entrenched GPO relationships. Target Florida, Texas, and Arizona orthopedic clinics building dedicated spine suites with C-arm navigation, where demand for compact single-tray instrument sets outstrips incumbent supply flexibility. Pursue a go-to-market angle centered on AI-assisted preoperative planning software bundled with patient-specific implant sizing databases to differentiate on revision rate reduction. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified orthopedic conglomerates seeking lateral approach capabilities or Japanese regulatory dossiers. Long-term viability favors manufacturers with in-house additive manufacturing of titanium lattice structures and established Yokohama testing facility relationships. Watch PMDA reimbursement code expansions beyond single-level indications as the primary inflection signal for Japanese procedural volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures multi-year contract locks through bundled training and warranty terms in California and New York IDNs. |
| PMDA Biomechanical Validation | Opens Japanese premium reimbursement pathway via Tokyo Institute of Technology testing partnerships. |
| Software Companion Development | Enables AI-assisted preoperative planning integration with patient-specific implant sizing databases. |
| CE Marking Pathway | Leverages MDR Article 54a centralized pathway to reduce redundant notified body audits across Germany, France, Netherlands. |
| Reimbursement Strategy | Captures UnitedHealth, Anthem, and Aetna prior authorization pathway expansions for ASC channel penetration. |
Study Parameters
Document review covered FDA premarket approval filings, EU MDR technical documentation, Japanese PMDA device master files, and hospital procurement database records, complemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation incorporated ISO 14155 clinical investigation standards, CMS Medicare procedure volume data, and commercial payer coverage policy documents. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue assessments across product type, material, and end user segments.
Installed base projections and revenue forecasts derived from modeling penetration rates across spinal surgery and pain management applications, with explicit accounting for polyethylene-on-ceramic bearing surface transition timelines and ASC channel buildout patterns. CAGRs across the analysis window were derived from logistic growth curve fitting to historical procedure volumes, adjusted for reimbursement code expansions and regulatory approval pathway timelines. Key inputs included PMDA medical fee schedule revision impacts, FDA orthopedic and rehabilitation devices panel review durations, and German hospital motion-preserving spine program expansion rates.
Caveats apply where FDA premarket approval timeline extensions, EU MDR notified body capacity constraints, or cobalt-chromium supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding commercial payer coverage stability and surgeon training pipeline capacity. A small set of named triggers—PMDA multi-level indication expansions, Medicare Advantage bundled payment adoption rates, and 3D-printed titanium cage clinical outcome data—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Organ Preservation Market
Medical Devices
EEG and EMG Equipment Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market
Medical Devices
Digital Phoropter Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
India Diabetes Devices Market
Medical Devices
Global Dermatoscope Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Low Vision Aids Market
Medical Devices
Prosthetic Disc Nucleus Market
Medical Devices
Epidural Anesthesia Sets Market
Medical Devices
Facial Implant Market
Medical Devices
Rapid Infuser Market