
 Disinfectant Fogging and Misting Chemicals for Large Facilities Market | 2026-2036
Disinfectant Fogging and Misting Chemicals for Large Facilities Market Size, Share, and Industry Trends Forecast 2026-2036
Disinfectant Fogging and Misting Chemicals for Large Facilities Market Insights
Hospital-grade specification tiers is collapsing toward broader facility-wide deployment as post-pandemic protocols normalize across large commercial infrastructure. Ecolab leverages its integrated service model to bundle chemical supply with application equipment and training programs. Diversey anchors its position through deep relationships with food processing and beverage bottling chains where sanitation audits operate on continuous cycles.
Disinfectant fogging and misting chemicals for large facilities are aqueous or solvent-based formulations engineered for aerosolized dispersion at particle sizes typically between 5 and 50 microns, designed to achieve uniform surface coverage in enclosed volumes exceeding 10,000 square feet without residue accumulation that would damage electronics or corrode stainless steel infrastructure. The primary industrial purpose is pathogen reduction in environments where manual wipe-down protocols prove insufficient for geometrically complex equipment or high-traffic schedules. Hydrogen peroxide formulations lead deployment in pharmaceutical cleanrooms where residue-free evaporation aligns with FDA validation requirements, while quaternary ammonium compounds occupy the volume base in educational institutions and transit authorities where cost-per-square-foot and material compatibility with plastics and rubber dominate procurement criteria. Cold fogging equipment sustains the fastest growth trajectory among deployment methods as battery-powered backpack units reduce corded constraints in active facilities.
EPA registration under FIFRA governs label claims for efficacy against specific pathogen classes, and facilities managers must verify master label alignment with their target organism profiles before procurement. OSHA's Hazard Communication Standard shapes worker training burdens and personal protective equipment requirements during application windows, directly influencing labor cost models and scheduling constraints. The Joint Commission's infection control standards for accredited hospitals create recurring audit pressure that sustains replacement demand regardless of broader budget cycles. Stakeholders must monitor whether emerging state-level green procurement mandates begin restricting quaternary ammonium compounds in favor of peracetic acid or hydrogen peroxide alternatives.
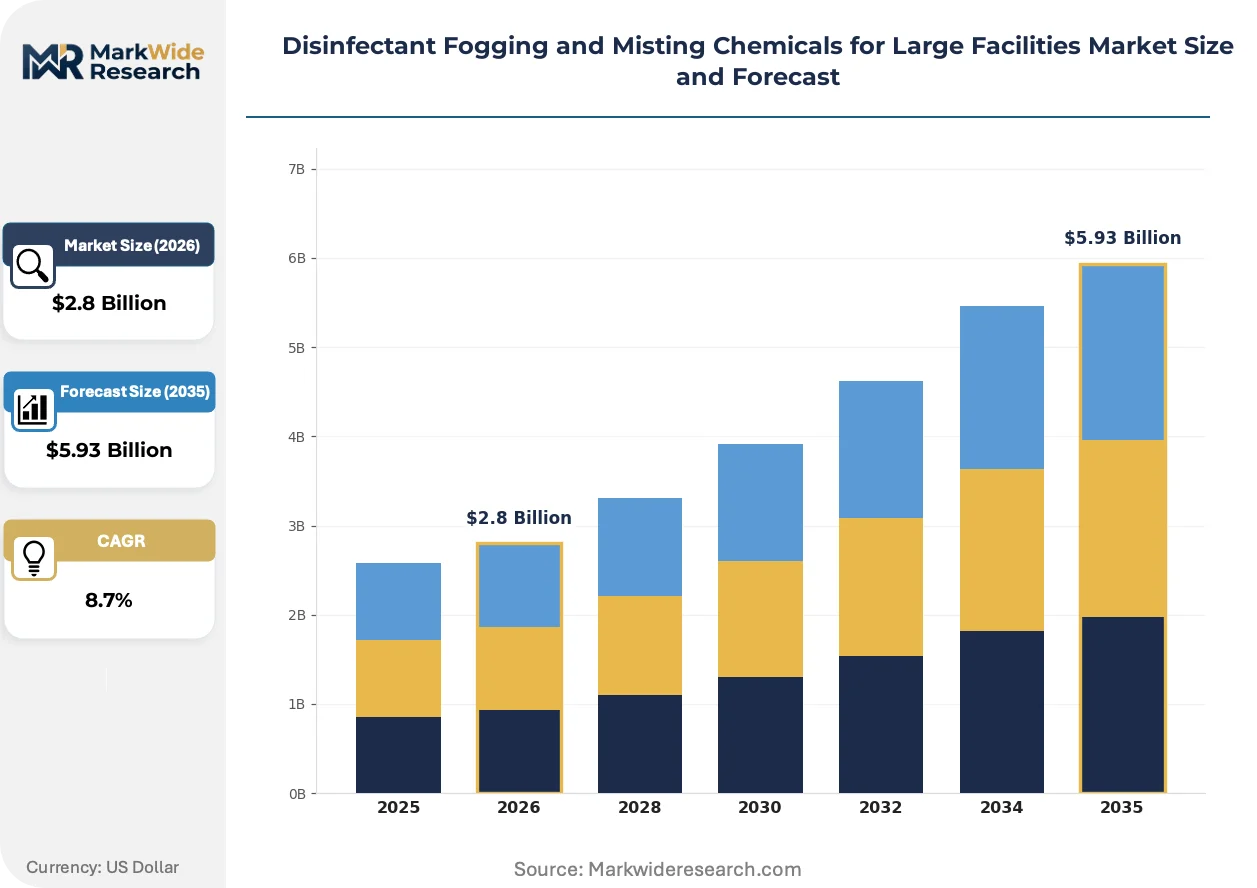
Market Dynamics
EPA registration timelines for emerging viral pathogens are compressing product development cycles while hospital liability frameworks accelerate replacement schedules across outpatient and long-term care wings.
Growth Catalysts
- Joint Commission audit frequency:Accredited hospitals face recurring infection control inspections that sustain chemical demand regardless of broader budget cycles.
- Food processing sanitation audits:Beverage bottling chains operate continuous validation cycles that anchor recurring procurement contracts.
- Battery-powered backpack units:Cordless cold fogging equipment reduces facility downtime constraints in active infrastructure.
Market Restraints
- EPA FIFRA registration friction:Master label alignment requirements for specific pathogen classes extend procurement verification timelines.
- Quaternary ammonium compound restrictions:Emerging state-level green procurement mandates threaten volume-base formulations in educational institutions.
- Hydrogen peroxide input volatility:Pharmaceutical cleanroom grade specifications concentrate supply risk among specialty chemical producers.
Strategic Opportunities
- Transit authority infrastructure:Geometrically complex equipment in high-traffic rail and bus terminals remains underserved by manual protocols.
- Peracetic acid reformulation:Regulatory tailwinds favoring residue-free alternatives create white space for suppliers with validated evaporation profiles.
- Integrated service bundling:Equipment supply combined with training programs captures facility manager preference for single-vendor accountability.
Industry Challenges
- OSHA Hazard Communication compliance:Worker training burdens and personal protective equipment requirements inflate labor cost models during application windows.
- FDA validation documentation:Pharmaceutical cleanroom deployments require extensive residue-free evaporation certification that extends sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disinfectant Fogging and Misting Chemicals for Large Facilities Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogen Peroxide, Quaternary Ammonium Compounds, Sodium Hypochlorite, Chlorine Dioxide, Phenolic Compounds, Peracetic Acid Application: Hospital Sterilization, Food Processing, Pharmaceutical Manufacturing, Educational Institutes, Transportation Vehicles, Sports Arenas Deployment Method: Cold Fogging, Thermal Fogging, ULV Misting, Electrostatic Spraying End User: Healthcare Facilities, Food & Beverage Plants, Academic Institutions, Public Transit Authorities |
| Companies Covered | Ecolab, Diversey, 3M, Procter & Gamble Professional, Reckitt, The Clorox Company, SC Johnson Professional, Neogen, Lanxess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disinfectant Fogging and Misting Chemicals for Large Facilities Market Trends and Innovations
Electrostatic application systems are rewriting coverage efficiency standards while regulatory pressure on residual toxicity reshapes formulation priorities across institutional buyers.
Peracetic acid blends engineered for sub-50 micron aerosolization are decomposing legacy quaternary ammonium dominance in healthcare settings. Hospital facilities in the United States are adopting these formulations at accelerated pace to preempt Joint Commission scrutiny on emerging pathogen coverage. The shift is decomposing volume-based procurement contracts that prioritized cost-per-square-foot over residue profiles.
EPA's emerging viral pathogen guidance under FIFRA is accelerating master label expansion requirements for chemical suppliers. Reformulation cycles now compress from 18-month windows to sub-12-month sprints to maintain claim validity against evolving organism profiles. Hydrogen peroxide specialists face the steepest compliance burden as pharmaceutical cleanroom validation demands outpace regulatory documentation availability.
Facility managers are consolidating vendor relationships around outcome-based service agreements that bundle chemical supply with equipment maintenance and staff certification. Educational institutions and transit authorities in the United States are displacing transactional procurement with multi-year performance contracts. The model shifts risk from buyer to supplier while locking in predictable replacement schedules.
Disinfectant Fogging and Misting Chemicals for Large Facilities Market Segmentation
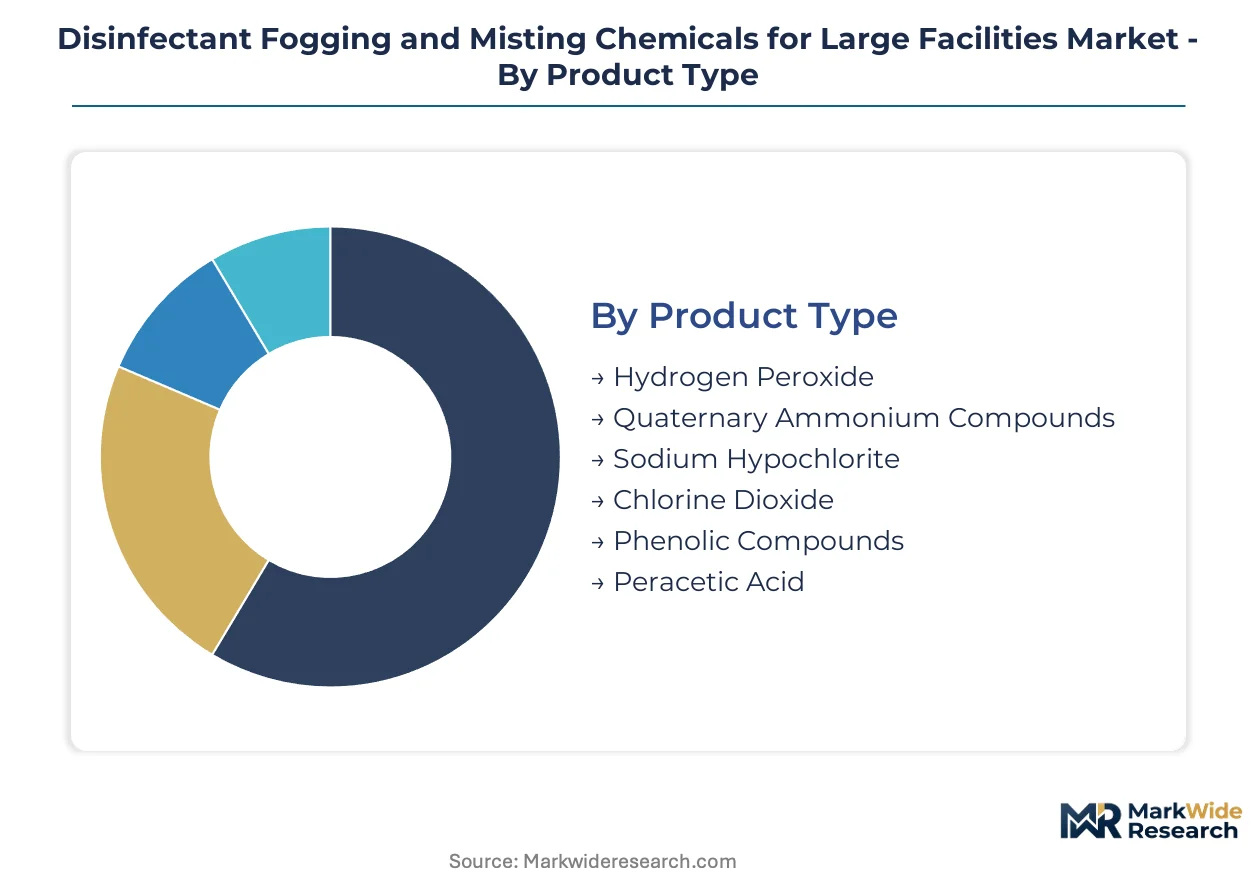
Segmentation in disinfectant fogging chemicals tracks how formulation chemistry, deployment hardware, and facility type create divergent compliance burdens and procurement cycles. EPA registration classes and OSHA exposure limits split the market into distinct specification tiers that resist substitution.
Product Type:
EPA master label requirements under FIFRA segment this category by residue profiles and pathogen claim breadth, with pharmaceutical cleanrooms and hospital OR suites imposing the strictest validation standards.
- Hydrogen Peroxide:Aqueous formulations engineered for complete evaporation without surface residue dominate pharmaceutical cleanroom deployments. FDA validation documentation for residue-free certification sustains premium positioning despite volatile input costs from specialty chemical producers.
- Quaternary Ammonium Compounds:Cost-optimized formulations with broad material compatibility anchor volume procurement in educational institutions and transit authorities. Emerging state-level green procurement mandates threaten this segment's dominance in plastics-heavy environments.
- Sodium Hypochlorite:Bleach-based solutions with established efficacy against enveloped viruses retain position in food processing sanitation protocols where corrosion tolerance permits.
- Chlorine Dioxide:Gas-phase compatible formulations serve specialized pharmaceutical isolator applications requiring sporicidal claims without hydrogen peroxide degradation risks.
- Phenolic Compounds:Legacy formulations persist in veterinary and agricultural facility disinfection where EPA registration history outweighs residue concerns.
- Peracetic Acid:Rapid-decomposition chemistry gains traction in healthcare settings seeking to preempt Joint Commission scrutiny on emerging pathogen coverage.
Quaternary ammonium compounds handle the majority of throughput; peracetic acid is the fastest mover on share.
Application:
Audit frequency and liability exposure stratify demand, with continuous validation cycles in food processing contrasting episodic deep-clean protocols in sports venues.
- Hospital Sterilization:Joint Commission infection control standards sustain replacement demand regardless of broader healthcare budget cycles. Outpatient and long-term care wings are expanding fogging protocols beyond traditional OR suite boundaries.
- Food Processing:Beverage bottling chains operate continuous sanitation audits that anchor multi-year procurement contracts with integrated service providers. Diversey maintains deep relationships across this application through bundled chemical and equipment offerings.
- Pharmaceutical Manufacturing:FDA validation requirements for residue-free evaporation concentrate demand among hydrogen peroxide specialists facing compressed documentation timelines.
- Educational Institutes:Cost-per-square-foot procurement dominates in K-12 and university settings where material compatibility with plastics and rubber seating outweighs premium formulation claims.
- Transportation Vehicles:Geometrically complex rail and bus terminal equipment remains underserved by manual wipe-down protocols, creating white space for cold fogging deployment.
- Sports Arenas:High-traffic event schedules drive demand for rapid-turnaround disinfection between performances, favoring battery-powered backpack units that reduce corded constraints.
Food processing commands the densest contract renewal cycles; transportation infrastructure shows the steepest expansion trajectory as transit authorities upgrade legacy manual protocols.
Deployment Method:
Particle size control and facility downtime tolerance differentiate hardware selection, with cordless mobility gaining preference in active infrastructure.
- Cold Fogging:Battery-powered backpack units eliminate corded constraints in active facilities, sustaining the fastest growth trajectory among deployment methods. Particle sizes between 5 and 50 microns achieve uniform coverage in enclosed volumes exceeding 10,000 square feet.
- Thermal Fogging:Oil-based carrier systems penetrate complex geometries in warehouse and agricultural settings where residue drying time permits extended facility closure.
- ULV Misting:Ultra-low volume precision suits pharmaceutical cleanrooms requiring controlled application rates and documented coverage validation.
- Electrostatic Spraying:Charged particle adhesion rewrites coverage efficiency standards in healthcare and educational settings, though equipment capital costs concentrate adoption among integrated service providers.
Cold fogging captures the majority of new equipment investment; electrostatic spraying is climbing the fastest on technology substitution.
End User:
Procurement sophistication and regulatory audit pressure separate institutional buyers, with outcome-based service agreements displacing transactional chemical purchasing.
- Healthcare Facilities:Hospital-acquired infection liability costs in the United States sustain accelerated replacement schedules. Ecolab leverages integrated service models bundling chemical supply with application equipment and training programs.
- Food & Beverage Plants:Continuous sanitation validation cycles anchor recurring procurement through deep supplier relationships, with audit documentation requirements favoring single-vendor accountability.
- Academic Institutions:Budget-constrained procurement prioritizes cost-per-square-foot over residue profiles, though green procurement mandates are beginning to restrict quaternary ammonium compound selection.
- Public Transit Authorities:Geometrically complex equipment in high-traffic terminals drives adoption of cordless fogging systems that minimize service disruption during operating hours.
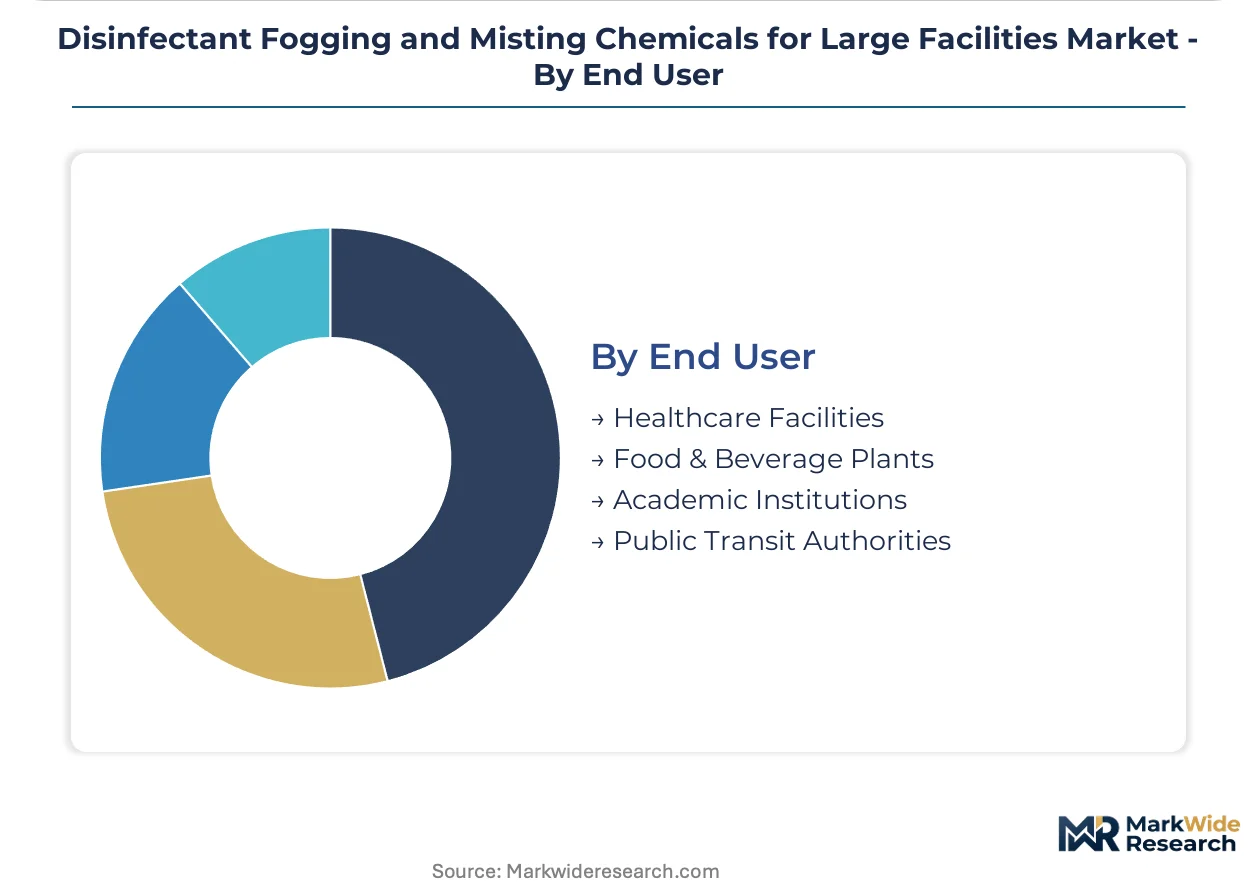
Healthcare facilities generate the most intensive replacement demand; public transit authorities are gaining share fastest as infrastructure disinfection protocols normalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in disinfectant fogging chemicals track regulatory stringency divergence, with formulation specialists in jurisdictions with accelerated EPA-style approval systems capturing premium contract flows from healthcare systems in import-dependent markets.
United States
Hospital-acquired infection liability costs sustain the densest replacement schedules worldwide, with Joint Commission audit frequency forcing accredited facilities into continuous procurement cycles. EPA FIFRA registration requirements under emerging viral pathogen guidance compress supplier reformulation timelines to sub-12-month sprints. The Northeast corridor from Boston to Philadelphia concentrates pharmaceutical cleanroom demand where hydrogen peroxide specialists face steep FDA validation documentation burdens.
Germany
Industrial hygiene standards in food processing and beverage manufacturing anchor recurring sanitation audit cycles that favor integrated chemical-equipment service providers. ECHA REACH compliance requirements for biocidal products under the EU BPR framework extend formulation approval timelines relative to North American counterparts. The Rhine-Ruhr industrial cluster houses concentrated beverage bottling capacity where continuous validation protocols sustain multi-year procurement contracts.
China
Domestic production of hydrogen peroxide and quaternary ammonium feedstocks supplies cost-optimized formulations for institutional cleaning across Asia-Pacific transit infrastructure. NMPA and SAMR regulatory harmonization with international residue standards is accelerating for pharmaceutical export-oriented facilities in the Yangtze River Delta. Shanghai and Suzhou pharmaceutical manufacturing zones drive demand for cold fogging equipment compatible with international cleanroom validation protocols.
India
Budget-constrained procurement in educational institutions and public healthcare facilities prioritizes cost-per-square-foot metrics over residue-free specifications. CDSCO and BIS standards for disinfectant efficacy claims are tightening alignment with EPA and ECHA benchmarks for hospital-grade formulations. Maharashtra and Gujarat industrial corridors concentrate food processing capacity where continuous sanitation audits are beginning to displace episodic deep-clean protocols.
Brazil
Import dependence for specialized hydrogen peroxide formulations creates supply vulnerability for pharmaceutical manufacturers serving Mercosur export markets. ANVISA registration timelines for hospital-grade disinfectants lag EPA and EMA approval cycles, concentrating premium procurement on validated international suppliers. São Paulo state anchors demand from both healthcare systems and food processing chains operating under intensifying sanitation audit pressure.
Disinfectant Fogging and Misting Chemicals for Large Facilities Market Competitive Landscape
Listed leaders compete with private specialists across integrated service bundling versus pure-formulation positioning. The vendor base stratifies into three tiers: multinational chemical conglomerates with full-service hygiene divisions, mid-cap specialists concentrated in single chemistry verticals, and regional formulators serving price-sensitive institutional accounts. Strategic moves center on outcome-based contract restructuring and geographic expansion through distributor partnerships rather than direct facility relationships.
Within the integrated service tier, Ecolab and Diversey exemplify archetypes of bundled chemical-equipment-training positioning, with the former anchored in North American healthcare systems and the latter concentrated in European food processing chains. 3M occupies a distinct materials-science intersection where application hardware and formulation chemistry converge. These three entities represent the dominant competitive anchors against which mid-cap specialists and regional formulators define their market positions.
| Leading Market Players |
|---|
| Ecolab |
| Diversey |
| 3M |
| Procter & Gamble Professional |
| Reckitt |
| The Clorox Company |
| SC Johnson Professional |
| Neogen |
| Lanxess |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at specialty hydrogen peroxide producers in the United States and Germany anchors both supply concentration and price floors for pharmaceutical-grade formulations, while quaternary ammonium compound manufacturing in China sustains volume-tier cost baselines that shape procurement negotiations across educational and transit infrastructure buyers.
Pricing Analysis
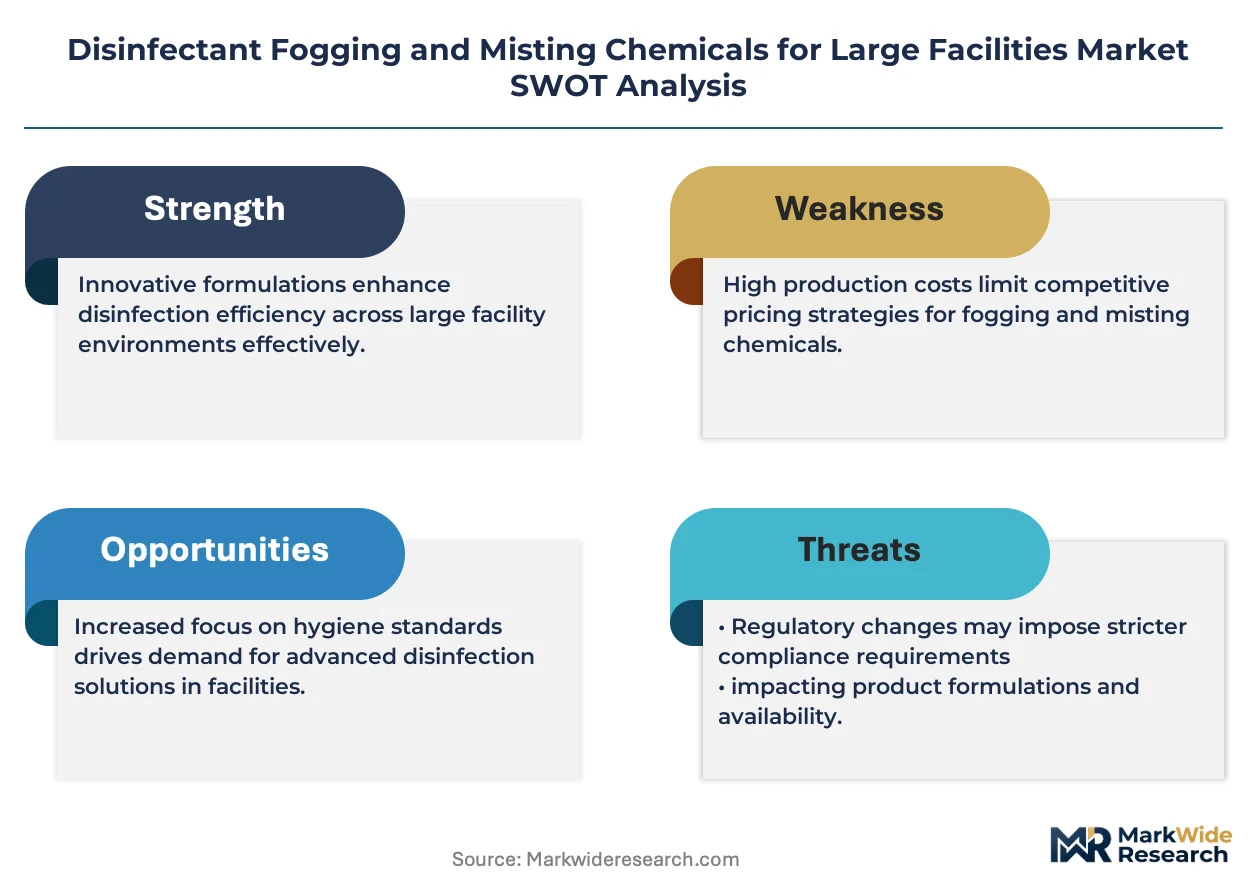
Industrial OEM buyers anchor a contract-based long-term offtake structure that dominates procurement in food processing and healthcare verticals. Price differentiation separates FDA-validated hydrogen peroxide grades from standard quaternary ammonium formulations, with certification level and volume scale as primary tiering mechanisms. Cost compression in the quaternary ammonium segment is intensifying because state-level green procurement mandates are forcing reformulation investments. Educational institutions exhibit the highest price sensitivity, while pharmaceutical cleanroom operators accept premium positioning to secure residue-free validation documentation.
Supply Chain Analysis
Specialty chemical production corridors in the United States, Germany, and China concentrate feedstock supply for divergent formulation tiers. Hydrogen peroxide production draws from captive anthraquinone oxidation capacity and imported peracetic acid precursors, while quaternary ammonium manufacturing rests on domestic amine supply chains. Single-source vulnerability concentrates in pharmaceutical-grade hydrogen peroxide where FDA validation requirements tether buyers to approved suppliers. Distribution runs through integrated service providers bundling chemical supply with equipment and training, displacing transactional distributor models in healthcare and food processing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around integrated service providers as facility managers displace transactional procurement with multi-year outcome-based contracts, fragmenting the vendor base between bundled incumbents and pure-formulation specialists.
For Market Incumbents: Consolidate service bundling depth to preempt displacement by pure-play equipment specialists entering through cold fogging hardware. Ecolab's integrated chemical-equipment-training model demonstrates defensible positioning against emerging entrants with superior battery-powered backpack units. Backward integration into peracetic acid feedstock production secures margin control as regulatory tailwinds accelerate chemistry substitution. For New Entrants and Emerging Players: Lead with cordless cold fogging equipment penetration in transit authority infrastructure where geometrically complex terminal equipment remains underserved by manual protocols. Peracetic acid reformulation services for healthcare accounts facing Joint Commission scrutiny offer the most penetrable white space, with validated evaporation documentation as the critical go-to-market credential displacing incumbent quaternary ammonium relationships. For Investors and Strategic Acquirers: Mid-cap hydrogen peroxide specialists with FDA-validated cleanroom documentation represent the most compelling acquisition archetype for portfolio exposure to pharmaceutical manufacturing growth. Long-term viability hinges on reformulation cycle compression capabilities under EPA emerging viral pathogen guidance. Watch EPA master label expansion velocity as the inflection signal—suppliers maintaining sub-12-month reformulation sprints will capture premium contract flows from liability-exposed healthcare systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peracetic Acid Feedstock | Captures margin expansion as EPA registration requirements accelerate chemistry substitution in healthcare accounts. |
| Cordless Cold Fogging Equipment Launch | Battery-powered backpack units reduce facility downtime constraints in active transit and sports infrastructure. |
| FDA Validation Documentation Investment | Residue-free evaporation certification extends sales cycles but locks in pharmaceutical cleanroom procurement preference. |
| Multi-Year Outcome-Based Service Contracts | Integrated bundling shifts risk from facility managers to suppliers while securing predictable replacement schedules. |
| Geographic Expansion through Distributor Partnerships | Regional formulators in India and Brazil leverage local relationships to displace multinational pricing in budget-constrained accounts. |
Research Methodology
A spread of perspectives from facility managers at healthcare systems, procurement leads at food processing chains, technical directors at chemical formulators, and regulatory affairs specialists at EPA-registered suppliers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA master label databases, FDA 510(k) filings for fogging equipment, customs trade data on hydrogen peroxide imports, and Joint Commission audit frequency reports. Bottom-up facility-level demand modeling triangulated against top-down chemical consumption benchmarks.
Segmentation dimensions modeled include formulation chemistry tier, deployment hardware type, facility application, and end-user procurement sophistication across the projection horizon. CAGRs were derived from replacement cycle analysis and audit-driven demand elasticity rather than extrapolation of historical trends. Industry-specific forecast inputs incorporated EPA emerging viral pathogen guidance timelines and state-level green procurement mandate adoption curves.
Forecasts assume regulatory continuity in EPA FIFRA registration regimes and OSHA Hazard Communication enforcement; material policy shifts would require re-modeling of supplier reformulation cycle assumptions and facility compliance cost burdens. Revision becomes warranted when EPA master label compression timelines or state-level quaternary ammonium restrictions cross thresholds that fundamentally alter chemistry substitution velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Chlorinators Market
Disinfectants and Preservatives
Preservatives Market
Disinfectants and Preservatives
Antimicrobial Chemicals Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
Bleach Gel Market
Disinfectants and Preservatives
North America Disinfectant Wipes Market
Disinfectants and Preservatives
North America Disinfectants and Cleaning Agents Market
Disinfectants and Preservatives
Surface Disinfectant Products Market
Disinfectants and Preservatives
India Air Treatment Products Market
Disinfectants and Preservatives
Disinfection Cap Market
Disinfectants and Preservatives
Deltamethrin Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
Disinfectant & Antimicrobial Chemicals Market
Disinfectants and Preservatives
Global Animal Disinfectants Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Surface Disinfectants Market