
 Global Turbidity Meters Market | 2026-2036
Global Turbidity Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Turbidity Meters Market Foresight
Germany is narrowing its precision instrumentation supply gap through dedicated sensor manufacturing corridors in Baden-Württemberg. Hach Company leverages captive optical component sourcing to sustain margin stability across European utility contracts. Thermo Fisher Scientific anchors its turbidity portfolio within broader water quality analytics suites. Xylem Inc. competes through integrated platform sales linking inline sensors to digital monitoring networks.
Turbidity meters quantify suspended particle concentration in liquid samples by measuring light scattering intensity, typically expressed in nephelometric turbidity units (NTU) with detection thresholds spanning 0.001 to 10,000 NTU depending on optical configuration. These instruments serve regulatory compliance and process control functions where particle load directly correlates with filtration efficiency, disinfection potential, or product clarity. Portable units dominate municipal field inspection workflows due to operational flexibility, while inline configurations capture fastest expansion as chemical firms automate continuous process monitoring. Nephelometric technology leads installed base volumes, though ratio methods gain traction in high-particle environments where single-detector linearity degrades.
EPA Safe Drinking Water Act turbidity standards and EU Drinking Water Directive parametric values compel municipal operators to maintain continuous measurement redundancy, directly sustaining replacement demand cycles. China's MEE surface water classification system and India's CPCB effluent monitoring mandates extend comparable compliance obligations across divergent enforcement architectures. Stakeholders must weigh calibration protocol standardization against emerging laser-based detection architectures that promise expanded dynamic range without consumable replacement cycles.
Market Dynamics
Inline turbidity sensors are displacing portable units across municipal water networks as EPA Safe Drinking Water Act revisions mandate continuous monitoring redundancy over spot-check compliance. This hardware transition compresses replacement cycles and forces vendors to restructure service revenue models around calibration contracts rather than unit sales.
Growth Catalysts
- EPA turbidity mandates:The Safe Drinking Water Act's tightened filtration and disinfection rules compel US municipal operators to deploy redundant inline sensors, sustaining equipment refresh demand across aging treatment infrastructure.
- China's MEE surface water classification:The Ministry of Ecology and Environment's upgraded quality tiers for rivers and lakes are accelerating turbidity meter procurement at provincial monitoring stations and industrial discharge points.
- Laser nephelometry:Solid-state laser sources are extending dynamic range without consumable lamp replacements, reducing total cost of ownership for high-particle environments like mining and paper processing.
Market Restraints
- Optical component concentration:Precision photodiodes and interference filters concentrate among Japanese and German suppliers, exposing meter manufacturers to lead-time volatility and currency fluctuation risk.
- Mercury lamp phase-out:RoHS restrictions on mercury-containing light sources force redesign of legacy tungsten-halogen architectures, imposing non-recurring engineering costs on mid-tier instrument makers.
- Electrochemical substitution:Particle counters and streaming current detectors capture some turbidity applications in chemical process control, narrowing addressable market scope in specific industrial verticals.
Strategic Opportunities
- India's CPCB effluent monitoring:The Central Pollution Control Board's real-time effluent quality monitoring mandates for textile and pharmaceutical clusters create first-time turbidity meter demand in previously unregulated installations.
- Digital twin integration:Convergence of inline turbidity sensors with SCADA analytics platforms enables predictive filtration maintenance, opening subscription-based service revenue streams.
- Brazil's ANVISA pharmaceutical water rules:Purified water quality standards for injectable manufacturing are extending turbidity verification from QC labs to point-of-use distribution loops.
Industry Challenges
- Metrology technician scarcity:Calibration protocol complexity for ratio turbidimeters exceeds skill levels available at smaller municipal utilities, forcing vendor field service dependency or compliance gaps.
- Legacy system interoperability:Proprietary digital protocols from 1990s-era SCADA installations resist integration with modern IoT-enabled sensors, complicating upgrade pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Turbidity Meters Market |
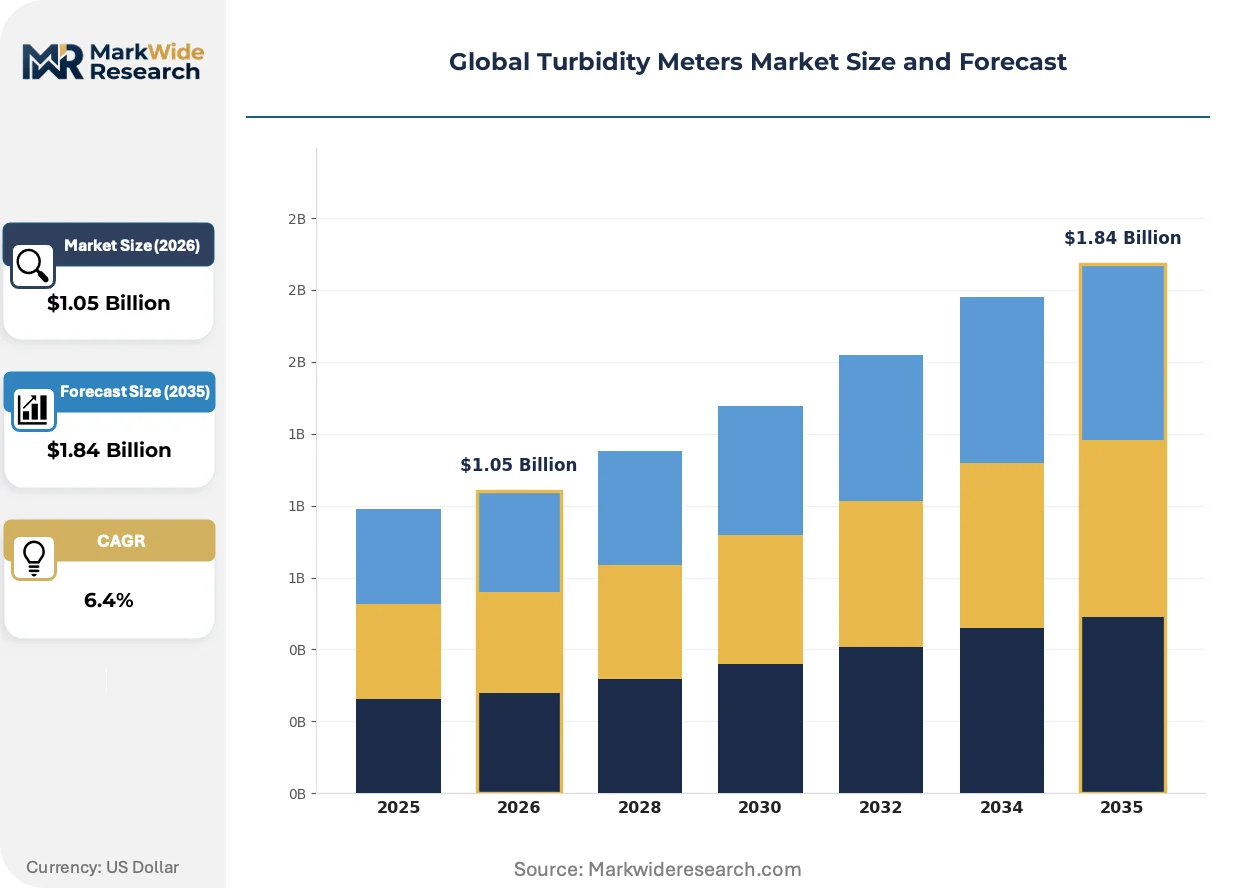
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Benchtop, Inline, Handheld, Panel Mounted Technology: Nephelometric, Ratio, Absorption, Laser, Infrared Application: Wastewater Analysis, Drinking Water Treatment, Industrial Process Control, Food & Beverage, Research Laboratories End User: Municipal Water Plants, Chemical Firms, Agricultural Monitoring, Academic Institutes, Pharmaceutical Manufacturers |
| Companies Covered | Hach Company, Thermo Fisher Scientific, Xylem Inc., Emerson Electric Co., Hanna Instruments, LaMotte Company, Endress+Hauser Group, METTLER TOLEDO, Lovibond (Tintometer Group), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Turbidity Meters Market Shifts & Advancements
Photodetector miniaturization and solid-state light sources are compressing instrument form factors while expanding measurement range, enabling sensor deployment in previously inaccessible process locations. These hardware shifts coincide with regulatory pressure for continuous rather than episodic water quality verification.
Single-detector nephelometry is collapsing into multi-angle ratio architectures as high-particle environments expose linearity limitations in conventional 90-degree scatter measurement. Mining tailings monitoring and ceramic slurry processing adopt ratio methods to maintain accuracy above 2,000 NTU without dilution protocols. This technical transition fragments the installed base between legacy single-angle instruments and upgrade-compatible ratio platforms.
REACH chemical registration requirements and the EU Drinking Water Directive's parametric value revisions are tightening traceability standards for wetted materials in potable water applications. Stainless steel optical windows face substitution by sapphire or coated polymers to eliminate nickel leaching risks. German municipal procurement specifications now prioritize material certificates over brand recognition in tender evaluations.
Calibration service unbundling from hardware sales is restructuring vendor-customer relationships as utilities seek ISO 17025-accredited third-party verification. Independent metrology laboratories in France and the Netherlands capture recurring revenue previously retained by original equipment manufacturers. This channel shift pressures integrated suppliers to certify external service providers or absorb margin compression on bundled contracts.
Global Turbidity Meters Market Segmentation
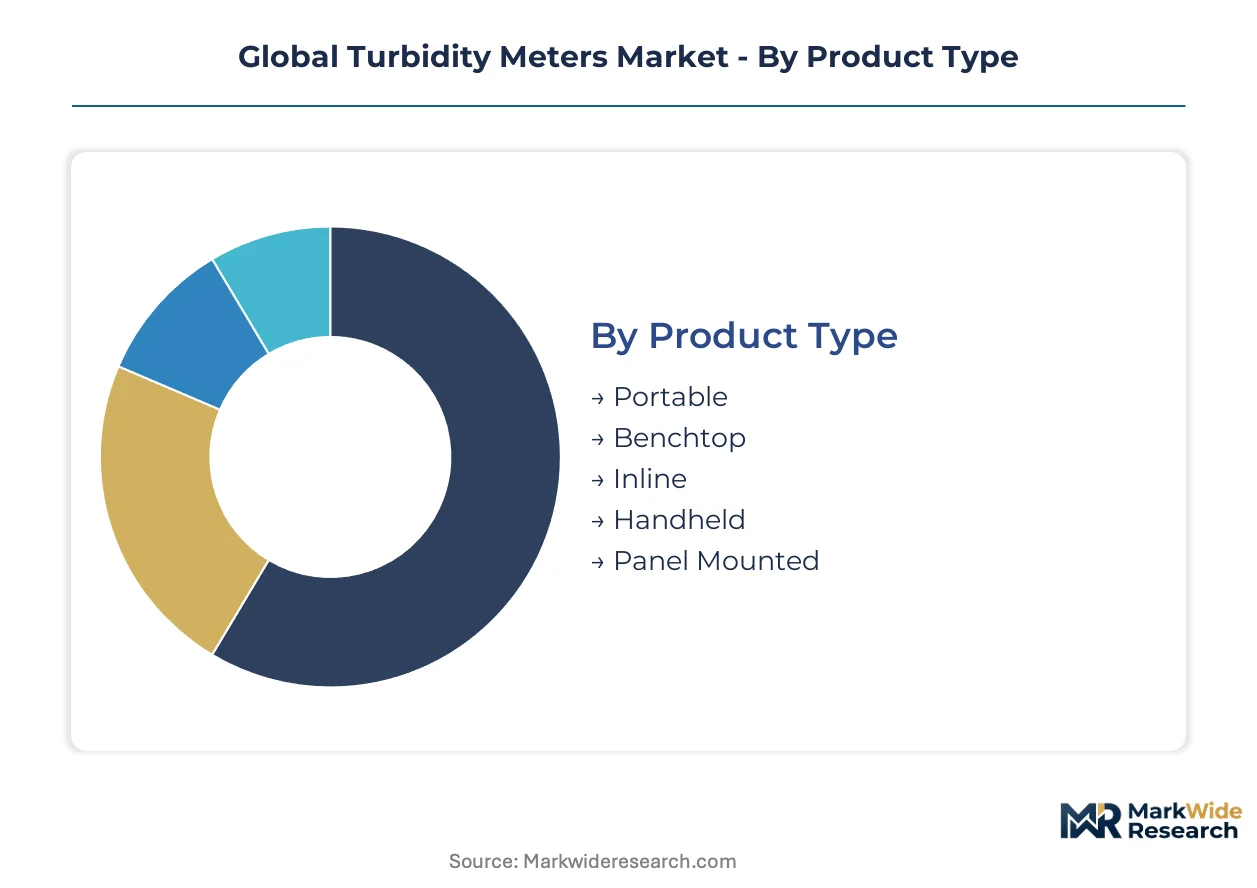
Turbidity meter segmentation reflects divergent operational requirements across field inspection, laboratory precision, and continuous process monitoring. Product form factors, detection technologies, and end-use compliance obligations create distinct procurement criteria that vendors must address through specialized configurations.
Product Type:
Portable units serve spot-check compliance in remote field locations, while inline sensors anchor automated treatment infrastructure requiring continuous verification.
- Portable:Battery-operated instruments with 0-1000 NTU range dominate municipal field inspection workflows where operators test multiple distribution points daily. US EPA Safe Drinking Water Act spot-check mandates sustain replacement demand across aging utility fleets.
- Inline:Process-integrated sensors with 4-20mA output signals capture steepest expansion trajectory as chemical firms automate continuous monitoring and China MEE mandates real-time surface water quality transmission.
- Benchtop:Laboratory-grade units with stabilized light sources serve regulatory certification and research calibration functions.
- Handheld:Compact single-button designs address agricultural drainage monitoring and small utility budgets.
- Panel Mounted:Rack-integrated configurations serve centralized SCADA systems in large municipal treatment plants.
The dominant share belongs to Portable units, while Inline is closing the gap fastest.
Technology:
Detection architectures differentiate by linearity range, consumable requirements, and capital intensity across particle concentration environments.
- Nephelometric:90-degree scatter measurement at 860nm wavelength constitutes the installed base majority, with tungsten-halogen or LED sources. EPA and EU Drinking Water Directive compliance protocols standardize on this method for potable water verification.
- Laser:Solid-state sources eliminate lamp replacement cycles and extend dynamic range above 10,000 NTU without dilution. Mining tailings monitoring in Australia and paper processing in Finland adopt laser architectures for high-particle environments.
- Ratio:Multi-angle detection corrects for color interference and particle size variation in industrial slurries above 2,000 NTU.
- Absorption:Transmittance-based measurement serves high-turbidity applications where scatter methods saturate.
- Infrared:880nm sources minimize interference from dissolved organic color in surface water monitoring.
Nephelometric methods hold the largest installed base, though Laser architectures are expanding most quickly in heavy industrial verticals.
Application:
Regulatory stringency and process criticality determine instrumentation specifications across water security, manufacturing quality, and environmental compliance.
- Drinking Water Treatment:Filtration breakthrough detection and disinfection efficacy verification require 0.001 NTU resolution at regulatory thresholds. US EPA Stage 2 Disinfectants and Disinfection Byproducts Rule compels continuous monitoring redundancy.
- Industrial Process Control:Real-time particle load feedback optimizes coagulant dosing and membrane filtration backwash cycles. Chemical manufacturing in Germany and semiconductor fabrication in South Korea drive precision inline sensor demand.
- Wastewater Analysis:Effluent compliance monitoring at discharge points employs ruggedized portable and inline configurations.
- Food & Beverage:Product clarity verification and CIP rinse validation use sanitary-design sensors with 3-A certification.
- Research Laboratories:Method development and standard reference material characterization require traceable, accredited instrumentation.
Drinking Water Treatment commands the largest revenue share, while Industrial Process Control is gaining share fastest.
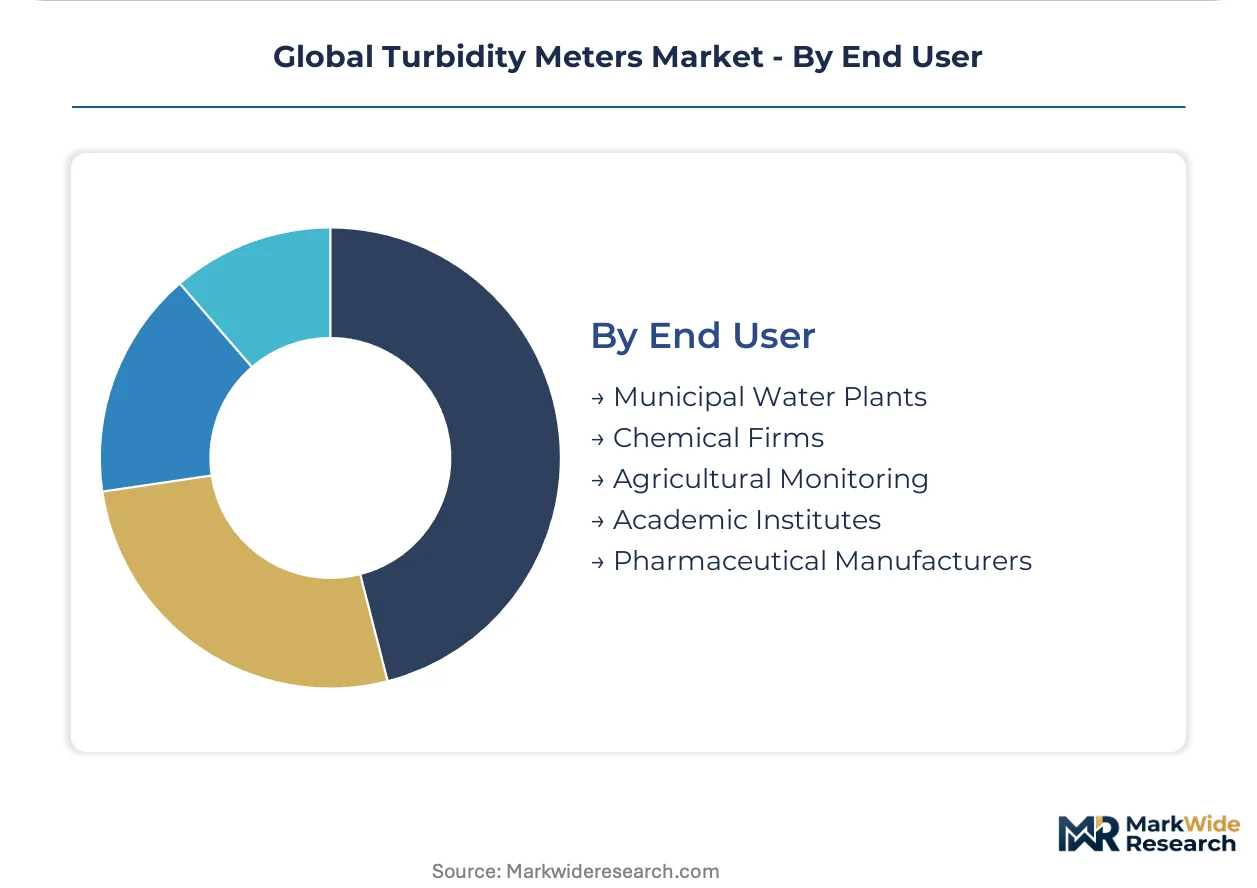
End User:
Procurement authority and technical capability shape vendor relationships across public infrastructure, private manufacturing, and research institutions.
- Municipal Water Plants:Public operators with standardized procurement specifications prioritize EPA-compliant nephelometric methods and multi-year calibration service contracts. Aging US infrastructure and China's rural water safety programs sustain equipment refresh cycles.
- Pharmaceutical Manufacturers:Purified water systems for injectable production require point-of-use verification under US FDA and Brazil ANVISA rules. Turbidity serves as an early indicator of filtration integrity failure.
- Chemical Firms:Process optimization and regulatory discharge monitoring drive inline sensor deployment with digital integration.
- Agricultural Monitoring:Irrigation water quality and runoff compliance employ cost-optimized portable units.
- Academic Institutes:Research and training applications utilize benchtop reference instruments with educational pricing.
Municipal Water Plants retain the dominant procurement volume, though Pharmaceutical Manufacturers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Safe Drinking Water Act revisions anchor demand concentration in the United States, while China's Ministry of Ecology and Environment tightens enforcement architectures. Germany's precision instrumentation corridors and India's Central Pollution Control Board mandates extend compliance obligations across divergent regulatory environments.
United States
Municipal water plants deploy redundant inline sensors under Stage 2 Disinfectants and Disinfection Byproducts Rule requirements. EPA mandates continuous monitoring redundancy over spot-check compliance, compressing replacement cycles across aging treatment infrastructure. Greater Chicago and Houston-Galveston clusters sustain equipment refresh demand through consolidated utility procurement.
China
Provincial monitoring stations accelerate turbidity meter procurement under MEE surface water classification upgrades. Real-time quality transmission mandates for rivers and lakes force hardware transitions at industrial discharge points. Yangtze River Delta municipalities concentrate demand as Shanghai and Jiangsu tighten enforcement protocols.
Germany
Baden-Württemberg sensor manufacturing corridors narrow precision instrumentation supply gaps through dedicated production facilities. EU Drinking Water Directive parametric value revisions tighten traceability standards for wetted materials. Stuttgart-area fabricators prioritize material certificates over brand recognition in municipal tender evaluations.
India
Textile and pharmaceutical clusters face first-time turbidity meter demand under CPCB real-time effluent monitoring mandates. Previously unregulated installations now require continuous verification at discharge points. Gujarat and Maharashtra industrial zones drive procurement volume as enforcement architectures mature.
Brazil
ANVISA purified water quality standards for injectable manufacturing extend turbidity verification from QC labs to point-of-use distribution loops. São Paulo pharmaceutical corridors anchor demand concentration as regulatory alignment with US FDA standards tightens. Rio de Janeiro and Minas Gerais clusters follow with comparable compliance investments.
Global Turbidity Meters Market Competitive Landscape
Capability concentration sits with precision optical specialists; scale advantage sits with diversified instrumentation conglomerates. The vendor base organizes around three strategic archetypes: integrated water analytics platforms, captive component manufacturers, and independent metrology laboratories. Consolidation pressure intensifies as calibration service unbundling forces integrated suppliers to certify external providers or absorb margin compression. Dominant competitive moves include M&A targeting digital integration capabilities and backward integration into photodiode supply.
Among diversified instrumentation conglomerates, Thermo Fisher Scientific anchors its turbidity portfolio within broader water quality analytics suites. Hach Company exemplifies the captive component archetype through optical sourcing strategies that sustain margin stability across European utility contracts. Xylem Inc. occupies a position linking inline sensors to digital monitoring networks through integrated platform sales. These three represent distinct strategic postures rather than direct substitutability.
| Leading Market Players |
|---|
| Hach Company |
| Thermo Fisher Scientific |
| Xylem Inc. |
| Emerson Electric Co. |
| Hanna Instruments |
| LaMotte Company |
| Endress+Hauser Group |
| METTLER TOLEDO |
| Lovibond (Tintometer Group) |
| Others |
Supply & Pricing Matrix
Japanese and German precision photodiode suppliers concentrate upstream optical component manufacturing, anchoring margin pools in meter calibration services and captive sourcing arrangements rather than hardware assembly. This supplier geography compresses pricing flexibility for mid-tier instrument makers while rewarding integrated vendors with service revenue stability.
Pricing Analysis
Price spreads between US municipal procurement and Indian industrial tenders exceed 40 percent for comparable nephelometric configurations. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified redundant systems from single-sensor field units and unbranded portable alternatives. Cost compression in economy tiers intensifies as Chinese manufacturers expand LED-source production. Municipal water plants exhibit lowest price sensitivity due to compliance-driven procurement, while agricultural monitoring buyers prioritize unit cost over calibration bundling.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for interference filter sourcing. Manufacturing concentrates in Japan, Germany, and China for photodetectors, optical windows, and solid-state laser modules respectively. Meter assembly rests on sapphire substrate availability, RoHS-compliant LED packages, and ISO 17025-certified reference standards. Single-source vulnerability concentrates in 860nm interference filters from Hoya and Asahi Glass. Distribution runs through authorized metrology distributors in Europe, direct utility contracts in North America, and regional system integrators across Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The turbidity meters market sits in early-cycle expansion as continuous monitoring mandates displace spot-check compliance across municipal infrastructure. Laser nephelometry adoption in mining and paper processing extends addressable applications beyond traditional potable water verification.
For Market Incumbents: Build calibration service lock-in through ISO 17025 laboratory certification networks. Hach Company's captive optical sourcing model provides template for margin defense against Chinese LED-source competitors. Secure exclusive photodiode allocation agreements with Hamamatsu or Osram to preempt lead-time volatility. Invest in multi-angle ratio platform R&D to capture mining tailings monitoring demand above 2,000 NTU.
For New Entrants and Emerging Players: Build out digital twin integration capabilities for predictive filtration maintenance subscriptions. India's CPCB-mandated textile cluster installations offer most penetrable geography for first-time turbidity meter demand. Target pharmaceutical point-of-use verification under Brazil ANVISA rules through sanitary-design sensor partnerships. Lead with SCADA-native 4-20mA output configurations to bypass legacy protocol interoperability barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed water analytics platforms seeking turbidity module tuck-ins. Five-to-ten year viability hinges on continuous monitoring mandate expansion rather than hardware replacement cycles. Acquire laser nephelometry specialists with mining sector installed base. Watch EPA enforcement variance across US states as inflection indicator for municipal procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photodiode Supply | Captive sourcing from Hamamatsu reduces lead-time exposure for EPA-compliant meter production. |
| Calibration Service Unbundling | ISO 17025 laboratory certification captures recurring revenue from municipal utility contracts. |
| Digital Twin Platform Integration | SCADA analytics convergence enables predictive filtration maintenance subscription models. |
| Multi-Angle Ratio Architecture Launch | Mining tailings monitoring above 2,000 NTU demands linearity correction beyond single-detector limits. |
| Sapphire Optical Window Adoption | REACH-compliant material certificates satisfy German municipal tender evaluations over stainless steel. |
Research Methodology
A standing panel of municipal water plant operators, environmental compliance officers, and metrology laboratory directors provided ongoing calibration against secondary data trends. Primary fieldwork encompassed procurement managers at German utility consortiums, Chinese MEE provincial enforcement teams, and Indian CPCB regional inspectors. Secondary validation drew from EPA enforcement and compliance data, EU Drinking Water Directive implementation reports, China MEE surface water quality transmissions, and SEC filings from listed instrumentation conglomerates. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across technology and application segments.
Scenario bracketing anchored projections across baseline, accelerated regulatory enforcement, and delayed infrastructure refresh pathways. Segmentation modeling spanned product form factor, detection technology, end-use application, and geographic regulatory cluster. CAGRs derived from polynomial trend fitting against historical replacement cycles and policy implementation timelines. Forecast inputs incorporated laser source cost curves, mercury lamp phase-out schedules, and SCADA upgrade penetration rates across municipal utility tiers.
Sensitivities concentrate around EPA enforcement variance, China MEE real-time transmission mandate compliance deadlines, and photodiode supplier capacity expansion timing. Forecasts reflect documented assumptions regarding regulatory implementation pace and technology substitution thresholds. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Polish Water Treatment Chemicals Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
Electrodeionization (EDI) Technology Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
Europe Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
Water Softening Systems Market