
 Global Electrodeionization Market | 2026-2036
Global Electrodeionization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrodeionization Market Intelligence
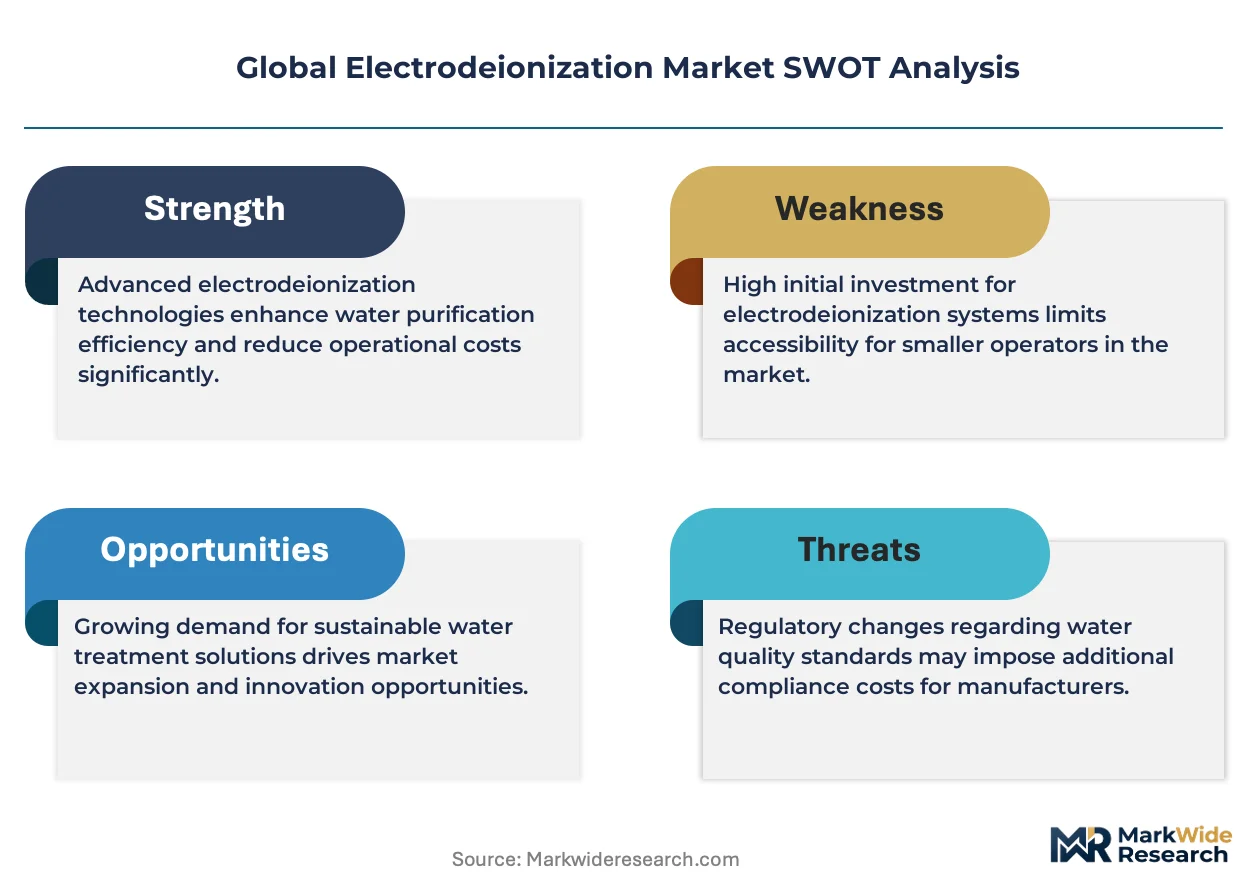
The rising importance of microelectronics fabrication for ultrapure water is realigning the end-use mix away from a sole focus on power generation. Veolia Water Technologies leverages its extensive global service network to serve both established and emerging sectors. DuPont differentiates through its advanced material science, supplying critical ion exchange resins and membrane stacks. Evoqua Water Technologies LLC sustains a strong competitive position in the North American market, particularly within industrial water purification.
Electrodeionization is a water purification process that uses electricity, ion exchange membranes, and resins to deionize water. This technology continuously removes ionized and ionizable species, producing ultrapure water with high resistivity, often exceeding 18 MΩ·cm. Within applications, ultrapure water production for the semiconductor and pharmaceutical industries constitutes the largest segment. The performance of membrane stacks and electrodialysis modules is a critical factor, determining the efficiency and operational cost of the entire system.
Regulatory frameworks directly influence technology adoption across key end-use markets. Water purity standards mandated by the US Pharmacopeia (USP) for pharmaceutical processing and the EU's RoHS directive for electronics manufacturing necessitate high-grade water. In parallel, China's GB standards for industrial water quality push facilities toward more advanced purification methods. Future competitive advantage will depend on developing more efficient, modular systems that can serve decentralized treatment needs in specialized manufacturing.
Market Dynamics
The fundamental demand pivot from traditional power generation towards ultrapure water requirements for microelectronics fabrication is reshaping the electrodeionization market. This shift elevates the importance of system performance, specifically high resistivity and the removal of trace ionizable species.
Growth Catalysts
- Semiconductor Expansion:Investment in new semiconductor fabrication plants, particularly in China and South Korea, creates substantial demand for ultrapure water systems where electrodeionization is a critical final polishing step.
- Stringent Wastewater Regulations:Policies such as the EU's Industrial Emissions Directive and effluent standards from the US EPA encourage adoption of EDI's chemical-free regeneration process to minimize hazardous waste discharge.
- Pharmaceutical Purity Mandates:Water quality standards defined by the US Pharmacopeia (USP) for pharmaceutical manufacturing necessitate the high-purity, low-microbial water that modern EDI systems reliably produce.
Market Restraints
- High Capital Outlay:The initial investment cost for electrodeionization systems is significantly higher than for conventional mixed-bed ion exchange deionization, posing a barrier for smaller enterprises or budget-constrained projects.
- Feed Water Sensitivity:EDI performance is highly dependent on feed water quality, often requiring extensive and costly pre-treatment systems to prevent fouling of membranes and resins from hardness, chlorine, or organics.
- Competition from Alternative Technologies:Advanced reverse osmosis (RO) and membrane degasification technologies are improving, presenting a viable, and sometimes more cost-effective, alternative for applications not requiring the absolute highest resistivity.
Strategic Opportunities
- Modular and Decentralized Systems:Developing compact, modular EDI units can serve the growing need for decentralized water treatment in specialized applications like biotechnology research labs and pilot-scale manufacturing plants.
- Emerging Pharmaceutical Markets:Expanding pharmaceutical and life sciences industries in Southeast Asian countries offer new growth avenues for EDI suppliers as local manufacturing aligns with global quality standards.
- Hybrid System Integration:Designing integrated water purification trains that optimally combine EDI with other technologies, such as reverse osmosis and ultraviolet (UV) treatment, creates value-added solutions for specific end-use challenges.
Industry Challenges
- Skilled Technician Scarcity:A shortage of operators and maintenance technicians with the specialized expertise to manage and troubleshoot advanced EDI systems can limit operational uptime and efficiency for end-users.
- Legacy System Integration:Retrofitting modern EDI modules into existing industrial water purification infrastructure presents significant engineering challenges and can lead to complex and costly integration projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrodeionization Market |
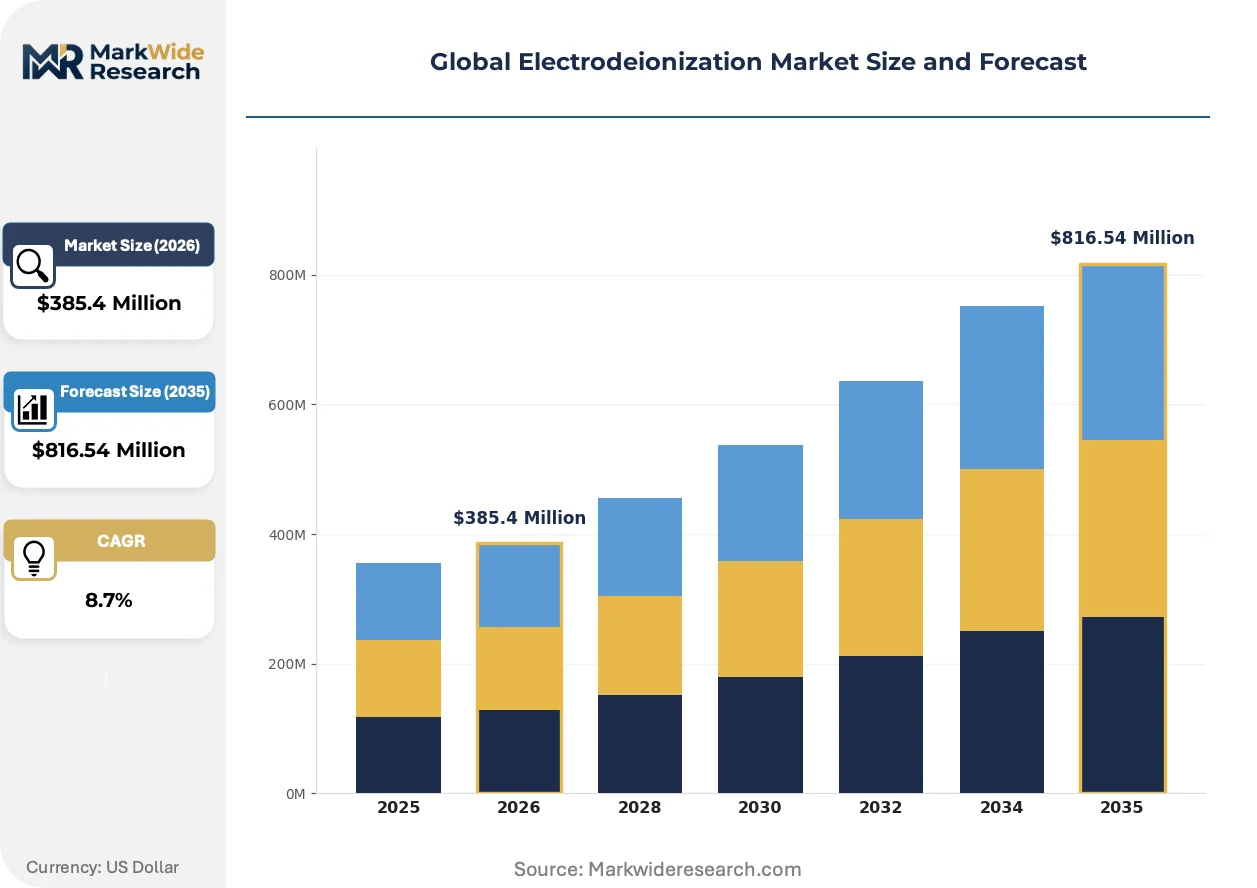
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
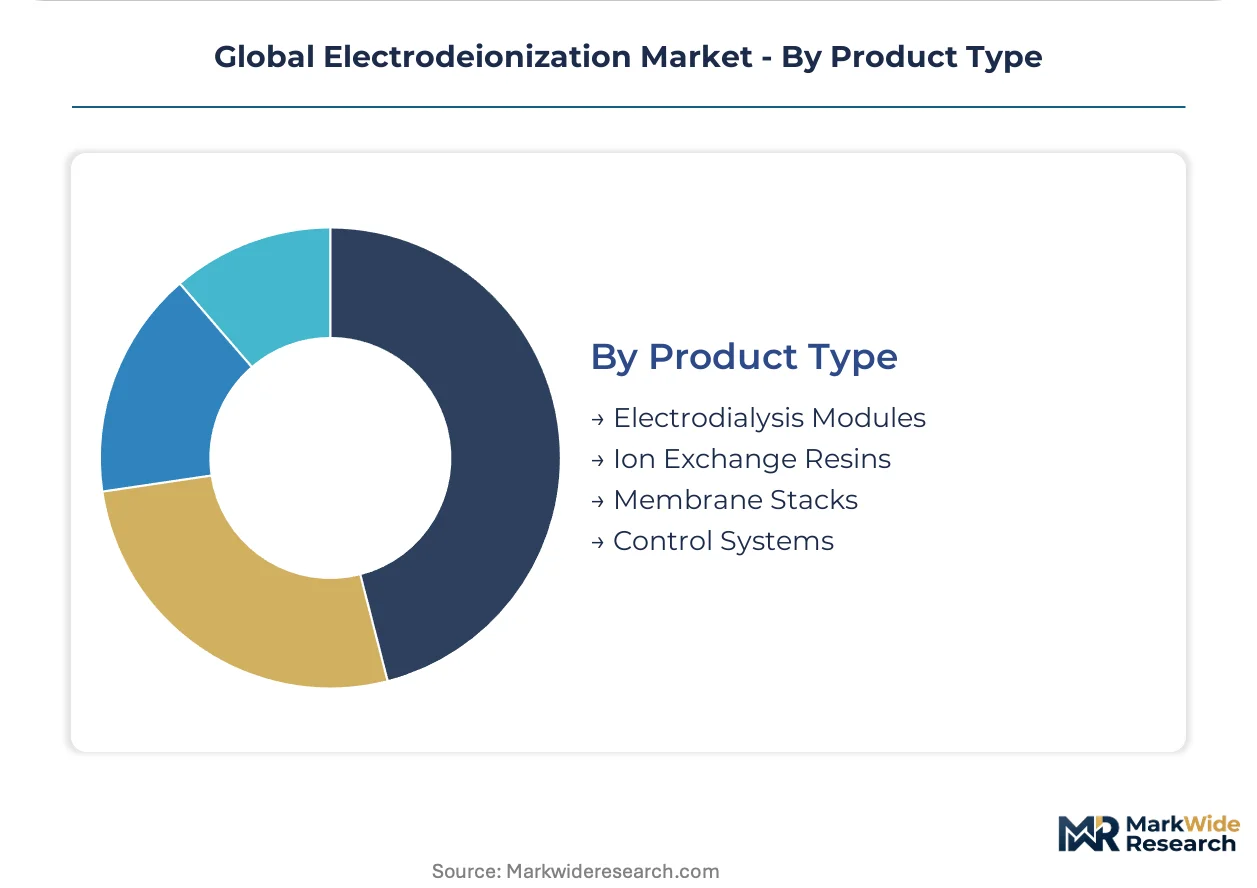
| Segmentation | Technology: Continuous Electrodeionization, Batch Electrodeionization, Modular Electrodeionization, Programmable Electrodeionization Application: Ultrapure Water Production, Pharmaceutical Processing, Power Generation, Microelectronics Fabrication End User: Water Treatment Facilities, Semiconductor Manufacturers, Pharmaceutical Companies, Power Plants Product Type: Electrodialysis Modules, Ion Exchange Resins, Membrane Stacks, Control Systems |
| Companies Covered | SUEZ Water Technologies & Solutions, Pure Aqua Inc., Veolia Water Technologies, Aquatech International LLC, Lenntech B.V., Evoqua Water Technologies LLC, Ovivo Inc., Kurita Water Industries, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrodeionization Market Strategic Shifts & Innovations
Technological refinement in membrane materials and modular system design is intersecting with tightening water purity mandates. This convergence pressures suppliers to deliver higher efficiency and specialized performance for distinct end-use verticals like microelectronics and biopharmaceuticals.
Continuous electrodeionization (CEDI) technology combines ion exchange resins and electricity for constant regeneration without chemical inputs. Pharmaceutical and semiconductor manufacturers are adopting CEDI at a notable pace for final water polishing. This continuous process is overtaking traditional batch-based ion exchange systems, reducing chemical waste, operational downtime, and variability in water quality.
Regulations such as the EU's RoHS directive place strict limits on hazardous substances within electronic components. This mandate indirectly requires electronics manufacturers to utilize ultrapure water for circuit board cleaning and rinsing to prevent ionic contamination. The microelectronics fabrication sector, especially in Germany and Taiwan, is most affected, investing in advanced EDI technology to ensure compliance.
A preference for service-based models for water purification is gaining traction over direct capital equipment sales. This approach often displaces the traditional one-time purchase with long-term agreements that cover system operation, consumables, maintenance, and performance guarantees. This trend is most visible in the North American industrial market, particularly for power generation and chemical processing facilities seeking predictable operational costs.
Global Electrodeionization Market Segmentation
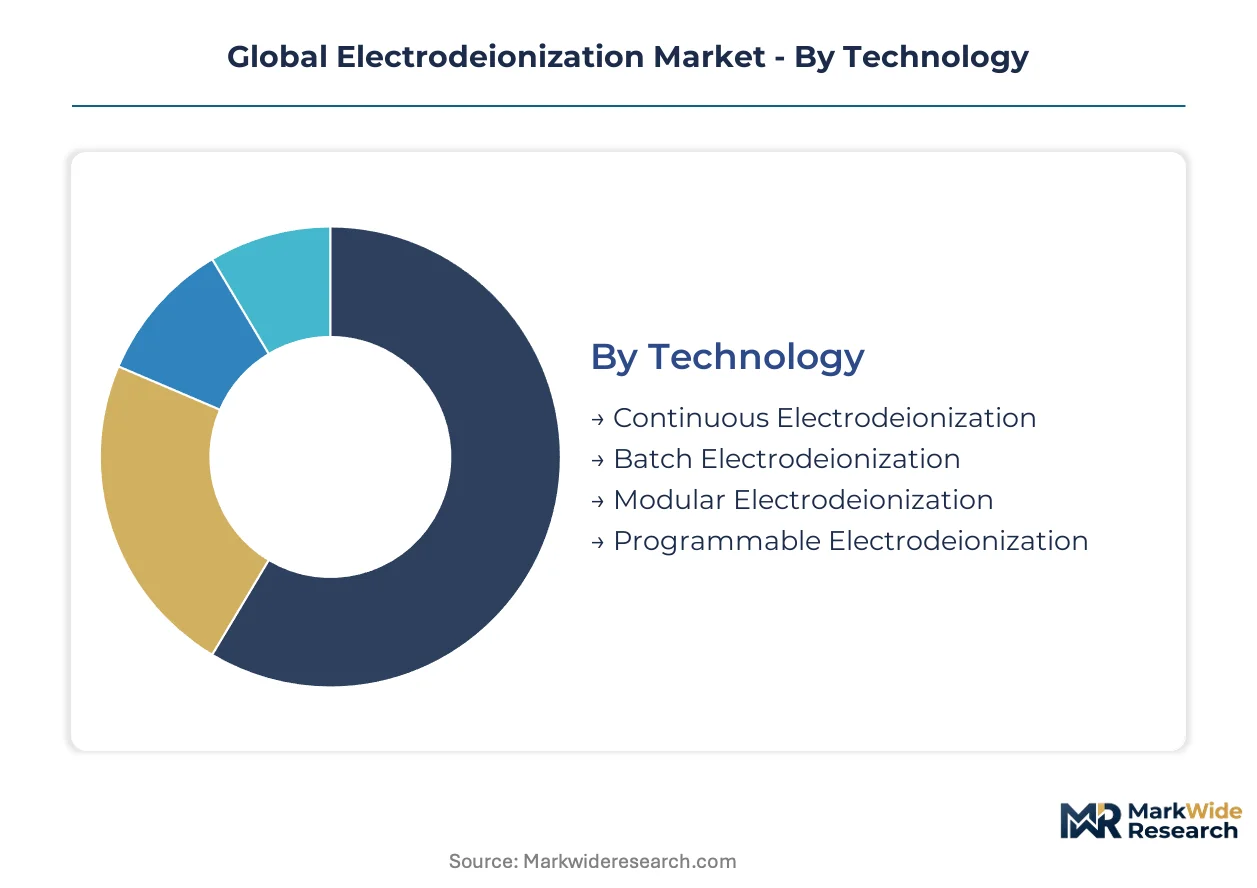
Understanding the segmentation of the global electrodeionization market provides clarity on where investment flows and which technological advancements are gaining traction. This breakdown highlights the varied demands across industries for high-purity water and the specialized components required to achieve it.
Technology:
The capital intensity of electrodeionization systems varies significantly by technology, influencing initial investment thresholds for end-users.
- Continuous Electrodeionization:This technology integrates ion exchange resins and membranes with an electric field for uninterrupted deionization, eliminating the need for chemical regeneration. Demand from semiconductor manufacturing and pharmaceutical production is concentrated in this segment.
- Batch Electrodeionization:These systems operate in cycles, requiring periodic regeneration or replacement of components, offering flexibility for lower volume or intermittent ultrapure water needs. Smaller research facilities often utilize batch systems.
- Modular Electrodeionization:Comprising pre-engineered, standardized units, modular systems allow for scalable and decentralized water treatment solutions, reducing installation complexity and footprint. Biotechnology research labs are increasing their adoption of modular units.
- Programmable Electrodeionization:These advanced systems incorporate intelligent controls for optimized performance, real-time monitoring, and predictive maintenance, enhancing operational efficiency. Industrial water treatment facilities seek programmable features for process control.
Most installed capacity flows through Continuous Electrodeionization. Expansion is steepest in Modular Electrodeionization.
Application:
Application-specific requirements dictate the overall cost structure and operational expenditure for electrodeionization systems.
- Ultrapure Water Production:This broad application encompasses various industries requiring water with extremely low conductivity and minimal ionic contaminants. Microelectronics fabrication represents a significant portion of this demand.
- Pharmaceutical Processing:Water purity standards mandated by the US Pharmacopeia (USP) for drug manufacturing necessitate electrodeionization for producing water for injection (WFI) and purified water. European pharmaceutical plants consistently invest in these systems.
- Power Generation:Electrodeionization systems purify boiler feedwater and condensate streams in power plants, preventing scaling and corrosion in critical equipment. North American power facilities rely on EDI for operational reliability.
- Microelectronics Fabrication:The semiconductor industry demands ultrapure water for chip rinsing and cleaning processes to prevent contamination and ensure device performance. Investments in East Asia's semiconductor plants drive significant demand.
Microelectronics fabrication applications consistently demand the highest purity. Pharmaceutical processing exhibits the most critical validation requirements.
End User:
End-user segments are differentiated by their water volume requirements and the criticality of water purity for their core operations.
- Water Treatment Facilities:Municipal and industrial water treatment plants use EDI for polishing effluent streams or producing high-quality process water. These facilities often require large-scale, robust systems.
- Semiconductor Manufacturers:Companies producing integrated circuits and other electronic components are primary consumers of ultrapure water, utilizing EDI as a final purification step. Major foundries in China and South Korea are key end-users.
- Pharmaceutical Companies:Drug manufacturers and biotechnology firms rely on EDI for producing purified water and water for injection (WFI) for various processes, including active pharmaceutical ingredient (API) synthesis. Global pharmaceutical firms prioritize validated EDI systems.
- Power Plants:Thermal and nuclear power generation facilities employ EDI to produce high-purity water for boiler feed and cooling systems, minimizing equipment downtime. Industrial power producers seek reliable EDI solutions.
Semiconductor manufacturers represent the largest consumer segment for ultrapure water. Pharmaceutical companies show the most consistent demand for validated systems.
Product Type:
The supply concentration for critical product types within electrodeionization influences procurement strategies and component availability.
- Electrodialysis Modules:These modules use an electric potential difference to transport ions through ion-selective membranes, often as a pre-treatment step for EDI or for desalination. Specialized manufacturers supply these components.
- Ion Exchange Resins:Synthetic polymeric materials used to remove ionic contaminants from water, forming a crucial part of the EDI process. DuPont is a significant supplier of these critical materials.
- Membrane Stacks:Assemblies of ion exchange membranes and spacers, forming the core of an EDI system where deionization occurs under an electric field. The performance of these stacks directly impacts system efficiency.
- Control Systems:These components manage and monitor the operational parameters of EDI units, ensuring optimal performance, safety, and integration with broader water treatment trains. Automation suppliers offer these specialized systems.
Membrane stacks are central to system performance. Ion exchange resins experience rapid replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microelectronics fabrication demands for ultrapure water are driving significant electrodeionization market growth across key industrial regions. Stringent environmental regulations and pharmaceutical purity mandates further shape regional adoption patterns. Investment in advanced manufacturing facilities consistently elevates the need for high-purity water systems globally.
China
Investment in new semiconductor fabrication plants creates substantial demand for electrodeionization systems in China. The country's GB standards for industrial water quality push facilities toward advanced purification methods. Major foundries in the Yangtze River Delta and Sichuan-Chongqing regions are significant end-users, driving technology adoption.
United States
The United States market benefits from strong demand in both microelectronics and pharmaceutical sectors. Water purity standards mandated by the US Pharmacopeia (USP) for drug manufacturing necessitate high-grade water. Industrial clusters in Silicon Valley and the Research Triangle Park consistently invest in advanced EDI technology.
Germany
Electronics manufacturing in Germany, particularly under the EU's RoHS directive, requires ultrapure water for various processes. The EU's Industrial Emissions Directive also encourages chemical-free regeneration processes for wastewater treatment. Bavaria and North Rhine-Westphalia house significant pharmaceutical and electronics production, influencing EDI demand.
South Korea
South Korea's robust semiconductor industry generates substantial demand for ultrapure water, making EDI a critical final polishing step. The country's advanced manufacturing sector continuously seeks efficient water treatment solutions to meet stringent quality requirements. Gyeonggi Province, a hub for technology companies, sees continuous investment in EDI systems.
Japan
Japan's semiconductor industry and pharmaceutical production require high-purity water for critical manufacturing processes. JIS standards for industrial water quality support the adoption of advanced purification technologies. Kyushu Island, known as "Silicon Island," remains a key region for semiconductor manufacturing and EDI integration.
Global Electrodeionization Market Key Industry Players
Strategic partnerships dominate the current landscape, as companies seek to combine specialized expertise and expand their geographic reach. The market structure exhibits a tiered approach, with large diversified water technology providers alongside specialized EDI system manufacturers and critical component suppliers. Portfolio diversification and technology licensing represent key competitive moves for players aiming to capture new opportunities.
Within the diversified water technology segment, Veolia Water Technologies and Evoqua Water Technologies LLC occupy significant positions, leveraging their extensive service networks. DuPont, a materials science company, anchors the market as a crucial supplier of ion exchange resins, essential components for EDI systems. These firms exemplify the broad range of capabilities required to serve the complex global demand for ultrapure water.
| Leading Market Players |
|---|
| SUEZ Water Technologies & Solutions |
| Pure Aqua Inc. |
| Veolia Water Technologies |
| Aquatech International LLC |
| Lenntech B.V. |
| Evoqua Water Technologies LLC |
| Ovivo Inc. |
| Kurita Water Industries |
| DuPont |
| Others |
Cost & Logistics Intelligence
The EU's Industrial Emissions Directive, requiring chemical-free regeneration, gates qualified electrodeionization system supply and enables premium pricing for compliant, high-performance solutions.
Pricing Analysis
Direct-to-OEM discounts are common for large-scale electrodeionization system procurements. Project-based pricing dominates for complex industrial installations, while modular units often use a per-unit transactional model. Certification levels like USP standards and comprehensive after-sales service bundles drive significant price differentiation. Pricing pressure stems from increasing competition from advanced reverse osmosis systems in less critical applications. Smaller research facilities are most price-sensitive, whereas semiconductor manufacturers exhibit the least price sensitivity due to purity criticality.
Supply Chain Analysis
Logistics and freight costs impact the final delivered price of bulky electrodeionization modules, particularly for international shipments. Supply concentrates in Germany, the United States, and Japan for advanced membrane stacks and control systems. The supply chain relies on specialized ion exchange resins, membrane materials, and proprietary electronic components. Single-source vulnerability for specific membrane stack components represents a structural risk. Distribution runs through specialized water technology integrators and direct sales channels to large industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global electrodeionization market is a stable compounder, driven by the persistent demand for ultrapure water in microelectronics fabrication. Continuous technological refinement ensures sustained value creation across established and emerging applications.
For Market Incumbents: Extend service-based models to new geographic markets like Southeast Asia, mitigating high capital outlay for end-users. Deepen vertical integration into critical membrane materials to counter supply chain volatility and ensure component availability. Invest in modular system R&D to address the growing need for decentralized treatment solutions in biotechnology labs. Competition from advanced reverse osmosis technologies represents a named threat in less stringent purity applications.
For New Entrants and Emerging Players: China's GB standards for industrial water quality open a window for specialized electrodeionization providers focusing on compliance solutions. Target the emerging pharmaceutical and life sciences industries in Southeast Asian countries with tailored, validated systems. Focus on developing compact, modular EDI units for biotechnology research labs, a penetrable segment. Partner with local engineering firms for installation and ongoing technical support, addressing skilled technician scarcity.
For Investors and Strategic Acquirers: Roll-up economics work for industrial water treatment specialists because of the fragmented end-user base requiring localized service. The market offers long-term viability over a 5-10 year window, driven by persistent demand for ultrapure water. Prioritize acquiring specialized component manufacturers for membrane stacks or advanced control systems. A signal to watch is the increasing adoption rate of continuous electrodeionization in new semiconductor fabrication plants.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Veolia Water Technologies expands global service network to serve both established and emerging sectors. |
| Technology Licensing | DuPont licenses advanced ion exchange resin formulations to regional manufacturers, enhancing market reach. |
| Product Launch | Evoqua Water Technologies LLC launches new modular EDI system for decentralized applications in biotechnology. |
| Strategic Partnership | Kurita Water Industries partners with semiconductor foundries for integrated ultrapure water solutions. |
| Green Manufacturing Transition | SUEZ Water Technologies & Solutions invests in chemical-free regeneration process development for compliance. |
Research Approach
Multiple input streams—primary interviews, company financial reports, and industry association publications—were reconciled for a comprehensive market view. Primary interviews involved R&D directors and procurement managers at semiconductor fabs. Secondary data sources included US EPA regulations and EU Industrial Emissions Directive texts. Rigorous bottom-up and top-down triangulation validated data points across the electrodeionization value chain.
Historical market data was cross-referenced with expert panel input to project future electrodeionization market trajectories. Segmentation dimensions modeled included technology type, application, end-user, and regional demand. Compound annual growth rates were derived through regression analysis, considering market drivers and restraints. Key forecast inputs included projected semiconductor plant investments and pharmaceutical industry expansion rates.
Revisions become necessary when significant shifts in regulatory frameworks or unexpected technological breakthroughs materialize. Forecasts reflect assumptions regarding economic stability and continued industrial investment. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
India Water Treatment Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
Asia-Pacific Drilling Waste Management Services Market
Water & Sludge Treatment
Ballast Water Treatment Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Homogenizer Tank Market
Water & Sludge Treatment
Global Water Treatment Technology Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
Deionized Water Systems Market
Water & Sludge Treatment
Aquarium Water Treatment Market