
 Water Softening Systems Market | 2026-2036
Water Softening Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Water Softening Systems Market Analysis
Commercial laundries and food processing facilities is hardening as the fastest-expanding end-use vertical for water softening systems. Pentair leverages its manufacturing scale to dominate commercial-grade ion exchange installations across North American industrial corridors. Culligan sustains brand strength through its dealer network control in residential markets, while Kinetico differentiates via non-electric, demand-initiated regeneration technology that reduces salt discharge.
Water softening systems are ion exchange or alternative-technology appliances designed to remove calcium and magnesium ions from feed water, typically achieving hardness reduction below 1 grain per gallon (17.1 ppm) through resin bed regeneration using sodium chloride or potassium chloride brine. Their primary purpose is preventing scale formation in plumbing, boilers, and process equipment while extending appliance lifespan and improving detergent efficiency. Ion exchange systems anchor the largest installed base due to proven performance across extreme hardness conditions, though salt-free conditioning technologies are gaining traction in regions with brine discharge restrictions. Smart technology integration represents the fastest-growing segment as connected sensors enable predictive regeneration cycles and remote monitoring, while traditional timer-based units occupy a mature, price-sensitive tier with thinning margins.
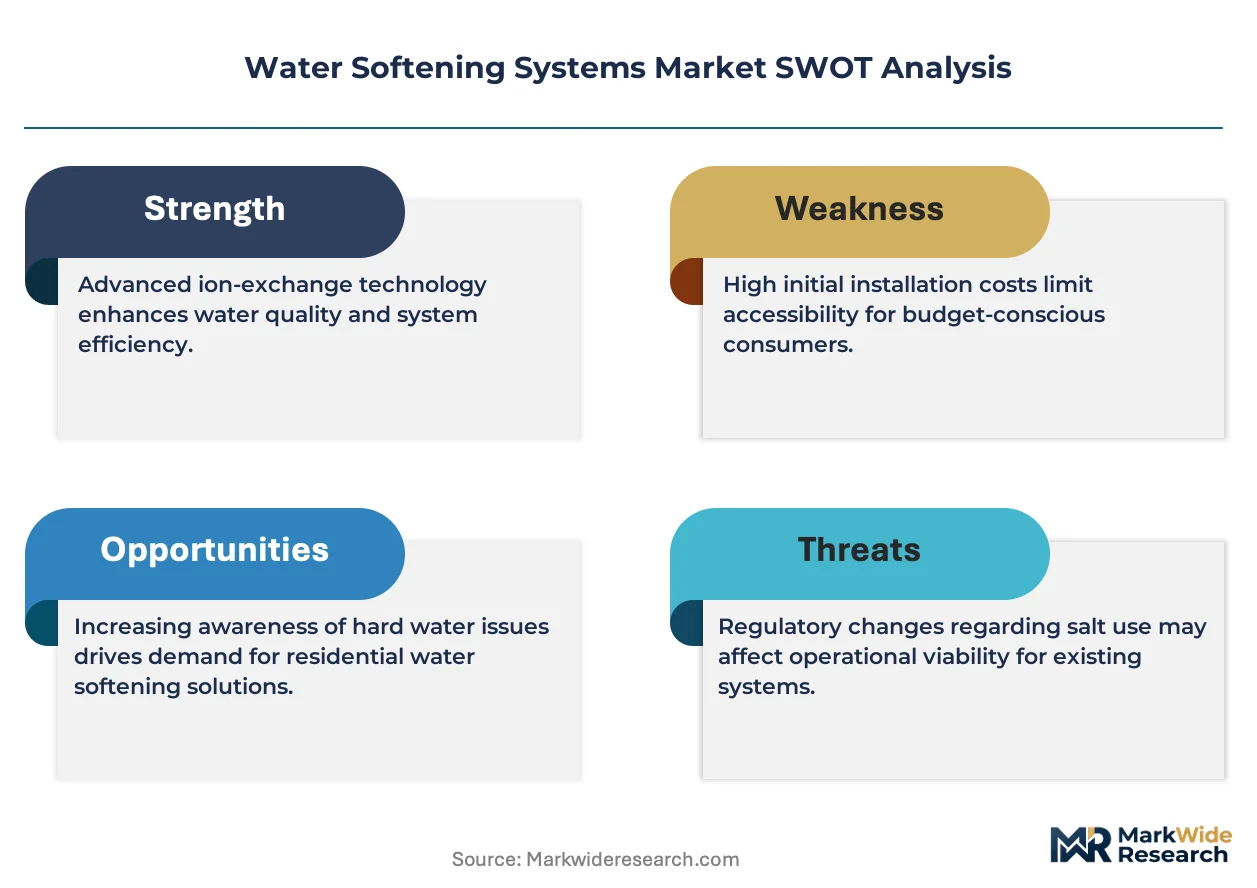
The EPA's secondary drinking water standards and NSF/ANSI 44 certification requirements shape product design and market access for residential systems in the United States. State-level brine discharge regulations in California, Texas, and Florida are forcing manufacturers to develop high-efficiency models that minimize salt consumption and wastewater volume. Stakeholders must monitor evolving municipal bans on self-regenerating water softeners and assess whether hybrid or template-assisted crystallization technologies can satisfy both performance expectations and environmental compliance without triggering replacement cycle compression.
Market Dynamics
Municipal water treatment utilities are accelerating procurement of automated softening infrastructure as the EPA's revised secondary maximum contaminant levels for total dissolved solids tighten certification requirements across the installed base. This regulatory pressure is compressing replacement cycles and reshaping vendor qualification criteria.
Growth Catalysts
- Brine discharge restrictions:California, Texas, and Florida state-level regulations are forcing high-efficiency model development that minimizes salt consumption and wastewater volume, creating pull-through demand for next-generation systems.
- Commercial laundries:Food processing facilities and industrial textile operations are hardening as the fastest-expanding end-use vertical, driven by scale-sensitive equipment protection needs and detergent cost optimization.
- Smart technology integration:Connected sensors enabling predictive regeneration cycles and remote monitoring represent the fastest-growing segment, displacing timer-based units in premium residential and commercial installations.
Market Restraints
- Sodium chloride price volatility:Salt input costs fluctuate with regional mining output and transportation constraints, compressing margins on high-frequency regeneration systems in price-sensitive tiers.
- Template-assisted crystallization performance gaps:Salt-free conditioning technologies struggle to achieve consistent hardness reduction below 1 grain per gallon across extreme hardness conditions exceeding 300 ppm, limiting substitution viability.
- Municipal ban proliferation:Local prohibitions on self-regenerating water softeners in drought-prone Southwestern jurisdictions are restricting addressable market access for conventional ion exchange systems.
Strategic Opportunities
- Hybrid technology convergence:Combining ion exchange resin beds with template-assisted crystallization pre-treatment offers a pathway to satisfy both performance expectations and environmental compliance without triggering replacement cycle compression.
- Potassium chloride substitution:Sodium-restricted diets and agricultural runoff concerns are creating demand for potassium-based regeneration in residential markets with cardiovascular health sensitivities.
- Dealer network digitization:Remote monitoring platforms enable servitization transitions from unit sales to recurring revenue models through predictive maintenance subscriptions and salt delivery logistics optimization.
Industry Challenges
- NSF/ANSI 44 certification timelines:Third-party testing protocols for residential system validation extend product launch schedules, delaying competitive response to regulatory shifts.
- Legacy plumbing integration:Retrofit installations in existing residential and commercial structures require customized bypass configurations and pressure vessel adaptations that complicate standardization efforts.
- Resin bed degradation prediction:Service life modeling for ion exchange media under variable feed water chemistry remains imprecise, complicating warranty exposure and maintenance scheduling algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Softening Systems Market |
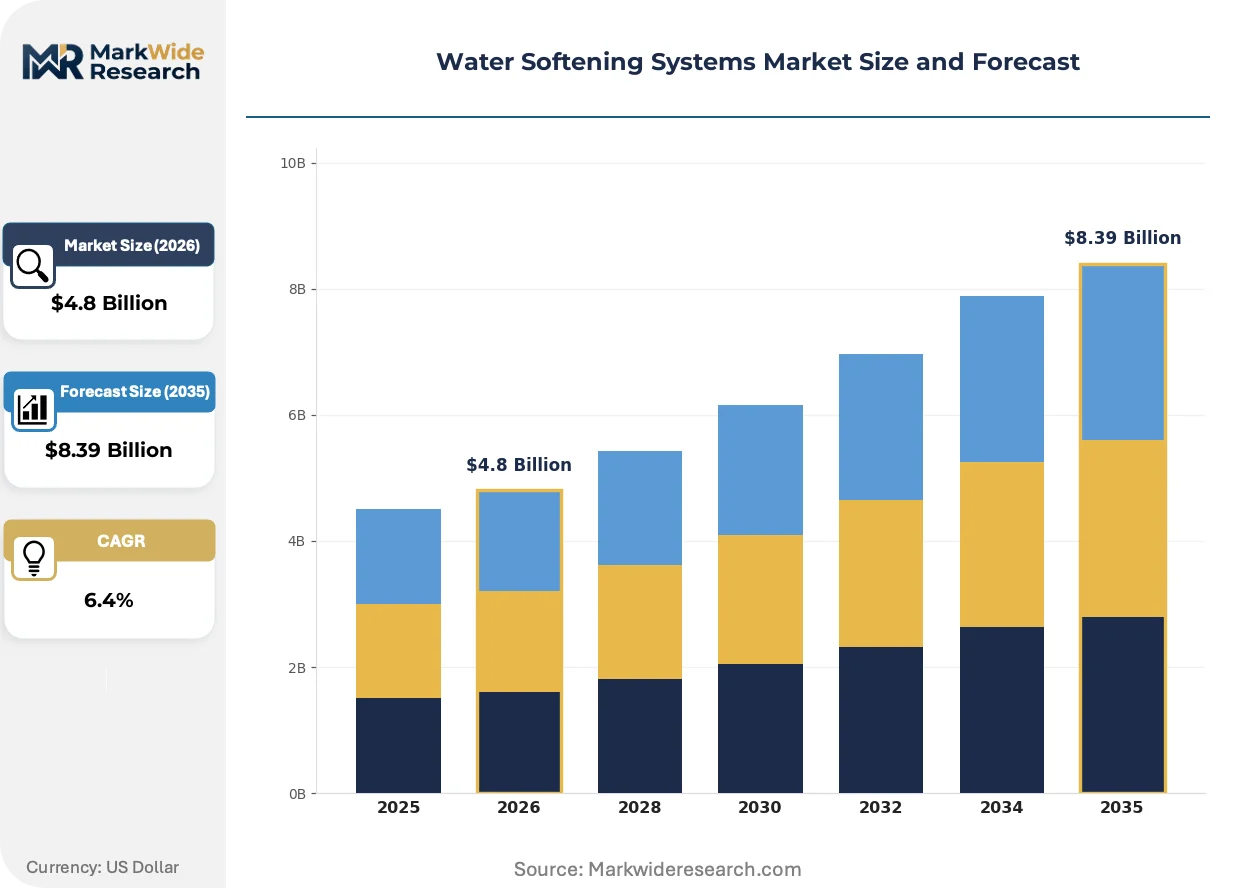
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ion Exchange, Salt-Free, Magnetic, Reverse Osmosis End User: Residential, Commercial, Industrial, Agricultural Distribution Channel: Online, Retail, Direct Sales, Wholesalers Technology: Traditional, Automated, Smart, Hybrid |
| Companies Covered | Fleck, Softpro, Culligan, Pentair, Kinetico, SpringWell, US Water Systems, Aquasana, Leaf Home Water Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Softening Systems Market Emerging Trajectories
Water softening system architecture is undergoing fundamental redesign as connected infrastructure, regulatory stringency, and servitization models reshape value capture mechanisms across the value chain.
Template-assisted crystallization media is converging with conventional ion exchange pre-treatment in hybrid configurations that split hardness removal between chemical-free conditioning and precision polishing stages. Municipal utilities in California and Arizona are piloting these dual-technology trains for centralized softening plants serving hardness levels above 250 ppm. This convergence is enabling vendors to satisfy brine discharge restrictions while maintaining guaranteed outlet hardness specifications that single-technology systems cannot achieve.
The EPA's revised secondary maximum contaminant levels for total dissolved solids are tightening product certification requirements and compressing grandfathering provisions for existing installations. Industrial boiler operators in food processing and pharmaceutical manufacturing face heightened scrutiny of scale prevention documentation for insurance and liability purposes. High-purity process water segments are responding by specifying dual-certified systems meeting both NSF/ANSI 44 and NSF/ANSI 61 standards, eliminating single-certification suppliers from consideration sets.
Commercial laundries and hospitality chains are consolidating vendor relationships through master service agreements that bundle equipment, salt supply, and predictive maintenance into per-gallon-treated pricing. This consumption-based contracting displaces capital expenditure procurement models and shifts performance risk to OEMs and their dealer networks. The Southwestern United States exhibits the most advanced penetration of these arrangements, driven by water cost volatility and labor scarcity for in-house maintenance functions.
Water Softening Systems Market Segmentation
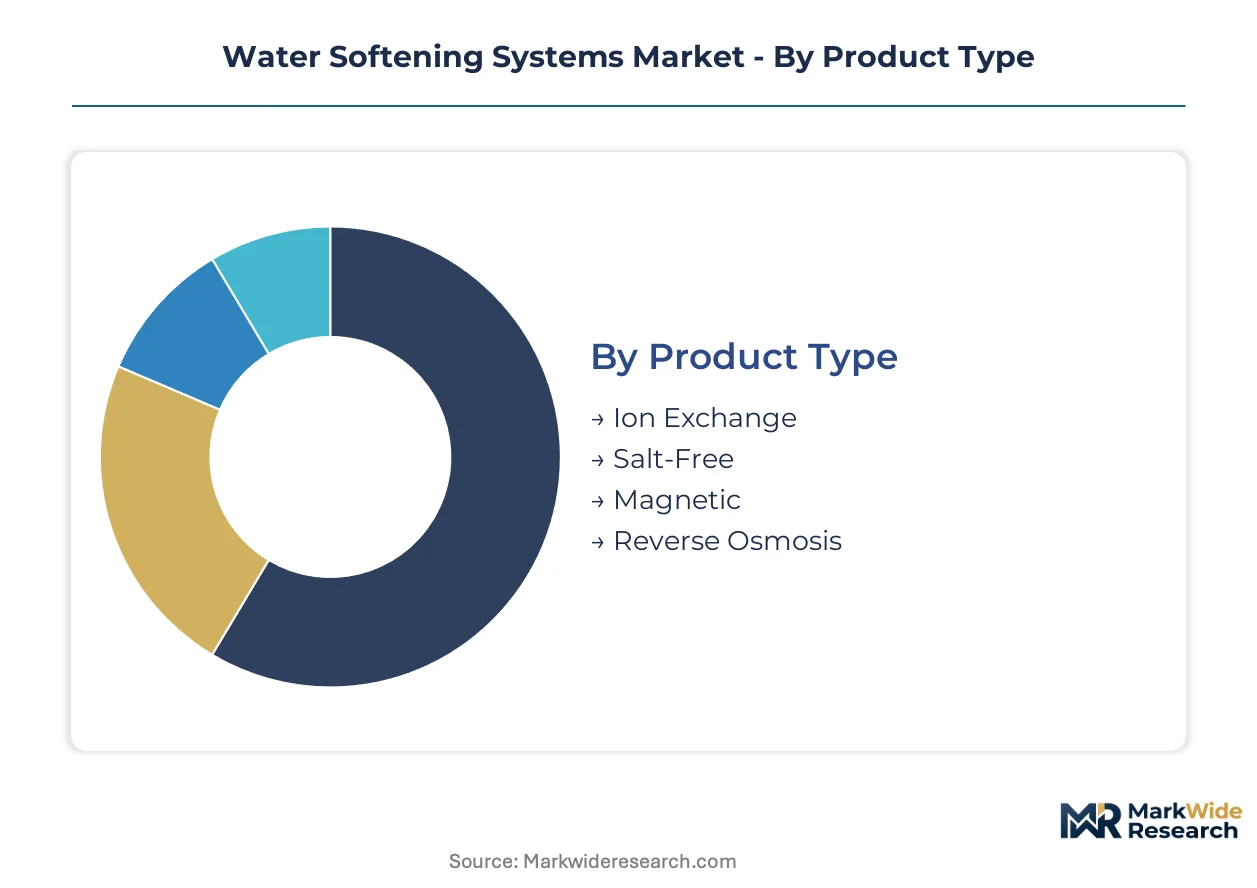
Water softening system purchasing decisions pivot on hardness severity, regulatory constraints, and operational scale. Buyers match technology categories to specific feed water chemistry and discharge compliance requirements rather than selecting generically.
Product Type:
Hardness concentration and brine discharge restrictions determine technology selection across residential and commercial installations.
- Ion Exchange:Resin bed systems using sodium or potassium chloride regeneration achieve hardness reduction below 1 grain per gallon even at extreme inlet conditions exceeding 300 ppm. Demand concentrates in Southwestern United States municipalities where groundwater hardness mandates proven performance, though California's brine discharge regulations are compressing replacement cycles toward high-efficiency models.
- Salt-Free:Template-assisted crystallization media induce calcium carbonate precipitation without chemical regeneration, eliminating brine discharge entirely. Adoption is climbing fastest in Florida and Texas jurisdictions with emerging discharge restrictions where hardness levels remain moderate enough to satisfy performance expectations.
- Magnetic:Electromagnetic field conditioning devices claim scale reduction through altered mineral crystallization without physical removal.
- Reverse Osmosis:Membrane-based separation removes dissolved solids including hardness ions through pressure-driven filtration, typically deployed for point-of-use drinking water rather than whole-building softening.
Volume sits with Ion Exchange; growth tilts toward Salt-Free.
End User:
Scale sensitivity and detergent cost exposure drive differential technology adoption across customer categories.
- Commercial:Laundries, food processing facilities, and hospitality operations require guaranteed hardness specifications for equipment protection and operational efficiency. This segment is expanding most quickly in drought-prone Southwestern states where water cost volatility and boiler insurance documentation requirements intensify procurement urgency.
- Residential:Single-family and multi-family dwellings prioritize appliance lifespan extension and soap efficiency. Demand clusters in suburban developments across Arizona, Nevada, and Texas where municipal water sources draw from mineral-rich aquifers.
- Industrial:Manufacturing plants with high-purity process water requirements deploy centralized softening trains.
- Agricultural:Irrigation systems in hard water regions utilize conditioning to prevent emitter clogging.
Residential commands installed base volume; commercial applications show steepest expansion trajectory.
Distribution Channel:
Customer technical sophistication and service requirements shape channel preference and margin structure.
- Direct Sales:OEM-controlled dealer networks deliver installation, salt supply logistics, and predictive maintenance subscriptions. This channel captures premium pricing in commercial master service agreements where performance risk shifts to vendors.
- Retail:Big-box and specialty plumbing stores serve price-sensitive residential replacement cycles with timer-based units.
- Online:E-commerce platforms facilitate specification comparison for technically confident buyers.
- Wholesalers:Plumbing supply houses distribute to contractor installers in new construction.
Direct Sales concentrates commercial value; Online is gaining share fastest in residential replacement.
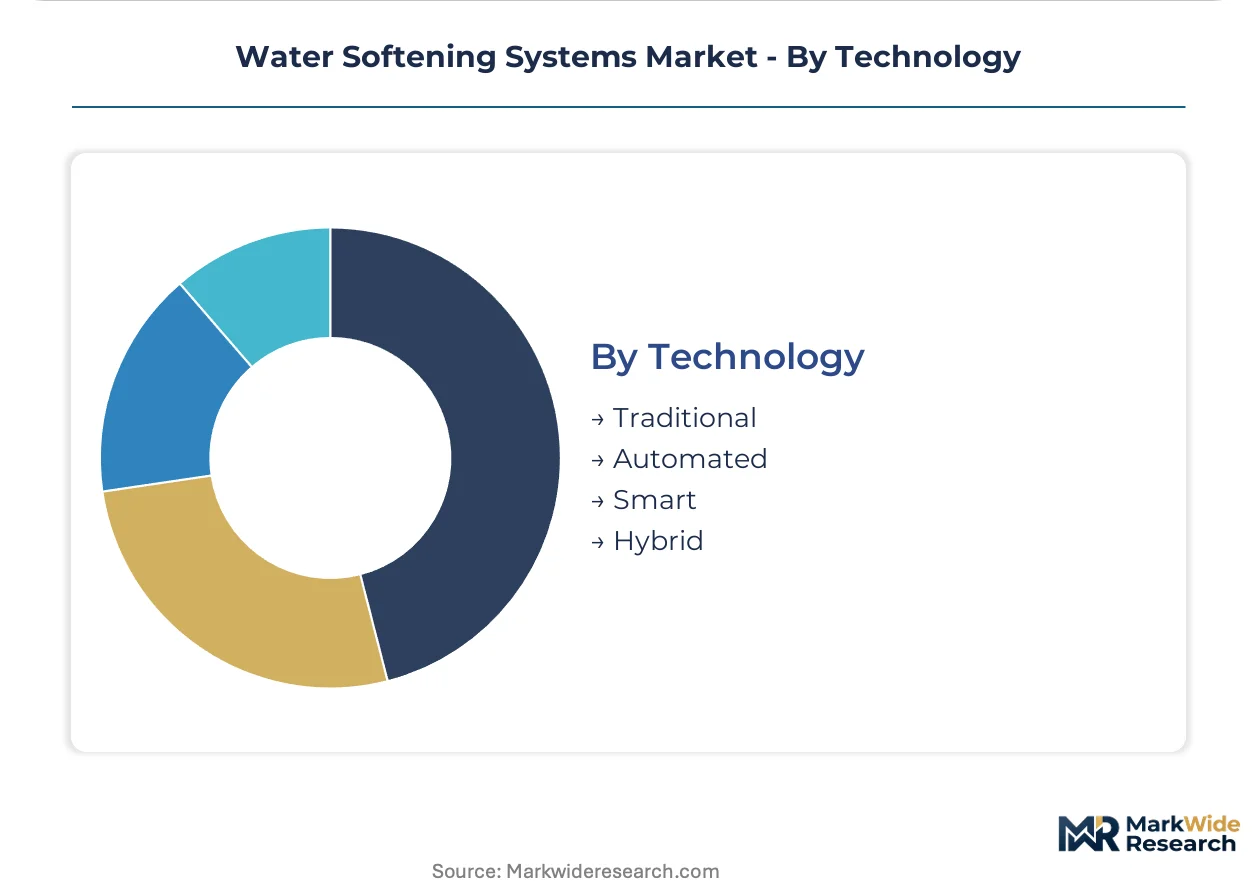
Technology:
Connectivity integration and regeneration control sophistication differentiate pricing tiers and customer segments.
- Smart:Connected sensors enable predictive regeneration cycles, remote monitoring, and salt level alerts through mobile applications. Adoption is climbing fastest in premium residential and commercial installations where labor scarcity for maintenance functions justifies subscription economics.
- Automated:Demand-initiated regeneration systems meter water usage to trigger resin bed cleaning, reducing salt consumption versus timer-based alternatives.
- Hybrid:Dual-technology trains combining template-assisted crystallization pre-treatment with ion exchange polishing satisfy brine discharge restrictions while maintaining guaranteed outlet specifications.
- Traditional:Timer-based regeneration units occupy mature, price-sensitive tiers with thinning margins.
Traditional systems anchor volume; Smart technology shows the sharpest growth incline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial water treatment zones across the United States, Germany, China, Japan, and Australia concentrate procurement activity for water softening infrastructure. Municipal utilities and commercial end-users in these markets face tightening discharge regulations and escalating hardness levels in groundwater sources.
United States
Southwestern states including Arizona, Nevada, and Texas drive residential demand where groundwater hardness exceeds 300 ppm. The EPA's revised secondary maximum contaminant levels for total dissolved solids are compressing replacement cycles toward high-efficiency models. California's brine discharge restrictions are forcing manufacturers to develop hybrid systems in Los Angeles and San Diego industrial corridors.
Germany
Commercial laundries and food processing facilities in North Rhine-Westphalia and Bavaria require guaranteed hardness specifications for boiler protection. The country's national environmental regulator enforces strict wastewater quality standards for industrial discharge. Manufacturing clusters around Stuttgart and Munich are piloting smart-enabled regeneration systems with predictive maintenance capabilities.
China
Rapid industrialization in the Yangtze River Delta and Pearl River Delta is expanding centralized softening infrastructure for high-purity process water. The Ministry of Ecology and Environment monitors discharge permits for manufacturing facilities with stringent effluent limits. Textile operations in Zhejiang province are consolidating vendor relationships through master service agreements with per-gallon-treated pricing.
Japan
Precision manufacturing in the Chubu region around Nagoya demands ultra-low hardness levels for semiconductor and pharmaceutical production. METI efficiency standards incentivize demand-initiated regeneration technologies over timer-based alternatives. Osaka-based commercial laundries are adopting connected sensor platforms to optimize salt consumption and maintenance scheduling.
Australia
Drought-prone regions in New South Wales and Queensland are experiencing accelerated municipal procurement of automated softening plants. State-level water authorities regulate brine discharge from self-regenerating systems in water-stressed catchments. Mining operations in Western Australia deploy conditioning systems to prevent emitter clogging in remote irrigation infrastructure.
Water Softening Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with residential markets favoring dealer-network control while commercial installations gravitate toward OEM-direct relationships. The vendor base organizes into three tiers: multinational infrastructure conglomerates with manufacturing scale, regional specialists with installation and service capabilities, and private-label assemblers serving price-sensitive retail channels. Competitive intensity centers on technology licensing for smart connectivity and geographic expansion through distributor acquisitions.
Among North American infrastructure providers, Pentair and Culligan occupy positions at opposite ends of the value chain archetype spectrum, while Kinetico exemplifies technology differentiation through non-electric system design. Pentair represents the scale-driven multinational tier with captive manufacturing and utility-sector relationships. Culligan anchors the dealer-network model with recurring revenue from salt logistics and maintenance subscriptions. Kinetico sits within the innovation-focused specialist tier, its demand-initiated regeneration approach serving as a template for efficiency-focused product development across the industry.
| Leading Market Players |
|---|
| Fleck |
| Softpro |
| Culligan |
| Pentair |
| Kinetico |
| SpringWell |
| US Water Systems |
| Aquasana |
| Leaf Home Water Solutions |
| Others |
Supply Flow & Price Mechanics
California's brine discharge regulations gate both qualified supply and premium-tier pricing access for water softening systems, forcing manufacturers to certify high-efficiency models while compressing margins on conventional ion exchange units that dominate price-sensitive residential tiers.
Pricing Analysis
Short lead-time premiums separate expedited commercial installations from standard residential replacement cycles in the water softening systems market. Pricing stratifies across smart-connected premium tiers, automated demand-initiated mid-market units, and timer-based economy segments where salt price volatility compresses margins most severely. Commercial laundries and food processing facilities exhibit the lowest price sensitivity due to equipment protection documentation requirements, while big-box retail channels serving residential replacement cycles face the most intense cost compression.
Supply Chain Analysis
Domestic-content mandates in California and Texas municipal procurement specifications are reshaping sourcing patterns for resin bed media and control valve assemblies. Manufacturing concentrates in the United States, Mexico, and Germany for precision-engineered components, with ion exchange resin supply anchored in China and the United States. Specialty zeolite and template-assisted crystallization media draw from Japanese and German chemical suppliers. Tariff exposure on Chinese-sourced resin creates single-source vulnerability for cost-optimized tier products. Distribution runs through OEM-controlled dealer networks for commercial master service agreements, while retail and e-commerce channels fragment residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water softening systems market consolidation is accelerating as EPA certification timelines and smart technology R&D requirements force sub-scale regional assemblers toward exit or acquisition.
For Market Incumbents: Extend predictive maintenance platform capabilities to capture recurring revenue from salt logistics and remote monitoring subscriptions before emerging IoT specialists displace traditional dealer relationships. Acquire distressed regional installers in Arizona and Nevada to consolidate Southwestern corridor density ahead of municipal softening infrastructure rollouts. Invest in hybrid technology certification to defend against template-assisted crystallization substitution in Florida and Texas discharge-restricted jurisdictions. For New Entrants and Emerging Players: E-commerce direct-to-consumer routes offer the most penetrable entry vector for salt-free conditioning systems targeting technically confident residential buyers in moderate-hardness markets. White-space concentrates in potassium chloride regeneration systems for sodium-restricted diet segments and portable rental units for temporary commercial installations. Pursue influencer partnerships with plumbing and home improvement content creators to bypass incumbent dealer network control. For Investors and Strategic Acquirers: Smart technology patent filings accelerating among second-tier manufacturers is the leading indicator that connected-system differentiation is becoming table stakes rather than premium positioning. Long-term viability favors vertically integrated platforms combining captive resin supply, predictive software, and salt logistics infrastructure. Monitor California municipal ban enforcement patterns as the critical signal for hybrid technology adoption velocity and conventional ion exchange asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Technology Certification | Dual NSF/ANSI 44 and brine-efficiency validation unlocks California and Florida municipal procurement. |
| Predictive Maintenance Platform Launch | Connected sensor deployments shift Pentair and Culligan toward per-gallon-treated servitization contracts. |
| Potassium Chloride Supply Agreement | Agricultural runoff concerns in Midwest watersheds pull residential buyers toward sodium-free regeneration. |
| Dealer Network Digitization | Remote monitoring integration enables Leaf Home and SpringWell to capture salt delivery logistics optimization. |
| Municipal Infrastructure Partnership | Centralized softening plant pilots in Arizona and Texas industrial corridors anchor multi-year equipment commitments. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this water softening systems analysis, combined with primary interviews spanning plant engineers at commercial laundries, procurement directors at food processing facilities, OEM technical R&D heads, dealer network operators, and municipal utility planning officers. EPA enforcement documentation, NSF certification databases, state-level discharge permit records, and water hardness monitoring data from the United States Geological Survey provided validation triangulation against bottom-up installation estimates and top-down market sizing.
Granularity-level modeling operated at the intersection of technology category, end-use vertical, and state-level regulatory cluster dimensions across the projection horizon. CAGRs derived from regression analysis against housing starts, commercial construction permits, and municipal capital expenditure disclosures. Hardness concentration thresholds, brine discharge restriction adoption timelines, and smart technology penetration curves served as industry-specific forecast inputs.
The model holds under stable regulatory enforcement and resin supply continuity; deviation in EPA secondary standard revision timing or Chinese export restriction triggers would shift replacement cycle assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
US Sludge Management and Dewatering Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
India Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Water Recycle and Reuse Technologies Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
Polish Water Treatment Chemicals Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Electrodeionization (EDI) Technology Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market