
 Process Chemicals for Water Treatment Market | 2026-2036
Process Chemicals for Water Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Process Chemicals for Water Treatment Market Outlook
Power generation is decoupling from municipal water treatment as the fastest-growing demand vertical for process chemicals. Kemira Oyj anchors Nordic pulp-and-paper applications with specialized coagulant chemistry. Dow Inc. extends its membrane-compatible antiscalant portfolio into Middle Eastern desalination projects. Solenis competes aggressively on service bundling across North American refinery cooling towers.
Process chemicals for water treatment comprise formulated additives—aluminum sulfate, polyacrylamide polymers, chlorine dioxide generators, and sulfuric acid buffers—designed to alter suspended solids, microbial load, or ionic balance in aqueous streams. These chemicals enable compliance with discharge permits, protect downstream equipment from fouling, and render brackish or wastewater sources fit for industrial reuse. Coagulants and flocculants together dominate product-type revenue due to their irreplaceable role in primary and secondary clarification, though pH adjusters command higher per-ton margins in semiconductor ultrapure water loops. Industrial process water applications outpace municipal drinking water in growth velocity because manufacturing facilities face tightening effluent standards while seeking to reduce freshwater intake.
EPA effluent limitation guidelines and China's MEE discharge permits for heavy industries directly expand the addressable market for advanced flocculants and disinfectant systems. REACH registration requirements in Europe filter out non-compliant biocide suppliers, concentrating supply among registrants with full toxicological dossiers. ISO 14001-certified facilities increasingly specify third-party-validated chemical feed systems, raising the bar for vendor qualification. Stakeholders must monitor how circular-water mandates in water-stressed manufacturing clusters reshape chemical specification priorities.
Market Dynamics
Zero-liquid-discharge mandates in China's coal-to-chemical corridor are forcing a wholesale upgrade of chemical dosing infrastructure, compressing procurement cycles from five years to eighteen months and privileging vendors with integrated service capabilities.
Growth Catalysts
- EPA Effluent Limitation Guidelines:US industrial facilities must retrofit chemical regimes to meet tightened discharge limits for nitrogen and phosphorus, expanding demand for advanced coagulant systems.
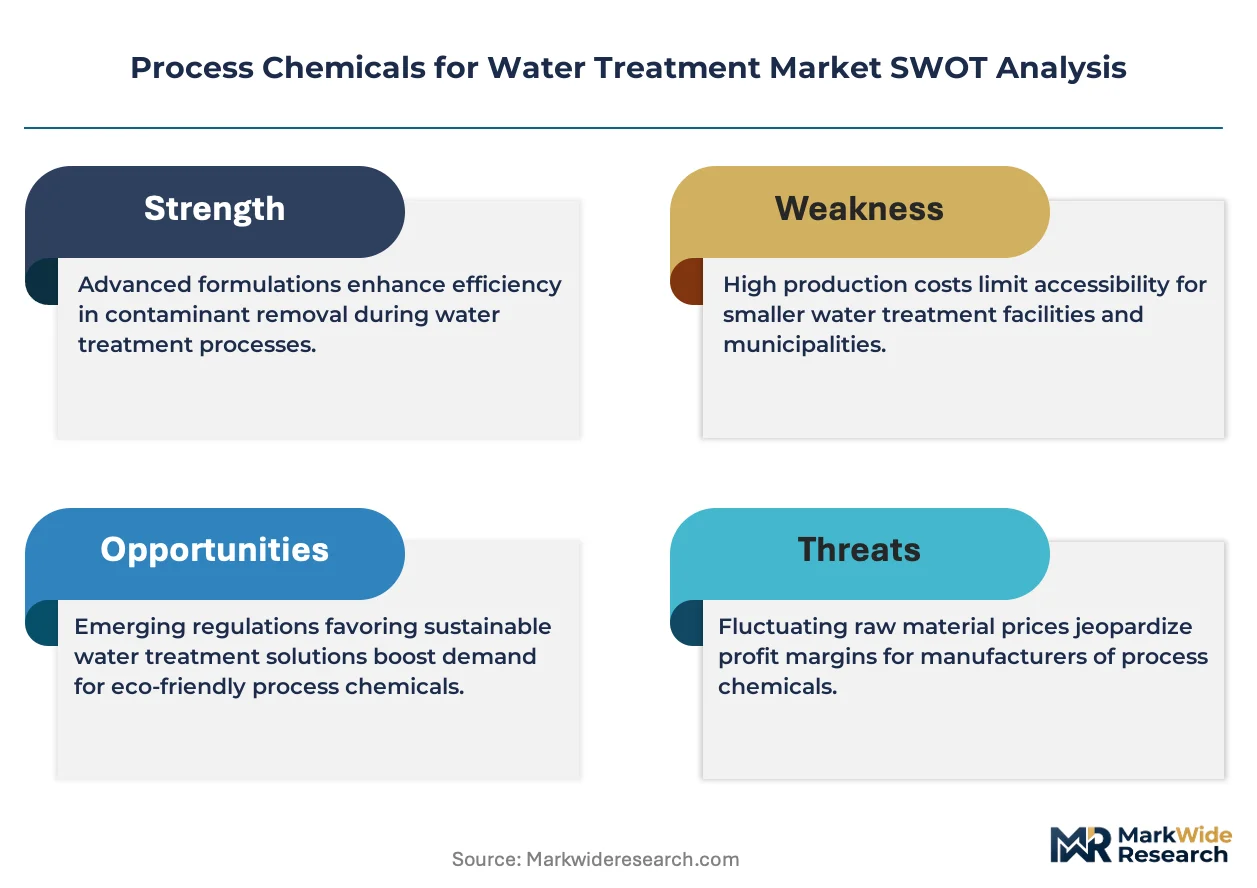
- Semiconductor ultrapure water loops:Fabrication plants in Taiwan and South Korea now specify pH adjusters with sub-ppb contamination thresholds, creating premium product tiers.
- Desalination scale-up:Saudi Arabia and UAE megaprojects are absorbing membrane-compatible antiscalants at volumes that reshape supplier capacity planning.
Market Restraints
- Alumina and sulfur input volatility:Aluminum sulfate production costs swing with bauxite refining economics, squeezing margin predictability for coagulant formulators.
- REACH registration concentration:European biocide supply has consolidated among dossier holders with full toxicological data, raising barriers for new entrants.
- On-site chlorine generation:Electrochlorination systems are displacing bulk hypochlorite delivery in municipal plants above 50 MGD capacity.
Strategic Opportunities
- Indonesia's nickel processing corridor:New hydrometallurgical facilities lack established chemical supply relationships, opening first-mover positioning for flocculant vendors.
- Cooling tower water reuse:North American refineries are unbundling chemical feed from equipment maintenance contracts, creating standalone procurement channels.
- EU Green Deal industrial water targets:Manufacturing clusters in Belgium and Netherlands must close water loops by 2030, mandating closed-circuit chemical monitoring.
Industry Challenges
- Certified chemical feed system integration:ISO 14001 facilities now require third-party-validated dosing skids, extending vendor qualification timelines by 8-14 months.
- Polymer handling expertise:High-molecular-weight flocculant activation demands specialized training that outpaces workforce development in emerging industrial zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Chemicals for Water Treatment Market |
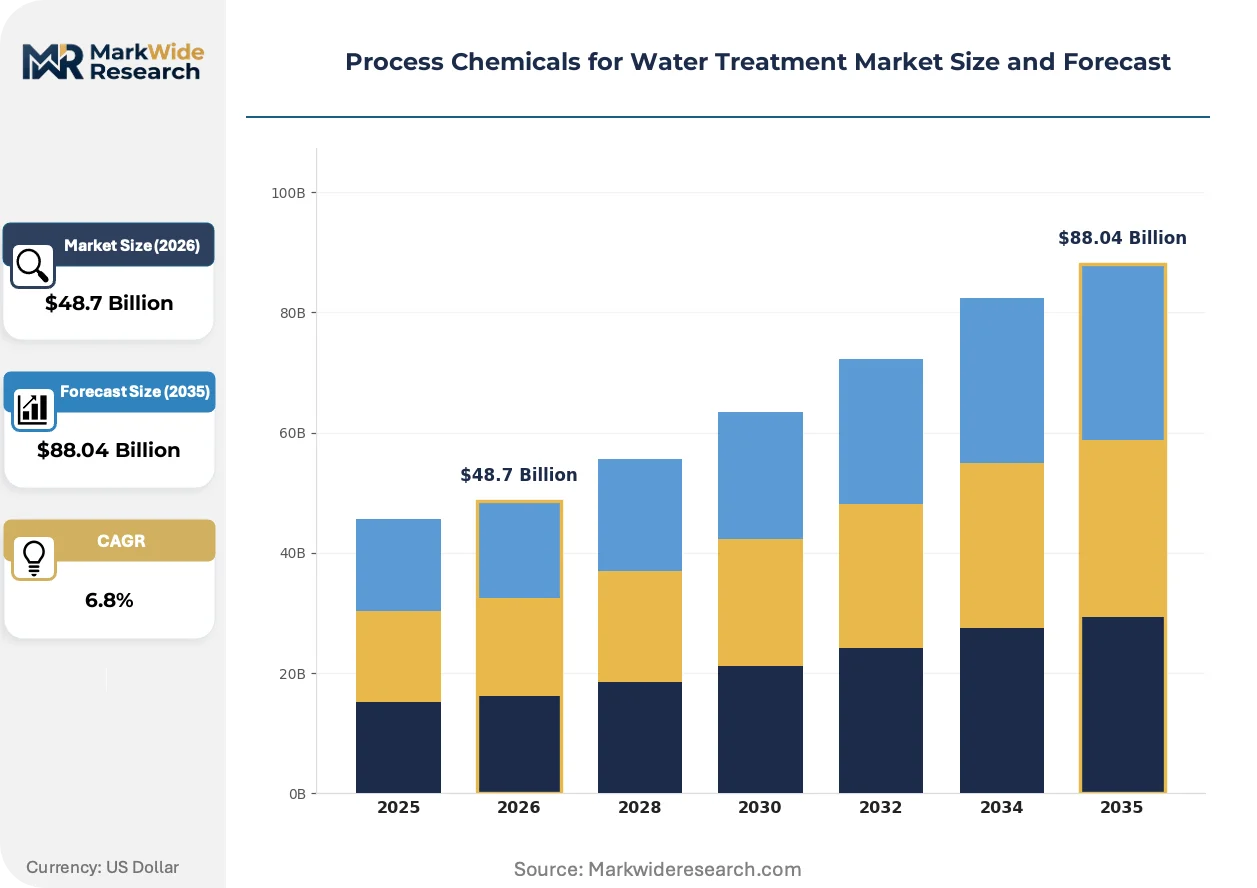
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Flocculants, Disinfectants, pH Adjusters Application: Wastewater Treatment, Drinking Water Treatment, Industrial Process Water, Desalination End User: Municipalities, Industrial Facilities, Commercial Establishments, Household Consumers Distribution Channel: Direct Sales, Online Sales, Retail Distribution, Distributors |
| Companies Covered | Ecolab Inc., Kemira Oyj, BASF SE, Solenis, Veolia Environnement SA, Dow Inc., Akzo Nobel N.V., Kurita Water Industries Ltd., ChemTreat, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Chemicals for Water Treatment Market Strategic Shifts
Digital dosing control and bio-based polymer chemistry are converging to redefine performance benchmarks, while regulatory tightening in major manufacturing economies accelerates specification turnover.
Magnetic ion exchange resin technology is absorbing dissolved organic carbon loads that conventional coagulants cannot capture. Dutch drinking water utilities are retrofitting MIEX pretreatment ahead of ultrafiltration membranes. The technology is absorbing market share from powdered activated carbon in surface water treatment applications.
China's MEE discharge permits for heavy industries now mandate real-time effluent monitoring with automated chemical adjustment. Steel and coal-chemical complexes face penalties for excursion events. This policy shift most acutely affects Shanxi and Inner Mongolia facilities, which are consolidating chemical procurement under single-vendor performance contracts.
Refinery operators in Texas and Louisiana are unbundling chemical supply from cooling tower maintenance agreements. Standalone chemical procurement now runs through specialized water treatment distributors rather than original equipment manufacturers. This channel shift concentrates volume with regional formulators capable of same-day delivery response.
Process Chemicals for Water Treatment Market Segmentation
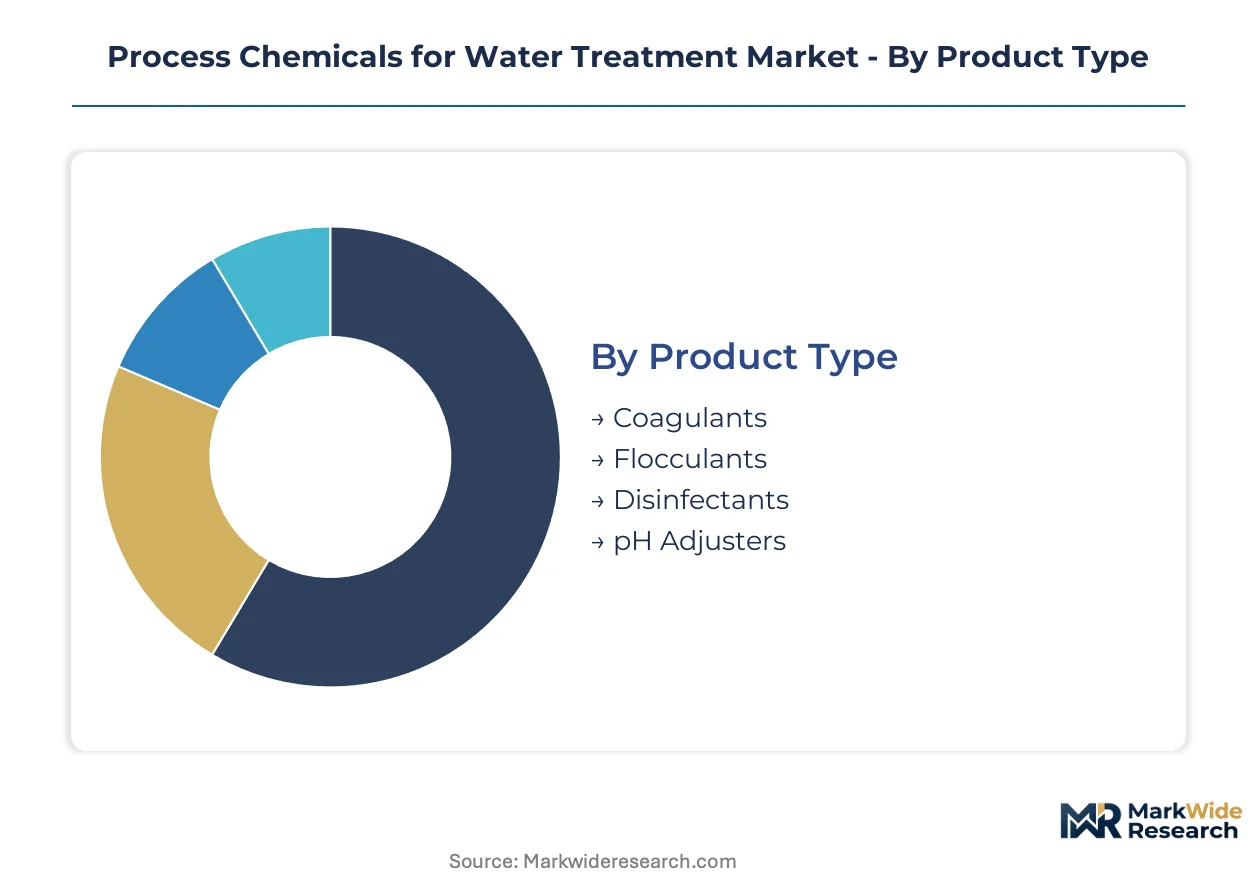
Process chemicals for water treatment demand divergent certification pathways across product categories. REACH dossier requirements, EPA registration mandates, and ISO 14001 feed system validation each reshape procurement priorities for distinct segments.
Product Type:
REACH registration requirements in Europe and EPA approvals in the United States impose tiered compliance burdens that segment suppliers by toxicological data depth.
- Coagulants:Aluminum sulfate and ferric chloride formulations dominate primary clarification. Municipalities in China's coal-to-chemical corridor now specify automated dosing systems to meet MEE discharge permits.
- Flocculants:Polyacrylamide polymers require high-molecular-weight activation expertise. Steel complexes in Shanxi province consolidate procurement under single-vendor performance contracts to manage excursion penalties.
- Disinfectants:Chlorine dioxide generators face REACH biocide concentration in Europe.
- pH Adjusters:Sulfuric acid buffers command premium margins in semiconductor ultrapure water loops.
Coagulants sit at the top of the volume ranking, with pH adjusters climbing the fastest.
Application:
Cost tier differentiation separates commodity-scale municipal contracts from precision-specified industrial installations.
- Wastewater Treatment:Tertiary capacity expansion across Asia-Pacific municipalities drives coagulant consumption. Facilities must retrofit chemical regimes to capture nitrogen and phosphorus under tightened discharge limits.
- Industrial Process Water:Manufacturing facilities face dual pressure from effluent standards and freshwater reduction targets. Zero-liquid-discharge mandates in China's industrial corridors compress procurement cycles from five years to eighteen months.
- Drinking Water Treatment:Dutch utilities deploy magnetic ion exchange resin ahead of ultrafiltration membranes.
- Desalination:Saudi Arabia and UAE megaprojects absorb membrane-compatible antiscalants at volumes reshaping supplier capacity planning.
Industrial process water holds the dominant revenue position, while desalination applications expand most quickly.
End User:
Customer type determines service bundling intensity and qualification timeline length.
- Municipalities:Public procurement favors established formulators with validated feed system integration. ISO 14001-certified facilities extend vendor qualification timelines by 8-14 months for third-party-validated dosing skids.
- Industrial Facilities:Refinery operators in Texas and Louisiana unbundle chemical supply from cooling tower maintenance agreements. Standalone procurement now channels through specialized distributors capable of same-day delivery response.
- Commercial Establishments:Smaller-scale demand concentrates on standardized coagulant formulations.
- Household Consumers:Point-of-use disinfectant systems represent a marginal segment with limited chemical volume.
Industrial facilities command the highest service-margin tier, with municipalities providing the steadiest volume base.
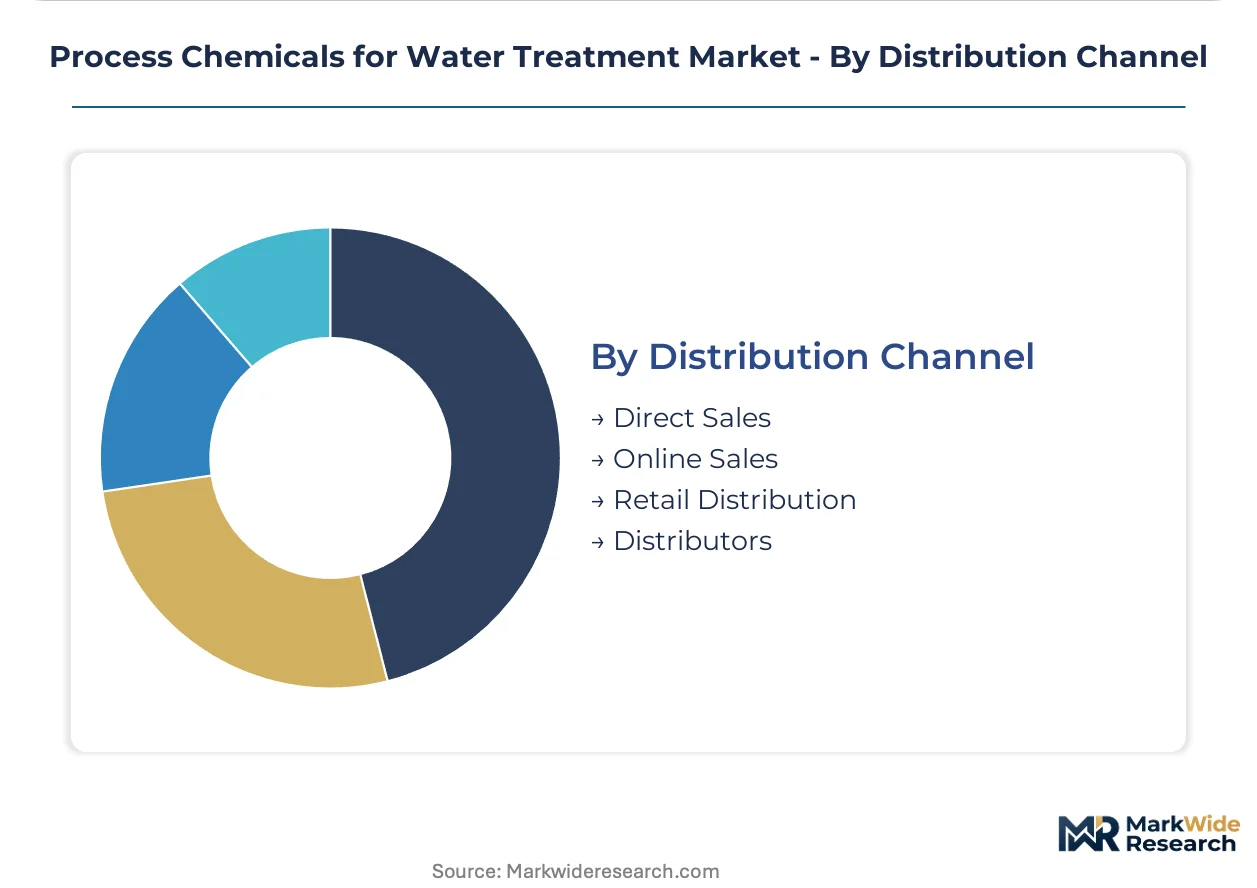
Distribution Channel:
Supply concentration patterns favor direct relationships for bulk industrial volumes while fragmenting municipal access.
- Direct Sales:Large industrial accounts negotiate performance contracts with integrated service capabilities. Single-vendor consolidation in China's heavy industry clusters privileges suppliers with automated chemical adjustment systems.
- Distributors:Regional formulators capture North American refinery cooling tower volumes through unbundled procurement channels. Same-day delivery response distinguishes competitive positioning.
- Online Sales:Limited to standardized commodity chemicals with minimal technical support requirements.
- Retail Distribution:Serves household consumer and small commercial segments with low-volume disinfectant products.
Distributors maintain the broadest geographic coverage, with direct sales capturing the highest-margin industrial accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as suppliers relocate manufacturing to jurisdictions with streamlined chemical registration pathways. Cost-of-compliance gaps between REACH-regulated Europe and EPA-governed United States create divergent investment incentives for coagulant and flocculant formulators.
United States
Industrial facilities across Texas and Louisiana are retrofitting chemical dosing regimes to meet tightened EPA effluent limitation guidelines for nitrogen and phosphorus. The agency's discharge permits now mandate real-time monitoring with automated adjustment capabilities. Refinery operators in the Gulf Coast corridor are unbundling chemical procurement from equipment maintenance contracts, channeling volume through regional distributors with same-day delivery response.
China
Zero-liquid-discharge mandates in Shanxi and Inner Mongolia coal-to-chemical complexes are compressing procurement cycles from five years to eighteen months. MEE discharge permits now impose penalties for excursion events, forcing steel and coal-chemical facilities to consolidate chemical procurement under single-vendor performance contracts. Automated chemical adjustment systems are becoming standard in heavy industry clusters.
Germany
REACH registration requirements are filtering biocide suppliers to dossier holders with full toxicological data, raising barriers for new entrants. Manufacturing clusters in North Rhine-Westphalia must close water loops by 2030 under EU Green Deal industrial water targets, mandating closed-circuit chemical monitoring. Dutch utilities are deploying magnetic ion exchange resin technology ahead of ultrafiltration membranes.
Saudi Arabia
Desalination megaprojects are absorbing membrane-compatible antiscalants at volumes reshaping supplier capacity planning. The country's national water regulator is specifying automated dosing systems for new reverse osmosis installations. Eastern Province industrial cities are consolidating chemical procurement under performance-based contracts with integrated service capabilities.
Japan
Semiconductor fabrication plants in Kyushu and the Tokyo metropolitan area now specify pH adjusters with sub-ppb contamination thresholds, creating premium product tiers. METI industrial water reuse guidelines are tightening chemical purity specifications for electronics manufacturing. Osaka-based utilities are retrofitting tertiary treatment capacity with advanced coagulant systems.
Process Chemicals for Water Treatment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated service providers capturing premium-tier industrial accounts while regional formulators dominate municipal procurement. The vendor base concentrates among registrants with full toxicological dossiers in regulated jurisdictions, filtering out non-compliant suppliers. Three archetypes define positioning: diversified chemical conglomerates with water treatment divisions, pure-play water treatment specialists, and regional formulators with distribution density. Competitive moves center on M&A for technology access and capacity expansion in high-growth corridors.
Among Nordic specialists, Kemira Oyj exemplifies the pure-play archetype with concentrated pulp-and-paper applications. Dow Inc. occupies a position among diversified conglomerates extending membrane-compatible chemistry into desalination markets. Solenis represents the service-bundling model competing aggressively across North American refinery cooling towers. These three anchors illustrate how geographic origin and corporate structure shape strategic options without determining specific market outcomes.
| Leading Market Players |
|---|
| Ecolab Inc. |
| Kemira Oyj |
| BASF SE |
| Solenis |
| Veolia Environnement SA |
| Dow Inc. |
| Akzo Nobel N.V. |
| Kurita Water Industries Ltd. |
| ChemTreat, Inc. |
| Others |
Value Chain & Pricing Dynamics
Single-vendor performance contracts in China's Shanxi and Inner Mongolia coal-to-chemical corridors are compressing procurement cycles from five years to eighteen months, forcing suppliers to absorb working capital strain while bidding on integrated service packages that bundle chemicals with automated dosing infrastructure.
Pricing Analysis
Distributor margins in North American refinery cooling tower channels absorb 15-25 point spreads between bulk formulators and end users, with regional formulators capturing premium positioning through same-day delivery response capabilities. Three-tier pricing structure across premium, standard, and economy levels separates membrane-compatible antiscalants for Saudi desalination megaprojects from commodity coagulants in municipal clarification. Cost compression in standard-grade aluminum sulfate is intensifying because bauxite refining economics swing with alumina spot markets. Municipal procurement teams exhibit highest price sensitivity due to public tender requirements, while semiconductor fabs in Taiwan and South Korea accept 40-60 point premiums for sub-ppb contamination threshold pH adjusters.
Supply Chain Analysis
ISO 14001 feed system validation and REACH dossier completeness filter supplier资格, extending vendor qualification timelines by 8-14 months and concentrating supply among registrants with full toxicological data. Manufacturing concentrates in Germany, China, and the United States, with bauxite-derived aluminum sulfate, acrylamide monomer for polyacrylamide synthesis, and sulfuric acid for pH adjustment serving as critical input dependencies. Single-source vulnerability runs through China's dominance of high-molecular-weight flocculant polymer production. Distribution runs through direct sales for large industrial accounts and specialized regional distributors for unbundled refinery procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story: semiconductor ultrapure water specifications now demand sub-ppb contamination thresholds that only premium-tier suppliers can satisfy, compressing commodity formulators into municipal and industrial bulk segments.
For Market Incumbents: Acquire automated dosing system capabilities to defend integrated service positioning against pure-play chemical vendors. Backward integration into acrylamide monomer production secures margin control as polymer feedstock costs fluctuate. Capacity addition in Saudi Arabia's Eastern Province captures desalination megaproject volume before regional formulators consolidate distribution relationships. For New Entrants and Emerging Players: Indonesia's nickel processing corridor lacks established chemical supply relationships, presenting first-mover positioning for flocculant vendors with hydrometallurgical expertise. EU Green Deal industrial water targets in Belgium and Netherlands manufacturing clusters mandate closed-circuit chemical monitoring by 2030, opening standalone procurement channels unbundled from equipment maintenance. Go-to-market through specialized water treatment distributors rather than direct OEM relationships accelerates same-day delivery qualification. For Investors and Strategic Acquirers: Asymmetric upside sits with regional formulators possessing REACH dossier completeness and ISO 14001-certified feed system integration capabilities. Five-to-ten year viability favors suppliers with toxicological data depth that regulatory concentration is filtering toward incumbents. The signal to watch is MEE discharge permit enforcement intensity in China's heavy industry clusters, which determines performance contract pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide Monomer | Secures polymer feedstock margin control against bauxite refining volatility. |
| Capacity Expansion in Saudi Eastern Province | Captures membrane-compatible antiscalant volume from megaproject pipeline. |
| REACH Dossier Investment for Biocide Registration | Maintains European market access as ECHA filters non-compliant suppliers. |
| Automated Dosing System Acquisition | Meets MEE permit requirements for real-time effluent monitoring in China. |
| Joint Venture with Indonesian Nickel Processors | Establishes flocculant supply relationships in hydrometallurgical expansion corridor. |
Study Parameters
Direct dialogue with plant managers at coal-to-chemical complexes, procurement leads at North American refineries, distribution channel partners in European industrial clusters, and technical R&D directors at polymer formulators grounded qualitative assessment. Secondary validation drew from customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings of diversified chemical conglomerates, and MEE discharge permit databases. Bottom-up and top-down triangulation cross-checked volume estimates against capacity announcements and end-use consumption patterns.
Bottom-up modeling built from segment-level consumption rates across coagulant, flocculant, disinfectant, and pH adjuster product tiers, then aggregated through end-use applications in wastewater treatment, industrial process water, drinking water, and desalination. Top-down verification anchored against macroeconomic drivers including EPA effluent guideline enforcement, EU Green Deal industrial water targets, and China's zero-liquid-discharge mandate expansion. CAGRs derived from regression analysis of historical procurement cycle compression and specification premium expansion across the analysis window.
Underlying measurement precision varies by segment; semiconductor ultrapure water and desalination antiscalant categories carry tighter precision than commodity municipal coagulants due to concentrated buyer visibility. Forecasts reflect assumptions about regulatory enforcement continuity and raw material input stability. A model refresh is warranted upon material change in MEE discharge permit penalty structures or REACH biocide registration timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
US Water and Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Water and Wastewater Treatment Technologies Market
Water & Sludge Treatment
Slurry Homogenizer Tank Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Africa Water Treatment Chemicals Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Industrial Wastewater Treatment Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
Australia Water Treatment Chemicals Market
Water & Sludge Treatment
Sedimentation and Centrifugation Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
North America Industrial Water Treatment Market
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
Water Gel Market