
 North America Industrial Water Treatment Market | 2026-2036
North America Industrial Water Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Water Treatment Market Analytics
Market Context
Texas and Louisiana is fragmenting as shale operators build modular treatment skids near the Permian and Haynesville formations. Ecolab Inc. leverages its on-site service model to embed chemists directly at refinery and petrochemical complexes across the Gulf Coast. Kurita Water Industries Ltd. anchors its North American position through captive membrane production and localized blending operations in California and Illinois.
Technical Definition and Segment Structure
North America Industrial Water Treatment encompasses engineered systems and chemical programs that remove suspended solids, dissolved minerals, biological contaminants, and hydrocarbons from influent streams to meet process specifications or discharge permits, typically operating across pressure ranges from ambient to 150 bar and temperatures up to 300°C in boiler applications. Chemical Treatment dominates current revenue as specialty coagulants and scale inhibitors command recurring formulation contracts, while Membrane Bioreactor technology leads growth in food and beverage facilities seeking compact biological nutrient removal. Oil & Gas end users concentrate procurement spending on mobile reverse osmosis units for frac water recycling, whereas Power Generation sustains steady demand for ion exchange resin regeneration services at combined-cycle plants.
Regulatory Framework and Outlook
EPA effluent limitation guidelines and the Clean Water Act Section 402 NPDES program shape product specifications by mandating technology-based treatment standards for specific industrial categories. State-level regulations in California, Texas, and Pennsylvania layer additional requirements for produced water recycling, cooling tower blowdown management, and selenium discharge limits. Stakeholders must monitor how emerging per- and polyfluoroalkyl substance rules redefine membrane selection criteria and chemical procurement protocols across manufacturing and power sectors.
Market Dynamics
Zero-liquid discharge mandates from the EPA are forcing power generators and shale operators to redesign treatment trains around crystallizers and evaporators rather than conventional discharge permits.
Growth Catalysts
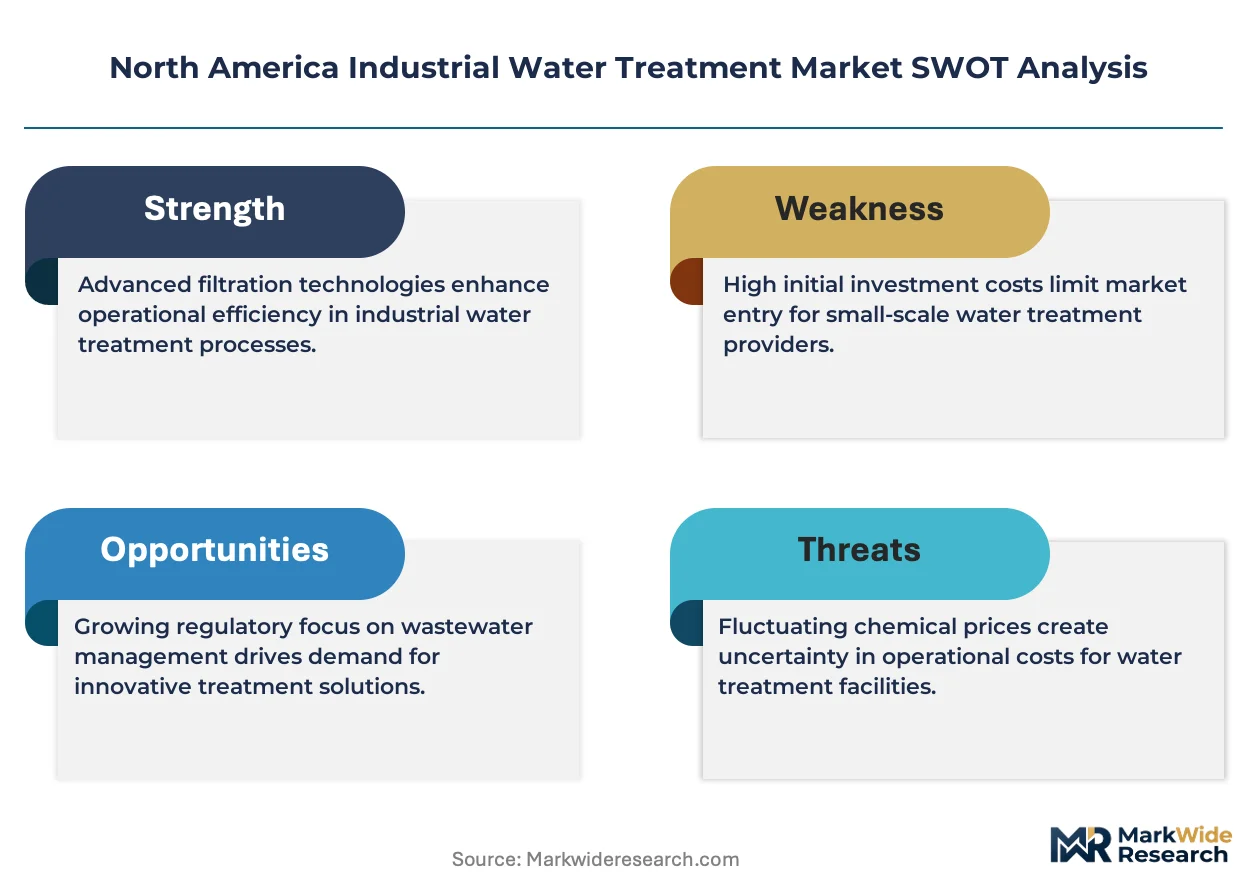
- ELG Stringency:EPA effluent limitation guidelines for steam electric power generation mandate advanced biological treatment for selenium and arsenic, compelling utilities to upgrade legacy physical-chemical systems.
- Permian Produced Water Volumes:Oilfield operators in West Texas and southeastern New Mexico require mobile treatment capacity to manage rising water-to-oil ratios in maturing shale wells.
- Membrane Bioreactor Adoption:Food and beverage processors deploy compact MBR units to meet stringent nutrient discharge limits while minimizing footprint constraints at existing facilities.
Market Restraints
- Specialty Chemical Feedstock Volatility:Acrylic acid and phosphonate precursor prices fluctuate with propylene and phosphorus rock markets, squeezing formulation margins for scale inhibitor suppliers.
- Membrane Import Concentration:Reverse osmosis and nanofiltration element production concentrates in East Asian manufacturing clusters, exposing North American system integrators to shipping cost spikes and tariff exposure.
- High-Pressure Vessel Certification Delays:ASME Section VIII pressure vessel approvals for boiler feedwater systems extend project timelines by four to eight months, constraining rapid deployment capacity.
Strategic Opportunities
- Alberta Oil Sands Brine Management:Canadian thermal extraction operations seek zero-liquid discharge partners to handle produced water volumes exceeding conventional evaporation pond capacity.
- PFAS Destruction Technologies:Emerging EPA drinking water standards for per- and polyfluoroalkyl substances create demand for supercritical water oxidation and plasma arc systems at fluoropolymer manufacturing sites.
- Digital Twin Integration:Convergence of membrane performance sensors with predictive analytics platforms enables remote optimization of chemical dosing and cleaning cycles at distributed industrial facilities.
Industry Challenges
- Cross-Membrane Fouling Expertise Gap:Facilities struggle to hire operators trained in diagnosing organic, inorganic, and biological fouling mechanisms across polyamide and ceramic membrane systems simultaneously.
- Legacy DCS Integration Friction:Modern treatment skids with IoT-enabled sensors require costly protocol translation to communicate with decades-old distributed control systems prevalent at Gulf Coast refineries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Water Treatment Market |
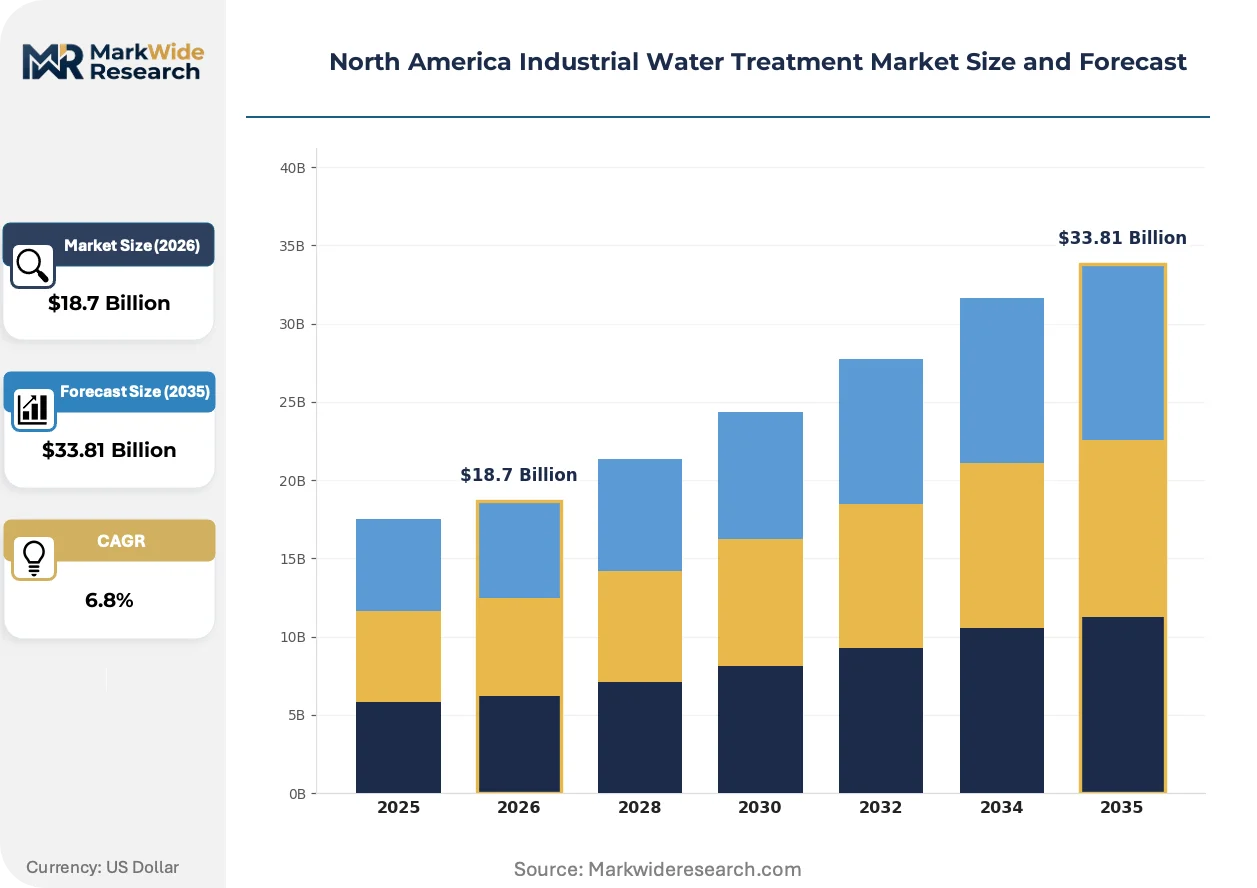
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtration Systems, Chemical Treatment, Disinfection Equipment, Softening Units End User: Manufacturing, Power Generation, Oil & Gas, Mining Technology: Reverse Osmosis, Ultraviolet, Ion Exchange, Membrane Bioreactor Application: Cooling Towers, Boiler Feed Water, Wastewater Treatment, Process Water |
| Companies Covered | Kurita Water Industries Ltd., Kemira, Ecolab Inc., Pentair, Xylem, Veolia Water Technologies, Solenis, BASF SE, SUEZ Water Technologies & Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Water Treatment Market Evolving Landscape
Digital instrumentation and real-time analytics are compressing the feedback loop between water quality measurement and chemical adjustment, displacing scheduled maintenance with condition-based intervention across heavy industrial sites.
Machine learning algorithms applied to membrane performance data are digitizing fouling prediction and cleaning optimization at power generation and semiconductor fabrication facilities. Duke Energy and Intel have deployed pilot systems that reduce unplanned downtime by triggering chemical cleans only when transmembrane pressure trends indicate imminent flux decline. This shift compresses operating expenditure while extending membrane element service life beyond manufacturer warranties.
EPA's pending maximum contaminant level rules for PFAS in drinking water are tightening pretreatment requirements for industrial dischargers to municipal wastewater systems. Manufacturing facilities in Michigan and North Carolina now face enhanced monitoring obligations for fluorinated compounds in process effluent. Activated carbon and ion exchange resin suppliers are scaling production of selective media to capture short-chain PFAS homologs that evade conventional GAC breakthrough curves.
Shale operators are consolidating produced water procurement around integrated service contracts that bundle treatment, transportation, and disposal rather than sourcing each component separately. This bundling concentrates purchasing power with midstream water handlers in the Permian and Bakken formations. E&P companies sacrifice operational flexibility for capital efficiency, accepting long-term offtake commitments in exchange for eliminated upfront equipment investment.
North America Industrial Water Treatment Market Segmentation
Industrial water treatment procurement patterns diverge sharply across technology platforms and end-use requirements. Equipment selection depends on influent chemistry, discharge permit stringency, and capital-versus-operating cost tradeoffs that vary by facility age and throughput.
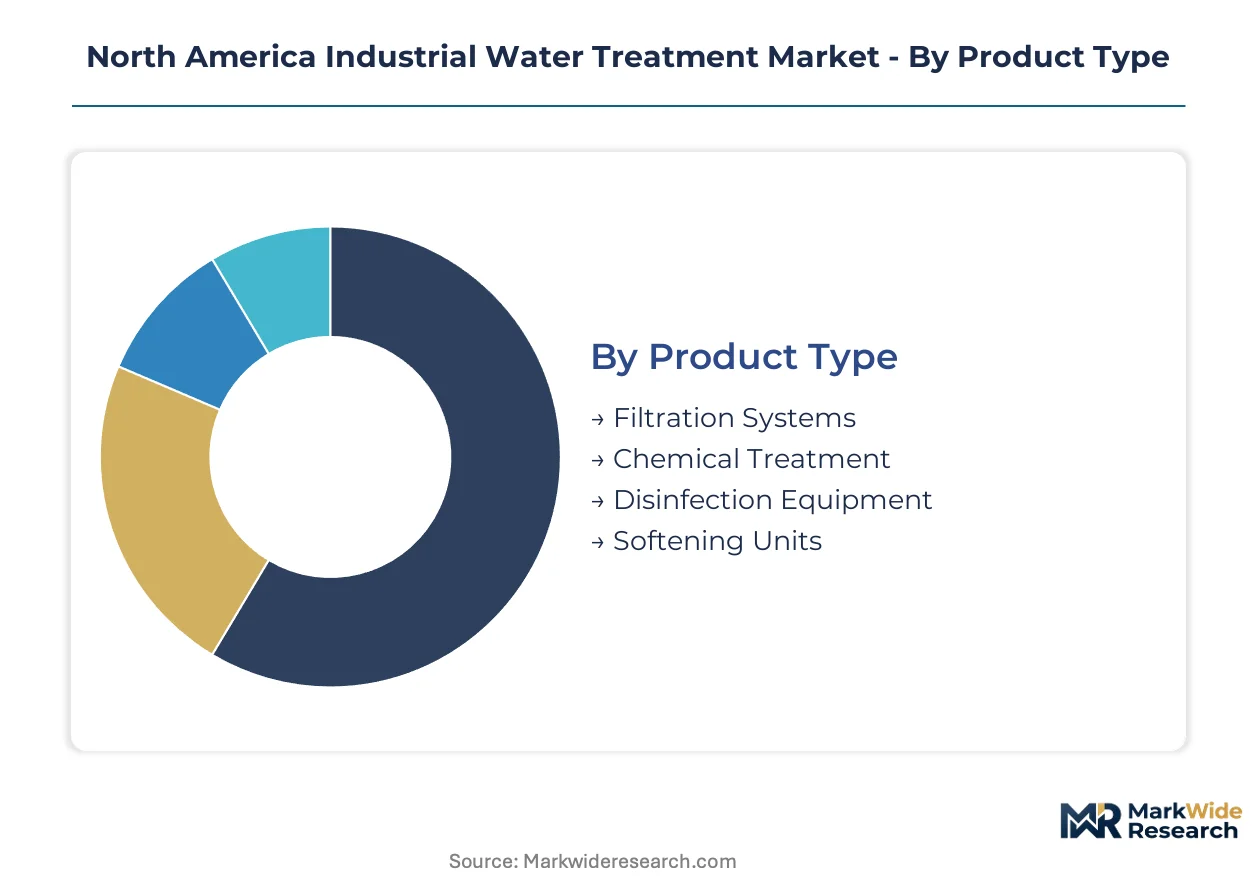
Product Type:
Cost tier stratification separates capital-intensive engineered systems from recurring chemical service contracts.
- Filtration Systems:Pressure-driven membrane and media filtration units remove suspended solids and particulate matter across 0.1 to 100 micron ranges. Power generators in Texas deploy high-rate granular media filters ahead of reverse osmosis trains to protect membrane integrity from cooling tower blowdown debris.
- Chemical Treatment:Specialty coagulants, flocculants, scale inhibitors, and corrosion control formulations dominate recurring revenue through long-term supply agreements. Gulf Coast refineries anchor demand for phosphonate-based scale inhibitors handling high-temperature boiler feedwater chemistry.
- Disinfection Equipment:Chlorination systems, ozone generators, and UV reactors eliminate biological contaminants in municipal and industrial effluent streams.
- Softening Units:Ion exchange and lime-soda softening systems reduce calcium and magnesium hardness to prevent scale deposition in heat transfer equipment.
Filtration Systems holds installed capacity. Chemical Treatment is rotating up the share rankings.
End User:
Application context determines specification intensity — thermal power plants demand ultra-pure boiler makeup while shale operators prioritize mobility.
- Power Generation:Combined-cycle and coal-fired plants require continuous demineralization, condensate polishing, and cooling water chemistry management. EPA effluent limitation guidelines for selenium and arsenic are compelling utilities across the Ohio River Valley to upgrade legacy physical-chemical treatment trains.
- Oil & Gas:Upstream operators and midstream handlers manage produced water volumes exceeding oil output in maturing Permian Basin wells. Mobile treatment skids enable frac water recycling at pad sites where pipeline infrastructure remains underdeveloped.
- Manufacturing:Automotive, electronics, and food processing facilities need process water meeting tight conductivity and microbial specifications.
- Mining:Hard rock and solution mining operations treat acid mine drainage and process slurry water for metals recovery or environmental compliance.
Power Generation commands the largest installed base. Oil & Gas is climbing the fastest on capital deployment intensity.
Technology:
Maturity gradients separate established pressure-driven membrane processes from emerging biological treatment platforms.
- Reverse Osmosis:Semi-permeable polyamide membranes operating at 15-85 bar reject dissolved salts and organics to produce high-purity permeate. Semiconductor fabrication plants in Arizona and Texas specify double-pass RO systems achieving resistivity above 18 megohm-cm for wafer rinsing operations.
- Membrane Bioreactor:Immersed or sidestream ultrafiltration membranes coupled with activated sludge bioreactors achieve compact biological nutrient removal. Food and beverage processors in California deploy MBR technology to meet stringent nitrogen discharge limits within constrained site footprints.
- Ultraviolet:Medium-pressure UV lamps destroy microbial contaminants and degrade trace organics without chemical residuals.
- Ion Exchange:Cation and anion resin beds remove dissolved ions through reversible chemical substitution, regenerated with acid and caustic.
Reverse Osmosis dominates existing capacity. Membrane Bioreactor is gaining share fastest on regulatory pressure for nutrient removal.
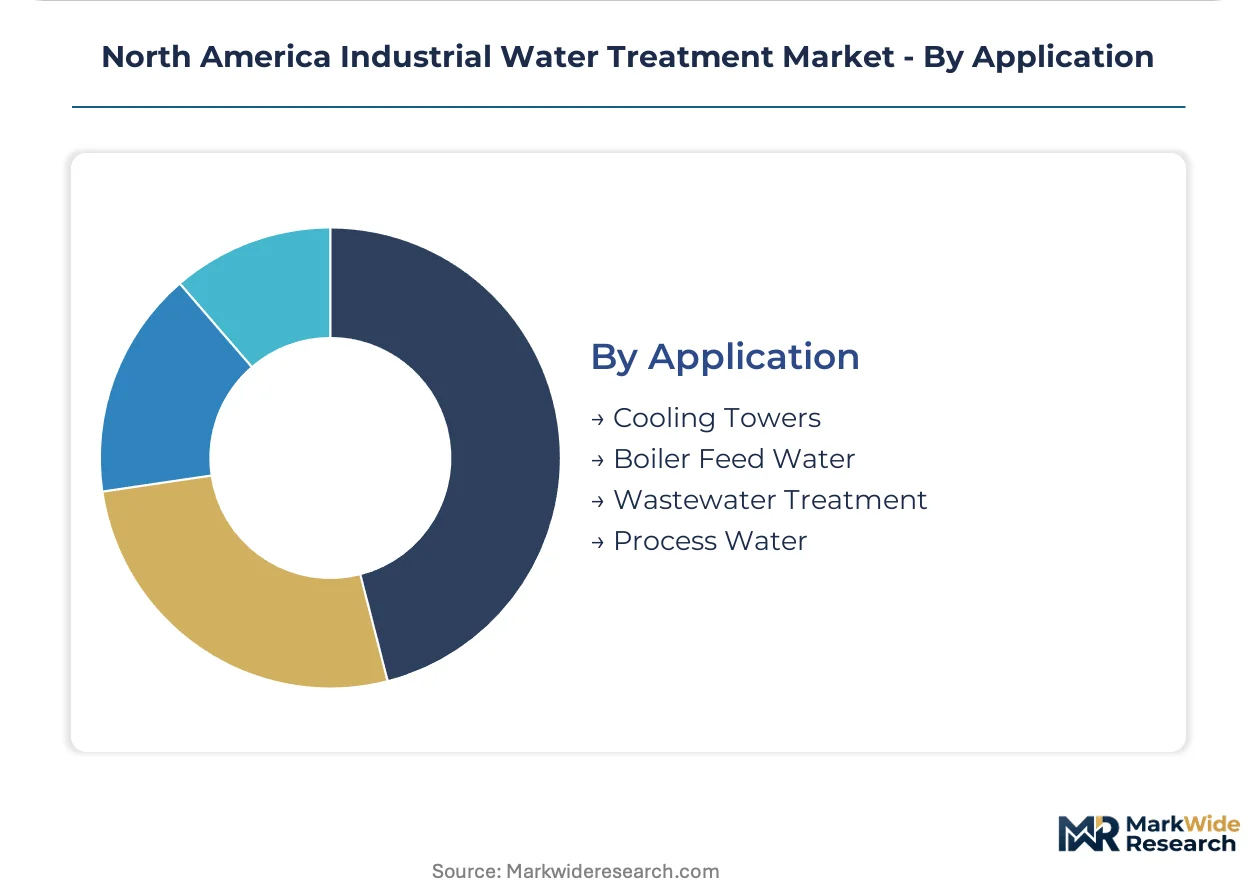
Application:
Volume throughput and water quality specifications create distinct equipment and chemical procurement patterns.
- Boiler Feed Water:Ultra-pure makeup water prevents scale, corrosion, and carryover in high-pressure steam generators. Combined-cycle plants in Louisiana specify mixed-bed polishers and continuous electrodeionization to maintain silica levels below 10 parts per billion.
- Wastewater Treatment:End-of-pipe systems ensure effluent meets NPDES permit limits before surface water discharge. Pennsylvania steel mills invest in advanced metals precipitation and biological treatment to comply with renewed discharge permits.
- Cooling Towers:Open and closed recirculating systems require biocide dosing, scale inhibition, and blowdown management to control cycles of concentration.
- Process Water:Manufacturing operations need consistent water chemistry for rinsing, coating, chemical formulation, and product contact applications.
Boiler Feed Water anchors premium system sales. Wastewater Treatment is expanding most quickly on tightening discharge standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water treatment intensity varies sharply across North American jurisdictions. Canada emphasizes oil sands brine management, Mexico faces industrial discharge infrastructure gaps, and the United States fragments between Permian produced water recycling and power sector zero-liquid discharge mandates.
United States
Texas and Louisiana anchor equipment demand through shale operators and Gulf Coast refineries. EPA effluent limitation guidelines for steam electric power generation force selenium and arsenic treatment upgrades across the Ohio River Valley. The Permian Basin concentrates mobile reverse osmosis deployment where water-to-oil ratios exceed three-to-one in maturing wells.
Canada
Alberta's thermal oil sands operations generate produced water volumes exceeding conventional evaporation pond capacity. Alberta Energy Regulator directives on tailings pond closure accelerate zero-liquid discharge partnerships for brine management. The Athabasca oil sands region attracts crystallizer and evaporator system integrators seeking long-term service contracts.
Mexico
Northern border states house maquiladora manufacturing clusters with inconsistent municipal wastewater infrastructure. CONAGUA's national water law amendments tighten industrial discharge monitoring obligations for foreign-owned assembly plants. Monterrey and Tijuana face acute pressure to upgrade end-of-pipe treatment for electronics and automotive rinse water.
California
Semiconductor fabrication plants in Silicon Valley and Central Valley food processors drive ultra-pure water and nutrient removal demand. State Water Resources Control Board recycling mandates compel facilities to meet Title 22 standards for agricultural reuse. The Central Valley concentrates membrane bioreactor installations where dairy and vegetable processing discharge limits tighten.
Pennsylvania
Appalachian shale gas operators manage flowback water from hydraulic fracturing in the Marcellus formation. Department of Environmental Protection regulations on total dissolved solids limit direct surface water discharge options. Pittsburgh-area steel mills invest in advanced metals precipitation to comply with renewed NPDES permits.
North America Industrial Water Treatment Market Competitive Landscape
Capability concentration sits with specialty chemical formulators and membrane system integrators; scale advantage sits with diversified water technology conglomerates. The market structures around three tiers: multinational chemical-service hybrids with embedded field teams, equipment-focused system builders with captive membrane production, and regional water handlers consolidating Permian produced water logistics. Dominant competitive moves include backward integration into chemical precursor supply and strategic partnerships between treatment technology vendors and midstream water handlers.
Within the chemical-service tier, Ecolab Inc. and Solenis exemplify the embedded technical specialist model through on-site chemist deployment at heavy industrial complexes. Kurita Water Industries Ltd. anchors the captive manufacturing archetype through localized blending operations. Among diversified technology providers, Xylem and Pentair occupy positions spanning equipment and digital monitoring platforms. Veolia Water Technologies and SUEZ Water Technologies & Solutions represent the integrated service-contract model with treatment-as-a-service offerings. BASF SE and Kemira sit within the specialty chemicals vector, supplying phosphonate scale inhibitors and coagulant formulations under long-term supply agreements.
| Leading Market Players |
|---|
| Kurita Water Industries Ltd. |
| Kemira |
| Ecolab Inc. |
| Pentair |
| Xylem |
| Veolia Water Technologies |
| Solenis |
| BASF SE |
| SUEZ Water Technologies & Solutions |
| Others |
Value Network & Pricing Analysis
Overcapacity in East Asian membrane manufacturing clusters is compressing supplier margins and forcing North American system integrators toward long-term offtake contracts that lock in volume commitments in exchange for pricing stability.
Pricing Analysis
Long-term offtake contracts dominate procurement for high-volume shale operators in the Permian Basin, while spot purchasing persists for emergency membrane replacements and mobile treatment skid deployments. Price differentiation hinges on ASME Section VIII certification tier and bundled field service chemist deployment. Pricing pressure stems from acrylic acid and phosphonate precursor volatility squeezing formulation margins. Midstream water handlers exhibit highest price sensitivity due to thin offtake economics, whereas semiconductor fabricators prioritize specification compliance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with membrane element producers in Japan, South Korea, and Taiwan, where polyamide thin-film composite production feeds North American system integrators. Raw material dependencies encompass propylene derivatives for phosphonate scale inhibitors, phosphorus rock for specialty coagulants, and high-grade stainless steel for pressure vessel fabrication. Tariff exposure on imported membrane elements creates margin vulnerability for equipment-focused builders. Distribution runs through authorized regional distributors holding technical inventory and regeneration service capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America industrial water treatment sits in early-cycle expansion as EPA zero-liquid discharge mandates force wholesale treatment train redesigns across power generation and shale extraction.
For Market Incumbents: Pre-empt margin erosion in commodity chemical formulations by accelerating backward integration into phosphonate precursor supply and captive membrane production. Defend position against emerging digital-twin specialists by embedding predictive analytics platforms within existing service contracts. Prioritize certification investment in PFAS-selective media production ahead of federal maximum contaminant level enforcement. For New Entrants and Emerging Players: Pursue white-space opportunity in Alberta oil sands brine management crystallizer deployments and PFAS destruction technology integration at fluoropolymer manufacturing sites. The most penetrable segment is midstream water handling consolidation in the Permian, where bundled service contracts concentrate purchasing power with undercapitalized regional handlers. Go-to-market angle should emphasize treatment-as-a-service models that eliminate upfront capital burden for E&P operators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty chemical formulators with embedded field chemist deployments at Gulf Coast refineries. Long-term viability favors targets with captive manufacturing and localized blending operations that insulate against import tariff exposure. Acquisition target archetype: regional water handlers with Permian logistics networks and underutilized treatment capacity. Signal to watch: EPA PFAS rulemaking acceleration triggering pretreatment infrastructure upgrades at manufacturing facilities discharging to municipal systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemical Precursors | Captive phosphonate supply insulates Ecolab and Solenis from propylene derivative volatility. |
| Zero-Liquid Discharge Partnership | Alberta oil sands operators seek crystallizer integrators as tailings pond closure deadlines tighten. |
| PFAS-Selective Media Scale-Up | Activated carbon and ion exchange resin suppliers expand production for EPA drinking water standards. |
| Digital Twin Platform Deployment | Membrane performance sensors with predictive analytics reduce unplanned downtime at Intel fabrication plants. |
| Midstream Water Handler Consolidation | Integrated service contracts bundle treatment, transportation, and disposal in Permian Basin logistics. |
Research Methodology
Desk research of EPA effluent limitation guidelines, state-level discharge permit databases, and oilfield water production statistics preceded structured interviews with plant engineers at Texas power generators, procurement leads at Permian shale operators, technical R&D directors at specialty chemical formulators, and aftermarket service heads at membrane system integrators. Secondary validation drew from EIA power plant water use disclosures, SEC 10-K filings of diversified water technology providers, and Alberta Energy Regulator tailings management directives. Bottom-up equipment deployment tallies and top-down chemical consumption estimates were triangulated against regional water stress indices.
Assumptions held fixed include EPA regulatory timelines for selenium and arsenic treatment mandates, while oil-to-water ratio trajectories in maturing shale wells and PFAS maximum contaminant level stringency were varied across sensitivity scenarios. Segmentation modeling spanned technology platform, end-use intensity, and regional regulatory cluster dimensions. CAGRs were derived from installed base replacement cycles and emerging technology penetration curves. Forecast inputs incorporated membrane element replacement intervals and chemical dosing rates per barrel of produced water treated.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or propylene feedstock pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement pace and technology cost reduction curves. Quarterly review of EPA rulemaking dockets and Permian water-to-oil production ratios is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Water and Wastewater Treatment Technologies Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
Global Turbidity Meters Market
Water & Sludge Treatment
Process Water Treatment Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
Industrial Wastewater Treatment Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Global Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market
Water & Sludge Treatment
US Liquid Waste Management Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
United Kingdom Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market