
 Mexico Water Treatment Chemicals Market | 2026-2036
Mexico Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Water Treatment Chemicals Market Intelligence
Monterrey's industrial chemical manufacturing base is reshaping supply availability for northern Mexico's water-intensive sectors. Solenis leverages its regional blending facilities to serve pulp and paper customers with tailored coagulant programs. Kemira sustains competitive positioning through captive polymer production and technical service teams embedded at major industrial accounts. Dow anchors the high-performance flocculant segment with anionic and cationic polymer lines optimized for Mexican wastewater chemistry.
Water treatment chemicals comprise formulated products including coagulants, disinfectants, flocculants, and pH adjusters designed to remove suspended solids, neutralize pathogens, and stabilize water chemistry across municipal and industrial systems. These formulations typically operate within specified dosage ranges measured in parts per million and require compatibility with target contaminant profiles to achieve regulatory compliance. The coagulants and flocculants category captures the largest volume share due to persistent turbidity challenges in Mexican surface water sources, while disinfectants command premium pricing tied to NOM-127-SSA1 potable water microbiological standards. Cooling water treatment applications within the industrial end-user segment represent the fastest-expanding demand pool as manufacturing capacity expands in automotive and electronics maquiladoras.
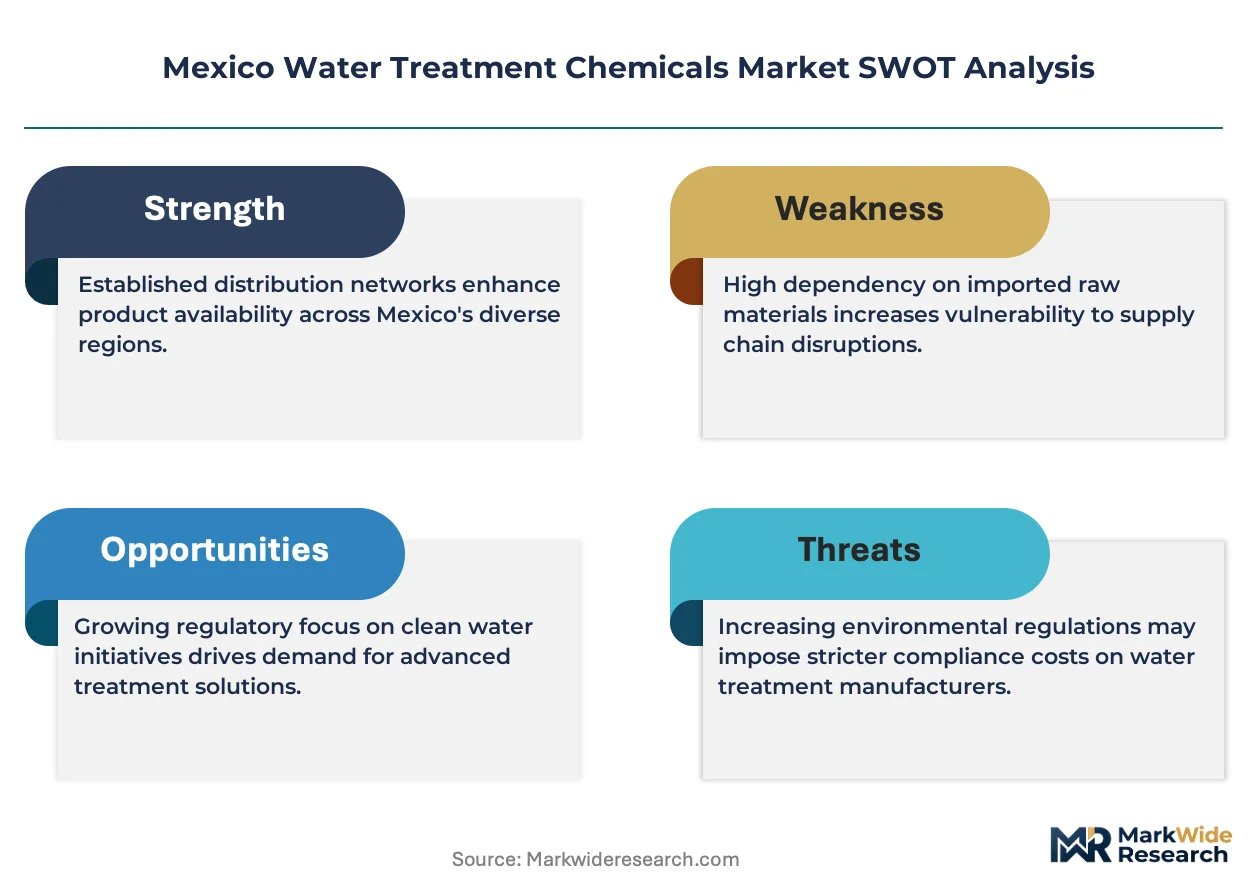
SEMARNAT enforces NOM-001-SEMARNAT effluent limits that mandate tertiary treatment at industrial discharge points, directly expanding demand for advanced oxidation and membrane-compatible chemical pretreatment. CONAGUA's basin management plans for the Lerma-Santiago-Pacific and Bravo-Conchos systems impose withdrawal allocations that force industrial users toward higher-cycle cooling chemistry and zero-liquid-discharge configurations. Stakeholders must monitor pending updates to NOM-003-SEMARNAT reuse standards and assess biological treatment technology integration against chemical-intensive alternatives.
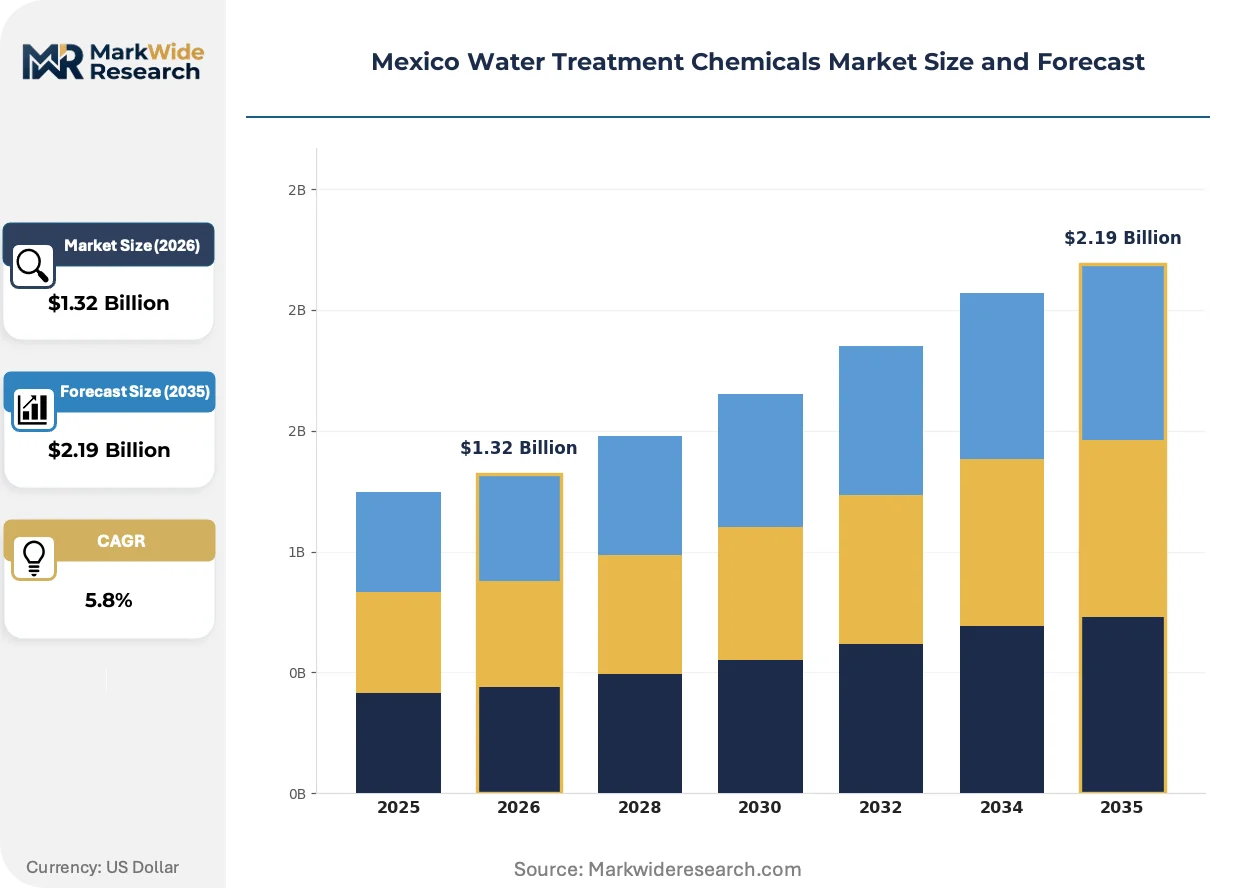
Market Dynamics
SEMARNAT's enforcement of NOM-001-SEMARNAT tertiary treatment mandates is compressing chemical specification windows and forcing industrial discharge points toward membrane-compatible pretreatment chemistries.
Growth Catalysts
- Automotive maquiladora expansion:Cooling water treatment demand accelerates as Querétaro and Guanajuato assembly plants scale zero-liquid-discharge configurations.
- NOM-127-SSA1 microbiological standards:Municipal utilities in Monterrey and Mexico City expand chlorine dioxide and chloramine procurement for potable water disinfection compliance.
- CONAGUA basin allocation limits:Lerma-Santiago-Pacific withdrawal caps push industrial users toward higher-cycle cooling chemistry and chemical-intensive water reuse.
Market Restraints
- Aluminum sulfate price volatility:Monterrey's industrial chemical manufacturing base faces feedstock cost pressure from bauxite supply fluctuations.
- Polymer import concentration:Cationic flocculant supply depends on US Gulf Coast production, exposing northern Mexico to cross-border logistics friction.
- Membrane fouling incompatibility:Legacy coagulant chemistries create irreversible fouling in reverse osmosis pretreatment, limiting retrofit options.
Strategic Opportunities
- Baja California semiconductor fabs:Ultrapure water chemical demand outpaces local supply, creating entry points for high-purity reagent specialists.
- NOM-003-SEMARNAT reuse standards:Pending updates to industrial wastewater reuse rules will expand tertiary chemical dosing requirements.
- Digital dosing integration:IoT-enabled chemical feed systems converge with predictive analytics to enable precision coagulation control.
Industry Challenges
- Certified chemical engineer scarcity:Complex NOM compliance documentation requires specialized regulatory affairs capacity that outstrips university pipeline output.
- Legacy SCADA integration:Automated chemical feed systems face protocol mismatches with decades-old municipal control infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Water Treatment Chemicals Market |
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.19 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Disinfectants, Flocculants, pH Adjusters End User: Municipal, Industrial, Residential, Commercial Application: Drinking Water Treatment, Wastewater Treatment, Cooling Water Treatment, Swimming Pool Treatment Technology: Chemical Treatment, Biological Treatment, Membrane Filtration, Advanced Oxidation |
| Companies Covered | Solenis, Solvay, Ecolab, Veolia, Dow, BASF SE, SNF Group, Baker Hughes Company, Kemira, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Water Treatment Chemicals Market Strategic Shifts & Innovations
Biopolymer flocculants and smart dosing platforms are disrupting Mexico's historically commodity-driven water treatment chemical procurement patterns.
Chitosan-derived biocoagulants from shrimp processing waste streams are rendering obsolete conventional aluminum sulfate programs in Baja California seafood processing plants. Guerrero and Sinaloa aquaculture operations adopt these formulations to meet organic certification requirements for export markets. The shift is compressing synthetic coagulant margins while opening premium pricing tiers for bio-based alternatives.
SEMARNAT's pending NOM-003-SEMARNAT reuse standard revision tightens allowable contaminant limits for industrial process water recycling. Automotive stamping plants in Aguascalientes and electronics assembly in Tijuana face mandatory tertiary treatment upgrades. The regulation is accelerating demand for membrane-compatible antiscalants and advanced oxidation process chemicals.
Volume-based chemical procurement contracts face displacement by performance-guaranteed service agreements in Monterrey's pulp and paper sector. Solenis and Kemira technical service teams embed at major accounts to assume operational risk for treatment outcomes. The model concentrates buyer power among large industrial water users while squeezing spot-market chemical distributors.
Mexico Water Treatment Chemicals Market Segmentation
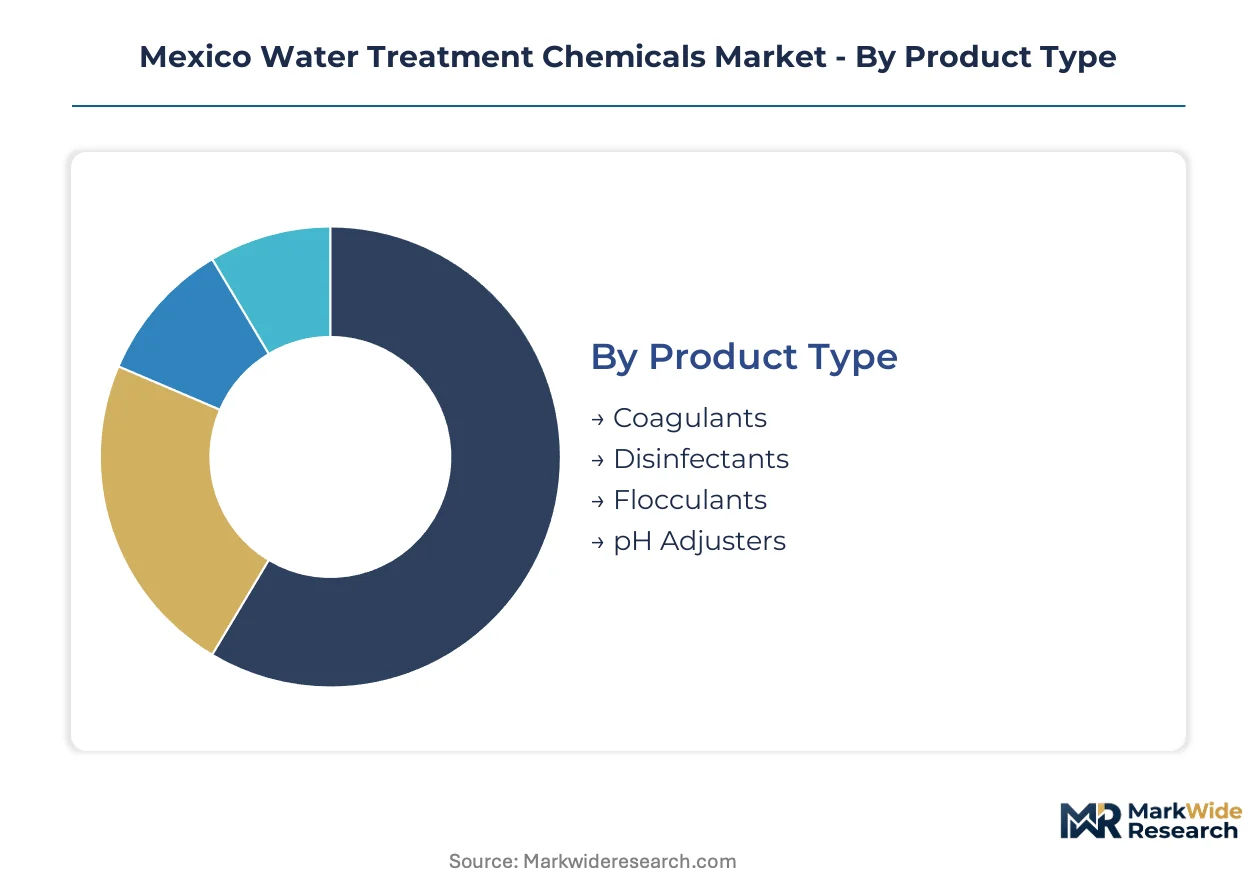
Water treatment chemical procurement in Mexico diverges sharply across user types and regulatory exposure. Product specifications vary with contaminant profiles, while technology choices reflect capital availability and discharge permit stringency.
Product Type:
Mature commodity chemistries dominate procurement volumes, though membrane-compatible formulations are accelerating as tertiary treatment mandates spread.
- Coagulants:Aluminum sulfate and ferric chloride formulations precipitate suspended solids from turbid surface water sources. Municipal utilities in the Lerma-Santiago-Pacific basin rely on these programs to meet CONAGUA turbidity standards for potable supply.
- Flocculants:Anionic and cationic polyacrylamide polymers bridge coagulated particles into settleable flocs. Electronics maquiladoras in Tijuana and Guadalajara deploy high-molecular-weight cationic grades for semiconductor wastewater clarification ahead of reverse osmosis.
- Disinfectants:Chlorine dioxide, sodium hypochlorite, and chloramine formulations neutralize pathogens per NOM-127-SSA1 microbiological limits.
- pH Adjusters:Sulfuric acid, caustic soda, and lime products stabilize influent chemistry for biological and membrane processes.
Coagulants retain volume leadership; flocculants hold the steepest expansion curve.
End User:
Customer scale determines procurement sophistication, with large industrial accounts demanding performance guarantees unavailable to fragmented residential buyers.
- Industrial:Automotive assembly plants, pulp and paper mills, and electronics manufacturers operate closed-loop cooling and zero-liquid-discharge systems requiring continuous chemical optimization. SEMARNAT discharge permits for these facilities mandate real-time monitoring and documented dosing protocols.
- Municipal:State water commissions and city utilities manage potable treatment for Monterrey, Mexico City, and Guadalajara metropolitan areas. NOM-127-SSA1 compliance drives chlorine-based disinfection procurement at centralized treatment plants serving millions of connections.
- Commercial:Hotels, hospitals, and office complexes maintain secondary disinfection for building plumbing systems.
- Residential:Individual households purchase point-of-use filters and small-scale disinfectants through retail channels.
Industrial users capture the premium service tier; municipal accounts anchor baseline volume commitments.
Application:
Process intensity varies with water quality targets, from pathogen elimination in drinking water to mineral scaling control in high-cycle cooling systems.
- Cooling Water Treatment:Scale inhibitors, corrosion control agents, and biocides maintain heat exchange efficiency in power generation and manufacturing. Querétaro and Guanajuato automotive plants expanding zero-liquid-discharge configurations are driving specialty chemical demand for high-concentration operation.
- Wastewater Treatment:Coagulants, flocculants, and advanced oxidation chemicals remove solids and degrade organics ahead of discharge or reuse. NOM-001-SEMARNAT tertiary treatment mandates are forcing industrial facilities toward membrane-compatible pretreatment chemistries.
- Drinking Water Treatment:Disinfection and turbidity control dominate municipal treatment trains.
- Swimming Pool Treatment:Chlorine stabilizers and pH buffers maintain recreational water quality.
Wastewater treatment commands the most complex chemical portfolios; cooling water applications are climbing fastest on manufacturing expansion.
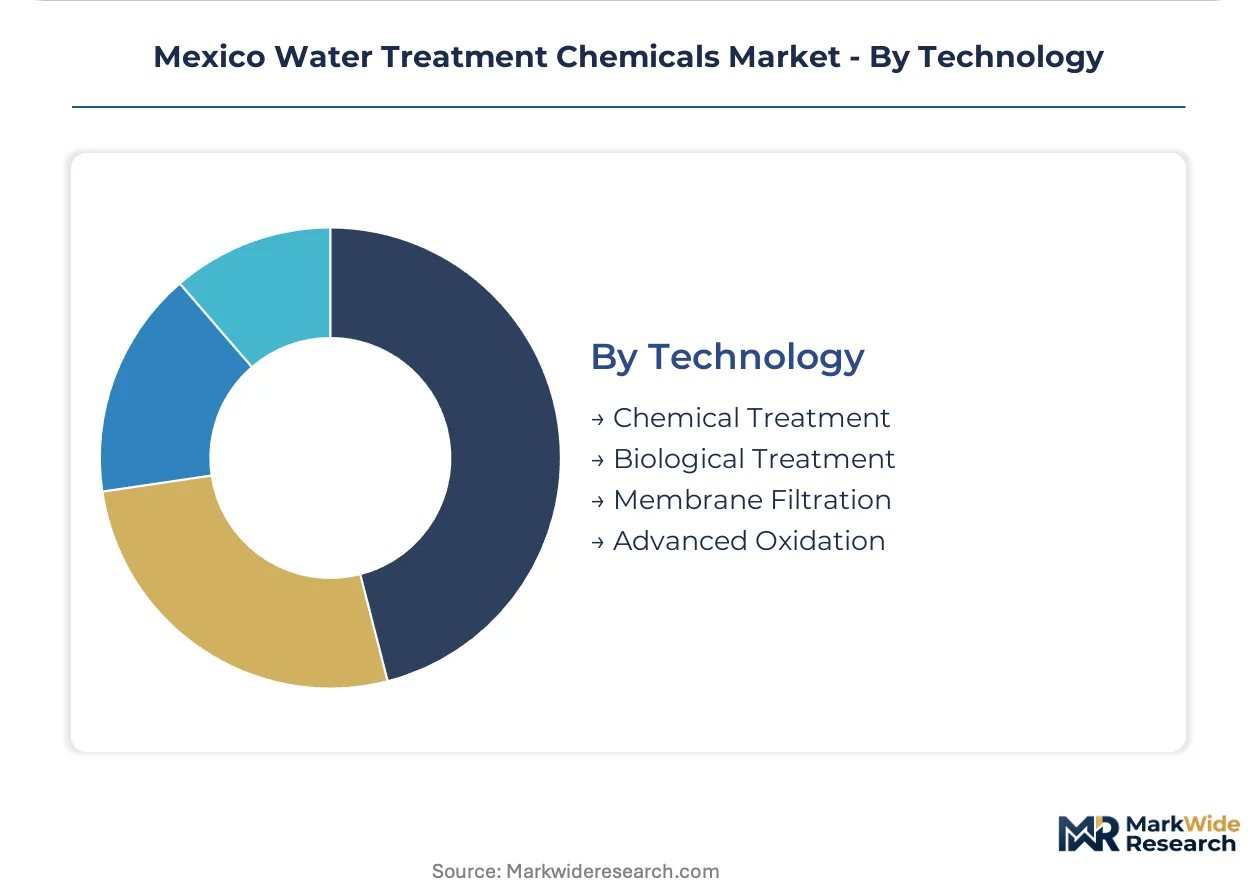
Technology:
Capital intensity and operational expertise stratify adoption, with chemical treatment remaining accessible where technical staffing is limited.
- Chemical Treatment:Dosing systems for coagulation, disinfection, and pH adjustment require lower capital investment than biological or membrane alternatives. Small and mid-sized industrial facilities across San Luis Potosí and Aguascalientes default to chemical-intensive approaches given scarce certified engineering capacity.
- Membrane Filtration:Reverse osmosis and ultrafiltration systems demand compatible pretreatment chemistries to prevent irreversible fouling. Baja California semiconductor fabs and pharmaceutical operations in Mexico State are expanding ultrapure water capacity with specialized antiscalant programs.
- Advanced Oxidation:Hydroxyl radical processes degrade recalcitrant organics in industrial effluents.
- Biological Treatment:Activated sludge and biofilm systems reduce organic loading with minimal chemical input.
Chemical treatment retains installed base dominance; membrane filtration is gaining share fastest on electronics and pharmaceutical investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's water treatment chemical consumption concentrates in manufacturing corridors where industrial discharge permits drive specification intensity, while municipal procurement patterns diverge sharply between northern industrial cities and southern agricultural zones.
Nuevo León
Monterrey's automotive and steel clusters generate concentrated demand for cooling water biocides and corrosion inhibitors. SEMARNAT's NOM-001-SEMARNAT enforcement at the Pesquería industrial park forces membrane-compatible pretreatment upgrades. The Santa Catarina valley hosts expanding zero-liquid-discharge installations serving appliance manufacturing.
Jalisco
Guadalajara's electronics maquiladoras and food processing plants require ultrapure water chemistries and organic-certified biocoagulants. CONAGUA's Lerma-Santiago-Pacific basin allocation limits push industrial users toward higher-cycle cooling chemistry. The El Salto industrial corridor anchors specialty polymer demand for semiconductor wastewater clarification.
Bajío Region
Querétaro and Guanajuato automotive assembly plants drive the fastest-expanding demand pool for closed-loop cooling treatment. NOM-127-SSA1 compliance in León's leather tanneries forces advanced oxidation process chemical adoption. The Apaseo el Grande industrial park exemplifies chemical-intensive water reuse configuration.
Northern Border States
Tijuana and Ciudad Juárez maquiladoras depend on US Gulf Coast polymer supply chains for flocculant procurement. EPA cross-border water quality agreements influence pretreatment standards at discharge points entering shared watersheds. The Mexicali valley's geothermal power plants anchor scale inhibitor demand for high-silica brine handling.
Mexico City Metro
The Valley of Mexico's potable water utilities deploy chlorine dioxide and chloramine systems under NOM-127-SSA1 microbiological mandates. Cutzamala system turbidity challenges sustain aluminum sulfate procurement volumes. The Tula industrial corridor's petroleum refining drives pH adjustment chemical demand for process water neutralization.
Mexico Water Treatment Chemicals Market Key Industry Players
Capability concentration sits with technical service specialists; scale advantage sits with commodity chemical producers with captive raw material access. The vendor base stratifies into three tiers: multinational formulators with embedded account teams, regional distributors with logistics networks, and import-dependent traders serving spot demand. Consolidation pressure intensifies as performance-guaranteed service agreements displace volume-based procurement. Backward integration into polymer production and forward integration into digital dosing systems represent the dominant competitive vectors.
Among multinational formulators, Solenis, Kemira, and Dow exemplify divergent strategic positioning. Solenis occupies the technical-service-intensive tier with account-embedded engineering capacity. Kemira represents captive polymer production integration with regional manufacturing footprints. Dow anchors the high-performance specialty segment with anionic and cationic polymer lines. These three companies illustrate the capability-scale tradeoff structuring competitive dynamics across Mexico's industrial water treatment procurement.
| Leading Market Players |
|---|
| Solenis |
| Solvay |
| Ecolab |
| Veolia |
| Dow |
| BASF SE |
| SNF Group |
| Baker Hughes Company |
| Kemira |
| Others |
Cost & Logistics Intelligence
US Gulf Coast polymer production concentration directly determines margin capture for northern Mexico's cationic flocculant buyers, with logistics friction amplifying cost pass-through to maquiladora wastewater treatment operations.
Pricing Analysis
Long-term offtake agreements dominate procurement for Monterrey's pulp and paper sector, while spot-market transactions persist among fragmented municipal utilities. Price differentiation hinges on technical service bundling and volume scale, with performance-guaranteed contracts commanding premiums over commodity chemical deliveries. Cost compression in synthetic coagulants is intensifying because chitosan-derived biocoagulants are capturing organic-certified segments. Municipal water commissions exhibit highest price sensitivity due to constrained public budgets; semiconductor fabs show lowest sensitivity given ultrapure water quality requirements.
Supply Chain Analysis
Bauxite feedstock draws from Guinea, Australia, and Brazil to supply Monterrey's aluminum sulfate manufacturing base, with ore grade variability propagating into finished chemical cost structures. Polyacrylamide monomer production rests on acrylonitrile supply from US Gulf Coast and Chinese petrochemical complexes. Single-source vulnerability concentrates in cationic polymer grades where US import dependence creates tariff exposure. Distribution runs through regional blending facilities operated by multinational formulators, with secondary distribution via local chemical traders serving spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of certified chemical engineers capable of navigating SEMARNAT compliance documentation creates a persistent capability gap that stratifies competitive performance across Mexico's water treatment procurement landscape.
For Market Incumbents: Entrench account relationships by embedding technical service teams at major industrial facilities to assume operational risk for treatment outcomes, while deepening backward integration into polymer production to offset import dependency. Biopolymer substitution threatens synthetic coagulant margins; captive biocoagulant sourcing from shrimp processing waste streams in Baja California and Sinaloa represents the priority defensive lever. For New Entrants and Emerging Players: Mid-sized industrial facilities across San Luis Potosí and Aguascalientes represent the most penetrable entry point, given scarce certified engineering capacity that limits adoption of complex biological or membrane alternatives. Baja California semiconductor fabs offer secondary white-space for ultrapure water reagent specialists where local supply lags demand. A digital dosing integration angle—pairing IoT-enabled feed systems with predictive analytics—provides differentiation against legacy commodity distributors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional chemical distributors possessing logistics networks but lacking technical service capabilities. The five-to-ten year viability window favors platforms with demonstrated NOM compliance expertise and embedded municipal utility relationships. Watch for NOM-003-SEMARNAT reuse standard finalization as the inflection signal that will expand tertiary chemical dosing requirements and accelerate performance-guaranteed contract adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive acrylamide supply reduces exposure to US Gulf Coast logistics friction and tariff volatility. |
| Digital Dosing Platform Deployment | IoT-enabled chemical feed systems enable precision coagulation control for CONAGUA basin allocation compliance. |
| Biocoagulant Manufacturing Scale-Up | Chitosan-derived formulations from shrimp waste streams access organic-certified premium pricing tiers. |
| Long-term Service Agreement Conversion | Performance-guaranteed contracts displace volume-based procurement in Monterrey's pulp and paper sector. |
| Regional Blending Facility Expansion | Localized formulation capacity shortens delivery lead times to Querétaro and Guanajuato automotive clusters. |
Research Approach
A standing panel of municipal water utility procurement managers, industrial plant engineers, SEMARNAT compliance officers, and regional chemical distributors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with downstream OEMs and distribution channel partners alongside secondary validation through customs trade data, CONAGUA basin management documentation, and SEC filings from multinational chemical formulators. Bottom-up demand modeling triangulated against top-down market sizing from production capacity and import flow analysis.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, end-user industry, application intensity, and regional regulatory exposure. CAGRs derived from fitted growth curves applied to baseline consumption estimates, incorporating industry-specific inputs including NOM-001-SEMARNAT enforcement timelines and automotive maquiladora capacity expansion schedules.
Macroeconomic conditions sit as an overlay; deviation in peso-dollar exchange rates, bauxite ore pricing, and cross-border logistics costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation pace and industrial investment cycles. Cross-checking against CONAGUA water withdrawal allocation data and SEMARNAT discharge permit issuance records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Asia-Pacific Drilling Waste Management Services Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
US Sludge Management and Dewatering Market
Water & Sludge Treatment
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Africa Water Treatment Chemicals Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
India Water Treatment Market