
 US Sludge Management and Dewatering Market | 2026-2036
US Sludge Management and Dewatering Market Size, Share, and Industry Trends Forecast 2026-2036
US Sludge Management and Dewatering Market Intelligence
Multi-source equipment procurement is pivoting toward integrated service contracts among large US waste operators. Waste Management, Inc. leverages its national landfill network to anchor sludge disposal volumes. Republic Services, Inc. competes through regional contracting density in the Southeast. Clean Harbors, Inc. specializes in hazardous and industrial sludge streams with higher treatment complexity.
US sludge management and dewatering encompasses the collection, stabilization, thickening, and moisture reduction of organic residuals from wastewater treatment, typically reducing solids content from two percent to twenty percent or higher through mechanical or thermal processes before final disposal or beneficial reuse. Mechanical dewatering leads equipment deployment due to lower capital intensity and proven reliability across municipal installations. Thermal dewatering commands premium margins where energy recovery integrates with biogas production facilities. Chemical conditioning sustains steady demand as utilities optimize polymer dosing for centrifuge throughput gains.
EPA biosolids regulations under 40 CFR Part 503 shape pathogen reduction standards and land application limits, while OSHA enforces worker exposure controls during dewatering operations. State-level environmental agencies in California and Texas impose additional heavy metals testing and disposal site restrictions that filter market access. Stakeholders must monitor emerging PFAS screening requirements in biosolids and assess equipment flexibility for thermal destruction pathways.
Market Dynamics
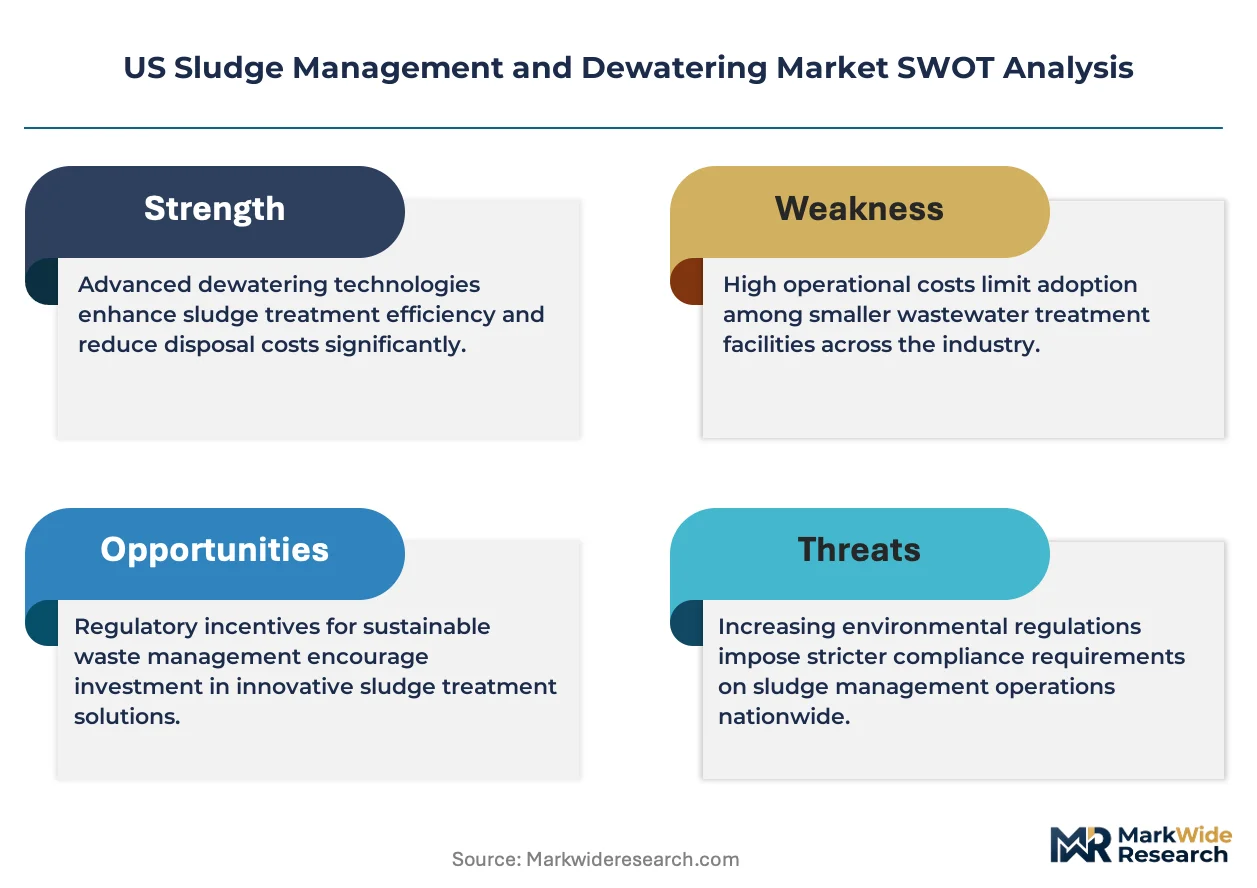
EPA's tightening biosolids regulations under 40 CFR Part 503 are forcing municipal utilities across Texas and California to accelerate mechanical dewatering upgrades ahead of landfill disposal deadlines. This regulatory compression is redistributing capital toward integrated service contracts and away from standalone equipment procurement.
Growth Catalysts
- 40 CFR Part 503 Pathogen Standards:Municipal utilities in the Great Lakes region must upgrade stabilization processes, driving centrifuge and belt press replacements.
- Texas Landfill Disposal Limits:State-level restrictions on sludge moisture content are compelling utilities to invest in higher-solids dewatering technologies.
- Biogas Facility Integration:Thermal dewatering systems coupled with anaerobic digesters are creating energy recovery revenue streams for wastewater treatment plants.
Market Restraints
- Polymer Cost Volatility:Chemical conditioning relies on acrylamide-based flocculants subject to petrochemical feedstock price swings.
- Equipment Supplier Concentration:Centrifuge manufacturing capacity clusters in Midwest industrial corridors, creating lead time bottlenecks for coastal utilities.
- PFAS Screening Uncertainty:Emerging state-level testing requirements for per- and polyfluoroalkyl substances in biosolids introduce compliance timeline risk.
Strategic Opportunities
- Southeast Municipal Expansion:Florida and Georgia utilities lag in dewatering automation, presenting retrofit potential for smart polymer dosing systems.
- Nutrient Recovery Mandates:EPA's anticipated phosphorus recovery requirements will create demand for struvite precipitation and thermal hydrolysis pre-treatment.
- Mobile Dewatering Services:Trailer-mounted centrifuge units are penetrating small-to-midsize treatment plants lacking permanent capital budgets.
Industry Challenges
- Operations Specialist Shortage:Centrifuge maintenance and polymer optimization require certified technicians scarce in rural utility districts.
- Legacy SCADA Integration:Modern dewatering controls must interface with decades-old distributed control systems common in Midwest plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Sludge Management and Dewatering Market |
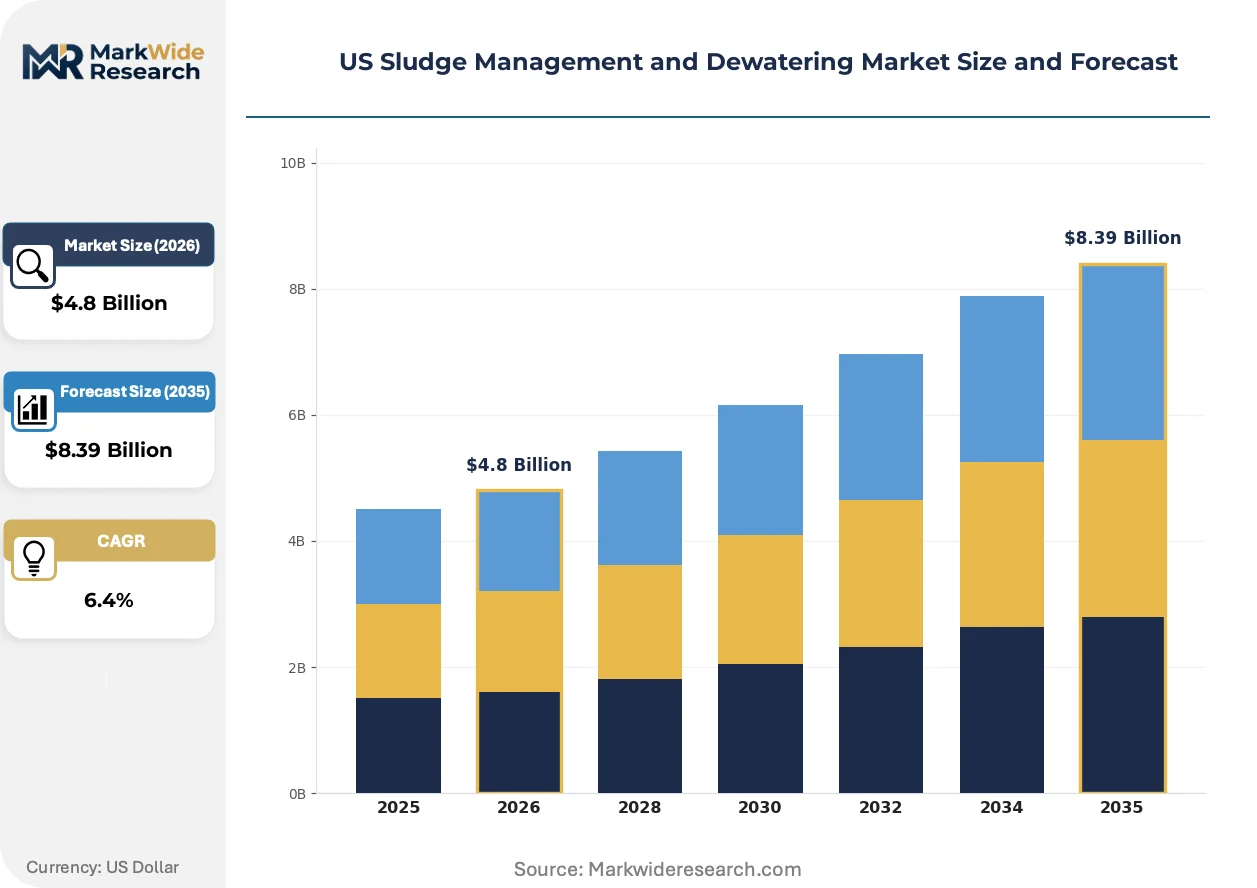
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mechanical Dewatering, Thermal Dewatering, Chemical Dewatering, Centrifugation End User: Municipal Wastewater Treatment, Industrial Wastewater Treatment, Agricultural Sector, Pulp & Paper Industry Service Type: Contracting Services, Equipment Rental, Consulting Services, Maintenance Services Application: Landfill Cover, Fertilizer Production, Biogas Production, Construction Material |
| Companies Covered | Clean Harbors, Inc., Recology, Waste Management, Inc., Montrose Environmental Group, Inc., Waste Pro USA, Republic Services, Inc., Casella Waste Systems, Inc., SNF Group, Waste Connections, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Sludge Management and Dewatering Market Strategic Shifts & Innovations
Mechanical dewatering technology is fragmenting into modular, service-embedded configurations. Equipment vendors are bundling remote monitoring and chemical supply into long-term contracts, compressing traditional capital sales cycles.
Containerized centrifuge systems are decentralizing sludge processing capacity across the US municipal sector. Small utilities in Colorado and Arizona are deploying skid-mounted units to avoid fixed infrastructure investments. This shift is decentralizing equipment ownership toward rental and service-based models.
EPA's emerging PFAS screening protocols for biosolids land application are tightening analytical requirements. Utilities in Michigan and Ohio face expanded testing burdens for perfluorinated compounds. Thermal destruction pathways are gaining evaluation as land application routes narrow.
Municipal procurement patterns are fragmenting equipment and service sourcing. Texas utilities are unbundling chemical supply from equipment maintenance, creating separate vendor relationships. This behavior is most pronounced in cities with strained operating budgets and limited capital reserves.
US Sludge Management and Dewatering Market Segmentation
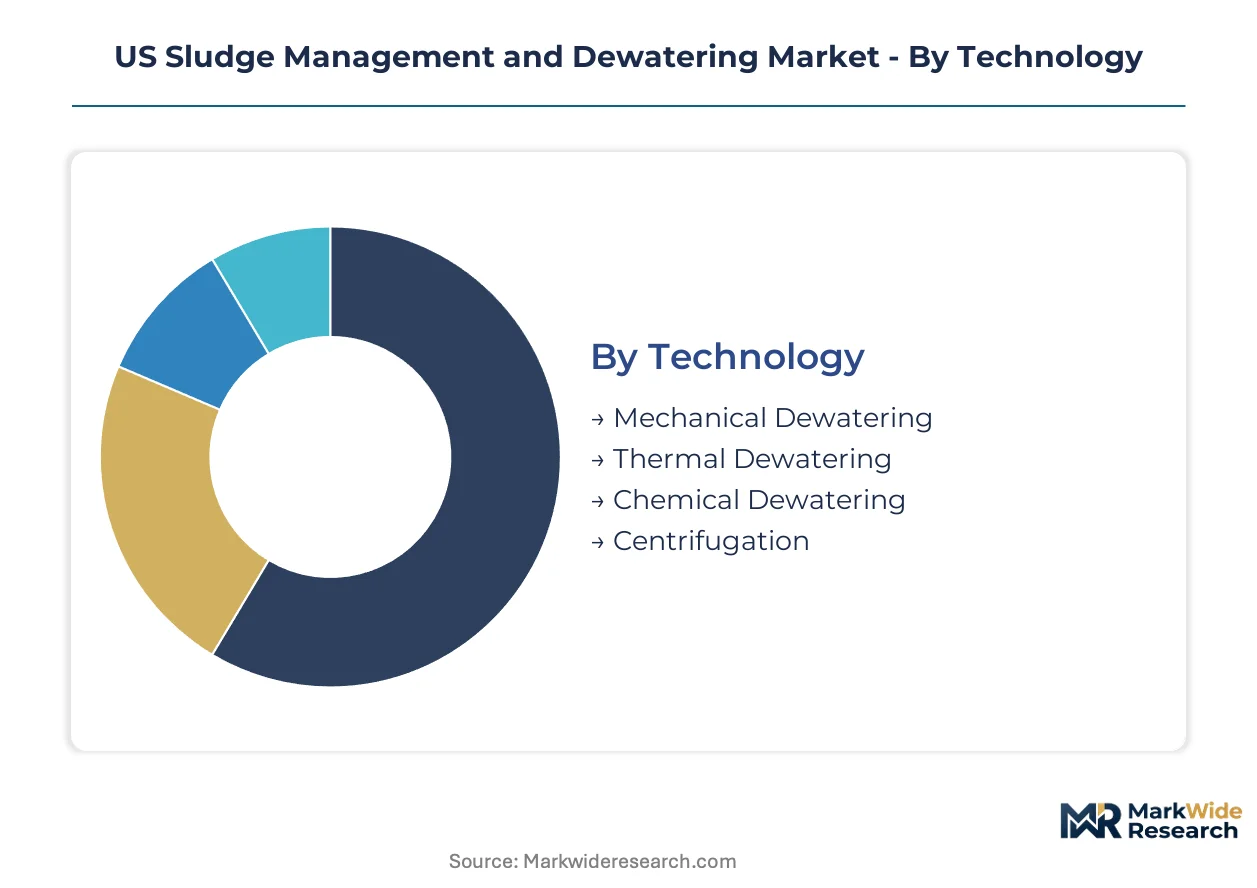
Technology selection in US sludge management reflects divergent capital availability and regulatory timelines across utility districts. End-user concentration and service model preferences further fragment procurement patterns, with implications for equipment vendor positioning and contract structuring.
Technology:
Standardized mechanical platforms dominate municipal procurement, while thermal systems command customization for energy integration projects.
- Mechanical Dewatering:Belt presses and filter presses reduce sludge volume through physical pressure and porous media separation. Demand concentrates in Texas and California utilities facing state landfill moisture limits, with EPA 40 CFR Part 503 compliance driving centrifuge-to-belt press conversions in the Great Lakes region.
- Thermal Dewatering:Heat-based moisture removal achieves higher solids content than mechanical alternatives, often coupling with anaerobic digesters for biogas capture. California utilities lead deployment where energy recovery mandates intersect with carbon reduction targets, though capital intensity restricts adoption to large treatment plants.
- Chemical Dewatering:Polymer-assisted flocculation conditions sludge for downstream dewatering equipment. Municipal buyers in the Southeast favor this approach for retrofit compatibility with legacy infrastructure.
- Centrifugation:High-speed rotational separation delivers continuous operation with minimal footprint. Industrial end-users in the pulp and paper sector specify these units for high-throughput fiber recovery applications.
Leading the category by volume: Mechanical Dewatering. Growing fastest: Thermal Dewatering.
End User:
Customer scale and capital access determine whether procurement favors permanent equipment or contracted services.
- Municipal Wastewater Treatment:Publicly owned treatment works process residential and commercial effluent across EPA-regulated systems. Belt press upgrades dominate capital planning in Ohio and Michigan as biosolids land application rules tighten.
- Industrial Wastewater Treatment:Manufacturing facilities generate sludge with elevated heavy metals and chemical contaminants. Clean Harbors and specialized hazardous waste operators capture this segment through service contracts rather than equipment sales.
- Agricultural Sector:Food processing and livestock operations produce organic residuals suitable for composting or anaerobic digestion. Midwest dairy cooperatives drive demand for mobile dewatering units.
- Pulp & Paper Industry:Fiber-rich sludge requires specialized handling for recovery or disposal. Pacific Northwest mills specify high-solids centrifuges to meet Washington state landfill restrictions.
Dominant by revenue: Municipal Wastewater Treatment. Expanding most quickly: Industrial Wastewater Treatment.
Service Type:
Ownership economics and operational expertise gaps push utilities toward rental and contracted models over capital purchases.
- Contracting Services:Full-service sludge management including hauling, treatment, and disposal. Waste Management leverages its national landfill network to anchor multi-year municipal contracts.
- Equipment Rental:Trailer-mounted centrifuge and belt press units deployed without permanent installation. Small Arizona and Colorado utilities adopt this model to bypass capital budget constraints.
- Consulting Services:Process optimization, regulatory compliance planning, and technology selection support. Demand rises in Florida and Georgia where dewatering automation lags national benchmarks.
- Maintenance Services:Preventive and corrective support for installed dewatering equipment. Certified technician scarcity in rural districts concentrates this demand around regional service hubs.
Leading by contract value: Contracting Services. Climbing the fastest: Equipment Rental.
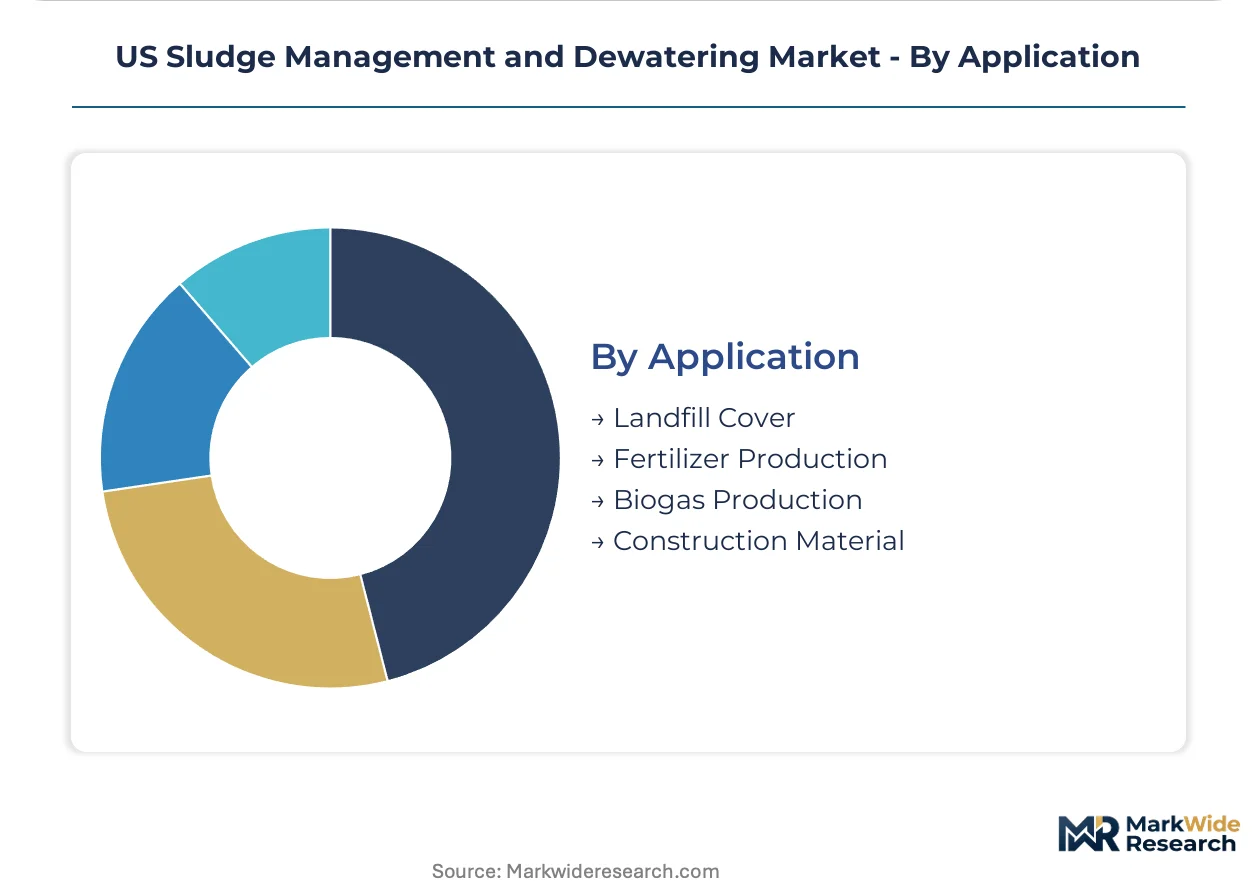
Application:
Regulatory acceptance and contamination screening determine viable end-use pathways for processed biosolids.
- Landfill Cover:Dewatered sludge substitutes for soil in daily landfill cover operations. Texas moisture content rules restrict this pathway unless solids exceed twenty percent.
- Fertilizer Production:Class A biosolids enter commercial nutrient products for agricultural distribution. EPA pathogen standards under 40 CFR Part 503 gate this application.
- Biogas Production:Anaerobic digestion of organic solids yields methane for energy recovery. California utilities integrate thermal dewatering pre-treatment to boost biogas yields.
- Construction Material:Processed sludge substitutes for aggregate in non-structural applications. Emerging evaluation in Ohio and Michigan as land application routes narrow.
Highest volume destination: Landfill Cover. Steepest expansion trajectory: Biogas Production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in coastal states and Great Lakes utilities where landfill restrictions and EPA enforcement intersect. Regional procurement patterns diverge sharply between capital-rich districts favoring permanent equipment and budget-constrained municipalities adopting rental models.
Texas
State-level moisture content rules for landfill disposal are compelling utilities from Houston to Dallas-Fort Worth toward higher-solids dewatering investments. The Texas Commission on Environmental Quality enforces disposal site restrictions that filter vendor access. The Permian Basin oilfield corridor generates industrial sludge volumes processed through mobile service contracts rather than fixed infrastructure.
California
Energy recovery mandates and carbon reduction targets are driving thermal dewatering deployment at large treatment plants in Los Angeles and San Francisco Bay Area metros. The State Water Resources Control Board imposes additional heavy metals testing beyond federal baselines. Central Valley agricultural processors are piloting struvite precipitation systems ahead of anticipated phosphorus recovery regulations.
Ohio
Great Lakes utilities face compressed EPA biosolids compliance timelines for pathogen reduction upgrades. The Ohio Environmental Protection Agency coordinates with federal 40 CFR Part 503 enforcement actions. Cleveland-Akron industrial clusters are evaluating thermal destruction pathways as land application routes narrow under emerging PFAS screening protocols.
Florida
Southeast municipal expansion lags national automation benchmarks, creating retrofit demand for smart polymer dosing systems. The Florida Department of Environmental Protection administers nutrient management rules affecting coastal discharge permits. Tampa-Orlando utility districts are unbundling chemical supply from equipment maintenance under strained operating budgets.
Arizona
Water scarcity pressures are accelerating adoption of skid-mounted centrifuge units to avoid fixed capital commitments. The Arizona Department of Environmental Quality permits reuse applications for processed biosolids in arid-region agriculture. Phoenix-Tucson corridor utilities are deploying containerized systems to decentralize processing capacity across dispersed treatment networks.
US Sludge Management and Dewatering Market Key Industry Players
Integrated service contracting dominates the current landscape as equipment vendors bundle remote monitoring and chemical supply into long-term agreements. The vendor base fragments across three tiers: national waste operators with landfill anchoring power, regional specialists in hazardous streams, and equipment fabricators pursuing rental penetration. Two strategic archetypes predominate: operators leveraging disposal infrastructure to capture municipal volumes, and technology providers pivoting from capital sales to subscription-based service models. M&A activity and geographic expansion through mobile service fleets represent the principal competitive vectors reshaping market structure.
Within the national operator tier, Waste Management, Inc. and Republic Services, Inc. exemplify landfill-anchored competitive positioning. Clean Harbors, Inc. occupies a specialized position serving industrial and hazardous sludge streams where treatment complexity sustains premium service margins. These three companies represent divergent strategic pathways: scale-driven national contracting, regional density concentration, and technical specialization in regulated waste categories.
| Leading Market Players |
|---|
| Clean Harbors, Inc. |
| Recology |
| Waste Management, Inc. |
| Montrose Environmental Group, Inc. |
| Waste Pro USA |
| Republic Services, Inc. |
| Casella Waste Systems, Inc. |
| SNF Group |
| Waste Connections, Inc. |
| Others |
Cost & Logistics Intelligence
Municipal procurement unbundling in Texas and Florida is forcing equipment vendors to separate chemical supply contracts from hardware sales, compressing margins on standalone machinery while elevating service-bundle premiums. This buyer-driven fragmentation reshapes supplier economics toward recurring revenue streams and away from capital-intensive unit transactions.
Pricing Analysis
Volume-driven municipal contracts trade at thin single-digit margins while hazardous industrial service bundles command premium pricing. Three-tier pricing structure across integrated service, equipment-only, and rental models reflects divergent buyer sophistication and capital access. Cost compression in standard mechanical dewatering intensifies as Midwest fabricators compete for Great Lakes replacement cycles. Small utilities in Arizona and Colorado exhibit highest price sensitivity due to constrained operating budgets, whereas California energy-recovery projects show lowest sensitivity given mandate-driven procurement.
Supply Chain Analysis
Polymer supply rests on petrochemical feedstock networks concentrated in Texas and Louisiana, with acrylamide monomer production anchoring in Gulf Coast industrial corridors. Centrifuge fabrication draws from Midwest machining clusters, while thermal system components source from specialized boiler and heat-exchanger manufacturers in Ohio and Pennsylvania. Single-source vulnerability concentrates in precision rotating assembly production for high-speed centrifuge bowls. Distribution runs through regional service hubs maintaining certified technician pools for preventive maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US sludge management sector is becoming a vertical-integration race as national operators acquire mobile service fleets and polymer supply channels to capture municipal volumes. Control over landfill disposal anchors and hazardous treatment permits represents the decisive downstream lever.
For Market Incumbents: Acquire trailer-mounted centrifuge fleets and certified technician networks to defend against regional rental specialists penetrating small-utility markets. Secure exclusive polymer supply agreements with municipal buyers in Texas and California before unbundling accelerates. Anchor multi-year service contracts through landfill disposal volume guarantees. For New Entrants and Emerging Players: Equipment rental partnerships with regional waste haulers offer the fastest path to revenue without capital-intensive manufacturing investments. Target Florida and Georgia utilities lagging in automation retrofit cycles. Lead with smart polymer dosing systems that integrate with legacy SCADA infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with specialized hazardous sludge operators given EPA's emerging PFAS screening mandates and thermal destruction pathway expansion. Long-term viability favors service-based models over capital equipment fabrication. Watch state-level biosolids land application restrictions as the inflection signal for thermal technology valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Service Fleet Expansion | Trailer-mounted centrifuge deployment captures small-utility volumes in Colorado and Arizona without fixed infrastructure commitment. |
| Polymer Supply Integration | Backward integration into acrylamide-based flocculant production secures margin capture and municipal contract stickiness. |
| Thermal Technology Licensing | Anaerobic digester coupling expertise transfers to California utilities facing energy recovery mandates and carbon targets. |
| Hazardous Waste Permit Acquisition | Industrial sludge treatment authorization in Texas and Ohio creates defensive moats against commoditized municipal competition. |
| Remote Monitoring Platform Launch | Predictive maintenance algorithms reduce centrifuge downtime for Great Lakes utilities under compressed EPA compliance timelines. |
Research Approach
EPA enforcement records, state environmental agency permit databases, and municipal utility capital improvement plans formed the secondary backbone for regulatory timeline and procurement pattern analysis. Primary interviews with wastewater treatment plant operators, centrifuge maintenance technicians, polymer supply distributors, and landfill disposal coordinators validated equipment deployment trends and service contract structures. Bottom-up installation counts and top-down waste volume flows were triangulated to anchor market sizing.
Historical capital expenditure patterns across Texas, California, and Great Lakes utilities established baseline replacement cycle assumptions over the projection horizon. Segmentation modeling incorporated technology type, end-user scale tier, service model preference, and regional regulatory stringency dimensions. CAGRs were derived from equipment shipment tracking and contracted service revenue disclosures, with biogas facility integration rates and PFAS screening protocol adoption serving as industry-specific forecast modifiers.
Several conditions sit outside the modeled scope, including potential federal biosolids classification changes, breakthrough dewatering technology commercialization, and municipal bankruptcy restructuring effects. Forecasts reflect documented assumptions about regulatory enforcement continuity and petrochemical feedstock price stability. A small set of named triggers warrants ongoing watch: EPA Part 503 revision timing, state-level PFAS maximum contaminant level establishment, and polymer cost volatility indices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Enzymes for Water Treatment Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
India Water and Wastewater Treatment (WWT) Technology Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Asia-Pacific Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Global Sodium Hypochlorite Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Nanotechnology in Water Treatment Market
Water & Sludge Treatment
Water and Wastewater Treatment Technologies Market
Water & Sludge Treatment
Flocculants Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
Water Purification Systems Market
Water & Sludge Treatment
Ultrapure Water Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Asia-Pacific Water Treatment Chemicals Market