
 Europe Boiler Water Treatment Chemicals Market | 2026-2036
Europe Boiler Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Boiler Water Treatment Chemicals Market Foresight
Phosphate-free formulation tiers is unwinding legacy product positions across the European supplier base. BASF SE leverages its Ludwigshafen integrated chemical complex to sustain captive production of polymer-based scale inhibitors. Kemira anchors Nordic utility contracts through specialized dispersant chemistry adapted to low-temperature boiler operations. Veolia Water Technologies competes on service bundling, combining chemical supply with remote monitoring across French industrial zones.
Boiler water treatment chemicals comprise formulated blends of corrosion inhibitors, scale inhibitors, pH adjusters, and biocides dosed into steam-generating systems to prevent metal degradation, mineral deposition, and microbial fouling; typical active concentrations range from 5 to 200 ppm depending on operating pressure and feedwater hardness. The primary purpose is extending boiler lifespan and maintaining thermal efficiency in continuous-duty industrial steam plants. Corrosion inhibitors occupy the largest product category share due to mandatory protection requirements in high-pressure power generation boilers across the region. Biocides represent the fastest-expanding segment as food processing and pharmaceutical end users tighten microbial control protocols under EU hygiene frameworks. Manufacturing applications command substantial volume flows, though margin pools concentrate in chemical processing where customized treatment programs command technical service premiums.
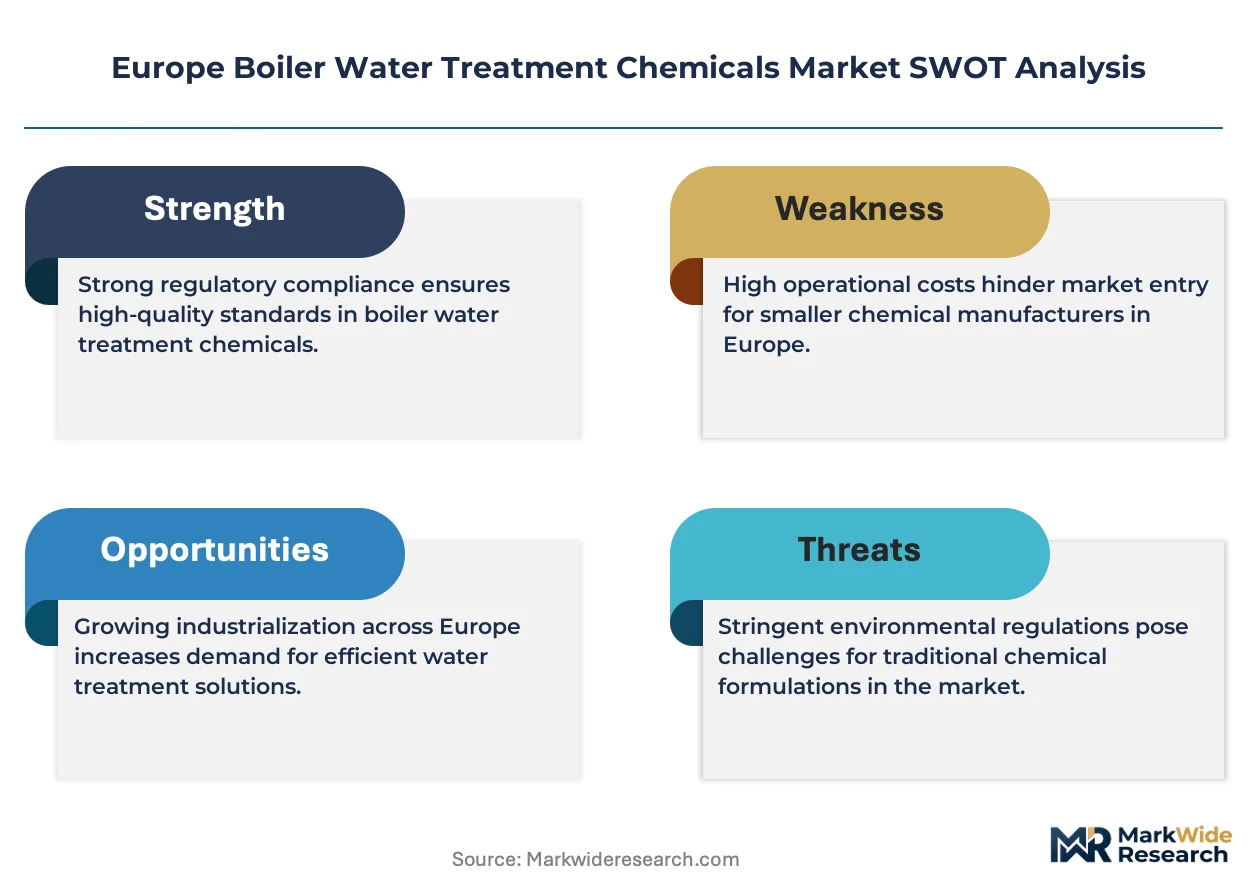
REACH registration obligations and the EU F-Gas Regulation are tightening permissible chemistries, pushing formulators toward bio-based and low-toxicity alternatives that meet ECHA hazard classification thresholds. CE marking requirements for water treatment equipment create compliance gateways that favor suppliers with documented substance safety portfolios. Germany's Federal Environment Agency enforces stricter discharge limits than EU minimums, creating regional product differentiation pressures. Stakeholders must monitor pending revisions to the EU Industrial Emissions Directive and assess how tightened boiler blowdown standards reshape chemical consumption intensity across member states.
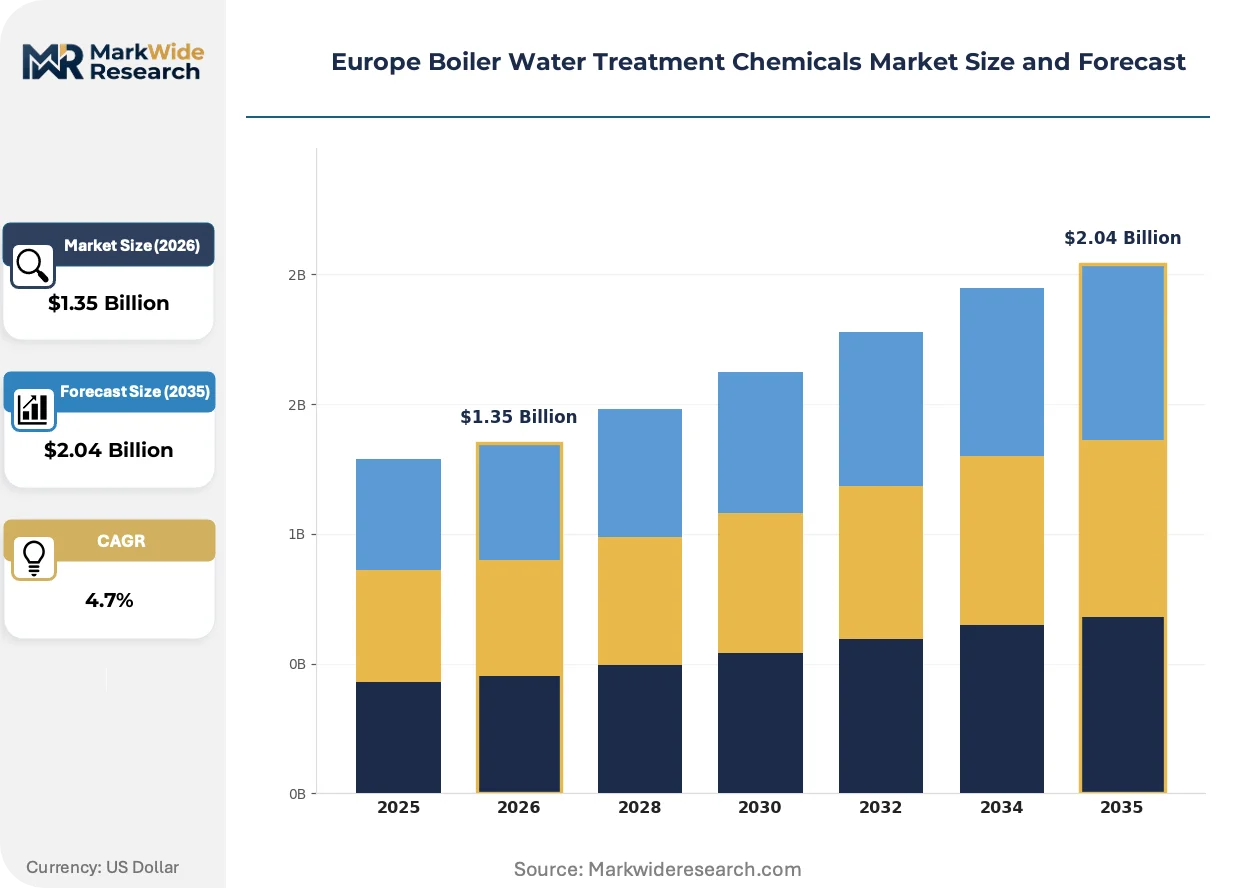
Market Dynamics
REACH registration deadlines and the EU Green Deal are forcing formulators to rebuild product portfolios around biodegradable actives, compressing legacy phosphate-based positions while opening margin pools for polymer-based alternatives.
Growth Catalysts
- EU Industrial Emissions Directive:Tightened boiler blowdown standards across member states are expanding chemical treatment intensity in power generation facilities.
- Food processing hygiene mandates:EFSA-guided microbial control protocols are accelerating biocide adoption in steam-dependent food manufacturing corridors.
- Benelux chemical cluster concentration:Integrated refining and petrochemical complexes in Antwerp-Rotterdam are driving demand for customized high-pressure boiler programs.
Market Restraints
- Ethylene oxide feedstock volatility:Key raw material for non-ionic surfactants faces price swings tied to European naphtha cracking economics.
- German supply concentration:Captive production at Ludwigshafen and Leverkusen complexes limits third-party formulator access to polymer intermediates.
- REACH data-sharing obligations:Registration costs for novel bio-based corrosion inhibitors create barriers for mid-tier specialty chemical entrants.
Strategic Opportunities
- Eastern European industrial zones:Polish and Romanian manufacturing expansion lags Western chemical treatment penetration rates by 15-20 percentage points.
- Remote monitoring convergence:IoT sensor networks paired with predictive dosing algorithms enable service-bundling models beyond commodity chemical supply.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases create openings for non-fluorinated scale inhibitor chemistries in high-pressure systems.
Industry Challenges
- Formulation chemist scarcity:Expertise in polymer scale inhibitor synthesis and boiler system metallurgy concentrates at aging specialist workforces in Germany and France.
- CE marking timeline compression:Water treatment equipment certification under the Pressure Equipment Directive demands 12-18 month validation cycles that delay program rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Boiler Water Treatment Chemicals Market |
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.04 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrosion Inhibitors, Scale Inhibitors, pH Adjusters, Biocides Application: Power Generation, Manufacturing, Food Processing, Chemical Processing End User: Utilities, Industrial Plants, Hospitals, Commercial Buildings Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Ecolab, BASF SE, Suez, Kemira, Kurita Water Industries Ltd., Solenis, Veolia Water Technologies, Buckman, Arkema, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Boiler Water Treatment Chemicals Market Shifts & Advancements
Formulation chemistry is pivoting toward bio-derived actives as regulatory hazard classifications harden, while digital service layers are unbundling traditional chemical supply relationships across European industrial zones.
Polymer-based threshold inhibitors, specifically polymaleic and polyacrylic acid derivatives, are supplanting traditional phosphonate chemistries in high-hardness feedwater applications. Food processors and pharmaceutical manufacturers in the Netherlands and Denmark are adopting these actives fastest to preempt REACH authorization hurdles. The shift is compressing legacy phosphonate margins while rewarding suppliers with captive polymer production capabilities.
REACH's 2026 registration deadline for existing substances is forcing portfolio rationalization across formulators serving the European market. Substances failing hazard classification thresholds face sunset clauses that eliminate commercial use in boiler applications. Power generation utilities in Germany and France are accelerating qualification programs for replacement chemistries to avoid supply discontinuity.
Performance-based service contracts are displacing volume-based chemical supply agreements in large industrial accounts. French and Belgian chemical processors now specify steam system efficiency guarantees rather than tonnage commitments, transferring operational risk to treatment providers. This model concentrates margin with integrated service-chemical suppliers capable of remote monitoring infrastructure deployment.
Europe Boiler Water Treatment Chemicals Market Segmentation
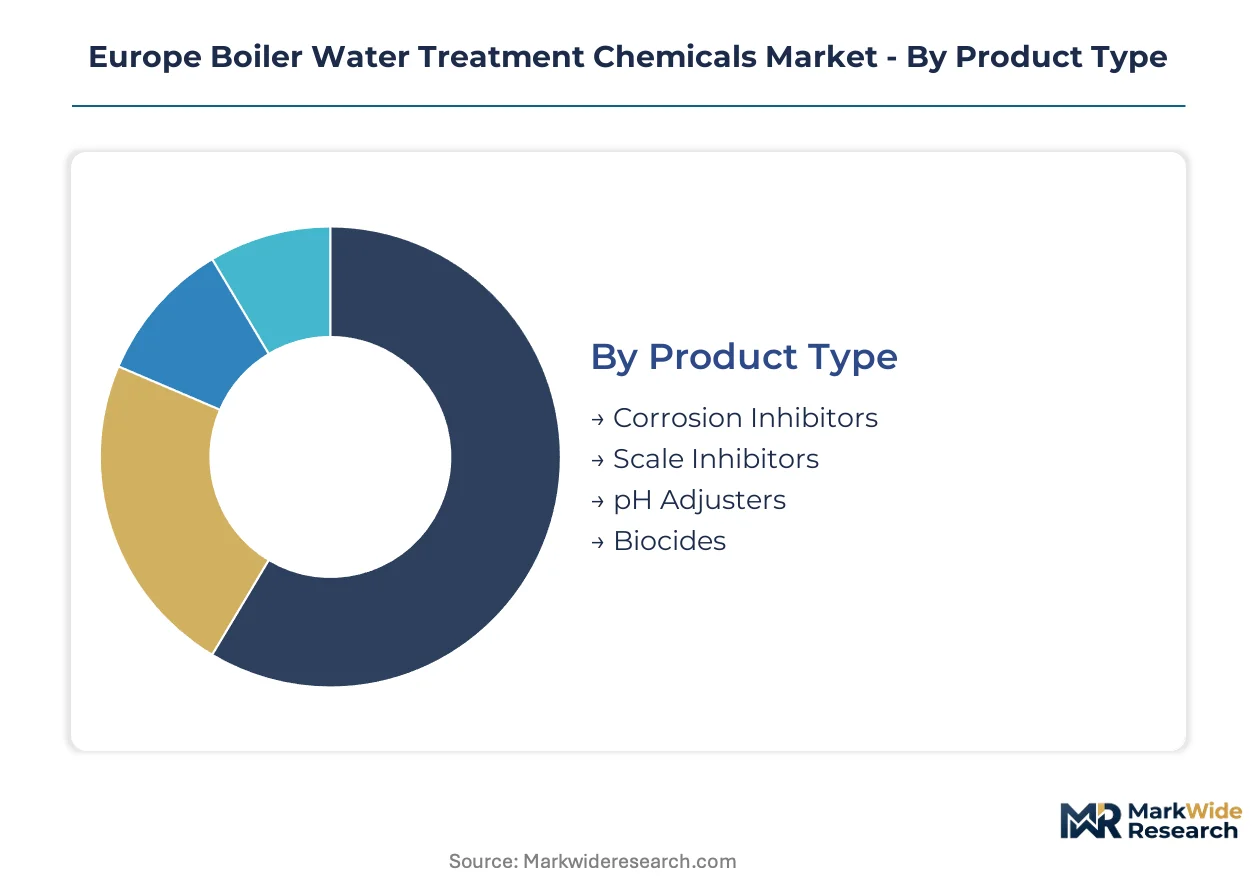
Segmentation in Europe's boiler water treatment chemicals market reveals how regulatory pressure and operational requirements fragment demand across distinct technical specifications. Each category carries different substitution risks and margin profiles that shape supplier positioning strategies.
Product Type:
REACH authorization deadlines and the EU Green Deal are forcing substitution across product tiers, with phosphate-based formulations facing the steepest displacement pressure.
- Corrosion Inhibitors:Formulated blends of organic amines, molybdates, and film-forming polymers protect boiler metallurgy from oxygen pitting and acidic attack. German power utilities and French nuclear facilities drive specification intensity here, with ECHA hazard classifications accelerating shifts from chromate-based legacy chemistries toward polymer alternatives.
- Scale Inhibitors:Phosphonates, polymaleic acids, and polyacrylic derivatives interrupt crystal nucleation in high-hardness feedwater. Benelux chemical processors and Antwerp-Rotterdam refining clusters anchor demand for high-performance polymer variants that withstand thermal degradation in supercritical boilers.
- pH Adjusters:Caustic soda, ammonia, and neutralizing amines maintain alkaline conditions to prevent acidic corrosion.
- Biocides:Oxidizing and non-oxidizing microbicides control microbial fouling in low-flow boiler sections.
Corrosion inhibitors retain volume leadership; biocides hold the steepest expansion curve.
Application:
Margin concentration varies sharply by application, with chemical processing commanding technical service premiums while manufacturing delivers scale volume.
- Power Generation:High-pressure utility boilers require continuous dosing of multi-component treatment programs to prevent turbine fouling and heat exchanger failure. German coal-to-gas conversion projects and French nuclear maintenance cycles are expanding chemical intensity as operators tighten blowdown standards under the EU Industrial Emissions Directive.
- Manufacturing:General industrial steam systems in metal fabrication, textiles, and paper production apply standardized treatment protocols. Polish and Romanian manufacturing corridors are expanding penetration as industrial zone development outpaces legacy water treatment infrastructure.
- Food Processing:Steam-contact applications demand food-grade chemistries compliant with EFSA hygiene frameworks.
- Chemical Processing:Petrochemical and specialty chemical plants require customized programs for high-purity steam and complex wastewater discharge constraints.
Power generation anchors absolute volume; chemical processing captures the widest margin spreads.
End User:
Procurement sophistication divides end users sharply, with utilities and industrial plants driving technical specification while smaller facilities prioritize cost containment.
- Utilities:Centralized power and district heating operators specify long-term service contracts with performance guarantees. Nordic municipal utilities and German municipal energy companies are adopting remote monitoring platforms that bundle chemical supply with predictive maintenance.
- Industrial Plants:Discrete manufacturing and process industry facilities balance treatment cost against downtime risk. French automotive suppliers and Italian textile producers concentrate demand for mid-tier formulations with documented REACH compliance.
- Hospitals:Healthcare steam systems for sterilization require validated microbial control with minimal operator intervention.
- Commercial Buildings:District heating and hospitality applications favor simplified dosing systems with reduced technical support requirements.
Utilities dominate contract value; industrial plants provide the broadest account base.
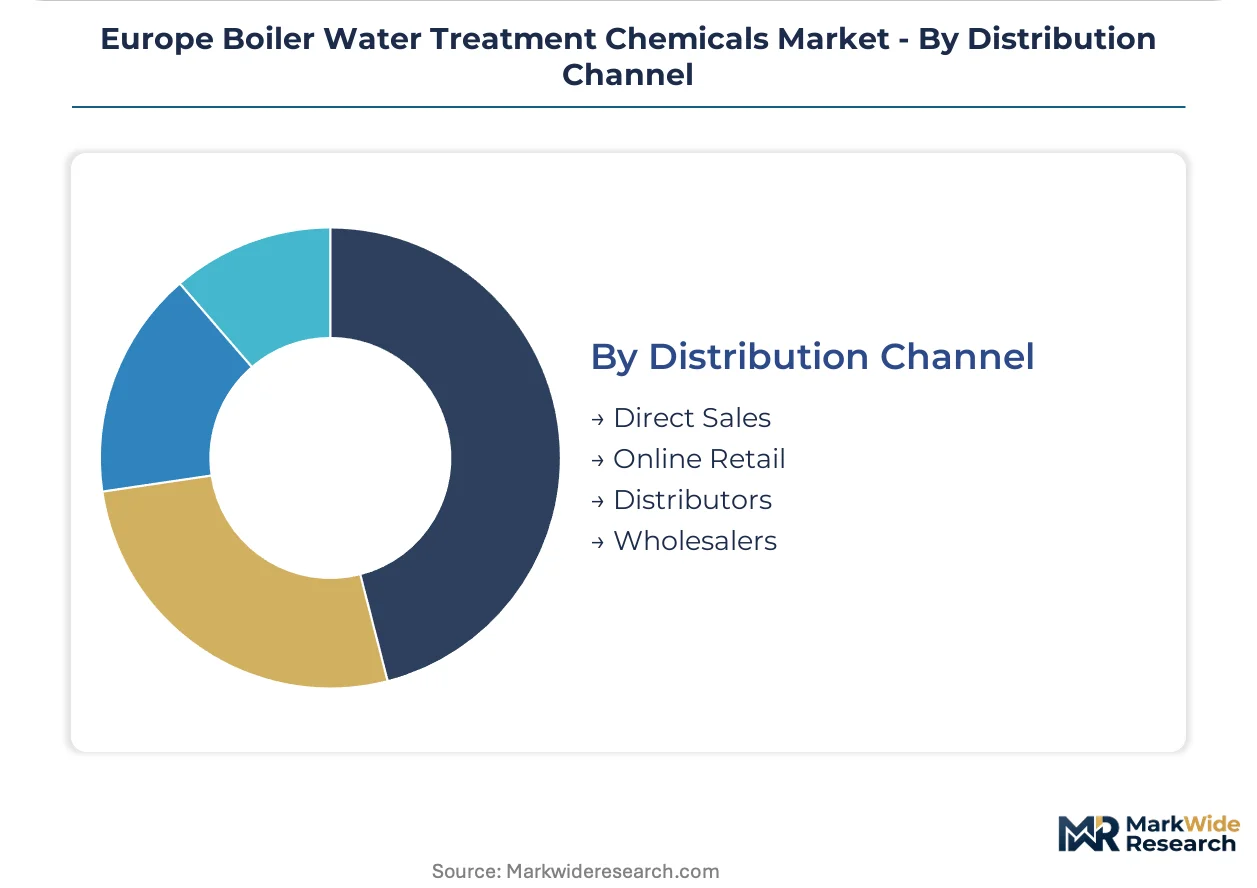
Distribution Channel:
Channel selection reflects customer scale and technical support requirements, with direct relationships consolidating among large accounts and intermediaries serving fragmented demand.
- Direct Sales:Integrated chemical suppliers deploy technical service teams for large utility and chemical processing accounts. BASF and Kemira maintain dedicated field organizations across German manufacturing corridors and Benelux industrial zones to manage complex treatment program implementation.
- Distributors:Regional chemical distributors stock standard formulations for manufacturing and commercial accounts. French and Italian distribution networks concentrate coverage of mid-sized industrial boilers with limited in-house water treatment expertise.
- Online Retail:E-procurement platforms serve small commercial and institutional buyers with standardized product grades.
- Wholesalers:Bulk chemical handlers supply commodity caustic and acid products to large volume consumers.
Direct sales capture the highest margin concentration; distributors provide the widest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical production clusters in Germany and Benelux anchor supply-side capacity for boiler water treatment formulations across Europe, with polymer intermediates and corrosion inhibitor actives flowing from Ludwigshafen and Antwerp-Rotterdam complexes to downstream formulators.
Germany
Coal-to-gas conversion projects in North Rhine-Westphalia and nuclear maintenance cycles drive chemical treatment intensity in utility boilers. The Federal Environment Agency enforces stricter discharge limits than EU minimums, forcing product differentiation. BASF's Ludwigshafen complex supplies captive polymer-based scale inhibitors to regional power generators.
France
Nuclear fleet maintenance and industrial emissions compliance expand multi-component treatment programs in high-pressure steam systems. The EU Industrial Emissions Directive shapes blowdown standard tightening. Veolia Water Technologies bundles chemical supply with remote monitoring across chemical processing zones in Lyon and the Paris Basin.
Netherlands
Food-grade polymer adoption accelerates among Dutch and Danish food processors preempting REACH authorization hurdles. EFSA-guided hygiene frameworks mandate microbial control protocols. Rotterdam-Antwerp refining clusters anchor demand for customized high-pressure boiler programs with thermal degradation resistance.
Poland
Manufacturing corridor expansion outpaces legacy water treatment infrastructure penetration by 15-20 percentage points. EU cohesion funding supports industrial zone development. Silesian and Łódź manufacturing belts drive standardized treatment protocol adoption in metal fabrication and textile steam systems.
Belgium
Integrated petrochemical complexes in the Antwerp port zone require specialized high-purity steam programs with complex wastewater constraints. REACH registration obligations filter supplier access. Flemish chemical processors specify performance-based service contracts transferring operational risk to treatment providers.
Europe Boiler Water Treatment Chemicals Market Competitive Landscape
Concentration sits with integrated chemical majors possessing captive polymer production and dedicated field service organizations. The supplier base stratifies into three tiers: multinational chemical conglomerates with full formulation portfolios, regional specialists with niche application expertise, and commodity distributors serving fragmented commercial accounts. Dominant competitive moves include backward integration into polymer intermediate production and service bundling combining chemical supply with IoT-enabled remote monitoring platforms.
Among integrated chemical suppliers, BASF SE and Kemira exemplify archetypes with captive manufacturing capabilities and technical service depth. Veolia Water Technologies occupies a position emphasizing service convergence over commodity chemical volume. Ecolab represents the service-led model with performance-based contracting structures. These three anchors illustrate how competitive positioning diverges between production-integrated and service-differentiated strategies.
| Leading Market Players |
|---|
| Ecolab |
| BASF SE |
| Suez |
| Kemira |
| Kurita Water Industries Ltd. |
| Solenis |
| Veolia Water Technologies |
| Buckman |
| Arkema |
| Others |
Supply & Pricing Matrix
Long-term service contracts with performance guarantees lock in both polymer intermediate supply access and price visibility for German utilities and Benelux chemical processors navigating REACH registration deadlines. These arrangements transfer operational risk to treatment providers while insulating buyers from ethylene oxide feedstock volatility.
Pricing Analysis
REACH authorization thresholds dictate the pricing tier structure across corrosion inhibitor and scale inhibitor categories. Three-tier pricing structure across premium, standard, and economy levels separates food-grade polymer formulations from industrial-grade phosphonates and commodity caustic products. Cost compression in legacy phosphate-based tiers is intensifying because ECHA sunset clauses eliminate commercial use pathways. Manufacturing accounts in Poland and Romania exhibit highest price sensitivity; French nuclear utilities and Belgian petrochemical complexes demonstrate lowest sensitivity due to downtime risk premiums.
Supply Chain Analysis
Inventory buffers for polymer intermediates stretch to 8-12 weeks given batch synthesis constraints at Ludwigshafen and Leverkusen complexes. Supply concentrates in Germany, Belgium, and the Netherlands for formulated blends; ethylene oxide and non-ionic surfactant precursors draw from Antwerp-Rotterdam cracking economics. Single-source vulnerability sits with captive polymer production at BASF's Ludwigshafen site. Distribution runs through direct technical service teams for large utilities and regional chemical distributors for fragmented manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe boiler water treatment chemicals market tracks a cyclical recovery pattern as coal-to-gas conversion projects and nuclear maintenance cycles drive replacement demand across German and French utility fleets.
For Market Incumbents: Shield polymer-based formulation margins by accelerating backward integration into polymaleic acid intermediate production before REACH registration deadlines sunset legacy phosphonate positions. Capture channel control through IoT-enabled remote monitoring deployments that lock in multi-year service contracts with Nordic municipal utilities. For New Entrants and Emerging Players: Remote monitoring capability gaps in Eastern European manufacturing corridors offer white-space entry points where incumbent technical service coverage remains thin. Polish and Romanian metal fabrication clusters represent the most penetrable geography; partner with regional distributors to bundle standardized treatment protocols with simplified dosing equipment. For Investors and Strategic Acquirers: Regional specialists with niche food-grade certification portfolios and established EFSA compliance documentation present acquisition targets with defensive moats against REACH authorization volatility. Monitor ECHA substance evaluation timelines as the critical inflection signal for portfolio rationalization waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Intermediates | Captive production of polymaleic acids insulates BASF and Kemira from ethylene oxide volatility. |
| Remote Monitoring Platform Deployment | Veolia's IoT sensor networks bundle chemical supply with predictive dosing algorithms across French industrial zones. |
| Food-Grade Certification Investment | EFSA compliance documentation opens premium positioning for Dutch and Danish food processing accounts. |
| Eastern European Distribution Partnership | Regional distributors in Poland and Romania bridge coverage gaps for standardized manufacturing formulations. |
| REACH-Compliant Formulation Development | Bio-based corrosion inhibitors preempt ECHA sunset clauses for German power generation utilities. |
Research Methodology
Initial hypotheses were tested against primary input from utility procurement managers, chemical processing plant engineers, water treatment technical directors, and regional distribution channel partners and refined through secondary validation against customs trade data, Cefic industry reports, ECHA substance registration databases, and SEC filings of listed chemical suppliers. Bottom-up volume estimates from individual facility treatment intensities were triangulated against top-down market sizing from production capacity and consumption coefficients.
Variance decomposition across product type, application sector, end-user procurement sophistication, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from slope-intercept modeling of historical consumption patterns adjusted for coal-to-gas conversion timelines and REACH registration phase-out schedules. Forecast inputs incorporated boiler blowdown standard tightening under the EU Industrial Emissions Directive and polymer substitution elasticity coefficients.
Forecasts assume regulatory continuity in REACH authorization processes and EU F-Gas Regulation phase-down schedules; material policy shifts would require re-modeling of substitution timelines and chemistry migration patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Slurry Heaters Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Water Free/ Waterless Urinals Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
India Cooling Water Treatment Chemicals Market
Water & Sludge Treatment
Deionized Water Systems Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
Alkalinity Control Chemicals Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Water Purification Systems Market
Water & Sludge Treatment
Europe Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
Water Treatment Market