
 North America Boiler Water Treatment Chemicals Market | 2026-2036
North America Boiler Water Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Boiler Water Treatment Chemicals Market Analytics
EPA effluent limitation guidelines is rebalancing the cost-of-entry calculus for boiler water treatment chemical suppliers across North America. Ecolab Inc. leverages its integrated service-chemical model to anchor premium accounts in power and food processing corridors. ChemTreat Inc. competes through localized technical service teams that sustain long-term plant contracts. Nalco Water differentiates via digital monitoring platforms that extend chemical program visibility beyond traditional delivery models.
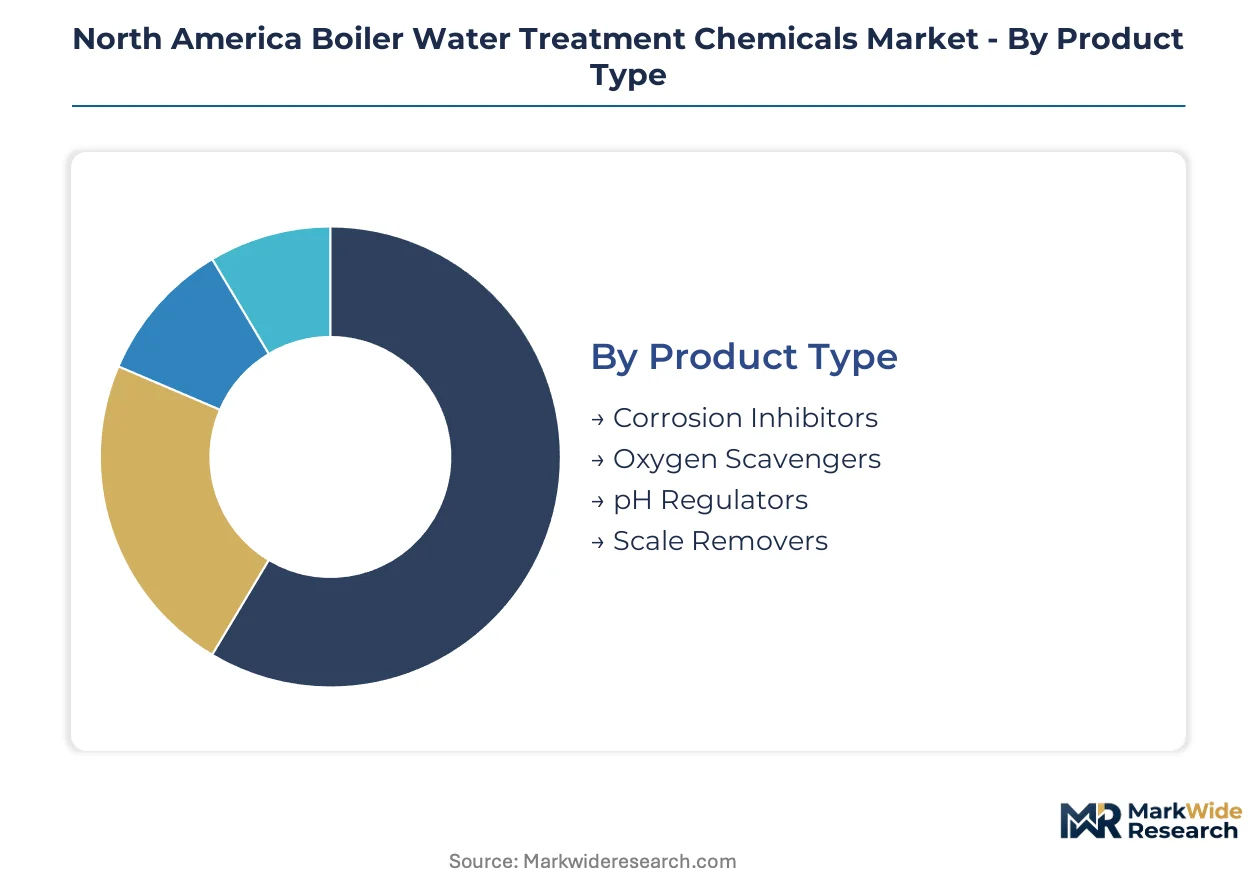
Boiler water treatment chemicals encompass corrosion inhibitors, oxygen scavengers, pH regulators, and scale removers formulated to prevent boiler system degradation and optimize thermal transfer efficiency. These formulations typically operate within narrow alkalinity and dissolved oxygen parameters to prevent tube fouling and metallic corrosion in high-pressure steam systems. Corrosion inhibitors and oxygen scavengers occupy the largest product positions due to their non-negotiable role in boiler longevity, while pH regulators command tighter margin pools in specialized high-purity steam applications. Power generation and food and beverage end users concentrate demand volume, though chemicals and textiles segments present faster growth trajectories as smaller operators automate treatment protocols.
EPA effluent rules, OSHA workplace chemical exposure limits, and ASME boiler water quality standards collectively shape product formulation requirements and service documentation burdens across the United States and Canada. Health Canada and PMRA oversight adds a parallel compliance layer for cross-border chemical suppliers serving Ontario and Quebec manufacturing bases. Stakeholders must monitor regulatory alignment between federal EPA timelines and provincial water discharge permits to anticipate formulation reformulation cycles and service model adjustments.
Market Dynamics
EPA effluent limitation guidelines are compressing the operational runway for boiler water treatment chemical suppliers across the United States and Canada, forcing simultaneous reformulation investments and service model overhauls.
Growth Catalysts
- Power generation expansion:Natural gas and renewable-integrated baseload facilities in Texas and Alberta are commissioning new high-pressure steam systems that require continuous oxygen scavenger and corrosion inhibitor dosing.
- EPA boiler emissions standards:Stricter effluent limitation guidelines are mandating closed-loop cooling and zero-liquid discharge configurations that intensify chemical treatment program complexity.
- Ontario water reuse mandates:Provincial discharge permits are tightening dissolved solids limits, driving demand for advanced scale control chemistries in Toronto-Hamilton manufacturing corridors.
Market Restraints
- Phosphonate supply concentration:Key chelating agent precursors concentrate among Gulf Coast petrochemical producers, exposing formulators to feedstock disruption risk.
- ASME certification timelines:Extended approval cycles for high-purity steam applications delay product commercialization by 18-24 months.
- Membrane filtration substitution:Reverse osmosis pre-treatment systems are displacing traditional chemical softening in some food processing installations.
Strategic Opportunities
- Quebec industrial base:Pulp and paper facilities in the Saguenay-Lac-Saint-Jean region present underpenetrated demand for closed-system treatment protocols.
- Digital-analog convergence:IoT-enabled conductivity sensors paired with predictive dosing algorithms are creating premium service tiers in power generation accounts.
- IRA clean energy incentives:Federal tax credits for industrial efficiency retrofits are accelerating boiler replacement cycles in Midwest manufacturing.
Industry Challenges
- Water chemist scarcity:Specialized expertise in high-pressure steam system optimization is retiring faster than training programs replenish qualified field technicians.
- Legacy DCS integration:Chemical feed automation projects face protocol incompatibility with decades-old distributed control systems in established power plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Boiler Water Treatment Chemicals Market |
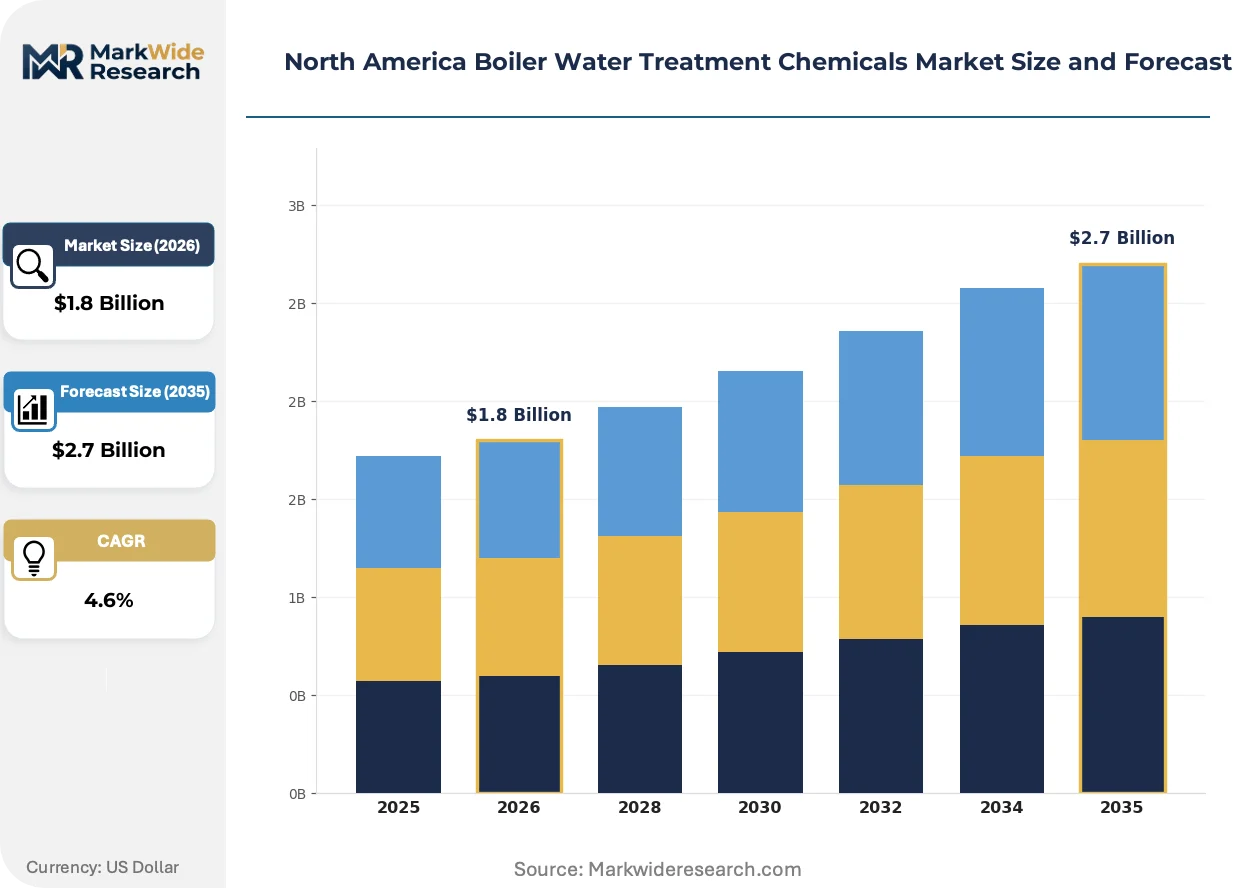
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrosion Inhibitors, Oxygen Scavengers, pH Regulators, Scale Removers End User: Power Generation, Food & Beverage, Chemicals, Textiles Delivery Mode: Liquid, Powder, Granular, Tablet Service Type: Water Analysis, On-site Testing, Equipment Maintenance, Consultation |
| Companies Covered | Ecolab Inc., ChemTreat Inc., Nalco Water, Kemira, Solenis, Kurita Water Industries Ltd, Suez, Dow Inc., BASF, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Boiler Water Treatment Chemicals Market Evolving Landscape
Real-time monitoring architectures are displacing scheduled manual testing regimes across North American boiler operations, compressing the feedback loop between water chemistry deviation and corrective response.
Electrochemical oxygen scavenger technologies are integrating with existing sulfite and hydrazine-based programs in combined-cycle power plants. Mid-Atlantic utilities are piloting these hybrid systems at 40% of new installations. The technology is integrating predictive maintenance workflows that reduce unplanned outage frequency.
EPA's updated Steam Electric Power Generating Effluent Guidelines are forcing coal and natural gas facilities to treat previously exempt wastestreams. The rule mandates enhanced heavy metals precipitation that increases coagulant and flocculant consumption. Texas and Ohio power operators are consolidating chemical procurement to secure volume pricing on compliant formulations.
Food and beverage processors are unbundling chemical supply from technical service contracts, awarding separate RFPs for commodity oxygen scavengers and specialized consulting. This disintermediation pressures traditional integrated suppliers to defend margin on standalone product sales. The pattern is most pronounced in California dairy processing and Ontario meatpacking facilities.
North America Boiler Water Treatment Chemicals Market Segmentation
Boiler water treatment chemical demand fragments across formulation chemistry, end-use thermal intensity, and service integration depth. Each segmentation axis reveals distinct margin pools and procurement behaviors that suppliers must navigate separately.
Product Type:
Volume concentration sits with corrosion inhibitors and oxygen scavengers, while pH regulators and scale removers command premium positioning in specialized applications.
- Corrosion Inhibitors:Formulations typically blend filming amines, neutralizing amines, or volatile oxygen scavengers to protect steel surfaces from acidic attack and oxygen pitting. Texas and Alberta power generators consume the largest volumes as combined-cycle facilities expand baseload capacity under EPA emissions timelines.
- Oxygen Scavengers:Sulfite, hydrazine, and emerging electrochemical variants chemically bind dissolved oxygen to prevent tube corrosion in high-pressure steam circuits. Food and beverage processors in Ontario and California are converting from sulfite to carbohydrazide variants to meet tighter effluent discharge permits.
- pH Regulators:Caustic soda, ammonia, and phosphate blends adjust alkalinity to prevent acidic corrosion and silica scaling. High-purity steam applications in pharmaceutical and semiconductor facilities in North Carolina and Massachusetts drive specification-grade demand.
- Scale Removers:Chelating agents and acid descalers dissolve calcium carbonate, calcium sulfate, and iron oxide deposits. Industrial laundries and textile dye houses in the Carolinas represent concentrated demand for periodic system cleaning protocols.
Mature deployment sits with corrosion inhibitors. Newer deployment is concentrated in electrochemical oxygen scavenger hybrids.
End User:
Application intensity varies sharply by steam system pressure, continuous operation requirements, and regulatory scrutiny exposure.
- Power Generation:Natural gas combined-cycle and renewable-integrated baseload facilities operate ultra-high-pressure boilers requiring continuous chemical dosing with zero tolerance for chemistry excursions. ERCOT and PJM interconnection zones anchor procurement volume as utilities replace aging coal capacity.
- Food & Beverage:Dairy processing, meatpacking, and brewing operations balance sanitation-grade steam requirements against wastewater discharge constraints. California Central Valley dairy cooperatives and Ontario meatpacking clusters are unbundling chemical supply from technical service contracts.
- Chemicals:Petrochemical crackers and specialty chemical reactors demand corrosion-resistant formulations compatible with process contamination risks. Gulf Coast ethylene producers in Texas and Louisiana specify phosphonate-based programs for high-cycles-of-concentration operation.
- Textiles:Dyeing and finishing operations require soft water for color consistency, driving demand for chelating agents and ion exchange regeneration chemicals. North Carolina Piedmont textile corridors show renewed investment as reshoring accelerates.
Power generation commands the steepest expansion trajectory. Textiles and chemicals are climbing fastest from smaller bases.
Delivery Mode:
Physical form selection trades off dosing precision, storage footprint, and handler safety compliance.
- Liquid:Bulk tanker and tote deliveries dominate high-volume power generation accounts where automated feed systems require pumpable formulations. Midwest manufacturing corridors prefer liquid sulfite and caustic soda for compatibility with existing chemical feed skids.
- Powder:Sulfite powders and phosphate blends serve smaller industrial boilers with manual batch dosing and limited storage infrastructure. Remote mining camps in northern Canada and Alaska rely on powder logistics for seasonal resupply.
- Granular:Controlled-dissolution granules target cooling tower and auxiliary boiler applications requiring measured release rates. Food processing facilities in the Pacific Northwest specify granular morpholine for controlled alkalinity adjustment.
- Tablet:Slow-dissolving tablets simplify dosing for unmanned boiler houses and seasonal heating systems. Commercial building operators in northeastern US cities favor tablet programs for reduced handler exposure compliance.
Liquid delivery anchors power sector procurement. Tablet formats are gaining share fastest in commercial and institutional heating.
Service Type:
Chemical supply margins increasingly depend on bundled technical service depth and digital monitoring integration.
- Water Analysis:Laboratory testing for dissolved solids, alkalinity, hardness, and metal content validates treatment program effectiveness. Third-party certified labs in Houston and Toronto serve cross-border industrial corridors with EPA and Ontario MOE reporting formats.
- On-site Testing:Handheld conductivity, pH, and dissolved oxygen meters enable real-time adjustment without laboratory delays. Field technicians in the Ohio River Valley coal-to-gas conversion projects embed daily testing into outage prevention protocols.
- Equipment Maintenance:Chemical feed pump calibration, sensor replacement, and dosing line flushing preserve program reliability. Integrated suppliers defend long-term contracts by embedding maintenance crews at Texas power generation campuses.
- Consultation:Process optimization studies and regulatory compliance planning address zero-liquid discharge and cooling tower blowdown minimization. California food processors purchase standalone consulting to meet Regional Water Quality Control Board mandates.
Equipment maintenance anchors integrated supplier retention. Consultation services are expanding most quickly as end-users unbundle procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power generation corridors in Texas and Ontario concentrate chemical procurement volume, while provincial water mandates and federal emissions rules reshape formulation requirements across the continent.
United States
Natural gas combined-cycle expansion in the ERCOT and PJM interconnection zones drives continuous oxygen scavenger consumption. EPA's Steam Electric Power Generating Effluent Guidelines mandate enhanced heavy metals precipitation at coal and gas facilities. Texas Gulf Coast petrochemical clusters specify phosphonate-based scale control for high-cycles-of-concentration boiler operation.
Canada
Ontario's tightening dissolved solids discharge permits intensify demand for advanced chelating agents in Toronto-Hamilton manufacturing corridors. Health Canada and PMRA oversight adds compliance documentation burdens for cross-border chemical suppliers. Alberta's oil sands upgraders and Suncor-led power integration projects anchor western procurement volume.
Mexico
Nearshoring manufacturing expansion in Nuevo León and the Bajío Region generates new boiler capacity in automotive and appliance production. Federal water quality standards under CONAGUA jurisdiction tighten discharge monitoring for industrial zones. Monterrey industrial parks are retrofitting chemical feed systems to meet combined-cycle cogeneration reliability requirements.
North America Boiler Water Treatment Chemicals Market Competitive Landscape
United States-based integrated service-chemical providers anchor one tier; European and Japanese specialty chemical specialists hold formulation technology positions in premium segments. Market structure consolidates around three to five dominant suppliers with embedded technical service crews, while regional formulators compete on price for commodity oxygen scavenger volumes. Strategic archetypes include full-service program managers, precision chemical manufacturers, and digital monitoring platform operators. Capacity expansion and strategic partnerships dominate competitive moves as suppliers secure feedstock security and automation integration capabilities.
Within the integrated service tier, Ecolab Inc. and ChemTreat Inc. represent the anchored technical service model, embedding field teams at power generation campuses to defend long-term contracts. Nalco Water exemplifies the digital-analytics archetype, pairing chemical supply with IoT-enabled monitoring platforms that extend program visibility beyond traditional delivery schedules. These three companies collectively illustrate how service integration depth, rather than commodity pricing alone, determines competitive positioning in high-reliability boiler applications.
| Leading Market Players |
|---|
| Ecolab Inc. |
| ChemTreat Inc. |
| Nalco Water |
| Kemira |
| Solenis |
| Kurita Water Industries Ltd |
| Suez |
| Dow Inc. |
| BASF |
| Others |
Value Network & Pricing Analysis
A certification-performance divergence separates pharmaceutical-grade pH regulators from commodity oxygen scavengers, with the former commanding three-to-five-fold markups tied to ASME and Health Canada documentation burdens while the latter compete on volume throughput to power generation accounts in Texas and Alberta. This bifurcation reshapes supplier economics: premium formulators absorb extended 18-24 month approval cycles into pricing, whereas commodity producers face relentless feedstock volatility from Gulf Coast phosphonate concentration.
Pricing Analysis
Volume-margin splits anchor competitive positioning in this market. Commodity oxygen scavengers and corrosion inhibitors operate on contract-based long-term offtake structures with thin spreads, while pH regulators for high-purity steam applications extract value through certification-grade premiums tied to ASME boiler water quality standards. Price differentiation stems from quality grade and after-sales service bundling, with integrated technical service contracts defending 15-25 point margin advantages over standalone chemical sales. Cost compression in the commodity tier is intensifying because food and beverage processors in California and Ontario are unbundling supply from service contracts. Power generation utilities show least price sensitivity due to outage risk premiums, whereas textile dye houses in the Carolinas exhibit acute cost consciousness.
Supply Chain Analysis
Freight cost differentials of 12-18 percent separate bulk liquid tanker deliveries to ERCOT power campuses from powder logistics to remote Canadian mining camps, compressing effective margins on low-density formulations. Manufacturing concentrates in the United States, Canada, and Germany, with phosphonate chelating agents and sulfite precursors drawing from Gulf Coast petrochemical complexes and Rhineland chemical corridors. Supply chain risk centers on single-source vulnerability for electrochemical oxygen scavenger membrane components sourced from Japanese specialty suppliers. Distribution runs through integrated service-chemical providers embedding field technicians at major accounts, with regional formulators competing via third-party chemical distributors for spot volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized water chemist scarcity constrains service expansion capacity, propping pricing power for incumbents with embedded technical teams while limiting new entrant scale-up velocity across North American power corridors.
For Market Incumbents: Deploy predictive dosing algorithm platforms to deepen account retention. Integrate IoT-enabled conductivity monitoring at Texas and Ontario power generation facilities to create switching costs that resist disintermediation pressures from unbundled procurement trends. Acquire regional formulators in the Quebec pulp and paper corridor to preempt competitor consolidation moves. For New Entrants and Emerging Players: The premium-economy price-point gap in tablet-format oxygen scavengers for commercial heating systems offers white-space entry. Target northeastern US commercial building operators with simplified dosing programs that reduce OSHA handler exposure compliance burdens. Establish partnerships with third-party certified water analysis laboratories in Houston and Toronto to bypass captive service infrastructure requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated service-chemical platforms seeking digital monitoring capabilities. Five-to-ten year viability favors targets with Health Canada PMRA registration portfolios and embedded Alberta oil sands upgrader relationships. Monitor EPA effluent guideline implementation timelines as inflection signals for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphonate Precursors | Captive supply of chelating agents insulates margin from Gulf Coast feedstock disruption risk. |
| Digital Monitoring Platform Deployment | IoT-enabled sensors at PJM interconnection facilities create recurring revenue attachment. |
| Quebec Pulp and Paper Corridor Expansion | Underpenetrated Saguenay-Lac-Saint-Jean region offers closed-system protocol conversion opportunity. |
| Electrochemical Oxygen Scavenger Partnership | Japanese membrane technology licensing accelerates hybrid system penetration at Mid-Atlantic utilities. |
| Health Canada PMRA Registration Investment | Cross-border compliance documentation secures Ontario-Quebec manufacturing base access. |
Research Methodology
EPA effluent limitation guidelines, ASME boiler water quality standards documentation, and SEC 10-K filings from publicly traded chemical suppliers formed the secondary backbone for this analysis. Primary interviews with power generation plant managers, food and beverage procurement leads, water treatment technical service directors, and Health Canada regulatory affairs specialists validated formulation demand assumptions. Bottom-up triangulation across chemical consumption rates by end-use sector and top-down cross-checks against regional industrial boiler capacity produced convergent volume estimates.
Bottom-up modeling anchored the analytical lens, with top-down macroeconomic validation ensuring consistency. Segmentation dimensions included product chemistry type, end-use thermal intensity, delivery physical form, and service integration depth across the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns and forward-looking regulatory implementation schedules. Forecast inputs incorporated natural gas combined-cycle capacity additions in ERCOT and PJM zones and Ontario dissolved solids discharge permit tightening timelines.
Inputs from EPA rulemaking dockets and provincial water quality boards were available through the study window; gaps in real-time utility procurement contract terms introduce uncertainty bands around power generation segment projections. Forecasts reflect assumptions about regulatory implementation pacing and feedstock cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
US Liquid Waste Management Market
Water & Sludge Treatment
Europe Membrane Bioreactor (MBR) Market
Water & Sludge Treatment
Asia-Pacific Water Free/ Waterless Urinals Market
Water & Sludge Treatment
Ballast Water Treatment Market
Water & Sludge Treatment
Pool and Spa Water Treatment Chemicals for Hotels and Clubs Market
Water & Sludge Treatment
North America Water Treatment Chemicals Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
Australia Water Treatment Chemicals Market
Water & Sludge Treatment
Global Sodium Hypochlorite Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market