
 Water Purification Systems Market | 2026-2036
Water Purification Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Water Purification Systems Market Insights
Chinese membrane module producers is restructuring output lines to serve both domestic municipal tenders and export OEM contracts. Pentair leverages backward integration into filter media manufacturing to protect margin pools across residential and commercial channels. Xylem Inc. anchors its position through digital water platform integration with physical treatment assets. Suez Water Technologies & Solutions specializes in ion exchange resin regeneration services that create recurring revenue streams alongside equipment sales.
Water purification systems combine physical barriers, chemical processes, and biological mechanisms to remove contaminants from raw water sources, typically achieving removal efficiencies of 99.9% for bacteria and protozoa through multi-barrier configurations. Reverse osmosis membranes operate at transmembrane pressures of 150-800 psi depending on feedwater salinity, producing permeate suitable for pharmaceutical process water and potable reuse applications. Membrane filtration leads product type value generation due to replacement cartridge economics and energy recovery innovations in seawater desalination. Residential end user demand is accelerating fastest in water-stressed urban corridors where point-of-entry systems displace bottled water dependence. Wastewater treatment applications command premium pricing through zero-liquid-discharge configurations required by semiconductor fabs and power plants.
The EPA enforces Safe Drinking Water Act maximum contaminant levels that force municipal operators into technology upgrades, while ISO 14001 environmental management certification gates supplier qualification for industrial procurement. India's Central Pollution Control Board mandates effluent quality standards that drive biological treatment adoption in textile and leather clusters. Stakeholders must monitor how per- and polyfluoroalkyl substance regulations expand liability for legacy contamination, reshaping activated carbon and ion exchange replacement cycles.
Market Dynamics
Membrane filtration technology is compressing capital cycles for municipal utilities while tightening compliance thresholds from the EPA's Lead and Copper Rule revisions force infrastructure reinvestment across aging distribution networks.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:The tightened compliance thresholds in the United States mandate technology upgrades for municipal operators, accelerating membrane filtration deployments in legacy distribution infrastructure.
- Seawater Desalination Energy Recovery:Innovations in pressure exchanger and turbocharger configurations reduce specific energy consumption for reverse osmosis plants, expanding viable project economics for coastal utilities.
- India Tier-One Urbanization:Centralized treatment capacity in Mumbai, Delhi, and Bangalore lags population growth, creating procurement urgency for point-of-entry residential systems and municipal scale-up.
Market Restraints
- Specialized Polymer Feedstock Concentration:High-performance membrane polymers depend on concentrated petrochemical supply chains, exposing module producers to input cost volatility and geopolitical disruption.
- Technical Limitation in PFAS Destruction:Current activated carbon and ion exchange systems capture but do not mineralize per- and polyfluoroalkyl substances, creating concentrated waste streams requiring thermal disposal.
- Substitution Threat from Bottled Water:Consumer trust gaps in municipal supply quality sustain parallel bottled water expenditure, fragmenting residential purification demand in emerging urban corridors.
Strategic Opportunities
- Zero-Liquid-Discharge Semiconductor Fabs:Ultra-pure water requirements and stringent effluent mandates in chip manufacturing create premium pricing configurations for closed-loop purification systems.
- Digital Platform Convergence:Integration of physical treatment assets with predictive analytics and remote monitoring enables outcome-based service contracts for industrial water management.
- India Textile Cluster Biological Treatment:Central Pollution Control Board effluent mandates in Tirupur and Surat drive adoption of membrane bioreactors for dyehouse wastewater recovery.
Industry Challenges
- Membrane Fouling Expertise Gap:Specialized operators capable of optimizing chemical cleaning protocols and transmembrane pressure management remain scarce across Southeast Asian utilities.
- Legacy Infrastructure Integration:Retrofitting membrane systems into Victorian-era distribution networks in London and northeastern US cities requires custom engineering and extended commissioning timelines.
- ISO 14001 Certification Burden:Industrial procurement gates demand environmental management system compliance, stretching qualification timelines for mid-tier equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Purification Systems Market |
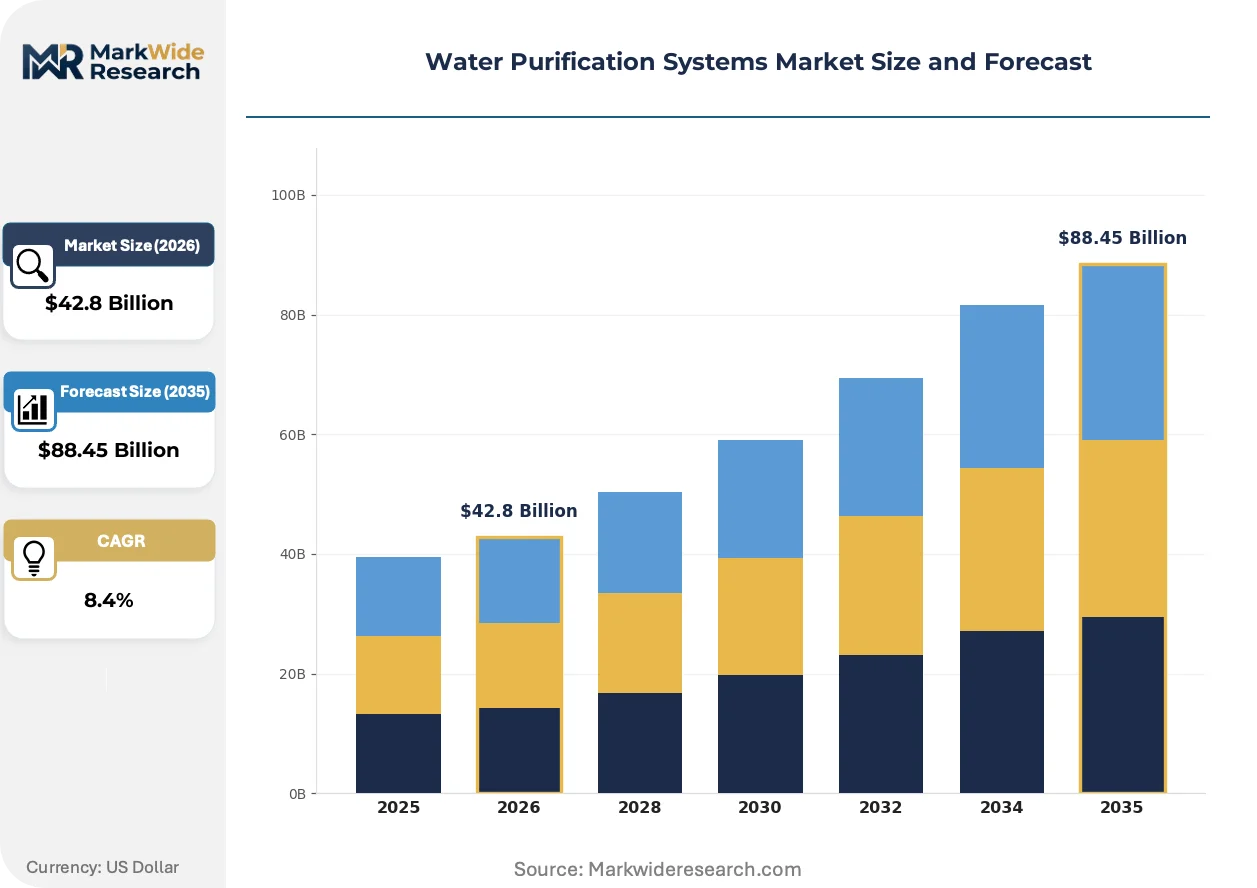
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $88.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Ultraviolet, Activated Carbon, Distillation End User: Residential, Commercial, Industrial, Municipal Application: Drinking Water Treatment, Wastewater Treatment, Process Water, Aquaculture Technology: Membrane Filtration, Ion Exchange, Chemical Treatment, Biological Treatment |
| Companies Covered | Pentair, A. O. Smith Corporation, Culligan International, Coway Co., Ltd., 3M, Panasonic Corporation, Veolia Water Technologies & Solutions, Suez Water Technologies & Solutions, Xylem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Purification Systems Market Trends and Innovations
Water purification architecture is converging around intelligent monitoring layers that overlay physical treatment assets, compressing the gap between operational data and predictive intervention.
Membrane bioreactor technology is unifying biological degradation with membrane separation in single-vessel configurations. Municipal utilities in water-stressed coastal zones are deploying these systems for direct potable reuse applications. The structural consequence is collapsing the historical separation between wastewater treatment and drinking water production, enabling utilities to recapture effluent as feedstock rather than discharge.
REACH restrictions on per- and polyfluoroalkyl substances are cascading through European supply chains for ion exchange resins and activated carbon media. Manufacturers face reformulation pressure for fluoropolymer-based membrane components used in aggressive chemical separation. The industrial water segment is responding by accelerating qualification of ceramic and polyethersulfone alternatives that bypass fluorinated chemistry entirely.
Service unbundling is fragmenting traditional equipment-procurement relationships in commercial and institutional verticals. Facility managers in US healthcare and education sectors are separating capital equipment acquisition from consumables logistics and membrane replacement scheduling. This pattern is most visible in California and Texas, where water cost volatility and sustainability reporting requirements compress decision cycles for outsourced water management.
Water Purification Systems Market Segmentation
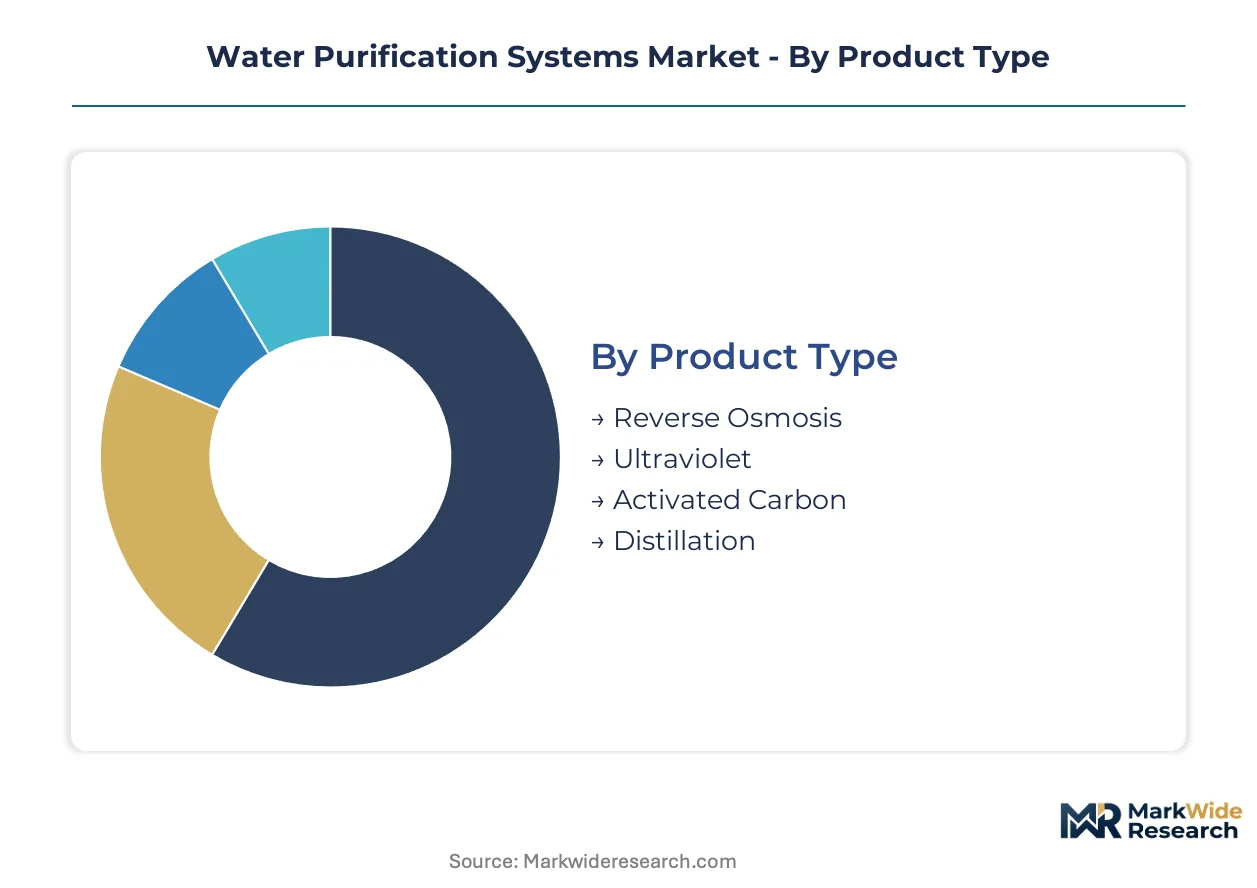
Technology choice in water purification locks in operational cost structures for decades. Membrane module selection determines energy intensity, chemical consumption, and replacement cadence across municipal and industrial deployments.
Product Type:
Supply concentration tilts toward membrane module producers with captive polymer extrusion capabilities and regional cartridge distribution networks.
- Reverse Osmosis:Thin-film composite polyamide membranes achieve 99.5% salt rejection at transmembrane pressures of 150-800 psi. Seawater desalination plants in Israel, Saudi Arabia, and Australia deploy these systems with energy recovery devices to compress specific consumption below 3 kWh per cubic meter.
- Ultraviolet:Low-pressure amalgam lamps emitting at 254 nanometers disrupt microbial DNA without chemical residuals. Pharmaceutical manufacturers in Switzerland and Germany specify UV-LED alternatives for cold sterilization of process water loops.
- Activated Carbon:Bituminous and coconut shell media adsorb chlorine, organics, and emerging contaminants. Municipal utilities in the United States specify reagglomerated grades for taste and odor control in surface water treatment.
- Distillation:Multi-effect thermal processes achieve ultra-pure water specifications for laboratory and medical applications. Semiconductor fabs in Taiwan and South Korea deploy vapor compression variants for process water make-up.
Reverse osmosis absorbs the bulk of installed capacity; ultraviolet is expanding most quickly.
End User:
Cost tier stratification separates capital-intensive municipal tenders from recurring-revenue residential cartridge replacements.
- Residential:Point-of-entry systems and under-sink configurations serve water-stressed urban corridors where municipal supply quality fluctuates. India's tier-one cities drive procurement urgency as centralized treatment capacity lags population growth in Mumbai and Bangalore.
- Commercial:Hotels, hospitals, and food service operations specify multi-barrier configurations combining sediment filtration, activated carbon, and UV disinfection. Healthcare facilities in the United States face Joint Commission standards for Legionella prevention in building water systems.
- Industrial:Power plants, refineries, and manufacturing facilities require high-volume treatment with minimal downtime. Zero-liquid-discharge configurations command premium pricing from semiconductor fabs with stringent effluent mandates.
- Municipal:Centralized treatment plants serve populations exceeding 10,000 through coagulation, filtration, and disinfection trains. Southeast Asian utilities accelerate membrane filtration deployments to replace aging conventional treatment infrastructure.
Municipal systems anchor capital expenditure volumes; residential point-of-entry configurations are climbing the fastest.
Application:
Volume concentration centers on drinking water treatment, while margin pools concentrate in specialized process water specifications.
- Drinking Water Treatment:Multi-barrier approaches combining coagulation, granular media filtration, and disinfection achieve 99.9% pathogen removal. EPA Lead and Copper Rule revisions force infrastructure reinvestment across aging distribution networks in the United States.
- Wastewater Treatment:Membrane bioreactors unify biological degradation with membrane separation for direct potable reuse. Coastal utilities in Singapore and California deploy these systems to recapture effluent as feedstock rather than discharge.
- Process Water:Ultra-pure specifications for electronics manufacturing require reverse osmosis followed by electrodeionization and final polishing. Chip fabrication facilities specify resistivity above 18 megohm-centimeter for wafer rinsing operations.
- Aquaculture:Recirculating aquaculture systems depend on biofiltration and solids removal to maintain water quality in intensive fish production. Norwegian salmon farms deploy drum filters and protein skimmers to reduce water exchange rates.
Drinking water treatment dominates installed base; process water applications for semiconductor manufacturing show the steepest expansion trajectory.
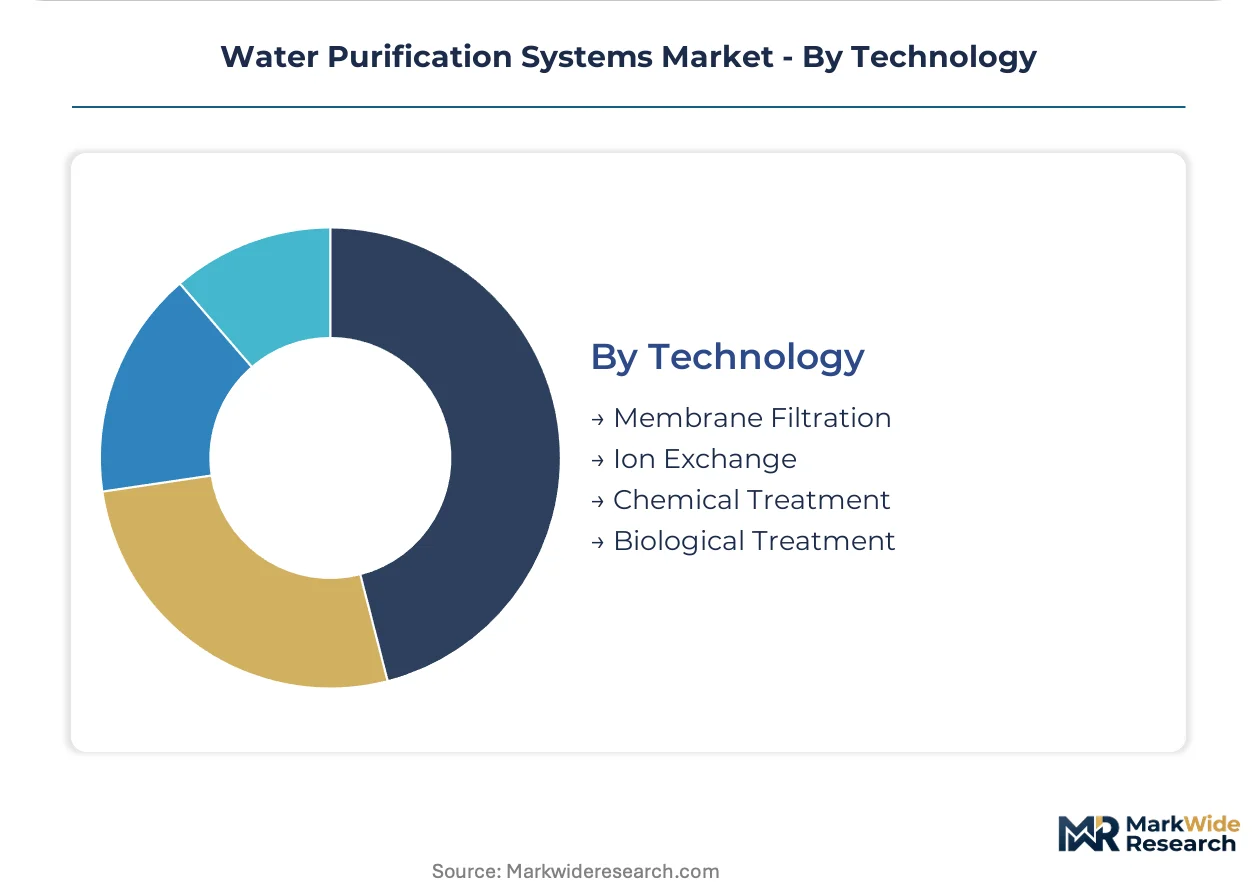
Technology:
Customer type determines whether physical separation, chemical transformation, or biological mechanisms dominate system architecture.
- Membrane Filtration:Microfiltration, ultrafiltration, nanofiltration, and reverse osmosis separate contaminants by size exclusion and solution-diffusion mechanisms. Replacement cartridge economics and energy recovery innovations sustain value generation across product lifecycles.
- Ion Exchange:Synthetic resins remove dissolved ions through reversible exchange reactions. Regeneration services create recurring revenue streams for suppliers serving boiler feedwater and pharmaceutical applications.
- Chemical Treatment:Oxidation, coagulation, and pH adjustment neutralize pathogens and precipitate dissolved metals. Chlorine-based disinfection remains dominant in municipal applications despite disinfection byproduct formation concerns.
- Biological Treatment:Activated sludge and biofilm processes degrade organic contaminants through microbial metabolism. India's Central Pollution Control Board mandates biological treatment adoption in Tirupur and Surat textile clusters.
Membrane filtration commands the largest share of new capital deployment; biological treatment is gaining share fastest in industrial effluent recovery applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer feedstock for membrane production concentrates in petrochemical corridors near Houston, Rotterdam, and Singapore, anchoring regional manufacturing clusters to raw material access points.
United States
Municipal utilities in Flint and Newark drive lead service line replacement programs. EPA Lead and Copper Rule revisions tighten compliance thresholds for aging distribution infrastructure. Southeast utilities accelerate membrane filtration tenders to meet Safe Drinking Water Act mandates.
Germany
REACH restrictions on per- and polyfluoroalkyl substances cascade through ion exchange resin supply chains. ECHA reformulation deadlines pressure membrane manufacturers to qualify ceramic alternatives. The Rhine-Ruhr industrial corridor adopts zero-liquid-discharge configurations for chemical process water.
China
Dual carbon goals compress energy intensity targets for seawater desalination plants. MIIT membrane module standards favor domestic producers in municipal tender processes. Yangtze River Delta utilities deploy membrane bioreactors for direct potable reuse pilots.
India
Tier-one urbanization in Mumbai and Bangalore outpaces centralized treatment capacity expansion. Central Pollution Control Board effluent mandates drive biological treatment adoption in Tirupur textile clusters. Point-of-entry residential systems displace bottled water dependence in water-stressed corridors.
Israel
Seawater desalination energy recovery innovations reduce specific consumption below 3 kWh per cubic meter. National water carrier integration with Mediterranean coastal plants sustains membrane replacement demand. The Negev semiconductor corridor requires ultra-pure process water specifications.
Water Purification Systems Market Competitive Landscape
Global majors compete with regional champions across technology licensing and municipal tender participation. The vendor base separates into membrane module specialists, integrated system fabricators, and service-centric operators. Three archetypes dominate: polymer science specialists with captive extrusion capabilities, digital platform integrators bundling hardware with predictive analytics, and regeneration service providers locking in recurring revenue through consumables logistics. Competitive moves concentrate on backward integration into filter media manufacturing and geographic expansion through local assembly partnerships.
Within the integrated system tier, Pentair and Xylem Inc. exemplify scale-driven positioning, while Suez Water Technologies & Solutions occupies a service-centric niche. Pentair anchors North American residential and commercial channels through backward integration strategies. Xylem Inc. represents the digital convergence archetype, bundling physical treatment assets with platform-based monitoring. Suez Water Technologies & Solutions exemplifies recurring-revenue positioning through ion exchange resin regeneration services alongside equipment placement.
| Leading Market Players |
|---|
| Pentair |
| A. O. Smith Corporation |
| Culligan International |
| Coway Co., Ltd. |
| 3M |
| Panasonic Corporation |
| Veolia Water Technologies & Solutions |
| Suez Water Technologies & Solutions |
| Xylem Inc. |
| Others |
Pricing and Supply Chain Analysis
EPA Lead and Copper Rule revisions are forcing municipal utilities into membrane filtration upgrades, compelling suppliers to reconfigure warranty and service bundles while absorbing engineering complexity into long-term contract pricing.
Pricing Analysis
Warranty and consumables bundling separates premium municipal tenders from unbundled residential cartridge sales. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and membrane polymer performance tier. Price differentiation reflects ISO 14001 environmental management certification status and geographic delivery logistics. Pricing pressure stems from raw material volatility in specialized polymer feedstocks. Municipal buyers exhibit lowest price sensitivity due to regulatory compliance mandates; residential point-of-entry purchasers show highest elasticity, substituting toward bottled water when capital costs spike.
Supply Chain Analysis
Single-source vulnerability sits with concentrated petrochemical corridors near Houston, Rotterdam, and Singapore anchoring high-performance membrane polymer production. Module assembly draws from China, the United States, and Germany for thin-film composite fabrication and cartridge distribution. Raw material dependencies center on polyamide resins, polysulfone substrates, and ceramic alumina precursors. Tariff exposure runs through cross-border resin shipments and finished module trade. Distribution runs through regional OEM partnerships and direct municipal tender channels with extended commissioning timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water purification sector is transitioning from conventional treatment trains to membrane-centric architectures, with membrane bioreactor technology displacing historical separation between wastewater and potable water production.
For Market Incumbents: Anticipate ceramic and polyethersulfone membrane alternatives bypassing fluorinated chemistry as REACH restrictions cascade through European supply chains. Backward integration into filter media manufacturing protects margin pools against polymer feedstock volatility. Digital platform convergence with predictive analytics locks in outcome-based service contracts against pure equipment vendors. For New Entrants and Emerging Players: Direct-to-utility digital sales channels bypass established distributor relationships in Southeast Asian membrane filtration tenders. India's tier-one cities present the most penetrable geography as centralized treatment capacity lags population growth in Mumbai and Bangalore. Service unbundling in US healthcare and education sectors creates white-space for outsourced membrane replacement logistics. For Investors and Strategic Acquirers: Re-rating potential sits with ion exchange resin regeneration service providers given recurring revenue visibility and consumables lock-in alongside equipment placement. Long-term viability favors operators with captive polymer extrusion capabilities and regional cartridge distribution networks. Monitor PFAS regulatory expansion as the signal indicating accelerated replacement cycles for activated carbon and ion exchange media.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | Pentair's captive manufacturing protects margins across residential and commercial channels. |
| Digital Platform Integration | Xylem bundles physical assets with predictive analytics for outcome-based industrial contracts. |
| Geographic Expansion via Local Assembly | Chinese producers restructure lines to serve domestic tenders and export OEM contracts simultaneously. |
| Service Unbundling | Facility managers in California and Texas separate capital acquisition from consumables logistics. |
| Membrane Bioreactor Deployment | Singapore and California utilities collapse wastewater treatment and drinking water production boundaries. |
Research Methodology
Document review covered EPA enforcement actions, ECHA substance restriction databases, and municipal tender announcements across Southeast Asia and India, complemented by interviews with membrane module procurement directors, plant engineers at semiconductor fabs, regeneration service operations managers, and Central Pollution Control Board officials. Secondary validation drew from ISO certification registries, customs trade data for polymer feedstocks, and SEC filings from listed water technology suppliers. Bottom-up capacity assessments and top-down regulatory mandate projections were triangulated against replacement cycle economics.
Segmented outputs across product type, end user, application, and technology dimensions were generated over the projection horizon. CAGRs were derived from installed base depreciation schedules, regulatory compliance timelines, and urbanization-driven demand elasticity. Forecast inputs incorporated energy recovery innovation adoption curves in seawater desalination and PFAS detection threshold revisions affecting media replacement frequency.
Inputs from municipal procurement databases and industrial facility water specifications were available through the study window; gaps in real-time membrane fouling rate data and proprietary polymer formulation costs introduce uncertainty bands. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
Global Flocculant and Coagulant Market
Water & Sludge Treatment
Slurry Valves Market
Water & Sludge Treatment
Wastewater Treatment Chemicals Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
Sludge Treatment and Disposal Equipment Market
Water & Sludge Treatment
Aquarium Water Treatment Market
Water & Sludge Treatment
North America Industrial Water Treatment Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Membrane Water Treatment Chemicals Market