
 Waste Management Market | 2026-2036
Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Waste Management Market Intelligence
Germany is tilting toward circular-economy infrastructure as its waste-to-energy and mechanical recycling capacity expands across the Rhine-Ruhr cluster. Veolia leverages its integrated treatment and energy recovery footprint to anchor European hazardous waste flows. Republic Services, Inc. dominates North American landfill gas capture and municipal collection routes through vertical control of transfer stations. Clean Harbors, Inc. specializes in high-complexity industrial and chemical waste streams that command premium treatment margins.
Waste management encompasses the systematic collection, transport, processing, recycling, and disposal of solid and hazardous materials through engineered facilities designed to minimize environmental release and recover embedded energy or materials. The sector relies on leachate containment systems, emissions scrubbers, and sorting robotics to meet health and environmental performance thresholds while serving urban sanitation and industrial compliance needs. Collection and recycling services capture the largest revenue pools given their recurring municipal contracts and commodity recovery economics, while anaerobic digestion is expanding fastest as biogas offtake agreements with utilities multiply. Hazardous waste treatment commands the deepest margins due to permitting barriers and liability structures that limit competitive entry.
The EPA enforces landfill methane regulations and RCRA subtitle standards that dictate containment technology and post-closure care obligations across the United States. The EU Green Deal and REACH framework restrict hazardous substance disposal routes while mandating recycled content quotas that pull material back into processing loops. Stakeholders must monitor how carbon border adjustments and evolving extended producer responsibility schemes redistribute cost accountability between generators, processors, and brand owners.
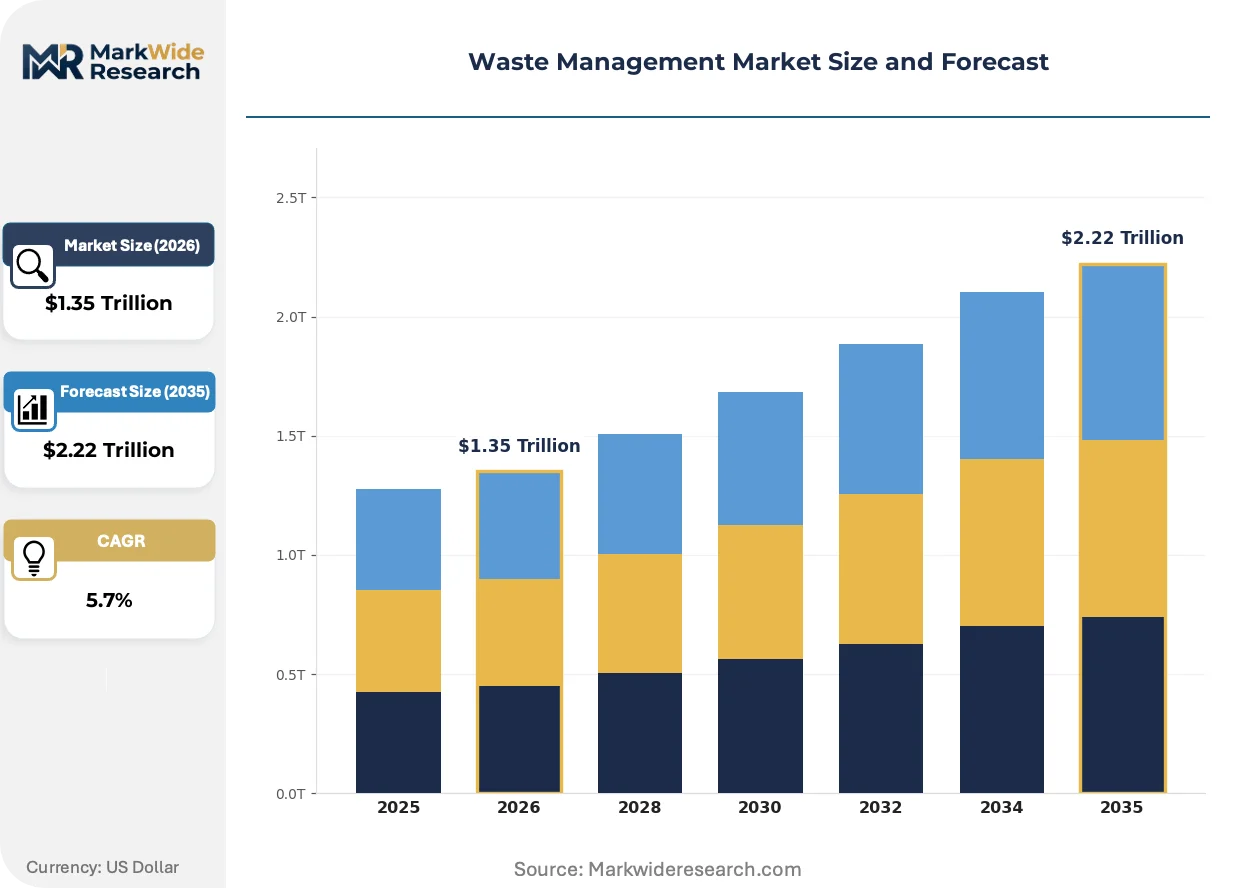
Market Dynamics
Extended producer responsibility mandates are forcing brand owners to internalize end-of-life costs, compressing landfill economics while pulling material volumes into recycling and anaerobic digestion infrastructure. This regulatory pivot is redrawing competitive boundaries between collection operators, treatment technology providers, and energy offtakers.
Growth Catalysts
- EU Green Deal landfill diversion targets:National caps on biodegradable waste disposal are accelerating anaerobic digestion buildout across Germany, Italy, and the Netherlands.
- Smart-bin sensor deployment:IoT-enabled fill-level monitoring is optimizing collection route density and reducing diesel consumption for municipal fleets.
- Biogas utility offtake agreements:Long-term power purchase contracts with grid operators are de-risking capital deployment for organic waste processors.
Market Restraints
- Sorting robotics capital intensity:Near-infrared and AI-powered separation systems require seven-figure installation outlays that strain mid-tier operator balance sheets.
- Secondary commodity price volatility:OCC and mixed plastic bale values fluctuate with Chinese import policy shifts, undermining recycling program economics.
- RCRA permitting timelines:EPA hazardous waste facility approvals stretch 18-36 months, freezing treatment capacity expansion where industrial generator demand concentrates.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and gasification technologies are unlocking value from contaminated plastic streams mechanical processes cannot handle.
- India's Swachh Bharat infrastructure gap:Formal collection coverage remains below 50% in tier-2 cities, creating whitespace for integrated waste-to-compost operators.
- Carbon border adjustment mechanism:EU CBAM embedded emissions tracking will reward low-circular-intensity material recovery with competitive export positioning.
Industry Challenges
- Leachate treatment operator shortage:Specialized wastewater chemists and membrane technicians command premium wages that erode landfill operating margins.
- Legacy ERP integration complexity:Route optimization software deployment stalls when interfacing with decades-old municipal billing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste Management Market |
| Market Size in 2026 | $1.35 Trillion |
| Market Size in 2035 | $2.22 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Recycling, Treatment, Disposal Technology: Incineration, Anaerobic Digestion, Composting, Landfilling End User: Municipalities, Industries, Households, Commercial Waste Type: Organic, Plastic, Hazardous, E-Waste |
| Companies Covered | Veolia, Clean Harbors, Inc., Waste Management, Inc., Stericycle, Inc., Casella Waste Systems, Inc., Republic Services, Inc., GFL Environmental, Remondis, Waste Connections, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste Management Market Strategic Shifts & Innovations
Digital twin technology is virtualizing asset performance modeling across the waste value chain. Operators now simulate collection network efficiency, treatment plant throughput, and landfill gas generation before committing capital, compressing pilot-to-deployment cycles.
Sensor fusion and machine vision are virtualizing manual quality control at materials recovery facilities. Advanced robotics from AMP Robotics and ZenRobotics are sorting commingled streams at 80 picks per minute, displacing hand-picking labor while improving contamination rates. European operators in the Netherlands and Belgium are deploying these systems fastest, driven by Packaging Act compliance deadlines.
REACH substance restriction amendments are tightening hazardous waste classification thresholds. The European Chemicals Agency is expanding SVHC candidate list coverage, forcing industrial generators to reroute spent solvents and catalyst residues toward licensed thermal treatment rather than fuel blending. German chemical parks are consolidating waste streams under single-operator contracts to manage liability exposure.
Retail and foodservice buyers are unbundling waste services from bundled facility management contracts. Large quick-service restaurant chains are direct-contracting organic waste haulers for store-level food scrap diversion, bypassing traditional multi-service vendors. This disintermediation concentrates volumes with specialized anaerobic digestion operators in California and the UK, where landfill disposal taxes create arbitrage value.
Waste Management Market Segmentation
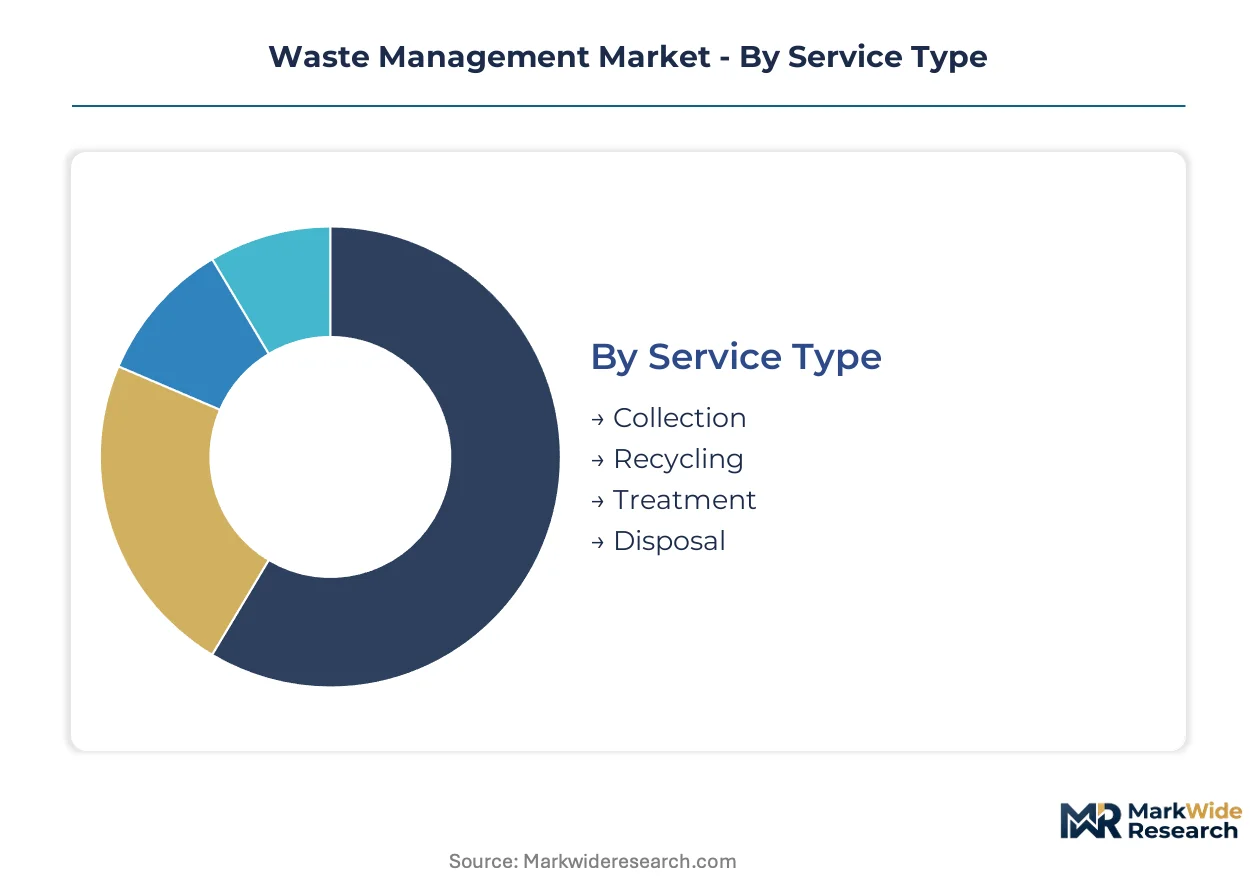
Waste management segmentation reveals how service economics, technology maturity, and regulatory pressure fragment revenue pools across distinct operational models. Understanding these divides clarifies where capital deployment concentrates and which technology pathways attract policy support.
Service Type:
Collection routes anchor recurring municipal revenue, while treatment and disposal services capture value from complexity and permitting scarcity.
- Collection:Curbside pickup and container logistics form the entry point for municipal contracts, with route density determining diesel cost recovery. Demand clusters in German cities where Packaging Act compliance mandates separate bin infrastructure and frequent collection cycles.
- Recycling:Materials recovery facilities sort commingled streams into commodity bales, with contamination rates dictating offtake pricing. North American operators face margin pressure from Chinese import restrictions that collapsed OCC and mixed plastic values.
- Treatment:Thermal and biological processing neutralizes hazardous constituents or extracts energy before final disposal. Industrial generators in the Rhine-Ruhr cluster contract integrated treatment to manage liability under REACH substance restrictions.
- Disposal:Engineered landfills with leachate containment and gas capture systems serve residual waste streams. EPA methane regulations and post-closure care obligations extend liability timelines for US operators.
The dominant share belongs to Collection, while Recycling is closing the gap fastest as extended producer responsibility laws pull material volumes out of landfill routes.
Technology:
Technology choice tracks waste composition, energy pricing, and air emissions standards that vary by jurisdiction.
- Incineration:Mass-burn and refuse-derived fuel plants recover electricity and district heat from combustible fractions. Dutch and Swedish utilities operate WtE plants at 90%+ availability, feeding district heating networks in Rotterdam and Stockholm.
- Anaerobic Digestion:Wet fermentation of organic waste produces biogas upgradable to biomethane for grid injection. Italian agricultural cooperatives and UK water utilities are scaling capacity to capture landfill diversion credits and renewable transport fuel certificates.
- Composting:Aerobic decomposition of garden and food waste yields soil amendments for agriculture and landscaping. French and Spanish operators dominate Mediterranean markets where lower heating values favor biological over thermal processing.
- Landfilling:Engineered containment with liner systems and gas collection remains the default for residual fractions. German landfill bans on untreated organic waste have collapsed biodegradable disposal volumes since implementation.
Incineration retains the largest installed base, though Anaerobic Digestion is expanding most quickly as biogas offtake agreements de-risk capital commitment.
End User:
Customer type determines contract structure, pricing power, and regulatory exposure across the value chain.
- Municipalities:Local governments procure integrated collection and processing through long-term concessions. Italian and Dutch cities bundle waste services with district heating or public transport contracts.
- Industries:Manufacturing and chemical generators purchase specialized treatment for hazardous byproduct streams. German chemical parks consolidate waste under single-operator contracts to streamline ECHA compliance.
- Households:Residential waste flows through municipal systems or pay-as-you-throw schemes. Swiss and Belgian municipalities apply weight-based or volume-based pricing to incentivize source separation.
- Commercial:Retail, foodservice, and office generators contract directly for specialized streams like organics or confidential document destruction. UK supermarket chains bypass traditional vendors to contract anaerobic digestion operators for food scrap diversion.
Municipalities command the deepest contract backlog, while Commercial users are diversifying fastest as disintermediation concentrates volumes with specialized haulers.
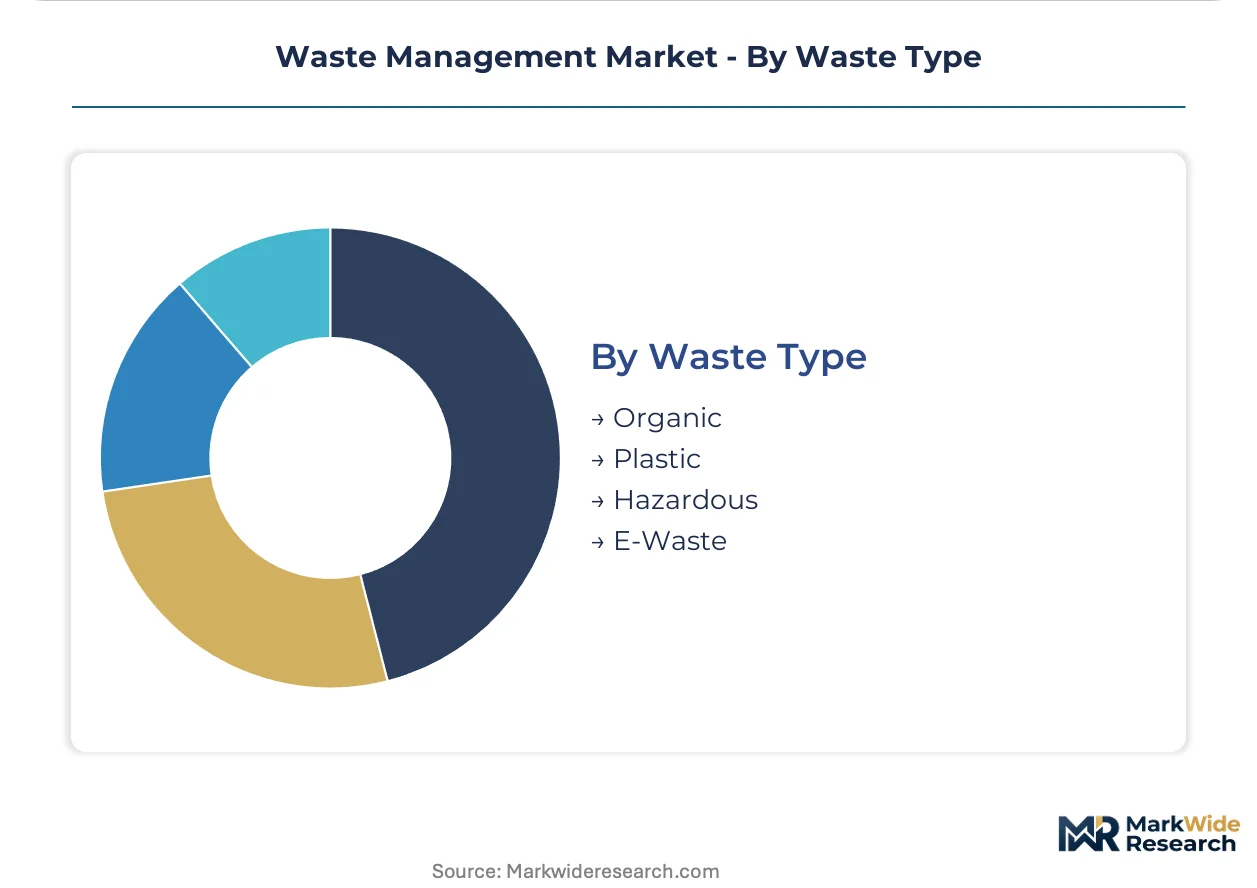
Waste Type:
Material composition dictates processing pathway, recovery value, and regulatory classification.
- Organic:Food, garden, and agricultural residues flow to composting or anaerobic digestion. EU landfill diversion targets and national biodegradable waste caps are accelerating processing capacity buildout across Germany, Italy, and the Netherlands.
- Plastic:Polymer streams split between mechanical recycling, chemical recycling, and energy recovery. Contamination levels and resin heterogeneity limit mechanical recovery rates for post-consumer films and mixed rigids.
- Hazardous:Industrial chemicals, solvents, and catalyst residues require licensed thermal treatment or secure landfill disposal. REACH SVHC list expansion is rerouting spent materials from fuel blending toward dedicated incineration.
- E-Waste:Discarded electronics contain recoverable metals and rare earth elements alongside hazardous flame retardants. WEEE directive collection targets and producer financing obligations structure European recovery economics.
Organic waste generates the largest tonnage flows, while E-Waste is climbing the fastest as device replacement cycles shorten and metal recovery technology improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany processes organic waste through anaerobic digestion at triple the rate of the United States, while India relies on informal collection networks that handle over half of urban refuse. This consumption-mix differential shapes infrastructure investment priorities and technology transfer patterns across major economies.
United States
Landfill gas capture dominates value recovery from municipal waste streams, with EPA methane regulations forcing closure of uncontrolled sites. The Infrastructure Investment and Jobs Act channels federal funding toward materials recovery facility upgrades in the Great Lakes and Southeast regions. Republic Services anchors collection density across Sun Belt metropolitan corridors through transfer station vertical control.
Germany
Packaging Act mandates drive separate bin infrastructure and mechanical recycling capacity expansion along the Rhine-Ruhr industrial corridor. The EU Green Deal landfill diversion targets have eliminated untreated organic waste disposal since 2021. Veolia operates integrated treatment and energy recovery complexes that anchor hazardous waste flows from chemical parks in Ludwigshafen and Leverkusen.
China
Municipal solid waste incineration capacity has tripled since 2015 under MEE air emissions standards that mandate flue gas scrubbing. The dual carbon goals framework restricts new landfill approvals in Yangtze River Delta cities. Shanghai and Shenzhen deploy AI-powered sorting robotics at materials recovery facilities to meet mandatory recycling rate targets.
India
Swachh Bharat Mission financing has expanded door-to-door collection to tier-1 cities while tier-2 urban areas remain below 50% formal coverage. Central Pollution Control Board rules mandate landfill biomining and capping of legacy dumpsites. Maharashtra and Gujarat host the fastest-growing waste-to-compost and biogas plant deployments.
United Kingdom
Landfill disposal taxes at 100 GBP per tonne drive food scrap diversion contracts with anaerobic digestion operators. The Environment Agency enforces waste hierarchy compliance through packaging recovery note obligations. Greater Manchester and West Midlands clusters concentrate mechanical recycling and refuse-derived fuel processing capacity.
Waste Management Market Key Industry Players
Capability concentration sits with specialized hazardous waste treatment operators; scale advantage sits with integrated collection and disposal networks spanning continental geographies. The market structures around three tiers: multinational infrastructure conglomerates with energy recovery assets, national collection specialists controlling municipal contract backlogs, and regional hazardous waste processors commanding premium margins through permitting scarcity. Dominant competitive moves include concession acquisitions to secure route density and technology licensing partnerships to deploy AI sorting without proprietary R&D investment.
Within the integrated infrastructure tier, Veolia and Waste Management, Inc. occupy positions that exemplify geographic diversification across treatment, collection, and energy recovery verticals. Clean Harbors, Inc. anchors the specialized hazardous waste segment where REACH compliance and RCRA permitting create structural barriers to competitive entry.
| Leading Market Players |
|---|
| Veolia |
| Clean Harbors, Inc. |
| Waste Management, Inc. |
| Stericycle, Inc. |
| Casella Waste Systems, Inc. |
| Republic Services, Inc. |
| GFL Environmental |
| Remondis |
| Waste Connections, Inc. |
| Others |
Cost & Logistics Intelligence
Overcapacity in German anaerobic digestion plants compresses gate fees for organic waste streams while simultaneously forcing operators toward long-term utility offtake contracts to secure revenue visibility. This utilization squeeze ripples backward through collection networks, where haulers absorb margin pressure to maintain municipal contract density.
Pricing Analysis
Long-term offtake contracts dominate revenue structures for waste-to-energy and anaerobic digestion assets, insulating operators from commodity volatility but locking in fixed returns. Hazardous waste treatment commands premium-mid-economy pricing differentiation based on RCRA permitting scarcity and liability transfer complexity. Pricing pressure stems from secondary commodity volatility, particularly OCC and mixed plastic bale values fluctuating with Chinese import policy shifts. Municipal buyers exhibit highest price sensitivity due to fixed budget appropriations, while industrial generators accept premium pricing for compliance-certain disposal routes.
Supply Chain Analysis
Extended payment terms from municipal clients strain working capital for collection operators, prompting supply-chain finance facilities backed by receivables pools. Equipment manufacturing concentrates in Germany, the Netherlands, and China for sorting robotics and emissions control systems. Raw material dependencies span high-density polyethylene for liner systems, specialized alloys for thermal treatment vessels, and rare earth elements for magnetic separation. Single-source vulnerability runs through Chinese sensor component suppliers for AI-powered sorting systems. Distribution runs through integrated transfer station networks that consolidate fragmented municipal volumes into scale-efficient treatment plant feeds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
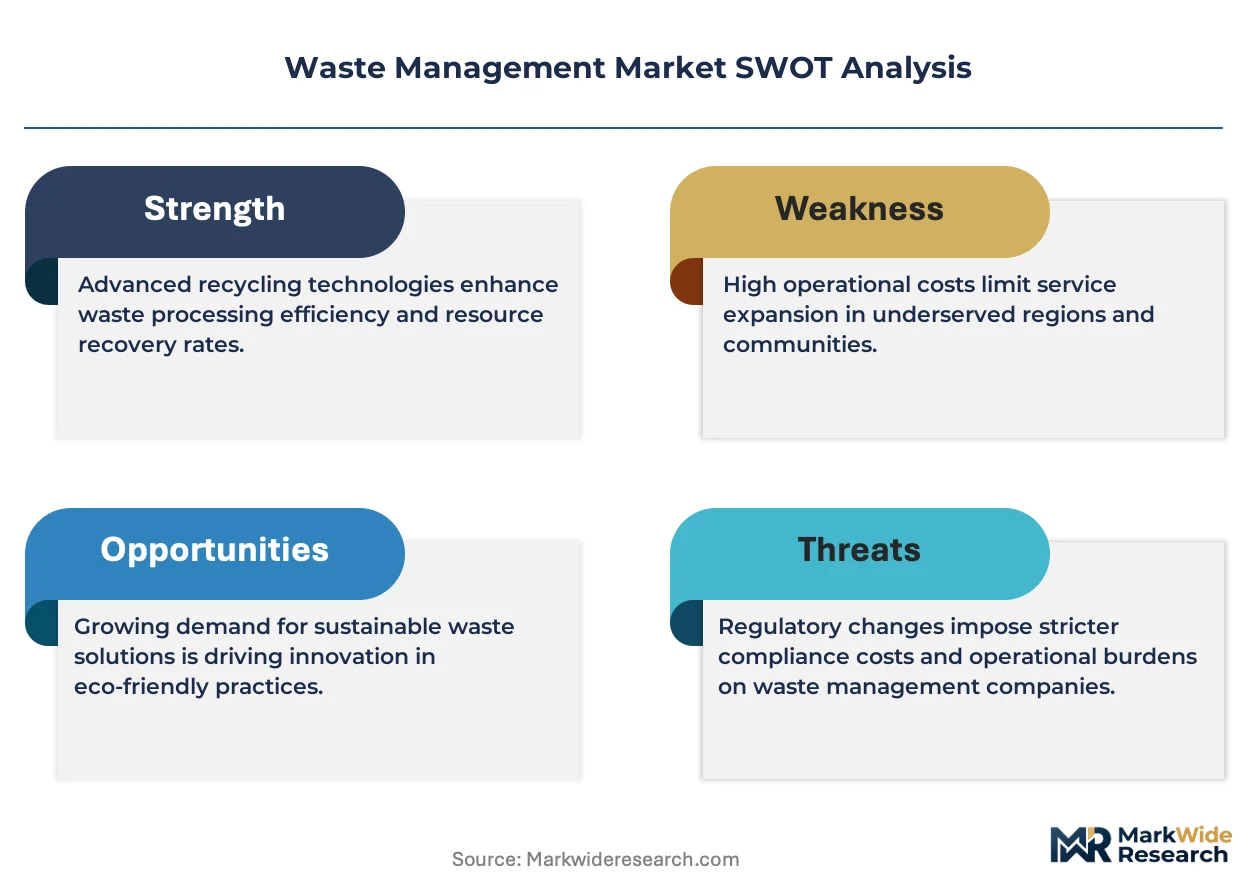
Waste management functions as a regulatory-entrenchment market where EPA and EU permitting timelines create structural moats measured in years rather than quarters.
For Market Incumbents: Insulate market position by securing concession renewals in Sun Belt metropolitan corridors before municipal budget pressures trigger competitive rebidding. Deepen upstream control over landfill gas capture infrastructure to anchor carbon credit revenue streams against biogas utility price compression. Counter emerging chemical recycling entrants by locking long-term feedstock agreements with retail chains for post-consumer plastic film streams. For New Entrants and Emerging Players: India's tier-2 cities below 50% formal collection coverage present whitespace for integrated waste-to-compost operators with Swachh Bharat Mission financing access. Target Maharashtra and Gujarat for biogas plant deployment where state-level renewable purchase obligations create offtake certainty. Pursue direct contracting with quick-service restaurant chains for store-level food scrap diversion, bypassing traditional multi-service vendors through specialized organic waste logistics. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across anaerobic digestion as biogas upgrading equipment and grid injection infrastructure expand project scope. Favor acquisition targets holding RCRA Part B permits in industrial corridor proximity, where 18-36 month approval timelines protect incumbent positioning. Monitor EPA methane regulation enforcement intensity as signal for landfill gas capture asset valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Acquisition | Route density in Sun Belt metros anchors diesel cost recovery under municipal contracts. |
| Technology Licensing Partnership | AI sorting deployment without proprietary R&D investment accelerates Packaging Act compliance. |
| Long-term Biogas Offtake Agreement | Utility power purchase contracts de-risk capital deployment for organic waste processors. |
| Backward Integration into Transfer Stations | Vertical control over consolidation points optimizes haul density and landfill gate fee capture. |
| Hazardous Waste Permit Expansion | RCRA Part B approvals in industrial clusters command premium treatment margins through scarcity. |
Research Approach
A standing panel of municipal procurement officers, landfill operations managers, anaerobic digestion plant engineers, and hazardous waste compliance directors provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement databases, EU ETS transaction registries, and municipal bond disclosure filings for waste infrastructure projects. Bottom-up volume modeling triangulated against top-down spending estimates from national environment ministry budgets.
Scenario-bracketing framed low, base, and high cases across the projection horizon without discrete year anchoring. Segmentation dimensions modeled include service type, processing technology, waste stream composition, end-user category, and regional regulatory cluster. CAGRs derived from installed capacity buildout trajectories, policy mandate enforcement schedules, and commodity price elasticity assumptions. Forecast inputs incorporated biogas grid injection tariff schedules, landfill diversion credit trading volumes, and mechanical recycling contamination rate trends.
Practitioners should monitor EPA methane rulemaking, EU Green Deal implementation delays, and Chinese import policy shifts for early signals of trajectory revision. Forecasts reflect documented assumptions about regulatory enforcement continuity, technology cost curves, and utility offtake appetite. Macroeconomic contraction, permitting timeline extension, or breakthrough chemical recycling scale-up would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Waste Sorting Equipment Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
Europe Bio-Medical Waste Management Market
Waste Management & Pollution Control
North America Solid Waste Management Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
Waste Paper Recycling Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Landfill Gas Market