
 Hazardous Waste Management Market | 2026-2036
Hazardous Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Hazardous Waste Management Market Analysis
Pharmaceutical manufacturing is consolidating its reliance on external hazardous waste handlers as in-house treatment costs escalate and liability exposure widens. Waste Management Inc. leverages its North American landfill network to anchor long-term service contracts with chemical producers. Veolia Environment SA sustains technology leadership in high-temperature incineration across European industrial zones. Clean Harbors Inc. specializes in emergency response and remediation, occupying a differentiated position in episodic waste events.
Hazardous waste management encompasses the controlled handling, treatment, and final disposition of wastes exhibiting ignitability, corrosivity, reactivity, or toxicity as defined under regulatory frameworks, with thermal destruction typically requiring combustion temperatures exceeding 1,800°F to achieve 99.99% destruction and removal efficiency for principal organic hazardous constituents. The industrial sector generates the largest volume of regulated hazardous waste streams, with treatment services commanding premium pricing due to the capital intensity of licensed facilities and the specialized labor required for compliant operations. Incineration technology leads the technology segment in destruction certainty for persistent organic pollutants, while bioremediation represents the fastest-growing treatment modality for petroleum-contaminated soils and organic solvent recovery applications.
The US EPA enforces cradle-to-grave manifest tracking under RCRA subtitle C, while the EU's Waste Framework Directive and Industrial Emissions Directive establish binding treatment standards that shape cross-border waste movement restrictions. China's MEE implements progressively stricter GB standards for hazardous waste storage and disposal, limiting market access for operators lacking localized treatment capacity. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance cost escalations and facility siting constraints.
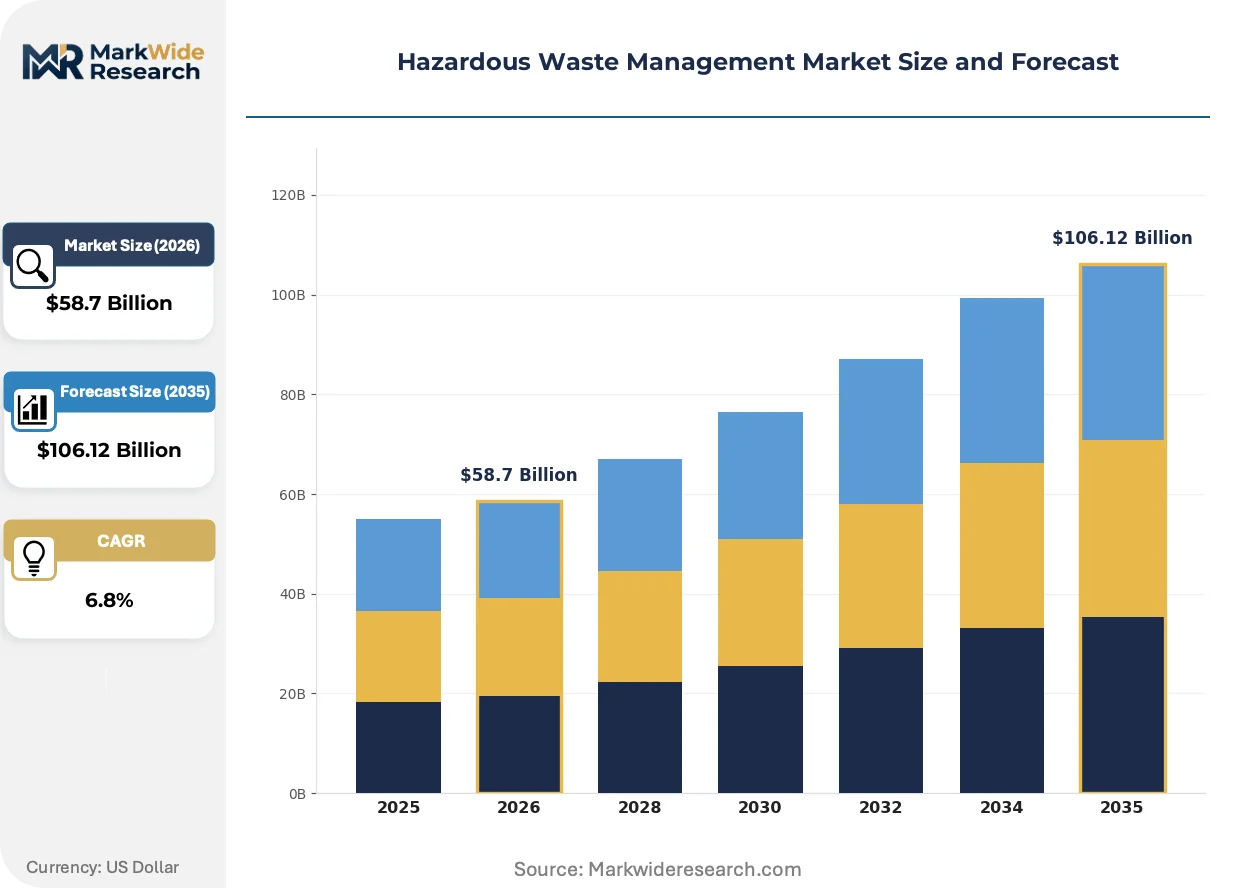
Market Dynamics
Pharmaceutical manufacturers are consolidating hazardous waste outsourcing as RCRA subtitle C amendments tighten cradle-to-grave manifest tracking and in-house treatment costs escalate beyond economic viability. Specialized third-party handlers capture volume as liability exposure widens for self-managed disposal operations.
Growth Catalysts
- RCRA Subtitle C Amendments:The US EPA's tightened manifest tracking requirements force chemical producers toward certified disposal networks, expanding contracted service demand.
- Rhine-Ruhr Chemical Density:Germany's industrial corridor concentrates pharmaceutical and specialty chemical manufacturing, driving infrastructure investment in high-capacity incineration and solvent recovery facilities.
- Plasma Gasification:High-temperature plasma arc systems achieve 99.99% destruction efficiency for persistent organic pollutants, attracting regulatory preference over conventional thermal treatment.
Market Restraints
- Licensed Facility Scarcity:Permitting timelines for new hazardous waste treatment plants extend 5-7 years in most OECD jurisdictions, constraining capacity expansion.
- Energy Input Volatility:Thermal destruction processes consume substantial natural gas and electricity, exposing operators to commodity price swings that compress treatment margins.
- Cross-Barder Movement Restrictions:The EU's Waste Framework Directive and Basel Convention amendments limit transboundary shipment flexibility, fragmenting service territories.
Strategic Opportunities
- Bioremediation for Petroleum Soils:Microbial degradation technologies for hydrocarbon-contaminated substrates remain underdeployed relative to incineration, offering cost-advantaged positioning.
- China's GB Standard Convergence:The MEE's progressively stricter storage and disposal mandates favor operators with localized treatment capacity over import-dependent models.
- Digital Manifest Integration:Blockchain-anchored waste tracking systems reduce compliance documentation burden while creating differentiated service tiers for audit-sensitive pharmaceutical clients.
Industry Challenges
- Specialized Technician Shortage:Licensed hazardous waste operations require certified personnel for handling, transport, and treatment compliance, with training pipelines failing to match facility expansion.
- Legacy Incinerator Retrofit Costs:Existing high-temperature combustion units face MACT (Maximum Achievable Control Technology) upgrade requirements demanding capital deployment without corresponding tariff increases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazardous Waste Management Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Treatment, Disposal, Recycling Sector: Industrial, Healthcare, Construction, Hazardous Materials Technology: Incineration, Chemical Treatment, Landfilling, Bioremediation End User: Manufacturers, Hospitals, Municipalities, Laboratories |
| Companies Covered | Waste Management Inc., Veolia Environment SA, Republic Services Inc., Clean Harbors Inc., SUEZ SA, Bechtel Corporation, Covanta Holding Corporation, GFL Environmental Inc., Stericycle Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazardous Waste Management Market Emerging Trajectories
Advanced thermal and biological treatment modalities are compressing the competitive position of conventional landfill disposal, while digital compliance tools reshape service differentiation. These shifts concentrate investment in destruction certainty and traceability infrastructure.
Plasma gasification is electrifying hazardous waste destruction by converting organic contaminants into synthesis gas at temperatures exceeding 5,000°C without combustion byproducts. Specialty chemical producers in the US and Germany are piloting units for chlorinated solvent streams that resist conventional incineration. This technology is electrifying competitive positioning by enabling on-site treatment that eliminates manifest liability chains.
The EU's Industrial Emissions Directive is tightening binding emission limits for hazardous waste incinerators, requiring continuous monitoring upgrades and best available technique documentation. Facility operators face capital-intensive retrofit cycles to maintain operating permits across the Rhine-Ruhr and Antwerp-Rotterdam chemical clusters. Pharmaceutical waste generators are responding by consolidating contracts with operators demonstrating sustained compliance investment.
Service unbundling is fragmenting traditional integrated contracts as large chemical producers separate transportation, treatment, and compliance documentation across specialized providers. Third-party logistics firms capture transport segments while technology-specific handlers compete for treatment slots. This pattern concentrates in the US market where generator liability under CERCLA incentivizes disaggregated vendor selection to isolate exposure.
Hazardous Waste Management Market Segmentation
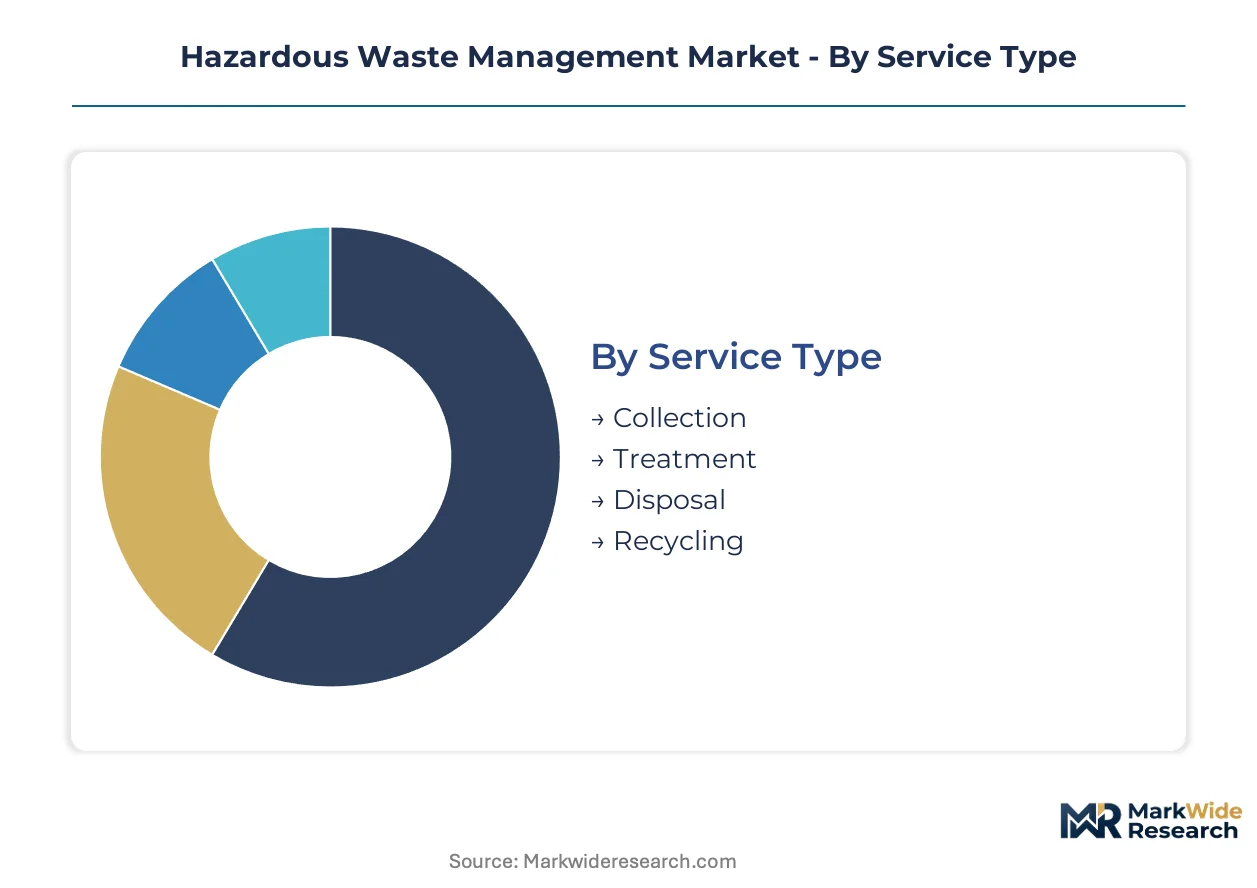
Hazardous waste management segments diverge sharply by liability exposure, capital intensity, and regulatory treatment standards. Each category captures distinct buyer priorities that reshape vendor selection criteria and contract structures across pharmaceutical, chemical, and healthcare generators.
Service Type:
Buyers differentiate primarily by risk allocation preferences—whether to retain cradle-to-grave liability or transfer it through outsourced service tiers.
- Collection:Specialized transport fleets with EPA-certified drivers and manifest documentation systems handle containerized waste from generator sites to licensed facilities. Pharmaceutical manufacturers in the US consolidate contracts with handlers offering real-time GPS tracking and digital manifest integration to satisfy RCRA subtitle C audit requirements.
- Treatment:Physical, chemical, or thermal processes neutralize hazardous characteristics before final disposition. Germany's Rhine-Ruhr chemical corridor concentrates demand for high-temperature incineration and solvent recovery infrastructure serving specialty chemical producers facing tightened EU Industrial Emissions Directive limits.
- Disposal:Secure landfill placement for stabilized residues and treated wastes requiring perpetual care obligations. Clean Harbors and Waste Management anchor North American capacity with engineered containment cells for pharmaceutical heavy metal sludges.
- Recycling:Solvent reclamation, acid regeneration, and metals recovery extract value from waste streams. Petroleum refineries in the US Gulf Coast drive demand for spent catalyst recycling and sulfuric acid recovery services.
Volume sits with Treatment; growth tilts toward Recycling as circular economy mandates intensify.
Sector:
Sector boundaries reflect waste stream toxicity profiles and generator compliance maturity rather than industrial output scale alone.
- Industrial:Chemical manufacturing, petroleum refining, and metal finishing generate the largest regulated waste volumes with complex multi-constituent contamination. US EPA enforcement actions against self-managed disposal operations accelerate third-party handler consolidation among mid-size chemical producers.
- Healthcare:Hospitals, clinics, and research facilities generate pathological, pharmaceutical, and sharps wastes requiring dual biohazard and chemical compliance. US OSHA bloodborne pathogen standards and RCRA pharmaceutical waste rules drive specialized contractor relationships.
- Construction:Asbestos abatement, lead paint removal, and contaminated site remediation generate episodic, project-based waste streams. Demolition contractors in Germany's urban renewal zones contract specialized asbestos transport and disposal services.
- Hazardous Materials:Emergency response, spill cleanup, and legacy site remediation require rapid mobilization capabilities. Clean Harbors dominates US episodic demand with dedicated response fleets and temporary treatment systems.
Industrial commands absolute tonnage; Healthcare posts the steepest expansion trajectory as pharmaceutical waste rules tighten.
Technology:
Technology selection hinges on destruction certainty requirements versus cost minimization for specific contaminant classes.
- Incineration:High-temperature combustion exceeding 1,800°F achieves 99.99% destruction and removal efficiency for principal organic hazardous constituents. Veolia sustains technology leadership across European industrial zones with continuous emissions monitoring systems satisfying EU best available technique mandates.
- Chemical Treatment:Neutralization, oxidation, and precipitation processes render corrosive or reactive wastes non-hazardous. Metal finishing facilities in the US Great Lakes region concentrate demand for chromium reduction and cyanide destruction systems.
- Landfilling:Secure placement in double-lined cells with leachate collection for stabilized inorganic residues. Permitting scarcity extends 5-7 years for new capacity in most OECD jurisdictions, constraining expansion.
- Bioremediation:Microbial degradation of petroleum hydrocarbons and organic solvents offers cost-advantaged positioning against thermal alternatives. US military base closures and brownfield redevelopments drive soil remediation demand.
Incineration anchors revenue; bioremediation gains share fastest as petroleum-contaminated site liabilities proliferate.
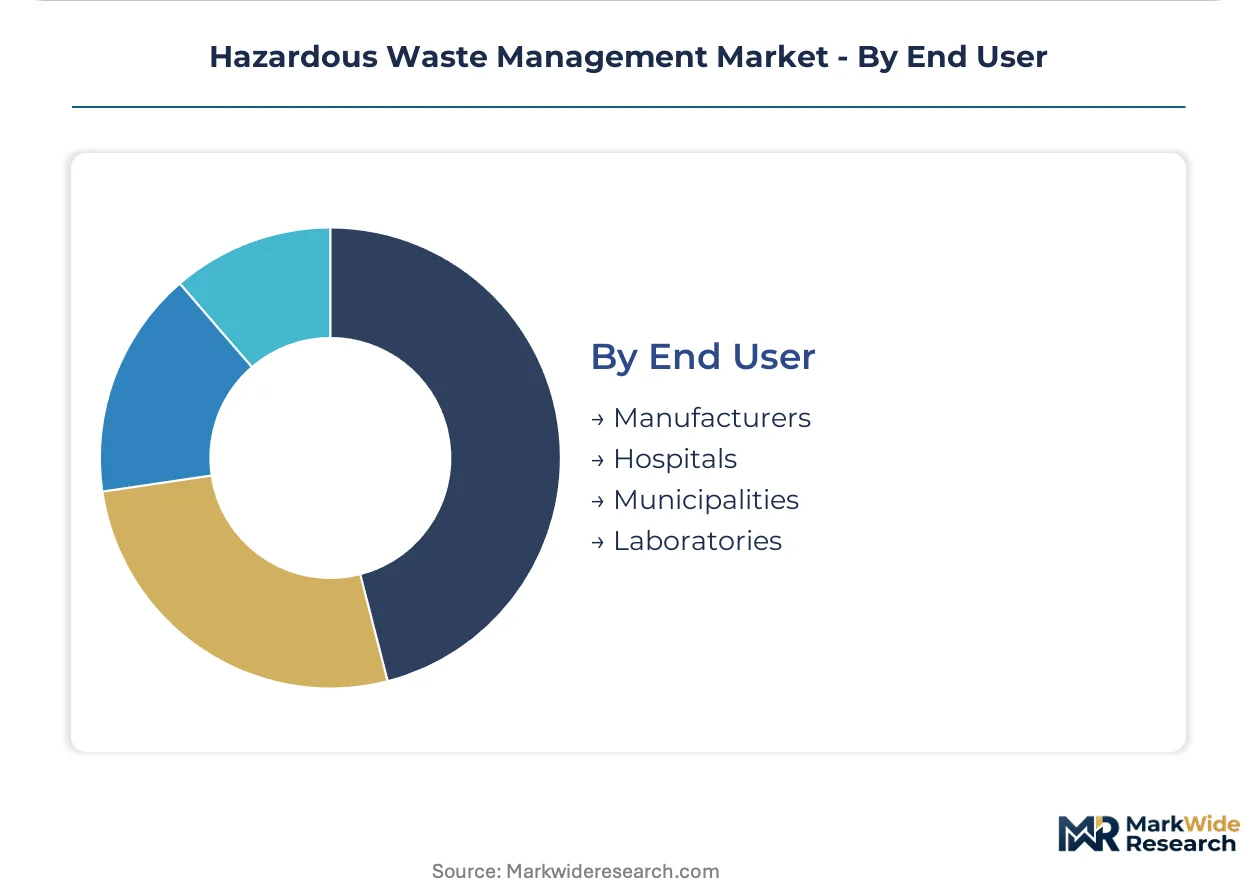
End User:
End user categories segment by internal compliance capability and regulatory scrutiny intensity.
- Manufacturers:Chemical, pharmaceutical, and electronics producers generate continuous waste streams with stringent manifest documentation requirements. US chemical producers disaggregate vendor relationships across transport, treatment, and compliance specialists to isolate CERCLA liability exposure.
- Hospitals:Healthcare facilities face dual EPA and state pharmaceutical waste regulations with high penalty exposure for misclassification. Large US health systems consolidate national contracts with handlers offering training and waste characterization services.
- Municipalities:Publicly owned treatment works and waste authorities manage household hazardous waste collection events and legacy site liabilities. German municipalities contract regional consortia for solvent and paint waste aggregation.
- Laboratories:Research and analytical facilities generate diverse small-quantity waste streams requiring flexible pickup schedules. University and government research clusters in the US Northeast drive demand for lab pack services.
Manufacturers dominate contract value; laboratories expand most quickly as R&D outsourcing proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate hazardous waste treatment investment through MEE-mandated capacity expansion quotas. Germany's Rhine-Ruhr corridor leverages EU cohesion funds for incineration infrastructure modernization. The US Gulf Coast petrochemical corridor attracts private equity into thermal treatment facilities serving refinery waste streams.
United States
Petrochemical refineries along the Texas-Louisiana Gulf Coast generate chlorinated solvent wastes requiring high-temperature destruction. EPA's RCRA subtitle C amendments tighten cradle-to-grave manifest documentation for pharmaceutical manufacturers. Houston's Ship Channel chemical cluster contracts specialized third-party handlers as in-house treatment costs escalate beyond economic viability.
Germany
Specialty chemical producers in North Rhine-Westphalia face EU Industrial Emissions Directive limits on dioxin and mercury releases. The country's Federal Immission Control Act mandates continuous emissions monitoring upgrades for existing incinerators. Leverkusen and Dormagen chemical parks drive demand for solvent recovery infrastructure serving agrochemical and pharmaceutical synthesis operations.
China
MEE's GB 18597-2023 storage standards force pharmaceutical manufacturers in Jiangsu province toward certified disposal networks. The ministry's dual carbon goals accelerate plasma gasification pilot programs for persistent organic pollutants. Shanghai's Pudong chemical industrial zone concentrates demand for high-capacity rotary kiln incineration serving electronics manufacturing waste streams.
India
Central Pollution Control Board hazardous waste management rules tighten landfill acceptance criteria for metal finishing sludges. Gujarat's Dahej and Mundra special economic zones attract investment in integrated treatment complexes serving dye and pigment manufacturers. Maharashtra's Taloja industrial area contracts regional consortia for chromium reduction and cyanide destruction services.
Japan
METI's circular economy roadmap prioritizes solvent reclamation over thermal destruction for electronics manufacturing wastes. The country's Waste Management and Public Cleansing Law mandates manifest documentation for cross-prefectural waste movement. Osaka's Sakai industrial zone concentrates demand for spent acid regeneration serving steel and semiconductor fabrication operations.
Hazardous Waste Management Market Vendor Landscape
Top-tier vendors anchor integrated service portfolios spanning collection, transport, treatment, and compliance documentation, while mid-tier specialists capture niche technology segments. The market structure reflects consolidation pressure from regulatory compliance cost escalation and facility permitting scarcity. Three archetypes dominate: diversified environmental service conglomerates, technology-specific treatment specialists, and emergency response mobilizers. Competitive intensity concentrates on M&A-driven geographic expansion and technology licensing partnerships for plasma gasification deployment.
Among North American integrated service providers, Waste Management Inc., Clean Harbors Inc., and Republic Services Inc. exemplify distinct strategic positioning archetypes. Waste Management anchors scale-driven landfill and transportation infrastructure. Clean Harbors occupies the emergency response and episodic waste event specialist tier. Republic Services represents the municipal and industrial contract consolidation model. Veolia Environment SA and SUEZ SA exemplify European technology leadership in high-temperature incineration and water-integrated waste solutions.
| Leading Market Players |
|---|
| Waste Management Inc. |
| Veolia Environment SA |
| Republic Services Inc. |
| Clean Harbors Inc. |
| SUEZ SA |
| Bechtel Corporation |
| Covanta Holding Corporation |
| GFL Environmental Inc. |
| Stericycle Inc. |
| Others |
Supply Flow & Price Mechanics
EU Industrial Emissions Directive compliance gates qualified supply for high-temperature incineration services while reserving premium-tier pricing access for operators with continuous emissions monitoring and best available technique certification. Pharmaceutical manufacturers in Germany's Rhine-Ruhr corridor pay tariff premiums to handlers demonstrating sustained regulatory investment, while spot-market treatment slots trade at discounts due to manifest liability uncertainty.
Pricing Analysis
Short lead-time pricing premiums dominate contract structures for emergency response and episodic waste events, while scheduled collection services secure volume discounts through annual offtake commitments. Treatment pricing stratifies across certified destruction certainty tiers, with plasma gasification units commanding premium positioning against conventional rotary kiln incineration. Cost compression in standard thermal treatment is intensifying because natural gas input volatility erodes operator margins without corresponding tariff escalation. Small-quantity generators in laboratory and research segments exhibit highest price sensitivity, while large chemical producers prioritize liability transfer over unit cost minimization.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical and chemical producers mandate multi-supplier qualification for transport, treatment, and compliance documentation to isolate CERCLA liability exposure. Licensed facility capacity concentrates in the United States, Germany, and China, with permitting scarcity extending development timelines. Thermal destruction processes draw from natural gas, electricity, and specialized refractory materials as core inputs. Single-source vulnerability persists for high-temperature incineration in the EU Rhine-Ruhr corridor where MACT upgrade cycles constrain effective capacity. Distribution runs through EPA-certified transport fleets with real-time GPS tracking and digital manifest integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hazardous waste management sector sits in a technology-transition phase as plasma gasification displaces legacy incineration for chlorinated solvent streams and persistent organic pollutants. Incumbents must defend positioning through compliance infrastructure investment while new entrants exploit regulatory tailwinds in underpenetrated bioremediation segments.
For Market Incumbents: Deepen vertical integration into transport fleets and digital manifest systems to anchor long-term pharmaceutical contracts against specialized technology entrants. Veolia and Waste Management should accelerate MACT-compliant retrofit cycles ahead of EU Industrial Emissions Directive enforcement windows. Secure exclusive offtake agreements with chemical producers in the US Gulf Coast and Germany's Leverkusen-Dormagen cluster to lock in volume before permitting scarcity worsens.
For New Entrants and Emerging Players: RCRA subtitle C amendments in the United States open a window for blockchain-anchored waste tracking specialists to capture compliance documentation segments from traditional integrated handlers. Target petroleum-contaminated soil bioremediation in US military base closures and brownfield redevelopments where microbial degradation costs undercut thermal alternatives. Lead with on-site plasma gasification pilots for chlorinated solvent generators seeking manifest liability elimination.
For Investors and Strategic Acquirers: MEE GB 18597-2023 storage standard enforcement in Jiangsu province is the leading indicator that localized Chinese treatment capacity will command valuation premiums over import-dependent models. Acquire mid-tier handlers with existing permits in OECD jurisdictions where 5-7 year development timelines create artificial scarcity value. Watch for plasma gasification technology licensing partnerships as the inflection signal for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Gasification Licensing | Technology transfer agreements enable on-site treatment eliminating manifest liability chains for chlorinated solvent generators. |
| Digital Manifest Integration | Blockchain-anchored tracking systems differentiate service tiers for audit-sensitive pharmaceutical clients under RCRA subtitle C. |
| Bioremediation Capacity Expansion | Microbial degradation infrastructure captures petroleum-contaminated soil demand from US military base closures. |
| MACT Retrofit Acceleration | Continuous emissions monitoring upgrades preserve operating permits across EU Rhine-Ruhr chemical clusters. |
| Regional Permit Acquisition | Licensed facility scarcity in OECD jurisdictions creates defensive moats through artificial capacity constraints. |
Methodological Framework
Independent corroboration across EPA enforcement records, EU ETS emissions disclosures, and MEE facility licensing databases underwrites the qualitative findings in this study. Primary interviews with hazardous waste operations managers, pharmaceutical EHS directors, and third-party logistics procurement leads combined with secondary validation from RCRA manifest data, Basel Convention transboundary shipment records, and chemical industry SEC filings. Bottom-up treatment capacity modeling and top-down waste generation estimates triangulate market sizing across service type, technology, and end-user segments.
Rate-of-change decomposition anchors the analytical framework across the projection horizon, with volume trajectories modeled by service tier, technology modality, generator sector, and regional regulatory cluster. CAGRs derive from facility capacity expansion schedules, permitting approval velocities, and waste stream growth correlations with downstream chemical and pharmaceutical production indices. Plasma gasification adoption curves and bioremediation penetration rates for petroleum-contaminated soils constitute industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for plasma gasification commercialization would alter the outlook for incumbent incineration operators. Deviation in MEE enforcement intensity or EU Industrial Emissions Directive implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
North America Waste Recycling Services Market
Waste Management & Pollution Control
North America Industrial Waste Management Market
Waste Management & Pollution Control
Polyfluoroalkyl Substances (PFAS) Waste Management Market
Waste Management & Pollution Control
Europe Medical Waste Management Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
Compostable Straws Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Waste Recycling Services Market