
 Alkaline Solid Waste Market | 2026-2036
Alkaline Solid Waste Market Size, Share, and Industry Trends Forecast 2026-2036
Alkaline Solid Waste Market Outlook
Fly ash from coal combustion is repositioning limestone in cement kiln feedstocks across European and Asian operations. Veolia leverages its integrated hazardous waste infrastructure to secure long-term supply contracts with cement producers in France and Poland. SUEZ anchors its alkaline waste recovery business through proprietary stabilization technologies that meet French ANSM leaching thresholds. Waste Management Inc. dominates the North American alkaline solids stream via landfill mining partnerships with regional construction material suppliers.
Alkaline solid waste comprises residues with pH exceeding 9.0, including steel slag, cement kiln dust, coal combustion residuals, and red mud, typically requiring neutralization or encapsulation before beneficial reuse or final disposal. The material serves primarily as a supplementary cementitious material, soil stabilizer, or landfill cover engineered to immobilize heavy metals through pozzolanic reactions. Industrial waste generates the largest volume segment, though agricultural residue streams are expanding fastest as dairy and poultry operations face manure management mandates. Anaerobic digestion of alkaline-amended agricultural waste yields higher biogas purity than conventional substrates, drawing investment from specialized processors. Energy recovery applications command premium pricing where waste-to-energy facilities achieve grid-connected electricity generation.
EPA Subtitle D landfill criteria and state-level beneficial use determinations govern alkaline solid waste handling in the United States, while the EU Waste Framework Directive and REACH compliance obligations shape product acceptance across member states. China's MEE enforces GB 16889 leaching standards that restrict direct landfill disposal of high-pH residues, compelling on-site neutralization or third-party processing. India's CPCB has notified hazardous waste management rules that reclassify certain alkaline slags as non-hazardous upon meeting BIS-specified toxicity characteristic leaching procedure limits. Stakeholders must monitor evolving classification thresholds that determine whether alkaline residues qualify for construction material exemptions or require costly hazardous waste treatment.
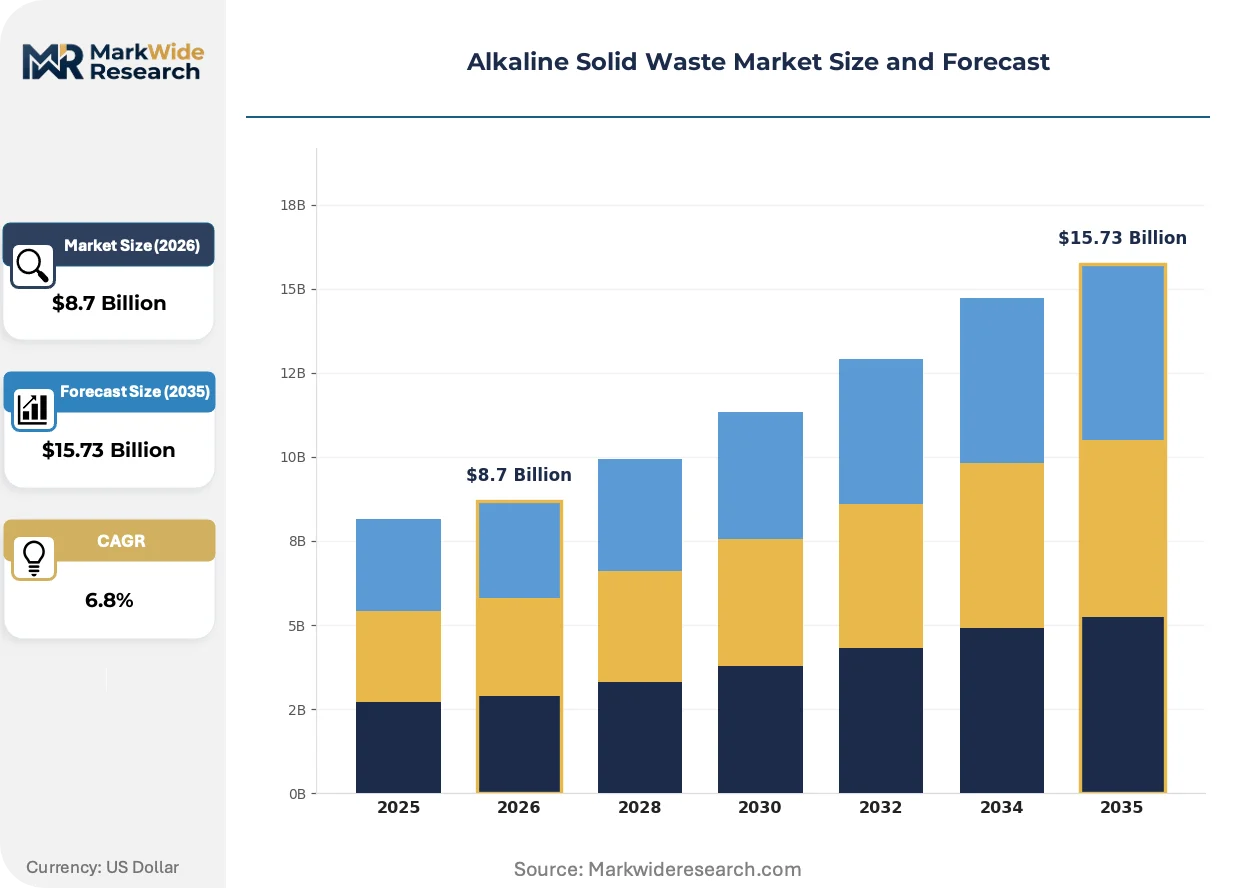
Market Dynamics
China's MIIT mandates on alternative raw material ratios in cement kilns are redirecting industrial alkaline residues from landfills to processing facilities, compressing supply availability for traditional waste handlers while opening procurement channels for construction material suppliers.
Growth Catalysts
- EU Waste Framework Directive:REACH compliance obligations across member states are accelerating beneficial use determinations for steel slag in soil stabilization applications.
- Cement sector demand:German and Indian cement manufacturers are expanding procurement volumes for clinker substitution under tightening industrial emissions rules.
- Biogas upgrading:Anaerobic digestion of alkaline-amended agricultural waste yields higher biogas purity than conventional substrates, drawing specialized processor investment.
Market Restraints
- Leaching standard fragmentation:China's GB 16889, India's BIS TCLP limits, and EPA Subtitle D criteria create incompatible compliance burdens for cross-border waste traders.
- Red mud processing concentration:Bauxite residue neutralization capacity clusters near aluminum smelters in Shanxi and Henan provinces, limiting supply flexibility.
- Limestone substitution ceiling:Fly ash pozzolanic reactivity varies by coal source, capping replacement rates in high-performance concrete specifications.
Strategic Opportunities
- Landfill mining partnerships:Waste Management Inc.'s North American model of excavating aged alkaline solids for construction feedstock is replicable in Australian and Canadian jurisdictions with mature landfill infrastructure.
- Grid-connected energy recovery:Waste-to-energy facilities achieving electricity generation certification command premium pricing for high-calorific alkaline waste streams.
- French ANSM stabilization thresholds:SUEZ's proprietary encapsulation technology meeting these leaching standards creates licensing potential for EU waste handlers seeking hazardous waste derogation.
Industry Challenges
- Pozzolanic reaction expertise:Cement kiln operators lack technical staff trained in alkaline waste blending ratios for consistent clinker quality.
- Legacy landfill liability:Unlined disposal sites from pre-1990s operations require costly capping with alkaline cover materials, diverting supply from productive reuse.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkaline Solid Waste Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Sewage Sludge, Agricultural Residue, Industrial Waste, Municipal Solid Waste Treatment Method: Composting, Anaerobic Digestion, Incineration, Landfilling End User: Environmental Agencies, Waste Management Companies, Government Bodies, Recycling Facilities Application: Soil Amendment, Energy Recovery, Fertilizer Production, Construction Material |
| Companies Covered | Veolia, SUEZ, Waste Management Inc., Republic Services Inc., Clean Harbors Inc., Waste Connections Inc., Stericycle Inc., GFL Environmental Inc., Remondis SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkaline Solid Waste Market Strategic Shifts
Processing technologies and regulatory frameworks are converging to transform alkaline solid waste from a disposal liability into a specified construction input, with implications for waste handler business models and cement sector procurement.
Mobile neutralization units are decentralizing alkaline waste processing by enabling on-site pH adjustment at industrial generator facilities. Steel mills in Poland and cement plants in Rajasthan are deploying containerized systems to avoid transportation costs to centralized treatment hubs. This distributed model is compressing third-party processor margins while expanding generator self-handling capabilities.
India's CPCB hazardous waste management rules are reclassifying certain alkaline slags as non-hazardous upon meeting BIS-specified TCLP limits. This regulatory relaxation enables steel producers to sell directly to construction material suppliers without intermediary treatment. The construction vertical in Gujarat and Maharashtra is responding fastest, with ready-mix concrete producers revising supplier qualification criteria.
Long-term offtake agreements are displacing spot market transactions as the dominant procurement mechanism for cement kiln dust and coal combustion residuals. Major concrete producers in France and Poland now contract directly with power utilities for multi-year supply security. This channel consolidation is most visible in markets where REACH compliance costs have driven smaller waste handlers from beneficial use certification.
Alkaline Solid Waste Market Segmentation
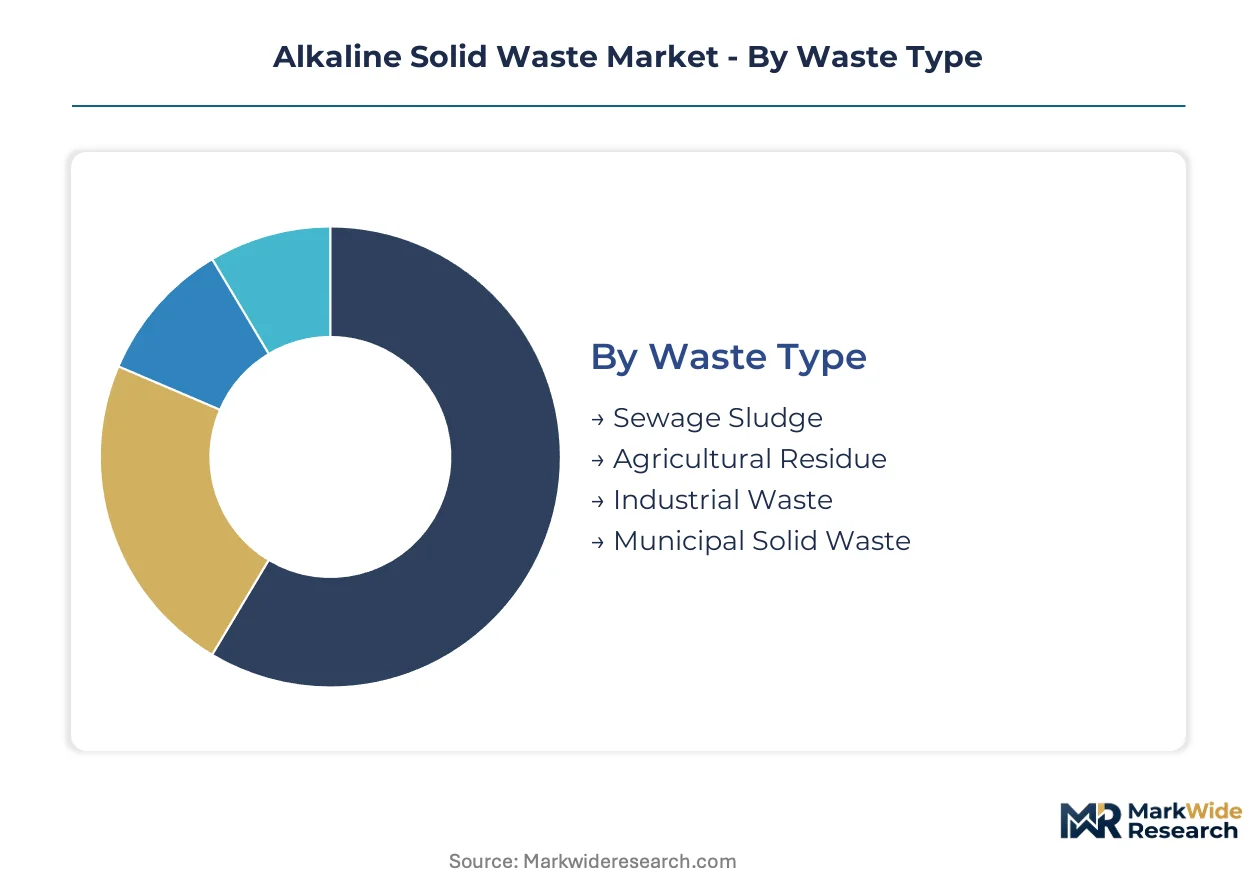
Alkaline solid waste segmentation reveals distinct value capture mechanisms across waste streams, treatment technologies, and downstream applications. Procurement patterns diverge sharply between industrial generators seeking disposal compliance and construction material suppliers pursuing feedstock security.
Waste Type:
Replacement cycles for alkaline waste handling infrastructure accelerate where pH buffering requirements intensify, forcing equipment upgrades every 7-10 years in high-volume processing corridors.
- Industrial Waste:Steel slag, cement kiln dust, and coal combustion residuals dominate tonnage flows. German cement manufacturers and Chinese MIIT-mandated kilns absorb the largest procurement volumes under tightening clinker substitution rules.
- Agricultural Residue:Dairy and poultry manure streams with alkaline amendment requirements for odor control and biogas upgrading. Anaerobic digestion facilities in Denmark and the Netherlands achieve higher methane purity from these substrates, drawing specialized processor investment.
- Sewage Sludge:Municipal wastewater residuals requiring pH neutralization before land application or incineration. Treatment concentrates near urban centers with advanced nutrient recovery mandates.
- Municipal Solid Waste:Post-recycling alkaline fractions including ash residues and contaminated paper stocks. Landfill mining operations in North America extract aged material for construction feedstock recovery.
Volume placements concentrate in Industrial Waste; the faster expansion belongs to Agricultural Residue.
Treatment Method:
Cost tier differentiation separates capital-intensive thermal processing from lower-technology biological routes, with equipment financing availability determining method selection across generator categories.
- Anaerobic Digestion:Biological conversion of organic alkaline waste to biogas with concurrent pH stabilization. Grid-connected facilities in France and Poland command premium feedstock pricing where electricity generation certification applies.
- Composting:Aerobic decomposition producing stabilized soil amendments. Agricultural residue processors in California's Central Valley and Lombardy, Italy leverage existing manure management infrastructure for alkaline waste co-processing.
- Incineration:High-temperature oxidation of combustible alkaline fractions with energy recovery. Japanese METI efficiency standards and EU Waste Framework Directive emissions limits shape plant economics.
- Landfilling:Final disposal with engineered cover systems utilizing alkaline materials for heavy metal immobilization. EPA Subtitle D criteria and China's GB 16889 leaching standards restrict direct placement of untreated high-pH residues.
Capital deployment concentrates in Anaerobic Digestion; the steepest expansion trajectory belongs to Composting as agricultural sector mandates proliferate.
End User:
Customer type fragmentation creates divergent procurement specifications, with government bodies prioritizing compliance documentation and private operators emphasizing feedstock cost stability.
- Waste Management Companies:Integrated handlers securing long-term supply contracts for landfill mining and material recovery. Veolia's hazardous waste infrastructure in France and Poland anchors European alkaline solids consolidation.
- Recycling Facilities:Specialized processors extracting construction-grade materials from industrial alkaline streams. SUEZ's proprietary stabilization technologies meeting French ANSM thresholds enable hazardous waste derogation licensing.
- Government Bodies:Municipal and national authorities mandating beneficial reuse quotas. India's CPCB reclassification of certain alkaline slags as non-hazardous upon BIS TCLP compliance redirects procurement toward direct construction sales.
- Environmental Agencies:Regulatory enforcement and site remediation oversight. Legacy landfill capping requirements in industrial corridors absorb substantial alkaline cover material volumes.
Contract value concentrates in Waste Management Companies; the fastest share gains belong to Recycling Facilities as beneficial use certification barriers ease.
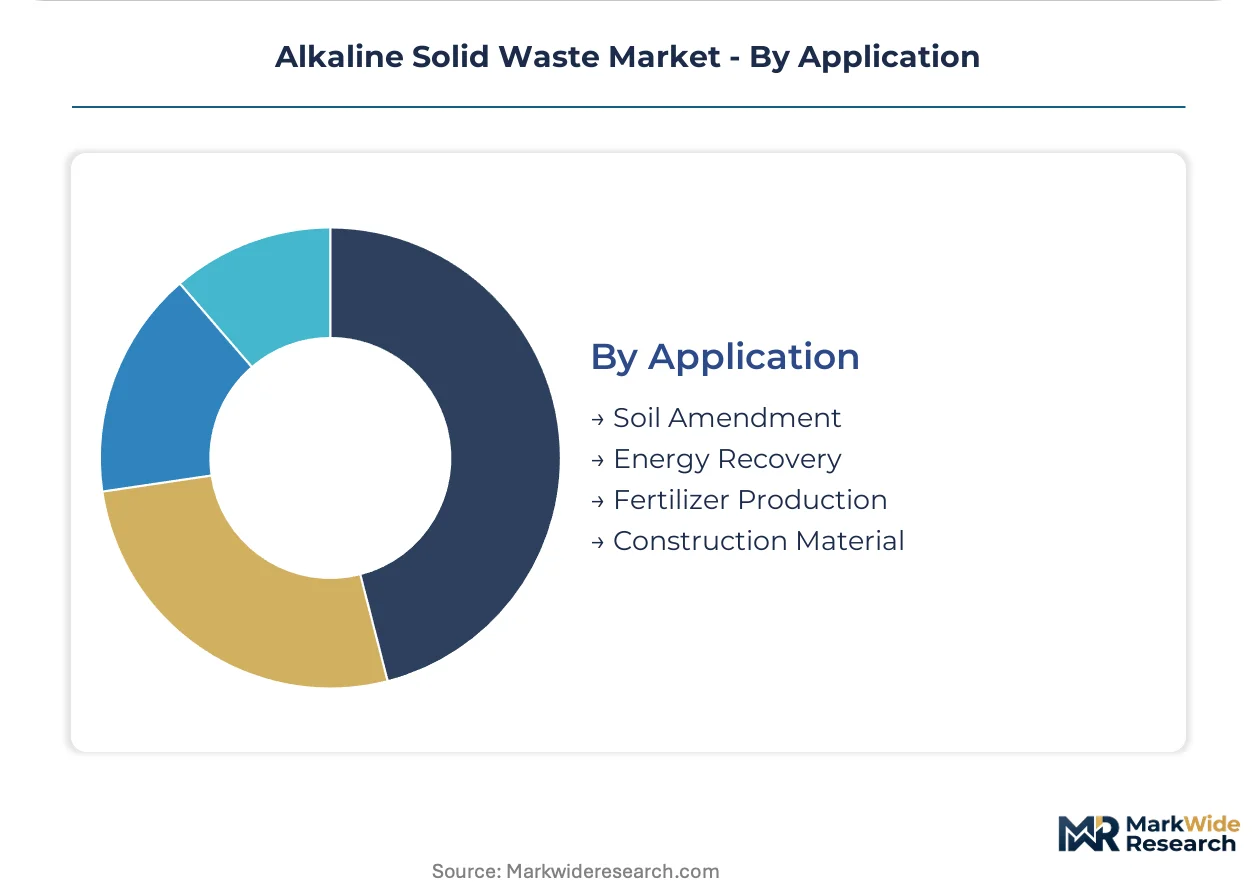
Application:
Application maturity varies by technical specification depth, with construction material integration requiring the most rigorous performance validation cycles.
- Construction Material:Supplementary cementitious material and soil stabilization feedstocks. Fly ash pozzolanic substitution for limestone faces performance ceilings in high-strength concrete specifications where coal source variability affects reactivity.
- Energy Recovery:Waste-to-electricity generation from high-calorific alkaline waste fractions. Premium pricing applies where grid connection certification is achieved, particularly in German and Polish markets.
- Soil Amendment:Agricultural pH correction and heavy metal immobilization. REACH compliance obligations across EU member states accelerate beneficial use determinations for steel slag in this channel.
- Fertilizer Production:Nutrient recovery from sewage sludge and agricultural residues. Phosphorus extraction technologies concentrate near major wastewater treatment clusters.
Revenue concentration sits with Construction Material; the quickest climb belongs to Energy Recovery as waste-to-energy capacity expands in Eastern Europe and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement volumes concentrate in cement manufacturing corridors where clinker substitution mandates redirect alkaline residues from disposal to productive reuse. Germany, China, and India absorb the largest procurement volumes under tightening industrial emissions frameworks.
China
Steel slag and coal combustion residuals dominate feedstock flows to cement kilns in Shanxi and Henan provinces. MIIT mandates on alternative raw material ratios compel producers to redirect industrial alkaline residues from landfills to processing facilities. The Yangtze River Delta cement corridor achieves the highest clinker substitution rates through integrated waste-to-material supply chains.
Germany
Construction material suppliers secure long-term offtake agreements for fly ash and steel slag under REACH compliance obligations. The KBA enforces leaching standards that accelerate beneficial use determinations for soil stabilization applications. North Rhine-Westphalia's cement manufacturing belt leads European procurement volumes for alkaline solid waste feedstocks.
India
Ready-mix concrete producers in Gujarat and Maharashtra revise supplier qualification criteria following CPCB reclassification of certain alkaline slags as non-hazardous. BIS-specified TCLP limits enable steel producers to sell directly to construction material suppliers without intermediary treatment. The Delhi-Mumbai Industrial Corridor anchors the fastest-expanding procurement channel for cement kiln dust substitution.
United States
Landfill mining partnerships excavate aged alkaline solids for construction feedstock recovery under EPA Subtitle D criteria. Waste handlers in the Midwest and Southeast concentrate on coal ash beneficiation for concrete-grade material production. Texas and Florida cement markets absorb the largest volumes of processed fly ash from regional power utility partnerships.
France
SUEZ and Veolia leverage hazardous waste infrastructure to secure supply contracts with cement producers under ANSM leaching thresholds. The EU Waste Framework Directive shapes product acceptance for steel slag in soil stabilization across member states. The Paris Basin and Lyon-Grenoble industrial corridor concentrate alkaline waste processing capacity for construction material integration.
Alkaline Solid Waste Market Competitive Environment
Long-term offtake agreements dominate the current landscape as cement producers secure multi-year supply security from power utilities and steel manufacturers. The vendor base organizes around three strategic archetypes: integrated waste handlers with landfill mining capabilities, specialized processors with proprietary stabilization technologies, and construction material suppliers with direct generator relationships. M&A consolidation and technology licensing represent the primary competitive moves as handlers seek hazardous waste derogation capabilities and cement producers demand consistent feedstock quality.
Within the integrated handler tier, Veolia and Waste Management Inc. exemplify the landfill mining and hazardous waste infrastructure model that anchors regional supply consolidation. SUEZ occupies a position among technology-driven processors where proprietary encapsulation systems enable regulatory compliance at premium pricing. These three entities represent the dominant competitive archetypes: European-anchored environmental services conglomerates, North American scale-driven waste handlers, and specialized stabilization technology licensors.
| Leading Market Players |
|---|
| Veolia |
| SUEZ |
| Waste Management Inc. |
| Republic Services Inc. |
| Clean Harbors Inc. |
| Waste Connections Inc. |
| Stericycle Inc. |
| GFL Environmental Inc. |
| Remondis SE & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Coal combustion residual spot indices in Shanxi and Henan provinces cascade through cement kiln procurement tiers, compressing margins for unprocessed material handlers while elevating premiums for stabilized feedstocks meeting China's GB 16889 leaching thresholds. Long-term offtake agreements between German power utilities and construction material suppliers anchor pricing floors, insulating integrated processors from volatility in landfill diversion markets.
Pricing Analysis
Volume contracts capture margin in the 70-85% range of alkaline solid waste flows, with spot transactions commanding 15-30% premiums for urgent kiln feedstock requirements. Price differentiation hinges on BIS TCLP certification tier and pozzolanic reactivity grade, with high-performance concrete specifications paying substantial uplifts over soil stabilization grades. Cost compression in unprocessed industrial waste streams is intensifying as China's MIIT mandates redirect supply toward cement manufacturers. Municipal procurement bodies exhibit highest price sensitivity, while ready-mix concrete producers in Gujarat and Maharashtra absorb certification premiums for supply security.
Supply Chain Analysis
Reverse-logistics networks for aged alkaline solids from pre-1990s landfill sites are expanding in Texas and Florida, where Waste Management Inc. excavates and beneficiates material for construction feedstock recovery. Primary supply concentrates in China, India, and Germany, with bauxite residue neutralization capacity clustering near aluminum smelters in Shanxi and Henan provinces. The supply chain draws from coal combustion residuals, steel slag, and cement kiln dust as core inputs. Single-source vulnerability runs through centralized red mud processing infrastructure. Distribution runs through direct generator-to-kiln contracting, bypassing traditional waste handler intermediaries where regulatory reclassification permits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alkaline solid waste procurement operates as a cost-of-compliance market, where India's CPCB hazardous waste reclassification creates a regulatory moat for processors achieving BIS TCLP certification. The barrier-to-entry dynamic favors capitalized handlers with proprietary stabilization capabilities.
For Market Incumbents: Anticipate margin compression in unprocessed material trading as China's MIIT mandates accelerate direct generator-to-cement-plant contracting. Defensive consolidation should target mobile neutralization unit operators in Poland and Rajasthan to capture distributed processing demand. Cement kiln operators lacking in-house blending expertise represent acquisition targets for technology licensing arrangements. For New Entrants and Emerging Players: India's CPCB reclassification of certain alkaline slags as non-hazardous opens a window for steel producers to bypass intermediary treatment and sell directly to construction material suppliers. Agricultural residue processing in Denmark and the Netherlands offers the most penetrable white-space, with anaerobic digestion facilities seeking alkaline amendments for biogas upgrading. A go-to-market angle anchored in grid-connected electricity generation certification commands premium feedstock pricing. For Investors and Strategic Acquirers: Distressed-cycle entries favor landfill mining specialists with EPA Subtitle D compliance infrastructure in the US Midwest and Southeast. Long-term viability over a 5-10 year horizon rests on regulatory reclassification trends that expand beneficial use exemptions. The signal to watch is REACH compliance cost escalation in EU member states, which will drive smaller waste handlers from certification and concentrate supply among scaled processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mobile Neutralization | Containerized pH adjustment systems in Poland and Rajasthan compress third-party processor margins while expanding generator self-handling capabilities. |
| Long-term Supply Agreement | Multi-year offtake contracts between French power utilities and concrete producers displace spot market transactions under REACH compliance cost pressure. |
| Proprietary Stabilization Technology Licensing | SUEZ's encapsulation systems meeting French ANSM thresholds enable hazardous waste derogation for EU handlers seeking premium positioning. |
| Landfill Mining Partnership | Excavation and beneficiation of aged alkaline solids in Texas and Florida redirects supply from final disposal to construction feedstock recovery. |
| Geographic Expansion into Agricultural Residue Processing | Anaerobic digestion facilities in Denmark and the Netherlands achieve higher methane purity from alkaline-amended substrates, drawing specialized investment. |
Study Parameters
Document review covered customs and trade data, SEC filings from waste handlers, EPA enforcement databases, and EU Waste Framework Directive implementation reports, complemented by interviews with cement plant procurement managers, steel mill environmental compliance officers, anaerobic digestion facility operators, and construction material supplier quality directors. Secondary validation drew from China's MIIT policy circulars, India's CPCB hazardous waste notifications, and BIS standard documentation. Bottom-up tonnage estimates from individual kiln operations were triangulated against top-down national cement production statistics.
Segment-level value outputs across the projection horizon reflect modeled interactions between waste type, treatment method intensity, and end-user procurement specifications. The analytical framework incorporated industrial waste, agricultural residue, sewage sludge, and municipal solid waste streams; anaerobic digestion, composting, incineration, and landfilling routes; and construction material, energy recovery, soil amendment, and fertilizer production applications. CAGRs were derived from regression analysis of historical clinker substitution rates and regulatory mandate implementation timelines. Forecast inputs included China's alternative raw material ratio mandates and India's reclassification thresholds for alkaline slag hazard status.
The model assumes a particular technology adoption path for mobile neutralization units; alternative pathways for distributed on-site pH adjustment would alter the outlook for centralized processor market share. Forecasts reflect assumptions regarding regulatory reclassification continuity, cement sector emissions compliance stringency, and agricultural biogas upgrading infrastructure deployment. Practitioners should monitor GB 16889 enforcement intensity in China, REACH compliance cost trajectories in EU member states, and BIS TCLP limit revisions in India for early signals of supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Waste Management Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
North America Waste Recycling Services Market
Waste Management & Pollution Control
Saudi Arabia Waste Management Market
Waste Management & Pollution Control
Wheeled Bins Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
PET Recycling Market
Waste Management & Pollution Control
Trash Pump Market
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
Qatar Waste Management Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
Metal Recycling Equipment Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market