
 Sludge Management Equipment Market | 2026-2036
Sludge Management Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sludge Management Equipment Market Analytics
Class-A biosolids certification is rotating from niche priority to baseline procurement requirement across municipal procurement frameworks. Andritz AG leverages its thermal drying technology leadership to anchor European utility contracts. Alfa Laval sustains competitive positioning through centrifuge specialization in high-oil industrial sludge streams. Evoqua Water Technologies differentiates via integrated dewatering-chemical conditioning packages for North American industrial end users.
Sludge management equipment encompasses mechanical, thermal, chemical, and biological systems engineered to reduce water content, stabilize organic matter, and enable safe disposal or resource recovery from wastewater residuals, with dewatering equipment typically achieving 15-30% dry solids and thermal dryers reaching 90%+ for energy recovery applications. Dewatering equipment dominates installed value due to universal upstream placement across treatment trains, while thermal drying systems capture disproportionate margin pools where energy recovery offsets operational expenditure. Municipal end users structure procurement around lifecycle cost models, whereas industrial buyers prioritize footprint reduction and contaminant-specific compliance.
The EPA enforces Clean Water Act Section 503 biosolids standards, while the EU Urban Wastewater Treatment Directive mandates tertiary treatment expansion, and China's MEE enforces stricter sludge disposal permits under water pollution control regulations. These frameworks collectively shift capital allocation toward pathogen-reduction technologies and trace-metal compliance systems. Stakeholders must monitor regulatory divergence between thermal energy recovery incentives and landfill restriction timelines when configuring regional product portfolios.
Market Dynamics
The EPA's Clean Water Act Section 503 enforcement is compressing discharge timelines for municipal utilities, forcing capital reallocation from conventional dewatering toward pathogen-reduction technologies and thermal drying infrastructure.
Growth Catalysts
- EU Urban Wastewater Treatment Directive:Tertiary treatment mandates across Germany, France, and the Netherlands are expanding installed base requirements for advanced dewatering and thermal processing systems.
- Energy recovery integration:Thermal drying systems capturing biogas from anaerobic digestion are offsetting operational expenditure for municipal operators facing rising electricity tariffs.
- Industrial pharmaceutical sludge streams:High-oil residuals from active pharmaceutical ingredient manufacturing are driving centrifuge demand for hazardous waste compliance.
Market Restraints
- Specialized alloy supply concentration:Duplex stainless steel for corrosion-resistant dewatering equipment faces sourcing bottlenecks from Scandinavian mill concentration.
- High capital intensity of thermal drying:Front-loaded infrastructure expenditure exceeds municipal bond financing thresholds for secondary cities.
- Landfill restriction timeline divergence:Germany's Waste Disposal Act prohibits landfilling of untreated sludge while Eastern European jurisdictions maintain lower-cost disposal alternatives.
Strategic Opportunities
- Poland and Czech Republic municipal upgrade cycles:EU cohesion fund allocations are financing first-generation thermal drying installations in catch-up markets.
- Pyrolysis-gasification convergence:Integration of thermal drying with biochar production is opening agricultural soil amendment revenue streams.
- Performance-based service contracting:Dewatering-as-a-service models are transferring operational risk from municipal operators to equipment vendors.
Industry Challenges
- Class-A biosolids certification timelines:Pathogen reduction validation protocols create 18-24 month commissioning delays for thermal drying projects.
- Legacy SCADA integration complexity:Brownfield wastewater facilities require custom middleware to connect new dewatering controls with existing distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sludge Management Equipment Market |
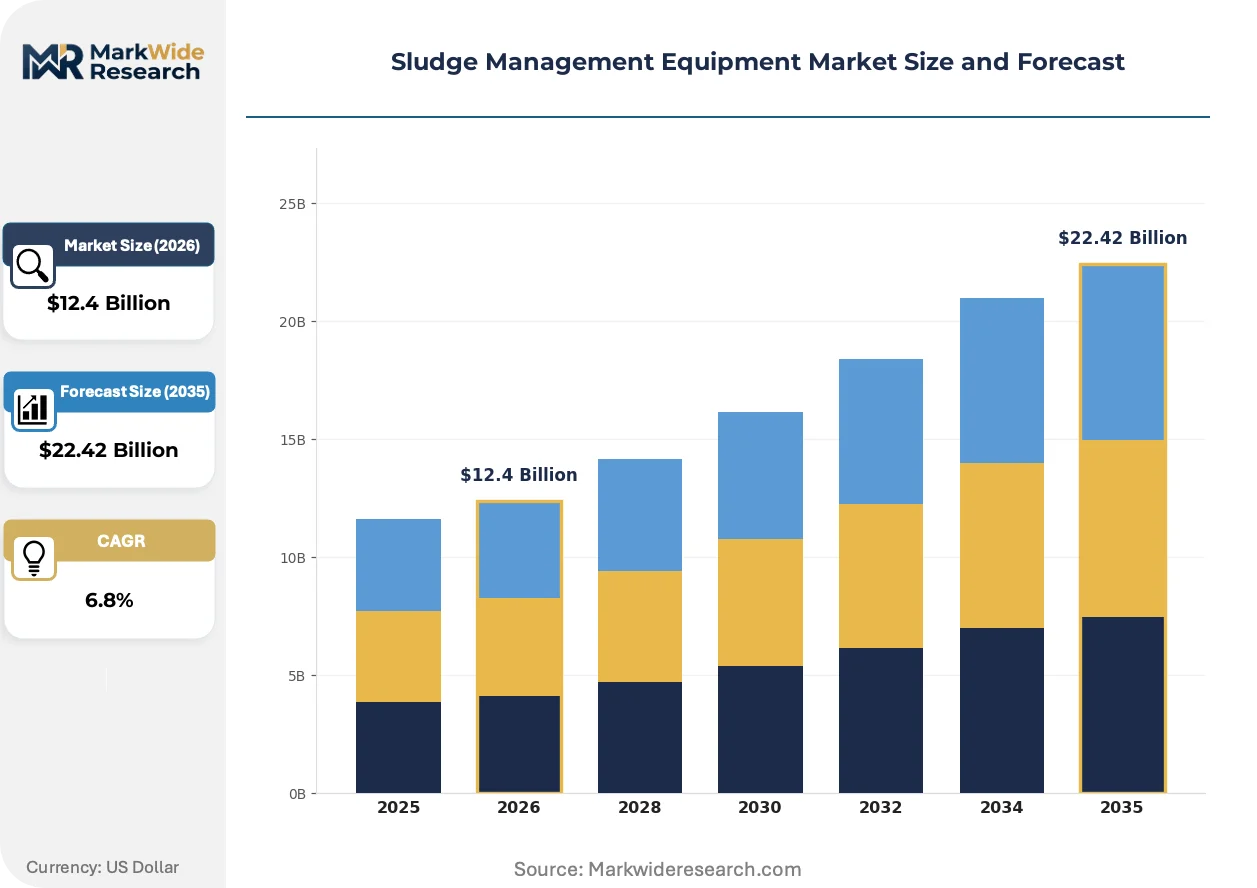
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sludge Pumps, Thickening Systems, Dewatering Equipment, Drying Systems Technology: Mechanical, Thermal, Chemical, Biological End User: Municipal, Industrial, Agricultural, Wastewater Treatment Facilities Installation: On-site, Off-site, Mobile, Permanent |
| Companies Covered | Andritz AG, Alfa Laval, Veolia Water Technologies, HUBER SE, Evoqua Water Technologies, Suez, Flottweg SE, Hitachi Zosen Corporation, Komline-Sanderson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sludge Management Equipment Market Evolving Landscape
Electromechanical dewatering technologies are displacing chemical-dependent processes as energy recovery economics reshape operational expenditure structures across municipal and industrial treatment facilities.
High-solids centrifuge technology is decomposing the traditional dewatering-thickening sequential workflow. German municipal utilities are retrofitting existing plants with direct-to-cake centrifugation, eliminating intermediate polymer conditioning stages. This compression is decomposing installed base value for gravity belt thickener manufacturers while concentrating margin capture in high-G force centrifuge specialists.
The EU F-Gas Regulation phase-down is restricting hydrofluorocarbon refrigerants in heat pump-assisted sludge dryers. Thermal drying OEMs are pivoting to CO2 transcritical cycles and absorption heat pumps for low-temperature evaporation. German equipment suppliers face the steepest compliance curve due to early enforcement timelines under the national Chemicals Climate Protection Ordinance.
Lifecycle cost modeling is displacing first-cost procurement for North American municipal buyers. Engineering firms are bundling dewatering equipment selection with 20-year operational expenditure forecasting, favoring higher-efficiency centrifuges over belt presses despite capital premiums. This recalculation is most visible in California and Texas utilities facing escalating biosolids hauling costs.
Sludge Management Equipment Market Segmentation
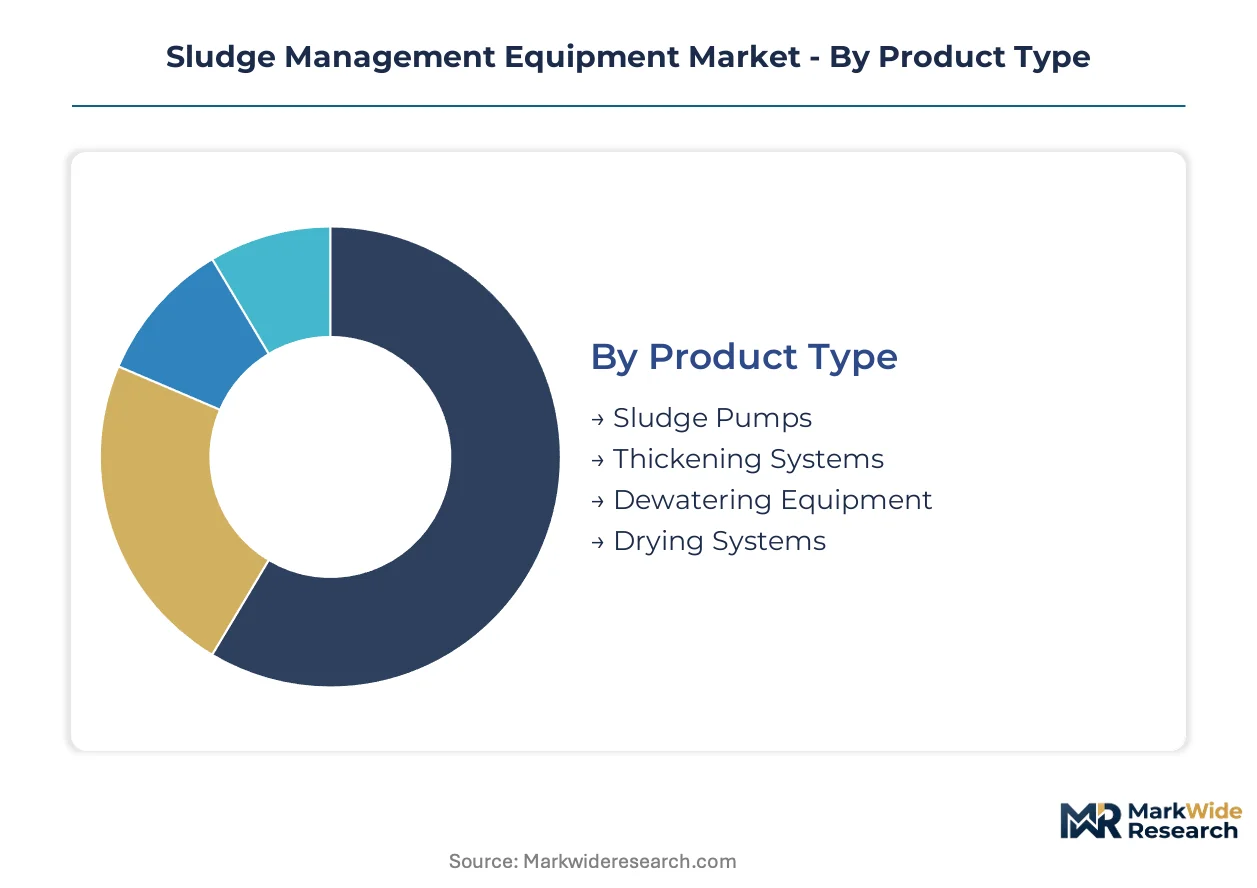
Equipment segmentation in sludge management reflects divergent procurement channels: municipal utilities favor integrated dewatering-drying packages through engineering-procurement-construction contractors, while industrial buyers source standalone units via direct OEM relationships. Channel specialization shapes margin structures and service attachment rates across each product category.
Product Type:
Dewatering equipment and drying systems flow predominantly through EPC integrators bundling with civil works, whereas pumps and thickeners see higher direct procurement volumes from municipal maintenance departments.
- Dewatering Equipment:Centrifuges, belt presses, and screw presses achieve 15-30% dry solids content through mechanical water removal. German municipal utilities under the Water Resources Act are retrofitting plants with high-solids centrifuges to eliminate intermediate thickening stages and reduce polymer consumption.
- Drying Systems:Thermal dryers utilizing direct or indirect heat transfer reach 90%+ dry solids for energy recovery and pathogen reduction. France and the Netherlands are expanding installed capacity to meet EU Urban Wastewater Treatment Directive tertiary mandates and landfill diversion timelines.
- Sludge Pumps:Progressive cavity and piston pumps handle high-viscosity residuals with abrasive solid content. Replacement demand concentrates in aging North American infrastructure.
- Thickening Systems:Gravity belt and rotary drum thickeners reduce volume prior to dewatering. Gravity belt installations are declining as high-solids centrifuges compress workflows.
Dewatering equipment dominates installed base. Drying systems are where expansion concentrates.
Technology:
Technology selection tracks end-user cost structures: mechanical systems appeal to capital-constrained municipalities, while thermal and biological approaches gain traction where energy recovery economics offset operational expenditure.
- Mechanical:Physical separation via centrifugation, filtration, and pressing requires no thermal energy input. This remains the default procurement choice for secondary cities facing municipal bond financing thresholds.
- Thermal:Evaporation and drying processes enable Class-A biosolids certification and biogas capture. Germany's Chemicals Climate Protection Ordinance is accelerating heat pump retrofits away from hydrofluorocarbon refrigerants.
- Chemical:Polymer conditioning and lime stabilization adjust sludge characteristics for downstream handling. Chemical costs are escalating with polymer supply chain volatility.
- Biological:Anaerobic digestion with biogas recovery precedes thermal drying in integrated energy recovery trains. Agricultural digestate markets are expanding in Poland and Czech Republic.
Mechanical technology anchors current installations. Thermal technology is climbing the fastest as energy recovery incentives reshape lifecycle cost models.
End User:
End-user segmentation determines compliance intensity: municipal buyers face EPA Clean Water Act and EU directive enforcement, while industrial users navigate contaminant-specific hazardous waste frameworks.
- Municipal:Public wastewater treatment facilities serve residential and commercial sewage loads. Section 503 biosolids standards are compressing discharge timelines and forcing capital reallocation toward pathogen-reduction infrastructure.
- Industrial:Pharmaceutical, food processing, and petrochemical operations generate high-oil or hazardous residuals. Active pharmaceutical ingredient manufacturing in Ireland and Switzerland is driving centrifuge demand for solvent-laden sludge compliance.
- Wastewater Treatment Facilities:Dedicated tertiary and advanced treatment plants handle combined industrial-municipal flows. These facilities are expanding thermal drying capacity for regional biosolids processing hubs.
- Agricultural:Livestock operations and food processing residuals management utilize smaller-scale anaerobic digestion. This segment remains fragmented with lower equipment specification intensity.
Municipal end users command the largest equipment volumes. Industrial applications are gaining share fastest as pharmaceutical and chemical sector compliance tightens.
Installation:
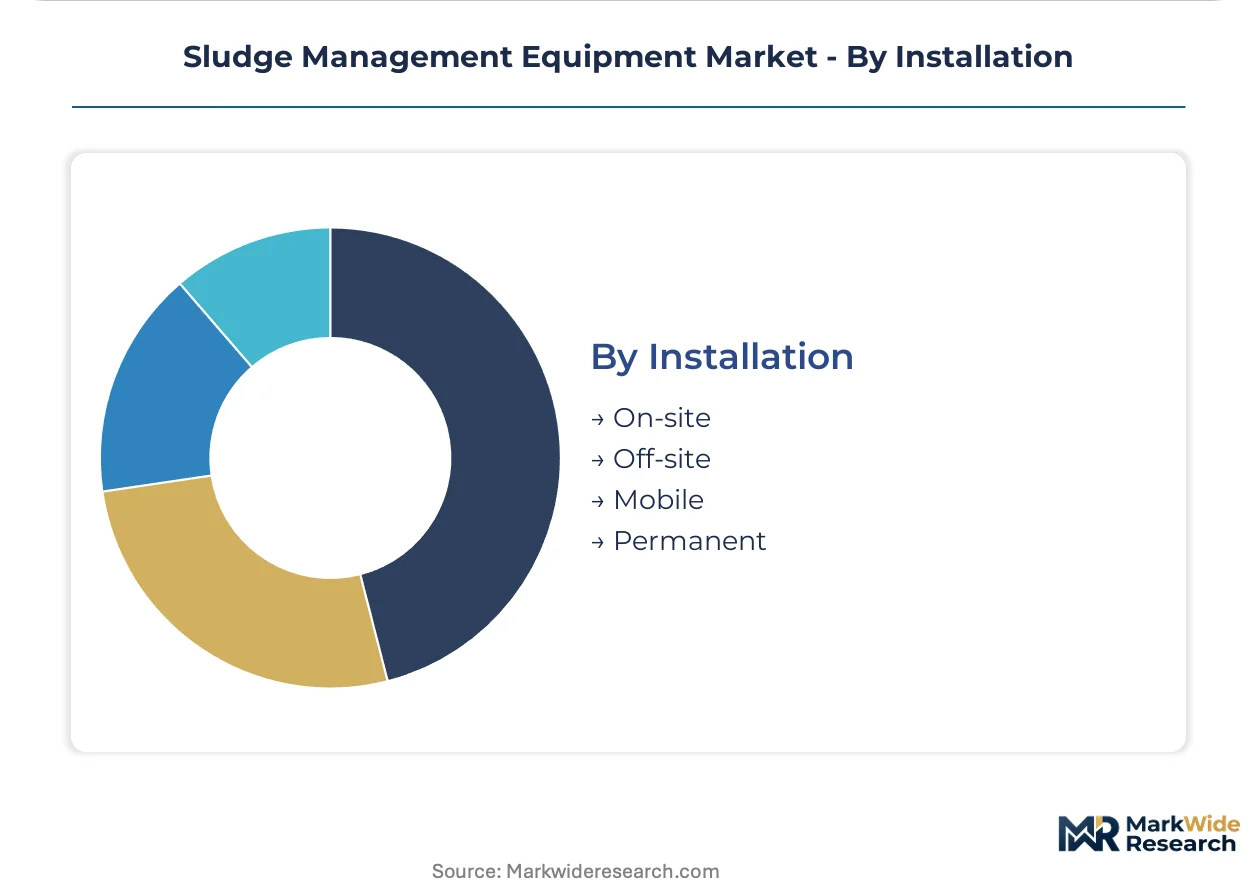
Installation modality reflects asset ownership models: permanent on-site systems dominate municipal balance sheets, while mobile and off-site configurations serve industrial spot treatment and regional hub strategies.
- Permanent:Fixed infrastructure with 20-30 year depreciation schedules anchors municipal utility capital planning. California and Texas utilities are favoring higher-efficiency permanent centrifuges over belt presses despite capital premiums.
- On-site:Integrated within treatment train boundaries to minimize hauling costs. Brownfield facilities face legacy SCADA integration complexity requiring custom middleware.
- Mobile:Trailer-mounted dewatering units serve emergency response and seasonal demand peaks. Rental penetration is expanding in industrial maintenance turnarounds.
- Off-site:Regional centralized processing facilities accept sludge from multiple generators. Germany's Waste Disposal Act prohibition on untreated sludge landfilling is accelerating off-site thermal drying hub development.
Permanent installations anchor the equipment base. Off-site configurations are expanding most quickly as regional hub economics overcome distributed treatment legacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. German municipal utilities accept capital premiums for thermal drying systems, while Eastern European buyers prioritize first-cost mechanical dewatering. Chinese industrial users drive mid-market centrifuge volumes through compliance-driven replacement cycles.
Germany
The Water Resources Act and Waste Disposal Act prohibit untreated sludge landfilling, forcing tertiary treatment expansion. The Chemicals Climate Protection Ordinance accelerates heat pump retrofits away from hydrofluorocarbon refrigerants. Municipal utilities in North Rhine-Westphalia and Bavaria are retrofitting plants with high-solids centrifuges to eliminate intermediate thickening stages.
United States
EPA Clean Water Act Section 503 enforcement compresses discharge timelines for biosolids management. California and Texas utilities favor higher-efficiency permanent centrifuges over belt presses despite capital premiums, driven by escalating hauling costs. The Southeast faces aging infrastructure replacement demand concentrated in Florida and Georgia treatment facilities.
France
EU Urban Wastewater Treatment Directive tertiary mandates expand installed capacity requirements. The country's national water agency enforces stricter sludge quality standards for agricultural reuse. Industrial clusters around Lyon and Marseille are investing in thermal drying infrastructure for regional biosolids processing hubs.
China
The Ministry of Ecology and Environment enforces stricter sludge disposal permits under water pollution control regulations. Yangtze River Delta municipalities face compliance-driven replacement of legacy dewatering equipment. Pharmaceutical manufacturing zones in Jiangsu and Zhejiang provinces drive centrifuge demand for hazardous waste compliance.
Poland
EU cohesion fund allocations finance first-generation thermal drying installations in catch-up markets. The national environmental regulator tightens discharge standards to align with Western European timelines. Municipal utilities in Warsaw and Krakow are developing regional centralized processing facilities to overcome distributed treatment legacy.
Sludge Management Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. European engineering conglomerates anchor premium thermal drying segments through integrated energy recovery systems, while Asian fabricators compete on mechanical equipment first-cost. Three archetypes dominate: full-line system integrators bundling dewatering-drying packages, centrifuge specialists capturing high-oil industrial streams, and regional fabricators serving price-sensitive replacement demand. M&A activity concentrates on thermal technology acquisitions, while strategic partnerships link equipment vendors with biogas project developers.
Among European full-line suppliers, Andritz AG and Alfa Laval occupy positions exemplifying divergent specialization strategies—one anchored in thermal drying technology leadership, the other in centrifuge engineering for high-solids applications. Evoqua Water Technologies represents the North American integrated solutions archetype, bundling equipment with chemical conditioning services. These three companies illustrate how geographic origin and structural focus shape competitive positioning without requiring identical capability portfolios.
| Leading Market Players |
|---|
| Andritz AG |
| Alfa Laval |
| Veolia Water Technologies |
| HUBER SE |
| Evoqua Water Technologies |
| Suez |
| Flottweg SE |
| Hitachi Zosen Corporation |
| Komline-Sanderson |
| Others |
Value Network & Pricing Analysis
Heat pump refrigerant substitution from hydrofluorocarbons to CO2 transcritical cycles is simultaneously relocating thermal dryer manufacturing toward German engineering clusters and compressing margin structures for equipment suppliers facing Chemicals Climate Protection Ordinance compliance deadlines.
Pricing Analysis
After-sales service contracts and spare parts provisioning capture lifetime value exceeding original equipment margins by substantial multiples. Three-tier pricing structure across premium thermal drying systems, standard centrifuge packages, and economy belt press configurations reflects certification grade differentiation. Cost compression in the economy tier is intensifying as Asian fabricators expand mechanical equipment exports. Municipal utilities in Germany and France demonstrate lowest price sensitivity due to lifecycle cost modeling adoption, while Eastern European municipal buyers prioritize first-cost procurement.
Supply Chain Analysis
Inbound logistics costs from Scandinavian duplex stainless steel mills to German and Austrian manufacturing hubs have tightened following container availability constraints on Baltic trade lanes. Equipment fabrication draws from specialized alloy supply concentrated in Sweden and Finland, electric motor assemblies anchored in Germany and Italy, and polymer conditioning chemicals sourced from Belgium and the Netherlands. Single-source vulnerability persists for corrosion-resistant alloy plate. Distribution runs through engineering-procurement-construction contractors bundling civil works with mechanical installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where regulatory entrenchment—specifically EPA Section 503 and EU Urban Wastewater Treatment Directive compliance timelines—creates substantial switching costs for municipal utilities locked into validated thermal drying infrastructure.
For Market Incumbents: Fortify aftermarket service attachment through predictive maintenance platforms and captive spare parts inventory positioned near regional biosolids processing hubs. Expand vertical integration into polymer conditioning chemical supply to offset margin pressure from equipment commoditization. Prioritize certification investment for Class-A biosolids validation protocols to extend commissioning-phase competitive exclusion. For New Entrants and Emerging Players: EPA fast-track equivalency pathways for pathogen-reduction technologies offer accelerated market access compared to full Section 503 validation cycles. Target industrial pharmaceutical sludge streams in Ireland and Switzerland where hazardous waste compliance drives centrifuge replacement demand. Pursue performance-based service contracting models transferring operational risk from municipal operators to equipment vendors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors thermal technology specialists with integrated energy recovery capabilities over pure-play mechanical equipment fabricators. Acquisition targets with established biogas project developer partnerships demonstrate superior long-term viability within the 5-10 year infrastructure replacement window. Monitor EU cohesion fund allocation announcements as inflection indicators for Polish and Czech Republic municipal upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Duplex Stainless Steel | Captive alloy supply secures margin control against Scandinavian mill concentration. |
| Heat Pump Retrofit Certification Program | F-Gas Regulation compliance opens German municipal utility replacement cycles. |
| Regional Biogas Partnership Development | Energy recovery integration anchors long-term service contract renewals. |
| Performance-Based Service Contracting Launch | Operational risk transfer models penetrate municipal procurement frameworks. |
| Pyrolysis-Gasification Technology Licensing | Biochar revenue streams diversify thermal drying system value propositions. |
Research Methodology
The analysis maps dewatering equipment, thermal drying systems, sludge pumps, and thickening technologies, each validated through municipal utility procurement officers, EPC contractor engineering directors, and aftermarket service managers. Primary fieldwork combined structured interviews with plant engineers at wastewater treatment facilities and OEM procurement teams with secondary validation against EPA enforcement data, EU Urban Wastewater Treatment Directive implementation reports, and national environmental regulator filings. Bottom-up equipment installation tracking and top-down infrastructure investment flow analysis were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated equipment type, technology category, end-user industry, and installation modality dimensions. CAGRs were derived from regression analysis of historical municipal capital expenditure patterns and forward infrastructure replacement schedules. Forecast inputs included EU cohesion fund allocation trajectories and EPA enforcement timeline acceleration scenarios.
Underlying assumptions cover regulatory enforcement continuity, alloy supply chain stability, and municipal bond financing availability, with deviation risk concentrated in landfill restriction timeline divergence between Western and Eastern European jurisdictions. Forecasts reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
ASEAN Waste Management Market
Waste Management & Pollution Control
Global Waste Management Software Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
Trash Rakes Market
Waste Management & Pollution Control
Industrial Waste Management Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
North America Waste Recycling Services Market
Waste Management & Pollution Control
Wood Recycling Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Household Composters Market